
 Liner Hanger System Market | 2026-2036
Liner Hanger System Market Size, Share, and Industry Trends Forecast 2026-2036
Liner Hanger System Market Intelligence
A shift from single-source procurement to multi-source contracting is broadening vendor qualification requirements across major exploration basins. Halliburton Company leverages its integrated well construction portfolio to anchor long-term service agreements in the Permian Basin. Schlumberger Limited differentiates through proprietary expandable hanger metallurgy that sustains performance in high-pressure, high-temperature reservoirs. Baker Hughes Company competes by extending its digital lifecycle monitoring capabilities to subsea installations, reducing unplanned intervention frequency.
A liner hanger system is a mechanical or hydraulically actuated downhole tool that suspends and seals a liner within a previously set casing string, typically rated for differential pressures exceeding 10,000 psi and temperatures above 350°F to isolate formations and enable zonal production control. Mechanical hangers dominate land-based installations where simplicity and retrieval speed offset premium pricing, while expandable hangers represent the fastest-growing product category as operators push into deeper, more geologically complex subsea plays where conventional slip mechanisms face fatigue limitations. Smart hanger technologies with real-time load and pressure telemetry are capturing margin pools in integrated system contracts where service companies bundle hardware with predictive analytics subscriptions.
The US Bureau of Safety and Environmental Enforcement mandates subsea well containment capabilities that directly shape hanger design specifications for Gulf of Mexico operators, while API RP 100-1 well integrity guidelines establish testing protocols that filter market access for uncertified suppliers. Norway's Petroleum Safety Authority and Brazil's national petroleum regulator enforce analogous barrier verification standards that constrain product interchangeability across jurisdictions. Stakeholders must monitor regulatory divergence between prescriptive load-testing regimes and performance-based integrity frameworks when allocating R&D budgets across product lines.
Market Dynamics
Deepwater operators are consolidating procurement around integrated hanger-service bundles, compressing standalone hardware margins while elevating predictive maintenance and telemetry capabilities as competitive differentiators in subsea contract awards.
Growth Catalysts
- API RP 100-1 well integrity protocols:The US Bureau of Safety and Environmental Enforcement mandates rigorous barrier verification for Gulf of Mexico subsea installations, forcing replacement cycles for aging mechanical hanger fleets.
- High-pressure high-temperature reservoirs:Expandable hanger metallurgy sustains differential pressures exceeding 10,000 psi in Brazil's pre-salt formations where conventional slip mechanisms face fatigue failure.
- Shale revitalization programs:Permian Basin operators accelerate liner hanger replacement cycles as refracturing campaigns and extended lateral drilling intensify mechanical wear on existing infrastructure.
Market Restraints
- Specialized alloy supply concentration:Premium nickel-based superalloys for expandable hangers concentrate among a limited supplier base, exposing procurement costs to raw material volatility.
- Prescriptive load-testing regimes:Norway's Petroleum Safety Authority enforces rigid certification timelines that extend product qualification cycles and constrain rapid technology iteration.
- Mechanical retrieval limitations:Conventional slip-based hangers face displacement risk in ultra-deepwater plays where differential thermal expansion compromises seal integrity.
Strategic Opportunities
- Smart hanger telemetry convergence:Real-time load and pressure monitoring systems bundled with predictive analytics subscriptions capture margin pools in integrated service contracts.
- Angola and Mozambique offshore leasing:Underpenetrated deepwater basins offer first-mover positioning for expandable hanger technologies as national oil companies expand exploration programs.
- Digital lifecycle monitoring platforms:Subsea installations in Brazil's Santos Basin generate recurring revenue streams through remote condition monitoring that reduces unplanned intervention frequency.
Industry Challenges
- HPHT metallurgy certification timelines:Extended qualification protocols for proprietary expandable hanger alloys delay commercialization and compress R&D return windows.
- Multi-vendor integration complexity:Operators bundling hanger hardware with third-party telemetry systems face interoperability failures that erode reliability guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liner Hanger System Market |
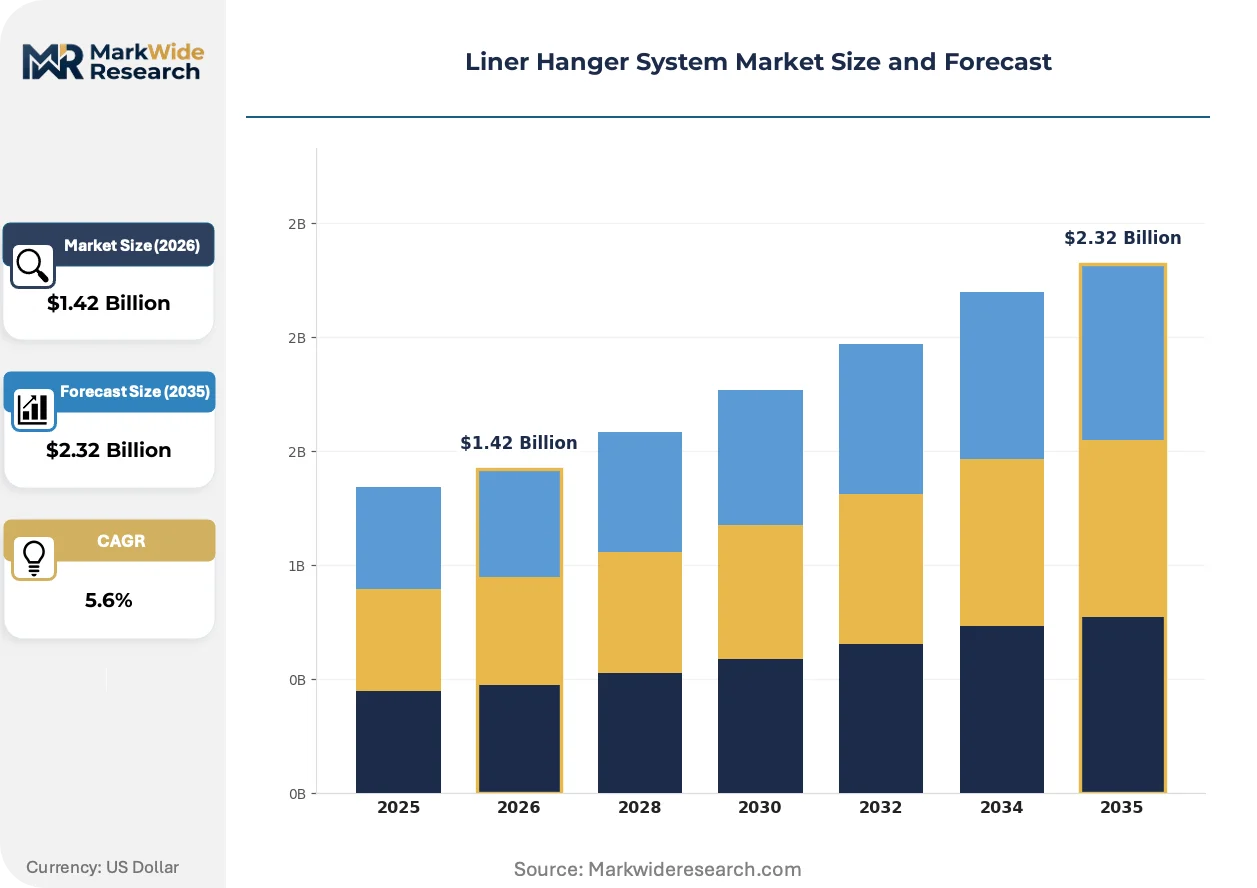
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.32 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Hangers, Hydraulic Hangers, Expandable Hangers, Inflatable Hangers Technology: Single-Trip Systems, Dual-Trip Systems, Integrated Systems, Smart Hangers End User: Oil & Gas Producers, Service Companies, Contract Operators, Equipment Manufacturers Installation Type: Onshore, Offshore, Subsea, Land-Based |
| Companies Covered | Weatherford International plc, TechnipFMC plc, Halliburton Company, NCS Multistage Holdings, Inc., Dril-Quip, Inc., Schlumberger Limited, National Oilwell Varco, Inc., Innovex Downhole Solutions, Inc., Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liner Hanger System Market Strategic Shifts & Innovations
Expandable metallurgy and embedded sensor networks are actively displacing conventional mechanical architectures, while regulatory pressure on barrier verification accelerates digital lifecycle tracking adoption across deepwater basins.
Proprietary expandable hanger alloys is consolidating competitive positioning in ultra-deepwater segments. Operators in Brazil's pre-salt formations and US Gulf of Mexico Lower Tertiary plays adopt these systems at accelerating rates as differential pressure requirements exceed conventional slip ratings. The technology is consolidating vendor relationships around metallurgy-licensing agreements that lock in long-term service捆绑.
REACH substance restrictions and EU Green Deal carbon accounting requirements are tightening material traceability standards for subsea wellhead components. European-headquartered operators now demand full lifecycle emissions documentation for hanger alloys and elastomeric seals. North Sea installations face the most immediate compliance burden, with procurement specifications increasingly excluding suppliers lacking ISO 14001-certified foundry networks.
Integrated performance-based contracting is displacing standalone hardware procurement in major exploration basins. Gulf of Mexico and West Africa deepwater operators now bundle hanger supply with installation, monitoring, and workover services under unified liability frameworks. This restructuring concentrates purchasing authority within integrated well construction divisions and marginalizes pure-play hanger manufacturers lacking service execution capabilities.
Liner Hanger System Market Segmentation
Segmentation in the liner hanger system market reveals how supply concentration, technology maturity, and installation complexity create divergent margin structures across product categories. Understanding these divisions enables targeted positioning against specific procurement consolidation patterns.
Product Type:
Supply concentration for premium metallurgy and actuation mechanisms varies sharply across hanger architectures, with expandable systems consolidating around proprietary alloy licensors while mechanical variants fragment across multiple fabrication sources.
- Mechanical Hangers:Slip-and-cone assemblies using hardened steel wedges anchor liners through radial expansion against casing walls. Permian Basin operators favor these systems for land-based refracturing campaigns where rapid retrieval and lower capital exposure offset pressure limitations.
- Hydraulic Hangers:Piston-actuated setting mechanisms transmit surface pressure to energize seals and slips downhole. Gulf of Mexico shelf installations specify these units where consistent setting force across variable wellbore conditions reduces non-productive time.
- Expandable Hangers:Solid tubulars expanded plastically against formation walls using hydraulic or mechanical swaging tools. Brazil's pre-salt formations and US Lower Tertiary plays drive specification as differential pressure ratings exceed 15,000 psi.
- Inflatable Hangers:Elastomeric bladders inflated against casing ID provide conformable sealing in irregular wellbores. Niche applications include highly deviated laterals and washout zones where rigid slips face engagement failures.
Mechanical hangers absorb the bulk of installed capacity across mature onshore basins; expandable hangers are expanding most quickly as deepwater operators push into HPHT reservoirs.
Technology:
Cost tier differentiation separates commoditized multi-trip installations from premium integrated systems where telemetry bundling commands recurring revenue streams.
- Single-Trip Systems:Liner, hanger, and packer run and set in one deployment operation. North Sea operators prioritize these configurations to minimize rig day rates in high-cost offshore environments.
- Dual-Trip Systems:Liner run separately from hanger setting tool, requiring two distinct deployment sequences. Legacy infrastructure in mature US onshore fields sustues demand where capital constraints favor equipment reuse.
- Integrated Systems:Hanger, packer, and centralizer modules pre-assembled at surface for unified deployment. West Africa deepwater contracts increasingly specify these packages under performance-based liability frameworks.
- Smart Hangers:Embedded fiber-optic or wireless sensors transmitting real-time load, pressure, and temperature data. Santos Basin subsea installations generate predictive analytics subscription revenue that offsets hardware margin compression.
Single-trip systems dominate current procurement volumes; smart hangers are climbing the fastest as barrier verification mandates accelerate digital adoption.
End User:
Customer type determines contract structure complexity, with integrated service bundling favored by national oil companies while independent producers retain discrete hardware purchasing.
- Oil & Gas Producers:Supermajors and national oil companies specifying hanger systems directly for operated assets. Saudi Aramco and Petrobras anchor demand through long-term framework agreements tied to reserve replacement programs.
- Service Companies:Schlumberger, Halliburton, and Baker Hughes procuring hanger hardware for rental fleets and integrated well construction contracts. These entities increasingly specify proprietary expandable metallurgy under exclusive licensing arrangements.
- Contract Operators:Independent entities managing production on behalf of mineral rights holders. US Gulf Coast independents drive replacement cycles for aging mechanical hanger infrastructure in shelf properties.
- Equipment Manufacturers:OEMs sourcing hanger components for assembly into completion system packages. These suppliers concentrate in Houston and Aberdeen clusters serving regional fabrication demand.
Service companies absorb the bulk of procurement volume through rental fleet expansion; contract operators are gaining share fastest as shale revitalization intensifies infrastructure replacement.
Installation Type:
Application environment dictates metallurgy, sealing, and telemetry requirements, with subsea installations commanding 3-4x hardware premiums over equivalent land-based specifications.
- Onshore:Surface-accessible wells permitting conventional rig-based liner deployment. Permian and Eagle Ford basins sustain mechanical hanger demand through extended lateral drilling and refracturing campaigns.
- Offshore:Platform or jackup-supported installations in water depths up to 1,500 feet. US Gulf of Mexico shelf and North Sea mature fields specify hydraulic hangers with rapid-set capabilities to minimize weather window exposure.
- Subsea:Seabed wellhead installations requiring remote intervention compatibility and lifetime barrier verification. Brazil's pre-salt and US Lower Tertiary plays drive expandable hanger specification with integrated monitoring.
- Land-Based:Terminology overlap with onshore; increasingly reserved for unconventional pad drilling configurations. Multi-well pad efficiency demands favor single-trip systems with automated setting verification.
Onshore installations anchor current fleet utilization; subsea deployments are gaining share fastest as pre-salt and Lower Tertiary development accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deepwater exploration contracts concentrate procurement authority among Gulf of Mexico operators and Brazil's national oil company, while North Sea barrier verification mandates accelerate replacement cycles for aging mechanical hanger fleets.
United States
Permian Basin refracturing campaigns and extended lateral drilling intensify mechanical wear on liner hanger infrastructure. The US Bureau of Safety and Environmental Enforcement mandates subsea well containment capabilities that shape hanger design specifications for Gulf of Mexico operators. Houston anchors the national supply base, with fabrication clusters serving both onshore shale and deepwater contract awards.
Brazil
Pre-salt formation development drives specification of expandable hanger metallurgy rated for differential pressures exceeding 15,000 psi. The national petroleum regulator enforces barrier verification standards that constrain product interchangeability with other jurisdictions. The Santos Basin subsea installations generate concentrated demand for integrated monitoring systems that reduce unplanned intervention frequency.
Norway
North Sea mature field redevelopment accelerates replacement of mechanical hanger fleets with hydraulic and smart hanger configurations. The Petroleum Safety Authority enforces rigid certification timelines that extend product qualification cycles. Stavanger and Bergen clusters concentrate engineering expertise for subsea well integrity solutions serving regional operators.
United Kingdom
Decommissioning timelines for aging North Sea assets intersect with remaining production optimization to sustain hanger replacement demand. REACH substance restrictions and EU Green Deal carbon accounting requirements tighten material traceability standards for subsea wellhead components. Aberdeen maintains its position as the primary European procurement hub for integrated hanger-service bundles.
Saudi Arabia
Reserve replacement programs and gas field development anchor long-term framework agreements for liner hanger systems. The national oil company consolidates procurement around integrated well construction contracts that bundle hardware with installation and monitoring services. Dhahran-based engineering centers coordinate specification standards across operated assets.
Liner Hanger System Market Key Industry Players
Technology licensing agreements dominate the current landscape as proprietary expandable metallurgy consolidates vendor relationships. The market structure reflects a tiered configuration with integrated service conglomerates, specialized downhole tool manufacturers, and regional fabrication specialists competing across distinct contract categories. Two strategic archetypes define positioning: full-service well construction providers bundling hanger supply with predictive analytics, and pure-play metallurgy licensors capturing margin through alloy certification exclusivity. M&A activity and capacity expansion in premium nickel-based superalloy supply represent the dominant competitive moves.
Among US-based integrated service providers, Halliburton Company and Baker Hughes Company occupy positions exemplifying the bundled-service archetype, while Schlumberger Limited anchors the proprietary metallurgy tier through its expandable hanger technology licensing arrangements. These three entities collectively represent the competitive concentration around integrated performance-based contracting that is displacing standalone hardware procurement in major exploration basins.
| Leading Market Players |
|---|
| Weatherford International plc |
| TechnipFMC plc |
| Halliburton Company |
| NCS Multistage Holdings, Inc. |
| Dril-Quip, Inc. |
| Schlumberger Limited |
| National Oilwell Varco, Inc. |
| Innovex Downhole Solutions, Inc. |
| Baker Hughes Company |
| Others |
Cost & Logistics Intelligence
Captive metallurgy licensing anchors supply positioning and pricing power for expandable hanger systems, as proprietary nickel-based superalloy agreements lock vendor relationships and insulate premium tiers from commoditization pressure facing mechanical alternatives.
Pricing Analysis
Warranty and predictive analytics bundling separates integrated service contracts from unbundled hardware procurement, with three-tier pricing structure across premium, standard, and economy levels. Premium tiers capture subscription telemetry and barrier verification guarantees; economy tiers compete on per-unit transactional pricing for land-based mechanical installations. Price differentiation stems from certification grade (API RP 100-1 compliance) and after-sales service depth. Cost compression in standard mechanical hangers is intensifying because shale operators prioritize rapid retrieval over longevity. Independent contract operators exhibit highest price sensitivity; national oil companies in Brazil and Saudi Arabia demonstrate lowest.
Supply Chain Analysis
Premium nickel-based superalloy feedstock rests on concentrated specialty steel producers in the United States, Germany, and Japan, with Inconel and Hastelloy variants serving HPHT expandable hanger specifications. Forged slip components and elastomeric seal assemblies draw from precision machining clusters in Houston and Aberdeen. Single-source vulnerability concentrates in superalloy melt capacity, where limited qualified foundries extend lead times during exploration cycle upturns. Distribution runs through integrated service company rental fleets and OEM direct channels to national oil company framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Expandable metallurgy is displacing conventional mechanical architectures across deepwater basins, compressing returns for legacy slip-based manufacturers while elevating sensor-embedded systems as the dominant value-capture mechanism.
For Market Incumbents: Acquire smart hanger telemetry portfolios to anchor integrated service contracts before pure-play sensor vendors consolidate. Secure captive superalloy supply through backward integration into nickel-based foundry capacity or long-term offtake agreements with German and Japanese specialty steel producers. Defend against margin erosion in mechanical hangers by embedding rapid-set verification tools that reduce non-productive time for Permian Basin refracturing campaigns. For New Entrants and Emerging Players: Enter via Angola and Mozambique offshore leasing rounds, where underpenetrated deepwater basins lack established expandable hanger service relationships. Target first-mover positioning in integrated monitoring subscriptions for subsea installations, bundling hardware with predictive analytics to bypass capital-intensive metallurgy licensing barriers. Pursue partnership routes with national oil companies seeking localized fabrication capacity under local content requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated service conglomerates seeking proprietary metallurgy licensing positions. Five-to-ten year viability favors expandable technology licensors with locked customer relationships in Brazil's pre-salt and US Lower Tertiary plays. Watch API RP 100-1 barrier verification mandate expansion as the signal for accelerated replacement cycles and telemetry bundling inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Metallurgy Licensing | Locks long-term service agreements with Petrobras and Saudi Aramco reserve replacement programs. |
| Smart Hanger Telemetry Integration | Captures recurring revenue streams through Santos Basin predictive analytics subscriptions. |
| Superalloy Foundry Backward Integration | Insulates margin from nickel price volatility and extends qualification control timelines. |
| Angola Offshore Leasing Entry | Establishes first-mover positioning before integrated service bundling consolidates procurement. |
| API RP 100-1 Certification Investment | Filters market access for Gulf of Mexico subsea barrier verification compliance. |
Research Approach
Document review covered regulatory filings from the US Bureau of Safety and Environmental Enforcement, Norway's Petroleum Safety Authority, and Brazil's national petroleum regulator, complemented by interviews with drilling engineers, subsea well integrity managers, procurement leads at national oil companies, and aftermarket service directors. Secondary validation drew from API standards documentation, SEC 10-K disclosures from listed service companies, and offshore lease round announcements. Bottom-up installation data triangulated against top-down exploration capital expenditure tracking.
Segmented projections across product type, technology tier, end-user category, and installation environment generated volume and value estimates over the projection horizon. CAGRs derived from regression against historical rig count trajectories, deepwater project sanctioning rates, and replacement cycle intensity in mature basins. Modeling incorporated HPHT well count growth, refracturing campaign density in Permian and Eagle Ford formations, and subsea barrier verification mandate adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity price collapse scenarios or accelerated prescriptive load-testing regime expansion. Projections reflect assumptions around exploration capital allocation stability and metallurgy qualification timeline continuity. A small set of triggers—deepwater project sanctioning delays, nickel superalloy supply disruption, or regulatory divergence between barrier verification frameworks—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Asset Integrity Management Services Market
Oil & Gas
Africa Oilfield Services Market
Oil & Gas
Malaysia Oilfield Services Market
Oil & Gas
Kazakhstan Oil and Gas Midstream Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
Flow Computer Oil Gas Market
Oil & Gas
Mobile Servicing Rig Market
Oil & Gas
Wireline Logging Services Market
Oil & Gas
Sucker Rod Market
Oil & Gas
Oil and Gas Processing Seals Market
Oil & Gas
Whipstocks Market
Oil & Gas
Iron Ore Mining Market
Oil & Gas
Malaysia Oil and Gas Market
Oil & Gas
Vietnam Oil and Gas Midstream Market
Oil & Gas
Clear Brine Fluids Market
Oil & Gas
Digital Oilfield Solutions Market