
 Vietnam Oil and Gas Midstream Market | 2026-2036
Vietnam Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Oil and Gas Midstream Market Analytics
The Vietnam oil and gas midstream sector is pivoting between premium LNG infrastructure and commodity pipeline services as tariff structures diverge. PV Gas Corporation anchors the domestic gas distribution grid through its pipeline monopoly in the southern economic corridor. PetroVietnam leverages integrated control over upstream supply and downstream offtake contracts to sustain margins across volatile cycles. Idemitsu Q8 Petroleum competes in the refined products terminal segment, where import dependency creates volume volatility.
Oil and gas midstream operations encompass the transportation, storage, and processing of hydrocarbons between extraction points and refineries or end-users, with pipeline specifications typically requiring API 5L grade steel rated for pressures exceeding 70 bar in Vietnam's offshore trunk lines. These systems balance supply security for power plants and industrial zones against inventory carrying costs across archipelagic geography. Pipeline infrastructure dominates current capacity but LNG facilities represent the fastest-growing segment as Power Development Plan VIII mandates gas-fired generation expansion. Storage and terminal assets command superior margins due to locational scarcity at deepwater ports, while spot contracting remains thin relative to long-term take-or-pay structures anchored by state-backed offtake.
Vietnam's Ministry of Industry and Trade shapes licensing timelines for cross-border pipelines, while the national technical standards based on QCVN regulations govern safety and environmental compliance for coastal tank farms. The country's central bank and state planning apparatus coordinate foreign participation caps through production sharing contract frameworks. Stakeholders must monitor how domestic gas reserve depletion alters the economics of pipeline reinvestment versus LNG import terminal commitments.
Market Dynamics
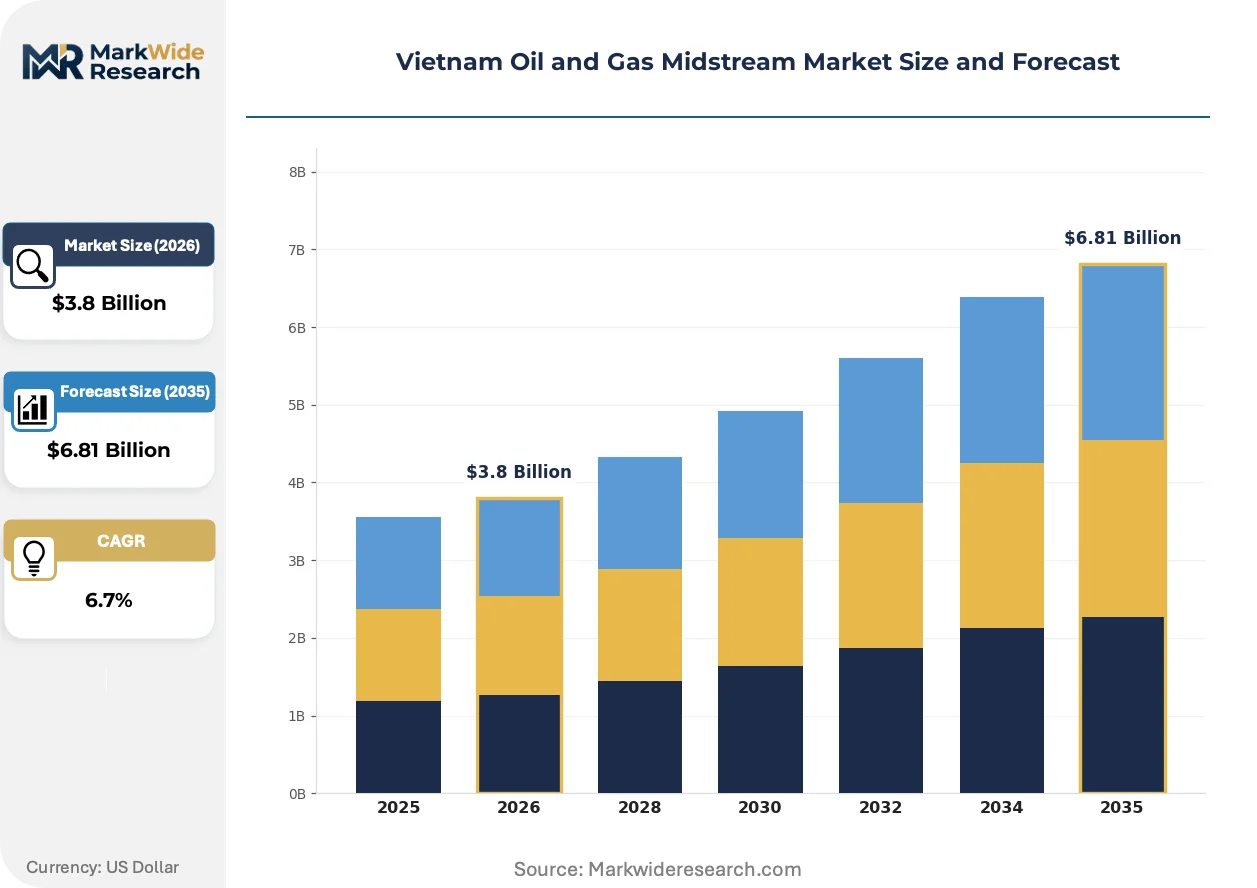
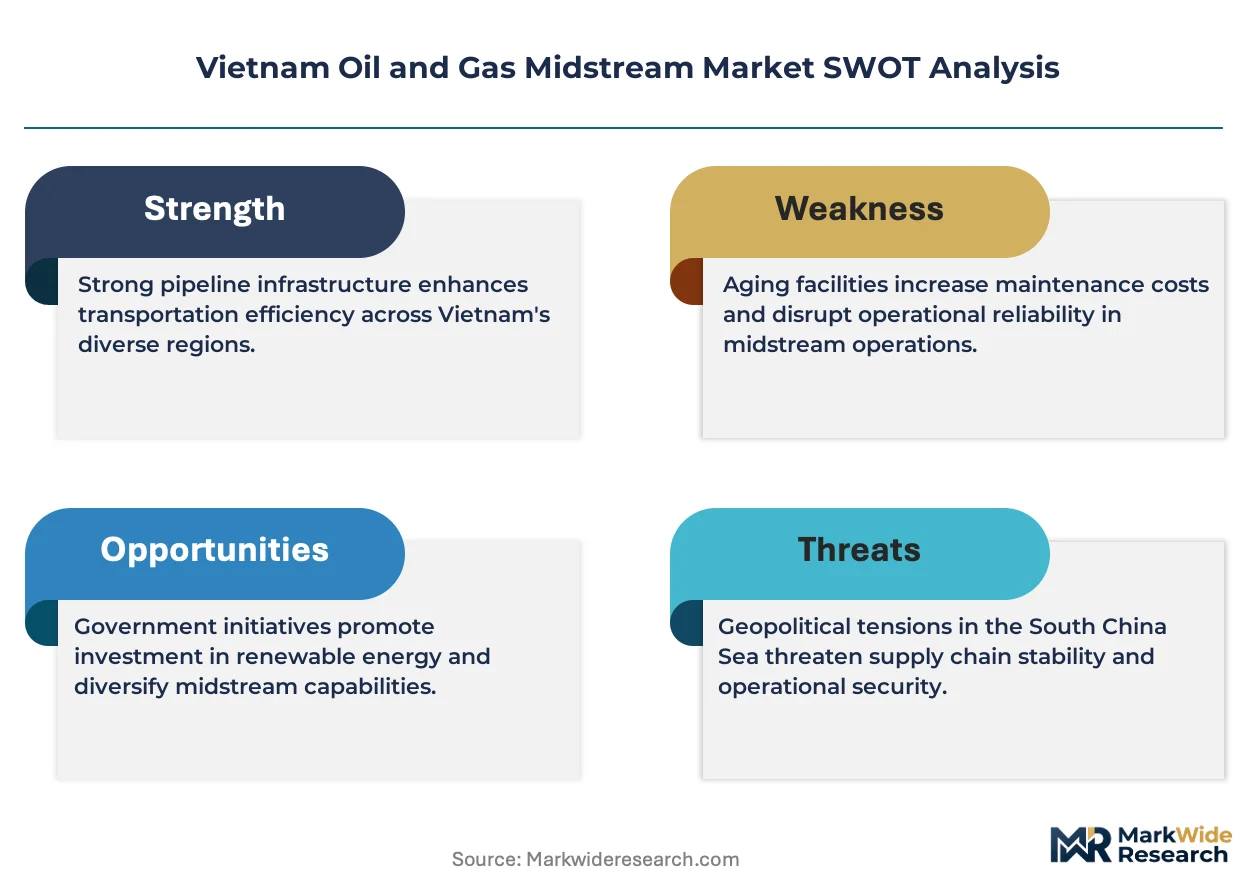
Vietnam's midstream sector faces structural recalibration as domestic gas reserve depletion accelerates the shift from pipeline dependency toward LNG import infrastructure. This transition compresses legacy asset valuations while elevating terminal development premiums.
Growth Catalysts
- Power Development Plan VIII:The national energy framework mandates gas-fired generation expansion, creating guaranteed offtake volumes for new LNG terminals and associated pipeline interconnects.
- Ba Ria-Vung Tau industrial clustering:Deepwater port access and existing petrochemical infrastructure concentrate demand for storage and processing capacity in Vietnam's southern economic corridor.
- Floating storage and regasification units:FSRU technology reduces capital intensity and construction timelines compared to onshore terminals, enabling faster market entry for import infrastructure developers.
Market Restraints
- Domestic reserve depletion:Declining output from mature offshore fields undermines the utilization rates and tariff economics of existing pipeline networks.
- Steel input volatility:API 5L grade steel prices fluctuate with global commodity cycles, compressing margins on new pipeline construction projects.
- Cross-border regulatory friction:The Ministry of Industry and Trade licensing timelines for international pipeline interconnects create uncertainty for regional gas trading schemes.
Strategic Opportunities
- Ca Mau gas hub development:Southwestern Vietnam's proximity to disputed offshore blocks positions the region for potential cross-border pipeline integration if maritime boundary negotiations advance.
- Hydrogen blending infrastructure:Emerging decarbonization pathways create demand for pipeline retrofitting and dedicated hydrogen storage at existing coastal terminals.
- Carbon capture and storage integration:QCVN environmental compliance requirements incentivize terminal operators to develop CCS-ready storage and processing facilities.
Industry Challenges
- Specialized welding and coating certification:Offshore pipeline construction requires ASME and API-certified technicians in short supply within Vietnam's labor market.
- Legacy SCADA system integration:New digital monitoring platforms must interface with decades-old pipeline control architectures without disrupting continuous operations.
- Environmental impact assessment timelines:Coastal tank farm expansions face extended approval cycles under national technical standards governing marine ecosystem protection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Oil and Gas Midstream Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Storage, Compression, Processing Infrastructure Type: Pipeline, Terminal, LNG Facility, Tank Farm Contract Type: Long-Term, Short-Term, Dedicated, Spot Product Type: Crude Oil, Natural Gas, NGL, Refined Products |
| Companies Covered | PV Oil Corporation, PJSC Rosneft Oil Company, Vietnam National Oil and Gas Group (PetroVietnam), Idemitsu Q8 Petroleum Limited Liability Company (IQ8), Perenco SA, Vietnam Gas Corporation (PV GAS), Vietsovpetro, Cửu Long Joint Operating Company (CLJOC), Binh Son Refining and Petrochemical Company Limited (BSR), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Oil and Gas Midstream Market Evolving Landscape
Digitalization and decarbonization mandates are restructuring how midstream assets are monitored, maintained, and monetized across Vietnam's archipelagic geography. Technology deployment now favors modular, rapidly deployable solutions over permanent infrastructure commitments.
Advanced pipeline integrity management systems utilizing fiber-optic sensing and drone-based corrosion detection are integrating real-time monitoring capabilities across Vietnam's offshore trunk lines. PV Gas Corporation and terminal operators deploy these platforms to reduce manual inspection frequency and extend asset life cycles. The technology is integrating predictive maintenance protocols that compress unplanned downtime and shift operational expenditure structures toward software subscriptions.
Vietnam's Ministry of Industry and Trade is tightening QCVN safety and environmental standards for coastal hydrocarbon storage facilities, mandating secondary containment upgrades and vapor recovery systems. The regulation compresses allowable emissions thresholds and elevates capital requirements for tank farm operators. Smaller import terminal projects in central provinces face compliance timeline pressures that favor larger, better-capitalized developers with established environmental management systems.
Power generation utilities are consolidating procurement through long-term take-or-pay contracts rather than spot market purchases, reversing earlier diversification attempts. This concentration transfers volume risk to midstream infrastructure owners while securing pipeline and terminal utilization rates. The shift is most visible in the Nam Con Son corridor, where state-backed electricity offtakers now dominate contracting negotiations with gas distributors.
Vietnam Oil and Gas Midstream Market Segmentation
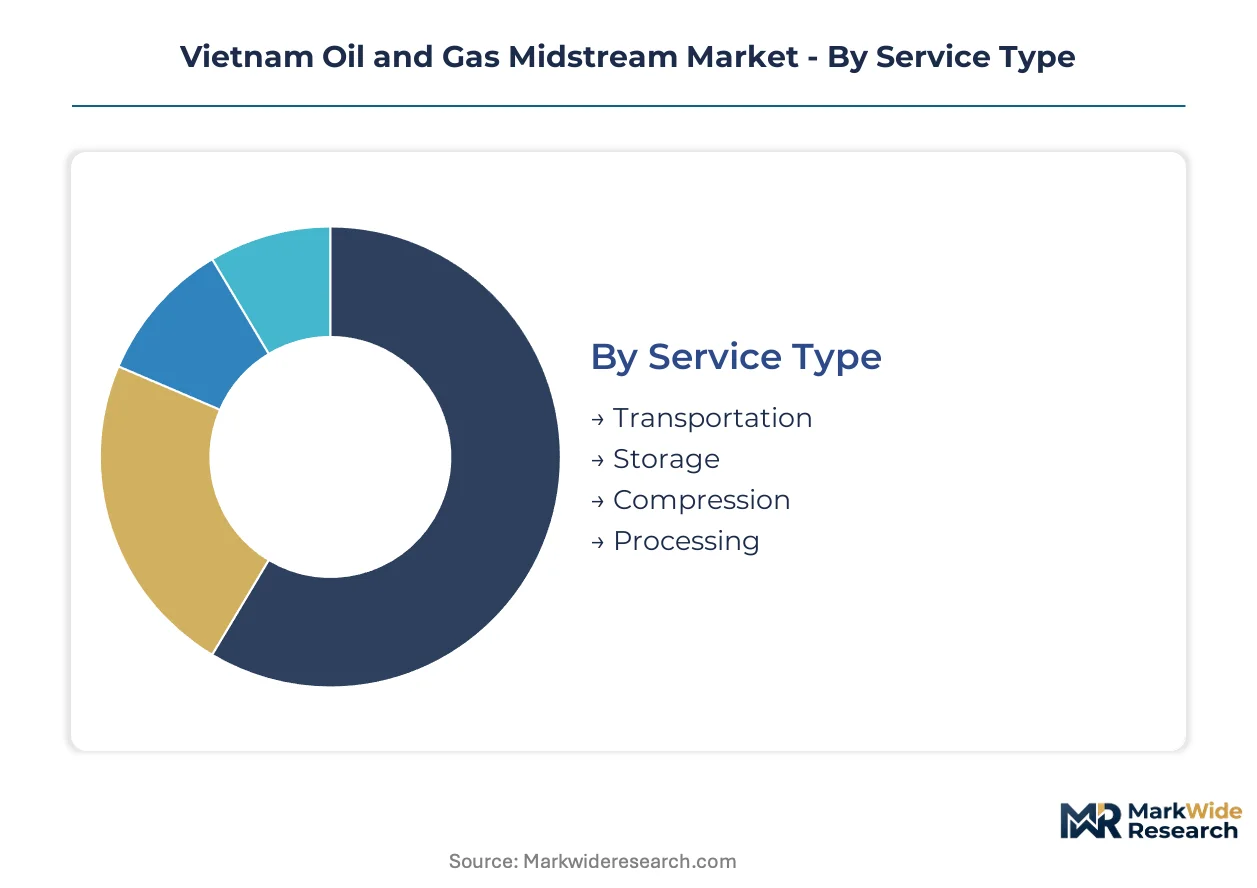
Vietnam's midstream infrastructure requires precise segmentation to capture how capital cycles differ between legacy pipeline reinvestment and greenfield LNG terminal construction. Each dimension reveals distinct margin structures, contract tenors, and regulatory exposure that shape investment allocation.
Service Type:
Replacement cycles for compression and processing equipment are shortening as domestic gas quality degrades, forcing operators to prioritize service segments with upgrade visibility over greenfield transportation.
- Transportation:Pipeline trunk systems move hydrocarbons across Vietnam's archipelagic terrain using API 5L grade steel rated for pressures exceeding 70 bar. Demand concentrates in the Nam Con Son corridor serving power generation utilities, though reserve depletion is compressing utilization rates on legacy offshore lines.
- Storage:Coastal tank farms and underground caverns balance supply security against inventory carrying costs, with deepwater port access at Ba Ria-Vung Tau commanding locational scarcity premiums. The segment gains from LNG import expansion under Power Development Plan VIII mandates.
- Compression:Booster stations maintain flow pressure across Vietnam's declining offshore fields, requiring specialized maintenance as reservoir pressure drops accelerate.
- Processing:Gas treatment and fractionation facilities remove contaminants and separate NGL streams, with margins tied to feedstock quality deterioration from mature basins.
Volume placements concentrate in Transportation; the faster expansion belongs to Storage.
Infrastructure Type:
Cost tier separation distinguishes permanent onshore commitments from modular floating solutions, with capital intensity dictating developer entry barriers.
- Pipeline:Subsea and onshore trunk lines dominate current capacity but face stranded asset risk as domestic reserves deplete, requiring selective reinvestment toward LNG interconnects.
- Terminal:Import and export terminals at deepwater ports handle vessel-to-shore transfers, with refined products terminals experiencing volume volatility from import dependency.
- LNG Facility:Floating storage and regasification units reduce construction timelines versus onshore terminals, enabling faster market entry as FSRU technology gains preference in Vietnam's southern provinces.
- Tank Farm:Coastal storage arrays face extended environmental approval cycles under QCVN marine ecosystem standards, favoring larger developers with established compliance systems.
Volume placements concentrate in Pipeline; the faster expansion belongs to LNG Facility.
Contract Type:
Customer type stratification separates state-backed offtakers seeking supply security from traders capturing price volatility, with contract tenor directly determining revenue predictability.
- Long-Term:Take-or-pay structures spanning 15-20 years anchor pipeline and terminal economics, transferring volume risk to midstream owners while securing utilization for state-backed power utilities.
- Short-Term:Annual or multi-year agreements offer flexibility for industrial buyers with variable demand profiles, though thin spot markets limit liquidity in Vietnam's nascent gas trading environment.
- Dedicated:Exclusive capacity reservations for single offtakers support bespoke infrastructure investments, common in petrochemical cluster developments.
- Spot:Single-cargo transactions remain underdeveloped due to limited domestic gas trading infrastructure and regulatory constraints on third-party pipeline access.
Volume placements concentrate in Long-Term; the faster expansion belongs to Dedicated.
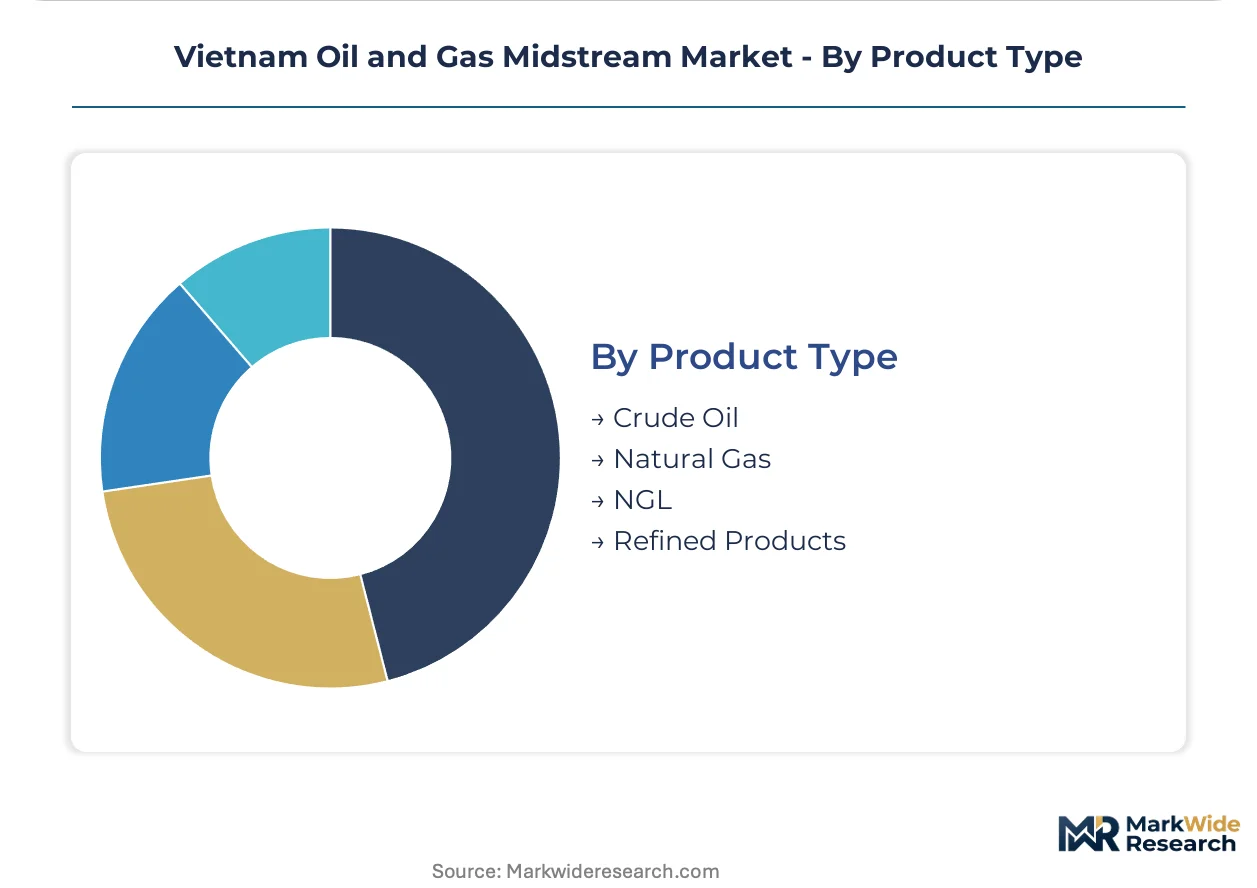
Product Type:
Application-based demand splits between power generation feedstocks and industrial feedstocks, with each product commanding distinct storage specifications and tariff structures.
- Crude Oil:Storage and marine terminal handling for upstream production and import volumes, with Dung Quat refinery offtake patterns influencing coastal tank farm utilization.
- Natural Gas:Pipeline gas and LNG regasification serving power plants and industrial zones, representing the dominant revenue stream as electricity demand climbs fastest.
- NGL:Fractionated liquids for petrochemical feedstock, with demand tied to Ca Mau gas hub development and potential cross-border processing integration.
- Refined Products:Gasoline, diesel, and fuel oil terminals face import dependency volatility, with Idemitsu Q8 Petroleum competing in this fragmented segment.
Volume placements concentrate in Natural Gas; the faster expansion belongs to Refined Products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ba Ria-Vung Tau province anchors Vietnam's midstream infrastructure concentration, with deepwater port access and petrochemical clustering driving capital allocation toward the southern economic corridor.
Southeast Region
Power generation utilities in the Nam Con Son corridor expand gas offtake contracts for electricity feedstock under Power Development Plan VIII mandates. The Ministry of Industry and Trade coordinates licensing for cross-border pipeline interconnects from this zone. Ho Chi Minh City industrial zones and surrounding provinces concentrate demand for LNG terminal capacity and refined products storage.
Southwest Region
Ca Mau gas hub development positions the Mekong Delta for potential cross-border pipeline integration pending maritime boundary negotiations. The national technical standards based on QCVN regulations govern environmental compliance for coastal processing facilities in this zone. Bac Lieu and Ca Mau provinces host emerging LNG import terminal projects serving regional power plants.
Central Region
Thanh Hoa and Nghe An provinces develop coastal storage capacity for refined products distribution to northern industrial zones. The central bank and state planning apparatus coordinate foreign participation caps through production sharing contract frameworks affecting terminal investments. Dung Quat refinery offtake patterns influence tank farm utilization along the central coastline.
Northern Region
Hai Phong port infrastructure supports crude oil import and refined products handling for Red River Delta manufacturing clusters. Environmental impact assessment timelines extend approval cycles for coastal tank farm expansions under marine ecosystem protection standards. Quang Ninh province hosts storage facilities serving regional cement and power generation feedstock demand.
South Central Coast
Khanh Hoa and Binh Thuan provinces attract floating storage and regasification unit deployments due to shorter construction timelines versus onshore terminals. QCVN safety standards mandate secondary containment upgrades for hydrocarbon storage facilities in this developing zone. Ninh Thuan province's power generation expansion creates anchor demand for new gas import infrastructure.
Vietnam Oil and Gas Midstream Market Competitive Landscape
Premium-margin players sit above commodity-margin players across infrastructure ownership and contract tenor dimensions, with state-backed entities controlling pipeline monopolies while international traders compete in fragmented terminal segments. The market structure consolidates around national champions with integrated upstream-downstream positions, supplemented by specialized foreign operators in niche service categories. Three archetypes dominate: state-owned integrated energy groups, international petroleum traders with terminal assets, and offshore production specialists with processing capabilities. Competitive moves center on LNG terminal capacity expansion and long-term offtake contract consolidation with power utilities.
Within the state-integrated tier, Vietnam National Oil and Gas Group and Vietnam Gas Corporation anchor domestic infrastructure control through pipeline networks and coastal storage assets. Among international terminal operators, Idemitsu Q8 Petroleum occupies a position in refined products handling, while PJSC Rosneft Oil Company exemplifies cross-border upstream-midstream integration through production sharing arrangements. These entities represent distinct strategic positioning across the tariff and volume risk spectrum.
| Leading Market Players |
|---|
| PV Oil Corporation |
| PJSC Rosneft Oil Company |
| Vietnam National Oil and Gas Group (PetroVietnam) |
| Idemitsu Q8 Petroleum Limited Liability Company (IQ8) |
| Perenco SA |
| Vietnam Gas Corporation (PV GAS) |
| Vietsovpetro |
| Cửu Long Joint Operating Company (CLJOC) |
| Binh Son Refining and Petrochemical Company Limited (BSR) |
| Others |
Value Network & Pricing Analysis
Long-term take-or-pay contract premiums diverge sharply from spot market thinness across Vietnam's midstream infrastructure, with tariff structures for pipeline capacity and LNG terminal slots commanding materially different supply chain configurations. State-backed power utilities anchor pricing power through guaranteed offtake volumes, while international traders face commodity margin compression in refined products terminals where import dependency creates volume volatility.
Pricing Analysis
Throughput-based pricing anchors LNG terminal economics, with regasification fees tied to guaranteed send-out volumes under 15-20 year contracts. Tariff differentiation rests on locational scarcity at deepwater ports and contract tenor length, with Ba Ria-Vung Tau facilities commanding premiums over central province alternatives. Cost compression in pipeline services intensifies as domestic reserve depletion erodes utilization rates on legacy offshore trunk lines. Industrial zones exhibit highest price sensitivity, while state-backed electricity offtakers prioritize supply security over rate negotiation.
Supply Chain Analysis
Direct-to-utility channels handle anchor demand from Power Development Plan VIII-mandated gas-fired generation expansion. API 5L grade steel supply concentrates in China, South Korea, and Japan, with coating and welding certification dependencies resting on ASME-qualified technician pools. Single-source vulnerability permeates specialized SCADA system integration for legacy pipeline control architectures. Distribution runs through state-controlled pipeline networks and international vessel-to-shore terminal operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's midstream capacity expansion lags Power Development Plan VIII-mandated demand growth, with LNG import terminal commissioning timelines propping infrastructure pricing premiums. Domestic gas reserve depletion accelerates the supply-constrained transition from pipeline dependency toward import infrastructure.
For Market Incumbents: Cement pipeline-to-LNG interconnect investments in the Nam Con Son corridor before reserve depletion compresses legacy asset valuations further. Prioritize long-term offtake consolidation with state-backed electricity utilities to lock in utilization rates against emerging FSRU competition. Vertical integration into floating storage and regasification technology licensing defends margin position against modular market entrants.
For New Entrants and Emerging Players: Launch via floating storage and regasification unit deployments in South Central Coast provinces where shorter construction timelines offset established terminal incumbency. Target Ca Mau gas hub development for potential cross-border pipeline integration as maritime boundary negotiations advance. White-space concentration sits with hydrogen blending infrastructure retrofitting and carbon capture-ready terminal design.
For Investors and Strategic Acquirers: Re-rating potential sits with LNG terminal developers holding secured power utility offtake under Power Development Plan VIII mandates given guaranteed volume visibility. Long-term viability favors assets with locational scarcity at deepwater ports and established QCVN environmental compliance systems. Monitor domestic gas production decline rates as the inflection signal for pipeline versus import infrastructure allocation shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| FSRU Capacity Deployment | Floating regasification units accelerate market entry in South Central Coast provinces facing power generation expansion deadlines. |
| Long-Term Offtake Consolidation | Take-or-pay contracts with state-backed electricity utilities transfer volume risk to midstream owners while securing utilization. |
| Hydrogen Blending Infrastructure | Pipeline retrofitting positions legacy assets for emerging decarbonization pathways under tightening QCVN environmental standards. |
| Carbon Capture Integration | CCS-ready terminal design satisfies coastal tank farm compliance requirements while differentiating premium storage offerings. |
| Cross-Border Pipeline Development | Ca Mau gas hub positioning captures potential regional integration if maritime boundary negotiations with neighboring states advance. |
Research Methodology
Multi-period observation of LNG terminal commissioning timelines, pipeline utilization rates, and power utility procurement patterns anchored the trend analysis, supplemented by interviews with infrastructure developers and regulatory officials. Primary fieldwork engaged EPC contractors, IPP project developers, utility planning officers, and Ministry of Industry and Trade licensing administrators. Secondary validation drew from project development databases, customs records for API 5L grade steel imports, and QCVN regulatory filings. Bottom-up capacity build-up triangulated against top-down power demand projections across the analysis window.
Segment-weighting applied infrastructure type, contract tenor, and regional demand concentration dimensions throughout the modeling period. Service type splits between transportation, storage, compression, and processing captured divergent capital cycle dynamics. Product type stratification isolated natural gas pipeline flows from LNG regasification and refined products terminal volumes. CAGRs derived from capacity expansion pipelines cross-referenced against Power Development Plan VIII implementation schedules and domestic reserve depletion curves.
Regulatory licensing delays, offshore exploration success rates, and regional maritime boundary negotiation outcomes are the dominant revision risks to infrastructure deployment timelines. Forecasts reflect documented assumptions regarding state-backed offtake contract conversion rates and FSRU technology adoption curves. Practitioners should monitor Ministry of Industry and Trade cross-border pipeline licensing decisions and QCVN environmental standard amendment proposals for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
North America Oil and Gas Electric Submersible Pump Market
Oil & Gas
Middle East and Africa Early Production Facility Market
Oil & Gas
Subsea Manifolds Market
Oil & Gas
Drilling Mud Desander and Desilter Market
Oil & Gas
Global Drilling Jars Market
Oil & Gas
Well Test Market
Oil & Gas
South and Central America Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Australia Oil and Gas Upstream Market
Oil & Gas
AI in Oil and Gas Market
Oil & Gas
Oilfield Roller Chain Market
Oil & Gas
Romania Oil and Gas Market
Oil & Gas
Well Completion Equipment Service Market
Oil & Gas
Asia-Pacific Oilfield Chemicals Market
Oil & Gas
Europe Oilfield Equipment Rental Services Market
Oil & Gas
Blockchain in Oil and Gas Market
Oil & Gas
Vietnam Oil and Gas Market