
 United States Artificial Lift Systems Market | 2026-2036
United States Artificial Lift Systems Market Size, Share, and Industry Trends Forecast 2026-2036
United States Artificial Lift Systems Market Analytics
Carbon fiber-reinforced polymer (CFRP) rod technology is consolidating as a replacement for traditional steel sucker rods in Permian Basin rod lift installations. Baker Hughes Company leverages its integrated manufacturing footprint to supply corrosion-resistant rod strings across West Texas and southeastern New Mexico. ChampionX anchors its market position through chemical-injection compatibility with advanced polymer rod designs. Schlumberger Limited competes by bundling diagnostics software with its artificial lift hardware portfolios.
Artificial lift systems are mechanical or electromechanical devices installed in oil and gas wells to increase reservoir pressure and sustain hydrocarbon flow to surface facilities, typically operating at depths exceeding 10,000 feet with power ratings from 50 to 1,500 horsepower depending on well architecture. Rod lift remains the dominant type across mature onshore fields where beam pump units account for the majority of installed base, while electrical submersible pump systems command premium margins in high-volume offshore and deep unconventional horizontals requiring continuous variable speed operation. Gas lift applications are expanding fastest in gassy shale plays where producers optimize gas handling capacity under tightening venting regulations. Progressive cavity pump demand concentrates in heavy oil thermal recovery operations where positive displacement mechanisms handle viscous crude more efficiently than dynamic pump types.
The Environmental Protection Agency enforces methane emissions standards under New Source Performance Standards that directly influence gas lift system design and leak detection protocol requirements for onshore production facilities. The Pipeline and Hazardous Materials Safety Administration regulates wellhead equipment integrity, while state regulators in Texas and New Mexico impose additional casing and venting rules that shape artificial lift specification and maintenance scheduling. OSHA process safety management requirements govern offshore platform lift system installations in federal Gulf of Mexico waters. Stakeholders must monitor evolving EPA methane rulemakings and state-level flaring restrictions to anticipate shifts in lift technology preference between gas lift and electrical submersible platforms.
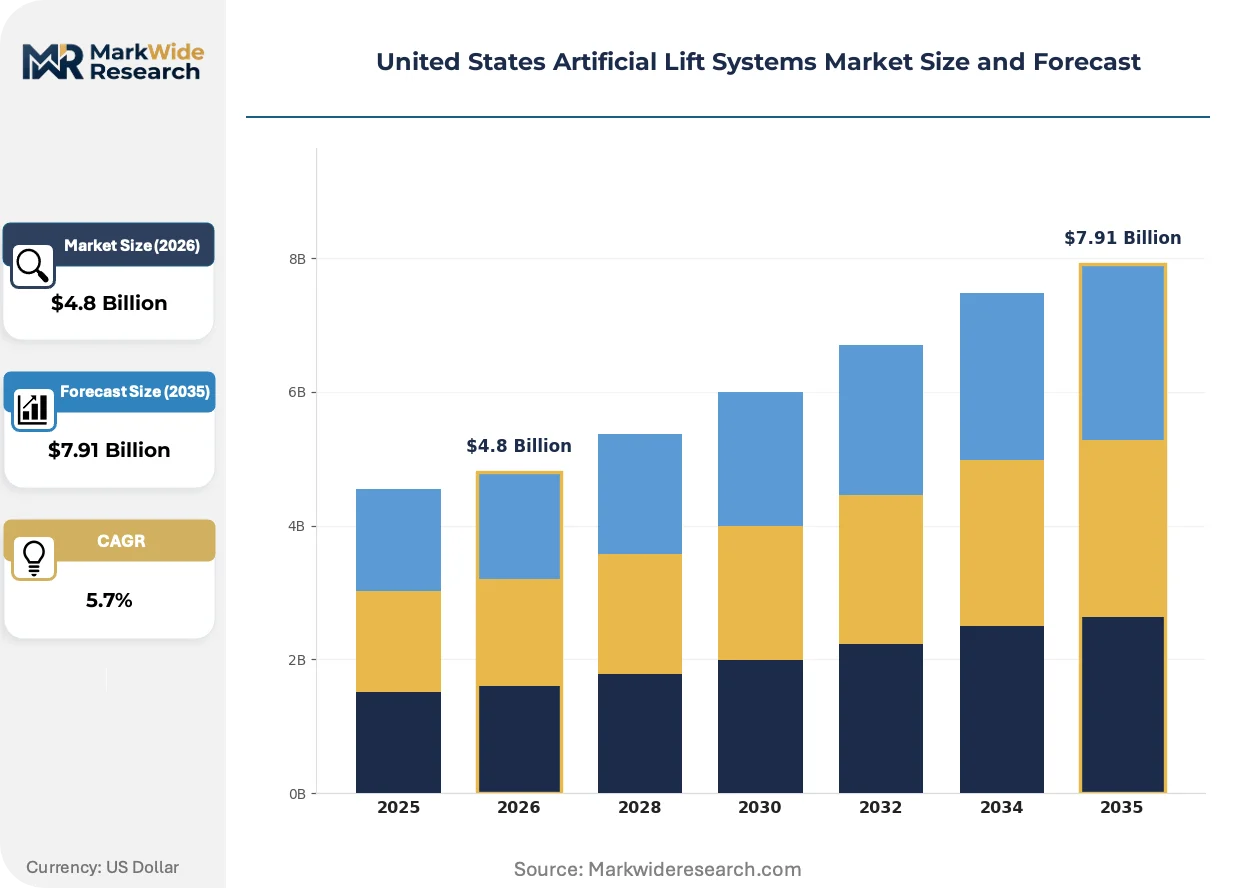
Market Dynamics
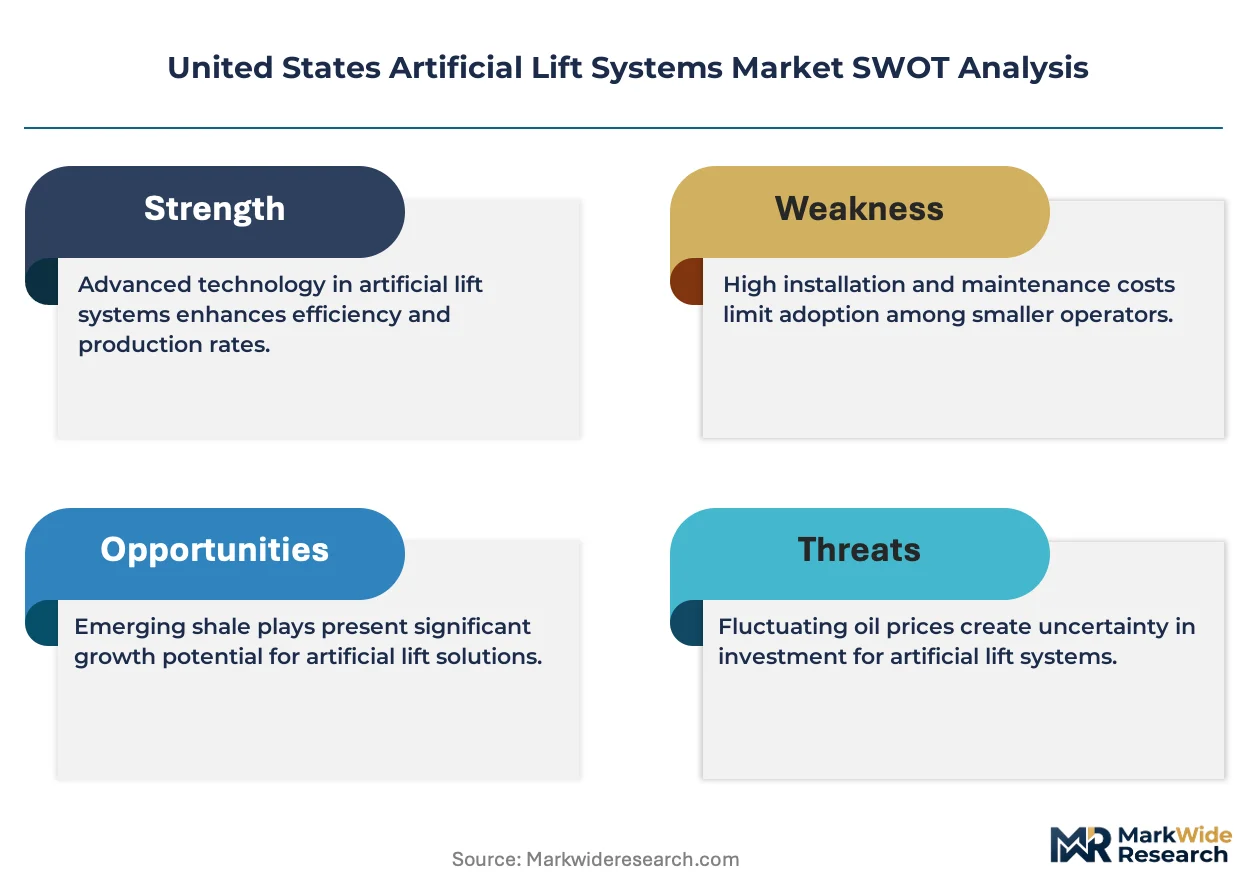
Permian Basin shale operators are accelerating artificial lift redeployment as steep initial production declines force earlier transitions from natural flow to mechanical lift, tightening the link between well age and equipment specification cycles.
Growth Catalysts
- EPA Methane Standards:New Source Performance Standards mandate reduced venting from rod lift and gas lift systems, compelling producers to upgrade seal designs and leak detection protocols across Texas and New Mexico operations.
- Carbon Fiber Rod Adoption:CFRP sucker rods deliver corrosion resistance and weight reduction that extends run life in high-salinity West Texas formations, cutting workover frequency for marginal well operators.
- Delaware Sub-basin Density:The densest concentration of horizontal completions in North America generates concentrated demand for high-horsepower ESP installations in gassy, high-drawdown environments.
Market Restraints
- Steel Price Volatility:Beam pump units and traditional rod strings remain exposed to scrap steel and alloy input cost swings that compress fabrication margins for domestic manufacturers.
- Permian Supply Concentration:Over 60% of domestic artificial lift demand clusters in a two-state corridor, creating geographic revenue vulnerability to regional drilling pauses or pipeline constraints.
- Gas Lift Substitution Ceiling:Electrical submersible pumps face technical limits in ultra-gassy horizontals where gas locking degrades motor cooling, preserving gas lift market share despite regulatory pressure.
Strategic Opportunities
- Appalachian Basin Expansion:Marcellus-Utica gas producers under Pennsylvania and Ohio venting rules present untapped retrofit demand for closed-loop gas lift systems with integrated plunger lift hybrids.
- Digital Twin Integration:Convergence of downhole sensor arrays with cloud-based predictive analytics enables remote rod load monitoring that shifts maintenance from calendar-based to condition-based scheduling.
- IRA Manufacturing Credits:Clean energy tax provisions incentivize domestic production of permanent magnet motors for ESP systems, reshaping supply chain geography toward Texas and Oklahoma assembly plants.
Industry Challenges
- Downhole Electronics Reliability:High-temperature ESP motor controllers and variable speed drives suffer elevated failure rates in 300°F-plus Bakken and Permian bottom-hole conditions, stretching warranty exposure for service companies.
- Legacy Beam Pump Interoperability:Retrofit of smart control systems onto 50-year-old pumping unit infrastructure requires custom bracket fabrication and power distribution upgrades that extend installation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Artificial Lift Systems Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Rod Lift, Gas Lift, Electrical Submersible Pump, Progressive Cavity Pump Application: Onshore, Offshore, Heavy Oil, Natural Gas Production End User: Oil & Gas Operators, Service Companies, Independent Producers, Government Entities Installation: New Installation, Retrofit, Maintenance, Inspection |
| Companies Covered | Schlumberger Limited, Baker Hughes Company, Halliburton Company, Weatherford International, ChampionX, NOV Inc., JJ Tech, Dover Corporation, DistributionNow, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Artificial Lift Systems Market Evolving Landscape
Artificial lift technology is pivoting toward materials substitution and closed-loop gas handling as regulatory pressure on methane intensity collides with unconventional well economics demanding longer run life and lower intervention costs.
Carbon fiber-reinforced polymer sucker rods are overtaking steel in Permian rod lift installations where corrosive formation waters and high cyclic loading previously drove frequent rod string failures. Delaware and Midland sub-basin operators now specify CFRP strings for new completions and workover replacements, compressing the addressable market for conventional alloy rod suppliers while extending mean time between failures in high-salinity environments.
OSHA process safety management requirements for offshore Gulf of Mexico platforms are tightening inspection intervals for gas lift compressor packages and wellhead safety valves. Platform operators must document functional testing of surface-controlled subsurface safety valves on quarterly rather than annual cycles, driving demand for automated test skids and electronic reporting systems that reduce manual technician exposure.
Service contract structures are fragmenting as Permian independents unbundle ESP installation from full-service maintenance agreements, preferring component-level procurement with third-party repair shops. This disintermediation concentrates in West Texas private equity-backed producers optimizing cash flow through direct sourcing of pumps, motors, and cables rather than integrated lift system packages.
United States Artificial Lift Systems Market Segmentation
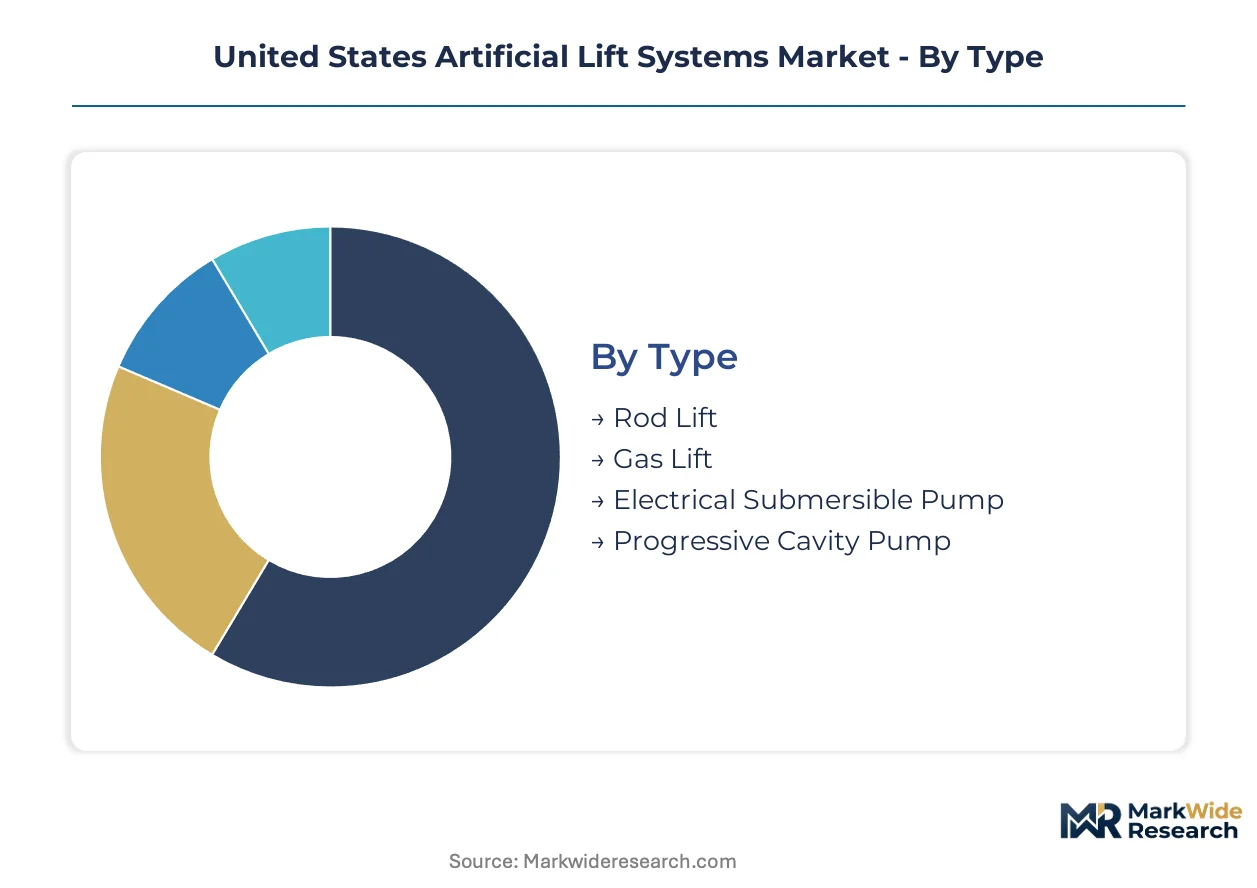
Artificial lift system specification cycles in the United States tighten around well decline curves and regulatory compliance windows, making segment boundaries fluid across type, application, and installation mode. Producers select lift technology based on gas-oil ratio, reservoir depth, and capital recovery timelines rather than fixed category definitions.
Type:
Upgrade and replacement cycles dominate type-level procurement as Permian Basin operators retire steel rod strings and gas-limited ESP installations ahead of failure.
- Rod Lift:Beam pump units with surface-mounted prime movers dominate mature onshore fields where mechanical simplicity offsets power efficiency limitations. Delaware and Midland sub-basin independents specify carbon fiber-reinforced polymer rods to cut workover frequency in high-salinity formations.
- Gas Lift:Compressed gas injection through mandrel valves handles high-gas-liquid-ratio horizontals where ESP gas locking would degrade motor cooling. Texas and New Mexico operators under EPA methane standards prioritize closed-loop compressor packages with integrated plunger lift hybrids.
- Electrical Submersible Pump:Multi-stage centrifugal pumps with variable speed drives command premium positioning in high-drawdown unconventional wells requiring continuous flow modulation.
- Progressive Cavity Pump:Positive displacement helical rotor-stator pairs concentrate in thermal heavy oil recovery where viscous crude exceeds dynamic pump handling limits.
Rod lift sits at the top of the volume ranking, with gas lift climbing the fastest as venting regulations tighten.
Application:
Cost tier stratification separates premium offshore installations from standard onshore deployments and economy-grade marginal well retrofits.
- Onshore:Surface pump jack and ESP installations across Permian, Bakken, and Appalachian basins account for the dominant equipment count. Texas Railroad Commission flaring rules shape gas lift specification cycles in the Delaware sub-basin.
- Offshore:Platform-mounted ESP and gas lift systems in federal Gulf of Mexico waters face OSHA process safety management inspection intervals that compress maintenance scheduling. Bureau of Safety and Environmental Enforcement well control rules mandate redundant subsurface safety valve configurations.
- Heavy Oil:Thermal recovery operations in California's Kern County and Alaska's North Slope deploy progressive cavity pumps and rod lift with heated flowlines to manage viscosity.
- Natural Gas Production:Dewatering applications in mature gas fields use ESP and rod lift to unload liquids and restore gas flow, particularly in the Appalachian Basin under Pennsylvania venting restrictions.
Onshore deployments capture the largest equipment count, with offshore applications maintaining the steepest margin structure.
End User:
Customer type determines procurement sophistication, from integrated majors with captive engineering to independents sourcing through distributors.
- Oil & Gas Operators:Supermajors and large independents with in-house artificial lift engineering teams specify integrated systems with predictive diagnostics. ExxonMobil and Chevron operations in the Permian Basin drive demand for high-horsepower ESP installations with permanent magnet motors.
- Service Companies:Schlumberger, Halliburton, and Baker Hughes artificial lift divisions bundle installation with maintenance contracts, though Permian independents increasingly disaggregate these services.
- Independent Producers:Private equity-backed operators in West Texas optimize cash flow through direct component sourcing and third-party repair shop relationships.
- Government Entities:State land offices and federal mineral managers specify lift equipment for royalty-bearing wells, particularly in New Mexico where State Land Office leases require methane monitoring compliance.
Oil and gas operators represent the largest procurement volume, with independent producers expanding share fastest through unbundled sourcing.
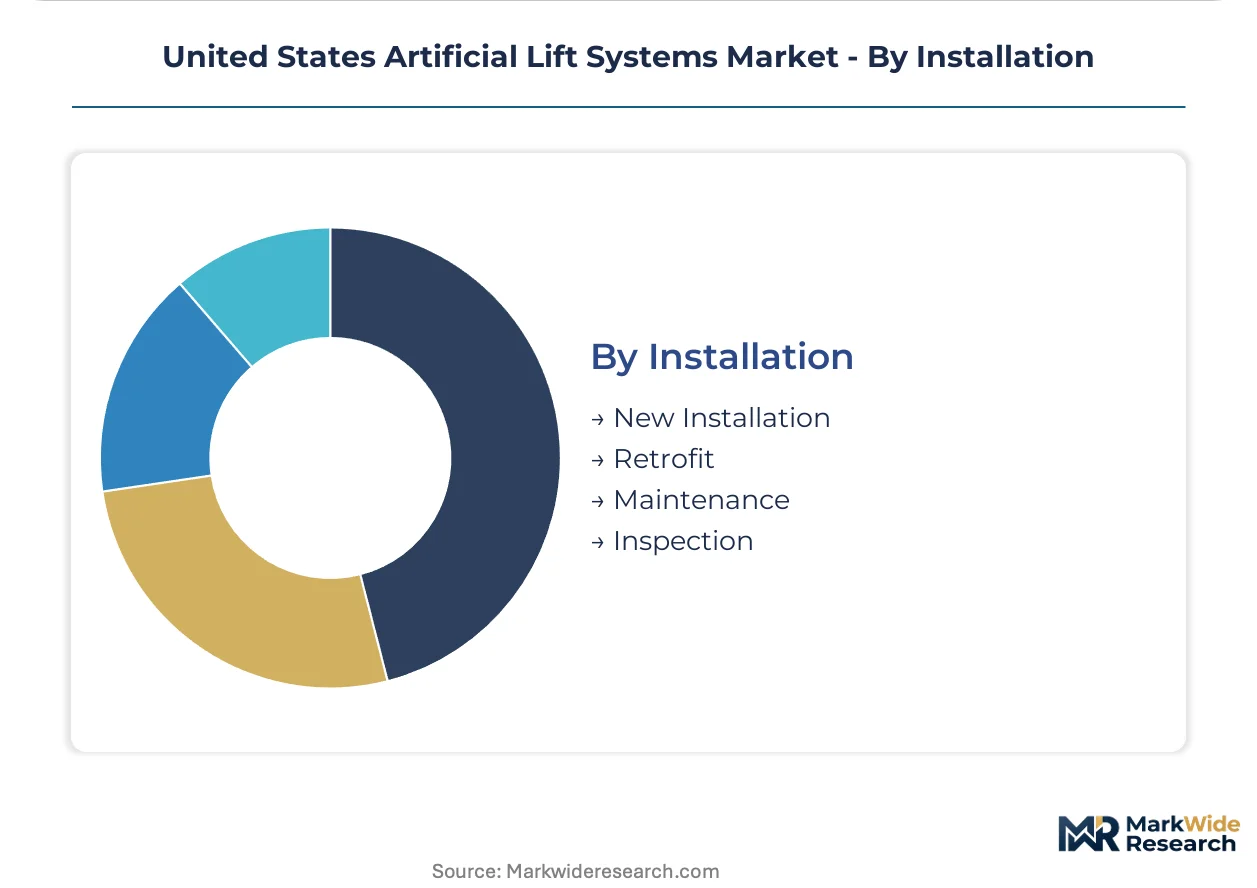
Installation:
Volume concentration in new completions versus retrofit and maintenance reflects drilling cycle timing and well inventory age.
- New Installation:Greenfield lift system deployment tracks horizontal completion counts in the Permian and Appalachian basins. Delaware sub-basin producers specify ESP-ready well architecture even when initial natural flow delays pump installation.
- Retrofit:Conversion from rod lift to gas lift or ESP accelerates as gassy shale wells mature and initial production declines steepen. EPA methane rulemakings force seal upgrades and leak detection retrofits across existing rod lift installations.
- Maintenance:Workover frequency for rod string replacement and ESP motor pulls generates recurring service revenue, particularly for carbon fiber rod suppliers with extended warranty programs.
- Inspection:Regulatory-mandated testing of surface-controlled subsurface safety valves and gas lift compressor integrity drives demand for automated test skids and electronic documentation systems.
Maintenance commands the largest recurring revenue pool, with retrofit activity expanding most quickly as shale well inventories age.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin anchors United States artificial lift demand through concentrated horizontal completion activity and aggressive well redeployment cycles.
Texas
The Delaware and Midland sub-basins generate the densest rod lift and ESP installation counts nationwide. EPA New Source Performance Standards mandate reduced venting from rod lift systems, compelling seal upgrades across West Texas operations. Midland-Odessa field service clusters support rapid workover response for carbon fiber rod deployments.
New Mexico
State Land Office methane monitoring requirements shape lift specification for royalty-bearing wells in the southeastern counties. The Oil Conservation Division flaring rules accelerate gas lift adoption in gassy horizontal completions. Hobbs and Carlsbad anchor equipment staging and technician deployment networks.
North Dakota
Bakken shale operators confront 300°F-plus bottom-hole temperatures that degrade ESP motor controllers and stretch warranty exposure. The North Dakota Industrial Commission gas capture targets push producers toward gas lift in high-gas-liquid-ratio wells. Williston Basin service yards specialize in high-temperature pump rebuilds.
Pennsylvania
Marcellus-Utica dewatering applications drive ESP and rod lift demand for liquid unloading in mature gas fields. Department of Environmental Protection venting restrictions create retrofit opportunity for closed-loop gas lift systems. Pittsburgh-area equipment distributors serve Appalachian Basin independents with plunger lift hybrid configurations.
California
Kern County thermal heavy oil operations deploy progressive cavity pumps and heated rod lift for viscous crude management. CalGEM surface expression regulations tighten wellbore integrity standards that influence lift system maintenance scheduling. Bakersfield service companies specialize in thermal recovery pump specifications.
United States Artificial Lift Systems Market Competitive Landscape
Portfolio diversification dominates the current landscape as integrated oilfield service providers bundle artificial lift hardware with diagnostics and chemical solutions. The vendor base concentrates around three strategic archetypes: full-service conglomerates with captive manufacturing, specialized lift system fabricators with regional density, and component suppliers selling through distribution channels. M&A activity and vertical integration into permanent magnet motor production represent the primary competitive vectors reshaping supply chain geography.
Among integrated service conglomerates, Schlumberger Limited, Baker Hughes Company, and Halliburton occupy positions that exemplify full-lifecycle bundling from installation through predictive maintenance. These entities anchor the premium tier through combined hardware and software portfolios. ChampionX represents the specialized archetype with chemical-injection compatibility positioning. The competitive terrain rewards backward integration into corrosion-resistant materials and permanent magnet supply chains as IRA manufacturing credits reshape domestic assembly economics.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Baker Hughes Company |
| Halliburton Company |
| Weatherford International |
| ChampionX |
| NOV Inc. |
| JJ Tech |
| Dover Corporation |
| DistributionNow |
| Others |
Value Network & Pricing Analysis
Permian Basin independents concentrate procurement authority for artificial lift systems, forcing suppliers toward project-based contracting with component-level unbundling rather than integrated service packages. This buyer consolidation in West Texas and southeastern New Mexico compresses margins on standard rod lift and ESP installations while preserving premium pricing for corrosion-resistant materials and predictive diagnostics bundling.
Pricing Analysis
Steel alloy and permanent magnet input costs pass through to equipment pricing with quarter-lag adjustments, pressuring fabrication margins for domestic beam pump and ESP motor manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates CFRP rod strings with extended warranties from commodity steel rods and refurbished ESP components. Pricing pressure stems from private equity-backed operators optimizing cash flow through direct component sourcing and third-party repair relationships. Marginal well operators in mature Permian fields exhibit highest price sensitivity, while integrated majors with captive engineering teams accept premium tiering for integrated predictive maintenance platforms.
Supply Chain Analysis
Single-source vulnerability sits with Chinese permanent magnet suppliers and German high-temperature motor controller manufacturers serving ESP system assemblers in Texas and Oklahoma. Carbon fiber precursor materials draw from Japan and the United States, with steel rod alloys sourced domestically and from Mexico. Tariff exposure on rare-earth magnets and semiconductor components for variable speed drives threatens cost stability for high-horsepower ESP production. Distribution runs through Midland-Odessa and Hobbs-Carlsbad field service clusters that stage equipment for rapid workover response across the Delaware and Midland sub-basins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artificial lift system deployment functions as a geographic-arbitrage play between methane-regulated Texas-New Mexico corridor operations and less restricted Appalachian Basin gas fields, with regulatory compliance cost differentials shaping equipment specification cycles and vendor selection criteria.
For Market Incumbents: Anticipate accelerated disintermediation as Permian independents unbundle installation from maintenance contracts, threatening recurring revenue pools for full-service providers. Defensive consolidation moves center on backward integration into permanent magnet motor production leveraging IRA manufacturing credits, and certification investment for EPA methane-compliant seal designs that smaller competitors cannot replicate. Channel control through exclusive field service density in Midland-Odessa and Hobbs-Carlsbad clusters protects incumbent positioning against regional repair shop encroachment. For New Entrants and Emerging Players: Capture white-space opportunity in Appalachian Basin Marcellus-Utica dewatering applications where Pennsylvania venting restrictions drive retrofit demand for closed-loop gas lift systems. Target plunger lift hybrid configurations for liquid unloading in mature gas fields, where incumbent service bundling has penetrated least deeply. Go-to-market execution should emphasize direct component sourcing relationships with private equity-backed operators already practicing procurement unbundling in West Texas. For Investors and Strategic Acquirers: Integrated oilfield service conglomerates represent the most active acquirer category in this space, seeking specialized lift fabricators with chemical-injection compatibility or corrosion-resistant materials expertise. Long-term viability over a multi-year horizon hinges on regulatory compliance technology rather than commodity equipment fabrication. Acquisition target archetype: regional ESP rebuild specialists with high-temperature pump expertise serving Bakken operators. Signal to watch: EPA methane rulemaking stringency revisions that would accelerate replacement cycles for non-compliant legacy installations.| Strategic Initiative | Industry Significance |
|---|---|
| Permanent Magnet Motor Production | IRA manufacturing credits reshape domestic ESP assembly economics toward Texas and Oklahoma plants. |
| CFRP Rod String Manufacturing | Carbon fiber-reinforced polymer capacity expansion cuts workover frequency for high-salinity Permian operators. |
| Predictive Diagnostics Platform Integration | Cloud-based rod load monitoring shifts maintenance from calendar-based to condition-based scheduling for Delaware sub-basin independents. |
| Closed-Loop Gas Lift System Certification | EPA methane-compliant compressor packages capture regulatory-driven retrofit demand across Texas and New Mexico. |
| High-Temperature ESP Rebuild Specialization | 300°F-plus motor controller expertise addresses Bakken warranty exposure and North Dakota Industrial Commission gas capture targets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with artificial lift engineering directors, Permian Basin field operations managers, ESP procurement leads at large independents, carbon fiber rod manufacturing specialists, and aftermarket repair shop owners with secondary validation. Secondary sources included EPA New Source Performance Standards rulemaking dockets, Texas Railroad Commission flaring compliance data, North Dakota Industrial Commission gas capture reports, and SEC 10-K filings from listed oilfield service providers. Bottom-up equipment count triangulation against top-down revenue estimates anchored market sizing.
Segment-weighting approaches distributed forecast mass across type, application, end user, and installation mode dimensions, with additional granularity for Permian versus Appalachian versus Bakken regional specification patterns. CAGRs derived from well decline curve analysis, horizontal completion projections, and regulatory compliance window timing. Industry-specific forecast inputs incorporated Delaware sub-basin ESP-ready well architecture trends and Pennsylvania Department of Environmental Protection venting restriction implementation schedules.
Regulatory enforcement variance, steel and magnet commodity volatility, and shale drilling cycle pauses are the dominant revision risks that could compress or extend artificial lift replacement timelines. Forecasts reflect documented assumptions about EPA methane rule stability and IRA credit continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Security Services Market
Oil & Gas
Deepwater Hydrocarbons Exploration Market
Oil & Gas
FTIR Oil Condition Monitoring Market
Oil & Gas
Gulf of Mexico Oil and Gas Upstream Market
Oil & Gas
United States Oil and Gas Market
Oil & Gas
Oil and Gas Refinery Maintenance Services Market
Oil & Gas
Southeast Asia Oil and Gas Market
Oil & Gas
Well Abandonment Services Market
Oil & Gas
Crude Oil Assay Testing Services Market
Oil & Gas
Riserless Light Well Intervention Market
Oil & Gas
Russia Oil and Gas EPC Market
Oil & Gas
Land Drilling Rig Market
Oil & Gas
Oil Breather Tank Market
Oil & Gas
Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
Vacuum Gas Oil Market