
 Fracking Fluid Market | 2026-2036
Fracking Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
Fracking Fluid Market Analysis
Petroleum engineer and fluid chemist shortages across the Permian and Appalachian basins is reorganizing how operators source technical services, forcing bundled procurement contracts that combine chemistry with real-time downhole monitoring. Halliburton Company leverages its integrated wellsite delivery model to capture multi-year service agreements. Baker Hughes Company anchors its position through proprietary friction-reducer chemistry optimized for high-salinity produced water. Schlumberger Limited competes via digital fluid design platforms that compress lab-to-field iteration cycles.
Fracking fluid comprises engineered aqueous or hydrocarbon-based carrier systems blended with performance additives to create and propagate fractures in low-permeability rock formations, typically formulated with viscosifiers, breakers, and proppant transport aids at surface pressures exceeding 8,000 psi. Water-based formulations dominate North American shale plays due to cost efficiency and compatibility with recycled produced water programs, while friction reducers represent the fastest-growing additive category as operators push higher pump rates through narrower wellbore geometries. Oil-based fluids retain niche dominance in water-sensitive formations where clay swelling risks formation damage, though environmental compliance costs constrain expansion.
EPA oversees underground injection control permitting for fluid disposal under the Safe Drinking Water Act, while state regulators in Texas and Oklahoma impose seismicity-triggered volume restrictions on Class II wells that directly constrain waste management economics. OSHA enforces workplace chemical exposure limits during blending and pumping operations, driving substitution toward lower-toxicity biocide packages. Stakeholders must monitor evolving state-level disclosure mandates for proprietary additive chemistries, as these transparency requirements threaten formulation intellectual property while creating compliance barriers for smaller chemical suppliers.
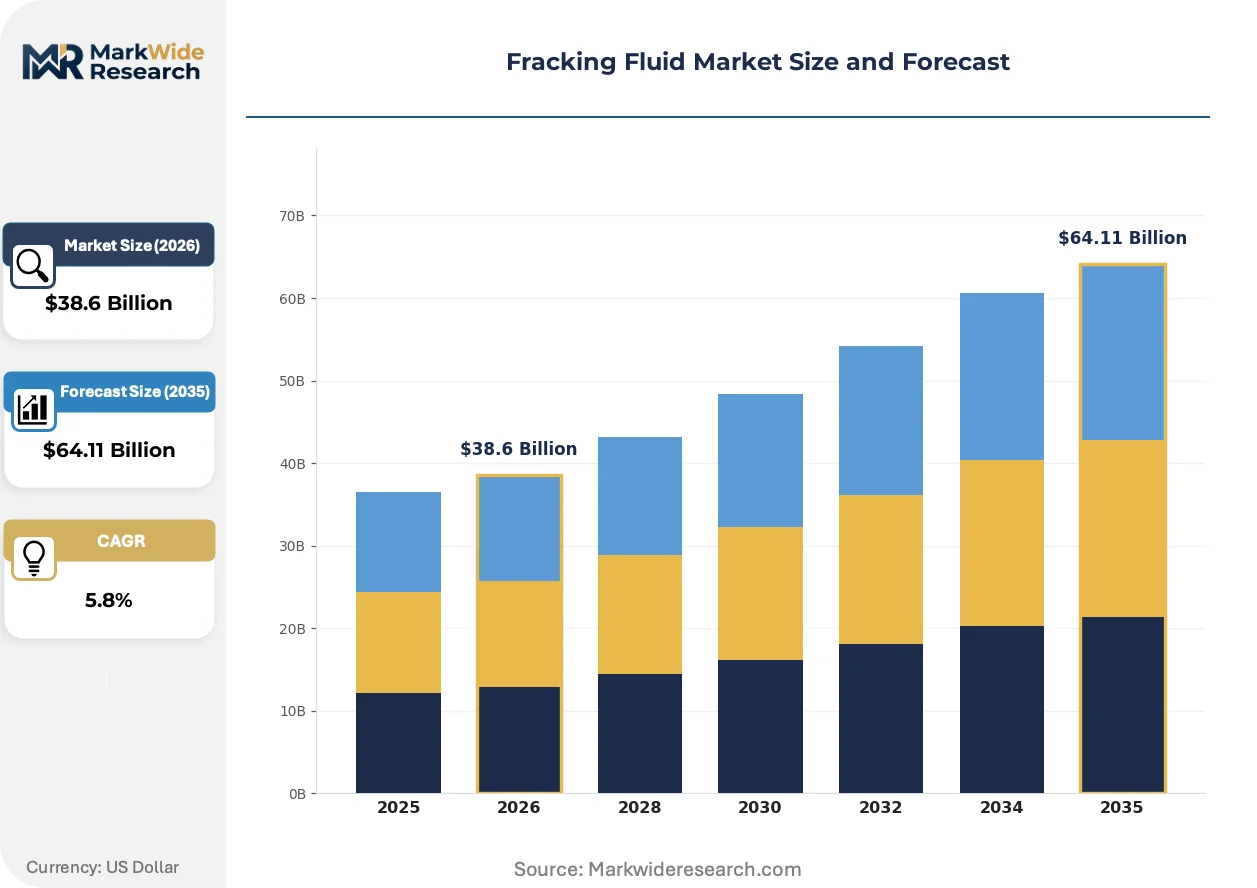
Market Dynamics
Consolidated pressure-pumping fleets across Texas and New Mexico are forcing chemical suppliers to co-locate blending facilities near centralized terminals, restructuring procurement from spot transactions toward multi-year volume commitments with embedded technical service obligations.
Growth Catalysts
- EPA Class II UIC Permitting:Stricter underground injection control standards for produced water disposal are accelerating demand for closed-loop fluid recycling systems that reduce freshwater consumption.
- Higher Pump Rate Intensification:Operators pushing 15,000+ psi surface pressures through extended-reach laterals require next-generation friction reducers capable of maintaining viscosity in high-salinity recycled water.
- Permian Basin Water Scarcity:Persistent drought conditions across West Texas and southeastern New Mexico are mandating produced water reuse quotas that favor advanced water-based formulations over conventional freshwater-dependent chemistries.
Market Restraints
- Guar Gum Price Volatility:Viscosifier costs swing with monsoon-dependent Indian agricultural output, compressing blender margins during poor harvest cycles.
- Seismicity-Triggered Volume Caps:Oklahoma Corporation Commission and Texas Railroad Commission injection limits near fault lines constrain waste disposal economics and extend logistics chains.
- Biocide Regulatory Friction:EPA re-registration requirements for glutaraldehyde-based microbicides are lengthening approval timelines and forcing formulation reformulation costs onto mid-tier chemical suppliers.
Strategic Opportunities
- Appalachian Basin Underpenetration:Marcellus and Utica operators lag Permian recycling adoption rates, creating white space for mobile on-site blending units that eliminate transportation costs.
- Digital Fluid Design Convergence:Integration of real-time downhole sensors with cloud-based rheology modeling enables just-in-time chemistry adjustments that reduce additive over-treatment.
- Colorado 181 Regulatory Tailwind:State-mandated disclosure of proprietary chemical constituents is creating compliance service opportunities for third-party formulation verification platforms.
Industry Challenges
- Petroleum Engineer Talent Scarcity:Retirement waves across Permian and Bakken field offices are forcing operators to outsource real-time pressure-monitoring decisions to remote technical centers.
- Produced Water Treatment Capex Burden:Mobile desalination units required for high-salinity recycling programs demand upfront capital commitments that strain independent pressure-pumper balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fracking Fluid Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Oil-Based, Foam, Gelled Additive Type: Biocides, Surfactants, Corrosion Inhibitors, Friction Reducers Application: Onshore, Offshore, Shale, Tight Gas End User: Oil Companies, Service Providers, Industrial Users, Government Agencies |
| Companies Covered | Halliburton Company, Schlumberger Limited, Baker Hughes Company, BASF SE, Dow Chemical Company, Akzo Nobel N.V., Albemarle Corporation, CES Energy Solutions Corp, Ecolab Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fracking Fluid Market Emerging Trajectories
Real-time chemistry optimization is displacing static batch formulations across North American shale plays, compressing iteration cycles from weeks to hours and embedding fluid suppliers deeper into drilling operations.
Polyacrylamide-based friction reducers are miniaturizing molecular weight distributions to maintain performance in 150,000+ ppm total dissolved solids produced water. Permian operators with centralized recycling facilities are adopting these high-salinity-tolerant polymers at accelerating rates. This molecular engineering is miniaturizing the performance gap between freshwater and recycled water systems, enabling broader produced water substitution without sacrificing pump rate targets.
Texas Railroad Commission seismicity protocols now mandate real-time injection pressure monitoring within 10 kilometers of mapped fault structures, triggering automatic volume reductions when seismic events exceed magnitude thresholds. This regulatory architecture is forcing disposal well operators to install distributed acoustic sensing fiber optics, raising fixed costs but reducing liability exposure. Small-cap disposal specialists in the Midland sub-basin are most affected, consolidating into larger networks to amortize compliance infrastructure.
Spot-market chemical purchasing is contracting as integrated exploration companies demand bundled procurement contracts combining base fluid, additives, and real-time technical support. Independent pressure-pumping fleets in the Delaware Basin are losing share to consolidated service providers offering chemistry-as-a-service models with embedded guaranteed performance clauses. This purchasing transformation is most visible among supermajor Permian operators who have centralized supply chain decision-making in Houston procurement centers.
Fracking Fluid Market Segmentation
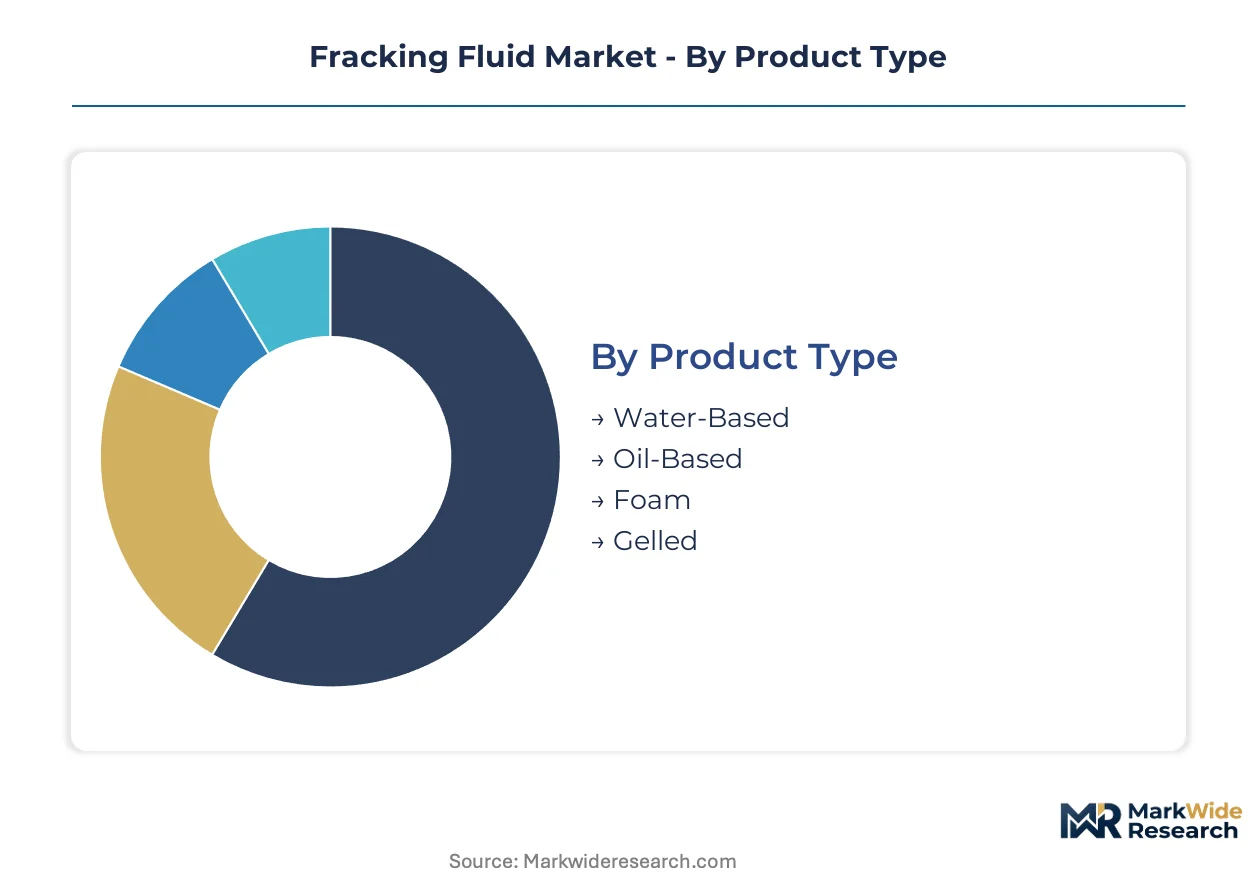
Fracking fluid procurement patterns diverge sharply between domestic shale basins and export-oriented supply chains, with formulation standards and logistics infrastructure driving segment-level investment priorities. Understanding these divisions reveals where technology premiums command pricing power versus where commodity economics dominate.
Product Type:
Water-based formulations anchor North American demand, while oil-based systems retain concentrated export relevance to water-sensitive formations in the Middle East and North Africa.
- Water-Based:Aqueous carrier systems blend viscosifiers, breakers, and proppant transport aids for surface pressures exceeding 8,000 psi. Permian Basin operators with centralized recycling facilities are expanding these formulations to meet produced water reuse quotas mandated by Texas Railroad Commission drought protocols.
- Oil-Based:Hydrocarbon-based fluids mitigate clay swelling risks in water-sensitive formations. Environmental compliance costs and EPA disposal regulations constrain North American adoption, though niche demand persists in specific geological conditions where formation damage risks override cost premiums.
- Foam:Nitrogen or carbon dioxide-stabilized systems reduce fluid volume requirements in underpressured reservoirs. Bakken operators deploy these for marginal well economics.
- Gelled:Crosslinked polymer systems deliver proppant suspension in high-temperature formations. Appalachian Basin high-pressure zones drive intermittent demand.
Water-based commands the established base. The steepest expansion runs through friction-reducer-enhanced water systems optimized for high-salinity recycling.
Additive Type:
Cost tier differentiation separates premium synthetic chemistry from commodity biocide packages, with procurement consolidation favoring suppliers offering integrated additive suites.
- Biocides:Microbial control agents prevent souring and corrosion in recycled water systems. EPA re-registration timelines for glutaraldehyde-based formulations are forcing mid-tier suppliers toward alternative chemistries with shorter approval pathways.
- Friction Reducers:Polyacrylamide-based polymers enable 15,000+ psi pump rates through extended-reach laterals. Delaware Basin operators with high-salinity produced water programs are driving fastest adoption of molecular-weight-miniaturized variants tolerant to 150,000+ ppm total dissolved solids.
- Surfactants:Surface-active agents reduce interfacial tension for improved cleanup. Spot-market purchasing dominates this commoditized category.
- Corrosion Inhibitors:Film-forming compounds protect tubulars from acidic formation fluids. Bundled procurement contracts increasingly subsume these into chemistry-as-a-service agreements.
Friction reducers concentrate technology investment. Biocides face the steepest regulatory headwinds.
Application:
Volume concentration tracks rig count distribution, with onshore shale economics scaling additive volumes that dwarf offshore unit-revenue premiums.
- Onshore:Land-based fracturing operations in Texas, New Mexico, and North Dakota account for the dominant share of fluid consumption. Consolidated pressure-pumping fleets are restructuring procurement toward multi-year volume commitments with embedded technical service obligations.
- Shale:Unconventional low-permeability formations require engineered fluid systems for fracture propagation. Permian and Bakken operators are expanding water-based programs to manage rising Class II injection well disposal costs under tightening EPA UIC standards.
- Tight Gas:Low-permeability sandstone formations demand modified rheology profiles. Appalachian Basin Marcellus and Utica plays lag Permian recycling adoption rates.
- Offshore:Platform-based operations face logistics constraints and environmental discharge restrictions. Premium pricing reflects supply chain complexity rather than volume scale.
Onshore shale anchors procurement volume. Tight gas applications are gaining share fastest as Appalachian operators close the recycling adoption gap.
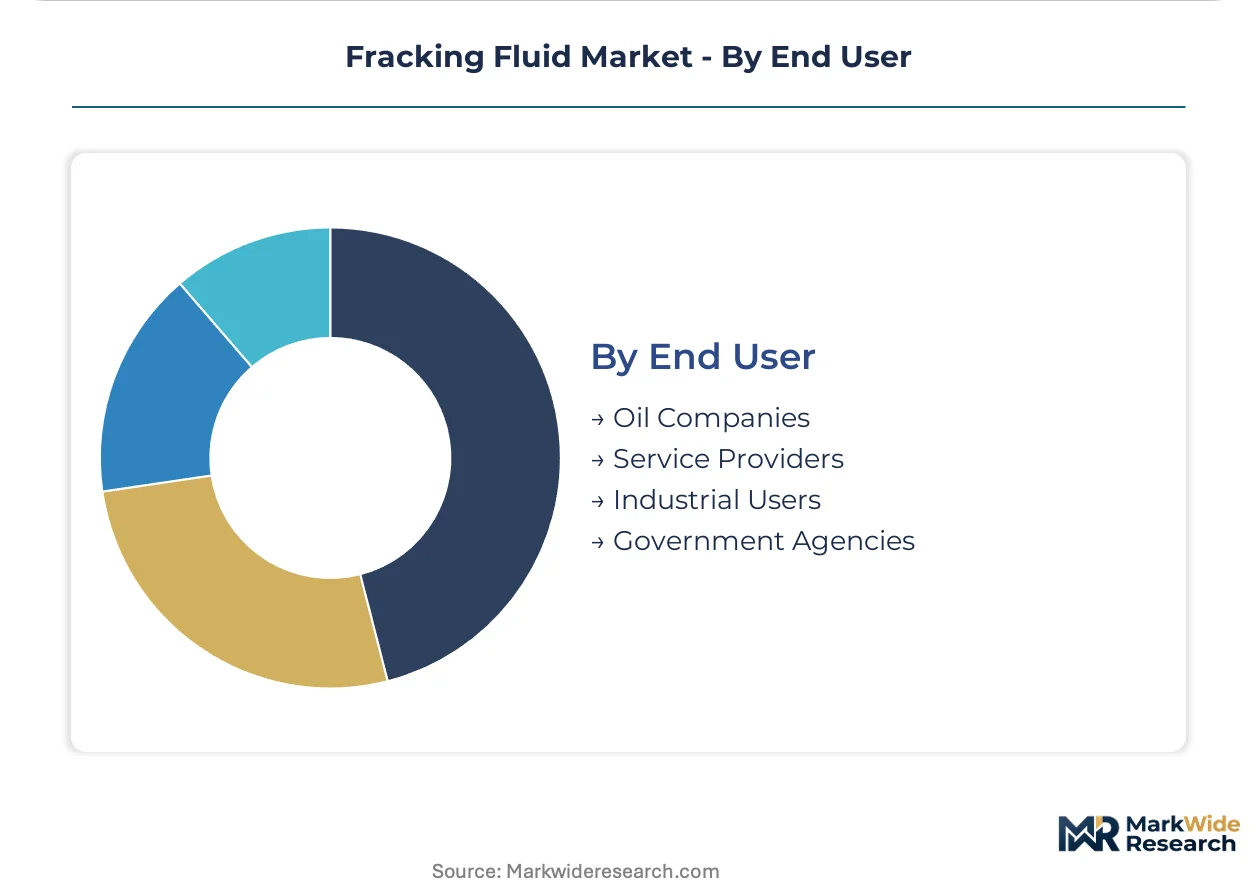
End User:
Customer type determines contract structure, with integrated oil companies centralizing supply chain decisions while service providers compete on technical integration depth.
- Oil Companies:Exploration and production operators with consolidated procurement functions in Houston and Midland are demanding bundled contracts combining base fluid, additives, and real-time downhole monitoring. Supermajor Permian divisions lead this purchasing transformation.
- Service Providers:Pressure-pumping and well completion specialists compete via chemistry-as-a-service models with guaranteed performance clauses. Independent Delaware Basin fleets are losing share to consolidated providers offering integrated wellsite delivery.
- Industrial Users:Non-oilfield industrial fracturing applications represent marginal demand. Spot purchasing prevails.
- Government Agencies:State and federal research programs fund alternative formulation development. Volumes remain negligible.
Oil companies concentrate procurement leverage. Service providers are expanding fastest through technical bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fracking fluid consumption patterns diverge sharply between North American shale operators running high-volume water recycling programs and international markets where water scarcity or formation sensitivity drives alternative chemistry adoption.
United States
Permian Basin operators in West Texas and southeastern New Mexico consume the dominant share of water-based formulations, driven by produced water reuse quotas under Texas Railroad Commission drought protocols. EPA Class II underground injection control permitting constrains disposal well economics, forcing investment in closed-loop recycling infrastructure. Midland and Odessa anchor chemical blending facility concentration, with consolidated pressure-pumping fleets restructuring procurement toward multi-year volume commitments.
Canada
Montney and Duvernay formation operators in Alberta and British Columbia favor gelled polymer systems for high-temperature zones, contrasting with the water-based dominance south of the border. Health Canada and provincial regulators impose stricter chemical disclosure requirements than US counterparts, elevating compliance costs for proprietary additive formulations. Calgary-based service providers compete through chemistry-as-a-service models bundling technical support with fluid delivery.
China
Sichuan-Chongqing shale gas development in the Fuling and Weiyuan blocks drives demand for friction reducers tolerant to high-salinity formation water. Ministry of Ecology and Environment (MEE) wastewater discharge regulations tighten faster than enforcement capacity, creating uneven compliance across state-owned versus independent operators. Chengdu anchors domestic chemical supplier concentration, with local producers capturing share from imported formulations.
Saudi Arabia
Unconventional gas development in the Jafurah Basin requires oil-based fluids to mitigate clay swelling in water-sensitive sandstone formations. Saudi Aramco's in-house technical capabilities reduce third-party service provider penetration compared to North American markets. Dhahran and the Eastern Province concentrate domestic chemical blending infrastructure, with state-directed procurement favoring long-term supply agreements over spot purchasing.
Argentina
Vaca Muerta shale operators in Neuquén Province lag Permian recycling adoption rates, creating white space for mobile on-site blending units that eliminate transportation costs across dispersed well pads. Provincial environmental regulators impose less stringent produced water management requirements than Texas or Oklahoma counterparts. Neuquén city anchors service provider concentration, with international operators testing high-salinity-tolerant friction reducers in pilot programs.
Fracking Fluid Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding bundled procurement contracts that combine base fluid chemistry with real-time technical services. The middle tier fragments across regional chemical blenders and additive specialists competing on formulation customization. Three archetypes dominate: integrated oilfield service providers with wellsite delivery capabilities, standalone chemical manufacturers supplying friction reducers and viscosifiers, and emerging digital fluid design platforms. Competitive moves concentrate on backward integration into additive manufacturing and geographic expansion through mobile blending unit deployment.
Within the integrated service tier, Halliburton Company and Schlumberger Limited exemplify the chemistry-as-a-service model embedding guaranteed performance clauses into multi-year agreements. Baker Hughes Company anchors the specialty chemistry vector through proprietary friction-reducer development. Among standalone chemical suppliers, BASF SE and Dow Chemical Company represent the industrial chemical conglomerate archetype, leveraging scale manufacturing across polymer and surfactant categories. Albemarle Corporation occupies a position in the specialty mineral and catalyst segment, while Ecolab Inc. exemplifies the water treatment and process chemical integration path.
| Leading Market Players |
|---|
| Halliburton Company |
| Schlumberger Limited |
| Baker Hughes Company |
| BASF SE |
| Dow Chemical Company |
| Akzo Nobel N.V. |
| Albemarle Corporation |
| CES Energy Solutions Corp |
| Ecolab Inc. |
| Others |
Supply Flow & Price Mechanics
Produced water substitution for freshwater in Permian Basin formulations is simultaneously relocating chemical blending capacity toward Midland-Odessa recycling clusters and compressing margin structures for conventional freshwater-dependent suppliers. This input transition rewards operators with captive recycling infrastructure while squeezing spot-market chemical vendors unable to meet high-salinity formulation specifications.
Pricing Analysis
Multi-year offtake contracts with embedded technical service obligations dominate procurement among supermajor Permian operators, displacing spot purchasing that still prevails among independent pressure-pumping fleets. Price differentiation hinges on salinity tolerance certification and volume scale commitments, with high-salinity-tolerant friction reducers commanding premiums over commodity biocide packages. Cost compression in standard water-based formulations is intensifying as consolidated fleets centralize supply chain decisions in Houston procurement centers. Independent Delaware Basin pressure-pumpers exhibit highest price sensitivity due to balance sheet constraints, while integrated oil companies prioritize performance guarantees over unit cost minimization.
Supply Chain Analysis
Inbound logistics costs for guar gum viscosifiers fluctuate with monsoon-dependent Indian agricultural output, creating volatile input cost exposure for North American blenders sourcing across Mumbai-JNPT trade lanes. Manufacturing concentration clusters in the United States, China, and India, with polyacrylamide friction reducer production anchored in Sichuan-Chongqing chemical parks and guar gum processing centered on Rajasthan agricultural cooperatives. Supply chain risk centers on single-source dependency for high-molecular-weight polymer feedstocks. Distribution runs through centralized terminals in Midland and Odessa, with mobile blending units extending reach to dispersed well pads in the Delaware sub-basin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fracking fluid demand is recovering through the upstream capital expenditure cycle, with Permian rig count expansion and produced water reuse mandates serving as the named cyclical driver restoring volume growth.
For Market Incumbents: Compound technical service integration depth to defend against chemistry-as-a-service competitors embedding guaranteed performance clauses. Prioritize backward integration into high-salinity-tolerant polyacrylamide manufacturing to capture margin currently flowing to specialty chemical suppliers. Expand mobile blending unit deployment in the Appalachian Basin before recycling adoption rates converge with Permian benchmarks.
For New Entrants and Emerging Players: Anchor in Vaca Muerta shale operations where Argentine environmental regulations impose lighter produced water management burdens than Texas or Oklahoma counterparts. Target mobile on-site blending for dispersed Neuquén Province well pads, eliminating transportation cost disadvantages against established suppliers. Pursue pilot program partnerships with international operators testing high-salinity friction reducers outside North American specifications.
For Investors and Strategic Acquirers: Capital is best deployed toward standalone chemical manufacturers with proprietary friction-reducer formulations and established recycling facility offtake relationships. Long-term viability favors suppliers capable of operating across the full salinity spectrum from freshwater to 150,000+ ppm total dissolved solids systems. Monitor Texas Railroad Commission seismicity protocol enforcement intensity as an inflection indicator for disposal well economics and closed-loop recycling investment returns.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyacrylamide Manufacturing | Captures margin from specialty chemical suppliers while securing supply of high-salinity-tolerant polymers for Permian recycling programs. |
| Mobile Blending Unit Deployment | Eliminates transportation costs for dispersed well pads in underpenetrated basins like Vaca Muerta and Appalachian tight gas plays. |
| Long-term Supply Agreement with Recycling Facility Operators | Locks in volume commitments from Permian operators facing Texas Railroad Commission produced water reuse quotas. |
| Digital Fluid Design Platform Development | Compresses lab-to-field iteration cycles and embeds suppliers deeper into real-time downhole monitoring workflows. |
| Alternative Biochemistry R&D Investment | Addresses EPA re-registration headwinds for glutaraldehyde-based microbicides with shorter approval pathway chemistries. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, EIA production data, EPA UIC permitting records, and state regulatory commission disclosure databases. Stakeholder interviews encompassed petroleum engineers at Permian and Bakken operators, procurement directors at consolidated pressure-pumping fleets, fluid chemists at chemical blending facilities, and regulatory affairs specialists tracking Texas Railroad Commission seismicity protocols. Bottom-up volume estimates derived from rig count projections and per-well fluid intensity benchmarks were triangulated against top-down market sizing from chemical supplier revenue disclosures.
Segmentation dimensions modeled span fluid type, additive category, application geology, and end-user procurement structure across the projection horizon. CAGRs were derived from elasticity-adjusted volume forecasts incorporating salinity tolerance adoption curves and regulatory compliance cost trajectories. Industry-specific inputs include produced water recycling penetration rates by basin and friction reducer performance specifications under high total dissolved solids conditions.
Decision-makers should treat outputs as directional under assumptions of sustained Permian drilling activity and stable EPA Class II UIC permitting timelines; material deviation would warrant model refresh. Specific risks include accelerated seismicity-triggered volume caps, guar gum harvest failures, or abrupt biocide regulatory restrictions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Libya Oil and Gas Midstream Market
Oil & Gas
Iron Ore Mining Market
Oil & Gas
Wellhead System Market
Oil & Gas
Sudan Oil and Gas Market
Oil & Gas
Chad Oil and Gas Market
Oil & Gas
Iran Oil and Gas Market
Oil & Gas
Global Oilfield Communications Market
Oil & Gas
Global LNG Regasification Terminals Market
Oil & Gas
Oil and Gas Logistics Market
Oil & Gas
US Oil and Gas Analytics Market
Oil & Gas
Southeast Asia Oil and Gas Market
Oil & Gas
US Oil and Gas Infrastructure Market
Oil & Gas
Offshore Oil and Gas Paints and Coatings Market
Oil & Gas
North America Artificial Lift Systems Market
Oil & Gas
Australia Oil and Gas Market
Oil & Gas
Vietnam Oil and Gas Upstream Market