
 Well Testing Services Market | 2026-2036
Well Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Well Testing Services Market Intelligence
EU methane emissions regulations under the EU Green Deal are hardening compliance requirements for upstream operators, pushing demand for continuous well monitoring and leak detection services. Schlumberger Limited leverages its integrated subsurface technology portfolio to anchor premium positioning in formation evaluation. Baker Hughes Company competes through advanced sensor technology deployed across both onshore and offshore testing programs. Weatherford International Plc specializes in managed pressure drilling and well integrity testing solutions for complex reservoir environments.
Well testing services encompass the systematic measurement of reservoir pressure, flow rates, and fluid properties to characterize hydrocarbon-bearing formations and validate production potential. Surface testing and downhole testing technologies employ pressure gauges, multiphase flow meters, and distributed temperature sensing to capture real-time reservoir performance data. Production testing dominates service revenue as operators require validated flow rates before committing capital to permanent production facilities. Formation testing represents the fastest-expanding category as pad drilling and multi-stage completions demand rapid reservoir characterization. Data acquisition systems increasingly integrate with cloud platforms, shifting margin pools toward software-enabled diagnostics and remote monitoring.
EPA methane rules in the United States and EU Green Deal emissions frameworks impose stringent monitoring obligations on operators, directly expanding demand for continuous well integrity testing and flare gas measurement. BIS certification requirements in India and NMPA oversight in China shape equipment standards and market access protocols for international service contractors. Stakeholders must weigh capital allocation between conventional surface testing assets and sensor-integrated digital platforms as regulatory complexity deepens across producing regions.
Market Dynamics
Real-time reservoir characterization through distributed fiber-optic sensing and cloud-native analytics platforms is compressing decision cycles for operators managing multi-well pad developments. This technological inflection is redistributing value from conventional surface testing equipment toward integrated data services.
Growth Catalysts
- EPA methane monitoring mandates:Continuous emissions surveillance requirements under US federal rules are expanding demand for automated well integrity diagnostics and flare gas quantification systems.
- Pad drilling intensification:Multi-well completion programs in unconventional basins require rapid formation evaluation to optimize stage spacing and proppant loading.
- EU Green Deal compliance:The EU methane emissions framework is forcing upstream operators to deploy permanent downhole monitoring infrastructure.
Market Restraints
- Specialized pressure gauge supply concentration:Precision quartz transducer manufacturing clusters in Japan and Germany create vulnerability to regional logistics disruptions.
- High-specification alloy input costs:Inconel and titanium components for corrosive reservoir environments expose service margins to nickel and titanium sponge price volatility.
- Extended certification timelines:BIS equipment approval processes in India delay market entry for international testing technology providers.
Strategic Opportunities
- Carbon capture site characterization:Saline aquifer and depleted field injection programs require formation injectivity testing and caprock integrity verification.
- Geothermal reservoir evaluation:Enhanced geothermal systems in Nevada and Utah demand high-temperature downhole testing tools adapted from oilfield technology.
- Remote operations platforms:Cloud-based diagnostics integrated with satellite telemetry enable service delivery to isolated offshore and Arctic locations without permanent crews.
Industry Challenges
- Petrophysicist talent scarcity:Specialized expertise in multiphase flow interpretation and pressure transient analysis is concentrating among a shrinking cohort of experienced practitioners.
- Legacy SCADA integration friction:Brownfield installations with proprietary data protocols resist seamless connection to modern IoT sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Well Testing Services Market |
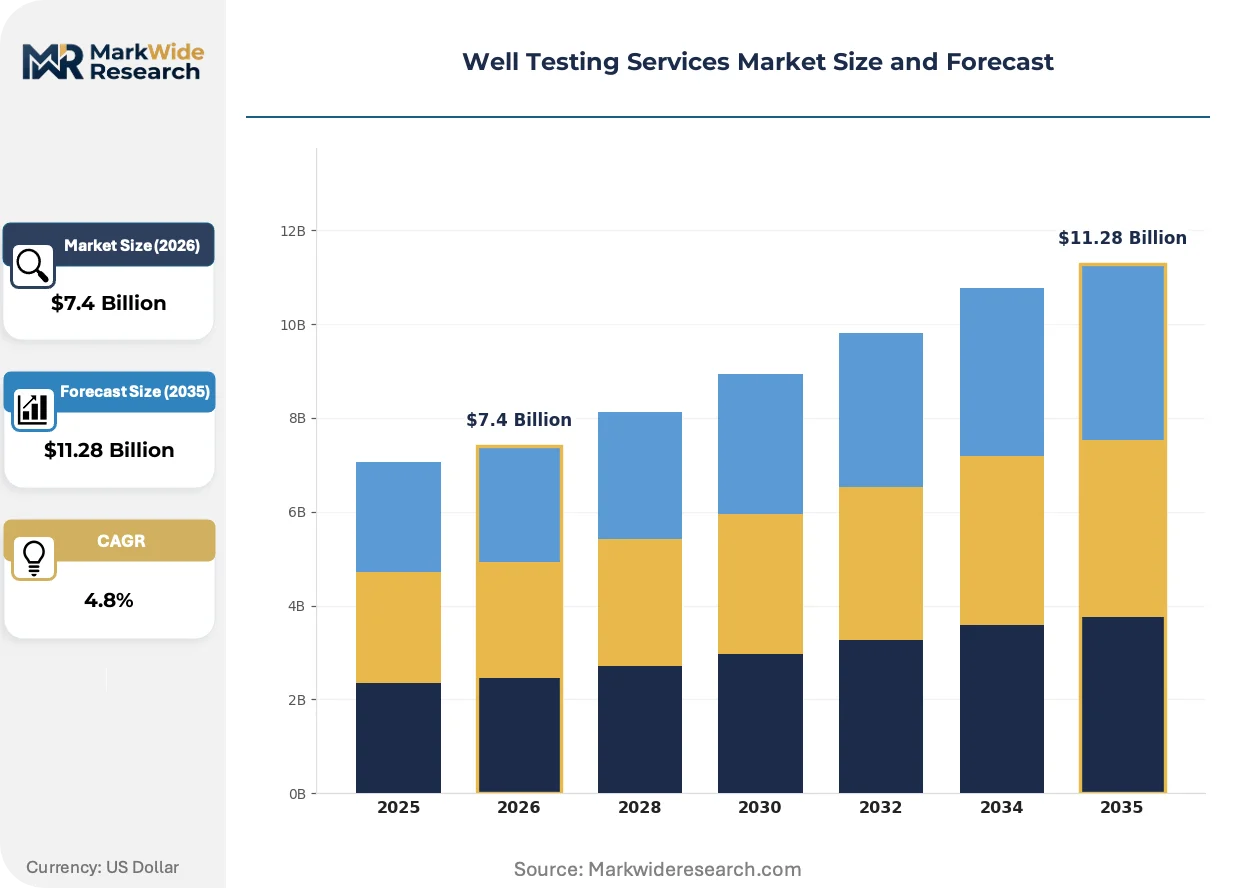
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $11.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Production Testing, Formation Testing, Early Production, Well Integrity Testing Technology: Surface Testing, Downhole Testing, Advanced Sensor Technology, Data Acquisition Systems End User: Oil & Gas Operators, Service Companies, Mining Firms, Research Institutions Application: Onshore Wells, Offshore Wells, Exploration Activities, Development Projects |
| Companies Covered | Weatherford International Plc, TETRA Technologies, Inc., Schlumberger Limited, National Oilwell Varco, China Oilfield Services Limited, Halliburton Company, Expro Group, Oil States Energy Services, Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Well Testing Services Market Strategic Shifts & Innovations
Digitization of subsurface measurement workflows is collapsing the latency between data acquisition and reservoir management decisions. Service providers are racing to embed predictive algorithms directly at the wellsite.
Fiber-optic distributed acoustic sensing is expanding into permanent wellbore monitoring installations. Permian Basin operators are retrofitting existing completions with fiber-deployed arrays to capture microseismic, flow profiling, and leak detection from a single infrastructure. This convergence of measurement domains is compressing capital requirements for comprehensive reservoir surveillance.
EU methane emissions regulations under the EU Green Deal are mandating quarterly leak detection surveys and annual equipment audits for upstream assets. The framework imposes penalties for venting and flaring exceedances, compelling operators to install continuous monitoring systems. Offshore installations in the North Sea and Norwegian Continental Shelf are deploying automated optical gas imaging to satisfy inspection frequency requirements.
Integrated service contracting is displacing discrete equipment rental arrangements. Majors in the Gulf of Mexico are procuring formation evaluation through performance-based agreements tied to drilling efficiency metrics. This transfers operational risk to service providers while locking in multi-year revenue streams. The model is gaining traction in Brazil's pre-salt developments where NOC procurement offices favor consolidated accountability.
Well Testing Services Market Segmentation
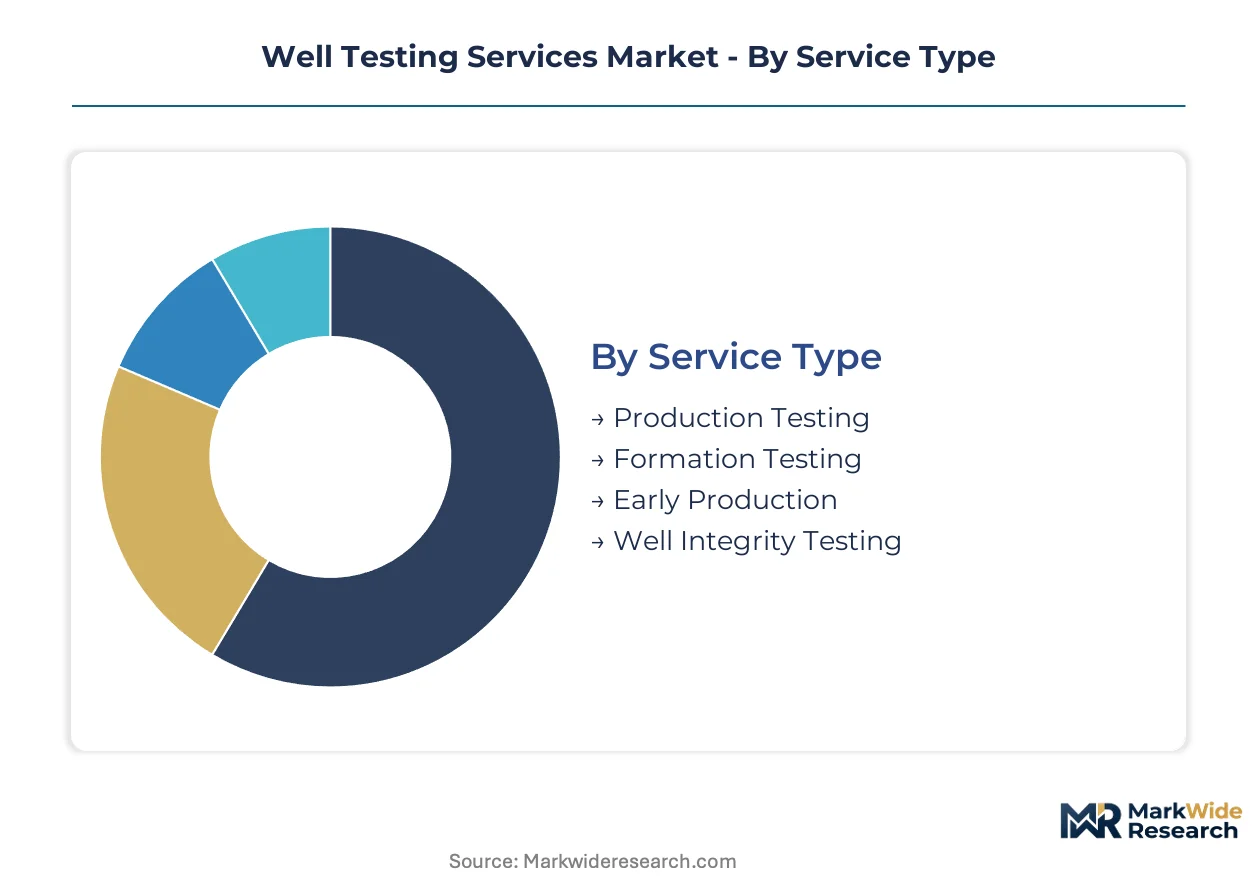
Service differentiation in well testing hinges on regulatory scope and technical complexity. Each segment carries distinct certification burdens that shape procurement patterns and margin structures across upstream operations.
Service Type:
EPA methane monitoring mandates and EU Green Deal compliance frameworks impose tiered certification requirements across service categories, with continuous monitoring obligations heaviest on integrity-focused offerings.
- Production Testing:Systematic measurement of stabilized flow rates, pressure drawdown, and fluid properties to validate commercial production capacity before facility commitment. Demand concentrates in Permian Basin multi-well pads where operators require rapid validation to optimize completion designs and reduce non-productive time.
- Formation Testing:Downhole pressure transient analysis and fluid sampling to characterize reservoir permeability, skin damage, and boundary conditions. Unconventional developments in North American shale basins drive intensifying demand as pad drilling programs require rapid reservoir characterization to optimize stage spacing and proppant loading.
- Early Production:Temporary production systems deployed during facility construction delays or reservoir evaluation periods.
- Well Integrity Testing:Annular pressure monitoring, casing inspection, and leak detection services mandated by tightening methane emissions regulations.
Production Testing sits at the top of the volume ranking, with Formation Testing climbing the fastest.
Technology:
Capital allocation across technology tiers reflects a cost-to-precision tradeoff, with premium sensor networks commanding margins three to four times conventional surface equipment.
- Surface Testing:Wellhead-mounted separators, multiphase flow meters, and flare gas measurement systems capturing surface pressure and flow data. Gulf of Mexico offshore developments anchor demand as majors require validated flow rates before subsea facility commitment.
- Downhole Testing:Wireline-conveyed and tubing-conveyed pressure gauges, samplers, and packer systems for direct reservoir measurement. North Sea operators deploy high-temperature quartz transducer arrays to satisfy EU methane monitoring mandates and maximize recovery from mature assets.
- Advanced Sensor Technology:Fiber-optic distributed acoustic sensing and permanent downhole monitoring infrastructure.
- Data Acquisition Systems:Cloud-integrated telemetry platforms shifting margin pools toward software-enabled diagnostics.
Surface Testing maintains the largest installed base, while Advanced Sensor Technology expands most quickly as fiber-optic retrofits proliferate.
End User:
Procurement authority fragmentation across customer types creates divergent sales cycles, with integrated operators favoring performance-based contracts and independents prioritizing equipment rental flexibility.
- Oil & Gas Operators:Upstream companies holding mineral leases and production rights, from supermajors to shale-focused independents. Brazilian pre-salt developments and US unconventional basins concentrate demand as NOC procurement offices favor consolidated accountability through integrated service contracting.
- Service Companies:Drilling contractors and completion specialists subcontracting specialized testing capabilities.
- Mining Firms:Mineral extraction companies adapting oilfield testing technology for geothermal and carbon storage applications.
- Research Institutions:Universities and national laboratories conducting reservoir simulation validation and enhanced recovery studies.
Oil & Gas Operators dominate contract value, with Mining Firms gaining share fastest as geothermal and carbon capture applications mature.
Application:
Geographic deployment patterns follow resource accessibility, with onshore developments offering scale economics and offshore programs demanding specialized mobilization capabilities.
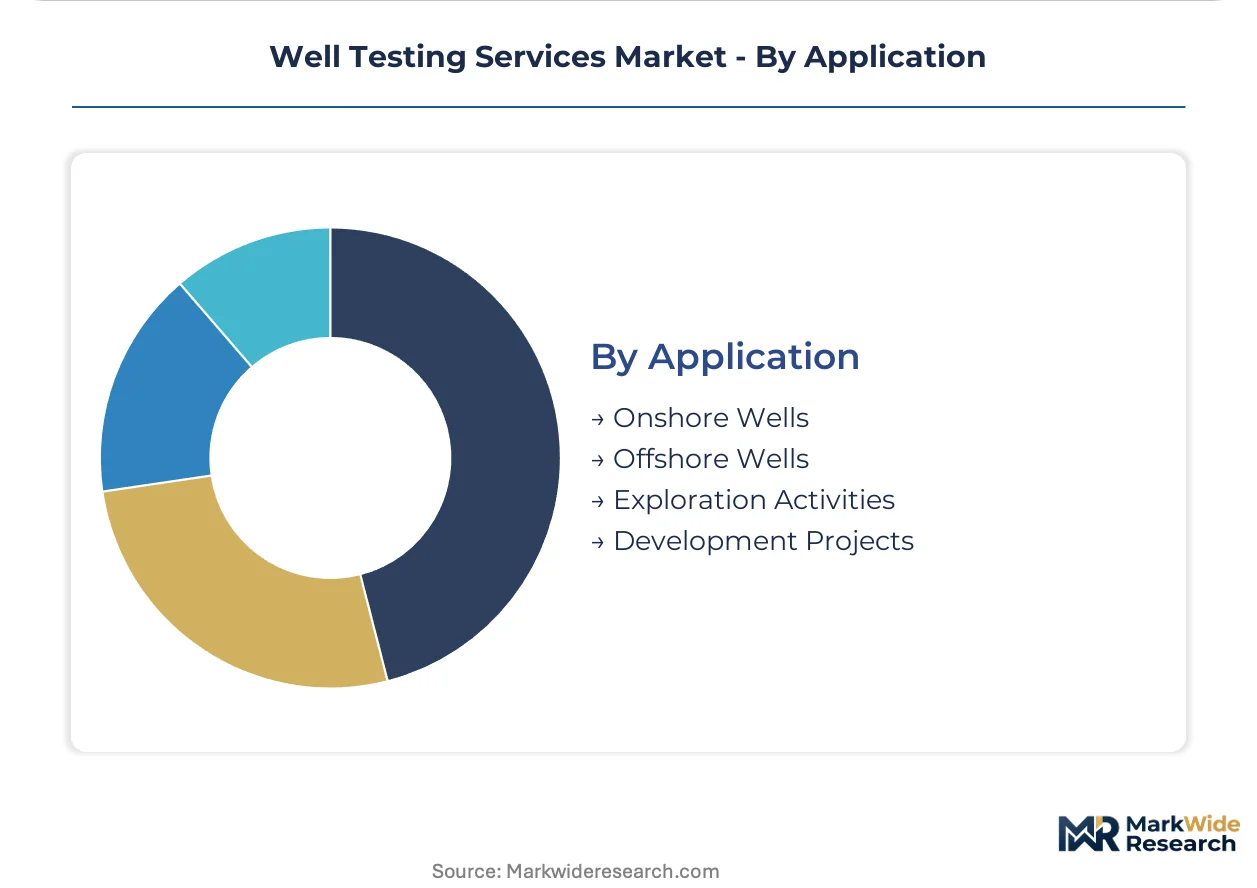
- Onshore Wells:Land-based drilling and completion programs across conventional and unconventional reservoirs. Texas, New Mexico, and North Dakota shale basins anchor global demand as pad drilling intensification requires rapid formation evaluation to optimize multi-stage completions.
- Offshore Wells:Subsea and platform-based developments in deepwater and harsh-environment provinces. Norwegian Continental Shelf and UK North Sea installations drive premium service demand as EU methane regulations mandate quarterly leak detection surveys and automated optical gas imaging systems.
- Exploration Activities:Wildcat drilling and appraisal programs requiring reservoir confirmation before development commitment.
- Development Projects:Field expansion and infill drilling programs with established production infrastructure.
Onshore Wells generate the highest service volume, with Offshore Wells commanding the steepest price premiums per test.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The well testing services industry traces its modern operational scale to the Permian Basin expansion of the 2010s, when hydraulic fracturing intensification created standardized demand for rapid formation evaluation across multi-well pads.
United States
EPA methane monitoring mandates and pad drilling intensification in Texas and New Mexico drive service demand. The EPA's New Source Performance Standards impose quarterly leak detection surveys on upstream operators. Midland-Odessa anchors the highest concentration of real-time reservoir characterization deployments.
Norway
North Sea mature field redevelopment and subsea facility commitments sustain premium testing volumes. The EU Green Deal methane emissions framework mandates annual equipment audits and automated optical gas imaging. Stavanger concentrates integrated service contracting for offshore developments.
China
Sichuan Basin shale gas development and Tarim Basin deep exploration expand formation testing requirements. NMPA oversight shapes equipment certification timelines for international contractors. Chengdu-Chongqing corridor hosts the fastest-growing cluster of high-temperature downhole tool deployments.
Saudi Arabia
Gas reservoir development and offshore field expansion sustain production testing demand. The national oil company's localization programs reshape procurement toward joint-venture service structures. Dhahran-Riyadh corridor anchors integrated project management for pre-salt analog developments.
Brazil
Pre-salt carbonate appraisal and FPSO facility commitments drive formation evaluation demand. ANVISA-equivalent petroleum regulator requirements shape equipment import protocols. Rio de Janeiro concentrates performance-based contracting for deepwater testing programs.
Well Testing Services Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology integration depth, with fiber-optic sensing and cloud-native analytics commanding three-to-four-fold margin multiples over conventional surface equipment rental. The vendor base organizes into three tiers: integrated technology conglomerates with subsurface software portfolios, specialized downhole tool manufacturers with precision sensor capabilities, and regional equipment rental firms with logistics-scale advantages. Consolidation pressure intensifies as operators shift procurement toward performance-based agreements, forcing capability gaps through acquisition and technology licensing rather than organic development.
Within the integrated technology tier, Schlumberger Limited and Baker Hughes Company exemplify the premium positioning archetype, anchoring formation evaluation through combined hardware-software offerings. Weatherford International Plc occupies a specialized position in managed pressure drilling and well integrity solutions. China Oilfield Services Limited represents the national champion model, leveraging domestic basin access to anchor scale within the Asia-Pacific theater.
| Leading Market Players |
|---|
| Weatherford International Plc |
| TETRA Technologies, Inc. |
| Schlumberger Limited |
| National Oilwell Varco |
| China Oilfield Services Limited |
| Halliburton Company |
| Expro Group |
| Oil States Energy Services |
| Baker Hughes Company |
| Others |
Cost & Logistics Intelligence
Integrated operators in the Permian Basin and Gulf of Mexico anchor procurement volume, concentrating negotiating leverage around performance-based contracting that bundles equipment rental with real-time data analytics. This buyer concentration shifts pricing power toward service providers with cloud-native platforms and fiber-optic sensing capabilities, while commoditizing conventional surface testing equipment.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated technology bundles from discrete equipment rental and spot-market labor services. Premium tiers capture fiber-optic distributed sensing and predictive diagnostics, while standard tiers cover conventional wireline and surface testing. Price differentiation hinges on certification grade for EU methane compliance and after-sales telemetry bundling. Cost compression in the economy tier intensifies because regional rental firms compete on logistics scale. Shale-focused independents exhibit highest price sensitivity; supermajors with pre-salt and deepwater commitments show lowest.
Supply Chain Analysis
Precision quartz pressure transducer manufacturing rests on Japanese and German specialty producers, while high-temperature alloy forging concentrates in the United States and Norway. Inconel and titanium sponge feedstock draws from Russian and Chinese raw material processors. Single-source vulnerability in precision sensor fabrication exposes lead times to regional logistics disruptions. Distribution runs through integrated service company direct sales forces and regional equipment rental depots anchored in Midland, Stavanger, and Dhahran.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA methane monitoring mandates and EU Green Deal compliance frameworks compound regulatory-driven demand, transforming well testing from episodic equipment rental into continuous monitoring infrastructure.
For Market Incumbents: Anchor premium positioning through backward integration into fiber-optic sensor manufacturing and captive cloud platform development. Consolidate regional rental firms to secure logistics density in the Permian Basin and North Sea. Vertical integration into permanent downhole monitoring hardware defends margins against software-native entrants. For New Entrants and Emerging Players: Geothermal developers in Nevada and Utah represent an underserved buyer archetype requiring high-temperature tool adaptation. Carbon capture site operators need formation injectivity testing with limited incumbent penetration. A specialized equipment-plus-telemetry bundling approach unlocks initial contracts without competing head-to-head on offshore logistics scale. For Investors and Strategic Acquirers: Integrated oilfield service conglomerates are the most active acquirer in this space, targeting fiber-optic sensing specialists and cloud analytics platforms. Long-term viability favors providers with regulatory certification depth across multiple jurisdictions. Watch EPA enforcement intensity and EU methane penalty implementation as inflection indicators for continuous monitoring demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Fiber-Optic Sensing Platform Integration | Permian Basin operators retrofit existing wells with distributed acoustic sensing for microseismic and leak detection. |
| EU Methane Compliance Certification | Automated optical gas imaging systems satisfy quarterly leak detection surveys under EU Green Deal mandates. |
| Geothermal Tool Adaptation | Enhanced geothermal systems in Nevada deploy high-temperature downhole testing tools adapted from oilfield technology. |
| Performance-Based Contracting | Brazilian pre-salt developments favor consolidated accountability through drilling efficiency-linked agreements. |
| Carbon Capture Site Characterization | Saline aquifer injection programs require formation injectivity testing and caprock integrity verification services. |
Research Approach
Direct dialogue with reservoir engineers, drilling superintendents, regulatory compliance officers, and procurement leads at national oil companies grounded qualitative findings. Secondary validation drew from EPA enforcement databases, EU ETS emissions registries, NMPA equipment certification filings, and customs trade records for high-specification alloy imports. Bottom-up service provider revenue aggregation and top-down operator capital expenditure analysis enabled triangulation across the analysis window.
Segmented outputs by service type, technology tier, end-user category, and application geography fed into the projection framework. CAGRs derived from historical demand elasticity to drilling activity, regulatory implementation timelines, and technology substitution curves. Formation testing intensity per unconventional well and offshore facility commitment schedules served as key forecast inputs.
Underlying measurement precision varies by segment; production testing and surface equipment carry tighter precision than emerging advanced sensor deployments. Forecasts reflect assumptions around regulatory enforcement consistency and technology adoption curves. Supply chain disruptions in precision sensor manufacturing or alloy feedstock warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Middle East and North Africa Oilfield Services Market
Oil & Gas
Venezuela Oil and Gas Market
Oil & Gas
Asia-Pacific LNG Bunkering Market
Oil & Gas
Oil and Gas Field Services Market
Oil & Gas
Floating Liquefied Natural Gas (FLNG) Terminals Market
Oil & Gas
United States Oil and Gas Separation Market
Oil & Gas
Oil & Gas Defoaming Separator Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Drones for Oil & Gas Market
Oil & Gas
North America Shale Market
Oil & Gas
Drilling Services Market
Oil & Gas
North America Perforating Gun Market
Oil & Gas
Crude Oil Carriers Market
Oil & Gas
Mexico Wireline Services Market
Oil & Gas
Smart Pigging Market
Oil & Gas
US Sand Control Systems Market