
 Cuttings Re-Injection Services Market | 2026-2036
Cuttings Re-Injection Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cuttings Re-Injection Services Market Outlook
Managed pressure drilling subscriptions bundled with cuttings re-injection is restructuring how offshore contracts are priced and awarded. Baker Hughes Company leverages its integrated drilling-waste portfolio to anchor long-term North Sea service agreements. Halliburton competes through proprietary slurry optimization technology that reduces injection downtime. Schlumberger dominates deepwater deployment with automated cuttings handling systems tied to digital wellsite platforms.
Cuttings re-injection services encompass the subsurface disposal of drilled rock fragments and drilling fluids through dedicated wellbores, typically requiring slurry densities between 10 and 16 pounds per gallon and annular friction pressures managed below formation fracture gradients to prevent caprock breach. These services eliminate surface discharge of oil-based mud residues and synthetic drilling waste, satisfying zero-discharge mandates on offshore platforms and sensitive onshore ecosystems. Offshore service type leads revenue contribution due to higher per-well waste volumes and regulatory stringency, while BAR technology represents the fastest-growing segment as operators seek borehole annulus remediation solutions that extend well integrity. Mobile deployment units capture expanding margin pools in remote frontier basins where fixed facility economics fail.
The EPA governs underground injection control through Class II well permitting, while OSPAR Convention signatories enforce zero-discharge thresholds for drilling waste in the Northeast Atlantic. These frameworks compel operators to contract certified re-injection services rather than pursue surface treatment or sea dumping alternatives. Stakeholders must monitor evolving carbon accounting rules that may recast subsurface waste disposal as either emissions-reducing or liability-creating depending on methane migration risk assessments.
Market Dynamics
Managed pressure drilling bundles now dominate offshore contract structures, forcing service providers to integrate cuttings handling with real-time pressure control or exit premium North Sea basins entirely.
Growth Catalysts
- OSPAR zero-discharge mandates:Northeast Atlantic operators must eliminate sea dumping of oil-based drilling residues, converting compliance spending into contracted re-injection service demand.
- Borehole annulus remediation (BAR) technology:This segment addresses integrity failures in aging wellbores, extending productive life of high-cost offshore assets.
- Remote frontier basin expansion:West African and South American deepwater projects lack fixed disposal infrastructure, creating pull for mobile re-injection units.
Market Restraints
- Specialized vessel and equipment costs:Mobile slurry processing units require capital deployment that only supermajors and national oil companies can absorb.
- Caprock integrity uncertainty:Subsurface fracture gradient miscalculation risks groundwater contamination liability, constraining service expansion in karst geology zones.
- EPA Class II well permitting timelines:US onshore projects face 18-24 month approval cycles that delay revenue recognition and tie up technical personnel.
Strategic Opportunities
- Carbon accounting integration:Methane migration risk scoring may recast subsurface disposal as emissions-reducing, opening ESG-linked financing for service providers.
- Real-time slurry monitoring:Convergence of automated density sensors with digital wellsite platforms enables predictive injection pressure management.
- Decommissioning waste streams:North Sea well abandonment programs generate contaminated cuttings stockpiles requiring certified re-injection, not surface treatment.
Industry Challenges
- Subsurface geomechanics expertise scarcity:Caprock stress analysis and fracture modeling require petroleum engineers with specialized training that universities are not producing at replacement rates.
- Legacy wellbore compatibility:Pre-digital era casing designs lack pressure ratings and monitoring access needed for safe slurry injection, forcing costly workovers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cuttings Re-Injection Services Market |
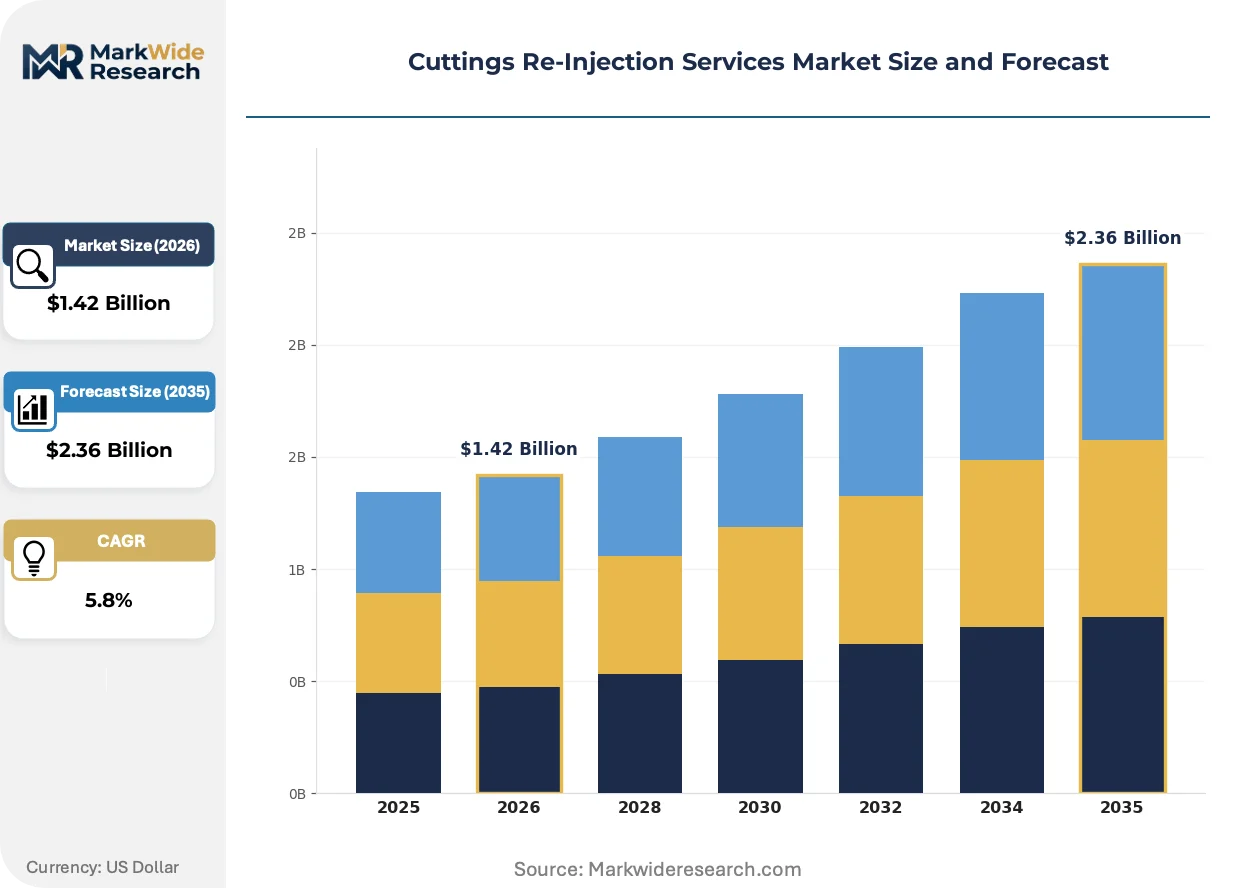
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Onshore, Offshore, Landfill, BAR Technology End User: Oil & Gas Companies, Drilling Contractors, Environmental Agencies, Waste Management Firms Deployment: Mobile Units, Fixed Facilities, Dedicated Platforms, Temporary Installations Technology: Thermal Management, Solidification, Biodegradation, Chemical Treatment |
| Companies Covered | Baker Hughes Company, Halliburton, Schlumberger, NOV Inc., Weatherford International, TWMA, Advantek, Augean PLC, GN Solids Control, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cuttings Re-Injection Services Market Strategic Shifts
Automation and predictive analytics are compressing the operational window between drilling waste generation and subsurface disposal, eliminating surface storage hazards and reducing platform footprint requirements.
Automated cuttings handling systems are converging with digital wellsite platforms to enable real-time slurry density adjustment based on downhole pressure feedback. Deepwater operators in the Gulf of Mexico and offshore Brazil are deploying these integrated stacks on sixth-generation drillships. This convergence is compressing injection cycle times and reducing manual intervention during high-risk pressure transitions.
REACH chemical authorization rules in Europe are tightening the allowable composition of synthetic drilling fluids, forcing mud suppliers to reformulate base stocks. These changes cascade into re-injection service specifications, as slurry compatibility testing must now cover novel surfactant packages. North Sea contractors are responding by embedding fluid chemists within field service teams.
Integrated service contracting now dominates procurement decisions, with operators bundling waste disposal into multi-year drilling agreements rather than awarding standalone re-injection work. This consolidation favors vendors with captive pressure control and cementing capabilities. The shift is most visible in Norway, where Equinor and Aker BP have eliminated discrete waste service tenders from their 2024-2028 offshore frameworks.
Cuttings Re-Injection Services Market Segmentation
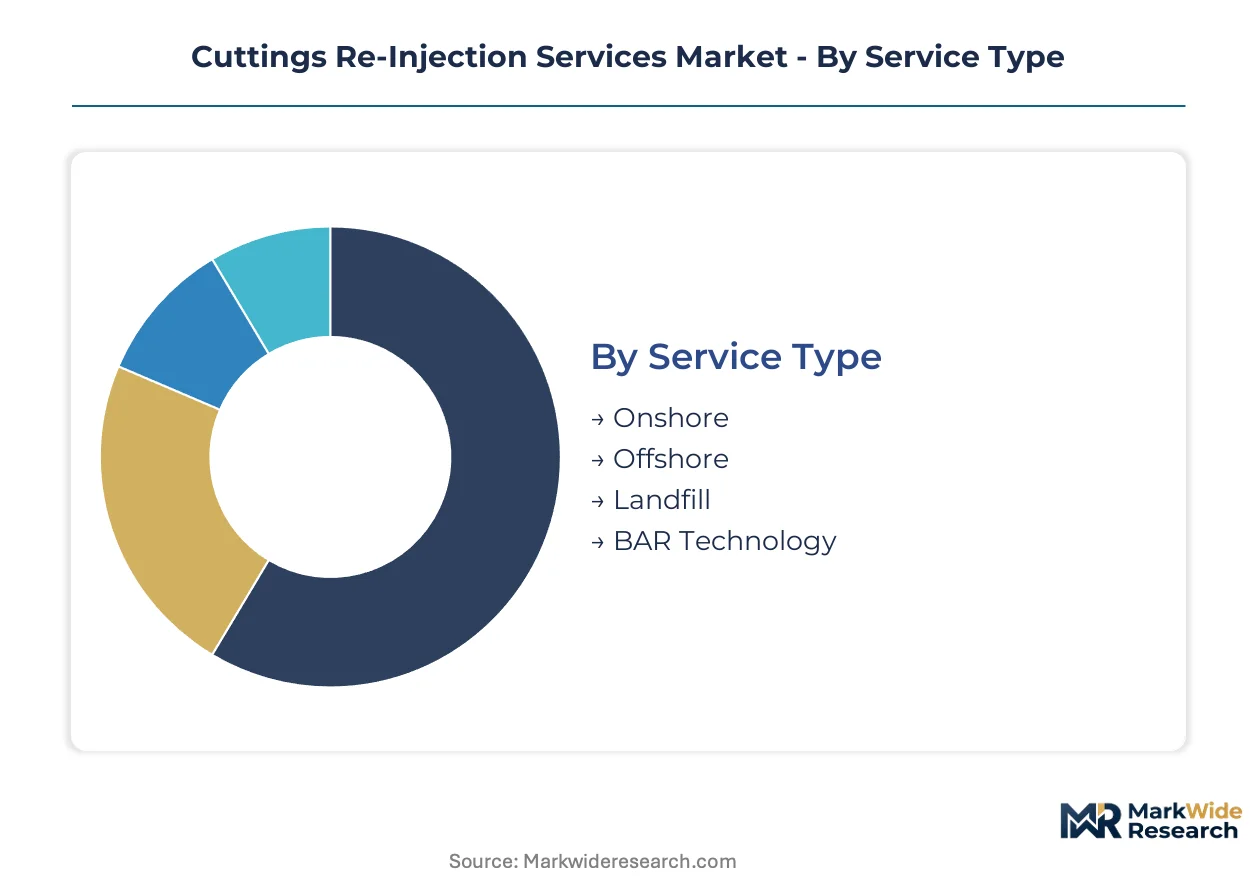
Segmentation in cuttings re-injection services reveals how regulatory pressure and operational complexity concentrate value across distinct service configurations. Each category maps to specific capital deployment patterns and risk profiles that shape vendor selection criteria.
Service Type:
Supply concentration in offshore service provision reflects the specialized vessel and platform infrastructure required for zero-discharge compliance in marine environments.
- Offshore:Subsurface disposal operations conducted from drilling platforms and floating production units handle slurry densities between 10 and 16 pounds per gallon. Demand concentrates in Norway, the United Kingdom, and Denmark where OSPAR zero-discharge mandates eliminate sea dumping alternatives.
- Onshore:Wellhead injection services for land-based drilling operations rely on Class II well permitting under EPA oversight. Operators in Texas and North Dakota face 18-24 month approval cycles that constrain service velocity.
- Landfill:Surface containment solutions for non-hazardous drilling residues serve jurisdictions with limited subsurface injection access.
- BAR Technology:Borehole annulus remediation addresses integrity failures in aging wellbores, extending productive life of high-cost offshore assets.
Today's leader: Offshore. Tomorrow's challenger: BAR Technology.
End User:
Cost tier differentiation separates integrated operators with captive waste handling capabilities from contractors purchasing discrete environmental services.
- Oil & Gas Companies:Supermajors and national oil companies deploy capital for dedicated injection infrastructure, absorbing specialized vessel costs that smaller players cannot finance.
- Drilling Contractors:Firms like Transocean and Seadrill bundle waste disposal into day-rate contracts, transferring compliance risk to service providers.
- Environmental Agencies:Government bodies contract certified re-injection for legacy contamination sites and decommissioning stockpiles.
- Waste Management Firms:Specialized environmental service companies intermediate between drillers and subsurface disposal operators.
Integrated operators dominate contract volume. Standalone environmental agencies represent the fastest-expanding procurement channel.
Deployment:
Application context determines whether mobile or fixed infrastructure delivers superior unit economics across frontier versus mature basins.
- Mobile Units:Self-contained slurry processing systems deploy to West African and South American deepwater projects lacking fixed disposal infrastructure. These units capture expanding margin pools in remote frontier basins.
- Fixed Facilities:Permanent injection well networks serve high-activity regions with predictable waste generation profiles.
- Dedicated Platforms:Purpose-built offshore structures house automated cuttings handling systems tied to digital wellsite platforms.
- Temporary Installations:Modular equipment packages address short-duration drilling campaigns and well abandonment programs.
Fixed facilities anchor revenue stability. Mobile units command the steepest expansion trajectory.
Technology:
Maturity gradients separate proven thermal and solidification methods from emerging biological and chemical approaches with unproven scale economics.
- Thermal Management:Heat-based slurry conditioning maintains fluid properties within operational windows for safe subsurface injection.
- Solidification:Cement and pozzolan-based stabilization converts liquid drilling waste into pumpable solids with controlled setting characteristics.
- Biodegradation:Microbial treatment systems reduce organic contaminant loads in synthetic drilling fluids, responding to REACH chemical authorization tightening in Europe.
- Chemical Treatment:Surfactant and polymer packages modify slurry rheology for compatibility with formation fracture gradients.
Solidification holds current volume leadership. Biodegradation approaches gain share fastest as mud suppliers reformulate base stocks under tightening European chemical rules.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norway commands premium pricing for offshore cuttings re-injection, while the United Kingdom competes through integrated decommissioning contracts. Regulatory divergence between North Sea jurisdictions is fragmenting service standardization.
Norway
Equinor and Aker BP drive demand through bundled drilling-waste procurement frameworks. The Norwegian Environment Agency enforces zero-discharge compliance through discharge permits tied to OSPAR Convention obligations. Stavanger anchors the country's service concentration, with contractors co-locating technical personnel alongside operator headquarters.
United Kingdom
North Sea decommissioning programs generate contaminated cuttings stockpiles requiring certified subsurface disposal. The Offshore Petroleum Regulator for Environment and Decommissioning oversees waste management consent applications. Aberdeen maintains its position as the primary service coordination hub, though mobile units increasingly deploy from Great Yarmouth for southern basin campaigns.
United States
Gulf of Mexico deepwater operators deploy automated cuttings handling systems on sixth-generation drillships. EPA Class II well permitting creates 18-24 month approval cycles that constrain service velocity. Houston hosts the principal vendor engineering centers, while Port Fourchorn serves as the logistics marshaling point for offshore mobilizations.
Brazil
Pre-salt development generates substantial drilling waste volumes without fixed disposal infrastructure. ANP regulatory frameworks mandate environmental licensing for injection operations in sensitive coastal zones. Macae and Rio de Janeiro concentrate service provider technical offices, with mobile processing units staging from Pecém port for northern basin campaigns.
Saudi Arabia
Aramco's unconventional gas programs require cuttings re-injection for water-sensitive formations. The Ministry of Energy oversees environmental compliance through the National Center for Environmental Compliance. Dhahran anchors vendor technical support functions, while Jubail Industrial City hosts slurry processing equipment fabrication.
Cuttings Re-Injection Services Market Competitive Environment
Top-tier vendors anchor integrated service contracting, while mid-tier specialists compete on mobile deployment flexibility. The vendor base concentrates around three strategic archetypes: full-service oilfield conglomerates with captive pressure control portfolios, environmental specialists with certified waste handling credentials, and equipment fabricators supplying modular slurry systems. Dominant competitive moves include backward integration into real-time monitoring technology and geographic expansion through mobile unit leasing partnerships.
Among Houston-based conglomerates, Baker Hughes Company and Halliburton occupy positions exemplifying integrated drilling-waste portfolio strategies, while Schlumberger anchors the deepwater automation tier. These entities represent the full-service archetype through bundled procurement structures that operators increasingly mandate. Mid-tier environmental specialists and Chinese equipment fabricators such as GN Solids Control compete outside this integrated core through standalone service offerings and modular system supply.
| Leading Market Players |
|---|
| Baker Hughes Company |
| Halliburton |
| Schlumberger |
| NOV Inc. |
| Weatherford International |
| TWMA |
| Advantek |
| Augean PLC |
| GN Solids Control |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up environmental specialists have consolidated mobile slurry processing assets across the North Sea, tightening supply discipline while operators absorb specialized vessel costs through multi-year drilling contracts. This ownership pattern concentrates pricing power among integrated service providers and forces mid-tier contractors into equipment leasing arrangements that compress margins.
Pricing Analysis
Capacity additions in the Gulf of Mexico are reshaping price floors for automated cuttings handling systems as sixth-generation drillships deploy integrated stacks. Contract-based long-term offtake dominates procurement, with Equinor and Aker BP eliminating discrete waste tenders from their frameworks. Price differentiation rests on certification tier—OSPAR-compliant operators command premiums over jurisdictions with looser discharge rules. Cost compression in mobile unit leasing is intensifying because supermajors internalize fixed infrastructure, leaving only frontier basin work for standalone providers. Drilling contractors like Transocean and Seadrill exhibit highest price sensitivity, while national oil companies absorb premiums for integrated pressure control bundling.
Supply Chain Analysis
Dual-sourcing requirements from North Sea operators mandate qualified backup providers for caprock stress analysis and slurry optimization services, fragmenting vendor concentration. Supply concentrates in Norway, the United Kingdom, and the United States, with Houston hosting principal engineering centers and Aberdeen anchoring service coordination. Raw material dependencies include high-pressure pumping equipment, automated density sensors, and synthetic drilling fluid base stocks. Single-source vulnerability runs through specialized subsurface geomechanics expertise, as universities fail to produce petroleum engineers at replacement rates. Distribution runs through operator headquarters co-location—Stavanger, Aberdeen, and Dhahran—rather than independent channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cuttings re-injection services market functions as a stable compounder, with regulatory compliance mandates under OSPAR and EPA frameworks generating contracted demand that resists commodity cyclicality.
For Market Incumbents: Acquire subsurface geomechanics consulting capabilities to address the talent scarcity constraining service expansion in karst geology zones. Baker Hughes Company and Halliburton should deepen backward integration into real-time slurry monitoring technology before Schlumberger extends its digital wellsite platform dominance. Defensive positioning requires embedding fluid chemists within field teams to manage REACH-driven surfactant reformulation, converting compliance complexity into switching costs. For New Entrants and Emerging Players: Capture mobile unit deployment opportunities in Brazil's pre-salt basins where ANP environmental licensing has lagged fixed infrastructure development. West African deepwater projects present parallel white-space for self-contained slurry processing systems lacking local disposal networks. A go-to-market angle through equipment leasing partnerships with national oil companies bypasses the capital barriers blocking direct contract pursuit. For Investors and Strategic Acquirers: Valuations sit cheapest among environmental specialists with certified waste handling credentials but without captive pressure control portfolios, as integrated contracting trends strand standalone providers. The five-to-ten year viability framing favors vendors with BAR technology capabilities addressing North Sea decommissioning stockpiles. The signal to watch is methane migration risk scoring methodology—carbon accounting recasts would trigger ESG-linked financing inflows and re-rate subsurface disposal leaders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Real-Time Monitoring | Automated density sensors tied to digital wellsite platforms compress injection cycle times for Gulf of Mexico drillship operators. |
| Mobile Unit Leasing Partnerships | Equipment fabricators like GN Solids Control access frontier basin margins without absorbing specialized vessel capital deployment. |
| BAR Technology Capability Buildout | Borehole annulus remediation extends productive life of high-cost North Sea assets facing abandonment programs. |
| Fluid Chemistry Team Embedding | Field-based chemists manage REACH-driven surfactant reformulation, converting compliance complexity into client switching costs. |
| Carbon Accounting Certification | Methane migration risk scoring opens ESG-linked financing channels and re-rates subsurface disposal as emissions-reducing. |
Study Parameters
Coverage spans Norway, the United Kingdom, the United States, Brazil, and Saudi Arabia, with primary inputs from each jurisdiction triangulated against secondary validation. Interviews with drilling waste procurement officers, petroleum engineering directors, environmental compliance managers, and slurry processing equipment fabricators combined with EPA Class II permitting databases, OSPAR discharge permit records, ANP environmental licensing filings, and operator framework agreement disclosures. Bottom-up well count and waste volume estimates reconciled with top-down service provider revenue segmentation across the analysis window.
Granularity-level modeling disaggregated service type, deployment configuration, technology maturity, and end-user cost tier across the projection horizon. CAGRs derived from regulatory mandate timing, frontier basin development schedules, and decommissioning program phasing. Industry-specific forecast inputs included OSPAR zero-discharge compliance deadlines and EPA permitting velocity assumptions.
Regulatory enforcement intensity, caprock integrity incident frequency, and methane migration assessment methodology shifts are the dominant revision risks to modeled outputs. Deviation in OSPAR signatory adoption timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Global Oil Line Corrosion Inhibitors Market
Oil & Gas
Singapore LNG Storage Tank Market
Oil & Gas
Land Drilling Rig Market
Oil & Gas
Gabon Oil and Gas Market
Oil & Gas
Romania Oil and Gas Market
Oil & Gas
Drilling Bits Market
Oil & Gas
Oil and Gas Security Services Market
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
Latin America AI in Oil and Gas Market
Oil & Gas
Asia Pacific Oil Storage Tank Service Market
Oil & Gas
Wireline Services Market
Oil & Gas
Zonal Isolation Market
Oil & Gas
West Africa Oil and Gas Midstream Market
Oil & Gas
Denmark Oil and Gas Midstream Market
Oil & Gas
Exploration and Drilling Security Market
Oil & Gas
Bunker Liners Market