
 Oilfield Drilling Elevator Market | 2026-2036
Oilfield Drilling Elevator Market Size, Share, and Industry Trends Forecast 2026-2036
Oilfield Drilling Elevator Market Analysis
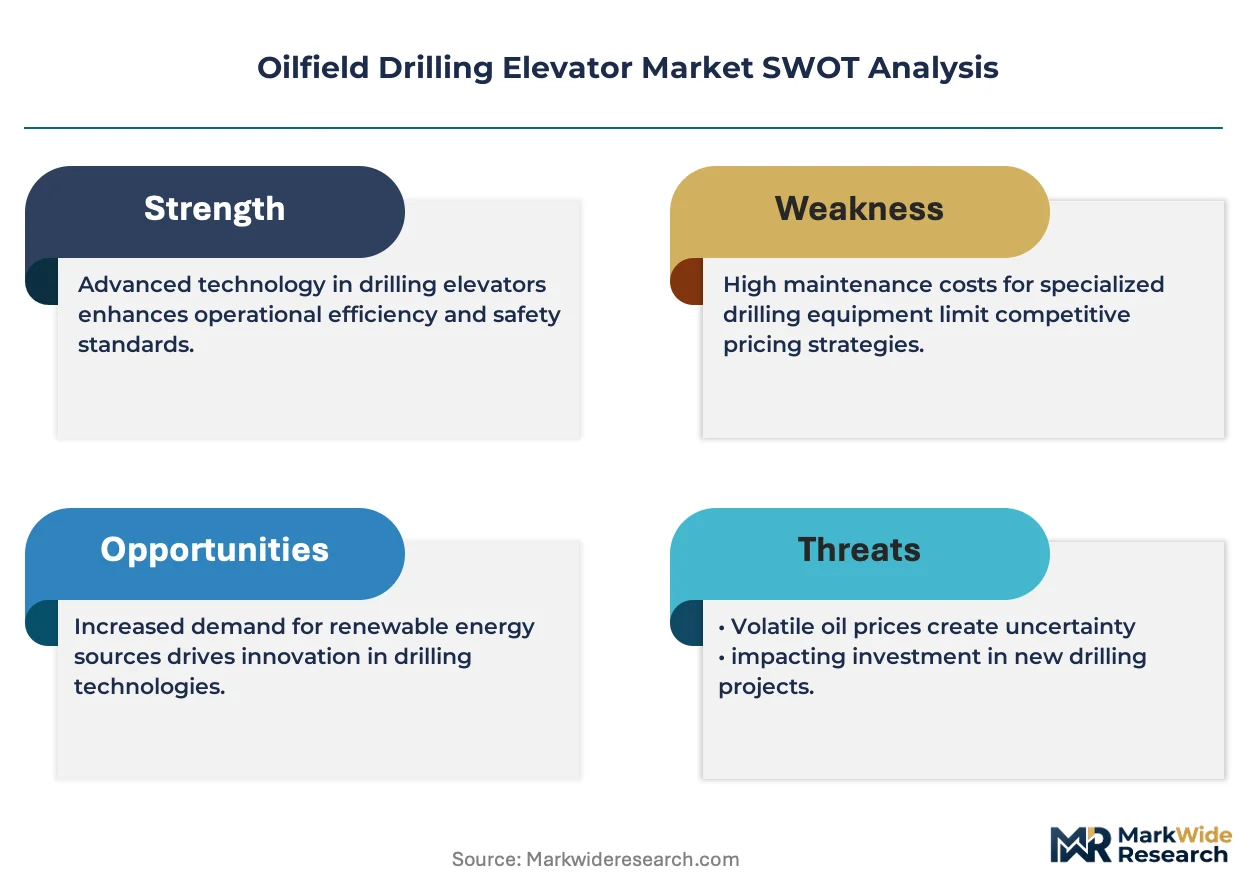
API 8C-certified load ratings is reorganizing procurement priorities among drilling contractors. National Oilwell Varco dominates integrated manufacturing of power elevators for harsh-environment deployments. Forum Energy Technologies differentiates through aftermarket service density across North American shale basins. Yantai Jereh Oilfield Services Group anchors cost-competitive mechanical elevator supply for Asian drilling contractors.
An oilfield drilling elevator is a hoisting tool engineered to API 8C standards, typically forged from alloy steel with rated load capacities spanning 150 to 1,000 short tons, designed to grip and lift drill pipe, casing, and tubing during tripping operations. Hydraulic elevators command premium positioning in deepwater applications where continuous-duty cycles exceed mechanical alternatives. Smart technology segments are gaining fastest traction as offshore operators integrate load-monitoring sensors and automated slip engagement to reduce crew exposure and non-productive time. Conventional technology still occupies the majority installed base across onshore drilling fleets where capital replacement cycles extend seven to ten years.
API 8C governs design, manufacture, and inspection requirements for drilling elevators in the United States, while the EU Machinery Directive and CE marking shape market access for European offshore suppliers. The US Bureau of Safety and Environmental Enforcement enforces incident-reporting thresholds that accelerate replacement of legacy manual elevators with automated systems. Stakeholders must monitor regulatory divergence between prescriptive API standards and performance-based European frameworks when configuring global product portfolios.
Market Dynamics
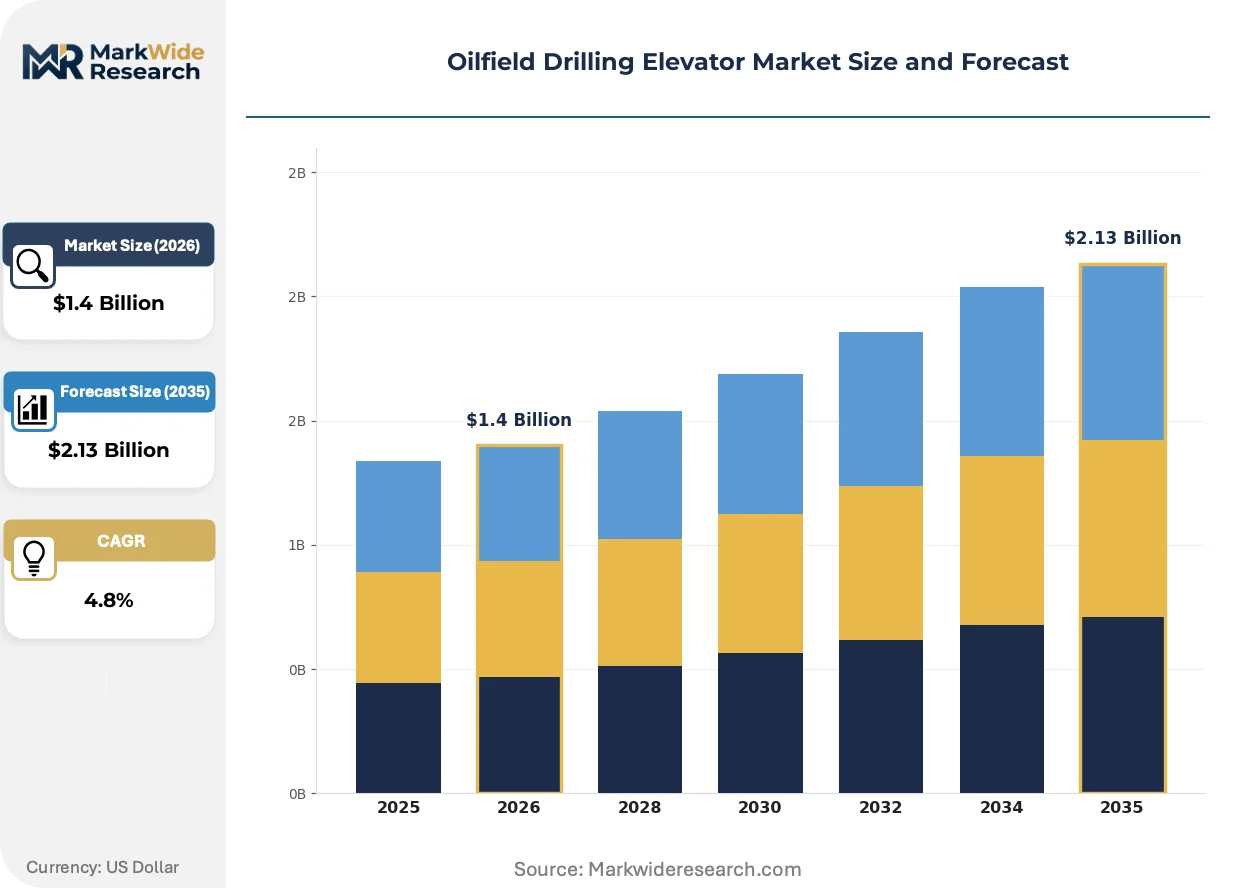
API 8C specification revisions are compressing replacement cycles for legacy manual elevators while hydraulic automation penetrates deepwater corridors. Offshore operators face mandatory load-rating upgrades that force capital redeployment toward sensor-integrated handling systems.
Growth Catalysts
- Deepwater automation mandates:The US Bureau of Safety and Environmental Enforcement enforces incident-reporting thresholds that accelerate replacement of manual elevators with automated slip-engagement systems in Gulf Coast operations.
- EU Machinery Directive compliance:CE marking requirements for European offshore suppliers are elevating design standards that penetrate export markets through harmonized safety protocols.
- Alloy steel forging advances:Continuous-duty hydraulic elevators forged from high-grade alloy steel now sustain load capacities exceeding 1,000 short tons in subsea tripping operations.
Market Restraints
- Specialized foundry concentration:Forged alloy steel capacity concentrates among a limited supplier base in heavy-industry corridors, exposing procurement to input bottlenecks.
- API 8C certification timelines:Prescriptive inspection protocols extend qualification periods for new elevator designs, delaying market entry for mechanical alternatives.
- Mechanical elevator substitution:Conventional grip mechanisms retain installed-base dominance in onshore fleets where seven-to-ten-year replacement cycles compress near-term upgrade demand.
Strategic Opportunities
- Asian contractor cost optimization:Chinese and Southeast Asian drilling contractors are expanding procurement of mechanical elevators from cost-competitive regional manufacturers.
- Sensor-telemetry convergence:Load-monitoring sensors paired with automated slip engagement create white space for predictive maintenance contracts in harsh-environment deployments.
- North American shale service density:Aftermarket parts and field service networks can capture recurring revenue from fragmented onshore rig operators.
Industry Challenges
- Automation technician scarcity:Hydraulic elevator deployment requires specialized crews trained in sensor calibration and automated grip control, creating hiring bottlenecks in deepwater hubs.
- Legacy fleet integration friction:Retrofitting automated handling systems onto existing mast configurations demands custom engineering that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oilfield Drilling Elevator Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Elevators, Mechanical Elevators, Manual Elevators, Power Elevators Technology: Conventional Technology, Smart Technology, Automated Systems, Digital Solutions End User: Oil & Gas Companies, Drilling Contractors, Offshore Operators, Energy Service Providers Application: Onshore Drilling, Offshore Drilling, Workover Operations, Maintenance Services |
| Companies Covered | Forum Energy Technologies, Frank's International, National Oilwell Varco, Weatherford International, Yantai Jereh Oilfield Services Group, Jereh Group, Texas Oilfield Company, Schlumberger, Halliburton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oilfield Drilling Elevator Market Emerging Trajectories
Smart load-monitoring systems are penetrating offshore installations as operators prioritize crew safety and non-productive time reduction. Technology trajectories diverge between deepwater automation and onshore mechanical longevity.
Sensor-integrated elevator systems are fragmenting the conventional supplier landscape. These platforms embed real-time load telemetry and automated slip engagement to eliminate manual handling exposure. Offshore contractors in the US Gulf Coast are adopting these systems fastest, with deployment cycles compressing from annual overhauls to continuous monitoring. The technology is fragmenting aftermarket service models by enabling predictive maintenance contracts that displace traditional break-fix arrangements.
REACH chemical compliance and the EU Machinery Directive are reshaping material specifications for European offshore suppliers. These frameworks restrict certain alloy treatments while mandating traceability documentation through the supply chain. Manufacturers serving North Sea installations must requalify forging processes, with certification costs concentrating among mid-tier mechanical elevator producers.
Buyer consolidation among drilling contractors is compressing procurement negotiation cycles. Large fleet operators now demand unified API 8C certification documentation across multiple rig classes, displacing fragmented supplier relationships. This pattern is most visible in the US Gulf Coast deepwater corridor where integrated drilling companies leverage scale for standardized elevator specifications.
Oilfield Drilling Elevator Market Segmentation
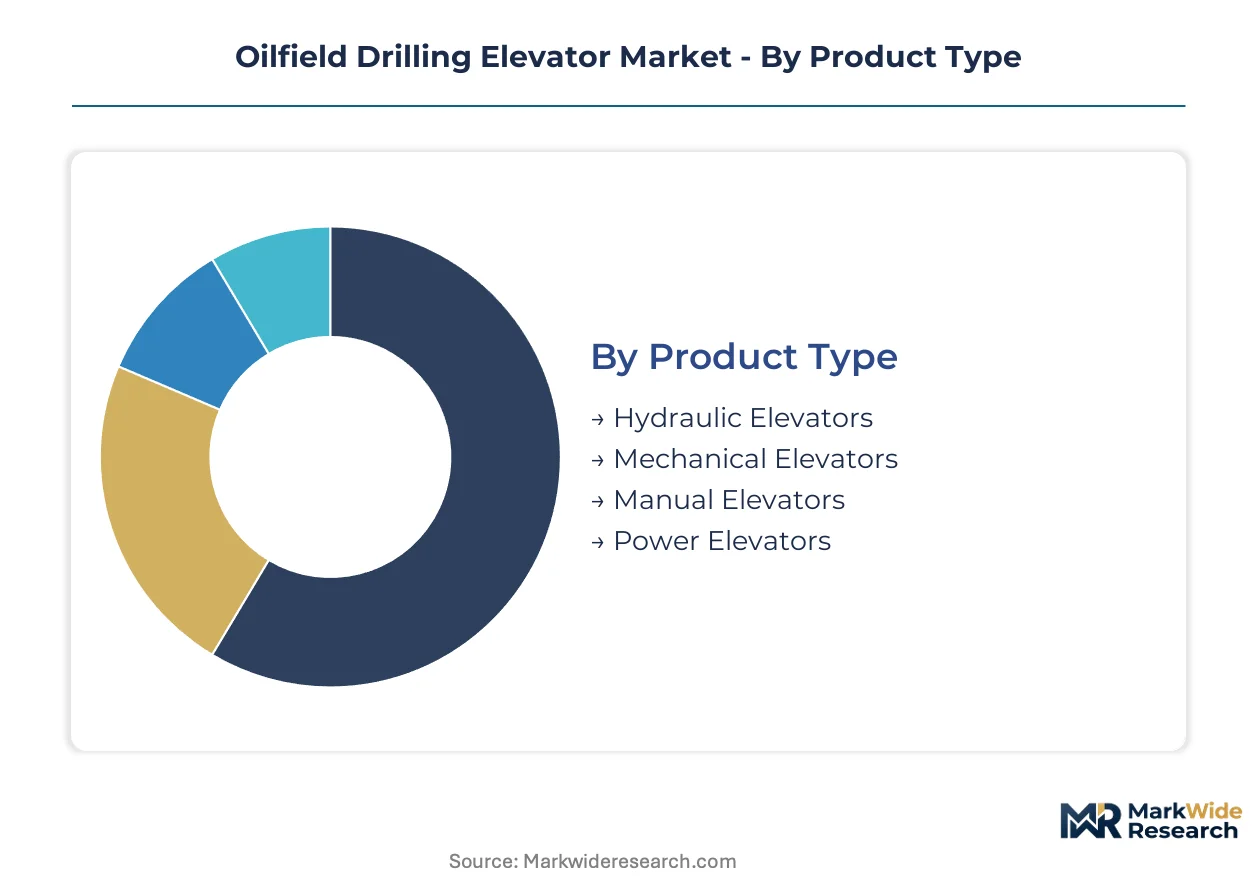
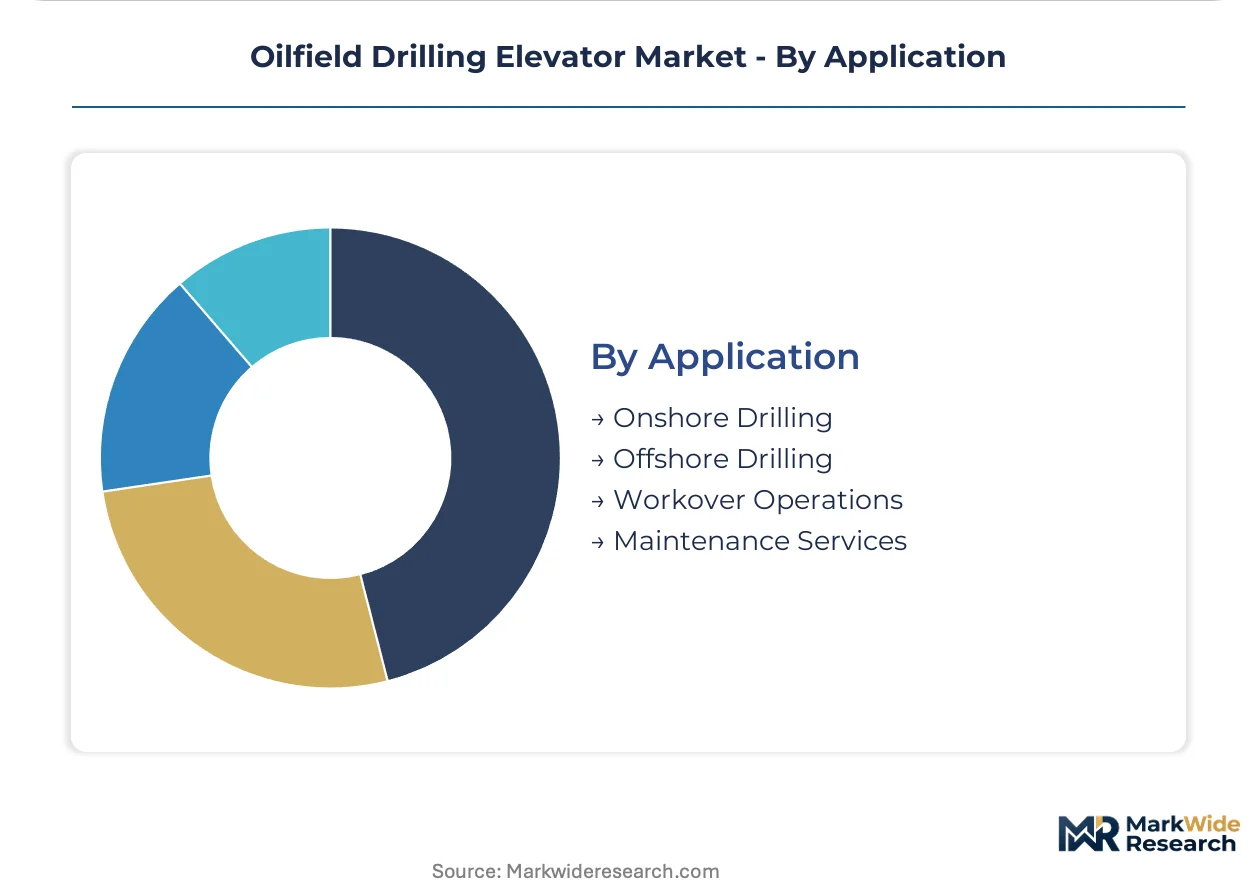
Segmentation in the oilfield drilling elevator market reveals divergent procurement patterns between deepwater automation mandates and onshore mechanical longevity. Regulatory pressure from BSEE and API 8C revisions are compressing technology choices differently across operator types and geographies.
Product Type:
API 8C certification requirements create asymmetric barriers across forging-intensive product categories, privileging established hydraulic manufacturers over mechanical entrants.
- Hydraulic Elevators:Forged from high-grade alloy steel with continuous-duty cycles exceeding 1,000 short ton ratings. Gulf Coast deepwater operators concentrate procurement here as BSEE incident-reporting thresholds mandate automated slip-engagement systems.
- Mechanical Elevators:Grip mechanisms relying on manual wedge engagement dominate installed-base economics. Onshore fleets across Texas and Oklahoma retain seven-to-ten-year replacement cycles that compress near-term upgrade demand.
- Manual Elevators:Legacy forged designs facing accelerated replacement timelines under revised load-rating protocols.
- Power Elevators:Integrated hoisting systems with motorized grip control for high-frequency tripping operations.
Established volume favors mechanical elevators; emerging adoption favors hydraulic elevators.
Technology:
Cost tier differentiation separates sensor-integrated platforms from conventional forged equipment, with premium pricing concentrated in offshore deployment corridors.
- Smart Technology:Embedded load-monitoring sensors with real-time telemetry and predictive maintenance algorithms. Offshore operators in the US Gulf Coast adopt these fastest, with continuous monitoring displacing annual overhaul cycles.
- Automated Systems:Slip-engagement automation eliminating manual handling exposure. Deepwater contractors face mandatory deployment under BSEE safety frameworks.
- Conventional Technology:Forged alloy steel designs without sensor integration, retaining majority installed base across onshore drilling fleets.
- Digital Solutions:Cloud-connected diagnostics and remote calibration platforms for distributed rig fleets.
Conventional technology retains installed-base dominance; smart technology is climbing the fastest in offshore procurement.
End User:
Customer type determines specification stringency, with integrated oil companies demanding unified API 8C documentation across rig classes.
- Offshore Operators:Deepwater specialists in the Gulf of Mexico and North Sea facing the most stringent BSEE and EU Machinery Directive compliance deadlines.
- Drilling Contractors:Fleet operators consolidating procurement negotiation cycles and standardizing elevator specifications across multiple rig classes.
- Oil & Gas Companies:Integrated majors with captive specification development and long-term supplier relationships.
- Energy Service Providers:Rental and maintenance specialists capturing aftermarket revenue from fragmented onshore rig operators.
Drilling contractors drive standardization momentum; offshore operators pull premium technology adoption.
Application:
Geography and environment dictate automation penetration, with marine exposure accelerating sensor integration beyond land-based deployment economics.
- Offshore Drilling:Subsea tripping operations requiring forged alloy steel ratings above 1,000 short tons with continuous-duty hydraulic cycles. BSEE mandates and crew safety protocols drive fastest technology turnover.
- Onshore Drilling:Permian Basin and Appalachian shale basins where mechanical elevators retain cost advantages and replacement cycles extend across multiple drilling programs.
- Workover Operations:Intervention-focused deployments with intermittent duty cycles favoring modular elevator configurations.
- Maintenance Services:Aftermarket overhaul and recertification work concentrated around API 8C inspection protocols.
Onshore drilling holds volume concentration; offshore drilling gains share fastest in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-manufactured hydraulic elevators flow into deepwater corridors across the Gulf of Mexico, while Chinese mechanical fabricators supply cost-optimized units to Southeast Asian drilling contractors.
United States
Gulf Coast deepwater operators drive automated elevator procurement under BSEE incident-reporting mandates. The Bureau of Safety and Environmental Enforcement enforces load-rating thresholds that accelerate manual system replacement. Houston anchors integrated manufacturing clusters where National Oilwell Varco and Forum Energy Technologies maintain forged-alloy production facilities.
China
State-backed drilling contractors in the South China Sea expand fleet capacity requiring API 8C-certified handling equipment. The Standardization Administration of China (SAC) aligns domestic GB standards with international forging protocols for offshore machinery. Yantai in Shandong Province concentrates mechanical elevator fabrication serving Asian cost-optimization procurement.
Norway
North Sea harsh-environment platforms demand continuous-duty hydraulic ratings exceeding 1,000 short tons. The Norwegian Petroleum Safety Authority enforces performance-based safety frameworks that exceed prescriptive API baselines. Stavanger hosts engineering clusters where automated slip-engagement systems undergo subsea qualification testing.
Brazil
Pre-salt deepwater development drives premium elevator adoption for extended-reach tripping operations. The National Agency of Petroleum, Natural Gas and Biofuels (ANP) mandates localized content requirements that shape supplier selection. Rio de Janeiro concentrates offshore service engineering for integrated drilling contractors.
Saudi Arabia
Aramco drilling programs sustain demand for high-capacity power elevators across onshore and offshore basins. The Saudi Standards, Metrology and Quality Organization (SASO) enforces conformity assessment for imported hoisting equipment. Dhahran anchors procurement decision centers where fleet standardization compresses supplier negotiation cycles.
Oilfield Drilling Elevator Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and aftermarket service density. The market structures around three tiers: integrated oilfield service conglomerates with captive forging capacity, mid-scale regional fabricators serving cost-sensitive contractors, and specialized automation technology vendors. Consolidation pressures concentrate among hydraulic elevator manufacturers where API 8C certification timelines favor incumbents. Competitive moves center on sensor-telemetry convergence and aftermarket service network expansion.
Within the integrated service tier, National Oilwell Varco and Forum Energy Technologies exemplify archetypes spanning forged manufacturing through predictive maintenance contracts. Yantai Jereh Oilfield Services Group occupies a position among Asia-Pacific cost-optimized mechanical fabricators. These three entities represent divergent strategic postures: conglomerate-scale vertical control, aftermarket service density in North American shale basins, and regional manufacturing scale for emerging-market drilling contractors.
| Leading Market Players |
|---|
| Forum Energy Technologies |
| Frank's International |
| National Oilwell Varco |
| Weatherford International |
| Yantai Jereh Oilfield Services Group |
| Jereh Group |
| Texas Oilfield Company |
| Schlumberger |
| Halliburton |
| Others |
Supply Flow & Price Mechanics
API 8C certification gates both supplier qualification and price stratification across the oilfield drilling elevator market, compressing mechanical fabricators into cost-competitive tiers while hydraulic manufacturers command premium positioning through forged-alloy technical barriers. BSEE incident-reporting mandates in the US Gulf Coast simultaneously elevate specification floors and widen spreads between automated and conventional handling systems.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation centers on API 8C certification grade and after-sales service bundling, with sensor-integrated hydraulic platforms commanding substantial premiums over mechanical alternatives. Cost compression in the mechanical tier is intensifying because Asian contractors are consolidating procurement around standardized forged units. National drilling contractors exhibit the highest price sensitivity, while integrated offshore operators prioritize performance over unit economics.
Supply Chain Analysis
Strait of Hormuz transit underwrites alloy steel feedstock security for Middle Eastern fabrication hubs, though forging capacity concentrates in the United States, China, and Norway. Supply draws from high-grade alloy steel billets, precision-machined grip mechanisms, and sensor-telemetry modules. Single-source vulnerability concentrates in specialized foundry corridors serving API 8C-qualified forging. Distribution runs through OEM direct sales for deepwater contracts and regional distributor networks for onshore mechanical replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat story where API 8C certification entrenchment creates substantial switching costs for drilling contractors standardizing fleet specifications. Certification timelines and inspection protocols embed incumbents while fragmenting new entrant access.
For Market Incumbents: Shield market position by deepening backward integration into captive alloy steel forging capacity in Houston and Stavanger corridors. Accelerate sensor-telemetry R&D to outpace mechanical substitution threats from Asian cost competitors. API 8C recertification investment represents the critical defensive lever against mid-tier mechanical fabricators. For New Entrants and Emerging Players: Lead with aftermarket service density in North American shale basins where fragmented rig operators lack integrated maintenance capabilities. The most penetrable white space sits in predictive maintenance contracts for legacy mechanical elevator installed bases. A rental-and-service go-to-market angle bypasses capital-intensive forging barriers while capturing recurring revenue streams. For Investors and Strategic Acquirers: BSEE automation mandates reshapes the acquisition landscape toward sensor-integrated hydraulic specialists with Gulf Coast deployment track records. Long-term viability across the projection horizon favors targets with demonstrated subsea qualification testing and API 8C documentation libraries. The signal to monitor is contractor fleet standardization announcements indicating consolidated procurement leverage.| Strategic Initiative | Industry Significance |
|---|---|
| API 8C Certification Investment | Accelerates market access for forged-alloy hydraulic platforms serving BSEE-mandated deepwater corridors. |
| Sensor-Telemetry Integration | Enables predictive maintenance contracts displacing traditional break-fix arrangements in offshore installations. |
| Backward Integration into Forging | Secures alloy steel supply continuity against specialized foundry concentration bottlenecks. |
| Aftermarket Service Network Expansion | Captures recurring revenue from fragmented onshore rig operators in Permian and Appalachian basins. |
| Regional Manufacturing Footprint | Aligns production proximity with cost-optimization procurement patterns among Asian drilling contractors. |
Methodological Framework
Operator-level perspectives from drilling superintendents, rig maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base. Secondary validation drew from API certification registries, BSEE incident databases, SEC filings of listed oilfield service conglomerates, and customs trade data on alloy steel forging imports. Bottom-up rig-count modeling triangulated against top-down fleet replacement cycle analysis.
Sensitivity analysis tested volume and value outputs across product type, technology tier, application environment, and regional regulatory cluster dimensions throughout the forecast period. CAGRs were derived from rig activity trajectories, replacement cycle compression rates, and technology penetration curves. Specific forecast inputs included Gulf Coast deepwater utilization rates and API 8C recertification timelines.
The analysis sits within stated boundaries; outcomes outside sustained offshore capital commitment or accelerated onshore replacement cycles would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and alloy steel supply stability. Practitioners should keep alternative scenarios live as BSEE mandate expansion and EU Machinery Directive harmonization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Egypt Natural Gas Market
Oil & Gas
United States Oil and Gas Upstream Market
Oil & Gas
Modular Gas Processing Plants Market
Oil & Gas
Crude Oil Carriers Market
Oil & Gas
Europe Completion Equipment and Services Market
Oil & Gas
Europe Seismic Services Market
Oil & Gas
Oil and Gas Security Services Market
Oil & Gas
Planned LNG Market
Oil & Gas
Central Asia Oil and Gas Midstream Market
Oil & Gas
Thailand Oil and Gas Upstream Market
Oil & Gas
Europe Natural Gas Market
Oil & Gas
Kuwait & Iraq Oilfield Chemicals Market
Oil & Gas
3D Printing in Oil and Gas Market
Oil & Gas
Oil and Gas Storage Market
Oil & Gas
Operational Digital Oilfield Solution Market
Oil & Gas
North America Drilling Completion Fluids Market