
 Russian Federation Oil and Gas Market | 2026-2036
Russian Federation Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Russian Federation Oil and Gas Market Analytics
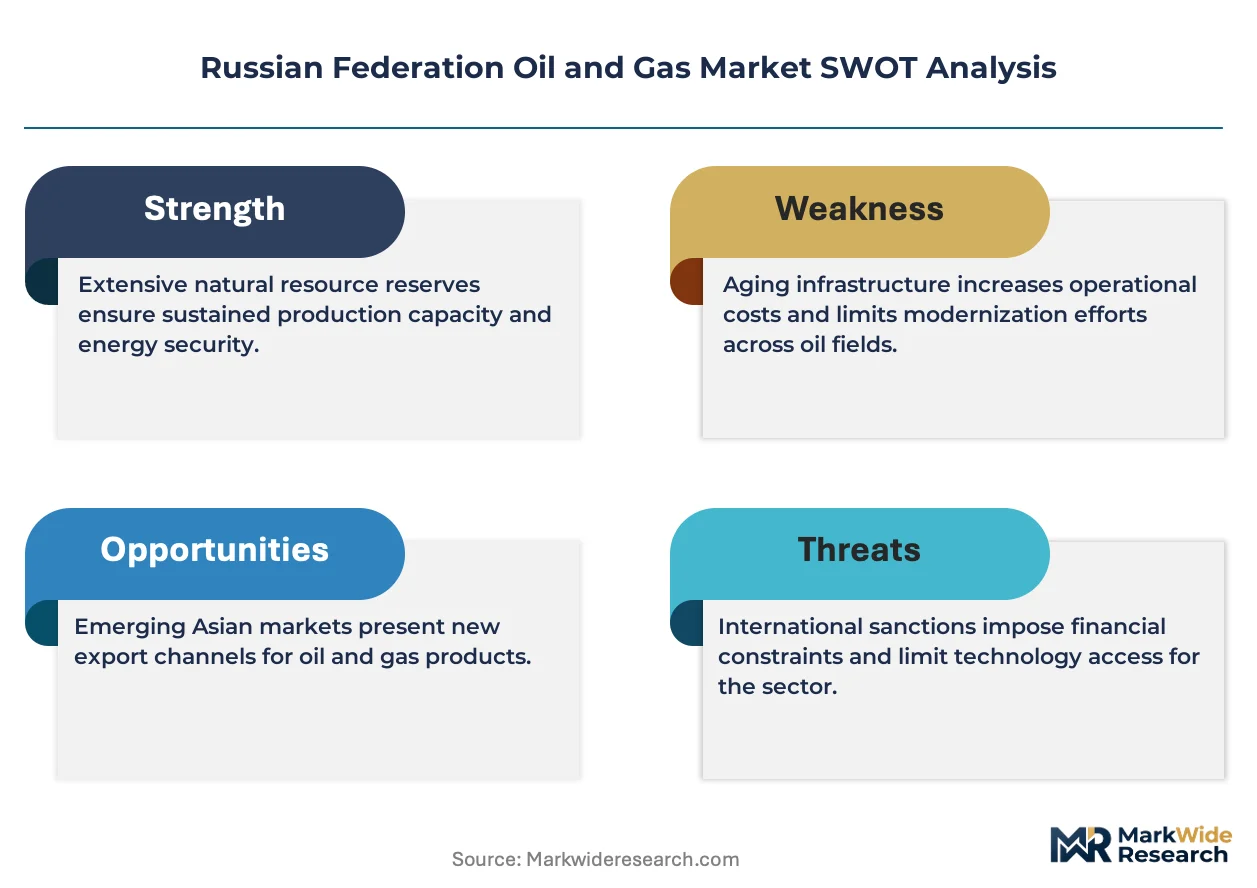
The EU Carbon Border Adjustment Mechanism is hardening compliance costs for Russian hydrocarbon exports still reaching European destinations. Gazprom sustains its dominance through integrated pipeline networks spanning domestic and export corridors. Rosneft Oil Company anchors production scale across Western Siberian brownfields and newer Arctic projects. Novatek differentiates through LNG specialization, leveraging Yamal feedstock for Asian-bound cargoes.
The Russian Federation oil and gas sector encompasses the exploration, extraction, processing, and distribution of hydrocarbon resources including crude oils with API gravities ranging from light sweet to heavy sour grades, plus methane-rich natural gas requiring dehydration and treatment before pipeline injection or liquefaction. Its primary purpose is supplying feedstock for power generation, petrochemical synthesis, and transportation fuel across domestic and export markets. Crude oil and natural gas together occupy the core revenue pool, though liquefied natural gas represents the fastest-expanding product type as Yamal and Arctic LNG projects scale. Conventional onshore extraction dominates volume, while unconventional and offshore categories attract capital for reserve replacement. Pipeline distribution controls the bulk of domestic and cross-border movement, though tanker and railway channels gain share for eastern and Arctic routes.
Russia's Ministry of Energy and Federal Agency for Mineral Resources set licensing terms and production quotas that directly shape field development economics and foreign participation rules. Technical regulation from GOST standards and evolving environmental oversight from Rosprirodnadzor constrain flaring intensities and wastewater discharge at extraction sites. Rosneft Oil Company and Gazprom navigate this framework while competing for Arctic licenses and tax relief under special economic zone provisions. Stakeholders must monitor how sanctions architecture and domestic localization mandates reshape equipment procurement and technology transfer pathways.
Market Dynamics
Russia's pipeline redirection toward Asian offtakers is compressing European contract tenors while forcing capital redeployment into eastern liquefaction infrastructure and Arctic tanker routes.
Growth Catalysts
- Arctic LNG Scale-Up:Yamal feedstock expansion targets Chinese and Indian term buyers through ice-class tanker corridors. Novatek's liquefaction trains anchor this pivot.
- Domestic Petrochemical Feedstock Demand:Ministry of Energy quotas prioritize methane-to-methanol and ammonia synthesis for fertilizer export programs.
- Tax Relief Zones:Special economic zone provisions in the Yamal-Nenets Autonomous Okrug reduce MET burdens for greenfield developments above 66 degrees latitude.
Market Restraints
- Equipment Localization Mandates:Domestic content rules for subsea hardware and compressors extend procurement timelines as Western OEMs exit.
- EU Carbon Border Adjustment Mechanism:Embedded emissions accounting raises delivered-cost spreads for residual pipeline volumes still reaching European destinations.
- Arctic Ice Window Constraints:Northern Sea Route navigability limits year-round tanker dispatch, forcing seasonal storage builds at Murmansk transshipment points.
Strategic Opportunities
- Eastern Siberia Field Development:Kovykta and Chayanda gas condensate complexes await pipeline tie-ins to Power of Siberia expansion corridors.
- Hydrogen Blending Pilots:Gazprom testing methane-hydrogen mixtures for turbine combustion in pipeline compressor stations.
- Railborne Crude to Pacific:ESPO spur capacity growth enables tank car dispatch to Kozmino when pipeline nominations exceed capacity.
Industry Challenges
- Arctic Construction Labor Pool:Rotational worker shortages at Yamal LNG site camps delay module integration schedules.
- Legacy SCADA Migration:Siemens and ABB control system replacement with domestic alternatives requires field retesting at hundreds of upstream nodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russian Federation Oil and Gas Market |
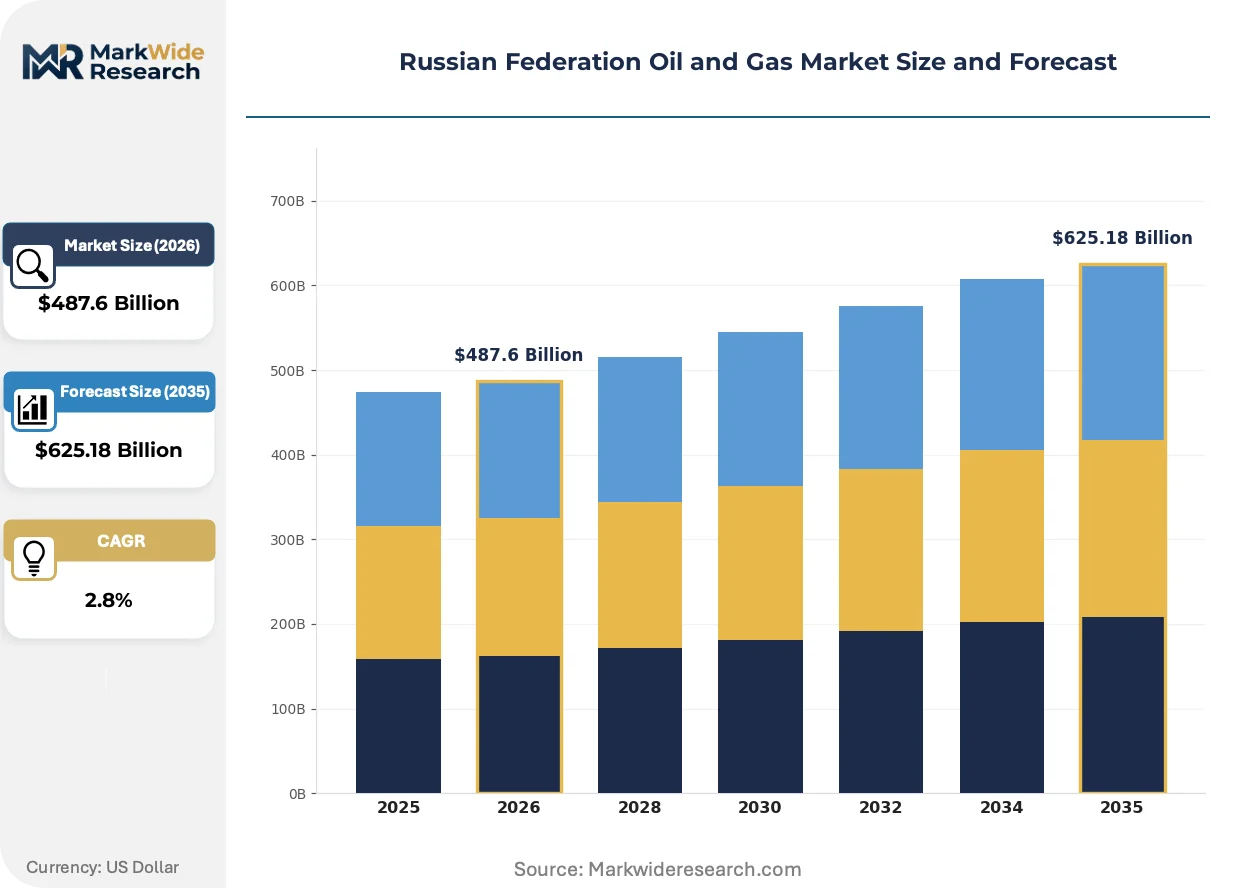
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $625.18 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, Liquefied Natural Gas, Refined Products Extraction Method: Conventional, Unconventional, Offshore, Onshore End User: Industrial, Power Generation, Transportation, Residential Distribution Channel: Pipelines, Tankers, Railways, Storage Facilities |
| Companies Covered | Novatek, Gazprom Neft, Rosneft Oil Company, Surgutneftegas, Tatneft, Gazprom, Transneft Group, Bashneft, Lukoil Oil Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russian Federation Oil and Gas Market Evolving Landscape
Digital field architecture and low-carbon process intensification are reconfiguring how Russian operators extract value from mature brownfields and frontier Arctic acreage.
Directional drilling automation paired with real-time geosteering is rewriting recovery economics in Western Siberian multilateral wells. Gazpromneft deploys these systems at Prirazlomnoye to reduce sidetrack frequency. The technology compresses well construction cycles and extends plateau production without new platform investments.
Rosprirodnadzor's methane intensity monitoring requirements now mandate quarterly optical gas imaging surveys at all licensed production sites. Operators must submit verified leak repair logs or face quota reductions. This enforcement is tightening most acutely at older Tyumen cluster fields with aging flange and valve populations.
Chinese offtakers now negotiate shorter-term LNG contracts with destination flexibility clauses, displacing the oil-indexed, take-or-pay structures that anchored Yamal Phase 1 financing. This contracting evolution concentrates in spot-indexed tenders from PetroChina and Sinopec procurement desks.
Russian Federation Oil and Gas Market Segmentation
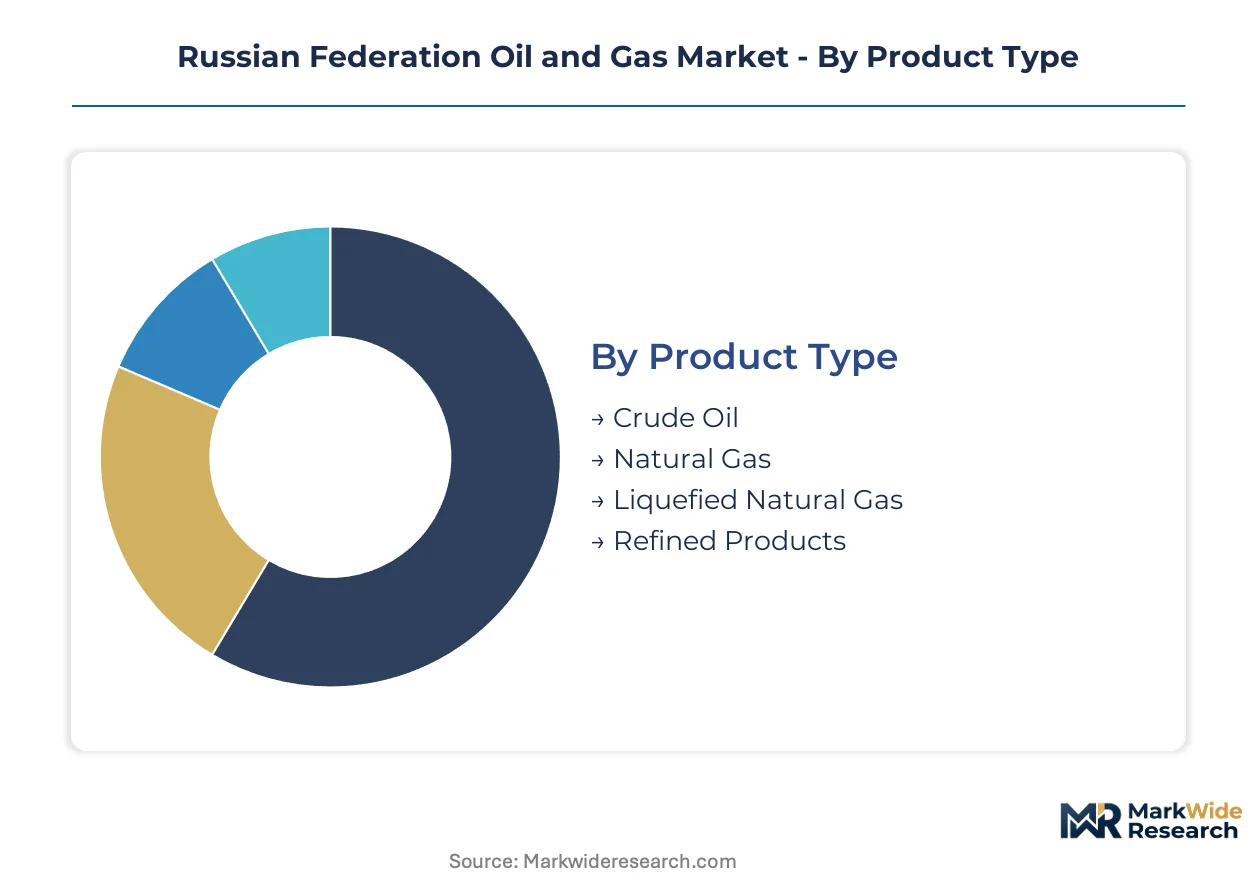
Segmentation reveals how capital allocation priorities differ across extraction modalities and customer types in Russia's hydrocarbon sector. Product mix and distribution channel choices directly shape tax exposure, infrastructure requirements, and offtake contract structures.
Product Type:
Upgrade cycles and refinery configuration decisions drive differential investment intensity across product categories, with downstream complexity requirements dictating capital deployment timelines.
- Crude Oil:Urals blend and ESPO grades dominate export nominations, with API gravities spanning 31-35 degrees. Western Siberian brownfields supply the bulk of volumes, though Arctic light sweet streams from Novy Port attract Asian premium pricing.
- Natural Gas:Methane-rich pipeline gas requires dehydration and treatment at compressor stations before injection into the Unified Gas Supply System. Gazprom's Power of Siberia corridors move volumes toward Chinese border metering stations.
- Liquefied Natural Gas:Yamal feedstock liquefaction targets ice-class tanker dispatch through Northern Sea Route windows.
- Refined Products:Diesel and fuel oil output from Angarsk and Omsk refineries supplies domestic agricultural and rail sectors.
Volume placements concentrate in Crude Oil; the faster expansion belongs to Liquefied Natural Gas.
Extraction Method:
Cost tier differentiation separates mature brownfield operations from frontier developments requiring specialized Arctic equipment and extended drilling seasons.
- Conventional:Vertical well completions in Western Siberia's Tyumen and Khanty-Mansiysk formations deliver lowest lifting costs per barrel. Rosneft operates thousands of these wells with artificial lift optimization.
- Unconventional:Bazhenov shale and Achimov tight sands demand hydraulic fracturing and horizontal laterals. Tax relief under MET reduction programs partially offsets higher completion costs.
- Offshore:Prirazlomnoye and Kirinskoye platforms in Pechora and Okhotsk Seas require ice-resistant structures.
- Onshore:Arctic onshore at Yamal and Gydan peninsula relies on modular construction and seasonal workforce rotations.
Volume placements concentrate in Conventional; the steepest expansion trajectory belongs to Offshore.
End User:
Application-specific purity and pressure requirements create divergent contract structures across customer categories, with industrial offtakers negotiating term flexibility distinct from residential distributors.
- Industrial:Petrochemical and fertilizer synthesis plants in Tatarstan and Samara Oblast consume methane feedstock for ammonia and methanol production. Ministry of Energy quotas prioritize these volumes.
- Power Generation:Combined-cycle gas turbine plants in Central Russia require consistent calorific value specifications. Gazprom Mezhregiongaz manages seasonal demand swings.
- Transportation:Compressed natural gas filling stations expand along federal highway corridors.
- Residential:District heating networks in Moscow and St. Petersburg depend on regulated tariff structures.
Volume placements concentrate in Industrial; the fastest share gain belongs to Transportation.
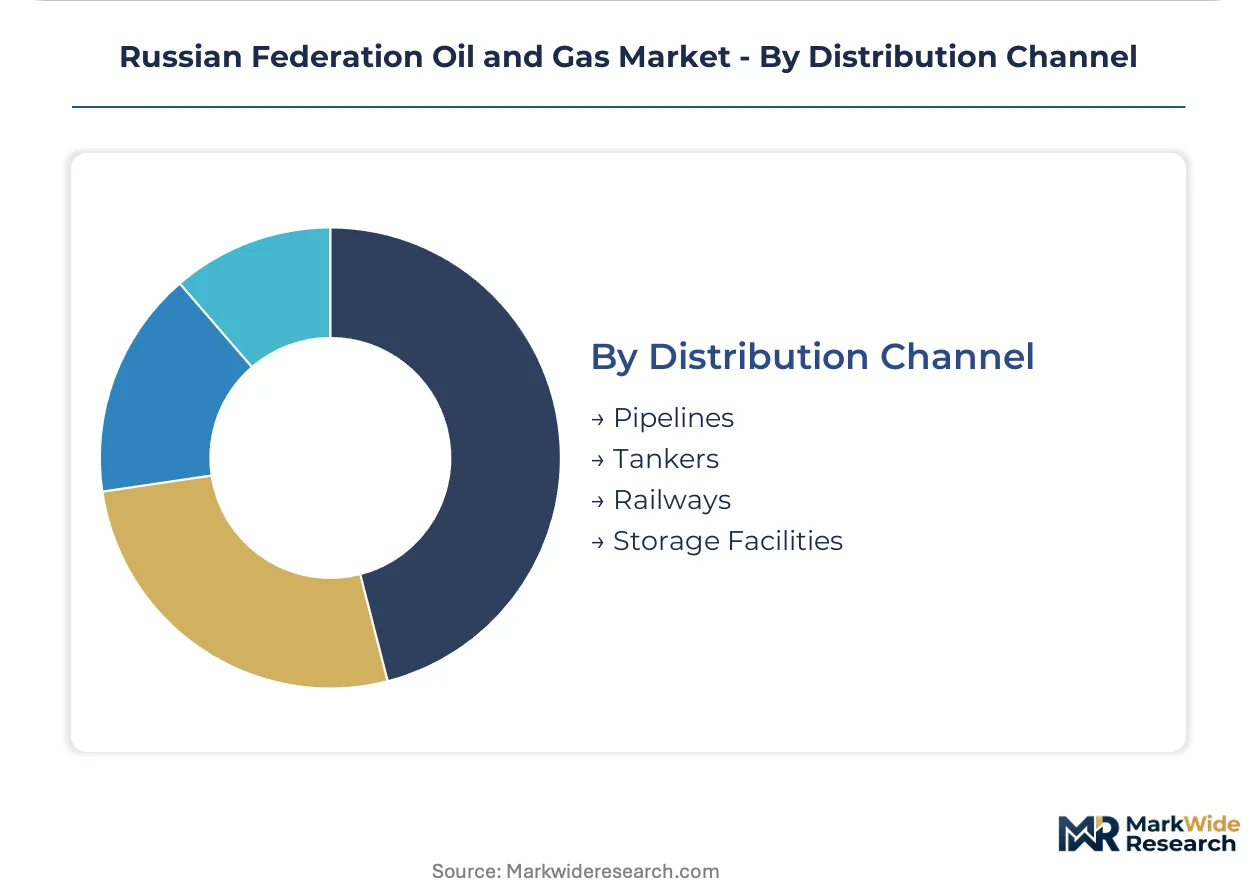
Distribution Channel:
Geographic concentration of infrastructure ownership determines margin capture, with pipeline control points offering tariff advantages over modal alternatives.
- Pipelines:The Unified Gas Supply System and Transneft oil trunk lines move the majority of hydrocarbons. Eastern Siberia-Pacific Ocean pipeline spurs enable Kozmino port exports.
- Tankers:Ice-class LNG carriers and Aframax crude vessels navigate Northern Sea Route seasonally. Atomflot icebreaker escorts extend navigation windows.
- Railways:Russian Railways tank car fleets serve destinations lacking pipeline connectivity.
- Storage Facilities:Underground gas storage at Kasimovskoye and Punginskoye fields balances seasonal demand.
Volume placements concentrate in Pipelines; the fastest infrastructure expansion belongs to Tankers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Novy Port on the Yamal Peninsula anchors Russia's Arctic crude export capacity, with ice-class terminal infrastructure enabling year-round tanker loading through the Northern Sea Route.
Yamal-Nenets Autonomous Okrug
Gazprom and Novatek operate liquefaction trains and condensate stabilization units serving Chinese and Indian term buyers. Russia's Ministry of Energy administers production quotas and export license terms through subsoil use agreements. The Gydan Peninsula hosts greenfield development camps where modular construction crews assemble drilling pads under polar night conditions.
Khanty-Mansiysk Autonomous Okrug
Rosneft and Surgutneftegas maintain thousands of brownfield wells across the Samotlor and Priobskoye supergiants with artificial lift optimization. Rosprirodnadzor enforces quarterly methane leak detection surveys using optical gas imaging protocols. Nizhnevartovsk serves as the logistics hub where drilling contractors stage workover rigs for multilateral well recompletions.
Tatarstan Republic
Tatneft operates enhanced oil recovery projects targeting carbonate reservoirs in the Romashkino field, Russia's largest by cumulative production. The republic's investment development agency coordinates special economic zone benefits for petrochemical downstream projects. Nizhnekamsk hosts ammonia and methanol synthesis plants consuming pipeline gas under Ministry of Energy feedstock allocation quotas.
Sakha Republic (Yakutia)
Chayanda and Kovykta gas condensate fields feed the Power of Siberia trunkline toward Chinese border metering stations. Permafrost foundation engineering constraints extend well pad construction seasons. The Lensk industrial corridor supplies rotational workforce housing and aviation logistics for remote Arctic drilling campaigns.
Leningrad Oblast
Gazprom's Portovaya compressor station processes Nord Stream corridor volumes, though throughput has shifted toward domestic grid injection and Baltic LNG project feedstock. The Ust-Luga oil terminal handles Urals blend loading for Aframax vessels. Russia's Federal Agency for Technical Regulation and Metrology certifies custody transfer metering systems at export custody points.
Russian Federation Oil and Gas Market Competitive Landscape
The competitive structure tilts toward state-controlled integrated majors with pipeline network ownership and Arctic license portfolios. Two tiers separate trunkline operators with unified gas supply system control from independent producers relying on railborne crude and spot LNG offtake. Strategic archetypes include vertically integrated upstream-midstream combines, independent gas specialists with liquefaction focus, and regional oil producers with mature brownfield expertise. Dominant competitive moves center on Arctic acreage consolidation through license auctions and eastern infrastructure corridor preemption.
Among the state-controlled tier, Gazprom anchors domestic pipeline gas distribution and cross-border export corridors, while Rosneft Oil Company exemplifies scale-driven upstream integration across Western Siberian and Arctic projects. Novatek occupies a distinct position as the independent liquefaction specialist leveraging Yamal feedstock for Asian-bound cargoes. These three represent the structural poles around which procurement relationships, tax relief negotiations, and infrastructure access terms are organized.
| Leading Market Players |
|---|
| Novatek |
| Gazprom Neft |
| Rosneft Oil Company |
| Surgutneftegas |
| Tatneft |
| Gazprom |
| Transneft Group |
| Bashneft |
| Lukoil Oil Company |
| Others |
Value Network & Pricing Analysis
Crude oil transportation tariffs from Western Siberian gathering systems through Transneft trunk lines to Kozmino or Primorsk terminals create cascading cost tiers that separate ESPO premium grades from discounted Urals blend nominations. These logistics differentials concentrate pricing power at pipeline custody transfer points where Gazprom and Rosneft negotiate term structures with Chinese and Indian offtakers.
Pricing Analysis
Throughput-linked pricing anchors term contracts for Power of Siberia volumes, where Chinese buyers pay tariffs indexed to delivery volumes at Manzhouli border stations rather than flat reservation fees. Price differentiation separates Yamal LNG cargoes bound for premium Asian markets from pipeline gas diverted to domestic industrial consumers under regulated tariffs. Cost compression in European-destined crude streams reflects EU Carbon Border Adjustment Mechanism compliance burdens and truncated contract tenors. Industrial petrochemical buyers in Tatarstan exhibit lowest price sensitivity due to Ministry of Energy feedstock allocation quotas, while spot LNG purchasers in India demonstrate highest sensitivity to destination flexibility clauses.
Supply Chain Analysis
Remanufacturing flows for subsea production hardware and gas turbine components create secondary supply channels as Western OEMs exit under sanctions architecture, with domestic fabricators at St. Petersburg and Chelyabinsk facilities refurbishing Siemens and ABB control systems. Geographic supply concentration centers on China for liquefaction heat exchangers and compressors, South Korea for ice-class tanker hull construction, and domestic Russian foundries for wellhead equipment. Raw material dependencies encompass specialized nickel alloys for Arctic structures, high-pressure pipeline steel from Magnitogorsk Metallurgical Combine, and electronic components for SCADA migration. Single-source vulnerability concentrates in icebreaker escort capacity through Atomflot's nuclear fleet. Distribution runs through the Unified Gas Supply System for domestic methane, Transneft oil trunk lines for crude, and Northern Sea Route tanker corridors for LNG.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arctic liquefaction train construction delays and ice-class vessel bottlenecks constrain supply expansion, propping term pricing for Yamal cargoes despite spot market softness. This capacity scarcity rewards operators with secured feedstock and shipping access.
For Market Incumbents: Anchor eastern infrastructure corridors through pre-emptive pipeline right-of-way acquisitions and Power of Siberia expansion tie-ins before greenfield licensing rounds conclude. Defend against independent LNG specialists by consolidating Arctic acreage through Rosgeologia seismic data partnerships and securing icebreaker priority scheduling with Atomflot. Prioritize backward integration into modular construction yards at Murmansk to control liquefaction train delivery timelines. For New Entrants and Emerging Players: EU Carbon Border Adjustment Mechanism in Europe opens a window for carbon-intensity certification services and embedded emissions auditing for residual Russian pipeline volumes still reaching European destinations. White-space targets include hydrogen blending pilot infrastructure for Gazprom compressor stations and methane leak detection technology deployment under Rosprirodnadzor mandates. The most penetrable segment is optical gas imaging survey services at aging Tyumen cluster fields. Go-to-market through joint ventures with regional service companies holding existing Rosneft and Gazprom maintenance contracts. For Investors and Strategic Acquirers: Novatek's final investment decision on Arctic LNG 2 Train 3 is the leading indicator that Yamal feedstock expansion remains financeable despite sanctions pressure. Long-term viability hinges on Asian buyer commitment to oil-indexed term structures versus spot-indexed displacement. Target acquisition archetypes include independent drilling contractors with Arctic modular construction expertise and domestic SCADA system vendors replacing Western automation. Monitor Chinese state bank credit facility renewals for Yamal project entities as early signal of sanctions circumvention capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Arctic LNG Capacity Buildout | Yamal and Gydan liquefaction trains anchor Asian-bound supply pivot through Novatek's operational platform. |
| Power of Siberia Expansion | Chayanda and Kovykta tie-ins secure Gazprom's eastern corridor dominance for Chinese border deliveries. |
| Domestic SCADA Migration | Replacement of Siemens and ABB control systems with Russian alternatives satisfies localization mandates under Federal Agency for Technical Regulation certification. |
| Ice-Class Tanker Fleet Expansion | Zvezda shipyard construction and Atomflot nuclear icebreaker additions extend Northern Sea Route navigation windows. |
| Carbon Intensity Certification Program | Rosprirodnadzor methane monitoring compliance creates service revenue streams for optical gas imaging providers at legacy fields. |
Research Methodology
Ministry of Energy production quota filings, Federal Agency for Mineral Resources licensing records, and Rosstat hydrocarbon export statistics formed the secondary backbone for volume and flow calibration. Primary interviews with upstream field development executives, pipeline operations planners at Transneft and Gazprom, Arctic construction contractors, and Chinese LNG procurement desks at PetroChina and Sinopec validated throughput assumptions and contract structure evolution. Bottom-up field-by-field production modeling combined with top-down export corridor capacity analysis enabled triangulation across data sources.
Bottom-up modeling aggregated individual field decline curves and greenfield ramp schedules across Western Siberian brownfields and Yamal Arctic developments, while top-down analysis constrained totals against Unified Gas Supply System injection capacity and Eastern Siberia-Pacific Ocean pipeline nominations. Segmentation dimensions encompassed product type, extraction method, end-user application, and distribution channel, with regional regulatory clusters differentiated by special economic zone tax relief eligibility. CAGRs derived from production quota trajectories and liquefaction train commissioning schedules, incorporating permafrost engineering constraints on construction timelines and ice window limitations on tanker dispatch.
The model assumes a particular technology adoption path for directional drilling automation and real-time geosteering deployment; alternative pathways for unmanned aerial methane monitoring or floating LNG liquefaction would alter the outlook for cost curves and emissions intensity. Forecasts reflect assumptions about sanctions architecture persistence, Asian buyer credit availability, and Arctic ice retreat trajectories. Practitioners should monitor Chinese term contract renewal negotiations, EU Carbon Border Adjustment Mechanism implementation scope, and Atomflot icebreaker commissioning schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
United States Oil and Gas Downstream Market
Oil & Gas
Containment and Handling Drilling Waste Management Market
Oil & Gas
North America Directional Drilling Services Market
Oil & Gas
North America Wireline Services Market
Oil & Gas
Indonesia Oilfield Equipment Rental Services Market
Oil & Gas
Japan LNG Bunkering Market
Oil & Gas
Southeast Asia LNG Market
Oil & Gas
Casing Centralizer Market
Oil & Gas
United States Liner Hanger System Market
Oil & Gas
Flow Computer Oil Gas Market
Oil & Gas
Digital Oil Field Technology Market
Oil & Gas
Clear Brine Fluids Market
Oil & Gas
Ecuador Wireline Logging Services Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
Cuttings Re-Injection Services Market
Oil & Gas
North America Shale Market