
 North America Wireline Services Market | 2026-2036
North America Wireline Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wireline Services Market Analytics
The EPA's methane emissions standards is rebalancing the cost-of-entry calculus for wireline contractors serving North American basins. Schlumberger Limited leverages its integrated logging and perforating portfolio to sustain premium positioning across the Permian and Bakken. Halliburton Company anchors its wireline division through proprietary electric line technologies that reduce rig downtime. Baker Hughes Company competes on intervention automation, differentiating its offerings against regional specialists with deeper digital tool strings.
Wireline services encompass the deployment of specialized cables and instruments into wellbores to perform logging, perforating, intervention, and testing operations, typically utilizing electric line, slickline, or coiled tubing conveyed tools rated for high-pressure, high-temperature environments exceeding 150°C and 10,000 psi. These services enable operators to evaluate formation properties, establish reservoir connectivity, and maintain well integrity throughout the full hydrocarbon extraction lifecycle. Logging services dominate value generation due to recurring demand for formation evaluation in deep horizontal wells, while intervention services represent the fastest-expanding segment as aging well stock across North America requires more frequent workovers and plug mill-outs. Completion services concentrate margin pools where perforating and fracturing diagnostics command technical premiums, and electric line technology leads technology adoption against slickline alternatives in complex multistage completions.
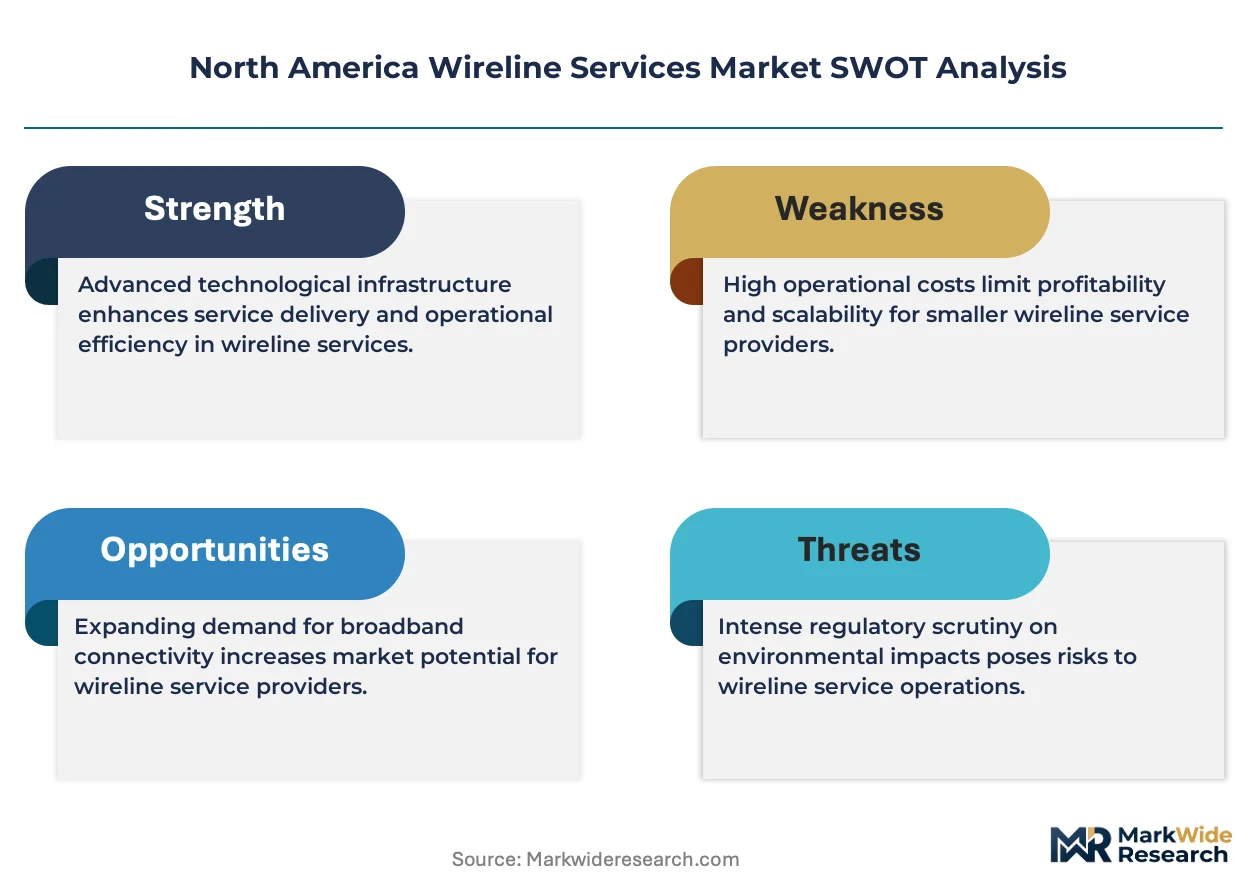
The EPA enforces methane capture mandates that directly shape wireline equipment specifications and operational protocols across US onshore fields. OSHA standards govern worker exposure limits during high-pressure wireline interventions, while BSEE regulations constrain offshore electric line deployments in the Gulf of Mexico through stringent well control requirements. Canada's provincial regulators, notably the AER in Alberta and the BC Oil and Gas Commission, impose parallel emissions and safety frameworks that equipment vendors must harmonize for cross-border service mobility. Stakeholders must monitor how evolving federal methane rules and state-level flaring restrictions in Texas and New Mexico reshape the economic viability of conventional versus automated wireline delivery models.
Market Dynamics
EPA methane capture mandates are forcing wireline contractors across US onshore fields to retrofit equipment specifications and operational protocols, compressing margins while elevating technical barriers for regional specialists.
Growth Catalysts
- Permian Basin horizontal complexity:Multistage completions in West Texas and New Mexico require sophisticated electric line interventions for perforating and plug mill-outs.
- EPA methane emissions rules:Tightening operational standards drive recurring demand for advanced logging services that verify well integrity and detect leaks.
- Aging well stock across the US:Mature producing assets in Oklahoma and Louisiana require frequent workovers, accelerating intervention service utilization.
Market Restraints
- Specialized steel alloy costs:High-grade materials for coiled tubing and wireline cables face price volatility tied to global metallurgical supply chains.
- Equipment vendor concentration:Digital tool string manufacturing concentrates among a limited supplier base in Houston, creating procurement bottlenecks.
- OSHA exposure limits:Worker safety regulations during high-pressure interventions extend operational timelines and elevate labor compliance costs.
Strategic Opportunities
- Alberta oil sands redevelopment:Canadian operators under AER oversight seek wireline solutions for mature SAGD well workovers and steam chamber monitoring.
- Real-time data integration:Convergence of downhole sensors with edge computing platforms enables predictive maintenance and reduces rig downtime.
- Texas flaring restrictions:State-level mandates in the Permian create demand for wireline-deployed diagnostics that optimize gas capture and reduce venting.
Industry Challenges
- High-pressure certification timelines:BSEE well control requirements for Gulf of Mexico electric line deployments extend equipment qualification periods.
- Digital tool string integration:Legacy wellhead configurations in older Texas and Oklahoma fields require costly retrofitting to accommodate automated intervention systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wireline Services Market |
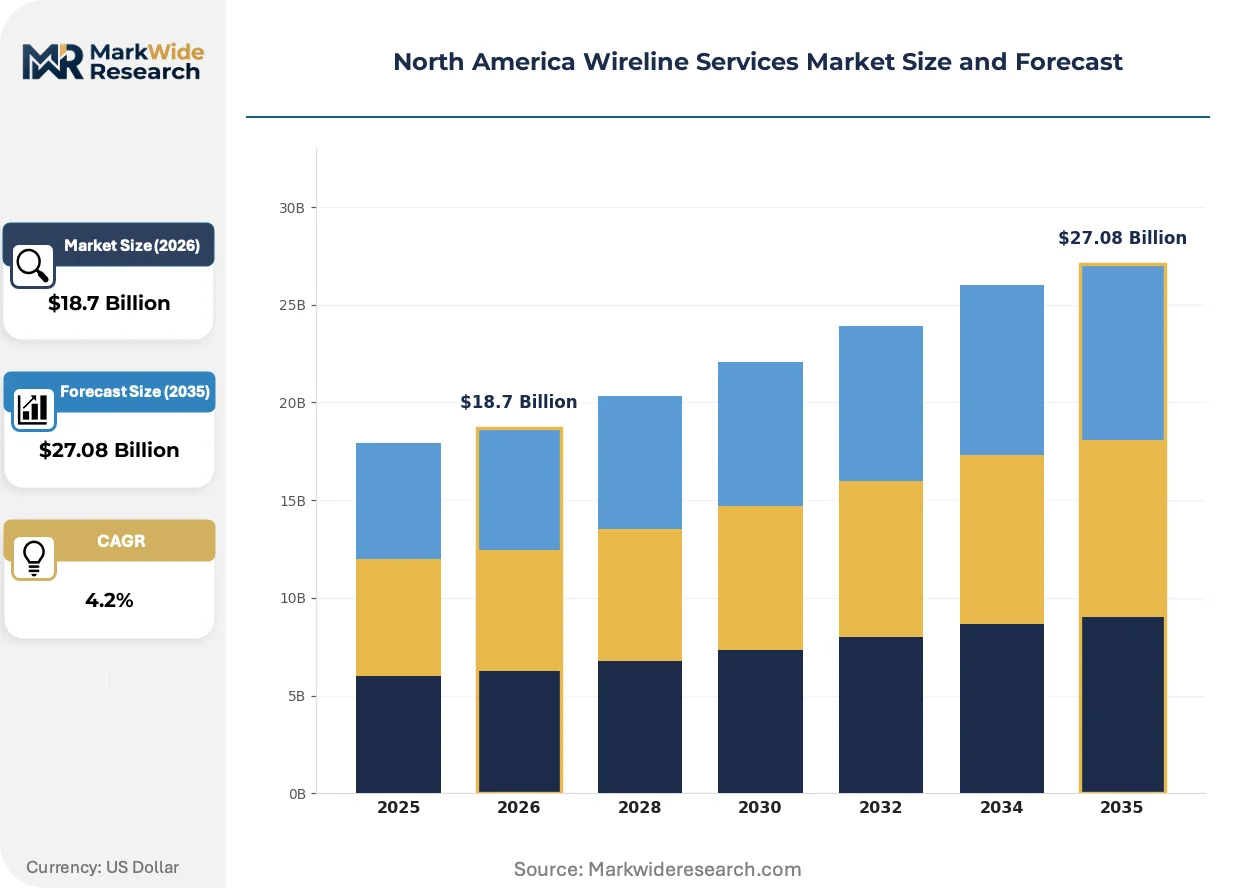
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Logging Services, Completion Services, Intervention Services, Testing Services End User: Oil & Gas Companies, Offshore Operators, Onshore Operators, Service Providers Technology: Electric Line, Coil Tubing, Slickline, Production Logging Application: Exploration, Development, Production, Decommissioning |
| Companies Covered | Weatherford International, Superior Energy Services Inc, Schlumberger Limited, National Oilwell Varco, Pioneer Energy Services Corp, Halliburton Company, Expro Group, Archer Limited, Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wireline Services Market Evolving Landscape
Wireline service delivery is compressing around three vectors: autonomous downhole intervention, emissions-driven equipment specification, and buyer consolidation around integrated service providers.
Intelligent electric line systems with automated depth correlation and real-time tension monitoring are automating perforating operations in Permian Basin multistage completions. Unconventional shale operators in Texas and New Mexico are deploying these systems at accelerating rates to reduce rig time per stage. The technology is automating intervention workflows that previously required manual wireline crew coordination, compressing service delivery windows and elevating technical barriers for non-automated competitors.
EPA methane capture mandates under the Clean Air Act are compelling wireline contractors to deploy zero-venting lubricator systems and closed-loop pressure control equipment across US onshore basins. The regulations are reshaping capital allocation toward emissions-compliant tool strings and surface equipment. Completion services in the Permian and Bakken are responding fastest, with operators tying contractor selection to verified methane reduction protocols.
Integrated service contracts bundling logging, perforating, and intervention under single-provider arrangements are displacing fragmented multi-vendor procurement in North American shale plays. Exploration and production companies in the Permian and Eagle Ford are consolidating spend around full-lifecycle wireline partners to reduce administrative overhead and improve operational coordination. The shift is most pronounced among large independents and majors operating horizontal programs across Texas and New Mexico.
North America Wireline Services Market Segmentation
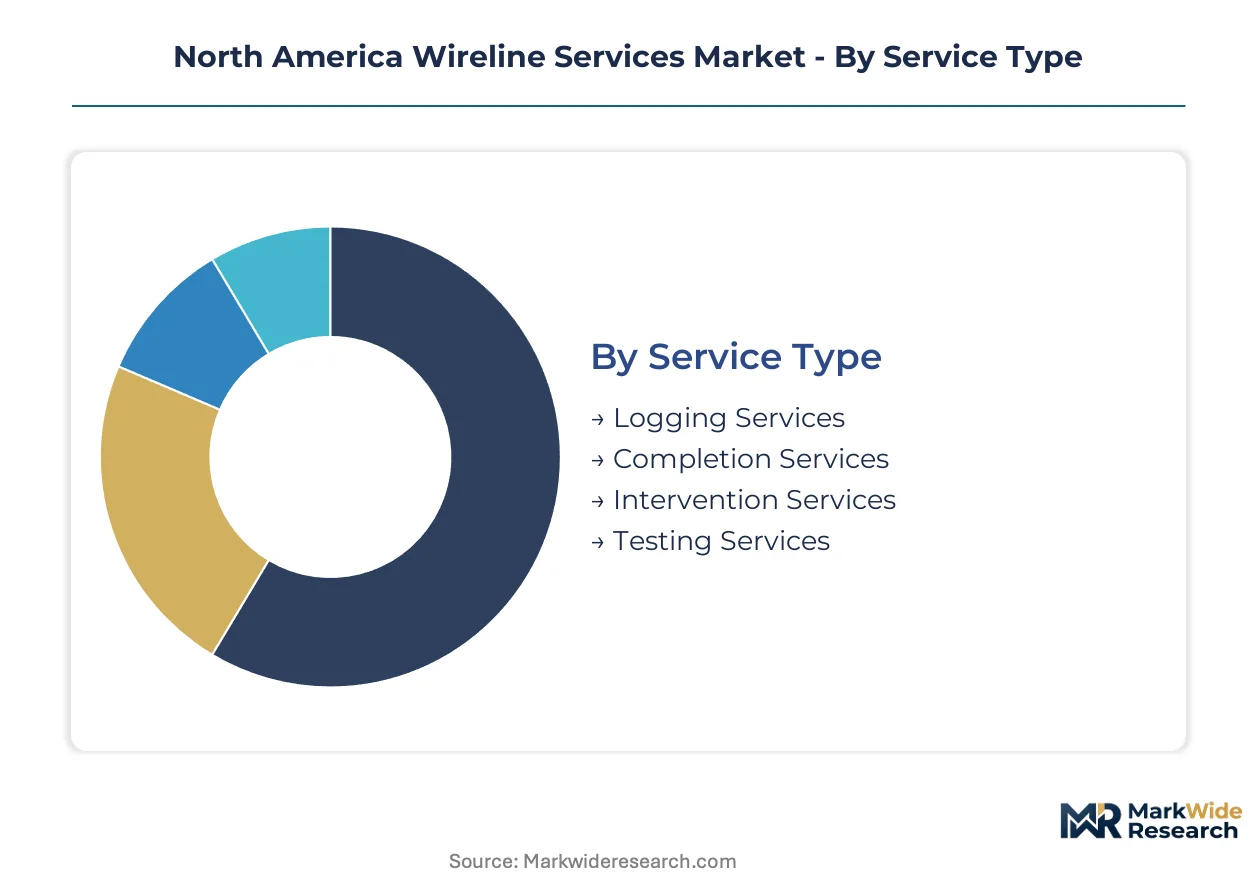
Wireline service segmentation reveals how technical specialization and regulatory pressure fragment procurement decisions across North American basins. Service providers must align capabilities with distinct operational phases and wellbore environments to capture contract value.
Service Type:
Supply concentration among integrated oilfield service providers shapes competitive dynamics across service categories, with technology-intensive segments commanding premium positioning.
- Logging Services:Formation evaluation through gamma ray, resistivity, and sonic tools dominates recurring revenue in deep horizontal wells. Permian Basin operators require continuous logging runs to optimize multistage completion designs, with EPA methane verification protocols adding service frequency.
- Completion Services:Perforating and fracturing diagnostics command technical premiums where electric line-conveyed guns execute precise zone isolation. West Texas horizontal complexity drives demand for real-time depth correlation systems that reduce stage-to-stage rig time.
- Intervention Services:Workovers and plug mill-outs expand most quickly as aging well stock across Oklahoma and Louisiana requires frequent remediation.
- Testing Services:Pressure transient and production validation supports reservoir characterization in Bakken tight oil developments.
Today's leader: Logging Services. Tomorrow's challenger: Intervention Services.
End User:
Customer scale and operational integration determine procurement patterns, with large independents consolidating spend around full-lifecycle partners.
- Oil & Gas Companies:Majors and large independents bundle logging, perforating, and intervention under integrated contracts to reduce administrative overhead and improve operational coordination across Permian and Eagle Ford programs.
- Onshore Operators:Unconventional shale producers in Texas and New Mexico concentrate demand for electric line interventions in multistage completions, with state-level flaring restrictions elevating diagnostic service requirements.
- Offshore Operators:Gulf of Mexico producers face BSEE well control requirements that extend equipment qualification timelines for electric line deployments.
- Service Providers:Regional specialists and equipment rental firms procure wireline technologies to serve fragmented operator bases in mature basins.
Integrated buyers anchor contract value. Fragmented operators create entry points for automated service differentiation.
Technology:
Capital intensity and digital integration separate technology tiers, with automated systems displacing manual alternatives in high-volume basins.
- Electric Line:Steel-cabled conveyance rated for high-pressure, high-temperature environments enables real-time data transmission and powered tool operation. Permian Basin horizontal complexity requires electric line for perforating and plug mill-outs, with intelligent systems automating depth correlation to compress stage delivery windows.
- Coil Tubing:Continuous steel pipe deployment supports milling, cleanout, and stimulation operations where rigidity and flow capacity matter.
- Slickline:Mechanical wireline for gauge runs and basic interventions retains cost advantage in mature Oklahoma and Louisiana fields with simpler wellbore geometries.
- Production Logging:Specialized sensors track fluid entry profiles and steam chamber development in Canadian SAGD operations under AER oversight.
Electric Line dominates capital allocation. Production Logging gains share in thermal recovery monitoring.
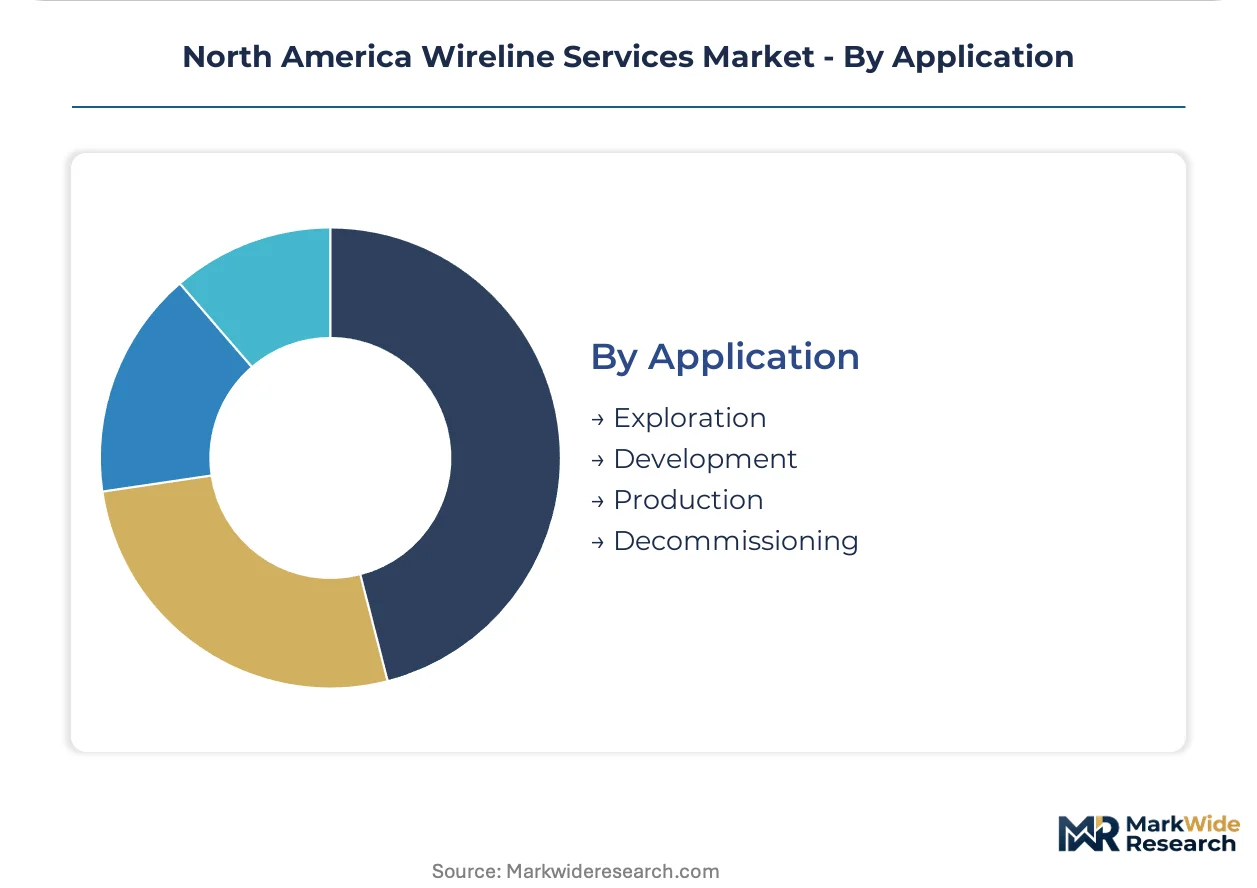
Application:
Lifecycle stage determines service intensity and margin structure, with development-phase completions generating concentrated value pools.
- Development:Multistage completion execution in unconventional shale concentrates wireline utilization, with perforating and fracturing diagnostics commanding premium pricing in Permian and Bakken drilling programs.
- Production:Ongoing intervention and maintenance sustain recurring revenue as aging well stock across North America requires workovers, plug mill-outs, and integrity verification.
- Exploration:Formation evaluation in frontier basins generates episodic demand for comprehensive logging suites.
- Decommissioning:Plug and abandonment operations in mature Gulf of Mexico assets and onshore fields require pressure testing and barrier verification.
Development commands margin concentration. Production sustains volume stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wireline services first achieved industrial scale in the United States during the 1920s logging boom in California's San Joaquin Valley. The technology migrated to Texas and Louisiana by mid-century, establishing the Gulf Coast as the foundational cluster for electric line and perforating expertise.
United States
Permian Basin operators in West Texas and Southeast New Mexico deploy electric line systems for multistage completion perforating and plug mill-outs. EPA methane capture mandates under the Clean Air Act compel zero-venting lubricator adoption across US onshore fields. Houston anchors equipment manufacturing and digital tool string development, with service headquarters clustering along the Energy Corridor.
Canada
Alberta's oil sands operators under AER oversight require wireline solutions for SAGD well workovers and steam chamber monitoring in the Athabasca region. Provincial emissions frameworks parallel US EPA standards, driving demand for closed-loop pressure control systems. Calgary serves as the operational hub for Canadian wireline contracting, with field activity concentrated around Fort McMurray thermal recovery sites.
Mexico
Onshore operators in the Burgos Basin and emerging unconventional blocks seek electric line interventions for tight gas completion execution. Mexico's national hydrocarbon regulator CNH imposes well integrity verification requirements that elevate logging service frequency. Ciudad del Carmen in Campeche supports offshore wireline logistics for shallow-water platforms in the southern Gulf.
North America Wireline Services Market Competitive Landscape
The competitive structure tilts toward integrated oilfield service conglomerates with full-lifecycle wireline portfolios. Three tiers populate the vendor map: global integrated providers commanding premium positioning, regional specialists competing on basin-specific responsiveness, and equipment-focused technology licensors. Consolidation pressure intensifies as operators bundle logging, perforating, and intervention under single-provider contracts. Capacity expansion in automated electric line systems and strategic partnerships for emissions-compliant tool strings represent the dominant competitive vectors.
Among US-based integrated service conglomerates, Schlumberger Limited and Halliburton Company occupy positions exemplifying the premium-tier archetype through comprehensive logging and intervention portfolios. Baker Hughes Company anchors the technology-automation vector with digital tool string capabilities. Weatherford International represents the diversified industrial conglomerate model spanning multiple oilfield service categories.
| Leading Market Players |
|---|
| Weatherford International |
| Superior Energy Services Inc |
| Schlumberger Limited |
| National Oilwell Varco |
| Pioneer Energy Services Corp |
| Halliburton Company |
| Expro Group |
| Archer Limited |
| Baker Hughes Company |
| Others |
Value Network & Pricing Analysis
Permian Basin majors and large independents concentrate procurement spend around integrated service contracts, anchoring a contract-based long-term offtake pricing model where volume commitments command preferential rates and bundled service tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates automated electric line systems with real-time diagnostics from conventional perforating packages and basic slickline interventions. Price differentiation rests on certification grade for EPA methane compliance and geographic delivery cost to remote West Texas pads. Cost compression in standard-tier electric line services is intensifying because equipment vendor concentration in Houston creates procurement bottlenecks. Fragmented onshore operators in Oklahoma and Louisiana exhibit highest price sensitivity, while Gulf of Mexico offshore operators under BSEE oversight show lowest sensitivity due to well control requirements.
Supply Chain Analysis
Refurbishment flows for coiled tubing units and digital tool strings cycle through Houston service centers before redeployment to Permian and Bakken fields, compressing capital intensity for regional specialists. Manufacturing concentrates in the United States, with specialized steel alloy sourcing from Japan and Germany for high-pressure cable ratings. Raw material dependencies include nickel-based superalloys, polymer cable sheathing, and precision-machined downhole sensors. Single-source vulnerability around Houston-based digital tool string vendors elevates supply risk. Distribution runs through basin-specific service yards in Midland, Odessa, and Calgary.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America wireline services constitute a late-cycle quality story as EPA methane capture mandates shift operator procurement toward premium-tier automated systems with verified emissions protocols.
For Market Incumbents: Lock in integrated contract renewals with Permian majors before competitive automation investments by regional specialists mature. Defensive consolidation of electric line fleet capacity in West Texas offsets margin pressure from equipment vendor concentration. Backward integration into proprietary sensor manufacturing reduces exposure to Houston procurement bottlenecks. For New Entrants and Emerging Players: EPA methane emissions rules in the United States open a window for zero-venting lubricator specialists to capture share from legacy contractors with non-compliant surface equipment. White-space targets include automated plug mill-out services in aging Oklahoma wells and SAGD thermal monitoring in Alberta under AER oversight. Go-to-market positioning as emissions-verification partners rather than commodity service vendors accelerates operator acceptance. For Investors and Strategic Acquirers: Integrated oilfield service conglomerates are the most active acquirer in this space, seeking electric line automation capabilities to complete full-lifecycle portfolios. Long-term viability hinges on differentiation through predictive maintenance platforms rather than equipment scale alone. Acquisition target archetype: regional specialists with EPA-certified tool strings and established Permian operator relationships. Monitor Texas Railroad Commission flaring restriction enforcement as inflection indicator for diagnostic service demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Line Fleet Automation | Schlumberger and Halliburton deployments in Permian Basin multistage completions compress rig time per stage. |
| Zero-Venting Lubricator Certification | EPA Clean Air Act compliance creates technical barrier elevating capital requirements for wireline contractors. |
| Integrated Service Contract Bundling | Permian operators consolidate logging, perforating, and intervention spend to reduce administrative overhead. |
| Backward Integration into Sensor Manufacturing | In-house production of downhole digital tool strings reduces Houston vendor concentration risk. |
| Alberta SAGD Thermal Monitoring Expansion | AER oversight of oil sands redevelopment creates demand for production logging in steam chamber applications. |
Research Methodology
Direct dialogue with wireline operations managers, E&P procurement directors, EPA compliance officers, and digital tool string engineers combined with secondary validation through BSEE incident reports, EIA drilling statistics, and SEC 10-K filings from integrated service providers. Bottom-up rig activity counts across Permian, Bakken, and Eagle Ford basins triangulate against top-down market sizing from equipment fleet capacity estimates.
Segmentation outputs across service type, technology tier, and application phase model revenue distribution across the projection horizon. CAGRs derive from basin-level drilling program forecasts and service intensity assumptions per well. Industry-specific inputs include EPA methane rule implementation timelines and electric line automation adoption curves in West Texas horizontal completions.
Revisions become necessary when EPA regulatory enforcement intensity shifts, steel alloy price volatility disrupts equipment manufacturing economics, or autonomous intervention technology achieves cost parity with crewed operations. Practitioners should monitor BSEE well control requirement changes and Texas flaring restriction amendments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Asia-Pacific Liner Hanger System Market
Oil & Gas
Oil and Gas Corrosion Protection Market
Oil & Gas
Well Abandonment Services Market
Oil & Gas
Europe Hydraulic Fracturing Fluids Market
Oil & Gas
Vietnam Oil and Gas Market
Oil & Gas
Netherlands LNG Bunkering Market
Oil & Gas
Modular Refinery Market
Oil & Gas
Coal Mining Market
Oil & Gas
Asia-Pacific Oilfield Services Market
Oil & Gas
Mud Logging Unit Market
Oil & Gas
Natural Gas Market
Oil & Gas
Iron Ore Mining Market
Oil & Gas
Global LNG Liquefaction Terminals Market
Oil & Gas
United States Oil and Gas Downstream Market
Oil & Gas
GCC and North Africa Coiled Tubing Market
Oil & Gas
Whipstocks Market