
 Offshore Drilling Fluid Market | 2026-2036
Offshore Drilling Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
Offshore Drilling Fluid Market Analysis
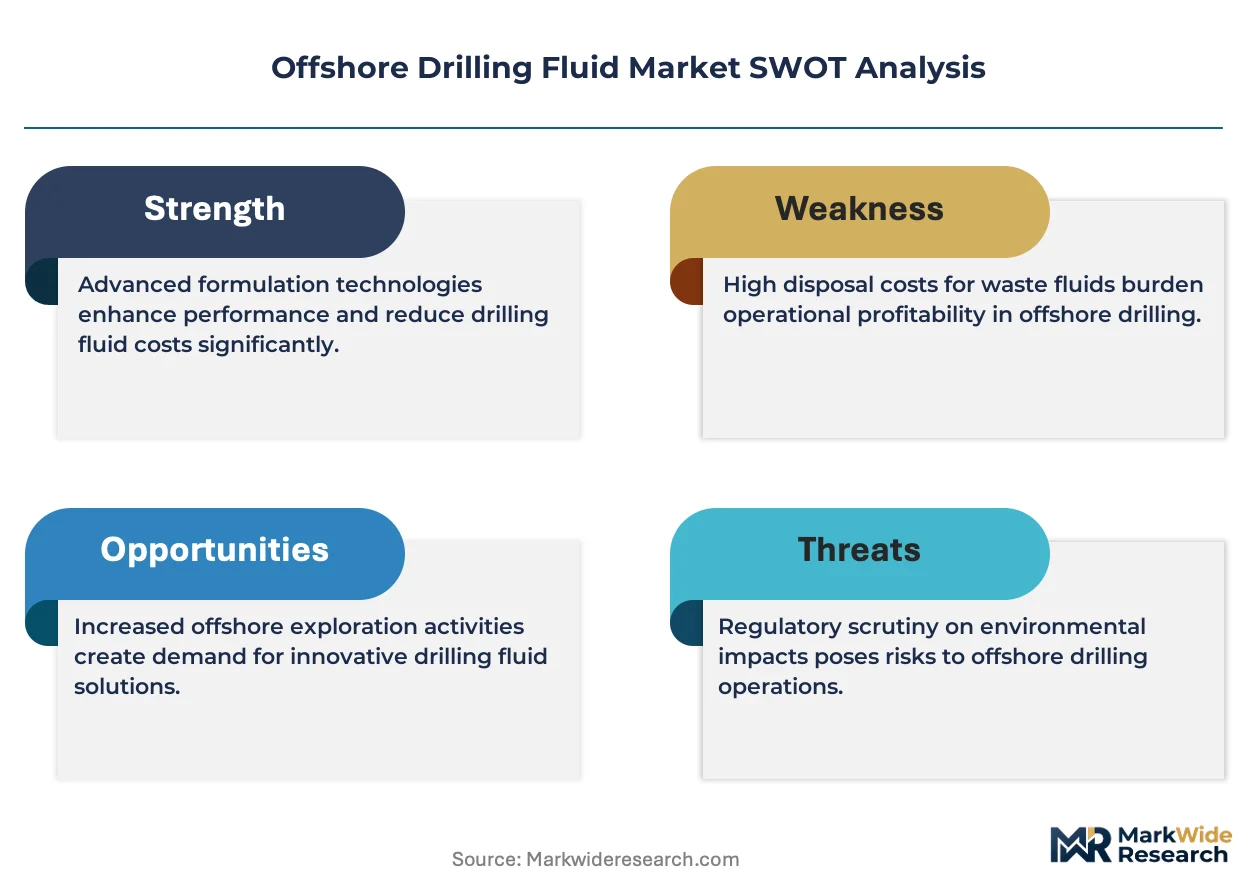
High-performance synthetic formulations is bifurcating the competitive landscape between premium specialty suppliers and commodity fluid blenders. SLB leverages its integrated drilling services platform to bundle fluid systems with downhole telemetry. Halliburton anchors its position through deepwater-specific additive packages engineered for high-pressure, high-temperature reservoirs. Baker Hughes differentiates via bio-based surfactant technologies that reduce environmental compliance costs in sensitive marine zones.
Offshore drilling fluids are engineered liquid and gas systems circulated through wellbores to control formation pressure, transport cuttings, and lubricate drill strings, with synthetic-based variants typically formulated from internal olefins or linear alpha olefins achieving density ranges of 0.8 to 2.4 specific gravity for ultra-deepwater deployment. Their primary purpose centers on maintaining wellbore stability across salt formations and depleted zones where conventional water-based systems fail. Oil-based fluids retain the largest revenue share among product types due to superior inhibition in reactive shales, though synthetic-based formulations are capturing fastest growth as operators retrofit fleets for stricter discharge protocols. Deepwater deployment commands the highest fluid consumption per well, while shallow water operations represent a mature, price-sensitive segment where local blending dominates procurement.
The US EPA enforces effluent limitation guidelines under the Clean Water Act that govern synthetic-based fluid discharge concentrations, while BSEE mandates real-time monitoring of fluid returns during subsea operations to prevent uncontrolled releases. Norway's Petroleum Safety Authority imposes chemical hazard assessments through its REACH-aligned offshore regulations, compelling operators to submit environmental risk profiles for each synthetic component before North Sea deployment. Stakeholders must track evolving marine toxicity testing protocols across multiple coastal jurisdictions, as regulatory divergence between the Gulf of Mexico and the North Sea is fragmenting formulation standardization and reshaping supplier certification requirements.
Market Dynamics
Deepwater exploration economics are reshaping fluid procurement as operators demand higher-performance systems for ultra-high-pressure reservoirs while simultaneously facing discharge compliance costs that now represent a material share of total drilling expenditure.
Growth Catalysts
- Brazil Pre-Salt Expansion:Petrobras and international joint ventures are deploying synthetic-based fluids in water depths exceeding 2,000 meters, creating sustained demand for high-density formulations.
- REACH-Aligned Chemical Hazard Assessments:Norway's Petroleum Safety Authority mandates pre-deployment environmental risk profiles, accelerating substitution of legacy oil-based systems with lower-toxicity alternatives.
- Internal Olefin Density Engineering:Advances in linear alpha olefin blending achieve 2.4 specific gravity without barite sag, enabling single-fluid solutions for extended-reach laterals.
Market Restraints
- Base Fluid Cost Volatility:Internal olefin and ester feedstock prices track palm oil and natural gas derivatives, compressing blender margins during upstream commodity spikes.
- Gulf of Mexico Supply Concentration:Port Fourchanch and Houston blending infrastructure dominates Western Hemisphere deepwater logistics, creating hurricane-related supply vulnerability.
- Shale Inhibition Trade-Offs:Water-based alternatives fail in reactive gumbo shale formations, locking operators into higher-cost synthetic systems despite discharge penalties.
Strategic Opportunities
- West Africa Ultra-Deepwater:Mauritania and Senegal offshore blocks lack established fluid supply chains, creating first-mover positioning for integrated service providers with floating storage.
- Real-Time Return Monitoring Integration:BSEE-mandated subsea monitoring systems are converging with automated mud weight adjustment, enabling predictive fluid management contracts.
- Bio-Based Surfactant Certification:EU Green Deal procurement preferences for marine-biodegradable additives create premium positioning for suppliers with OECD 306 test documentation.
Industry Challenges
- HPHT Reservoir Fluid Stability:Formulation chemists with experience above 200°C and 20,000 psi are scarce, extending R&D timelines for next-generation systems.
- Multi-Jurisdiction Certification Lag:Divergent toxicity protocols between EPA 1650 SBF guidelines and North Sea PARCOM standards force parallel testing regimens.
- Legacy Fleet Retrofit Complexity:Converting older platform supply vessels for synthetic-based fluid handling requires separator system upgrades and crew retraining.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offshore Drilling Fluid Market |
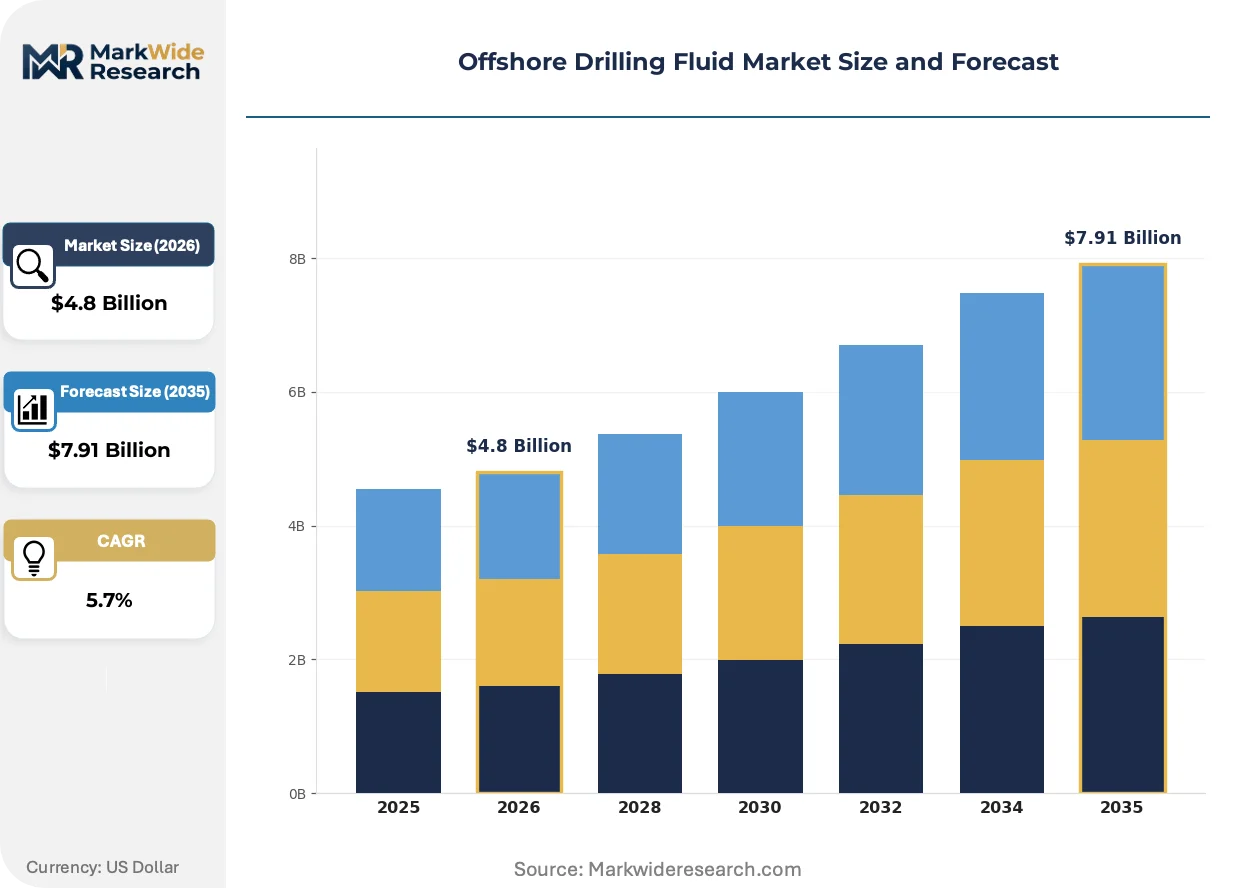
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Oil-Based, Synthetic-Based, Foam-Based Deployment: Deepwater, Shallow Water, Ultra-Deepwater, Coastal Technology: Rheology Modifiers, Weighting Agents, Additives, Surfactants End User: Petroleum Companies, Drilling Contractors, Service Providers, Others |
| Companies Covered | Weatherford International, SLB, Schlumberger, Chevron Phillips Chemical, Clariant, Halliburton, National Oilwell Varco, Lucite International, Baker Hughes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offshore Drilling Fluid Market Emerging Trajectories
Formulation chemistry and digital monitoring systems are converging to redefine fluid performance metrics, shifting competitive advantage from bulk supply scale to precision-engineered systems with embedded compliance documentation.
High-performance internal olefin blends with nano-particle weighting agents are supplanting conventional barite-loaded systems in Gulf of Mexico ultra-deepwater deployments. Operators targeting Lower Tertiary formations adopt these fluids for sag resistance during 10,000-foot laterals. The technology is compressing the addressable market for commodity blenders lacking polymer engineering capabilities.
EPA effluent limitation guidelines under the Clean Water Act now require discharge concentration reporting at the point of release rather than platform perimeter. This regulatory tightening forces real-time fluid return analysis aboard drilling units. Deepwater operators in the Gulf of Mexico are responding by specifying closed-loop systems with integrated solids control, eliminating surface discharge entirely.
Integrated drilling service contracts are unbundling fluid procurement from directional drilling packages, reversing a decade of bundled sourcing. National oil companies in Brazil and Norway now separate fluid system selection from rig contracting, enabling direct supplier relationships. This pattern is most pronounced in pre-salt blocks where Petrobras exercises procurement autonomy for high-specification formulations.
Offshore Drilling Fluid Market Segmentation
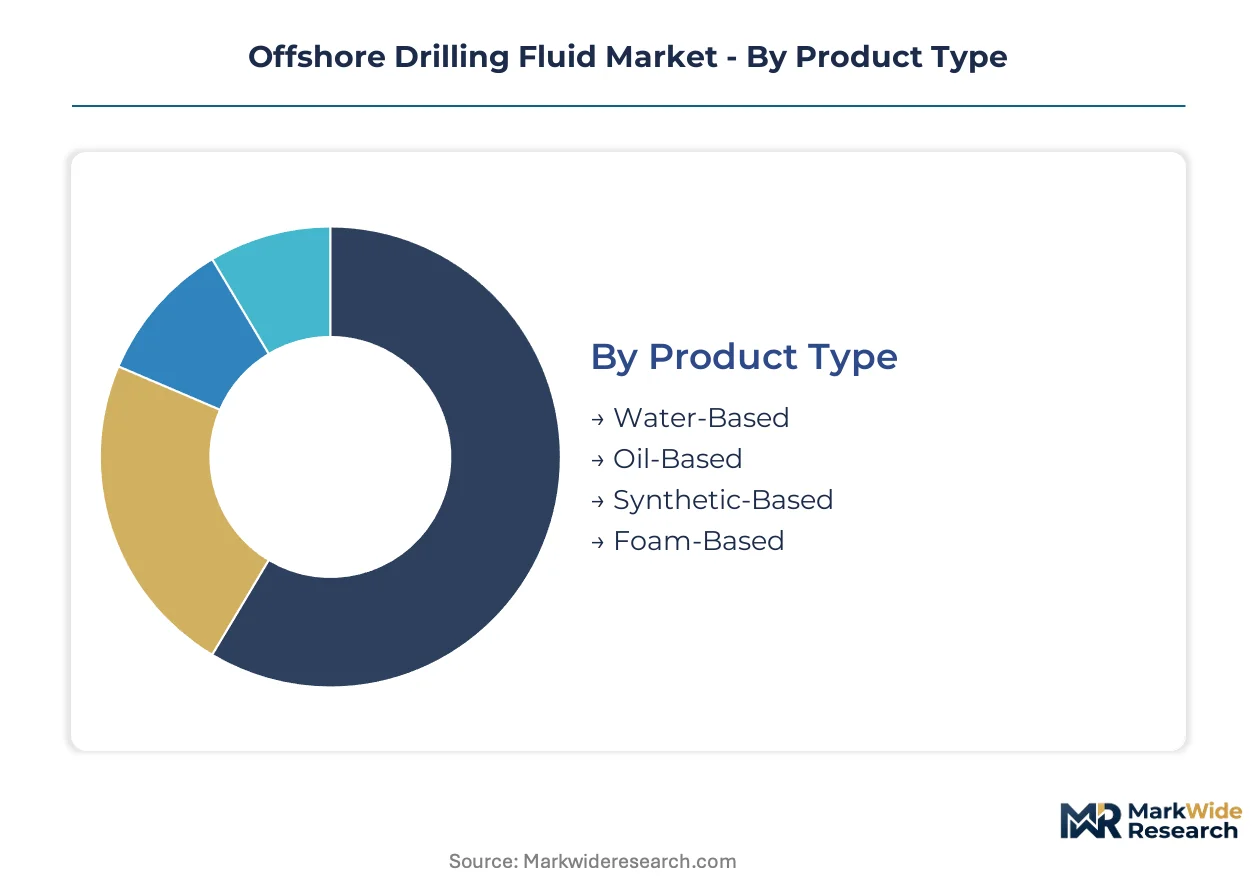
Offshore drilling fluid procurement patterns diverge sharply across product chemistry, water depth, and operator type, with regulatory stringency and reservoir complexity driving category-specific specification requirements. Understanding these segment boundaries reveals where formulation premiums concentrate versus where commodity blending suffices.
Product Type:
US EPA effluent limitation guidelines and Norway's REACH-aligned chemical hazard assessments create divergent compliance burdens across fluid chemistries, reshaping regional adoption patterns and supplier certification priorities.
- Synthetic-Based:Formulated from internal olefins or linear alpha olefins, these systems achieve 0.8 to 2.4 specific gravity for ultra-deepwater deployment. Demand concentrates in Brazil's pre-salt blocks and West Africa ultra-deepwater where Petrobras and international joint ventures require high-density formulations for water depths exceeding 2,000 meters. EPA and BSEE discharge standards are accelerating substitution of legacy oil-based systems in the Gulf of Mexico.
- Oil-Based:Conventional diesel or mineral oil formulations retain superior inhibition characteristics in reactive gumbo shale formations. Established volume favors this segment across mature Gulf of Mexico and North Sea infrastructure where operators accept discharge penalties to maintain wellbore stability in salt formations and depleted zones.
- Water-Based:Lower-cost formulations dominate shallow water and coastal deployment where formation reactivity permits. Nigerian and Angolan near-shore operations specify these fluids for routine development drilling with minimal environmental compliance overhead.
- Foam-Based:Compressed nitrogen or air systems address underbalanced drilling scenarios in depleted reservoirs. Norwegian North Sea operators deploy these for managed pressure drilling in formations with narrow pressure windows.
Established volume favors Oil-Based; emerging adoption favors Synthetic-Based.
Deployment:
Water depth directly determines fluid consumption intensity per well, with logistics complexity and specification requirements escalating discontinuously beyond continental shelf boundaries.
- Deepwater:Operations at 400-1,500 meters command the highest fluid volumes per well due to extended-reach laterals and complex wellbore geometries. Gulf of Mexico Lower Tertiary targeting drives nano-particle weighting agent adoption for sag resistance during 10,000-foot laterals.
- Ultra-Deepwater:Beyond 1,500 meters, single-fluid solutions with 2.4 specific gravity become essential. Mauritania and Senegal offshore blocks lack established supply chains, creating first-mover positioning for integrated service providers with floating storage.
- Shallow Water:Mature, price-sensitive segment where local blending dominates procurement. Port Fourchon and Houston infrastructure supports high-volume, low-specification deliveries for routine shelf development.
- Coastal:Proximity to shore enables rapid fluid turnover and simplified logistics. Southeast Asian near-shore gas development relies on these deployments with minimal synthetic content.
Deepwater generates the highest revenue per well; Ultra-Deepwater is climbing the fastest as frontier basins mature.
Technology:
Functional additive categories determine formulation performance ceilings and differentiate premium specialty suppliers from commodity blenders.
- Rheology Modifiers:Polymer and clay suspensions control viscosity across temperature and pressure gradients. High-pressure, high-temperature reservoirs above 200°C and 20,000 psi demand advanced polymer engineering capabilities concentrated among integrated service providers.
- Weighting Agents:Conventional barite systems face displacement by nano-particle alternatives in Gulf of Mexico ultra-deepwater. Sag resistance during extended-reach laterals commands formulation premiums.
- Additives:Emulsifiers, fluid loss control agents, and corrosion inhibitors customize base fluid performance. Brazil pre-salt procurement autonomy enables direct supplier relationships for high-specification additive packages.
- Surfactants:Bio-based variants reduce environmental compliance costs in sensitive marine zones. EU Green Deal procurement preferences for marine-biodegradable additives create premium positioning for suppliers with OECD 306 test documentation.
Weighting Agents anchor commodity volume; Surfactants are gaining share fastest on regulatory tailwinds.
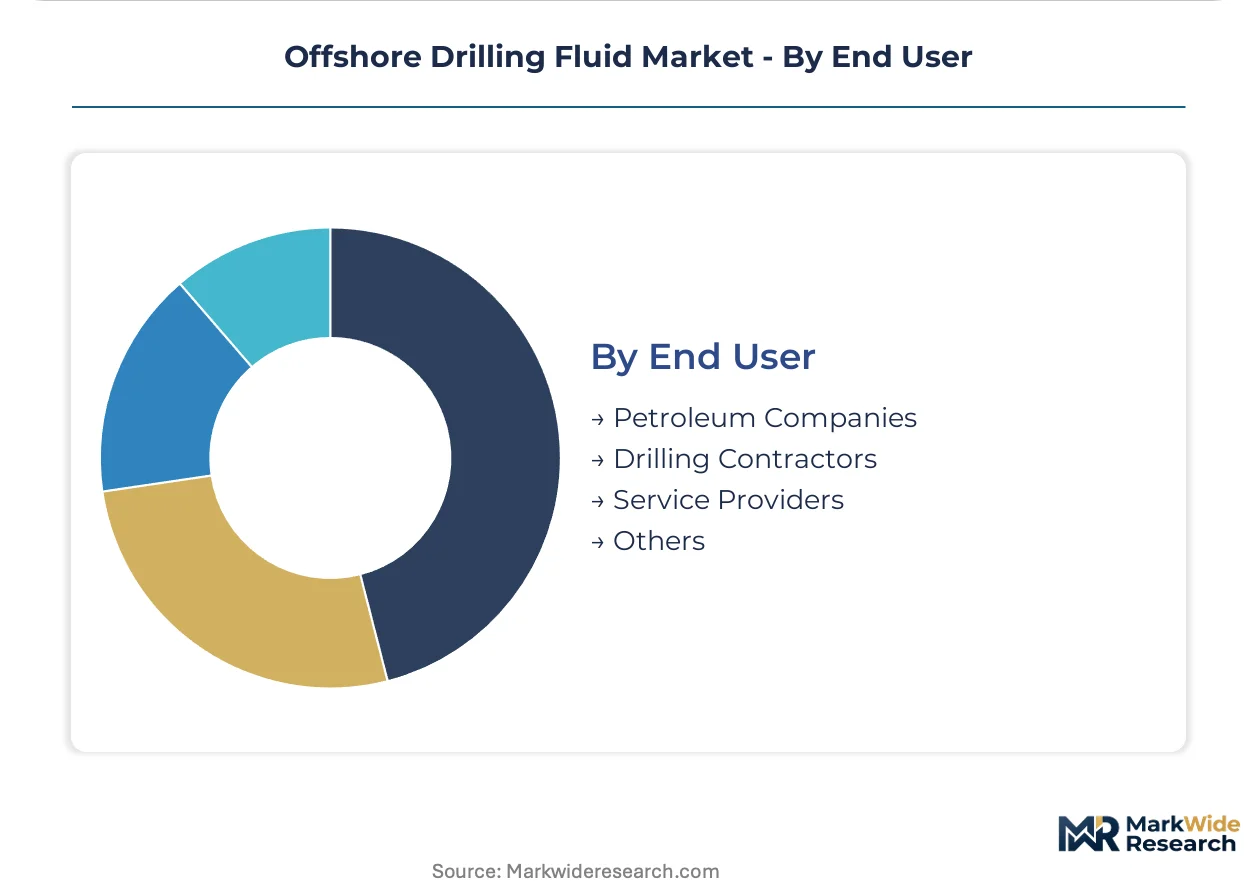
End User:
Procurement authority and technical specification control vary systematically across operator types, with national oil companies increasingly unbundling fluid selection from rig contracting.
- Petroleum Companies:IOCs and NOCs exercise direct procurement autonomy in pre-salt and high-complexity reservoirs. Petrobras and Equinor now separate fluid system selection from rig contracting, enabling supplier relationships independent of integrated drilling packages.
- Drilling Contractors:Dayrate-focused operators prioritize fluid cost minimization in standard well programs. Shallow water and mature basin operations default to contractor-managed procurement with limited technical specification input.
- Service Providers:Integrated drilling services platforms bundle fluid systems with downhole telemetry and directional drilling. SLB and Halliburton leverage this positioning to capture formulation premiums through performance-based contracts.
- Others:Specialist environmental consultants and regulatory compliance firms influence specification requirements in Norway and EU jurisdictions with mandatory chemical hazard assessments.
Petroleum Companies control premium specification; Service Providers are expanding fastest through bundled performance contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances tilt heavily toward supply concentration in the US Gulf Coast and North Sea, with frontier basins in West Africa and South America driving import dependency for high-performance synthetic formulations. Deepwater logistics networks shape regional competitive positioning more than raw material access.
United States
EPA effluent limitation guidelines under the Clean Water Act mandate real-time discharge monitoring for synthetic-based fluids, compelling operators toward closed-loop systems. The Gulf of Mexico dominates Western Hemisphere deepwater procurement, with Port Fourchon and Houston blending infrastructure supporting ultra-deepwater deployments in Lower Tertiary formations. Hurricane exposure creates periodic supply vulnerability.
Brazil
Petrobras pre-salt expansion at water depths exceeding 2,000 meters sustains demand for high-density internal olefin formulations. The national oil company exercises direct procurement autonomy for fluid system selection, unbundling specifications from rig contracting. Santos Basin operations command premium formulation volumes per well.
Norway
REACH-aligned chemical hazard assessments through the Petroleum Safety Authority require pre-deployment environmental risk profiles for each synthetic component. North Sea operators substitute legacy oil-based systems with lower-toxicity alternatives under mandatory toxicity protocols. Stavanger and Bergen clusters concentrate formulation engineering expertise.
Nigeria
Near-shore development drilling favors lower-cost water-based fluids where formation reactivity permits, with shallow water operations representing mature, price-sensitive procurement. Local blending dominates shelf development. Nigerian National Petroleum Corporation oversight shapes environmental compliance thresholds for coastal discharge.
Mauritania
Ultra-deepwater frontier blocks off Mauritania and Senegal lack established fluid supply chains, creating first-mover positioning for integrated service providers with floating storage capability. Operators targeting 1,500+ meter depths require single-fluid solutions with 2.4 specific gravity. Nouakchott logistics infrastructure remains underdeveloped for high-volume synthetic handling.
Offshore Drilling Fluid Market Vendor Landscape
Concentration sits with integrated drilling services platforms that bundle fluid systems with downhole telemetry and directional drilling packages. The vendor base stratifies between premium specialty suppliers with polymer engineering capabilities and commodity blenders serving mature basin price competition. Two archetypes dominate: technology-integrated service providers capturing formulation premiums through performance contracts, and regional blenders competing on logistics proximity. Competitive moves center on unbundling fluid procurement from rig contracting in Brazil and Norway, alongside bio-based surfactant certification for EU Green Deal procurement preferences.
Within the integrated services tier, SLB leverages its drilling services platform to anchor premium positioning, while Halliburton occupies a position exemplifying deepwater-specific additive specialization. Baker Hughes represents the bio-based surfactant vector for environmental compliance cost reduction. Among chemical specialists, Clariant and Chevron Phillips Chemical sit within the base fluid and specialty additive supply layer, supporting formulation differentiation without direct service integration.
| Leading Market Players |
|---|
| Weatherford International |
| SLB |
| Schlumberger |
| Chevron Phillips Chemical |
| Clariant |
| Halliburton |
| National Oilwell Varco |
| Lucite International |
| Baker Hughes |
| Others |
Supply Flow & Price Mechanics
Performance-based drilling contracts lock in multi-year fluid supply commitments while exposing base fluid costs to palm oil and natural gas derivative volatility. This structure concentrates pricing power with integrated service providers who control Port Fourchon blending capacity and can pass through feedstock spikes to national oil companies in Brazil and Norway.
Pricing Analysis
Petroleum companies with direct procurement autonomy anchor pricing stratification across premium, standard, and economy tiers. Premium internal olefin formulations command margins based on REACH-aligned certification and HPHT stability documentation, while shallow water operators in Nigeria and Angola drive price compression through local water-based blending. Cost compression in commodity synthetic fluids is intensifying because internal olefin feedstock prices track volatile agricultural and energy inputs. National oil companies in pre-salt blocks show least price sensitivity; drilling contractors managing mature Gulf of Mexico shelf development exhibit highest.
Supply Chain Analysis
Hurricane exposure along the Louisiana Gulf Coast underwrites supply vulnerability for Western Hemisphere deepwater operations. Base fluid production concentrates in the United States, Norway, and Singapore, with linear alpha olefin manufacturing drawing from ethylene feedstocks tied to regional petrochemical complexes. Single-source vulnerability runs through Port Fourchon and Houston infrastructure, where limited alternative blending capacity exists for ultra-deepwater specifications. Distribution feeds from integrated service provider hubs to floating storage units off West Africa and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based fluid substitutes threaten synthetic-based incumbents in shallow water segments where formation reactivity permits, forcing specialty suppliers to defend high-specification positioning.
For Market Incumbents: Fortify certification moats around REACH-aligned environmental risk profiles and OECD 306 bio-based surfactant documentation to neutralize compliance cost advantages. Deepen backward integration into internal olefin manufacturing to compress feedstock exposure. Lock in multi-year performance contracts with Petrobras and Equinor before procurement autonomy spreads to additional national oil companies. For New Entrants and Emerging Players: Anchor in Mauritania and Senegal ultra-deepwater blocks where floating storage logistics gaps create first-mover positioning. Target bio-based surfactant supply to EU Green Deal procurement preferences as the most penetrable regulatory wedge. Pursue direct supplier relationships with Brazilian pre-salt procurement teams unbundled from integrated drilling packages. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated service providers with closed-loop system contracts tied to BSEE-mandated real-time monitoring infrastructure. Five-to-ten year viability favors suppliers with polymer engineering capabilities above 200°C and 20,000 psi thresholds. Watch for inflection when EPA effluent limitation guidelines tighten discharge concentration reporting thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Internal Olefin Production | Captive supply of linear alpha olefin feedstocks insulates margin compression from palm oil volatility. |
| REACH-Aligned Certification Investment | Pre-deployment environmental risk documentation unlocks Norwegian Petroleum Safety Authority approval. |
| Floating Storage Deployment | Logistics infrastructure off Mauritania and Senegal addresses supply chain gaps in frontier ultra-deepwater. |
| Real-Time Return Monitoring Integration | BSEE-mandated subsea systems enable predictive fluid management contracts with Gulf of Mexico operators. |
| Bio-Based Surfactant Scale-Up | OECD 306 test documentation captures EU Green Deal procurement preferences in marine-biodegradable additives. |
Methodological Framework
Operator-level perspectives from drilling fluid procurement managers, offshore platform engineers, HSE compliance officers, and petrochemical supply planners anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through EPA effluent limitation guideline filings, BSEE incident reports, Norwegian Petroleum Safety Authority chemical hazard assessments, and customs data tracking internal olefin trade flows. Bottom-up well count modeling and top-down petrochemical demand analysis provided cross-verification.
Sensitivity analysis across price elasticity assumptions and regulatory timeline scenarios shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product chemistry tier, water depth deployment category, functional additive technology, and end-user procurement authority structure. CAGRs derived from well completion forecasts and fluid consumption intensity curves, with inputs from pre-salt block development schedules and Gulf of Mexico Lower Tertiary targeting patterns.
Material uncertainties — EPA discharge standard revisions, hurricane disruption frequency, and REACH alignment scope expansion — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory stability and feedstock price correlation patterns. Practitioners should keep alternative scenarios live as multi-jurisdiction certification lag and legacy fleet retrofit complexity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Europe Natural Gas Market
Oil & Gas
Digital Drilling Rigs Market
Oil & Gas
Delayed Coker Unit Process Technology Market
Oil & Gas
Subsea Well Access System Market
Oil & Gas
Asia Pacific Oil Storage Tank Service Market
Oil & Gas
Chad Oil and Gas Upstream Market
Oil & Gas
Oil and Gas Data Management Market
Oil & Gas
Wireline Services Market
Oil & Gas
Oil Field Drill Bits Market
Oil & Gas
Drilling Mud Desander and Desilter Market
Oil & Gas
Qatar Oil and Gas Market
Oil & Gas
Middle-East Enhanced Oil Recovery Market
Oil & Gas
South and Central America Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Oil and Gas Downhole Cables Market
Oil & Gas
Oil Breather Tank Market
Oil & Gas
Oil and Gas Engineering Services Market