
 North America Directional Drilling Services Market | 2026-2036
North America Directional Drilling Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Directional Drilling Services Market Analytics
The end-use vertical mix is broadening beyond conventional oil and gas operators as geothermal developers and carbon capture project sponsors enter the directional drilling procurement pool. Schlumberger NV leverages its rotary steerable portfolio to anchor deepwater contracts in the Gulf of Mexico. Halliburton Company sustains onshore market presence through integrated well construction packages across the Permian and Bakken. Baker Hughes Company differentiates via automated drilling systems that reduce non-productive time in extended-reach laterals.
Directional drilling services encompass the controlled deviation of wellbores from vertical to access subsurface targets using mud motors, whipstocks, or rotary steerable tools, with typical build rates ranging from 2 to 15 degrees per 100 feet depending on formation hardness. These services enable multi-well pad development, reservoir contact maximization, and collision avoidance in densely drilled fields. Rotary steerable systems command premium pricing due to real-time telemetry capabilities and continuous rotation advantages. Logging while drilling generates recurring revenue through formation evaluation contracts tied to footage drilled. Onshore exploration remains the volume anchor, though offshore exploration offers higher per-well service intensity.
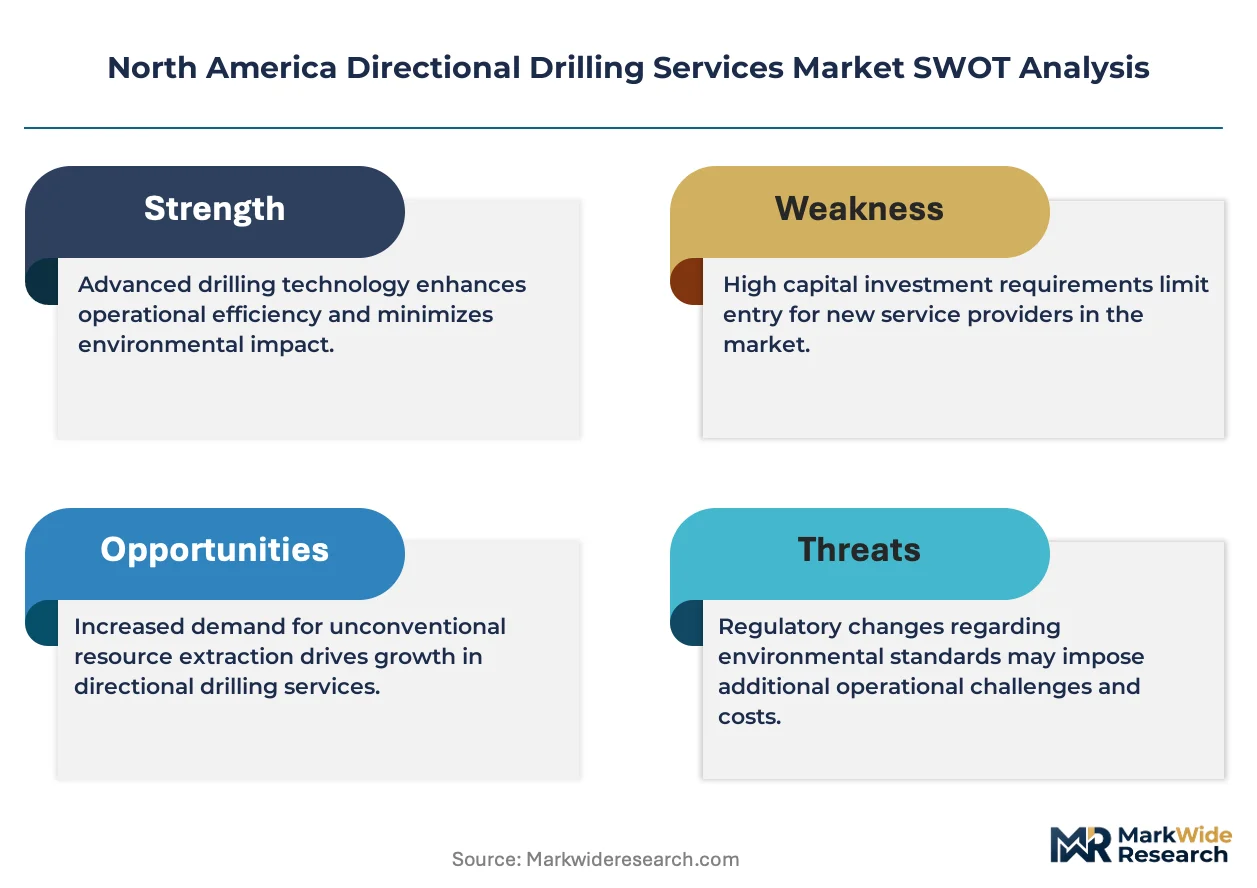
EPA methane regulations under the Clean Air Act, BLM venting and flaring rules, and Alberta Energy Regulator Directive 060 shape drilling program design, emissions monitoring obligations, and equipment certification requirements across the three-country operating zone. OSHA fall protection and confined space standards additionally govern rig-site service deployment. Stakeholders must weigh capital allocation between automated drilling platforms and conventional asset maintenance as regulatory compliance costs escalate and operator consolidation redefines vendor qualification criteria.
Market Dynamics
Horizontal wellbore complexity in the Permian Basin and Bakken formation is forcing directional drilling contractors to reconfigure mud motor specifications and rotary steerable toolkits for extended-reach laterals exceeding 15,000 feet. Service intensity per well has climbed as operators chase tighter spacing and multi-pad development.
Growth Catalysts
- EPA Methane Emissions Standards:The Clean Air Act rules mandate leak detection and repair protocols that favor advanced directional drilling for precise wellbore placement, reducing venting during completion operations.
- Geothermal developers:EGS projects in Nevada and Utah require directional drilling expertise to create engineered reservoir fractures, opening a procurement channel outside hydrocarbon extraction.
- Carbon capture and storage:Class VI well permitting for sequestration sites in Texas and Louisiana demands controlled deviation capabilities to access deep saline formations.
Market Restraints
- Specialized alloy supply:High-strength drill collar and heavy-weight drill pipe materials face concentration risk from limited domestic forging capacity, creating input cost volatility.
- BLM venting and flaring rules:Federal land restrictions in New Mexico and Wyoming delay drilling permit approvals, compressing active rig deployment windows.
- Directional surveying redundancy:Magnetic interference in the Alberta oil sands corridor forces dual gyroscopic verification, adding non-productive time per well.
Strategic Opportunities
- Alberta carbon capture hubs:The Alberta Energy Regulator's accelerated CCS approval pathway creates directional drilling demand for injection well clusters around Edmonton and Calgary.
- Real-time telemetry convergence:Integration of logging-while-drilling sensors with automated rig controls enables footage-based pricing models that align contractor and operator incentives.
- Geothermal district heating:Direct-use projects in Texas and New Mexico require shallow directional bores that existing oilfield service infrastructure can repurpose with minimal retooling.
Industry Challenges
- Directional driller talent pipeline:Experienced tool operators with MWD/LWD certification command premium wages, and training programs cannot replenish retirement-driven attrition in the Permian.
- API specification compliance:Downhole tool qualification to Q1 and Q2 standards extends procurement cycles for new rotary steerable system deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Directional Drilling Services Market |
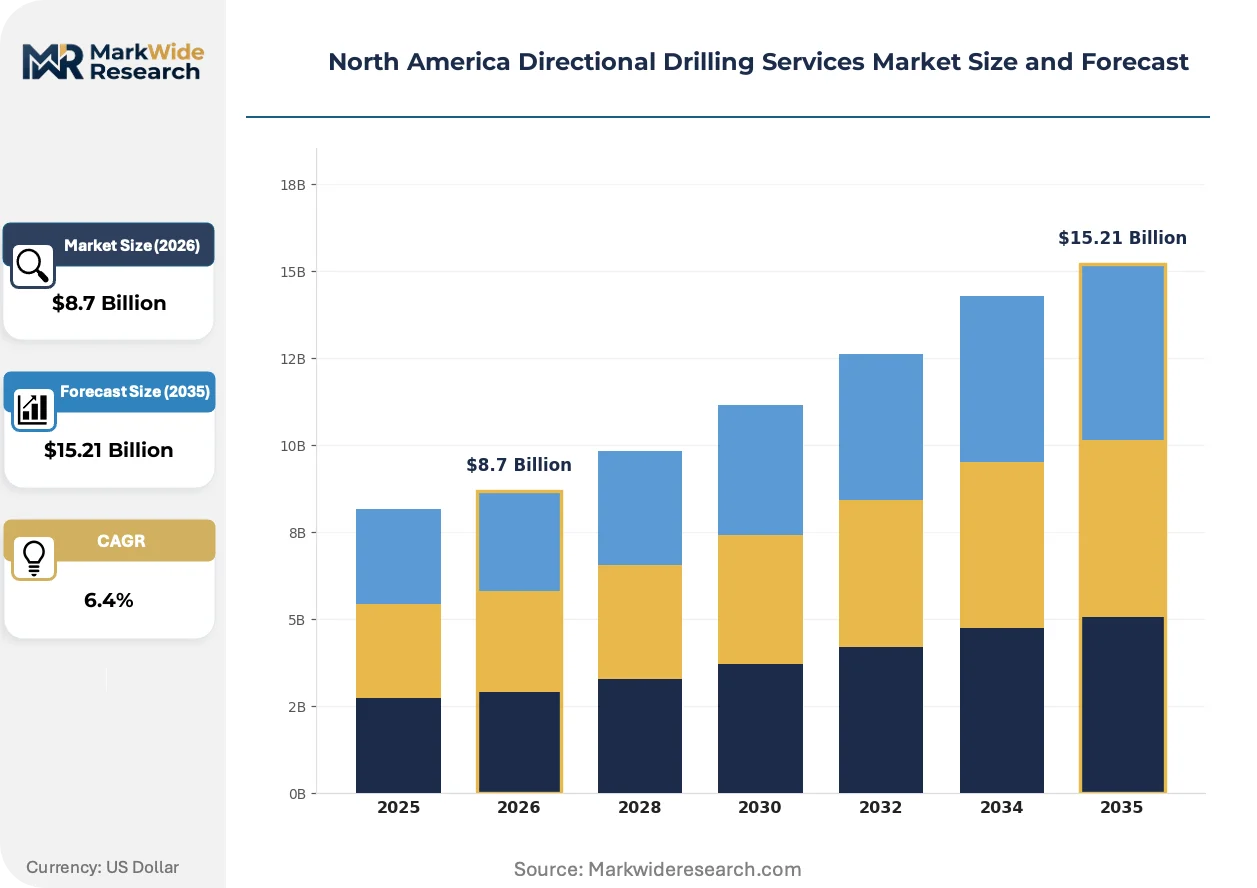
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Managed Pressure Drilling, Rotary Steerable Systems, Measurement While Drilling, Logging While Drilling End User: Oil & Gas Operators, Utilities, Mining Companies, Construction Firms Technology: Conventional Drilling, Advanced Drilling Systems, Hybrid Drilling Solutions, Automated Drilling Application: Onshore Exploration, Offshore Exploration, Well Completion, Environmental Remediation |
| Companies Covered | Schlumberger NV, Halliburton Company, Baker Hughes Company, Weatherford International plc, KLX Energy Services Holdings, Inc., National Oilwell Varco, Nabors Industries Ltd., Cathedral Energy Services Ltd., Scientific Drilling International, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Directional Drilling Services Market Evolving Landscape
Downhole automation and predictive analytics are compressing the feedback loop between geological steering decisions and surface rig response. Service contracts now embed performance guarantees tied to drilling efficiency metrics rather than day rates alone.
Closed-loop rotary steerable systems are integrating continuous inclination and azimuth measurements with automated trajectory corrections, eliminating slide drilling interruptions. Permian Basin operators deploying these tools report reduced wellbore tortuosity and improved casing running efficiency. The technology is integrating geosteering workflows with real-time formation evaluation, collapsing the traditional separation between directional and logging services.
Alberta Energy Regulator Directive 060 tightens flaring limits and mandates alternative compliance plans for sour gas drilling, forcing contractors to pre-qualify emission control equipment. Operators in the Montney and Duvernay plays must now document methane capture rates during directional drilling operations. The regulation is compressing project timelines as environmental approvals become gating items before spud.
Footage-based commercial structures are displacing traditional day-rate contracts in the Permian and Eagle Ford, transferring geological risk from operators to directional drilling providers. Contractors now price per lateral foot delivered within target zone tolerances, with bonuses for early section total depth. This model concentrates in Texas and New Mexico where well path predictability supports actuarial risk pricing.
North America Directional Drilling Services Market Segmentation
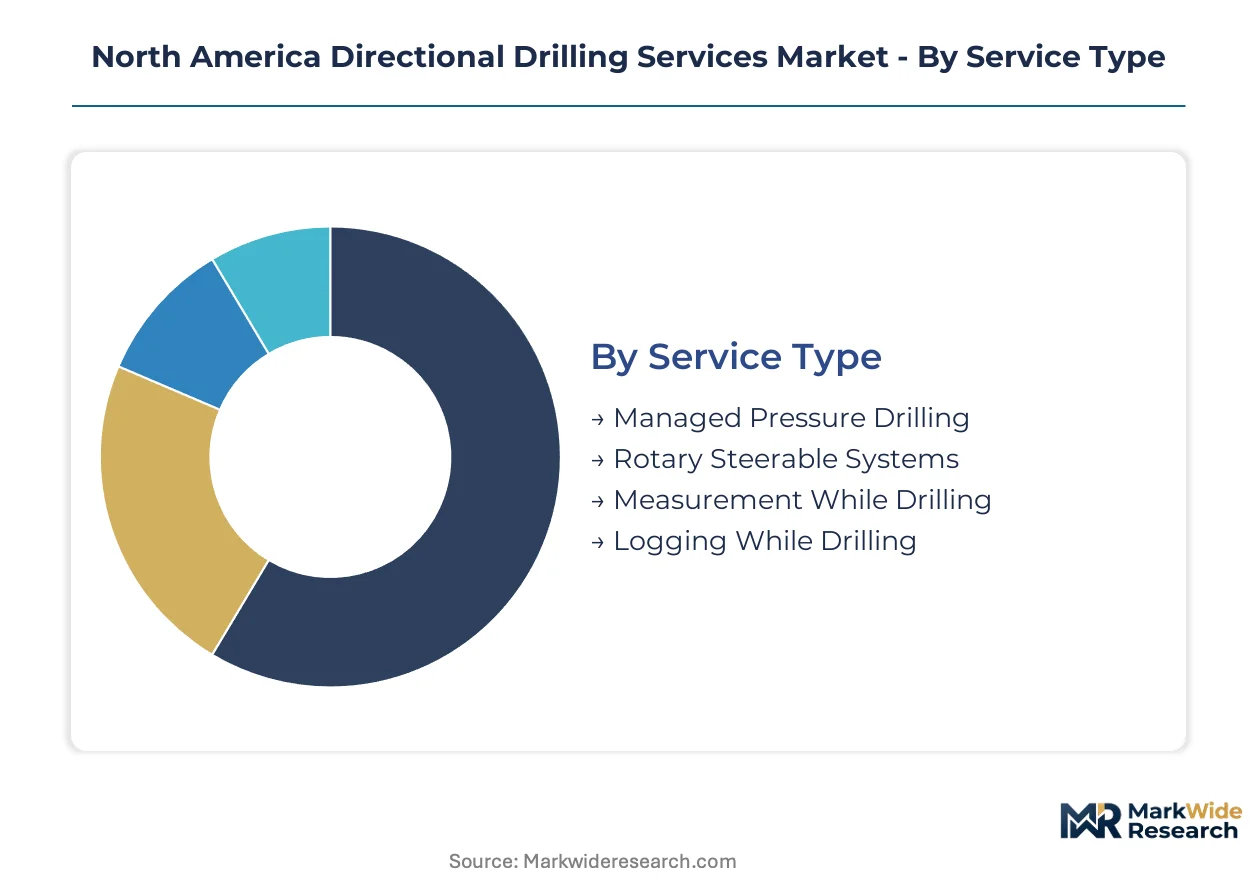
Directional drilling procurement patterns diverge sharply across service tiers and end-use verticals. Understanding these fault lines reveals where contractors command premium pricing versus where commoditization pressures dominate contract negotiations.
Service Type:
Customization intensity spans from fully automated closed-loop systems to standardized mud motor packages, with pricing power concentrating at the telemetry-integrated end of this spectrum.
- Rotary Steerable Systems:Continuous rotation during steering eliminates slide drilling interruptions and delivers real-time azimuth correction. Demand clusters in Permian Basin extended-reach laterals where wellbore tortuosity directly impacts casing running efficiency and completion costs.
- Logging While Drilling:Formation evaluation sensors embedded in bottom-hole assemblies generate recurring revenue through footage-based contracts tied to gamma ray and resistivity measurements. Operators in the Gulf of Mexico deepwater anchor procurement here, driven by reservoir characterization requirements before liner deployment.
- Managed Pressure Drilling:Annular pressure control for narrow drilling windows.
- Measurement While Drilling:Directional survey and toolface data transmission.
Most installed capacity flows through Rotary Steerable Systems. Expansion is steepest in Logging While Drilling.
End User:
Customer sophistication tiers separate integrated supermajors with multi-year framework agreements from spot-market buyers purchasing single-well packages.
- Oil & Gas Operators:Horizontal shale developers in Texas and New Mexico drive volume through multi-well pad programs requiring consistent directional crews and standardized tool configurations. Their procurement emphasizes drilling efficiency guarantees and non-productive time penalties over day-rate minimization.
- Utilities:Geothermal developers in Nevada and Utah represent an emerging procurement channel with distinct technical requirements—shorter laterals, higher temperature ratings, and engineered fracture connectivity rather than reservoir drainage optimization.
- Mining Companies:Ore body delineation and ventilation shaft drilling.
- Construction Firms:Horizontal directional boring for utility installation.
Revenue concentration sits with Oil & Gas Operators. Procurement momentum is shifting fastest toward Utilities.
Technology:
Capital deployment patterns reveal a maturity gradient from legacy conventional fleets to digitally integrated automated platforms commanding 40-60% pricing premiums.
- Automated Drilling:Surface-downhole closed-loop control with predictive analytics and autonomous trajectory optimization. Deployment concentrates in the Permian Basin where labor scarcity and pad drilling density justify capital intensity for consistent hole quality.
- Advanced Drilling Systems:Modular toolkits combining rotary steerable with managed pressure capabilities for complex wellbore architectures. Alberta oil sands operators anchor demand here, driven by steam-assisted gravity drainage well pairs requiring precise horizontal section placement.
- Conventional Drilling:Mud motor and positive displacement steering.
- Hybrid Drilling Solutions:Retrofitted automation on conventional iron.
Active rig hours accumulate heaviest in Conventional Drilling. Technology investment is accelerating most rapidly in Automated Drilling.
Application:
Service intensity per wellbore foot varies dramatically between exploration wildcats and factory-mode development drilling, reshaping contractor fleet allocation.
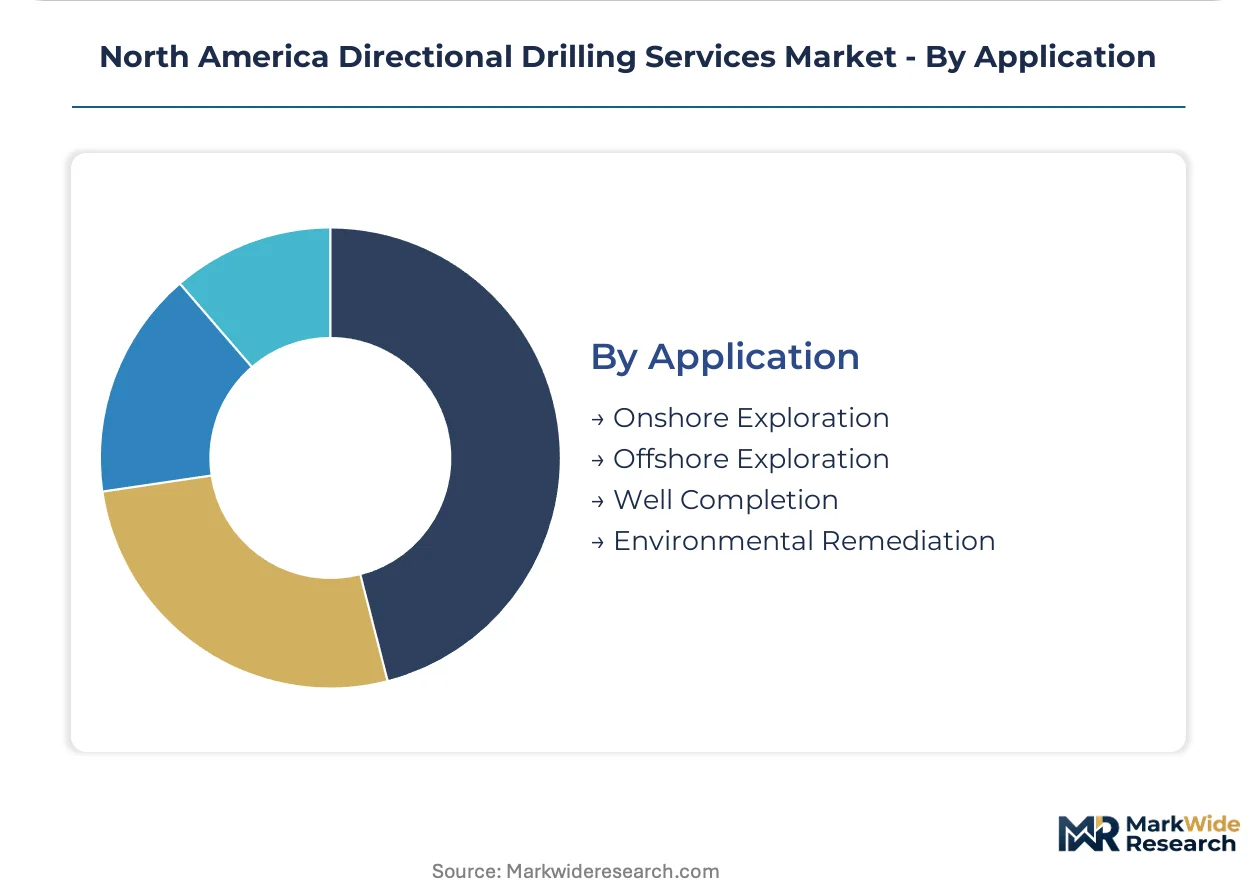
- Onshore Exploration:Multi-well pad development in the Permian, Bakken, and Eagle Ford formations generates predictable volume with standardized directional programs. Operators here prioritize crew continuity and tool reliability over cutting-edge telemetry for repetitive lateral landing zones.
- Offshore Exploration:Deepwater Gulf of Mexico projects demand premium rotary steerable systems with real-time geosteering and high-temperature ratings. Per-well service revenue multiples exceed onshore equivalents due to rig day rates and geological uncertainty.
- Well Completion:Lateral section drilling for production intervals.
- Environmental Remediation:Injection well drilling for groundwater cleanup.
Contractor headcount and iron allocation concentrate in Onshore Exploration. Margin expansion is sharpest in Offshore Exploration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials between sub-regions are redirecting capital deployment across the North American directional drilling services market. Operators migrate drilling programs toward jurisdictions with streamlined permitting and lower compliance burdens, compressing activity windows in restrictive zones.
United States
Permian Basin shale operators in Texas and New Mexico dominate horizontal well procurement, with extended-reach laterals exceeding 15,000 feet now standard. EPA methane emissions standards under the Clean Air Act mandate leak detection protocols that favor precise wellbore placement. Midland-Odessa anchors the densest directional drilling contractor concentration, where multi-well pad development drives crew specialization.
Canada
Alberta's oil sands corridors sustain steam-assisted gravity drainage drilling demand, while Montney and Duvernay operators navigate sour gas constraints. Alberta Energy Regulator Directive 060 tightens flaring limits and mandates alternative compliance plans, extending environmental approval timelines. Calgary-Edmonton corridor hosts the primary directional services procurement hub for CCS injection well clusters.
Mexico
Onshore conventional redevelopment in Tampico-Misantla and Burgos basins attracts directional drilling investment as Pemex accelerates farm-out agreements. National hydrocarbon regulator CNH permitting delays compress rig deployment schedules compared to US benchmarks. Northern border states concentrate contractor activity where cross-border supply chains from Texas reduce equipment mobilization costs.
North America Directional Drilling Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated oilfield service majors commanding premium rotary steerable contracts while regional contractors compete on mud motor spot pricing. Market structure tilts toward consolidation at the high-technology tier and fragmentation in conventional steering services. Three archetypes dominate: full-service multinationals with telemetry-integrated platforms, mid-tier specialists focused on specific basins, and equipment-rental contractors supplying standardized toolkits. M&A activity concentrates on automated drilling technology acquisitions, while geographic expansion into geothermal and carbon capture verticals reshapes portfolio composition.
Among Houston-based integrated service providers, Schlumberger NV, Halliburton Company, and Baker Hughes Company occupy positions exemplifying the full-service archetype with rotary steerable and logging-while-drilling capabilities. These entities anchor the premium tier where real-time telemetry and automated trajectory control command pricing premiums over conventional mud motor competitors.
| Leading Market Players |
|---|
| Schlumberger NV |
| Halliburton Company |
| Baker Hughes Company |
| Weatherford International plc |
| KLX Energy Services Holdings, Inc. |
| National Oilwell Varco |
| Nabors Industries Ltd. |
| Cathedral Energy Services Ltd. |
| Scientific Drilling International |
| Others |
Value Network & Pricing Analysis
Closed-loop rotary steerable adoption in Permian Basin extended-reach laterals is simultaneously compressing per-foot drilling costs and concentrating procurement power among telemetry-integrated service providers. This technology transition rewards contractors with real-time formation evaluation capabilities while marginalizing conventional mud motor suppliers.
Pricing Analysis
Direct-to-operator contract structures dominate directional drilling procurement, bypassing distributor markups entirely. Three-tier pricing separates premium rotary steerable packages with geosteering integration from standard mud motor day-rate contracts and economy rental-only toolkits. Price differentiation centers on telemetry sophistication and footage-based performance guarantees versus traditional time-based billing. Cost compression in conventional steering tiers is intensifying because operator consolidation demands standardized tool configurations across multi-well pads. Spot-market buyers in single-well programs exhibit highest price sensitivity, while integrated supermajors with framework agreements prioritize drilling efficiency over day-rate minimization.
Supply Chain Analysis
Regional distribution centers in Houston and Calgary anchor hub-and-spoke patterns for downhole tool deployment, with satellite facilities in Midland-Odessa and Denver reducing mobilization times to active pads. Manufacturing concentration rests on the United States, Norway, and Japan for high-strength drill collar alloys, precision gyroscopic sensors, and downhole electronics. Raw material dependencies draw from chromium-molybdenum steel forgings, rare-earth magnet assemblies, and high-temperature elastomer seals. Single-source vulnerability concentrates in specialized gyroscopic sensor suppliers serving magnetic-interference zones. Distribution runs through dedicated oilfield service yards rather than third-party logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA methane emissions standards under the Clean Air Act mandate precise wellbore placement, creating durable demand for advanced directional capabilities regardless of commodity price cycles.
For Market Incumbents: Hedge against footage-based contract commoditization by deepening proprietary telemetry integration and securing exclusive geothermal developer partnerships in Nevada and Utah. Backward integration into high-strength alloy forging reduces input cost volatility from concentrated supplier bases. Defensive patent positioning around automated trajectory algorithms protects premium pricing tiers from emerging automated drilling specialists. For New Entrants and Emerging Players: Equipment-rental contractors represent the most penetrable channel partner type for modular mud motor packages targeting spot-market operators in New Mexico and Wyoming. White-space opportunities concentrate in carbon capture injection well drilling around Edmonton and shallow geothermal district heating bores in Texas border towns. A go-to-market angle emphasizing rapid crew mobilization and standardized tool configurations addresses operator frustration with incumbent scheduling rigidity. For Investors and Strategic Acquirers: Valuations sit cheapest among regional contractors with established basin presence but limited automation technology portfolios. Long-term viability over the coming decade hinges on successful technology transition from day-rate to footage-based commercial structures. Acquisition target archetype: mid-tier specialists with Permian crew density and underutilized rotary steerable iron. The signal to watch is Class VI well permitting velocity in Texas and Louisiana as a proxy for carbon capture directional drilling demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing | Rotary steerable telemetry protocols licensed to geothermal developers accelerate EGS project timelines in Nevada. |
| Backward Integration | In-house production of high-strength drill collars insulates margins from domestic forging capacity constraints. |
| Joint Venture | Carbon capture hub partnerships with Alberta operators secure multi-year injection well drilling commitments around Edmonton. |
| Capacity Expansion | Automated rig control software development centers in Houston address directional dr talent pipeline attrition. |
| Long-term Supply Agreement | Multi-year framework contracts with Permian supermajors provide crew continuity and equipment utilization certainty. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drilling contractors, directional drillers with MWD/LWD certification, E&P procurement managers, and geothermal project developers with secondary validation. Secondary sources included SEC 10-K filings from oilfield service majors, EIA drilling productivity reports, Alberta Energy Regulator directive filings, and EPA Clean Air Act implementation guidance. Bottom-up rig count and footage projections triangulated against top-down market value estimates derived from contractor revenue disclosures.
Segment-weighting approaches distributed value across rotary steerable systems, logging-while-drilling services, mud motor packages, and emerging geothermal/carbon capture verticals. Deployment model differentiation separated onshore from offshore, automated from conventional, and footage-based from day-rate contract structures. CAGRs were derived through regression analysis of historical footage growth against operator capital expenditure patterns and regulatory compliance cost trajectories. Forecast inputs incorporated rig efficiency gains from closed-loop automation and permitting timeline assumptions for Class VI carbon sequestration wells.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to BLM permitting delays, commodity price volatility affecting operator drilling budgets, and breakthroughs in alternative geothermal drilling techniques. Forecasts reflect documented assumptions regarding regulatory implementation timelines and technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Big Data in Oil and Gas Exploration and Production Market
Oil & Gas
Oilfield Casing Spools Market
Oil & Gas
Middle East and Africa Digital Oilfield Market
Oil & Gas
Kuwait Oilfield Services Market
Oil & Gas
Malaysia Oilfield Services Market
Oil & Gas
Pumpjack Market
Oil & Gas
Well Completion Market
Oil & Gas
Smart Oilfield Market
Oil & Gas
Subsea Well Access and BOP System Market
Oil & Gas
West Africa Oil and Gas Midstream Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Oilfield Chemicals Market
Oil & Gas
Digital Oil Field Technology Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
Enhanced Gas Recovery (EGR) Market
Oil & Gas
Indonesia Coal Market