
 Oilwell Spacer Fluids Market | 2026-2036
Oilwell Spacer Fluids Market Size, Share, and Industry Trends Forecast 2026-2036
Oilwell Spacer Fluids Market Outlook
North American shale patch capacity expansion is fragmenting competitive dynamics across the oilwell spacer fluids supply base. Halliburton Co. leverages its integrated well construction portfolio to bundle spacer fluid delivery with cementing services. Baker Hughes Co. competes through advanced synthetic formulations engineered for high-pressure high-temperature wells. Schlumberger Ltd. anchors its position via global logistics networks that reduce mobilization times to remote offshore rigs.
Oilwell spacer fluids are engineered chemical systems, typically comprising weighted brines, viscosifiers, and surfactant packages, designed to separate incompatible drilling and cementing fluids during well construction. These formulations must maintain density stability within narrow tolerances while preventing fluid contamination that compromises zonal isolation integrity. Aqueous spacer fluids dominate routine onshore applications where cost efficiency governs procurement decisions, while synthetic formulations command premium positioning in deepwater and HPHT environments where thermal stability and compatibility margins determine operational outcomes. Service Companies represent the fastest-growing end-user channel as operators outsource cementing complexity to specialized providers.
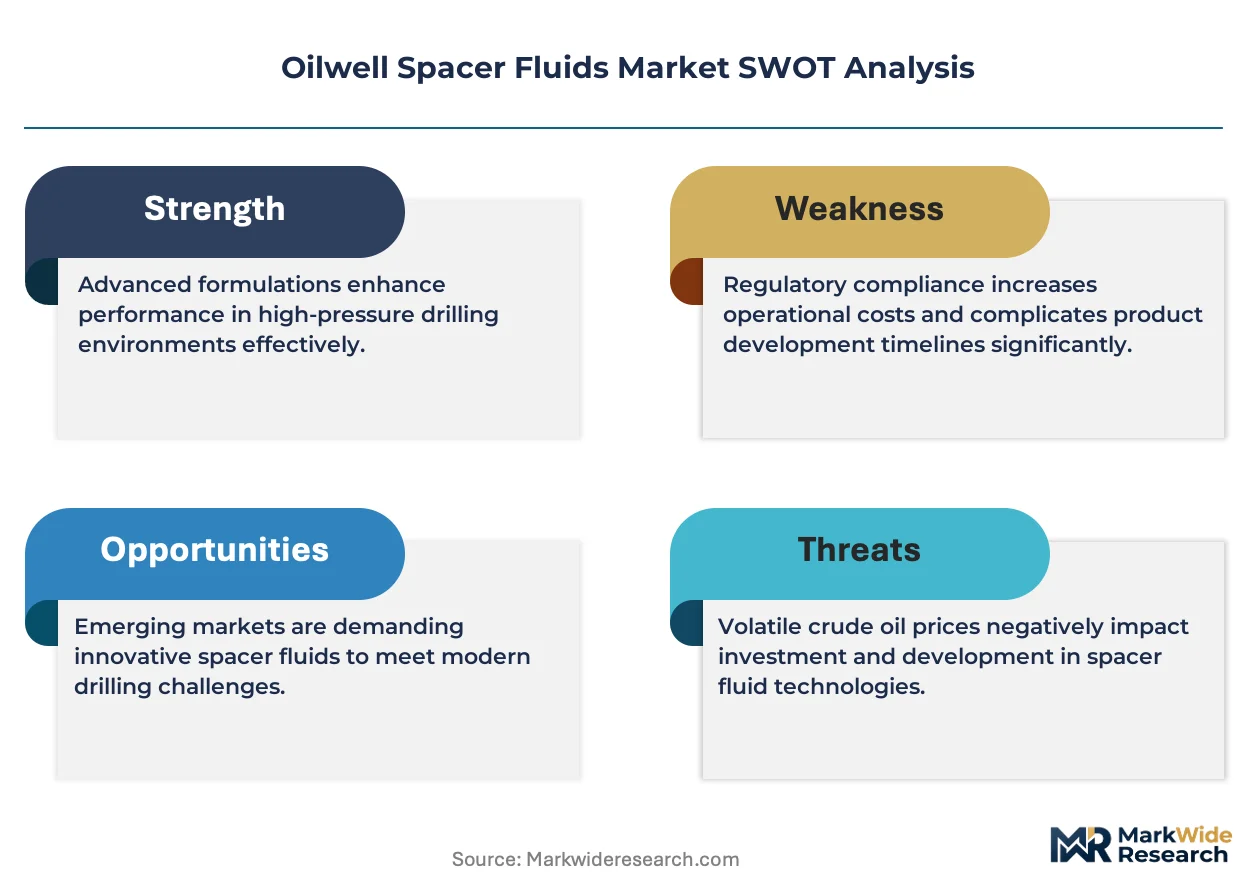
EPA offshore discharge regulations and BSEE well integrity standards shape formulation choices by restricting certain surfactant chemistries in federal waters. The EU REACH framework and OSPAR conventions impose parallel constraints on North Sea operations, forcing reformulation of conventional spacer systems. Stakeholders must monitor evolving regulatory thresholds for biodegradability and toxicity as these standards spread from European waters to other offshore jurisdictions.
Market Dynamics
Deepwater drilling complexity in Brazil's pre-salt basins and the Gulf of Mexico is compressing tolerance margins for cementing operations, forcing operators toward synthetic spacer formulations that maintain stability across extreme pressure-temperature gradients.
Growth Catalysts
- EPA Offshore Discharge Standards:Tightened biodegradability thresholds for marine environments are accelerating replacement of legacy surfactant packages with compliant synthetic chemistries in US federal waters.
- Brazil Pre-Salt Cementing Complexity:Ultra-deep carbonate reservoirs with high CO2 content demand specialty spacer fluids engineered for extended thickening time and gas migration control.
- HPHT Well Construction:Synthetic base fluids with thermal stability above 400°F are displacing aqueous systems in high-pressure high-temperature formations across the Gulf of Mexico and West Africa.
Market Restraints
- Barite Supply Concentration:Weighting agent procurement depends heavily on Chinese mineral processing capacity, exposing formulators to export restriction volatility and freight cost spikes.
- Specialty Surfactant Input Costs:Bio-based viscosifiers and biodegradable surfactant packages carry 40-60% cost premiums over conventional chemistries, compressing margins for standard-grade applications.
- REACH Compliance Burden:EU chemical registration requirements for novel spacer additives extend development timelines by 18-24 months and elevate R&D overhead for European offshore suppliers.
Strategic Opportunities
- West Africa Deepwater Expansion:Underdeveloped ultradeep blocks off Angola and Nigeria lack established supply chains, creating first-mover positioning for integrated service companies with logistics capabilities.
- OSPAR Convention Alignment:Anticipated adoption of North Sea biodegradability standards across South American and African offshore jurisdictions will favor pre-compliant formulation portfolios.
- Real-Time Spacer Monitoring:Integration of downhole sensors with automated density control systems is virtualizing manual mixing operations and enabling predictive cementing optimization.
Industry Challenges
- HPHT Fluid Engineering Talent:Scarcity of chemists with dual expertise in polymer rheology and high-temperature stability testing constrains product development velocity for next-generation synthetic systems.
- Multi-Jurisdiction Certification:Divergent approval timelines between BSEE, ANP, and NPD regulators force redundant qualification testing for global operators running standardized drilling programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oilwell Spacer Fluids Market |
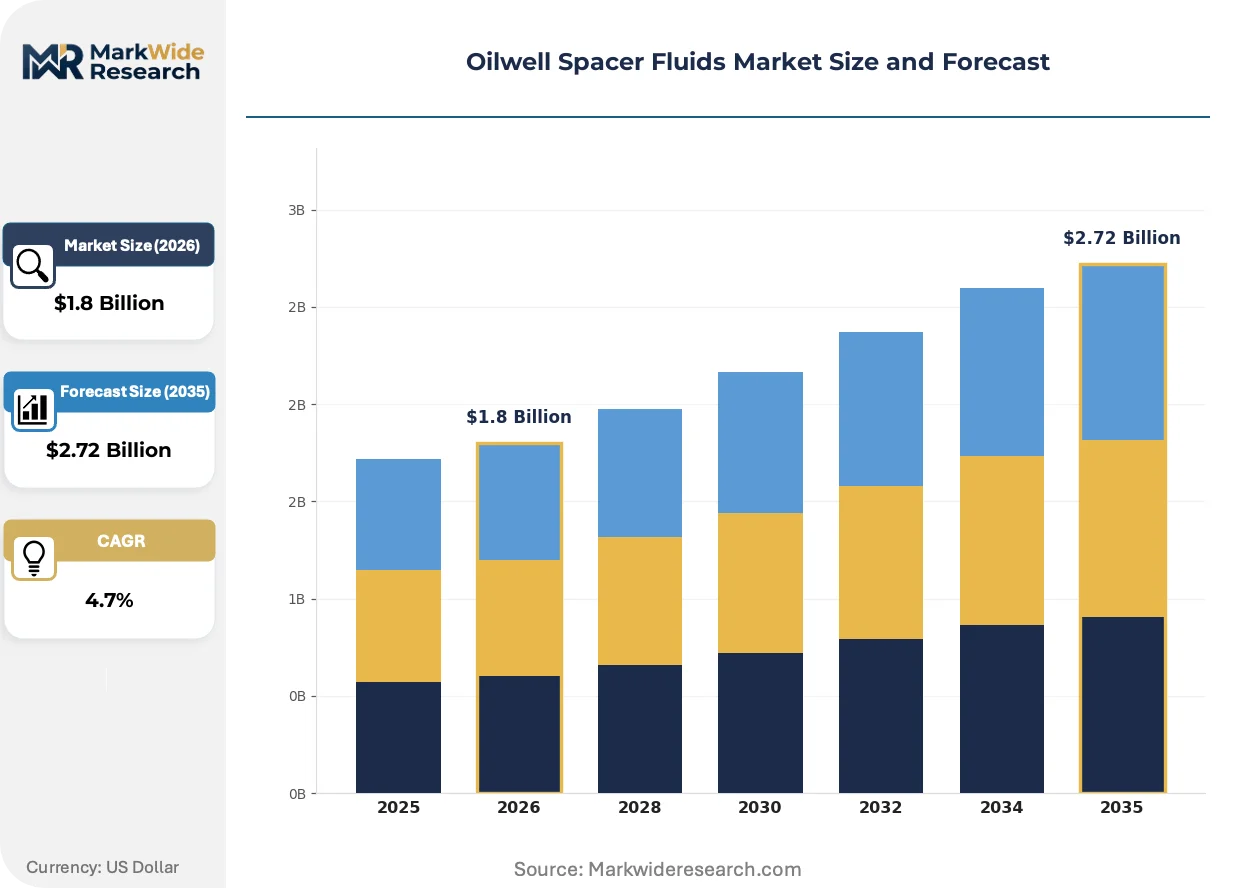
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fluid Type: Aqueous, Non-Aqueous, Gel, Synthetic Application: Wellbore Cleanup, Cementing, Drilling, Stimulation End User: Oil & Gas Operators, Service Companies, Engineering Firms, Independent Producers Formulation: Eco-Friendly, Conventional, High-Performance, Customized |
| Companies Covered | Chevron Phillips Chemical Co. LLC, Aubin Ltd., Halliburton Co., M and D Industries of LA Inc., Impact Fluid Solutions LP, Baker Hughes Co., BASF SE, Croda International plc, Schlumberger Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oilwell Spacer Fluids Market Strategic Shifts
Synthetic chemistry advances and digital integration are converging to redefine spacer fluid performance benchmarks, with formulation science increasingly inseparable from real-time operational data streams.
Nanoparticle-stabilized emulsion systems are virtualizing conventional density management by replacing mechanical weighting with electrosteric stabilization, enabling precise rheology control without barite sag. Deepwater contractors in Brazil and the Gulf of Mexico are piloting these systems for extended-reach wells where conventional weighted spacers risk density segregation. The technology is virtualizing traditional heavy brine logistics by collapsing inventory requirements at remote offshore supply bases.
REACH framework amendments tightening aquatic toxicity thresholds are forcing systematic reformulation of anionic surfactant packages used in North Sea spacer systems. Manufacturers must substitute legacy chemistries with bio-based alternatives that meet OECD 306 biodegradability standards while maintaining interfacial tension performance. Synthetic base fluid suppliers with pre-registered compliant portfolios are capturing specification advantages as operators front-load regulatory compliance ahead of 2027 enforcement windows.
Integrated cementing service contracts are consolidating procurement authority with major drilling contractors who bundle spacer fluid supply with pumping equipment and technical supervision. National oil companies in Brazil and Mexico are migrating from chemical purchase agreements to performance-based arrangements where payment ties to zonal isolation verification. This consolidation is most visible in Petrobras pre-salt campaigns where single-source accountability reduces interface risk between fluid design and placement execution.
Oilwell Spacer Fluids Market Segmentation
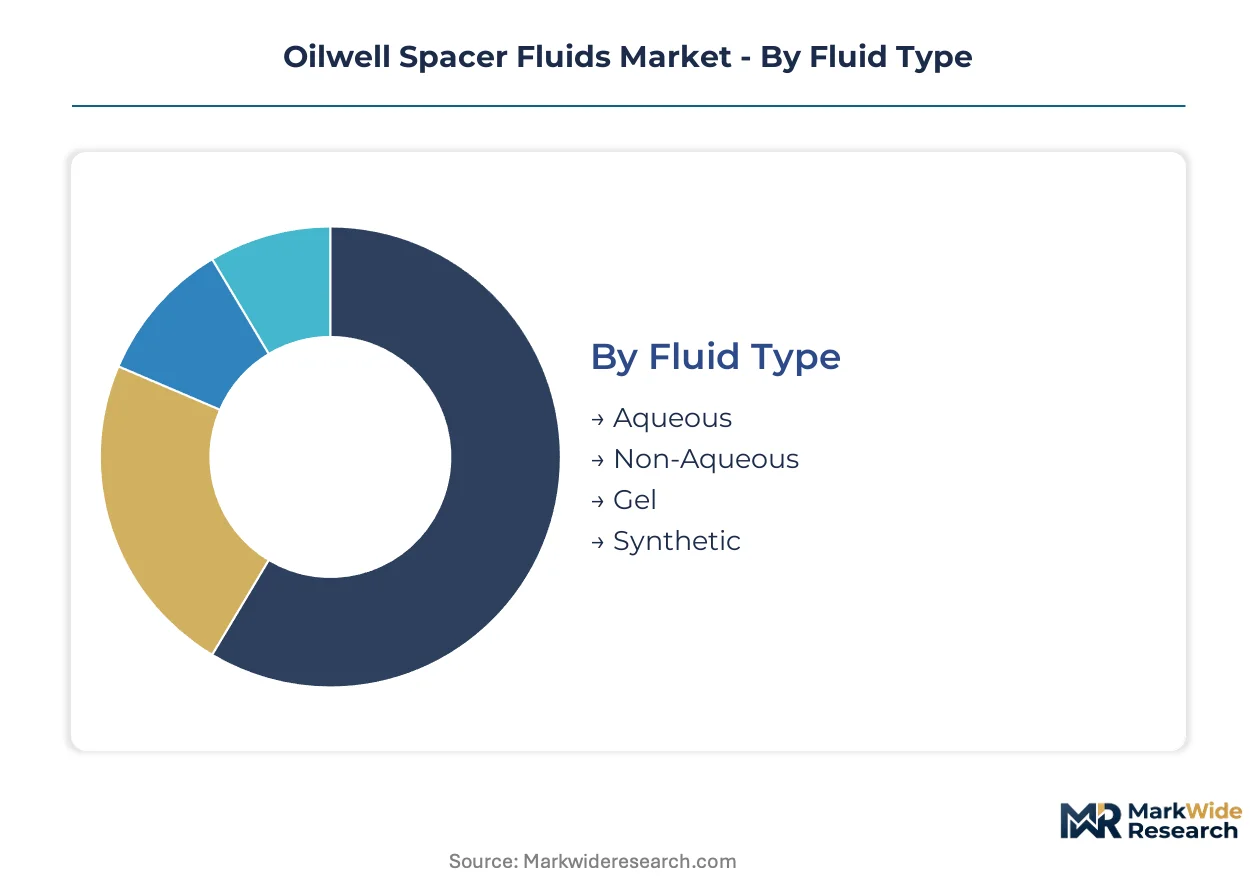
Segmentation in the oilwell spacer fluids market reflects divergent technical requirements across drilling environments. Formulation choices directly correlate with well complexity, regulatory jurisdiction, and procurement authority concentration among buyer types.
Fluid Type:
Cost tier differentiation separates commodity aqueous systems from premium synthetic formulations engineered for extreme downhole conditions.
- Aqueous:Water-based formulations weighted with barite or calcium carbonate dominate routine onshore cementing where cost efficiency governs procurement. Demand concentrates in North American shale basins where operators prioritize volume economics over thermal stability margins.
- Synthetic:Engineered base fluids with thermal stability exceeding 400°F command premium positioning in deepwater pre-salt campaigns off Brazil and HPHT wells across the Gulf of Mexico. These systems prevent density segregation during extended thickening times required for ultradeep carbonate reservoirs.
- Non-Aqueous:Oil-based spacer systems serve specialized applications where water sensitivity threatens formation integrity.
- Gel:Crosslinked polymer systems provide temporary zonal isolation during complex multi-stage cementing operations.
Aqueous formulations hold installed capacity across onshore fleets. Synthetic fluids are rotating up the share rankings in deepwater contractor specifications.
Application:
Application scope spans the well construction lifecycle from displacement operations through completion integrity verification.
- Cementing:Primary zonal isolation applications demand spacer fluids engineered for precise density compatibility with lead and tail cement slurries. Demand concentrates in Brazil's pre-salt basins where ultra-deep carbonate reservoirs with high CO2 content require extended thickening time control and gas migration prevention.
- Wellbore Cleanup:Displacement operations remove drilling fluid residues before cement placement to ensure bonding integrity. These applications are expanding in West Africa deepwater blocks where multi-zone completions increase mechanical complexity.
- Drilling:Specialized spacer pills separate incompatible mud systems during fluid changeouts.
- Stimulation:Pre-fracturing spacer applications protect formation faces from damaging filtrate invasion.
Cementing applications hold installed capacity in service company portfolios. Wellbore cleanup is climbing the fastest as operators outsource displacement complexity to integrated providers.
End User:
Customer type determines procurement structure from direct chemical purchase to performance-based service contracting.
- Service Companies:Integrated drilling contractors bundle spacer fluid supply with cementing equipment and technical supervision, consolidating procurement authority. This channel is expanding most quickly as national oil companies in Brazil and Mexico migrate from chemical purchase agreements to single-source accountability models.
- Oil & Gas Operators:Majors and independents with in-house cementing engineering retain direct formulation specification authority for critical wells.
- Engineering Firms:Third-party well construction consultants influence spacer selection through technical standards embedded in drilling programs.
- Independent Producers:Smaller operators rely on service company recommendations with limited technical intervention.
Service companies hold installed capacity in integrated contract structures. Oil & gas operators are gaining share fastest as performance-based payment terms spread from Petrobras pre-salt campaigns to other jurisdictions.
Formulation:
Formulation positioning reflects regulatory compliance tiering and performance specification stratification.
- High-Performance:Synthetic base fluids with nanoparticle stabilization and advanced surfactant packages serve HPHT and deepwater applications where narrow tolerance margins compress operational risk. Demand concentrates in Gulf of Mexico ultradeep blocks where BSEE well integrity standards mandate enhanced gas migration control.
- Eco-Friendly:Bio-based viscosifiers and biodegradable surfactant packages meeting OECD 306 standards are displacing legacy chemistries in North Sea operations under REACH framework amendments. These formulations carry 40-60% cost premiums but capture specification advantages as operators front-load compliance ahead of enforcement windows.
- Conventional:Standard aqueous systems with legacy surfactant packages retain position in cost-sensitive onshore markets.
- Customized:Project-specific formulations engineered for unique reservoir chemistry or regulatory constraints.
High-performance formulations hold installed capacity in deepwater contractor inventories. Eco-friendly systems are rotating up the share rankings as OSPAR-aligned biodegradability standards spread beyond European waters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical suppliers for oilwell spacer fluids concentrate manufacturing capacity near deepwater drilling hubs and established offshore logistics corridors. Formulation expertise clusters around Gulf Coast petrochemical infrastructure and North Sea supply bases serving mature offshore provinces.
United States
Deepwater drilling contractors in the Gulf of Mexico drive synthetic spacer fluid consumption for HPHT wells exceeding 400°F bottom-hole temperatures. EPA offshore discharge standards under the National Pollutant Discharge Elimination System restrict surfactant chemistries in federal waters. Houston anchors the domestic supply base where integrated service companies maintain blending facilities and offshore logistics networks.
Brazil
Pre-salt carbonate reservoirs with high CO2 content demand specialty formulations engineered for extended thickening time and gas migration control. ANP well integrity regulations mandate cementing performance verification for ultra-deep offshore completions. Macaé and Rio de Janeiro host the primary supply infrastructure supporting Petrobras pre-salt campaigns.
Norway
North Sea operators confront REACH framework amendments tightening aquatic toxicity thresholds for biodegradable spacer systems. OSPAR conventions drive replacement of legacy anionic surfactants with OECD 306-compliant alternatives. Stavanger and Bergen concentrate formulation development facilities serving Norwegian continental shelf drilling programs.
United Kingdom
Mature North Sea assets require wellbore cleanup and zonal isolation interventions driving demand for customized spacer packages. HSE offshore chemical notification schemes govern discharge permissions for novel additive chemistries. Aberdeen maintains the central supply hub for UKCS drilling contractors with integrated cementing service capabilities.
Mexico
Deepwater blocks in the Perdido Fold Belt and Salina Basin attract integrated service contracts bundling spacer fluid supply with cementing operations. ASEA environmental standards for offshore discharges shape formulation specifications in Mexican federal waters. Ciudad del Carmen serves as the logistics coordination point for Gulf of Mexico deepwater campaigns.
Oilwell Spacer Fluids Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying weighted brines, viscosifiers, and surfactant packages. The vendor base separates into three functional layers: integrated oilfield service companies bundling fluid delivery with pumping equipment, specialty chemical manufacturers providing formulation inputs, and regional blenders serving cost-sensitive onshore markets. Competitive positioning hinges on logistics reach into remote offshore supply bases and pre-qualified formulation portfolios spanning multiple regulatory jurisdictions. M&A activity targets synthetic base fluid capabilities and biodegradable surfactant technologies, while strategic partnerships secure barite supply chains and regional distribution rights.
Among integrated service providers, Halliburton Co., Baker Hughes Co., and Schlumberger Ltd. anchor the platform tier where cementing service contracts consolidate procurement authority. These companies exemplify the shift toward performance-based arrangements where payment ties to zonal isolation verification rather than chemical volume. Specialty chemical suppliers including BASF SE and Croda International plc occupy positions upstream, providing REACH-registered surfactant packages and bio-based viscosifiers that meet tightening biodegradability standards. Chevron Phillips Chemical Co. represents the petrochemical feedstock segment supplying synthetic base fluids with thermal stability margins required for HPHT applications.
| Leading Market Players |
|---|
| Chevron Phillips Chemical Co. LLC |
| Aubin Ltd. |
| Halliburton Co. |
| M and D Industries of LA Inc. |
| Impact Fluid Solutions LP |
| Baker Hughes Co. |
| BASF SE |
| Croda International plc |
| Schlumberger Ltd. |
| Others |
Value Chain & Pricing Dynamics
Chinese barite processing concentration anchors upstream weighting agent supply, capturing margin pools at the formulation tier where synthetic base fluid suppliers command premium positioning. Service companies bundle spacer fluid delivery with cementing operations, compressing standalone chemical margins while transferring value to integrated performance contracts.
Pricing Analysis
EPA offshore discharge standards dictate the pricing tier structure across the oilwell spacer fluids market, separating REACH-registered synthetic formulations from commodity aqueous systems. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and thermal stability performance. Cost compression in standard aqueous tiers is intensifying because of barite freight volatility and shale patch overcapacity. Independent producers in North American onshore basins exhibit highest price sensitivity, while deepwater contractors in Brazil's pre-salt campaigns prioritize gas migration control over unit economics.
Supply Chain Analysis
Extended payment terms from integrated service companies to specialty chemical suppliers are restructuring working capital requirements across the spacer fluid value chain. Manufacturing concentration centers on China for barite processing, the United States for synthetic base fluid production, and Norway for REACH-compliant surfactant development. Formulation chemistry draws from weighted brines, bio-based viscosifiers, and biodegradable surfactant packages. Single-source vulnerability in Chinese mineral processing exposes formulators to export restriction volatility. Distribution runs through offshore supply bases at Macaé, Houston, and Stavanger serving deepwater drilling hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oilwell spacer fluids market is recovering from cyclical lows as deepwater drilling activity rebounds in Brazil's pre-salt basins and Gulf of Mexico HPHT frontiers.
For Market Incumbents: Build regulatory compliance moats by pre-registering biodegradable surfactant portfolios under REACH framework amendments ahead of OSPAR convention spread. Secure backward integration into synthetic base fluid production to defend margins against specialty chemical input cost spikes. Anchor capacity expansion in West Africa deepwater corridors where supply chain gaps favor first-mover logistics networks. For New Entrants and Emerging Players: Mid-tier service contracts in Mexican deepwater blocks represent the most penetrable entry point, as Pemex outsourcing creates procurement authority fragmentation. Wellbore cleanup specialization for West Africa multi-zone completions offers technical differentiation without requiring full cementing service integration. Partner with established barite traders to bypass Chinese supply concentration risks while building formulation capabilities. For Investors and Strategic Acquirers: Capital is best deployed toward synthetic base fluid specialists with thermal stability testing infrastructure and ANP pre-qualification status. The five-to-ten year viability window favors suppliers with pre-compliant portfolios as biodegradability standards spread from European waters to South American and African offshore jurisdictions. Watch for BSEE enforcement pattern shifts on surfactant discharge thresholds as inflection indicators for formulation demand rotation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Base Fluids | Captures margin pools from Chevron Phillips Chemical and reduces thermal stability input cost exposure. |
| REACH-Compliant Surfactant Portfolio Pre-Registration | Secures specification advantages as OSPAR-aligned standards spread to Brazilian and West African waters. |
| West Africa Deepwater Logistics Network Buildout | Positions integrated service companies for first-mover advantage in Angolan and Nigerian ultradeep blocks. |
| Real-Time Spacer Monitoring Technology Partnership | Enables predictive cementing optimization through downhole sensor integration with automated density control. |
| Long-Term Barite Supply Agreement with Chinese Processors | Mitigates export restriction volatility and freight cost spikes for standard aqueous formulation tiers. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and SEC disclosures from integrated oilfield service companies. Cementing service directors, HPHT fluid engineers, procurement leads at national oil companies, specialty chemical R&D heads, and offshore logistics coordinators provided operational validation. Bottom-up volume triangulation across fluid type, application, and end-user segments was cross-checked against top-down value estimates from service contract disclosures and chemical purchase agreements.
Forecast inputs include drilling activity trajectories, regulatory enforcement timelines, and synthetic base fluid thermal stability adoption curves across the projection horizon. Segmentation dimensions span formulation chemistry, well complexity tier, procurement structure, and regional regulatory cluster. CAGRs were derived from elasticity modeling against upstream capital expenditure cycles and deepwater rig deployment patterns. HPHT well count projections and REACH amendment implementation schedules served as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in Brent crude pricing, offshore drilling dayrates, or Chinese export policy would shift the trajectory. Forecasts reflect documented assumptions on regulatory harmonization pace and synthetic chemistry cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Asia Pacific Oil Storage Tank Service Market
Oil & Gas
Europe Natural Gas Market
Oil & Gas
Mobile Servicing Rig Market
Oil & Gas
FTIR Oil Condition Monitoring Market
Oil & Gas
Oilfield Drilling Elevator Market
Oil & Gas
CO2 EOR Market
Oil & Gas
Asia-Pacific Oilfield Services Market
Oil & Gas
South America LNG Bunkering Market
Oil & Gas
LNG Terminal Market
Oil & Gas
India LNG Bunkering Market
Oil & Gas
Flexible Pipes for Oil and Gas Market
Oil & Gas
Oil Storage Terminal Market
Oil & Gas
Sucker Rod Market
Oil & Gas
Dry Natural Gas Market
Oil & Gas
North America Perforating Gun Market
Oil & Gas
Singapore LNG Storage Tank Market