
 Ecuador Oil and Gas Midstream Market | 2026-2036
Ecuador Oil and Gas Midstream Market Size, Share, and Industry Trends Forecast 2026-2036
Ecuador Oil and Gas Midstream Market Foresight
The capital-intensity divergence between state-backed and private operators is reorganizing competitive dynamics across Ecuador's midstream landscape. Petroecuador leverages its ownership of the Trans-Ecuadorian Pipeline System to dominate crude transportation from the Oriente basin to Esmeraldas. OCP Ecuador competes through its privately operated heavy-crude pipeline, which sustains alternative export capacity bypassing state infrastructure. Repsol anchors downstream integration by operating block partnerships that feed directly into midstream gathering systems.
Ecuador oil and gas midstream encompasses the transportation, storage, and processing infrastructure bridging upstream extraction with downstream refining and export, primarily involving pipeline networks operating at pressures up to 1,440 psi and crude storage terminals with combined capacity exceeding 16 million barrels. The service type dimension segments into transportation, storage, processing, and distribution functions, with transportation commanding the largest capital allocation due to pipeline replacement cycles and integrity management requirements. Processing is gaining structural importance as heavier crude blends from the Ishpingo-Tambococha-Tiputini fields require more intensive treatment before pipeline injection. The application split across crude oil, natural gas, NGLs, and refined products shows crude oil logistics occupying the dominant revenue share, while natural gas handling is expanding fastest as associated gas capture regulations tighten.
The Ministry of Energy and Non-Renewable Natural Resources sets licensing terms for pipeline concessions, while the country's national environmental regulator enforces watercourse crossing standards and spill response protocols that shape infrastructure routing and remediation budgets. International Maritime Organization standards for tanker exports and the national hydrocarbons law governing third-party pipeline access together determine market entry feasibility for new logistics providers. Stakeholders must monitor how fiscal regime negotiations between the state and private block operators redirect flow commitments across competing pipeline systems.
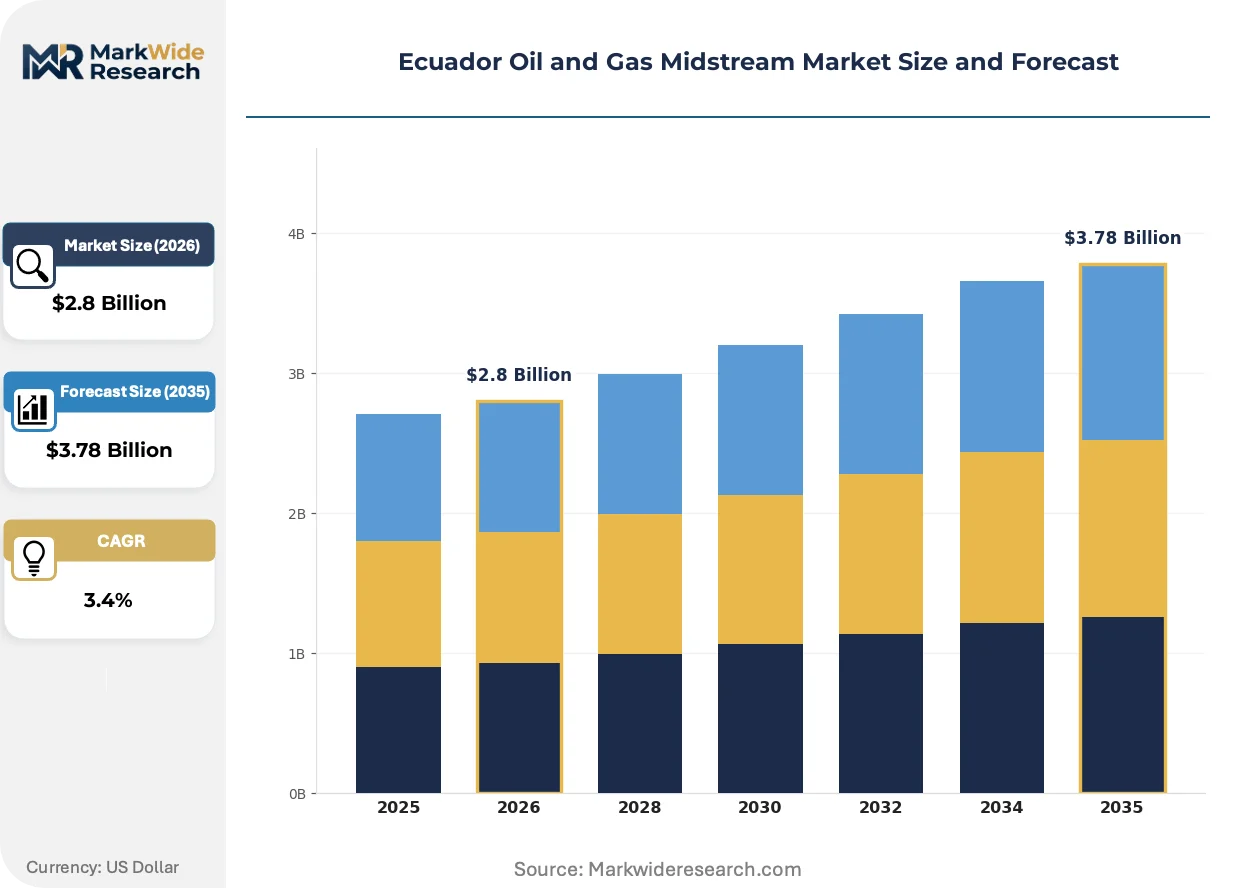
Market Dynamics
Pipeline integrity mandates from Ecuador's Ministry of Energy and Non-Renewable Natural Resources are forcing accelerated replacement cycles across the Trans-Ecuadorian system, compressing capital deployment timelines while operators balance heavy-crude processing upgrades against export commitments.
Growth Catalysts
- Amazon Basin production corridors:Concentrated extraction activity in the Oriente basin sustains throughput demand for existing pipeline infrastructure. Flow volumes from mature fields anchor transportation revenue.
- Associated gas capture regulations:Tightening environmental standards mandate gas processing infrastructure expansion. Midstream operators invest in NGL separation and handling capacity.
- Heavy-crude blend treatment requirements:Ishpingo-Tambococha-Tiputini field output demands specialized processing before pipeline injection. Technical service providers capture upgrade contracts.
Market Restraints
- State infrastructure concentration:Petroecuador's ownership of the Trans-Ecuadorian Pipeline System limits third-party access. Private operators face concession negotiation barriers.
- Environmental compliance cost escalation:Watercourse crossing standards and spill response protocols from the national environmental regulator inflate project budgets. Remediation reserves consume working capital.
- Geographic production dependence:Upstream output concentrates in remote Amazon regions. Pipeline construction and maintenance logistics compound operational complexity.
Strategic Opportunities
- Alternative export route development:OCP Ecuador's privately operated heavy-crude pipeline demonstrates viable bypass capacity. Independent logistics providers can negotiate throughput agreements.
- Downstream integration partnerships:Block operators like Repsol feed directly into midstream gathering systems. Vertical coordination reduces handoff friction.
- Storage terminal expansion:Combined capacity exceeding 16 million barrels supports buffer inventory strategies. Coastal terminals capture arbitrage between production cycles and tanker schedules.
Industry Challenges
- Specialized welding and coating expertise:High-pressure pipeline maintenance at 1,440 psi operating standards requires certified technicians. Training pipelines lag replacement demand.
- Fiscal regime negotiation uncertainty:State-private block operator agreements redirect flow commitments unpredictably. Midstream contracts face renegotiation risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ecuador Oil and Gas Midstream Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Storage, Processing, Distribution Technology: Pipeline, Tanker, Rail, Compression Application: Crude Oil, Natural Gas, NGLs, Refined Products End User: Refineries, Power Plants, Industrial Users, Exporters |
| Companies Covered | Sycar LLC, Petroecuador, Eni SpA, CNPC, Repsol, OCP Ecuador, Occidental Petroleum Corporation, Petrozamora SA, Techint International Construction Corp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ecuador Oil and Gas Midstream Market Shifts & Advancements
Digital monitoring systems and advanced integrity assessment tools are penetrating Ecuador's pipeline networks, replacing manual inspection regimes while operators confront heavier crude blends and tighter environmental enforcement.
Smart pigging technology equipped with magnetic flux leakage and ultrasonic sensors is displacing conventional hydrostatic testing for corrosion detection. Pipeline operators in the Oriente basin deploy these tools on accelerated cycles. The shift compresses inspection downtime while extending asset life projections for aging infrastructure.
Ecuador's national environmental regulator enforces watercourse crossing standards that mandate directional drilling and enhanced containment protocols. Infrastructure routing decisions now prioritize spill prevention over cost minimization. Operators redirect capital toward remediation bonds and emergency response equipment.
Refinery offtake contracts are consolidating around term structures that prioritize volume certainty over spot flexibility. State and private block operators negotiate longer-dated commitments with Esmeraldas processing facilities. Amazon Basin producers accept pricing discounts to secure guaranteed outlet capacity.
Ecuador Oil and Gas Midstream Market Segmentation
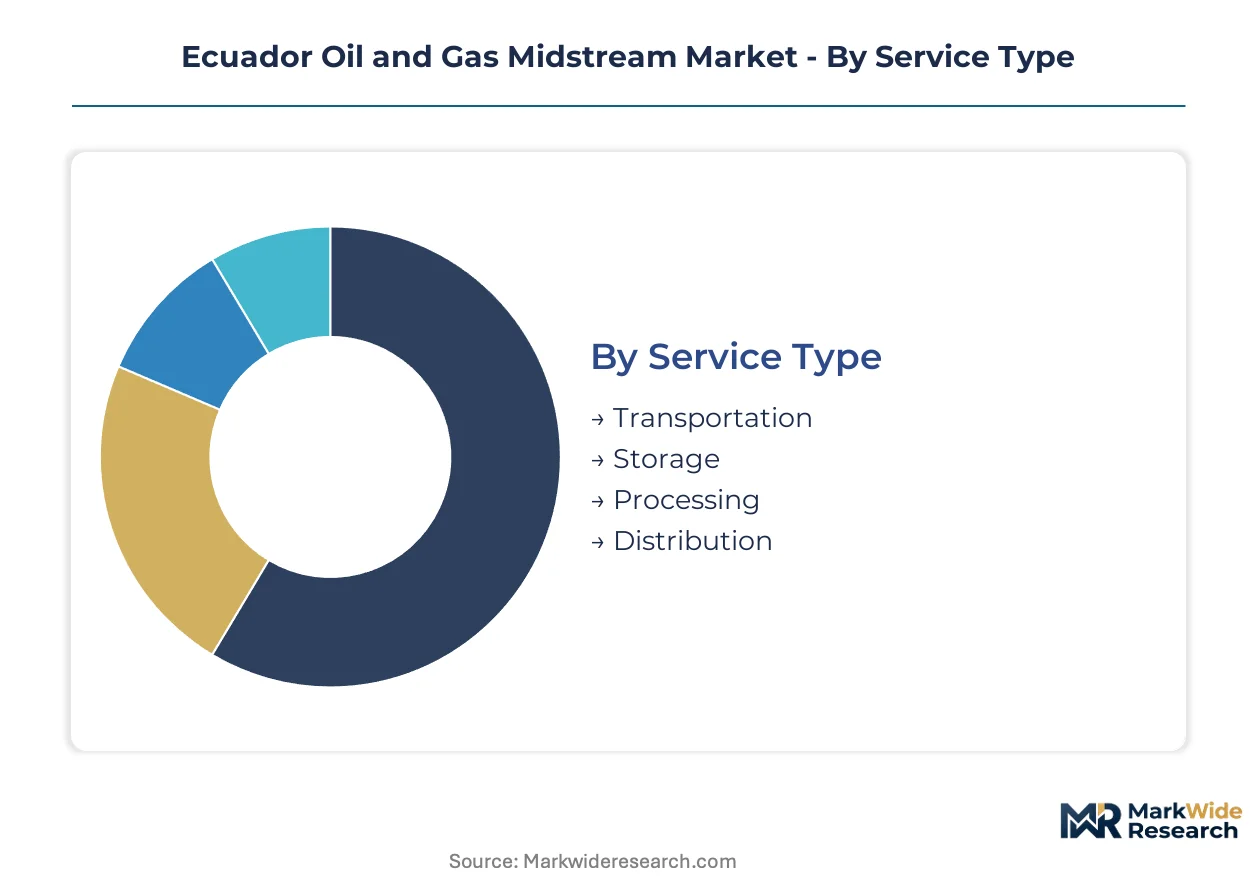
Midstream operators in Ecuador route hydrocarbons through distinct service and infrastructure channels, each shaped by crude quality, basin geography, and offtake destination. Segmentation reveals where capital concentrates and which customer types anchor revenue stability.
Service Type:
Transportation commands the largest capital allocation due to pipeline replacement cycles, while processing gains share as heavier crudes enter the system.
- Transportation:Pipeline networks operating at pressures up to 1,440 psi dominate crude movement from the Oriente basin to coastal terminals. The Trans-Ecuadorian Pipeline System and OCP's heavy-crude line constitute the primary channel infrastructure, with flow volumes from mature fields anchoring revenue.
- Processing:Specialized treatment facilities handle heavy-crude blends from Ishpingo-Tambococha-Tiputini fields before pipeline injection. Technical service providers capture upgrade contracts as environmental standards tighten on watercourse crossings.
- Storage:Crude storage terminals with combined capacity exceeding 16 million barrels support buffer inventory strategies. Coastal terminals capture arbitrage between production cycles and tanker schedules.
- Distribution:Final-mile logistics connect storage facilities to refineries and export terminals. Handoff efficiency determines working capital requirements for block operators.
Transportation dominates installed base. Processing is where expansion concentrates.
Technology:
Cost tiers separate high-pressure pipeline infrastructure from flexible modal alternatives, with each technology serving distinct volume and geography requirements.
- Pipeline:Fixed-route infrastructure at 1,440 psi operating standards carries the majority of crude volumes. Smart pigging technology with magnetic flux leakage sensors displaces conventional hydrostatic testing for corrosion detection.
- Tanker:Maritime transport handles export volumes from Esmeraldas terminals to international markets. International Maritime Organization standards shape vessel specifications and loading protocols.
- Rail:Supplementary capacity serves intermittent production spikes and maintenance bypass scenarios. Higher per-barrel costs limit deployment to contingency logistics.
- Compression:Associated gas handling infrastructure expands under tightening capture regulations. NGL separation equipment integrates with gas processing facilities.
Pipeline anchors volume throughput. Compression is climbing the fastest as gas regulations tighten.
Application:
Customer demand concentrates in crude logistics, while natural gas handling expands on regulatory mandate.
- Crude Oil:Heavy and medium crude blends from Amazon Basin fields constitute the dominant throughput category. Refinery offtake contracts consolidate around longer-dated term structures prioritizing volume certainty.
- Natural Gas:Associated gas capture requirements drive infrastructure investment across production corridors. Ministry of Energy and Non-Renewable Natural Resources mandates redirect capital toward gas processing.
- NGLs:Separation and handling capacity expands alongside gas processing infrastructure. Fractionation equipment serves both domestic industrial demand and export markets.
- Refined Products:Downstream logistics connect Esmeraldas refinery output to domestic distribution networks. Product pipelines face less capacity pressure than crude trunk lines.
Crude oil dominates installed base. Natural gas is where expansion concentrates.
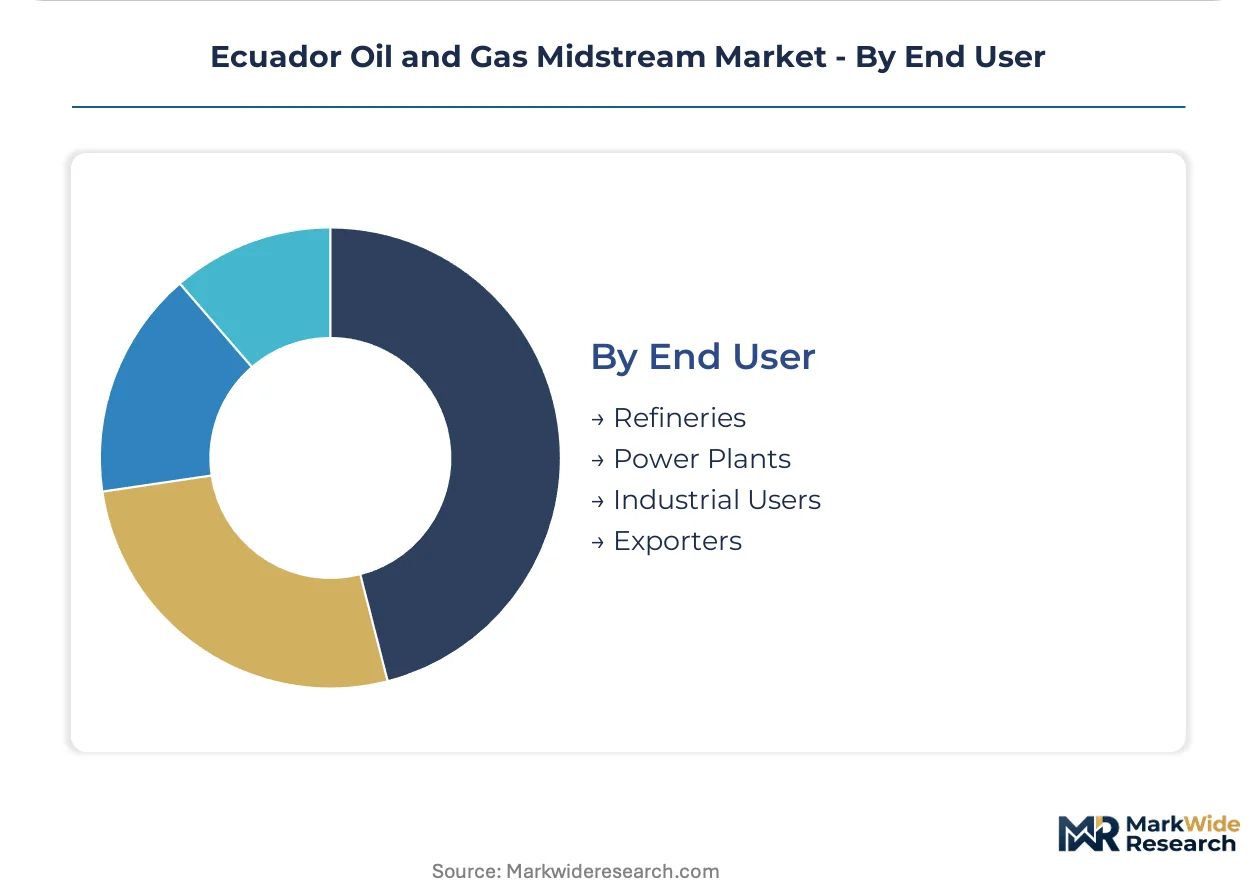
End User:
Volume flows concentrate toward coastal export terminals, while domestic offtake provides baseload stability.
- Refineries:Esmeraldas processing facilities anchor domestic crude demand. Long-term offtake contracts with state and private block operators prioritize volume certainty over spot flexibility.
- Power Plants:Natural gas offtake expands as generation fleets diversify from diesel dependence. Pipeline interconnections to thermal facilities require dedicated compression infrastructure.
- Industrial Users:Petrochemical and manufacturing facilities consume NGLs and refined products. Smaller volume profiles limit dedicated infrastructure investment.
- Exporters:International buyers receive the majority of Ecuador's crude production through maritime terminals. Tanker scheduling optimization drives storage terminal utilization patterns.
Exporters dominate volume throughput. Power plants are gaining share fastest as gas infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ecuador's midstream infrastructure channels crude exports toward Pacific terminals while import dependence concentrates on refined products. The country's pipeline networks bridge Amazon production zones with coastal refining and maritime loading capacity.
Amazon Basin Production Corridors
Oriente basin extraction sustains throughput demand for the Trans-Ecuadorian Pipeline System. The Ministry of Energy and Non-Renewable Natural Resources licenses pipeline concessions that shape flow commitments across competing infrastructure. Nueva Loja and Coca anchor gathering system concentration where heavy-crude treatment facilities process Ishpingo-Tambococha-Tiputini field output.
Coastal Export Terminals
Esmeraldas terminals handle the majority of maritime crude loading for international buyers. International Maritime Organization tanker standards govern vessel specifications and loading protocols at these facilities. The Esmeraldas refinery complex anchors domestic offtake while coastal storage terminals exceeding 16 million barrels buffer production cycles against tanker scheduling.
Sierra Interconnection Zone
Pipeline integrity mandates force accelerated replacement cycles across mountain crossing segments. The national environmental regulator enforces watercourse crossing standards that mandate directional drilling and enhanced containment protocols. Quito-based technical service providers coordinate integrity management programs for high-pressure infrastructure operating at 1,440 psi standards.
Guayas Industrial Corridor
Guayaquil distribution networks connect refined product terminals to domestic consumption centers. Associated gas capture regulations redirect infrastructure investment toward NGL separation and handling capacity. Industrial users in the petrochemical corridor consume fractionated products from expanding gas processing facilities.
Ecuador Oil and Gas Midstream Market Competitive Landscape
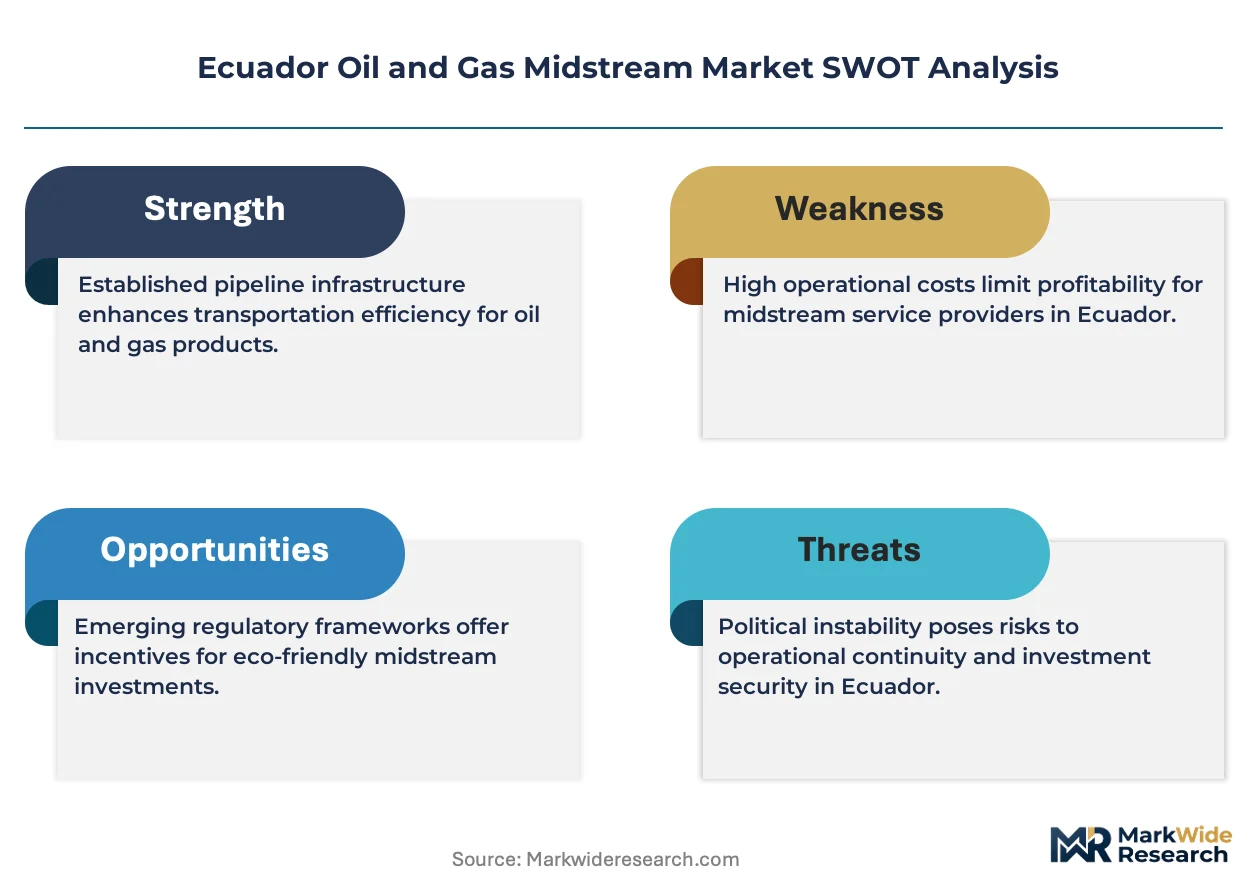
Concentration sits with state-backed pipeline operators who control trunk line infrastructure between extraction zones and coastal terminals. Private heavy-crude specialists compete through alternative export capacity that bypasses state systems. Three archetypes dominate: national oil company pipeline owners, international block operators with integrated gathering rights, and independent logistics providers with specialized treatment capacity. Competitive moves center on concession renegotiation for throughput access and downstream integration partnerships that secure offtake certainty.
Among state-affiliated operators, Petroecuador anchors infrastructure control through its ownership position in the Trans-Ecuadorian Pipeline System. OCP Ecuador occupies the private alternative export channel, demonstrating viable bypass capacity for heavy-crude flows. Repsol represents the international integrated archetype, with block partnerships feeding directly into midstream gathering systems. These three exemplify how capital allocation diverges between state-backed replacement cycles and private infrastructure development.
| Leading Market Players |
|---|
| Sycar LLC |
| Petroecuador |
| Eni SpA |
| CNPC |
| Repsol |
| OCP Ecuador |
| Occidental Petroleum Corporation |
| Petrozamora SA |
| Techint International Construction Corp |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with Esmeraldas refineries lock in throughput commitments for Petroecuador and private block operators, anchoring price visibility while constraining spot market liquidity. These term structures concentrate bargaining power with state infrastructure owners and limit price discovery for alternative export routes.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that prioritize volume certainty over spot flexibility. Price differentiation rests on crude quality grade and pipeline access tier, with heavy-crude blends from Ishpingo-Tambococha-Tiputini fields commanding treatment premiums before injection. Pricing pressure stems from environmental compliance cost escalation at watercourse crossings, compressing margins for operators without state-backed remediation reserves. State-affiliated refineries exhibit lowest price sensitivity due to strategic supply security mandates, while independent exporters face acute cost discipline.
Supply Chain Analysis
Ecuador and Colombia anchor crude gathering infrastructure, with specialized welding and coating inputs sourced from Brazilian and Mexican technical service providers. High-pressure pipeline segments at 1,440 psi operating standards draw from German and Japanese steel suppliers, while smart pigging equipment feeds from US and Canadian inspection technology vendors. Single-source vulnerability concentrates in the Trans-Ecuadorian Pipeline System's mountain crossing segments, where replacement cycles face certified technician shortages. Distribution runs through coastal maritime terminals governed by International Maritime Organization loading protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against renewable energy export corridors that redirect international offtake commitments away from fossil fuel dependency.
For Market Incumbents: Fortify pipeline integrity management programs to preempt regulatory enforcement actions from Ecuador's national environmental regulator. Secure backward integration into heavy-crude treatment capacity at Ishpingo-Tambococha-Tiputini gathering nodes. Deepen concession renegotiation capabilities to defend throughput share against OCP Ecuador's alternative export channel. For New Entrants and Emerging Players: Lead with specialized gas processing infrastructure to capture associated gas capture mandate expansion. Target NGL separation capacity in the Guayas Industrial Corridor where petrochemical demand outstrips fractionation supply. Position through joint venture structures with block operators seeking midstream integration without capital commitment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among independent logistics providers with throughput agreements on OCP Ecuador's heavy-crude pipeline. Long-term viability hinges on diversification into gas handling infrastructure as crude export volumes face energy transition headwinds. Monitor fiscal regime negotiation outcomes between the Ministry of Energy and Non-Renewable Natural Resources and private block operators as flow commitment inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Pipeline Integrity Upgrade Program | Accelerated replacement cycles comply with Ministry of Energy pressure mandates and extend asset life. |
| Heavy-Crude Treatment Capacity Expansion | Ishpingo-Tambococha-Tiputini field output requires specialized processing before Trans-Ecuadorian injection. |
| Associated Gas Capture Infrastructure | NGL separation facilities address tightening environmental regulations and feed Guayas petrochemical demand. |
| Alternative Export Route Development | OCP Ecuador's bypass capacity demonstrates viable private infrastructure outside state-controlled systems. |
| Downstream Integration Partnership | Repsol-style block-to-midstream coordination reduces handoff friction and secures offtake certainty. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pipeline operations managers, block operator logistics directors, Ministry of Energy licensing officials, Esmeraldas refinery procurement leads, and environmental compliance officers. Secondary validation drew from hydrocarbons law filings, International Maritime Organization tanker standards, national environmental regulator spill response protocols, and customs export volume records. Bottom-up field-level throughput data triangulated against top-down infrastructure capacity assessments.
Across the analysis window, the forecasting framework modeled service type segmentation alongside crude quality tiers, pipeline pressure classifications, and regulatory compliance cost trajectories. CAGRs were derived from flow volume projections weighted against replacement capital cycles and integrity management spending patterns. Inputs incorporated fiscal regime negotiation scenarios and associated gas capture mandate implementation timelines.
Forecasts assume regulatory continuity in Ecuador's hydrocarbons law and national environmental enforcement regimes; material policy shifts would require re-modeling. Specific risks include concession renegotiation outcomes that redirect flow commitments and renewable energy substitution that compress international crude offtake. Recalibration cycles align with material shifts in Ministry of Energy licensing terms and environmental regulator enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Well Test Market
Oil & Gas
Deepwater Hydrocarbons Exploration Market
Oil & Gas
Zonal Isolation Market
Oil & Gas
US Oil and Gas Analytics Market
Oil & Gas
United States Oil and Gas Pipeline Maintenance, Repair, Overhaul (MRO) Market
Oil & Gas
Asia Pacific Upstream Oil and Gas Services Market
Oil & Gas
Norway Oilfield Equipment Rental Services Market
Oil & Gas
Drill Collar Market
Oil & Gas
Leak Detection for Oil & Gas Market
Oil & Gas
Fracking Fluid Market
Oil & Gas
Thailand Oil and Gas Market
Oil & Gas
Proppant Market
Oil & Gas
Oilwell Completion Tools Market
Oil & Gas
Underreamers Market
Oil & Gas
Italy Oil and Gas Upstream Market
Oil & Gas
Nigeria Upstream Oil Sector Market