
 Hydraulic Fracturing Market | 2026-2036
Hydraulic Fracturing Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Fracturing Market Analysis
Proppant-grade ceramic is expanding its share in high-closure-stress environments, displacing raw frac sand in deeper Permian and Eagle Ford wells where crush resistance determines EUR outcomes. Halliburton leverages in-house resin-coating capabilities to command premium pricing on northern White Sand alternatives. Baker Hughes sustains technology leadership through its adaptive drill-bit and frac fleet integration, while Liberty Oilfield Services LLC anchors its position with the largest pure-play pressure pumping fleet in North America.
Hydraulic fracturing is the engineered injection of pressurized fluid—typically water mixed with proppant and chemical additives at rates exceeding 100 barrels per minute—to create and propagate fractures in low-permeability subsurface formations, thereby enhancing hydrocarbon flow to the wellbore. Pressure pumping dominates service revenue as the most capital-intensive and labor-heavy segment, while wireline services and coiled tubing capture faster growth through their role in multi-well pad efficiency and re-fracturing campaigns. Slick water formulations lead volume in shale gas applications due to lower cost per stage, though gelled systems retain margin concentration in complex carbonate and tight oil completions where viscosity control proves critical.
The US EPA regulates underground injection through UIC Class II permits and enforces methane standards under Clean Air Act Section 111(b), while OSHA sets exposure limits for respirable crystalline silica during proppant handling. State regulators in Texas and New Mexico overlay additional chemical disclosure and water sourcing requirements that shape operational planning. Stakeholders must monitor how evolving federal methane fees and state groundwater protection rules alter the economics of completion design and fluid selection.
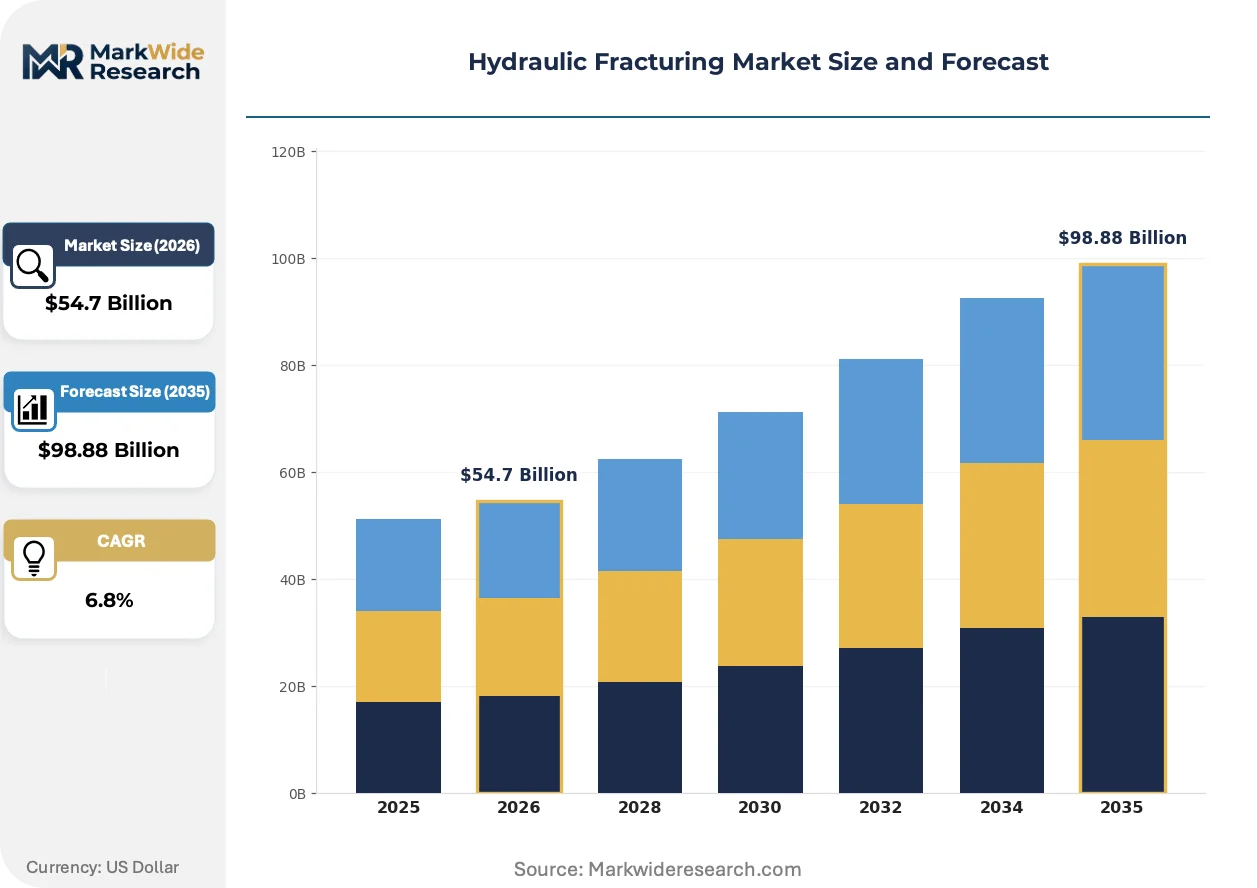
Market Dynamics
Longer lateral sections and higher stage counts in Permian Basin completions are compressing cycle times while amplifying proppant intensity per well, forcing service providers to reconfigure fleet logistics and chemical supply chains around continuous batch operations.
Growth Catalysts
- US EPA methane standards:Operators retrofitting gas capture systems on older Delaware Basin pads unlock incremental production volumes that justify re-fracturing campaigns on legacy horizontals.
- Resin-coated proppant:Northern White Sand alternatives with in-house coating capabilities command pricing premiums in high-closure-stress environments where crush resistance determines EUR outcomes.
- Pad development density:Multi-well pad efficiency gains in West Texas sustain drilling intensity despite volatile commodity price environments.
Market Restraints
- Proppant supply concentration:Wisconsin and Minnesota mines control premium Northern White Sand volumes, exposing operators to rail logistics bottlenecks and weather-related delivery disruptions.
- Water sourcing constraints:State-level groundwater protection rules in Texas and New Mexico restrict freshwater withdrawal volumes, forcing costly recycling infrastructure investments.
- Silica exposure liability:OSHA respirable crystalline silica limits during proppant handling impose PPE mandates and medical monitoring costs that erode field-level margins.
Strategic Opportunities
- Re-fracturing technology:Mature shale basins in the Eagle Ford and Bakken contain thousands of underperforming horizontals amenable to second-generation diversion techniques.
- Closed-loop water systems:Regulatory tailwinds from New Mexico's produced water recycling mandates create captive demand for mobile treatment units.
- Electric frac fleets:Dual-fuel and grid-tied pressure pumping equipment converges with utility-scale solar installations to reduce diesel consumption and emissions profiles.
Industry Challenges
- Specialized pressure pumping labor:Experienced pump operators and maintenance technicians command wage premiums that compress service company margins during oversupply cycles.
- UIC Class II permitting timelines:Underground injection control approval delays for saltwater disposal wells extend completion-to-production intervals and strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Fracturing Market |
| Market Size in 2026 | $54.7 Billion |
| Market Size in 2035 | $98.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pressure Pumping, Well Cleaning, Wireline Services, Coiled Tubing Technology: Water-based, Foamed, Slick Water, Gelled Application: Shale Gas, Tight Gas, Coal Bed Methane, Oil Sands End User: Independent Operators, National Oil Companies, Oilfield Service Companies, Majors |
| Companies Covered | Halliburton, Schlumberger, Liberty Oilfield Services LLC, Baker Hughes, NexTier Oilfield Solutions, Calfrac Well Services Ltd., ProFrac Holding Corp., Patterson-UTI Energy, Inc., Weatherford, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Fracturing Market Emerging Trajectories
Digital frac fleet management and real-time pressure monitoring are compressing operational variability while enabling remote supervision of multi-pad campaigns across dispersed acreage positions.
Electric-powered pressure pumping equipment is decentralizing fleet deployment patterns by reducing noise restrictions and emissions compliance burdens that previously limited operations near populated areas. Permian operators with proximity to transmission infrastructure are adopting grid-tied or dual-fuel systems at accelerating rates. This technology is decentralizing the geographic radius of acceptable wellsite locations and expanding accessible inventory in the Midland Basin's western periphery.
The US EPA's updated methane emissions rules under Clean Air Act Section 111(b) mandate continuous monitoring and repair protocols for pneumatic controllers and storage vessels. Completion crews now integrate optical gas imaging surveys into post-frac flowback procedures. Pressure pumping providers serving Delaware Basin operators face the steepest compliance cost escalations as venting restrictions tighten on high-gas-oil-ratio wells.
Integrated service contracts bundling pressure pumping, wireline, and coiled tubing are displacing single-service awards as operators prioritize single-point accountability for multi-well pad economics. Large independents in the Permian are consolidating vendor rosters to three or fewer integrated providers. This procurement consolidation is most visible among Permian Basin operators with contiguous acreage blocks exceeding 50,000 net acres.
Hydraulic Fracturing Market Segmentation
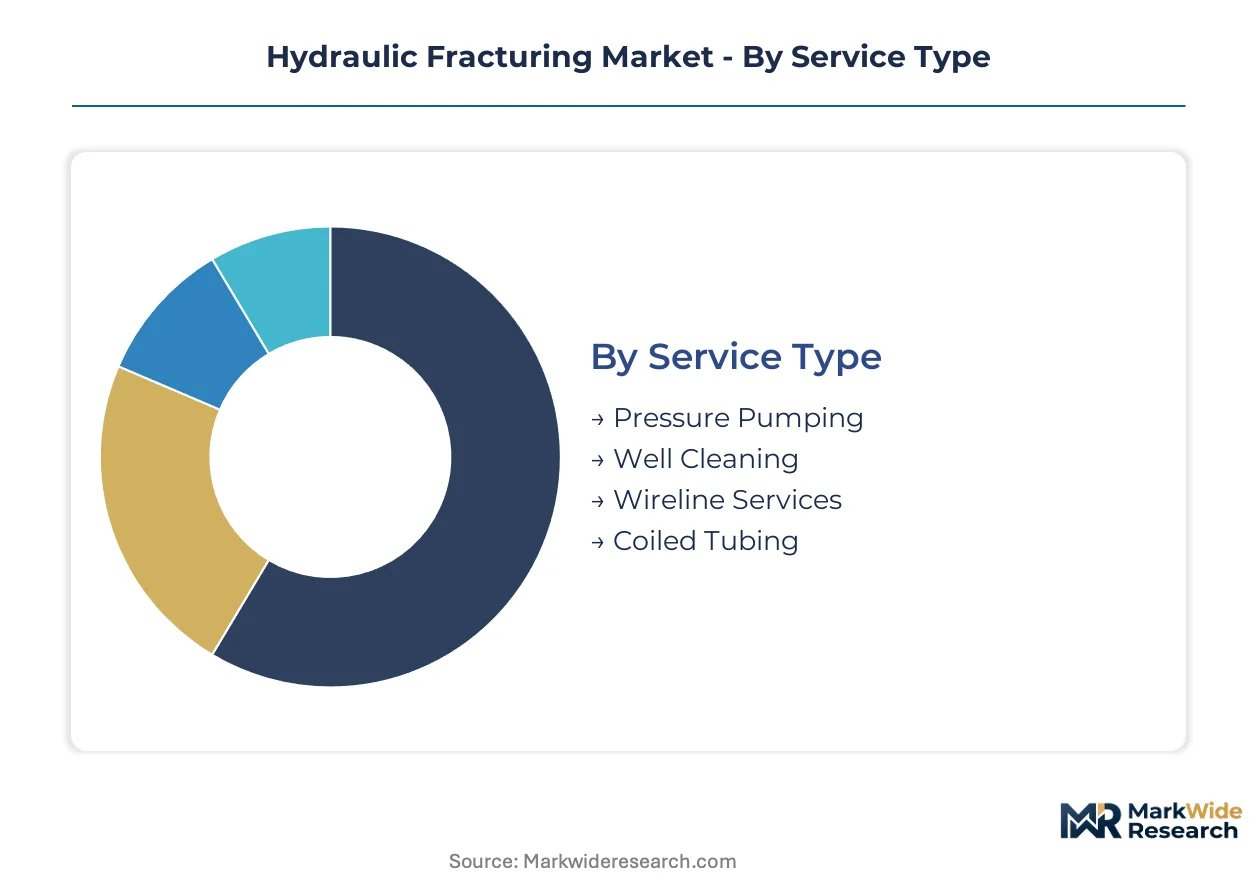
Service mix and fluid technology choices in hydraulic fracturing determine capital intensity, labor deployment, and regulatory exposure across basins. Completion economics hinge on matching service configuration to formation permeability and stress profiles.
Service Type:
Capital deployment and crew density drive operator selection among service tiers, with pad-scale efficiency favoring bundled awards over discrete procurement.
- Pressure Pumping:High-horsepower fleet operations inject proppant-laden fluid at rates exceeding 100 barrels per minute. Permian Basin operators with contiguous acreage above 50,000 net acres concentrate demand here, prioritizing continuous batch logistics over spot market flexibility.
- Well Cleaning:Post-frac flowback and wellbore debris removal services reduce non-productive time between completion and production. Eagle Ford independents deploy these services intensively where gas-oil ratios complicate initial production.
- Wireline Services:Perforating and diagnostic packages enable multi-well pad efficiency through simultaneous operations.
- Coiled Tubing:Re-fracturing campaigns and plug drillouts in mature shale basins sustain fleet utilization.
Pressure Pumping leads on scale; Coiled Tubing leads on momentum.
Technology:
Fluid rheology and chemistry selection trade off cost per stage against conductivity outcomes in varying closure-stress regimes.
- Slick Water:Low-viscosity water formulations with friction reducers dominate Marcellus and Haynesville shale gas applications. Operators favor this technology where fracture complexity and proppant transport distance outweigh conductivity optimization.
- Gelled:Cross-linked polymer systems maintain viscosity for proppant suspension in high-temperature carbonate formations. Permian Delaware Basin completions with closure stresses above 8,000 psi require these formulations to prevent screenouts.
- Water-based:Baseline fracturing fluids without foam or gel additives serve conventional tight gas reservoirs.
- Foamed:Nitrogen or carbon dioxide energized systems reduce water intensity in water-constrained jurisdictions.
Slick Water commands volume share; Gelled captures margin concentration.
Application:
Formation type dictates lateral design, stage spacing, and proppant intensity, creating distinct service procurement patterns by reservoir geology.
- Shale Gas:Ultra-low permeability mudstone formations in Appalachia and Louisiana require high-stage-count completions with engineered proppant ramps. EPA methane monitoring mandates under Clean Air Act Section 111(b) reshape flowback protocols in these gas-weighted basins.
- Tight Gas:Low-permeability sandstone reservoirs in the Rocky Mountain region sustain steady demand for gelled fluid systems.
- Coal Bed Methane:Shallow dewatering-dependent production in the Powder River Basin employs reduced-pressure fracturing techniques.
- Oil Sands:Steam-assisted gravity drainage and cyclic steam stimulation in Alberta require specialized thermal fracturing approaches distinct from unconventional shale methods.
Shale Gas anchors service revenue; Tight Gas maintains stable replacement demand.
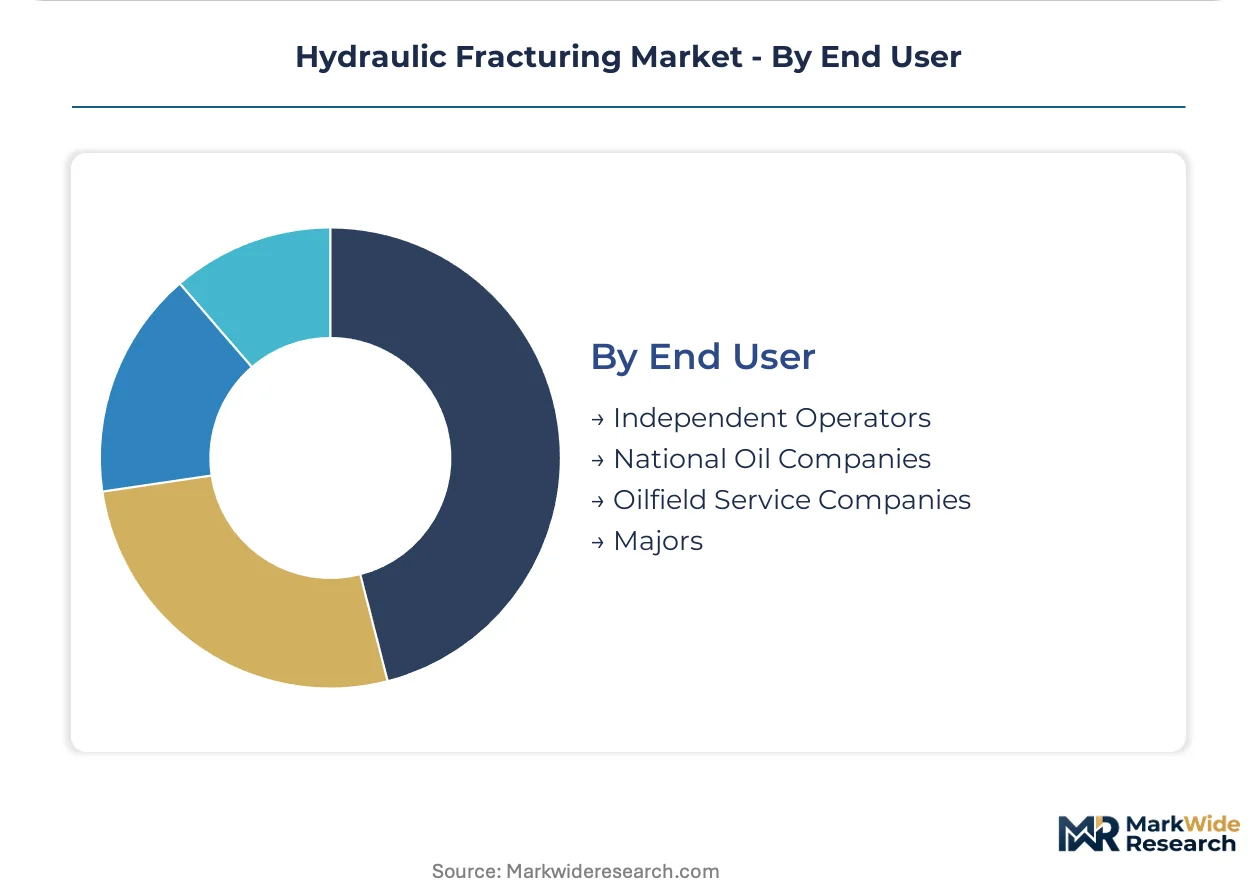
End User:
Balance sheet capacity and vertical integration depth determine procurement sophistication and contract tenure preferences across operator categories.
- Majors:Integrated supermajors with Permian and Eagle Ford positions leverage long-term integrated service agreements bundling pressure pumping, wireline, and coiled tubing. These operators consolidate vendor rosters to three or fewer providers to enforce single-point accountability on multi-well pad economics.
- Independent Operators:Privately held and publicly traded E&Ps without downstream assets prioritize spot market flexibility and stage-by-stage pricing. West Texas independents with sub-10,000 net acre positions drive fragmentation in service procurement.
- National Oil Companies:State-backed operators in Argentina and China deploy fracturing technology through technology transfer agreements with North American service providers.
- Oilfield Service Companies:Tier-2 and tier-3 pressure pumping specialists subcontract specialized wireline or coiled tubing capacity during demand surges.
Majors concentrate contract value; Independent Operators generate transaction velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin of West Texas and southeastern New Mexico anchors hydraulic fracturing service demand through pad development density and infrastructure access that sustains drilling intensity despite commodity volatility.
United States
Longer laterals and higher stage counts in Delaware Basin completions compress cycle times while amplifying proppant intensity per well. EPA methane standards under Clean Air Act Section 111(b) mandate continuous monitoring protocols for pneumatic controllers and storage vessels. Midland Basin operators with proximity to transmission infrastructure adopt grid-tied electric frac fleets at accelerating rates.
Canada
Thermal fracturing approaches for Alberta oil sands sustain specialized service demand distinct from unconventional shale methods. Health Canada and provincial regulators enforce produced water management standards that shape recycling infrastructure investments. Calgary-based operators concentrate procurement for Montney tight gas completions where gelled fluid systems retain margin concentration.
Argentina
Vaca Muerta shale development drives technology transfer agreements with North American service providers for pressure pumping capacity expansion. The national hydrocarbons regulator enforces chemical disclosure mandates that reshape completion fluid formulations. Neuquén Basin operators deploy imported proppant volumes through Bahía Blanca port infrastructure.
China
Sichuan Basin shale gas extraction absorbs domestic pressure pumping fleet expansion backed by state capital deployment. MEE methane monitoring requirements and provincial groundwater protection rules alter completion economics. Chongqing metropolitan area anchors service company regional headquarters for Fuling shale play operations.
Saudi Arabia
Tight gas and unconventional reservoir development in the Jafurah Basin drives imported fracturing technology deployment through Aramco vendor qualification programs. The national oil company mandates local content requirements that reshape supply chain configurations. Eastern Province industrial cities concentrate proppant import terminals and chemical blending facilities.
Hydraulic Fracturing Market Vendor Landscape
Global majors compete with regional champions across pressure pumping fleet scale and integrated service bundling. The vendor base concentrates around three tiers: full-service conglomerates with proprietary technology stacks, pure-play pressure pumping specialists with fleet density advantages, and regional contractors capturing spot market fragmentation. Strategic archetypes include integrated technology providers commanding premium pricing through in-house manufacturing capabilities, fleet-heavy specialists anchoring market share through continuous batch logistics, and nimble independents exploiting stage-by-stage pricing flexibility. Dominant competitive moves encompass vendor roster consolidation by large independents and electric fleet differentiation to capture emissions-compliant contract awards.
Among North American service conglomerates, Halliburton and Baker Hughes exemplify integrated technology providers with captive supply chains for proppant coating and adaptive drill-bit systems. Liberty Oilfield Services LLC occupies a position as the largest pure-play pressure pumping fleet operator in the region, representing the specialist archetype that anchors market presence through labor-intensive horsepower deployment rather than diversified service portfolios.
| Leading Market Players |
|---|
| Halliburton |
| Schlumberger |
| Liberty Oilfield Services LLC |
| Baker Hughes |
| NexTier Oilfield Solutions |
| Calfrac Well Services Ltd. |
| ProFrac Holding Corp. |
| Patterson-UTI Energy, Inc. |
| Weatherford |
| Others |
Supply Flow & Price Mechanics
Captive in-house resin-coating capabilities at Halliburton and Baker Hughes anchor premium pricing power on Northern White Sand alternatives, insulating integrated providers from raw frac sand spot volatility while forcing pure-play pressure pumpers toward volume-based contract structures.
Pricing Analysis
Input-cost pass-through from Wisconsin and Minnesota Northern White Sand mining operations drives contract renegotiation cycles, with rail freight surcharges and weather-related delivery premiums flowing directly to Permian Basin operators. Pricing stratifies across resin-coated ceramic, in-house coated sand, and uncoated raw sand tiers based on crush resistance certification and closure-stress performance grade. Cost compression in standard-grade proppant is intensifying because of oversupply in Permian logistics corridors, while premium-coated alternatives retain margin stability. Independent operators with sub-10,000 net acre positions exhibit highest price sensitivity, demanding stage-by-stage spot flexibility; majors with contiguous 50,000+ net acre blocks accept long-term integrated premiums for single-point accountability.
Supply Chain Analysis
Proppant supply rests on Wisconsin and Minnesota mining concentration for premium Northern White Sand, Chinese ceramic manufacturing for high-stress applications, and regional Texas in-basin sand mining for cost-sensitive Permian operations. Key inputs include resin coating chemicals, high-purity silica feedstock, and specialized railcar fleets for bulk transport. Single-source vulnerability concentrates around the BNSF and Union Pacific rail corridors serving West Texas, where weather disruptions and crew shortages cascade into completion delays. Distribution runs through direct mine-to-wellsite rail spurs for integrated operators, while spot-market buyers depend on transload terminals and third-party logistics brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydraulic fracturing service demand compounds steadily as unconventional shale extraction in North American basins sustains drilling intensity through commodity cycles, with EPA methane regulations and state chemical disclosure mandates creating durable compliance spending that locks in integrated provider relationships.
For Market Incumbents: Cement market position by accelerating electric frac fleet deployment to capture emissions-compliant contract awards from Delaware Basin operators facing steep venting restrictions, and deepen backward integration into resin-coating chemistry to defend margin against raw sand price erosion. The threat of regulatory compliance cost escalation favors providers with captive manufacturing capabilities over pure-play pumpers dependent on spot procurement. For New Entrants and Emerging Players: Mobile water treatment unit providers represent the most penetrable channel partner type for entering the New Mexico produced water recycling mandate environment, with regulatory tailwinds creating captive demand from operators constrained by groundwater withdrawal limits. Target closed-loop water system partnerships with Permian independents lacking capital for fixed recycling infrastructure. White-space exists in re-fracturing technology services for Eagle Ford and Bakken underperforming horizontals using second-generation diversion techniques. For Investors and Strategic Acquirers: Consolidation pressure builds where pure-play pressure pumping specialists face margin compression from electric fleet capital requirements and silica exposure liability costs. The market exhibits long-term viability as a compounder through regulatory-driven service intensity and pad development density sustaining completion volumes. Acquisition target archetype: regional pressure pumpers with 50,000+ horsepower and established rail spur access in Permian or Eagle Ford corridors. Watch EPA methane fee escalation and state UIC Class II permitting timelines as inflection indicators for working capital stress and vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion | Grid-tied pressure pumping equipment reduces diesel consumption and expands operable inventory near populated areas. |
| Resin-Coating Capacity Expansion | In-house Northern White Sand alternatives command premium pricing in high-closure-stress Delaware Basin completions. |
| Closed-Loop Water System Deployment | Mobile treatment units capture regulatory-mandated demand from New Mexico groundwater protection rules. |
| Re-Fracturing Technology Development | Second-generation diversion techniques unlock underperforming Eagle Ford and Bakken legacy horizontals. |
| Integrated Service Contract Bundling | Single-point accountability for pressure pumping, wireline, and coiled tubing displaces discrete procurement among large independents. |
Methodological Framework
Direct dialogue with pressure pumping fleet managers, Permian Basin drilling engineers, EPA regulatory compliance officers, proppant procurement leads at major independents, and wireline service supervisors grounded qualitative findings, validated against EIA drilling productivity reports, EPA enforcement and compliance databases, FERC infrastructure filings, and state regulatory chemical disclosure records. Bottom-up well count and stage intensity estimates triangulated against top-down service revenue segmentation.
Model outputs span service type, fluid technology, application geology, and operator category dimensions across the projection horizon. CAGRs derived from basin-level drilling intensity forecasts, proppant consumption per well trajectories, and regulatory compliance cost escalation curves. Industry-specific inputs include lateral length extension rates, stage count compression timelines, and electric fleet adoption slopes tied to transmission infrastructure proximity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to commodity price volatility, federal methane fee implementation, and state groundwater withdrawal restriction tightening. Forecasts reflect documented assumptions on pad development density, fleet utilization rates, and proppant supply chain configuration. Material deviation in EPA enforcement intensity or Permian rail logistics capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Asia-Pacific Liner Hanger System Market
Oil & Gas
Small Scale LNG (SSLNG) Market
Oil & Gas
Dry Natural Gas Market
Oil & Gas
Nigeria Oil and Gas Market
Oil & Gas
Small Scale LNG Terminal Market
Oil & Gas
Europe Oil and Gas Electric Submersible Pump Market
Oil & Gas
Modular Refinery Market
Oil & Gas
Oil and Gas Cloud Applications Market
Oil & Gas
Crude Oil Desalter and Electrostatic Dehydrator Market
Oil & Gas
Riserless Light Well Intervention Market
Oil & Gas
Central Asia Oil and Gas Midstream Market
Oil & Gas
Brazil Wireline Logging Services Market
Oil & Gas
Slickline Services Market
Oil & Gas
Asia-Pacific Oil Country Tubular Goods Market
Oil & Gas
Well Stimulation Vessels Market
Oil & Gas
Exploration and Drilling Security Market