
 India AI in Oil and Gas Market | 2026-2036
India AI in Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
India AI in Oil and Gas Market Insights
India's net-zero commitments under its updated Nationally Determined Contributions is consolidating procurement priorities across the oil and gas value chain. Reliance Industries leverages deep digital infrastructure across its Jamnagar refining complex to anchor operational efficiency gains. ONGC competes through indigenous AI deployment across Mumbai High offshore assets, while Detect Technologies specializes in computer-vision pipeline monitoring systems for hazardous environments.
India AI in Oil and Gas encompasses machine learning algorithms, natural language processing engines, and computer vision systems applied to hydrocarbon exploration, production, and refining workflows. These technologies process seismic datasets, optimize drilling parameters, and predict equipment failures across temperatures exceeding 150°C and pressures above 10,000 psi. Predictive maintenance applications currently capture the deepest margin pools as operators prioritize asset uptime over exploration spending. Machine learning technology leads deployment volumes, though computer vision is recording the fastest adoption curve across pipeline integrity management. Downstream refineries represent the most mature end-user segment, while upstream operators present the largest untapped addressable base for managed services contracts.
The Petroleum and Natural Gas Regulatory Board mandates digital infrastructure standards for city gas distribution networks, while BIS certification requirements govern AI system reliability classifications for hazardous area deployments. CEA guidelines on critical energy infrastructure cybersecurity further shape vendor qualification protocols and data governance architectures. Stakeholders must monitor evolving PLI scheme eligibility for domestic AI hardware manufacturing, as localization requirements will reshape total cost of ownership calculations and partnership structures.
Market Dynamics
The Petroleum and Natural Gas Regulatory Board's digital infrastructure mandate is compressing deployment timelines across city gas distribution networks, forcing operators to accelerate AI procurement cycles and requalify vendor ecosystems under tighter certification windows.
Growth Catalysts
- Upstream Predictive Maintenance:Operators across Gujarat's refining corridor prioritize asset uptime algorithms over exploration capital, pulling machine learning deployment into hazardous environments. BIS certification for hazardous area equipment creates procurement clarity.
- CEA Cybersecurity Directives:Critical energy infrastructure guidelines reshape data governance architectures, mandating domestic data residency and encrypted transmission protocols for SCADA-integrated AI systems.
- Offshore Seismic Processing:Mumbai High cluster operators deploy neural networks to compress interpretation cycles for complex carbonate reservoirs, reducing dry-hole risk in high-pressure formations.
Market Restraints
- GPU Hardware Import Dependency:Training-grade semiconductor supply concentrates through US and Taiwan fabrication channels, exposing operators to DGFT licensing delays and foreign exchange volatility.
- Legacy System Integration Friction:Decades-old DCS architectures in Jamnagar-scale refineries resist API standardization, forcing middleware-heavy deployment models that inflate total cost of ownership.
- Subsurface Data Silos:ONGC and private operators hoard proprietary seismic and well-log datasets, starving algorithm training pipelines of volume diversity needed for generalized models.
Strategic Opportunities
- PLI Scheme Localization:Domestic AI hardware manufacturing incentives under the Production Linked Incentive scheme reshape partnership structures, favoring joint ventures with Indian semiconductor packagers over pure imports.
- Pipeline Integrity Convergence:Computer vision systems merge with drone-mounted thermal sensors and fiber-optic acoustic monitoring, creating multi-modal leak detection networks for the 33,000 km trunk line network.
- Kochi-Visakhapatnam Industrial Corridor:Greenfield petrochemical complexes in Andhra Pradesh and Kerala present untapped addressable bases for integrated AI deployment without legacy system drag.
Industry Challenges
- Petroleum Data Science Talent Scarcity:Reservoir engineering expertise rarely overlaps with machine learning competency, forcing operators to either import expensive hybrid profiles or accept slower model iteration cycles.
- Hazardous Area Certification Timelines:BIS reliability classifications for Zone 0 and Zone 1 deployments require 18-24 month validation windows, compressing competitive advantage windows for first movers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India AI in Oil and Gas Market |
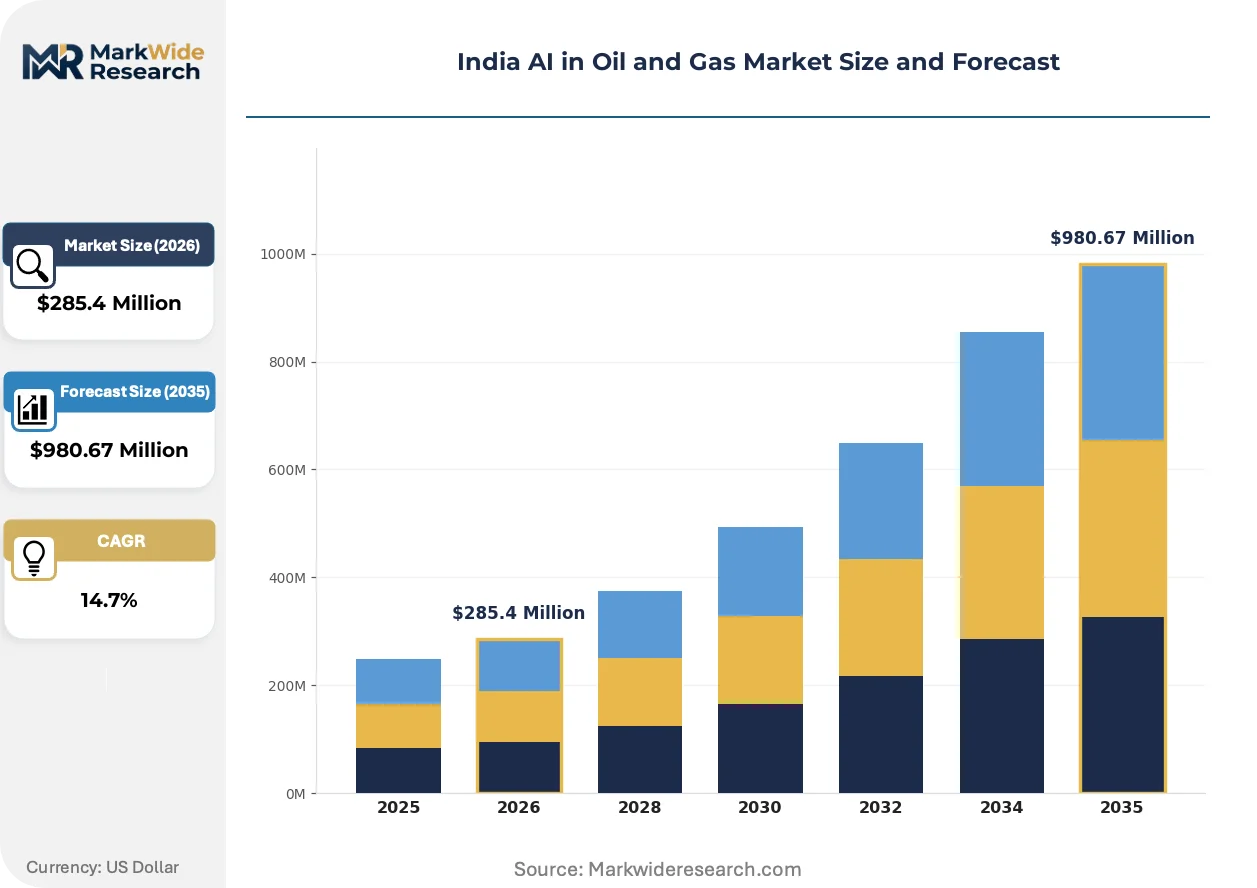
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $980.67 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Exploration, Production Optimization, Reservoir Management, Predictive Maintenance Technology: Machine Learning, Natural Language Processing, Computer Vision, Data Analytics Service Type: Consulting, System Integration, Managed Services, Support Services End User: Upstream Operators, Midstream Companies, Downstream Refineries, Service Providers |
| Companies Covered | PRAYOG, Petronet LNG, Detect Technologies, Reliance Industries, ONGC, Planys Technologies, OligoQHSE, Indian Oil Corporation, Visage Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India AI in Oil and Gas Market Trends and Innovations
Digital twin architectures are displacing static simulation models across the hydrocarbon value chain, compressing the gap between physical asset behavior and predictive algorithm training data.
Edge computing platforms are unifying real-time inference capabilities with subsurface sensor networks, eliminating latency bottlenecks that previously forced data transmission to centralized cloud infrastructure. ONGC's Mumbai High assets deploy these systems for immediate drilling parameter optimization. The structural consequence is collapsing the feedback loop between downhole measurement and surface decision-making from hours to seconds.
Petroleum and Natural Gas Regulatory Board mandates on city gas distribution telemetry standards are forcing uniform API specifications across 300+ licensed entities. Industrial consequence includes accelerated vendor consolidation as smaller operators cannot absorb compliance engineering costs. The most affected segment is compressed natural gas retail networks, which are re-tendering SCADA contracts to include AI-ready data architectures.
Buying patterns among downstream refiners are rotating toward managed service contracts with uptime guarantees rather than perpetual software licenses. Reliance Industries and public sector refiners now demand outcome-based pricing tied to energy efficiency deltas or unplanned outage reduction. This shift is most visible in Jamnagar-scale complexes where operational technology budgets exceed information technology spending by three-to-one ratios.
India AI in Oil and Gas Market Segmentation
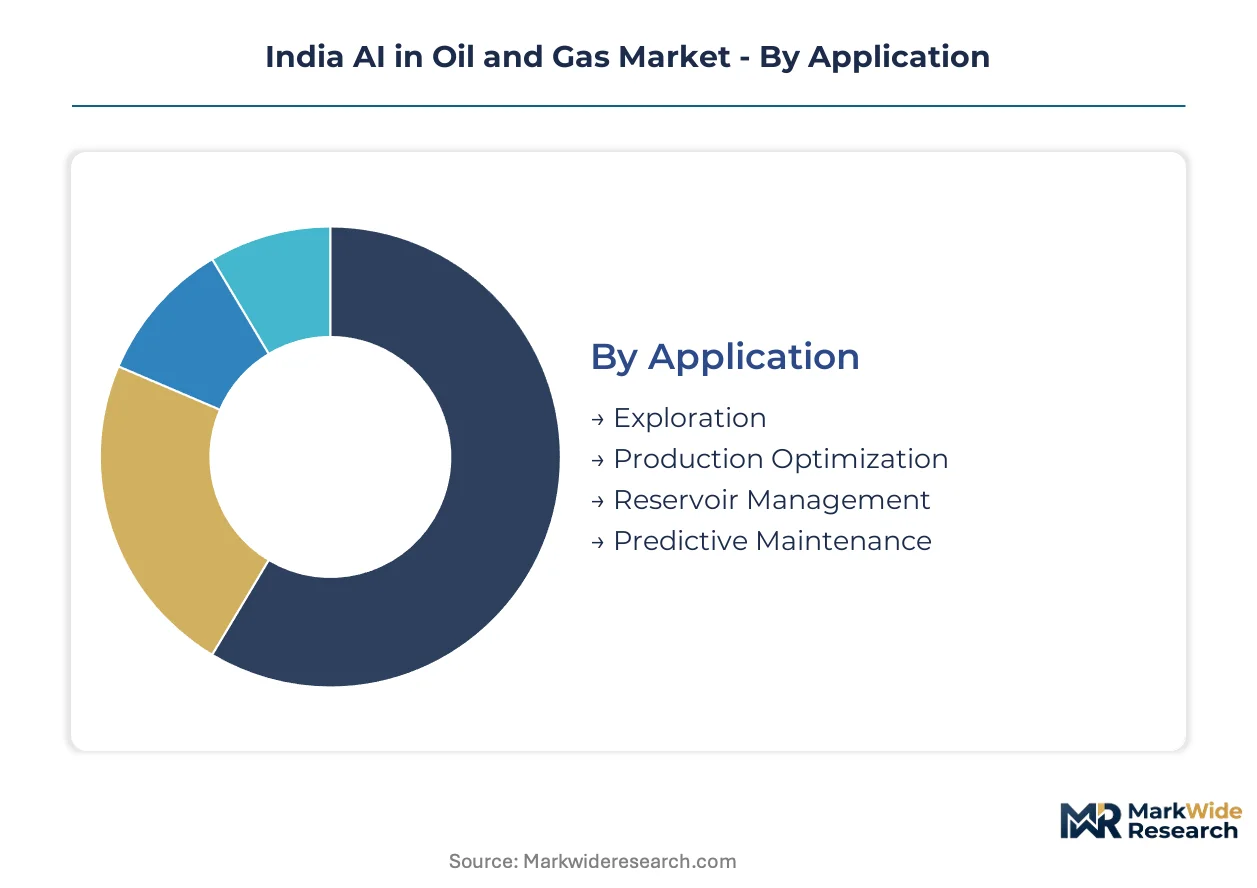
Segmentation in India's AI oil and gas market reveals where capital deployment concentrates and which technology configurations match specific operational constraints. Understanding these splits helps vendors align pricing models with customer readiness and regulatory exposure.
Application:
Capital intensity varies sharply across deployment scenarios, with subsurface applications demanding the heaviest upfront sensor infrastructure and edge computing investment.
- Predictive Maintenance:Algorithms monitor vibration signatures, thermal patterns, and lubricant degradation across rotating equipment operating above 150°C. Demand clusters in Gujarat's refining corridor where Reliance Industries and public sector refiners prioritize asset uptime over exploration spending, driven by BIS hazardous area certification requirements that favor proven vendors.
- Production Optimization:Real-time drilling parameter adjustment systems process downhole measurements at Mumbai High offshore assets. ONGC deploys these to compress feedback loops between subsurface conditions and surface decisions, constrained by legacy DCS integration friction in decades-old platforms.
- Exploration:Neural networks interpret seismic datasets for carbonate reservoir characterization, reducing dry-hole risk in high-pressure formations.
- Reservoir Management:Simulation models integrate historical production data with real-time well performance metrics for decline curve analysis.
Predictive Maintenance absorbs the bulk of installed capacity; Production Optimization is expanding most quickly.
Technology:
Technology selection tracks the maturity gradient from statistical modeling to perception systems, with deployment complexity rising alongside data heterogeneity.
- Machine Learning:Supervised and unsupervised algorithms dominate deployment volumes across the value chain, processing structured time-series data from SCADA historians and process control systems. The technology anchors most managed services contracts in downstream refineries where outcome-based pricing ties fees to efficiency deltas.
- Computer Vision:Pipeline integrity monitoring systems merge drone-mounted thermal sensors with fiber-optic acoustic arrays for leak detection across the 33,000 km trunk line network. Adoption accelerates fastest where Petroleum and Natural Gas Regulatory Board mandates compress procurement timelines for city gas distribution networks.
- Natural Language Processing:Document intelligence engines extract technical specifications from decades of drilling reports and equipment manuals.
- Data Analytics:Descriptive and diagnostic platforms aggregate operational metrics for dashboard visualization and exception reporting.
Machine Learning captures the deepest margin pools through recurring managed services; Computer Vision climbs the fastest as multi-modal sensor fusion matures.
Service Type:
Customer procurement patterns rotate from perpetual licenses toward risk-transfer arrangements, reshaping vendor revenue recognition and working capital requirements.
- Managed Services:Outcome-based contracts with uptime guarantees now dominate downstream refinery spending, particularly in Jamnagar-scale complexes where operational technology budgets exceed information technology by three-to-one ratios. Vendors absorb integration risk and hardware refresh cycles in exchange for recurring revenue streams.
- System Integration:Middleware-heavy deployment models address legacy DCS architectures that resist API standardization, inflating total cost of ownership but enabling phased modernization without production shutdowns.
- Consulting:Reservoir engineering and machine learning hybrid expertise commands premium pricing given talent scarcity at the petroleum data science intersection.
- Support Services:Post-deployment maintenance, model retraining, and regulatory compliance updates sustain long-term vendor relationships.
Managed Services represents the dominant revenue configuration; System Integration carries the highest project complexity and margin risk.
End User:
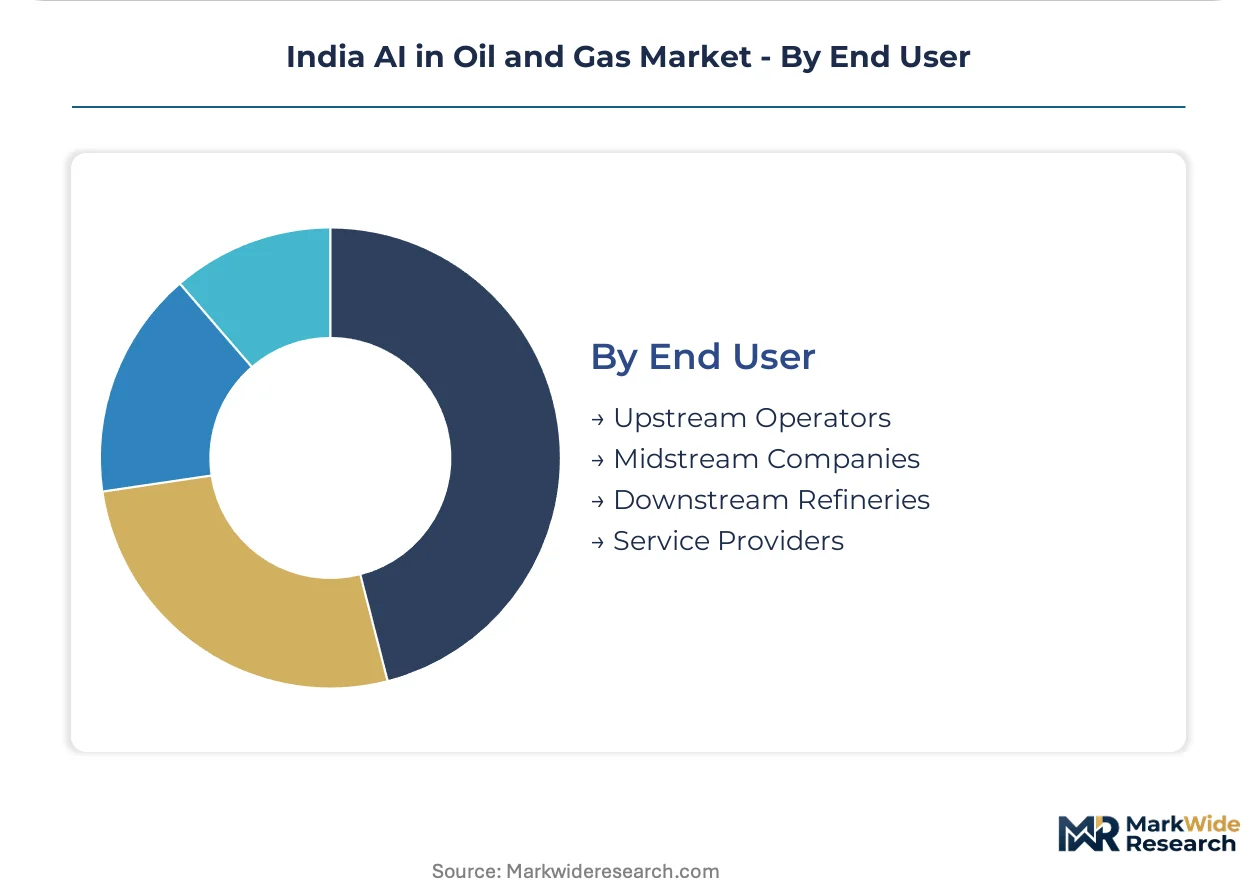
Buyer sophistication and procurement authority diverge across the value chain, with integrated operators exercising greater control over data governance architectures than fragmented service tiers.
- Downstream Refineries:The most mature end-user segment with established digital infrastructure, standardized telemetry protocols, and procurement processes accustomed to enterprise software contracts. Reliance Industries anchors demand through deep digital deployment across the Jamnagar complex.
- Upstream Operators:The largest untapped addressable base for managed services contracts, constrained by subsurface data silos where ONGC and private operators hoard proprietary seismic datasets that starve algorithm training pipelines.
- Midstream Companies:Pipeline operators face Petroleum and Natural Gas Regulatory Board digital infrastructure mandates that force accelerated AI procurement cycles and vendor requalification.
- Service Providers:Drilling contractors and equipment lessors adopt AI for fleet optimization and predictive maintenance of rented assets.
Downstream Refineries command the deepest technology penetration; Upstream Operators present the steepest expansion trajectory as offshore production economics tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India produces roughly 600,000 barrels of crude oil daily while consuming over 5 million barrels, creating a structural import dependency that intensifies operational efficiency imperatives across domestic extraction and refining assets.
Gujarat
Reliance Industries operates the Jamnagar refining complex, deploying deep digital infrastructure for operational efficiency gains. The Petroleum and Natural Gas Regulatory Board mandates digital infrastructure standards for city gas distribution networks, compressing procurement timelines. The refining corridor concentrates predictive maintenance algorithm deployment across hazardous environments operating above 150°C.
Maharashtra
ONGC manages Mumbai High offshore assets through indigenous AI deployment for real-time drilling parameter optimization. CEA cybersecurity directives mandate domestic data residency and encrypted transmission protocols for SCADA-integrated systems. The Mumbai offshore production cluster compresses feedback loops between subsurface conditions and surface decisions through edge computing platforms.
Andhra Pradesh
Greenfield petrochemical complexes in the Kochi-Visakhapatnam Industrial Corridor present untapped addressable bases for integrated AI deployment. PLI scheme incentives for domestic AI hardware manufacturing reshape partnership structures, favoring joint ventures with Indian semiconductor packagers. The corridor avoids legacy system drag that inflates total cost of ownership in older facilities.
Kerala
Specialized pipeline integrity monitoring demand concentrates along coastal refining infrastructure and import terminal networks. BIS certification requirements for hazardous area equipment create procurement clarity for Zone 0 and Zone 1 deployments. Computer vision systems merge with drone-mounted thermal sensors for multi-modal leak detection across concentrated industrial zones.
Tamil Nadu
Manali and Ennore industrial belts anchor downstream refining technology adoption with established digital infrastructure. DGFT licensing delays for training-grade GPU hardware expose operators to foreign exchange volatility and supply concentration risks. The region's procurement patterns rotate toward managed service contracts with uptime guarantees rather than perpetual software licenses.
India AI in Oil and Gas Market Competitive Landscape
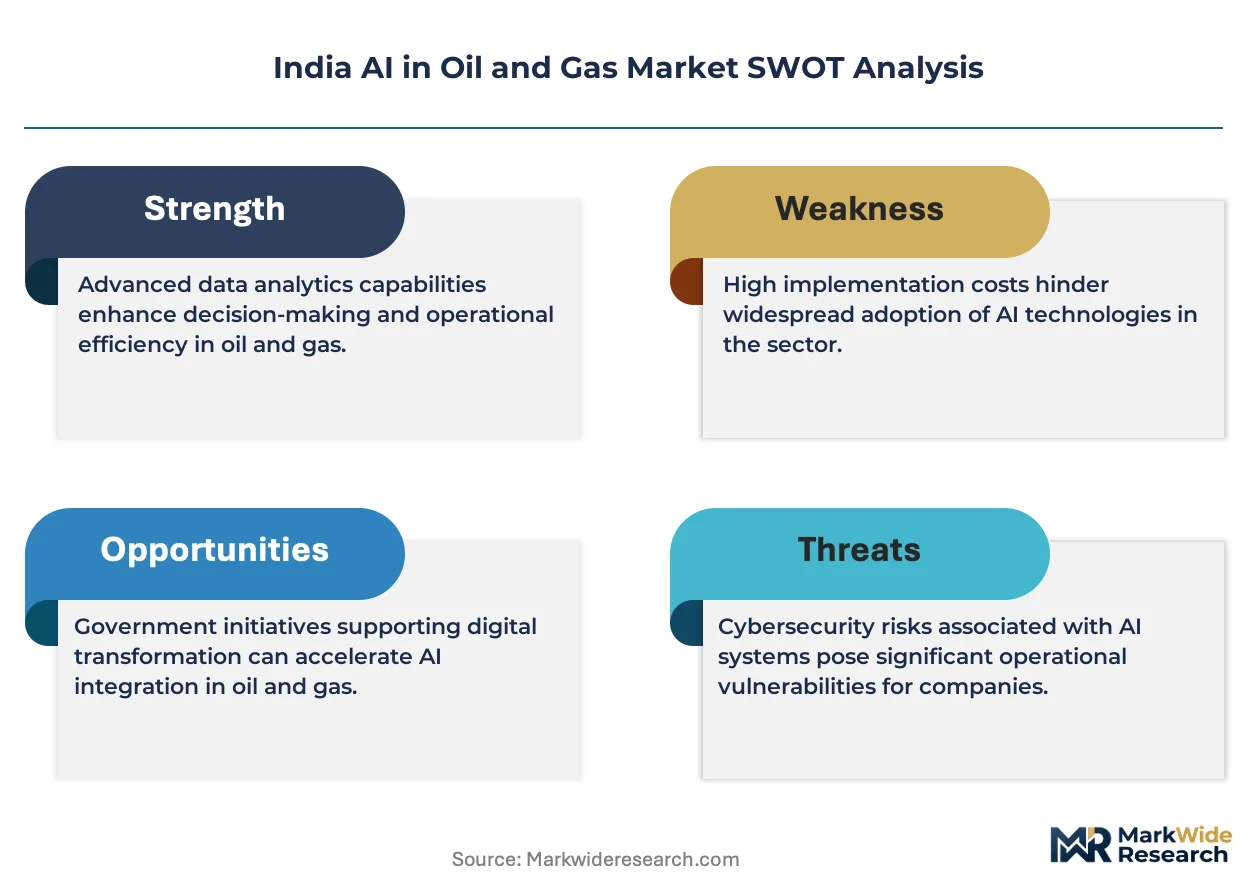
The competitive structure tilts toward integrated energy conglomerates with captive digital deployment capabilities. Domestic technology specialists and public sector upstream operators occupy distinct tier positions based on data asset control and hazardous area certification timelines. Strategic archetypes include refining-anchored digital integrators, offshore-focused indigenous deployers, and computer-vision pipeline specialists. Competitive moves concentrate on vendor requalification under compressed BIS certification windows and outcome-based pricing negotiations tied to energy efficiency deltas.
Among domestic technology specialists, Detect Technologies and Planys Technologies exemplify the hazardous-environment hardware-software convergence archetype, while Reliance Industries and ONGC anchor the integrated operator tier through captive deployment across Jamnagar-scale and Mumbai High assets respectively. These named entities represent the spectrum from pure-play technology vendors to vertically integrated energy majors, with procurement authority and data governance architectures diverging sharply between fragmented service tiers and consolidated operators.
| Leading Market Players |
|---|
| PRAYOG |
| Petronet LNG |
| Detect Technologies |
| Reliance Industries |
| ONGC |
| Planys Technologies |
| OligoQHSE |
| Indian Oil Corporation |
| Visage Technology |
| Others |
Pricing and Supply Chain Analysis
BIS certification tiers for Zone 0 and Zone 1 hazardous area deployments split vendor economics into 18-month validation premiums versus commodity middleware pricing, with procurement officers at Jamnagar-scale refineries paying efficiency-guarantee premiums while city gas distributors absorb compressed requalification costs under Petroleum and Natural Gas Regulatory Board mandates.
Pricing Analysis
Margin tightening in downstream managed services reflects outcome-based contract structures where vendors absorb hardware refresh cycles and integration risk in exchange for recurring revenue tied to energy efficiency deltas. Three-tier pricing structure across premium, standard, and economy levels stratifies by BIS certification grade and after-sales service bundling, with upstream operators showing highest price sensitivity due to exploration budget constraints and downstream refiners least sensitive given operational technology budget dominance.
Supply Chain Analysis
PLI scheme localization mandates for domestic AI hardware manufacturing reshape sourcing toward Indian semiconductor packagers and joint venture structures, reducing pure import dependency. Training-grade GPU supply draws from Taiwan, South Korea, and the United States, with edge computing hardware and fiber-optic acoustic sensors feeding from Chinese and Japanese component channels. Single-source vulnerability concentrates through DGFT licensing delays for US-origin semiconductors, while distribution runs through systems integrators with hazardous area certification expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Petroleum and Natural Gas Regulatory Board digital infrastructure mandates erect a compliance moat that favors incumbent vendors with validated BIS certifications and compresses competitive windows for unqualified entrants.
For Market Incumbents: Cement market position by acquiring computer-vision specialists with existing Zone 0 certifications before 18-24 month validation windows close, and deepen backward integration into edge computing hardware assembly under PLI scheme incentives to capture localization premiums and reduce DGFT exposure.
For New Entrants and Emerging Players: Launch via managed service partnerships with midstream pipeline operators facing compressed procurement timelines under city gas distribution mandates, targeting the Kochi-Visakhapatnam Industrial Corridor greenfield complexes where legacy system drag is absent and integrated AI deployment faces lower integration friction.
For Investors and Strategic Acquirers: Re-rating potential sits with domestic technology specialists possessing hazardous-environment hardware-software convergence capabilities given PLI scheme catalysts and import substitution tailwinds. Long-term viability centers on vendors with proven Mumbai High or Jamnagar deployment references. Watch BIS certification backlog clearance rates as inflection indicator for competitive entry velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Fast-Track Investment | Compresses 18-24 month validation windows for Zone 0 deployments ahead of competitor requalification cycles. |
| PLI Scheme Joint Venture Formation | Localizes GPU and edge hardware sourcing to reduce DGFT licensing exposure and capture manufacturing incentives. |
| Managed Services Contract Conversion | Shifts revenue from perpetual licenses to outcome-based uptime guarantees at Jamnagar-scale refineries. |
| Multi-Modal Sensor Fusion Development | Integrates drone thermal and fiber-optic acoustic arrays for 33,000 km trunk line leak detection networks. |
| Greenfield Corridor Pre-Positioning | Establishes integrated AI deployment capabilities in Kochi-Visakhapatnam before operational technology budgets finalize. |
Research Methodology
Document review covered Petroleum and Natural Gas Regulatory Board circulars, BIS hazardous area certification databases, and CEA cybersecurity directives, complemented by interviews with upstream operations managers at ONGC, downstream digital transformation leads at Reliance Industries, systems integration specialists, and PLI scheme implementation officers. Secondary validation drew from DGFT trade data, CEA critical infrastructure filings, and petroleum industry association procurement surveys. Bottom-up deployment estimates triangulated against top-down energy sector IT/OT spending ratios.
Installed base projections and value estimates emerged from segment-level modeling across application type, technology configuration, service delivery model, and end-user sophistication tiers throughout the forecast period. CAGRs derived from historical adoption velocity in comparable industrial AI markets adjusted for BIS certification friction and PLI scheme incentive timelines. Industry-specific inputs included SCADA integration complexity scores and hazardous area equipment replacement cycles.
The model assumes a particular technology adoption path; alternative pathways for edge computing deployment would alter the outlook if cloud-centric architectures prevail over on-premise inference. Forecasts reflect assumptions around regulatory enforcement consistency and semiconductor supply normalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Well Completion Market
Oil & Gas
Middle East and Africa Drilling Market
Oil & Gas
China Oil and Gas Market
Oil & Gas
Oil and Gas Separator Market
Oil & Gas
Crude Oil Carriers Market
Oil & Gas
Chad Oil and Gas Upstream Market
Oil & Gas
Romania Oil and Gas Upstream Market
Oil & Gas
Europe Oilfield Equipment Rental Services Market
Oil & Gas
Egypt Oil and Gas Market
Oil & Gas
Operational Digital Oilfield Solution Market
Oil & Gas
Global Oil Line Corrosion Inhibitors Market
Oil & Gas
APAC Oil and Gas Automation Market
Oil & Gas
Indonesia Oil and Gas Midstream Market
Oil & Gas
United Kingdom LNG Market
Oil & Gas
Well Abandonment Services Market
Oil & Gas
Oil and Gas Asset Integrity Management Services Market