
 Servo Drive Market | 2026-2036
Servo Drive Market Size, Share, and Industry Trends Forecast 2026-2036
Servo Drive Market Analysis
High-precision positioning tier is rotating toward center stage as semiconductor and medical device manufacturers demand sub-micron accuracy from motion control systems. Yaskawa Electric Corporation leverages decades of servo motor integration to anchor its position in robotics and CNC machinery. Siemens AG sustains technology leadership through its digital twin-enabled drive platforms that merge hardware with industrial software ecosystems.
A servo drive is an electronic amplifier that modulates power delivery to servo motors using pulse-width modulation at switching frequencies typically between 4 kHz and 16 kHz, enabling precise closed-loop control of position, velocity, and torque in automated machinery. AC servo drives dominate installed capacity across manufacturing floors due to superior power density and regenerative energy recovery, while servo controllers capture expanding margin pools as machine builders prioritize software-defined motion architectures over standalone hardware. Closed-loop control technology leads adoption in aerospace and automotive end-use segments where feedback resolution directly determines part quality and process yield.
EU Machinery Directive and CE marking requirements enforce functional safety standards through ISO 13849 and IEC 61800-5-2, compelling servo drive vendors to integrate safe torque-off circuitry and diagnostic coverage into base product designs. China's GB/T 12668 and SAMR certification protocols create parallel compliance obligations for suppliers targeting domestic automation infrastructure buildouts. Stakeholders must monitor how IEC energy efficiency classifications and emerging cyber-security standards for industrial control systems reshape R&D allocation and product roadmaps.
Market Dynamics
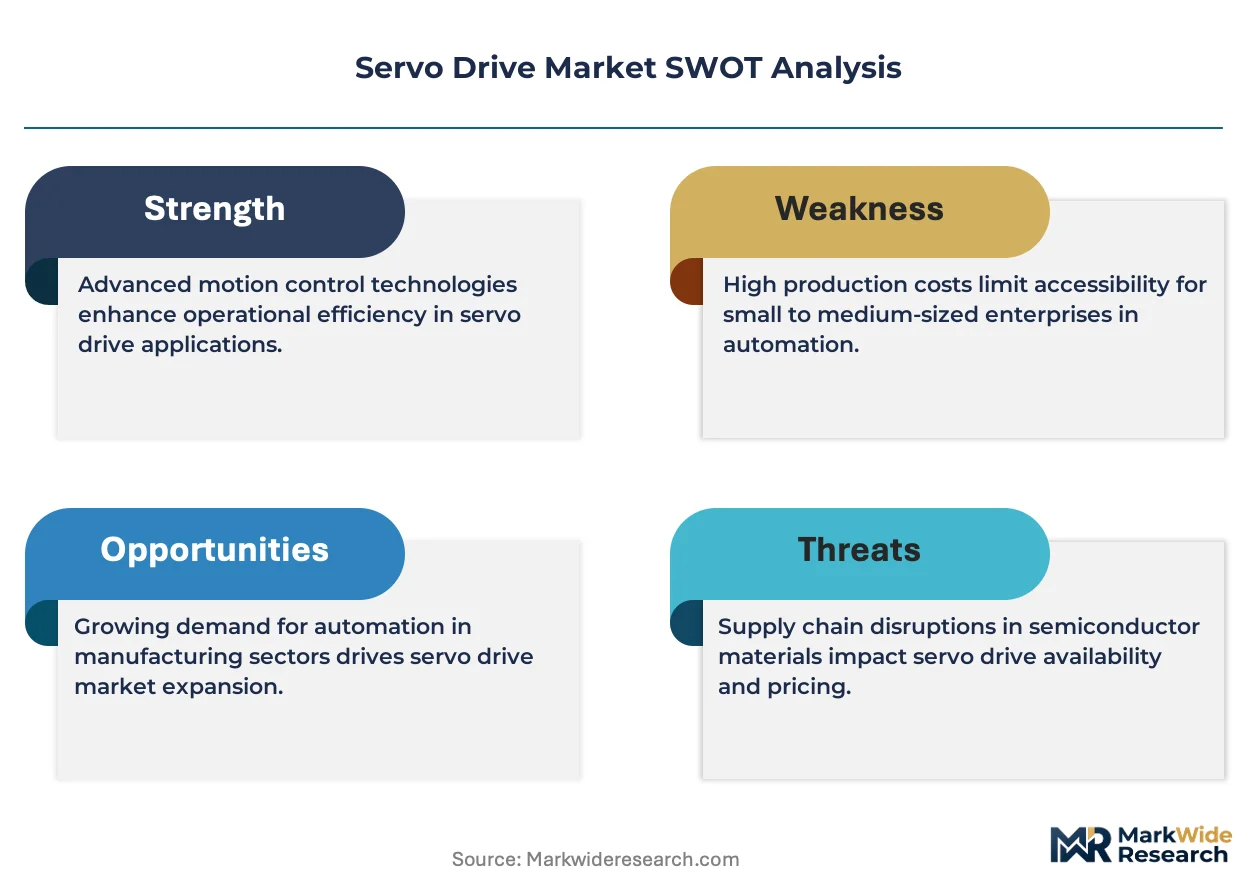
Semiconductor fabrication expansion in Taiwan and South Korea is compressing servo drive procurement cycles as lithography and wafer handling systems demand sub-micron positioning accuracy. This demand concentration is forcing vendors to reconfigure supply chains around precision manufacturing corridors.
Growth Catalysts
- EU Machinery Directive compliance:ISO 13849 and IEC 61800-5-2 functional safety mandates compel machine builders to upgrade legacy motion control systems with safe torque-off circuitry.
- AC servo drive power density:Superior regenerative energy recovery and switching frequencies between 4 kHz and 16 kHz displace hydraulic actuation in automotive press lines.
- Medical device manufacturing:Sub-micron accuracy requirements for surgical robotics and diagnostic imaging equipment pull high-resolution closed-loop controllers into cleanroom environments.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium processing dependence on Chinese refining capacity creates input cost volatility for permanent magnet servo motors.
- GB/T 12668 certification friction:China's SAMR electromagnetic compatibility protocols impose parallel testing obligations that extend product launch timelines for foreign suppliers.
- Integrated servo motor substitution:Compact motor-drive units eliminate cabinet space and cabling costs in material handling applications, eroding standalone drive margins.
Strategic Opportunities
- India PLI scheme automation:Production-linked incentives for electronics manufacturing and pharmaceuticals create fresh demand corridors for cost-optimized servo systems in Pune and Chennai industrial zones.
- Digital twin convergence:Siemens AG and Rockwell Automation are merging hardware with industrial software ecosystems, enabling predictive maintenance revenue streams.
- Cyber-physical security standards:Emerging IEC 62443 frameworks for industrial control systems create certification-driven preference shifts toward vendors with embedded security architectures.
Industry Challenges
- Motion control firmware expertise scarcity:Embedded systems engineers capable of tuning PID loops for high-dynamic applications command premium compensation in German and Japanese labor markets.
- Legacy fieldbus integration complexity:EtherCAT and PROFINET migration projects stall when brownfield facilities cannot retire DeviceNet or Modbus installations without production downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Servo Drive Market |
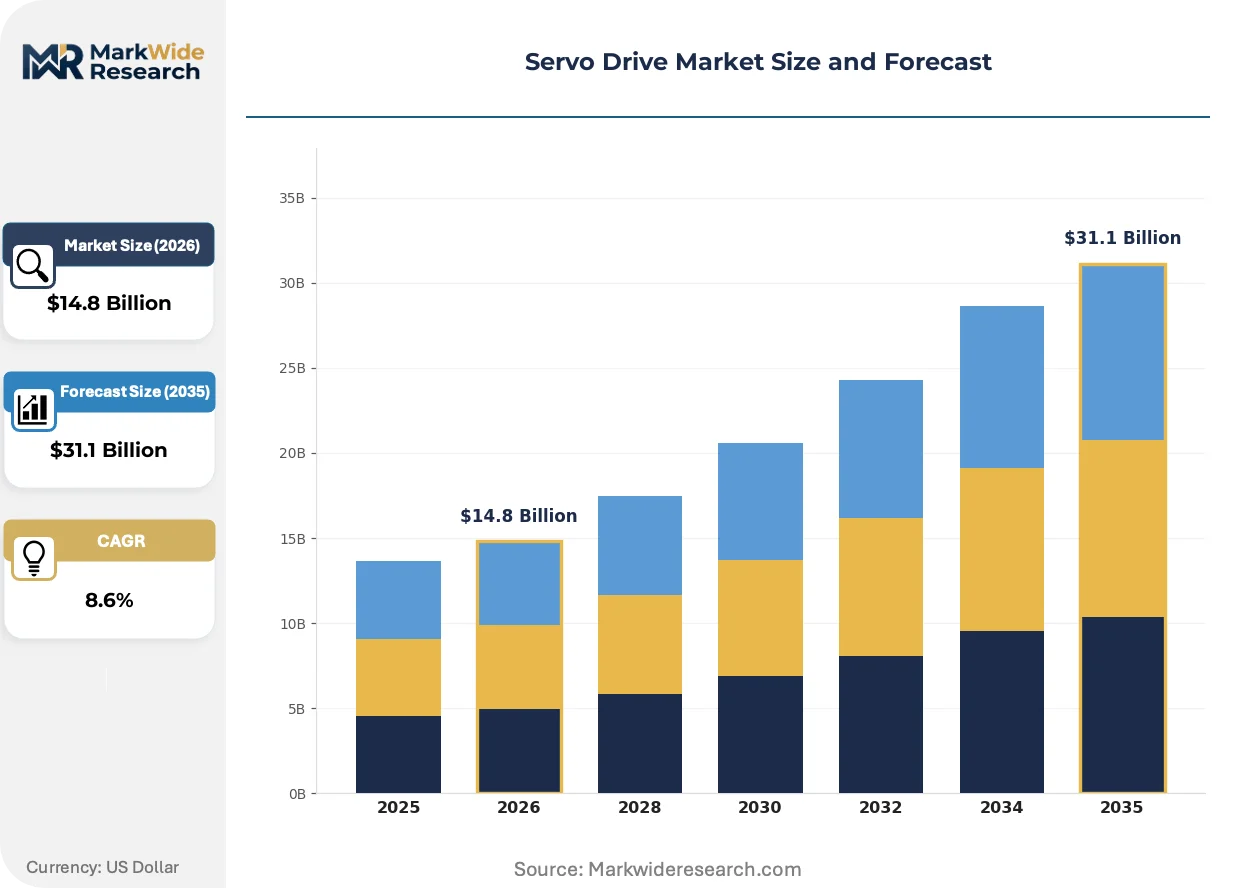
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.1 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Servo Drives, DC Servo Drives, Servo Motors, Servo Controllers End User: Manufacturing, Robotics, Aerospace, Automotive Technology: Closed-Loop Control, Open-Loop Control, Synchronous, Asynchronous Application: Position Control, Velocity Control, Torque Control, Motion Control |
| Companies Covered | Rockwell Automation, Schneider Electric, Yaskawa Electric Corporation, Delta Electronics Inc., FANUC Corporation, Mitsubishi Electric Corporation, ABB Ltd, Bosch Rexroth AG, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Servo Drive Market Emerging Trajectories
Software-defined motion architectures are displacing standalone hardware as machine builders prioritize configurable control algorithms over fixed-function drives. This shift compresses product lifecycles and expands margin pools toward servo controllers.
Silicon carbide power semiconductors are decomposing thermal management constraints in high-frequency servo drives. Aerospace tier-one suppliers in Toulouse and Hamburg are adopting 16 kHz switching systems for electric actuation in next-generation flight control surfaces. The technology is decomposing heatsink volume requirements, enabling cabinet space reduction of thirty to forty percent in confined aerospace bay configurations.
China's GB standards and SAMR certification protocols are tightening electromagnetic compatibility enforcement for industrial motion control equipment. Domestic automation infrastructure buildouts now require pre-market testing at designated laboratories in Shanghai and Shenzhen. European and Japanese suppliers are responding by establishing captive certification facilities within mainland China to compress approval timelines.
Machine-as-a-service contracting is restructuring capital equipment procurement in automotive battery manufacturing. Korean and German cell producers now specify performance-based payment terms tied to throughput and availability metrics rather than upfront hardware purchase. This model concentrates in gigafactory deployments where OEMs seek to offload obsolescence risk onto motion control vendors.
Servo Drive Market Segmentation
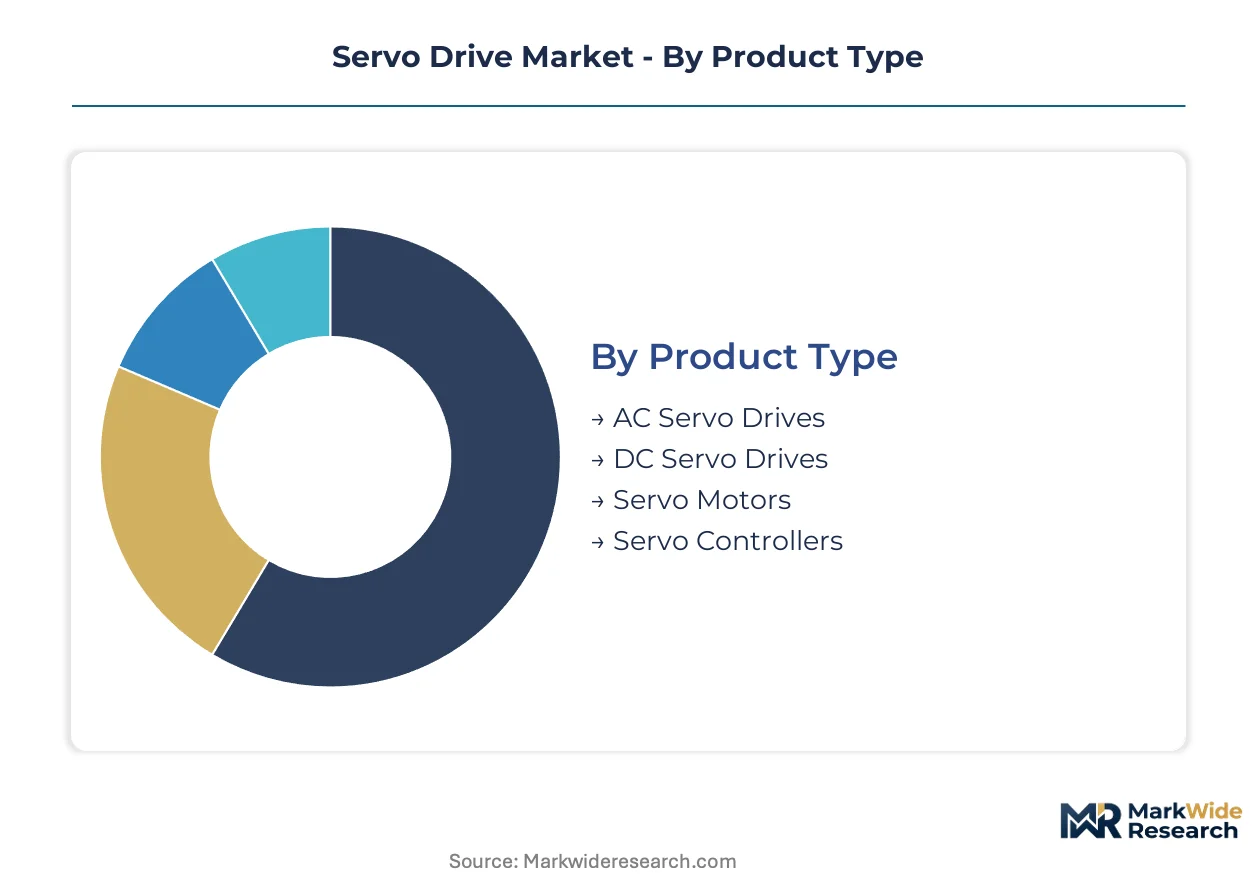
Servo drive segmentation reveals how value migrates across hardware, software, and control architectures. Understanding these divisions exposes where vendors capture margin and where commoditization pressures concentrate.
Product Type:
Margin pools concentrate in control intelligence rather than power electronics, with software-defined architectures expanding addressable value per unit.
- AC Servo Drives:Pulse-width modulation systems operating at 4-16 kHz switching frequencies deliver superior power density and regenerative energy recovery. Semiconductor fabrication facilities in Taiwan and South Korea specify these for lithography positioning stages where thermal stability determines wafer yield.
- Servo Controllers:Configurable control algorithms embedded in industrial software ecosystems command expanding margin pools as machine builders deprecate fixed-function hardware. Siemens AG and Rockwell Automation merge these with digital twin platforms to enable predictive maintenance revenue streams.
- AC Servo Drives:See above — already covered as full treatment.
- DC Servo Drives:Brushed and brushless variants persist in legacy retrofit applications where existing motor investments constrain upgrade paths.
- Servo Motors:Permanent magnet synchronous machines face input cost volatility from neodymium and dysprosium refining concentration in Chinese processing capacity.
The dominant share belongs to AC Servo Drives, while Servo Controllers are closing the gap fastest.
End User:
Application intensity varies sharply across sectors, with precision requirements and regulatory exposure determining willingness to pay for certified systems.
- Manufacturing:CNC machinery and automated assembly lines constitute the volume foundation, with EU Machinery Directive ISO 13849 compliance mandates forcing safe torque-off upgrades across German and Italian installed bases.
- Robotics:Surgical and collaborative systems demand sub-micron positioning accuracy in cleanroom environments. Medical device manufacturers in Stuttgart and Minneapolis specify high-resolution closed-loop controllers for diagnostic imaging equipment.
- Aerospace:Electric actuation for flight control surfaces drives 16 kHz switching adoption at Airbus and Boeing tier-one suppliers in Toulouse and Hamburg.
- Automotive:Battery gigafactory deployments in Germany and South Korea are restructuring procurement toward machine-as-a-service contracts tied to throughput metrics.
Manufacturing retains the largest installed base, though Robotics demonstrates the steepest expansion trajectory as surgical automation accelerates.
Technology:
Control methodology determines feedback resolution and directly shapes part quality in high-value production environments.
- Closed-Loop Control:Real-time position, velocity, and torque feedback via encoders or resolvers enables sub-micron accuracy. Aerospace and automotive segments mandate this technology where process yield correlates with feedback resolution.
- Synchronous:Field-oriented control of permanent magnet motors achieves highest efficiency at variable speeds, dominating precision applications where thermal management constrains envelope dimensions.
- Open-Loop Control:Stepper-based architectures persist in cost-sensitive material handling where absolute positioning accuracy remains secondary to capital expenditure minimization.
- Asynchronous:Induction motor control without rotor position sensors reduces system cost in pump and fan applications with modest dynamic requirements.
Closed-Loop Control holds the technology lead, while Synchronous architectures are gaining share fastest in electrified motion systems.
Application:
Functional specialization reflects how motion control integrates into broader automation workflows across discrete manufacturing processes.
- Position Control:Multi-axis coordination for pick-and-place, machining, and assembly operations requires interpolation algorithms and synchronized servo networks. Semiconductor wafer handling systems in Hsinchu and Pyeongtaek demand nanometer-scale repeatability.
- Motion Control:Trajectory planning and coordinated multi-axis profiles enable complex path following for robotics and CNC applications. Yaskawa Electric Corporation leverages decades of servo motor integration to anchor capabilities here.
- Velocity Control:Spindle drives and conveyor systems prioritize speed regulation over absolute positioning, with regenerative braking recovering kinetic energy in automotive press lines.
- Torque Control:Direct force modulation enables winding, tensioning, and pressing operations where material properties dictate force limits rather than position targets.
Position Control commands the dominant application share, while Motion Control is climbing the fastest as software-defined architectures proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German servo drive exports flow into Taiwanese semiconductor fabrication facilities, while Japanese precision components supply automotive battery production lines in South Korea and the United States.
United States
Automotive battery gigafactories in Michigan and Nevada specify machine-as-a-service procurement models tied to throughput metrics. OSHA and NHTSA safety mandates accelerate safe torque-off upgrades across legacy automotive press lines. The Detroit-Windsor corridor concentrates servo drive deployment for electric vehicle powertrain assembly.
Germany
CNC machinery and automated assembly lines constitute the volume foundation for servo drive demand across Baden-Württemberg and Bavaria. EU Machinery Directive ISO 13849 compliance mandates force safe torque-off circuitry upgrades through KBA enforcement. Stuttgart anchors medical device manufacturing where surgical robotics demand sub-micron positioning accuracy.
China
Domestic automation infrastructure buildouts in the Yangtze River Delta and Pearl River Delta require pre-market electromagnetic compatibility testing at SAMR-designated laboratories. GB/T 12668 certification protocols impose parallel testing obligations that extend product launch timelines for foreign suppliers. Shanghai and Shenzhen industrial zones concentrate captive certification facilities established by European and Japanese vendors.
Japan
Robotics and CNC machinery demand pulls high-resolution closed-loop controllers into Nagoya and Osaka manufacturing corridors. METI industrial standards enforce functional safety requirements through JIS certification protocols. Yaskawa Electric Corporation leverages decades of servo motor integration to anchor capabilities in precision motion control.
South Korea
Semiconductor fabrication expansion in Pyeongtaek and Hsinchu-linked supply chains compresses servo drive procurement cycles for lithography positioning stages. MFDS medical device regulations and industrial safety standards shape certification requirements for surgical automation equipment. Domestic battery cell producers specify performance-based contracting tied to availability metrics rather than upfront hardware purchase.
Servo Drive Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and software integration depth. The vendor base organizes around three tiers: diversified industrial conglomerates with digital twin platforms, motion control specialists with decades of servo motor integration heritage, and emerging Asian electronics manufacturers with cost-optimized architectures. Consolidation pressures concentrate in the middle tier as software-defined motion architectures expand margin pools toward control intelligence. Dominant competitive moves include strategic partnerships merging hardware with industrial software ecosystems and geographic expansion through captive certification facilities in mainland China.
Within the diversified industrial tier, Siemens AG and Rockwell Automation exemplify the convergence of drive hardware with predictive maintenance software platforms. Yaskawa Electric Corporation anchors the motion control specialist archetype through integrated servo motor expertise. These three names represent distinct competitive positioning vectors: European digital twin enablement, American industrial software ecosystems, and Japanese precision manufacturing heritage.
| Leading Market Players |
|---|
| Rockwell Automation |
| Schneider Electric |
| Yaskawa Electric Corporation |
| Delta Electronics Inc. |
| FANUC Corporation |
| Mitsubishi Electric Corporation |
| ABB Ltd |
| Bosch Rexroth AG |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
Twelve-to-sixteen-week lead times for silicon carbide power modules now govern procurement calendars across servo drive manufacturing, compressing margin buffers for vendors dependent on Taiwanese foundry capacity while amplifying pricing leverage for suppliers with captive semiconductor fabrication. This inventory pressure concentrates cost volatility in the high-frequency switching tier where aerospace and semiconductor equipment buyers demand 16 kHz performance.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with ISO 13849 functional safety certification and CE marking tier creating the primary price differentiation alongside volume scale. Pricing pressure stems from integrated servo motor substitution eroding standalone drive margins in material handling applications. Automotive battery gigafactory buyers exhibit highest price sensitivity through machine-as-a-service contracting, while semiconductor lithography OEMs remain least sensitive due to sub-micron accuracy requirements.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane now determine inbound logistics costs for European servo drive assemblers sourcing magnetic components and power semiconductors. Manufacturing concentrates in China, Japan, and Germany, with rare earth magnet processing drawing from Chinese neodymium and dysprosium refining capacity. Single-source vulnerability in permanent magnet supply creates structural risk. Distribution runs through authorized industrial automation distributors and direct OEM supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Servo drive market fragmentation creates entry niches as software-defined motion architectures displace fixed-function hardware and demand splinters across precision manufacturing corridors.
For Market Incumbents: Compound defensive positioning through backward integration into silicon carbide semiconductor sourcing and captive certification facilities in Shanghai and Shenzhen to compress GB/T 12668 approval timelines. Siemens AG and Yaskawa Electric Corporation demonstrate how digital twin platforms and integrated servo motor expertise respectively anchor margin defense against emerging Asian electronics manufacturers. For New Entrants and Emerging Players: Firmware customization services for legacy fieldbus migration represent a service-layer gap where incumbents under-serve brownfield facilities stalled on DeviceNet and Modbus retirement. Target India's PLI scheme automation corridors in Pune and Chennai with cost-optimized architectures. Pursue hospital system partnerships for surgical robotics controllers as the most penetrable cleanroom segment. For Investors and Strategic Acquirers: Long-term, this sits as a control-intelligence consolidation play because margin pools migrate toward software-defined architectures and predictive maintenance revenue streams. Acquisition targets should emphasize motion control firmware expertise and embedded cyber-security architectures per IEC 62443 frameworks. Monitor silicon carbide power semiconductor supply agreements as the inflection signal for manufacturing cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Certification Facility Establishment | European and Japanese vendors compress SAMR approval timelines by locating pre-market testing laboratories in Shanghai and Shenzhen industrial zones. |
| Digital Twin Platform Integration | Siemens AG merges servo drive hardware with predictive maintenance software to capture recurring revenue from automotive battery gigafactory deployments. |
| Silicon Carbide Power Semiconductor Adoption | Aerospace tier-one suppliers in Toulouse and Hamburg reduce heatsink volume thirty to forty percent through 16 kHz switching systems. |
| Machine-as-a-Service Contracting | Korean and German cell producers specify performance-based payment terms tied to throughput metrics rather than upfront hardware purchase. |
| Legacy Fieldbus Migration Services | Brownfield facilities require embedded systems engineers capable of tuning PID loops for high-dynamic applications without production downtime. |
Methodological Framework
Desk research of SEC 10-K filings, customs and trade data, IEC and ISO standard documentation, and industrial automation distributor records preceded structured interviews with plant engineers, OEM procurement teams, maintenance directors, and aftermarket service heads. Primary fieldwork across German CNC machinery corridors, Taiwanese semiconductor fabrication zones, and Japanese robotics manufacturing clusters combined with secondary validation from EIA energy data and ACC industry reports. Bottom-up unit economics triangulated against top-down sector sizing.
Variance decomposition across product type, end user, control technology, and application segments shaped the analytical framework over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macro industrial automation capex indicators. Modeled inputs included semiconductor fabrication capacity expansion schedules, EU Machinery Directive compliance upgrade cycles, and rare earth magnet price volatility indices.
Underlying assumptions cover sustained semiconductor capital expenditure, stable Chinese rare earth export policies, and incremental IEC cyber-security standard adoption, with deviation risk concentrated in tariff exposure on power electronics and sudden GB standards revision. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Laser Drilling Market
Industrial Equipment
Case Handling Machines Market
Industrial Equipment
Industrial Fans Market
Industrial Equipment
Global Industrial Actuators Market
Industrial Equipment
Global High Power Laser Systems Market
Industrial Equipment
Equipment Cases Market
Industrial Equipment
Commercial Refrigeration System Market
Industrial Equipment
Global Ultrasonic Cleaning Market
Industrial Equipment
Dust Collector Systems Market
Industrial Equipment
Portable Laser Cleaning Machine Market
Industrial Equipment
Spot Curing System Market
Industrial Equipment
Seal Inspection Equipment Market
Industrial Equipment
Glass Engraving Machines Market
Industrial Equipment
United States Ball Bearing Market
Industrial Equipment
Soldering Iron Market
Industrial Equipment
Industrial Tags Market