
 Industrial Fans Market | 2026-2036
Industrial Fans Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Fans Market Analytics
ISO 13350 certification for jet fans in tunnel ventilation is bifurcating the competitive landscape into qualified and non-qualified suppliers. ZIEHL-ABEGG SE leverages its German engineering base to dominate high-pressure centrifugal systems for industrial process cooling. Greenheck Fan Corporation anchors North American demand through extensive manufacturing scale and HVAC channel control. Nidec Corporation extends its motor technology leadership into direct-drive fan architectures, reducing maintenance intervals for data center clients.
Industrial fans are electromechanical devices comprising impellers, housings, and drive assemblies designed to move air or gases at specified flow rates and static pressures, typically constructed from galvanized steel, aluminum, or corrosion-resistant alloys. These systems serve critical functions across manufacturing floors, power plants, and agricultural facilities by controlling thermal loads, extracting hazardous particulates, and maintaining breathable atmospheres. Centrifugal fans command the largest installed base due to their pressure-generation advantages in dust removal and fume extraction applications. Axial fans are gaining share in agricultural ventilation and HVAC retrofit projects where space constraints and energy efficiency priorities favor their compact footprint and direct-drive compatibility.
The US Department of Energy enforces minimum efficiency standards for commercial and industrial fans under federal regulation, compelling manufacturers to redesign impeller geometries and motor pairings. The EU Ecodesign Directive and F-Gas Regulation jointly constrain refrigerant-based cooling alternatives, indirectly expanding demand for advanced air-moving equipment in European process industries. China's GB standards for fan energy efficiency and noise emissions create separate compliance thresholds for products serving its domestic manufacturing sector. Stakeholders must monitor how regional efficiency benchmarks diverge and whether modular fan platforms can achieve cross-certification without prohibitive engineering overhead.
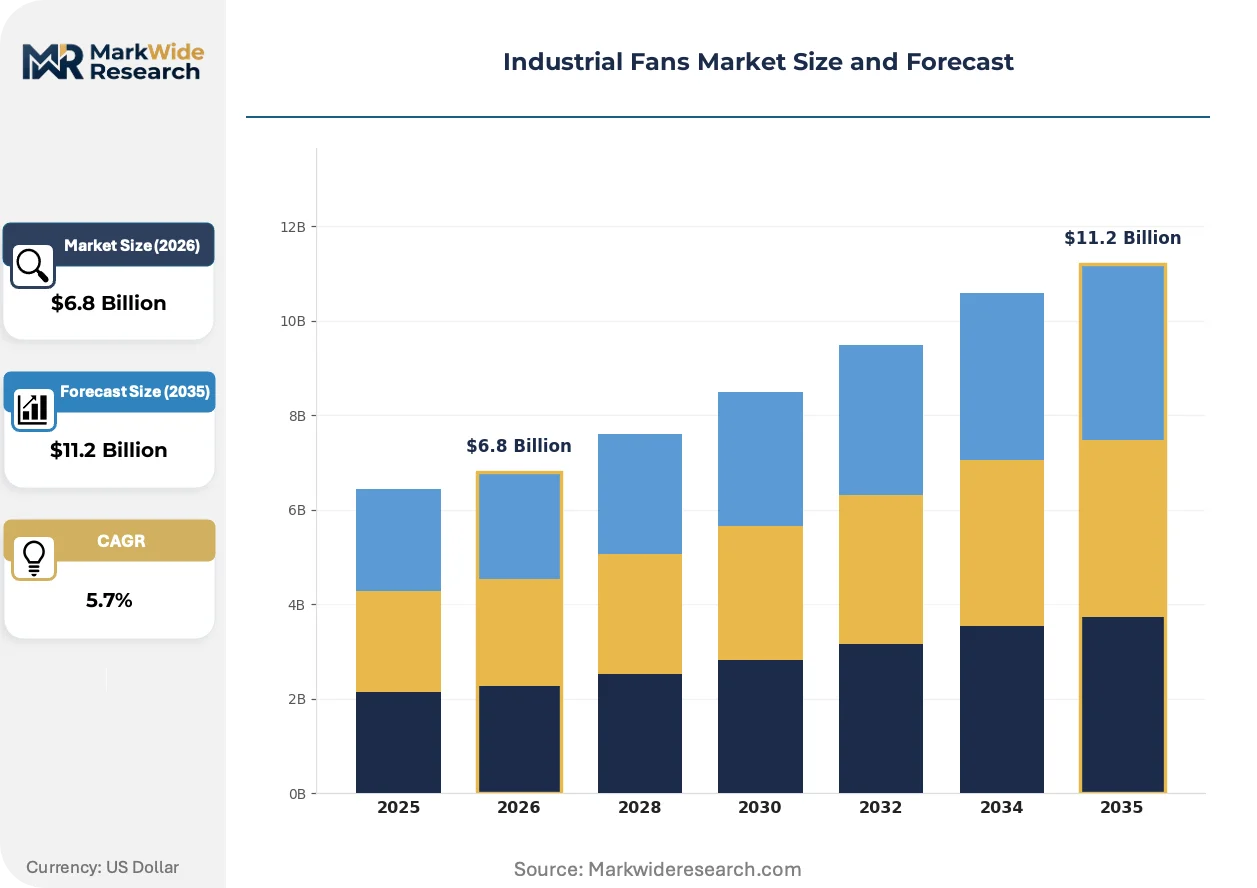
Market Dynamics
EU F-Gas Regulation phase-down schedules and US Department of Energy efficiency standards are compressing allowable operating envelopes for refrigerant-based cooling, forcing industrial process operators toward high-efficiency air-moving equipment as thermal management alternatives.
Growth Catalysts
- Data Center Cooling Mandates:Hyperscale facilities in Germany and the Netherlands are deploying high-pressure centrifugal systems to manage GPU thermal loads from AI training clusters.
- REACH Chemical Restrictions:European corrosion-resistant alloy specifications are accelerating replacement cycles in chemical processing ventilation infrastructure.
- Agricultural Mechanization:Poultry and dairy operations across Poland and Spain are retrofitting axial fans for precision climate control to meet animal welfare certification requirements.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings from Chinese export controls are destabilizing permanent magnet motor cost structures for direct-drive architectures.
- ISO 13350 Certification Bottleneck:Tunnel ventilation projects in Alpine regions face 14-18 month qualification timelines for jet fan suppliers lacking existing test documentation.
- Heat Pump Substitution:Industrial heat pump deployments for low-grade process heating are reducing ventilation-only thermal management investments in Nordic pulp and paper mills.
Strategic Opportunities
- Romanian Manufacturing Resurgence:Automotive supply chain relocation from Ukraine is creating demand for paint booth ventilation systems in Cluj-Napoca and Timișoara industrial zones.
- ECODESIGN 2025 Pre-Compliance:Manufacturers achieving draft motor efficiency thresholds six months early are capturing specification lock-in from major HVAC engineering firms.
- Digital Twin Convergence:CFD modeling platforms integrated with IoT vibration sensors are enabling predictive maintenance contracts that extend fan lifecycle revenue streams.
Industry Challenges
- Aerodynamicist Talent Scarcity:European universities produce fewer than 200 specialized impeller design graduates annually, constraining R&D throughput for next-generation blade geometries.
- Legacy BAS Integration:BACnet and Modbus protocol fragmentation across 1990s-era building automation systems is extending commissioning timelines for smart fan retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Fans Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Centrifugal Fans, Axial Fans, Blower Fans, Exhaust Fans End User: Manufacturing, HVAC, Power Generation, Agriculture Technology: Direct Drive, Belt Drive, VFD Technology, Low Noise Technology Application: Agricultural Ventilation, Industrial Process Cooling, Dust Removal, Fume Extraction |
| Companies Covered | Pelonis Technologies, Cooltron, Nidec Corporation, Fantech Pty Ltd, SEPA Europe, Big Ass Fans, ACDCFAN, ZIEHL-ABEGG SE, Greenheck Fan Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Fans Market Evolving Landscape
Computational fluid dynamics and additive manufacturing are collapsing iteration cycles for impeller optimization, while regulatory pressure on refrigerants elevates air-based thermal management from auxiliary to primary system status.
Magnetically levitated bearing systems are displacing conventional oil-lubricated arrangements in high-speed centrifugal applications. Pharmaceutical cleanrooms in Switzerland and Belgium are specifying mag-lev blowers for contamination elimination. The technology is displacing maintenance-intensive gearbox-driven alternatives in continuous-process environments where downtime costs exceed six figures hourly.
EU F-Gas Regulation bans on virgin HFCs with GWP above 150 are eliminating refrigerant-based precision cooling in battery cell manufacturing. German gigafactory projects are specifying dry air cooling with high-static-pressure fans for electrode drying processes. Automotive OEMs are responding by qualifying suppliers capable of delivering ATEX-certified systems for solvent recovery ventilation.
Performance-based service agreements are replacing capital equipment purchases in Dutch greenhouse operations. Cultivation facilities in Westland municipality are contracting cubic-meter-per-watt airflow guarantees rather than owning fan assets. This shift concentrates procurement authority with agricultural engineering consortia rather than individual growers.
Industrial Fans Market Segmentation
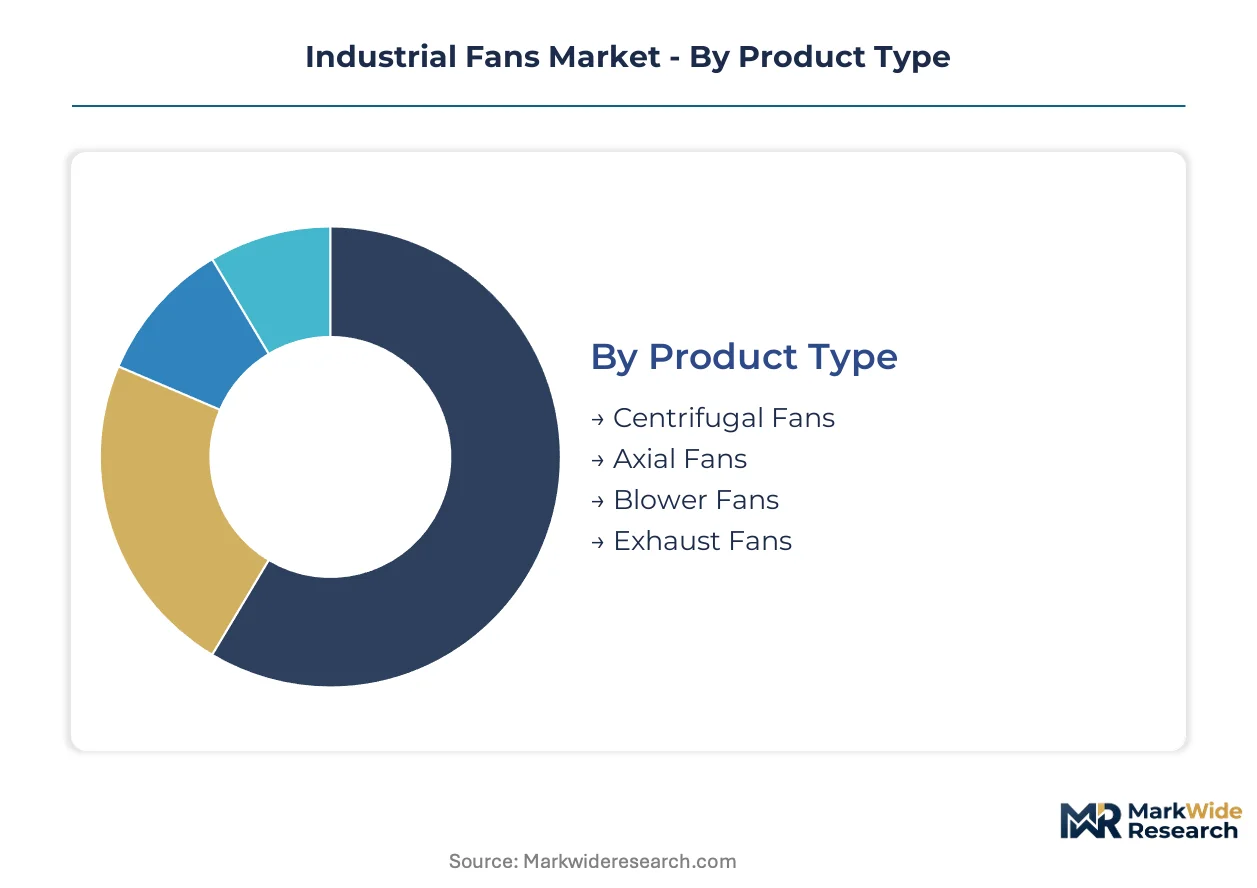
Industrial fan procurement channels diverge sharply by segment. Centrifugal systems move through specialized industrial distributors and direct OEM relationships, while axial and HVAC-oriented products flow through broader mechanical contractor networks. Understanding these channel dynamics shapes pricing power and specification capture.
Product Type:
Centrifugal fans command premium positioning through engineering-intensive channels, while axial and exhaust products compete through volume-oriented distribution networks serving retrofit and maintenance demand.
- Centrifugal Fans:Impellers mounted perpendicular to airflow generate high static pressure through curved blade geometries in spiral housings. German precision manufacturing and automotive supply chains specify these systems for process cooling, with ISO 13350 certification creating qualification barriers for tunnel ventilation projects.
- Axial Fans:Propeller-style impellers move air parallel to the shaft axis, delivering high flow rates at lower pressures. Polish and Spanish agricultural operations are retrofitting these for poultry climate control, driven by animal welfare certification mandates that demand precise humidity management.
- Blower Fans:Positive-displacement rotary designs deliver pulsation-free airflow for pneumatic conveying and combustion air supply.
- Exhaust Fans:Wall- and roof-mounted configurations extract contaminated air from confined industrial spaces, serving maintenance-driven replacement cycles.
Centrifugal fans dominate installed base. Axial fans are where expansion concentrates.
End User:
Cost tiers separate specification-grade systems for continuous-process manufacturing from price-sensitive agricultural and commercial HVAC procurement.
- Manufacturing:Paint booths, metal fabrication floors, and electronics assembly lines demand corrosion-resistant alloys and ATEX certification for solvent recovery. REACH chemical restrictions in European chemical processing are accelerating replacement cycles in ventilation infrastructure.
- HVAC:Building automation integration and energy retrofits drive specification, with BACnet protocol fragmentation complicating smart fan deployments in legacy infrastructure.
- Power Generation:Cooling towers and turbine hall ventilation require extreme-duty construction for continuous operation in thermal stress environments.
- Agriculture:Mechanized poultry and dairy operations prioritize cubic-meter-per-watt efficiency metrics over capital cost, with Dutch greenhouse consortia shifting toward performance-based service agreements.
Manufacturing captures highest margin per unit. Agriculture is climbing the fastest as livestock welfare regulations tighten.
Technology:
Volume concentration favors direct-drive architectures in new installations, while belt-drive systems sustain aftermarket and legacy replacement demand.
- Direct Drive:Permanent magnet motors eliminate mechanical transmission losses and maintenance intervals. Rare earth magnet volatility from Chinese export controls is destabilizing cost structures for these architectures.
- Belt Drive:Flexible speed ratios through pulley configurations accommodate variable duty cycles in intermittent-process environments.
- VFD Technology:Variable frequency drives modulate motor speed against actual thermal load, reducing energy consumption in part-load conditions.
- Low Noise Technology:Aerodynamic blade profiling and acoustic housings meet stringent workplace exposure limits in pharmaceutical cleanrooms and precision manufacturing.
Direct drive leads new specification. Belt drive sustains replacement revenue.
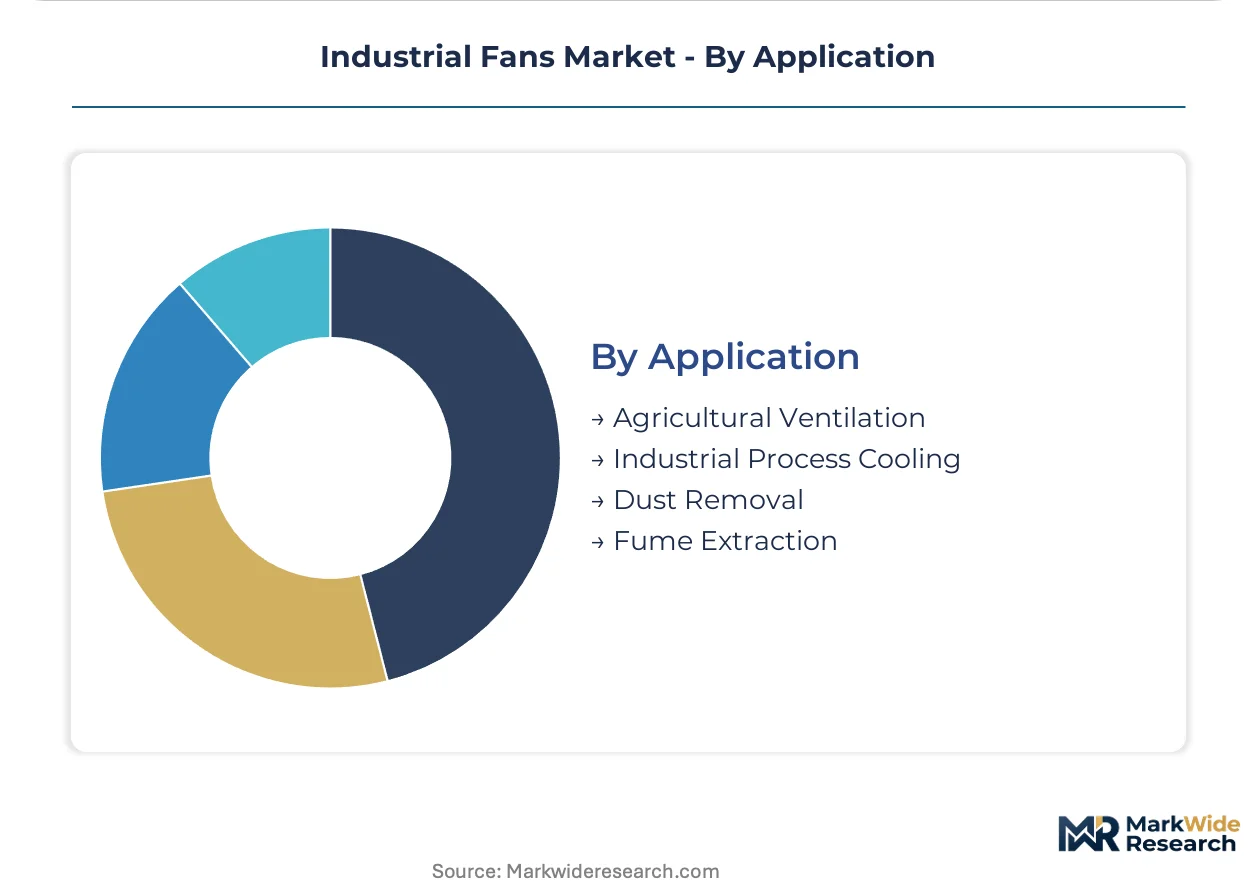
Application:
Application mix determines margin structure, with hazardous environment systems commanding engineering premiums over standard ventilation commodities.
- Industrial Process Cooling:High-static-pressure centrifugal systems manage GPU thermal loads in German and Dutch hyperscale data centers, with AI training cluster expansion driving specification volume.
- Dust Removal:Cyclone pre-separators and baghouse integration require abrasion-resistant impeller materials in woodworking and mineral processing.
- Agricultural Ventilation:Precision climate control for livestock housing emphasizes reliability and energy efficiency over peak performance.
- Fume Extraction:Hood-captured contaminant removal in welding and chemical processing demands spark-resistant construction and corrosion-proof coatings.
Industrial process cooling commands highest engineering value. Agricultural ventilation is expanding most quickly through mechanization subsidies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision manufacturing and Dutch data center expansion concentrate specification-grade demand, while Polish agricultural mechanization and Spanish livestock welfare enforcement drive volume procurement in peripheral markets.
Germany
Automotive supply chains and chemical processing infrastructure sustain centrifugal system orders, with REACH chemical restrictions accelerating corrosion-resistant alloy replacements. The EU F-Gas Regulation eliminates refrigerant alternatives in battery cell manufacturing, compelling gigafactory projects in Saxony and Lower Saxony to specify high-static-pressure ventilation for electrode drying processes.
Netherlands
Hyperscale data center clusters in Amsterdam and Eindhoven deploy high-pressure centrifugal architectures to manage GPU thermal loads from AI training facilities. Performance-based service agreements dominate Dutch greenhouse operations in Westland municipality, shifting procurement authority toward agricultural engineering consortia.
Poland
Mechanized poultry and dairy operations across Greater Poland and Silesia retrofit axial fans for precision climate control under animal welfare certification mandates. EU structural funds subsidize ventilation infrastructure upgrades, concentrating deployment in newly consolidated livestock facilities.
Spain
Poultry welfare regulations in Catalonia and Andalusia mandate humidity-controlled housing environments, driving axial fan replacement cycles in legacy agricultural infrastructure. Spanish engineering firms specify low-noise technologies to meet stringent workplace exposure limits in pharmaceutical cleanrooms near Barcelona.
Romania
Automotive supply chain relocation from Ukraine into Cluj-Napoca and Timișoara industrial zones generates paint booth ventilation demand. Romanian manufacturing resurgence attracts German and Italian component suppliers requiring ATEX-certified solvent recovery systems.
Industrial Fans Market Competitive Landscape
Player mix skews toward diversified electromechanical conglomerates with captive motor technology and specialized ventilation engineering houses with certification depth. Market structure concentrates specification-grade procurement around German and Japanese engineering specialists, while volume-oriented agricultural and HVAC segments fragment across regional fabricators. Two strategic archetypes dominate: integrated motor-fan platforms leveraging permanent magnet architectures, and certification-heavy tunnel ventilation specialists capturing ISO 13350-qualified project work. Competitive moves center on early ECODESIGN 2025 pre-compliance to lock engineering firm specifications and predictive maintenance service contracts extending lifecycle revenue.
Within the integrated motor-fan tier, Nidec Corporation and ZIEHL-ABEGG SE exemplify divergent geographic anchoring—Japanese conglomerate scale against German engineering-house certification depth. Greenheck Fan Corporation occupies the North American volume position, leveraging manufacturing scale and HVAC channel control. These three represent the archetype spectrum: motor technology verticalization, precision engineering qualification, and continental distribution dominance.
| Leading Market Players |
|---|
| Pelonis Technologies |
| Cooltron |
| Nidec Corporation |
| Fantech Pty Ltd |
| SEPA Europe |
| Big Ass Fans |
| ACDCFAN |
| ZIEHL-ABEGG SE |
| Greenheck Fan Corporation |
| Others |
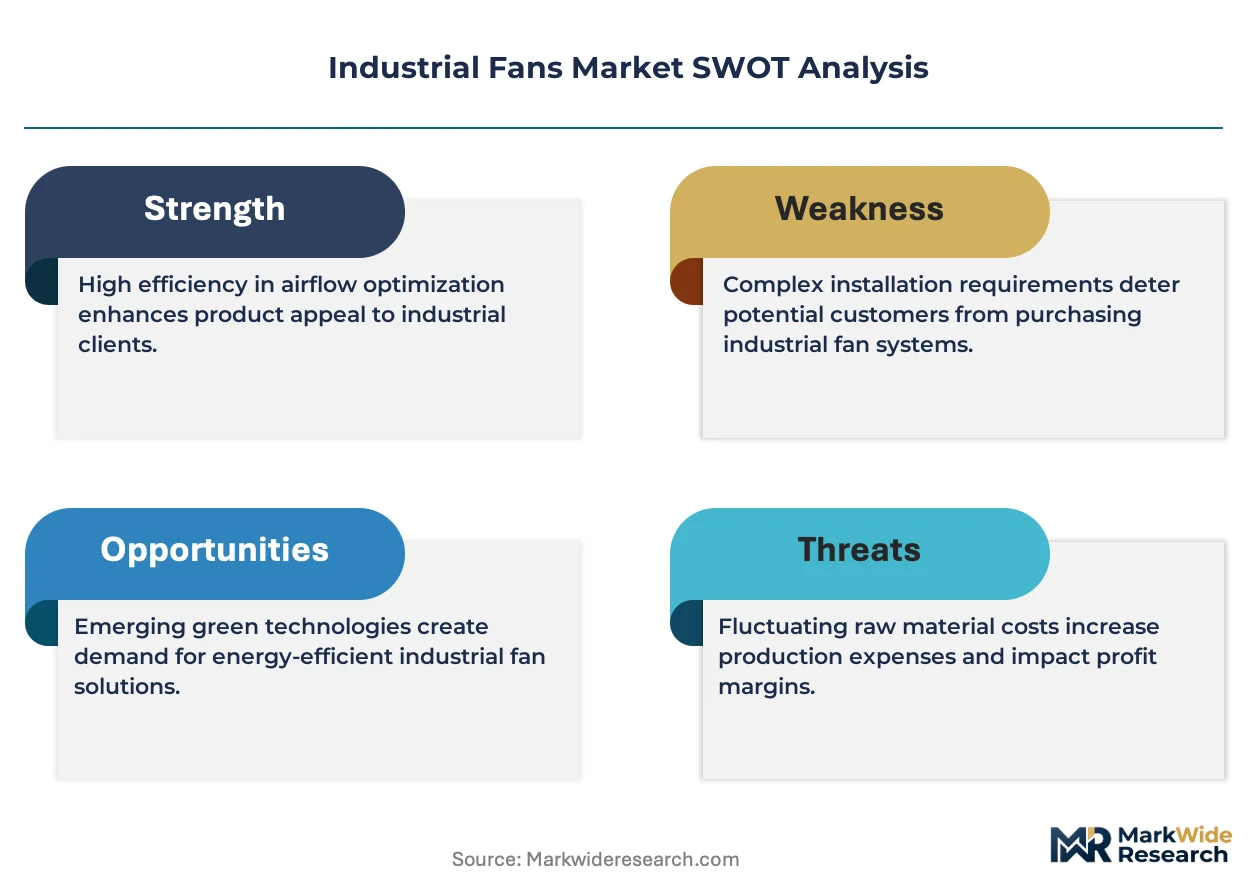
Value Network & Pricing Analysis
EU F-Gas Regulation phase-down schedules simultaneously gate supplier qualification and stratify price tiers, compressing operating envelopes for refrigerant-based cooling alternatives while elevating air-moving equipment to premium system status. Certification-heavy centrifugal systems for German precision manufacturing command substantial markups over commodity axial products serving Polish agricultural retrofits, with ISO 13350 tunnel ventilation documentation creating 14-18 month qualification barriers that lock in specification capture.
Pricing Analysis
Cost-plus contracts with rare earth magnet indexation dominate direct-drive fan procurement, tethering final pricing to neodymium and dysprosium volatility from Chinese export controls. Three-tier pricing structure across ATEX-certified premium, ISO 13350-qualified standard, and uncertified economy levels separates German automotive paint booth specifications from Spanish poultry ventilation retrofits. Price erosion runs through the agricultural axial segment as EU structural fund subsidies concentrate procurement authority with Dutch greenhouse consortia. Manufacturing process cooling buyers exhibit lowest price sensitivity, accepting six-figure hourly downtime costs against ventilation system capital outlay.
Supply Chain Analysis
Rare earth magnet refining in China, permanent magnet motor assembly in Japan, and precision impeller fabrication in Germany form the critical path for high-efficiency direct-drive architectures. Raw material dependencies span neodymium-dysprosium alloys for permanent magnet motors, corrosion-resistant aluminum-magnesium alloys for chemical processing environments, and high-grade electrical steel for stator laminations. Single-source vulnerability concentrates in Chinese rare earth processing, with export license unpredictability destabilizing motor cost structures. Distribution runs through specialized industrial distributors for centrifugal systems and mechanical contractor networks for axial HVAC products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European aerodynamicist output of fewer than 200 specialized impeller design graduates annually constrains R&D throughput, creating sustained scarcity premiums for engineering houses with captive blade geometry expertise. This capability gap rewards early investment in computational fluid dynamics platforms and additive manufacturing iteration cycles.
For Market Incumbents: Shield specification-grade positioning by accelerating ECODESIGN 2025 pre-compliance six months ahead of draft motor efficiency thresholds, locking engineering firm relationships before competitors achieve cross-certification. Deepen backward integration into permanent magnet motor architectures to offset rare earth price volatility from Chinese export controls, while extending predictive maintenance service contracts through IoT vibration sensor deployments to capture lifecycle revenue streams. For New Entrants and Emerging Players: Lead with Romanian automotive supply chain relocation from Ukraine, targeting paint booth ventilation demand in Cluj-Napoca and Timișoara industrial zones where ATEX-certified solvent recovery systems face qualified supplier shortages. Agricultural ventilation in Poland and Spain offers the most penetrable white space, with animal welfare certification mandates driving precision climate control retrofits and EU structural funds subsidizing infrastructure upgrades. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electromechanical conglomerates with underperforming ventilation divisions lacking ISO 13350 certification depth or ECODESIGN pre-compliance positioning. Long-term viability hinges on 5-10 year regulatory alignment with refrigerant phase-down trajectories and data center thermal load expansion from AI training clusters. Monitor German gigafactory electrode drying process specifications as the inflection indicator for high-static-pressure fan demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ECODESIGN 2025 Pre-Compliance | Six-month early qualification locks specifications from major HVAC engineering firms ahead of regulatory enforcement. |
| Magnetically Levitated Bearing Integration | Swiss and Belgian pharmaceutical cleanrooms specify mag-lev blowers for contamination elimination in continuous-process environments. |
| Digital Twin Convergence | CFD modeling platforms with IoT vibration sensors enable predictive maintenance contracts extending fan lifecycle revenue streams. |
| Rare Earth Magnet Backward Integration | Captive permanent magnet motor production insulates cost structures from Chinese neodymium export control volatility. |
| Romanian Manufacturing Zone Penetration | Automotive supply chain relocation from Ukraine generates paint booth ventilation demand requiring ATEX-certified solvent recovery systems. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this industrial fans assessment. Primary fieldwork combined structured interviews with secondary validation through customs and trade data, SEC 10-K filings from electromechanical conglomerates, and industry association reports from European ventilation engineering bodies. Bottom-up unit economics triangulated against top-down sectoral demand models to establish market sizing boundaries.
Sensitivity analysis across rare earth magnet price scenarios, regulatory phase-down velocities, and data center deployment trajectories informed the analytical framework. Segmentation dimensions spanned product type, end-use industry, technology architecture, and application severity across the projection horizon. CAGRs derived from installed base replacement cycles, greenfield capacity announcements, and efficiency mandate compliance deadlines, with AI training cluster thermal load density and battery cell manufacturing air-cooling specifications serving as industry-specific demand inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU F-Gas Regulation enforcement, continued Chinese rare earth export licensing unpredictability, or accelerated data center buildout timelines would require recalibration. Forecasts reflect documented assumptions regarding certification qualification timelines, agricultural mechanization subsidy continuity, and motor efficiency standard adoption curves. Practitioners should keep alternative scenarios live as refrigerant phase-down schedules, rare earth supply chain reconfigurations, and hyperscale facility deployment patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Fiber Laser Market
Industrial Equipment
Commercial Refrigeration System Market
Industrial Equipment
Dust Extraction System Market
Industrial Equipment
Global Servo Motor Market
Industrial Equipment
Vibration Isolation Tables Market
Industrial Equipment
Global Abrasive Waterjet Cutting Machine Market
Industrial Equipment
Chemical Storage Tank and Bottle for Semiconductor Market
Industrial Equipment
Middle East and Africa Industrial Centrifuge Market
Industrial Equipment
Electronic Beam Machining Market
Industrial Equipment
Dynamic Scales Market
Industrial Equipment
North America Rental Chillers Market
Industrial Equipment
Precision Dispensing Accessories Market
Industrial Equipment
Industrial Tags Market
Industrial Equipment
Screw Air End Market
Industrial Equipment
Electrode Slag Remelting (ESR) Furnace Market
Industrial Equipment
Global Safety Relays and Timers Market