
 Multi-Axis Sensor Market | 2026-2036
Multi-Axis Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Axis Sensor Market Foresight
Market Context with Strategic Players
Sensor-as-a-service leasing models and asset-light manufacturing partnerships are reshaping competitive entry barriers for mid-tier suppliers. Honeywell International Inc. leverages its aerospace certification heritage to dominate high-reliability defense and aviation contracts. STMicroelectronics sustains cost leadership through captive MEMS foundry capacity and automotive-grade volume production. Bosch Sensortec anchors consumer electronics supply chains with compact multi-axis inertial modules for smartphones and wearables.
Technical Definition and Structural Segments
Multi-axis sensors integrate two or more transduction principles—typically accelerometers, gyroscopes, and magnetometers—into monolithic or hybrid packages measuring linear acceleration, angular rate, and magnetic field orientation in three dimensions, with typical noise floors below 0.01 degrees per second and cross-axis sensitivity under 1 percent. These devices enable closed-loop control, navigation, and vibration monitoring across industrial, automotive, and aerospace systems where single-axis measurement proves insufficient. MEMS technology captures the largest installed base due to silicon batch fabrication economies, while optical sensing commands premium positioning in precision robotics and satellite stabilization where drift tolerance demands exceed MEMS capability. Capacitive transduction leads consumer and automotive volumes, though magnetic technologies gain traction in harsh-environment industrial deployments where electromagnetic immunity requirements exclude capacitive architectures.
Regulatory Frame and Forward-Looking Close
FAA airworthiness directives and NHTSA autonomous vehicle testing protocols mandate traceable calibration chains and fault-tolerant redundant sensing architectures, elevating compliance costs for suppliers without established aerospace or automotive qualification pathways. FDA device regulations and ISO 13485 quality management standards further constrain medical robotics applications where patient-contact systems require biocompatible packaging and electromagnetic compatibility validation. Stakeholders must monitor evolving functional safety standards across these jurisdictions, as harmonization gaps between FAA, NHTSA, and FDA test methodologies create certification duplication risks that favor suppliers with pre-existing multi-domain qualification portfolios.
Market Dynamics
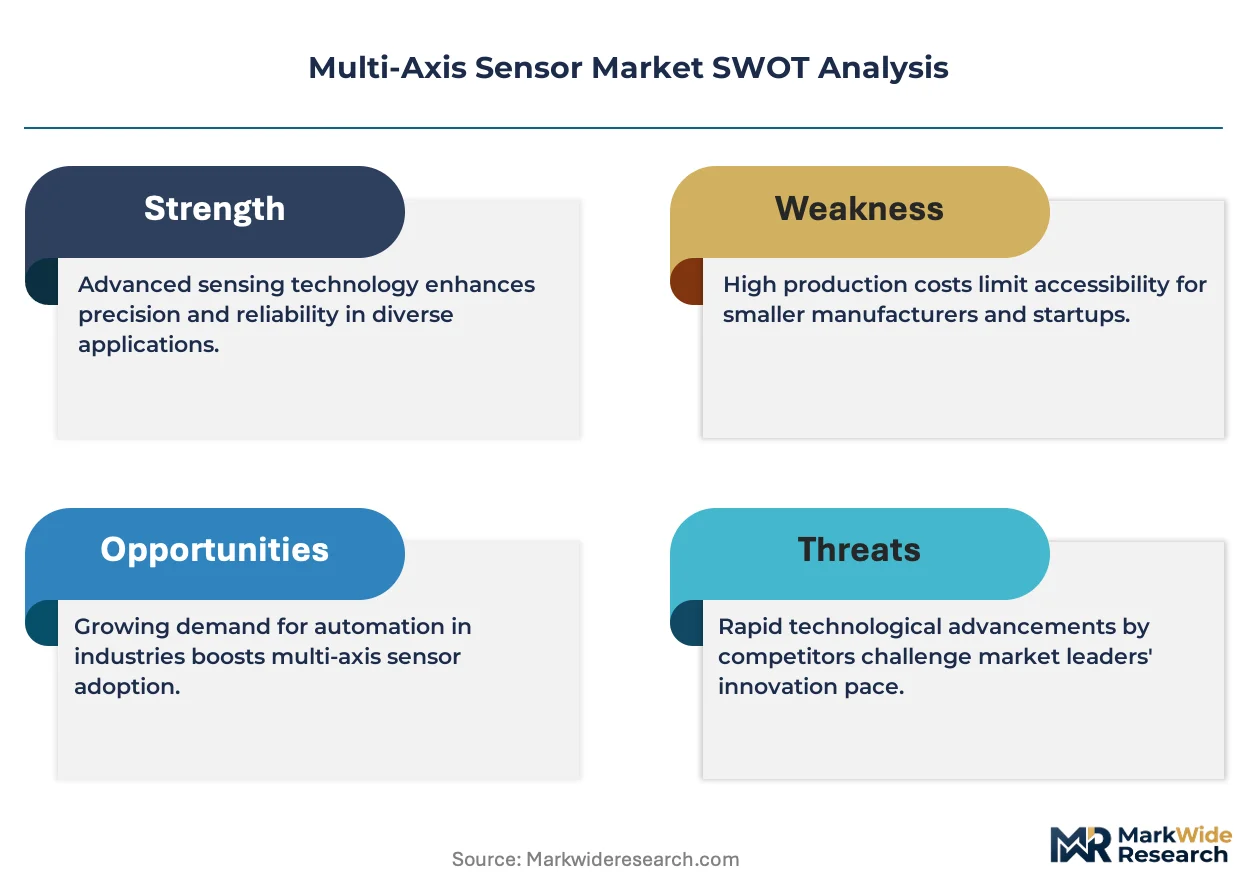
Wafer-level MEMS packaging advances are compressing unit economics while automotive OEMs demand redundant sensing architectures for Level 4 autonomy, forcing suppliers to recalibrate cost-reliability trade-offs across defense, industrial, and consumer tiers.
Growth Catalysts
- NHTSA Autonomous Vehicle Testing Protocols:Mandated fault-tolerant sensor arrays for self-driving validation fleets are pulling triple-redundant IMU configurations into commercial vehicle platforms.
- Optical Sensing Convergence:Fiber-optic gyroscope integration with MEMS accelerometers is opening precision robotics applications where drift tolerance exceeds silicon capability.
- German Precision Manufacturing Clusters:Stuttgart and Munich industrial automation corridors are anchoring volume demand for six-axis force-torque sensors in collaborative robot deployments.
Market Restraints
- MEMS Foundry Concentration:Taiwan and South Korea captive fabs control critical 200mm silicon-on-insulator wafer supply, exposing automotive programs to single-source disruption risk.
- FAA Airworthiness Calibration Chains:Traceable certification requirements for aerospace IMUs impose eighteen-month qualification timelines that freeze out mid-tier suppliers without established aviation heritage.
- Piezoelectric Substitution:Bulk acoustic wave resonators are displacing capacitive MEMS in harsh-environment vibration monitoring where temperature swings exceed 150°C.
Strategic Opportunities
- India PLI Scheme for Electronics:Production-linked incentives for semiconductor packaging are attracting MEMS module assembly investments serving domestic automotive and defense procurement.
- Sensor-as-a-Service Leasing:Asset-light subscription models for industrial vibration monitoring are penetrating mid-market manufacturers lacking capital for upfront hardware acquisition.
- EU AI Act Compliance:Mandatory transparency requirements for autonomous decision systems are creating certified sensor data provenance services as a new revenue layer.
Industry Challenges
- Multi-Domain Certification Portfolios:Harmonization gaps between FAA, NHTSA, and FDA test methodologies force redundant validation spending on platforms serving aerospace, automotive, and medical robotics simultaneously.
- Cross-Axis Sensitivity Calibration:Achieving sub-1% error alignment between accelerometer, gyroscope, and magnetometer axes demands specialized cleanroom infrastructure that concentrates talent in Germany, Japan, and the United States.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Axis Sensor Market |
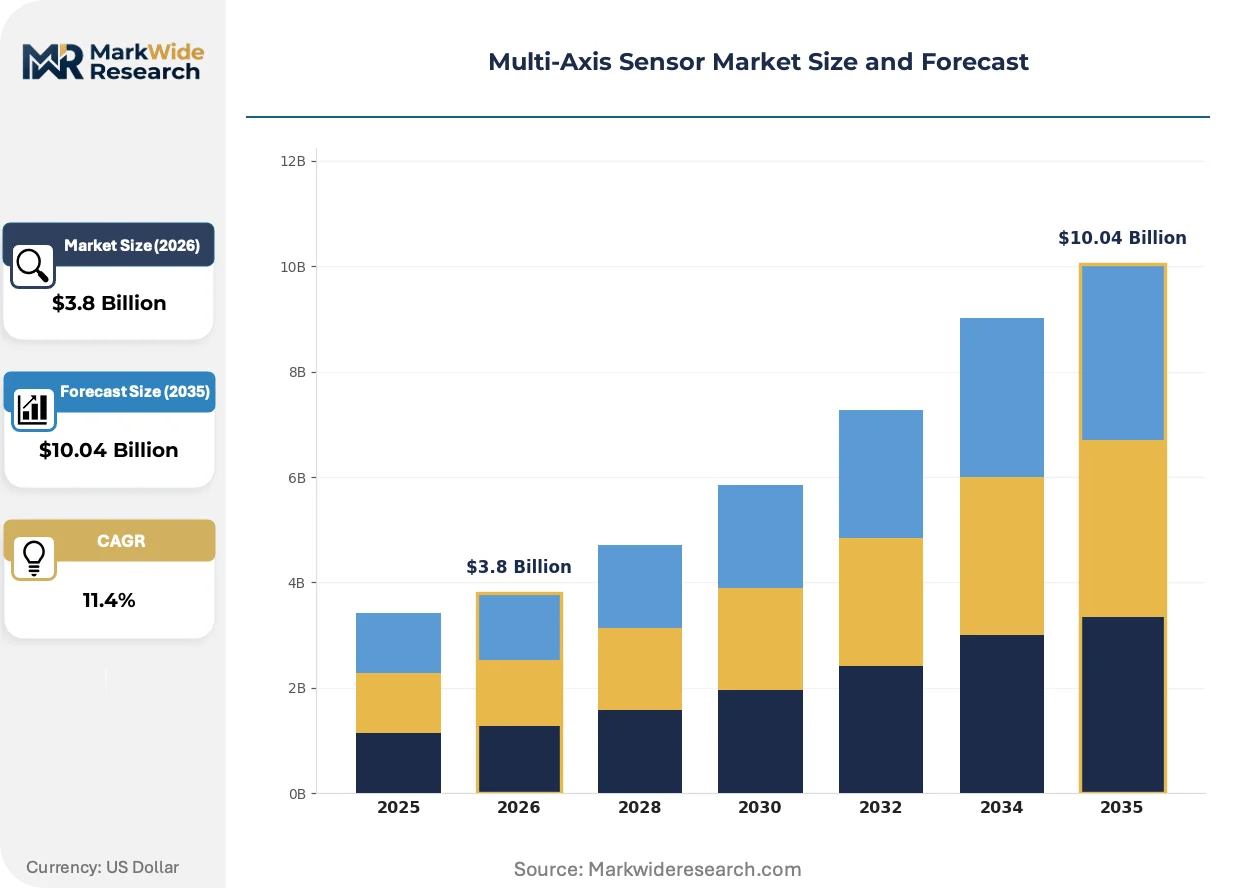
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Accelerometers, Gyroscopes, Magnetometers, Inclinometers Application: Automotive Systems, Robotics, Aerospace, Consumer Electronics End User: Manufacturers, Research Institutes, Defense, Automotive OEMs Technology: MEMS, Optical, Capacitive, Magnetic |
| Companies Covered | Honeywell International Inc., STMicroelectronics, Parker Hannifin, Trimble Navigation, Bosch Sensortec, Analog Devices, NXP Semiconductors, ATI Industrial Automation, Interface Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Axis Sensor Market Shifts & Advancements
Silicon photonics integration and edge-AI sensor fusion are compressing latency budgets while regulatory mandates for explainable autonomy are rewriting data architecture requirements across end-use verticals.
Monolithic integration of MEMS transducers with CMOS readout circuitry is collapsing the cost floor for six-degree-of-freedom inertial modules. Automotive Tier 1 suppliers are adopting these devices for chassis stabilization systems at volumes that previously required discrete component assembly. The structural consequence is collapsing price bands between consumer-grade and industrial-grade IMU categories, forcing specialty suppliers to differentiate through firmware-based sensor fusion rather than hardware performance tiers.
REACH restrictions on perfluorinated compounds are eliminating traditional MEMS release etchants from European supply chains. German sensor foundries are retrofitting vapor-phase xenon difluoride systems to maintain production continuity. Medical robotics manufacturers serving EU markets are absorbing qualification costs for alternative chemistries ahead of MDR device recertification cycles, compressing margins on patient-contact sensing platforms.
Industrial buyers are consolidating vendor relationships around suppliers offering predictive maintenance analytics bundled with hardware. Japanese automotive component makers are displacing traditional distribution through direct sensor-data service contracts with fleet operators. This pattern is most visible in United States commercial trucking where uptime guarantees now dominate procurement criteria over unit price.
Multi-Axis Sensor Market Segmentation

Multi-axis sensor procurement patterns diverge sharply across technical specifications and end-use reliability requirements. Buyers in aerospace and medical robotics prioritize calibration traceability over unit cost, while automotive and consumer electronics volumes reward fabrication scale and packaging integration.
Sensor Type:
Mature transduction principles dominate installed base volumes, though emerging architectures are capturing precision applications where drift tolerance exceeds silicon capability.
- Accelerometers:MEMS capacitive designs measuring linear acceleration across ±2g to ±200g ranges anchor automotive chassis stabilization and consumer motion tracking. German automotive Tier 1 suppliers consume the highest volumes for active suspension systems, with NHTSA rollover mandates accelerating redundant dual-axis deployments.
- Gyroscopes:Angular rate sensors utilizing Coriolis force detection enable closed-loop stabilization in drone flight controllers and vehicle navigation systems. Optical fiber gyroscopes command premium positioning in satellite attitude control where bias stability below 0.001 degrees per hour outweighs MEMS cost advantages.
- Magnetometers:Three-axis magnetic field sensing provides heading reference for compass-augmented inertial navigation.
- Inclinometers:Tilt measurement devices integrate electrolytic or MEMS sensing for construction equipment leveling and industrial machinery alignment.
Accelerometers handle the majority of throughput; gyroscopes are expanding most quickly on share as autonomous navigation architectures proliferate.
Application:
End-use requirements fragment the supplier landscape between high-volume consumer modules and qualification-intensive aerospace contracts.
- Automotive Systems:Electronic stability control, rollover detection, and autonomous navigation platforms consume six-axis inertial measurement units in volumes exceeding other verticals combined. Stuttgart and Munich manufacturing corridors anchor European demand for force-torque sensors in collaborative robot deployments alongside traditional vehicle applications.
- Robotics:Surgical systems and industrial automation demand sub-millimeter positioning repeatability with electromagnetic immunity validation. FDA 510(k) pathways and ISO 13485 quality management standards constrain supplier entry for patient-contact platforms.
- Aerospace:FAA airworthiness directives mandate traceable calibration chains and fault-tolerant redundant architectures for flight-critical inertial reference systems.
- Consumer Electronics:Smartphone image stabilization and wearable fitness tracking prioritize packaging miniaturization and power efficiency over absolute accuracy.
Automotive Systems generates the dominant revenue base; Robotics is climbing the fastest as surgical and collaborative applications multiply.
End User:
Procurement authority concentrates in organizations with captive integration capabilities or regulatory qualification heritage.
- Manufacturers:Industrial automation and precision machinery builders specify multi-axis force sensors for process control and quality assurance.
- Research Institutes:National laboratories and university consortia drive demand for experimental-grade inertial systems with configurable data output protocols.
- Defense:Military procurement programs in the United States, Germany, and Japan require ITAR-compliant supply chains and radiation-hardened packaging for satellite and missile applications.
- Automotive OEMs:Volkswagen, Toyota, and Ford internal engineering groups are displacing traditional Tier 1 distribution through direct sensor-data service contracts with predictive maintenance guarantees.
Automotive OEMs command the largest procurement volumes; Defense is gaining share fastest as hypersonic and space-based programs accelerate.
Technology:
Fabrication approach determines cost floor, environmental tolerance, and calibration stability across operating temperature ranges.
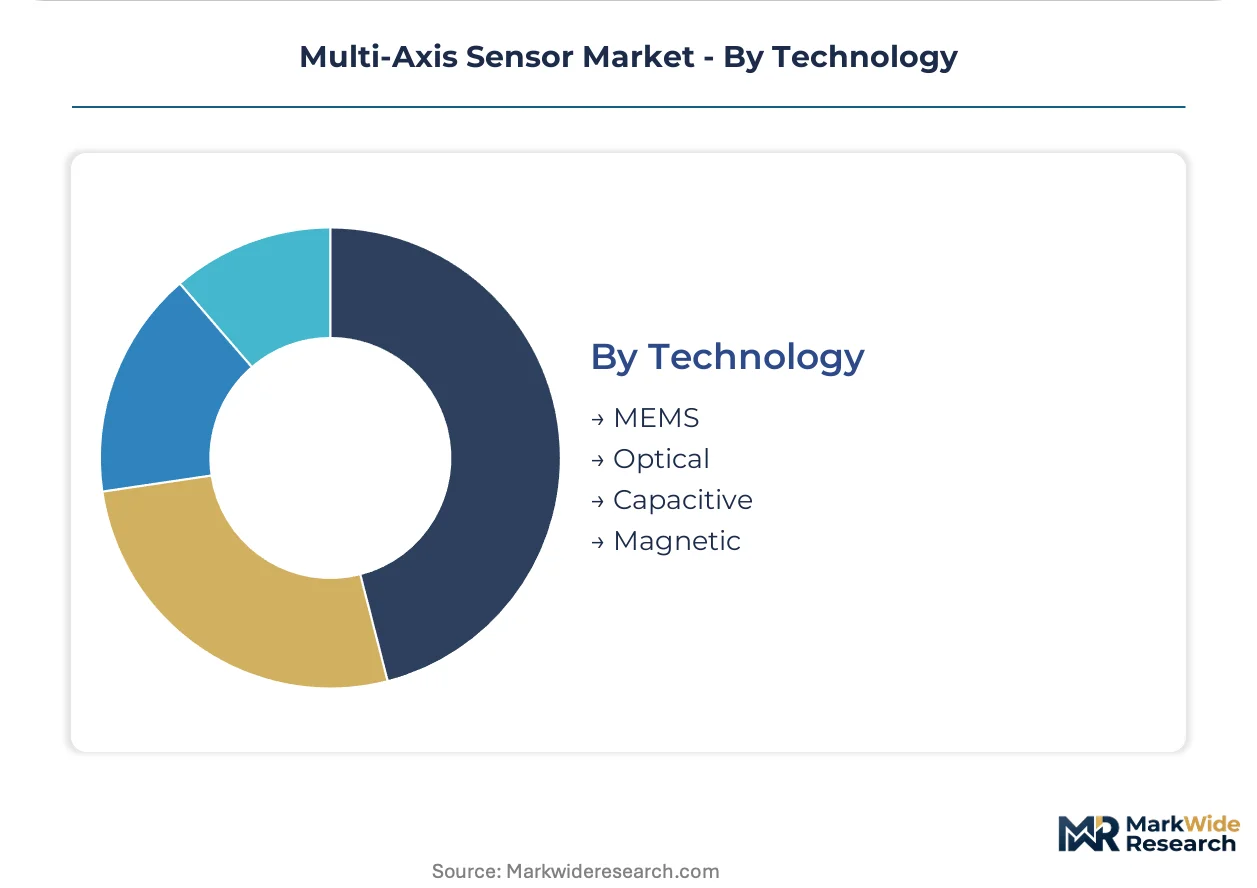
- MEMS:Silicon batch fabrication enables sub-dollar unit costs at million-piece volumes, capturing consumer electronics and automotive chassis applications. Taiwan and South Korea captive foundries control critical 200mm silicon-on-insulator wafer supply, exposing automotive programs to single-source disruption risk.
- Optical:Fiber-optic and ring laser gyroscopes achieve bias stability orders of magnitude superior to silicon, commanding positioning in precision robotics and satellite stabilization where drift tolerance demands exceed MEMS capability.
- Capacitive:Electrostatic transduction dominates consumer and automotive volumes through established CMOS-compatible process flows.
- Magnetic:Hall-effect and magnetoresistive architectures gain traction in harsh-environment industrial deployments where electromagnetic immunity requirements exclude capacitive architectures.
MEMS processes the dominant unit volume; Optical is expanding most quickly on share as precision robotics and autonomous navigation requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in multi-axis sensors tilt toward export surplus in Germany, Japan, and the United States, while import dependence concentrates in emerging automotive manufacturing hubs seeking precision navigation components for autonomous vehicle programs.
Germany
Stuttgart and Munich precision manufacturing corridors anchor European demand for six-axis force-torque sensors in collaborative robot deployments. REACH restrictions on perfluorinated compounds are forcing German foundries to retrofit vapor-phase xenon difluoride release etching systems. Bosch Sensortec leverages captive MEMS capacity in Reutlingen to supply automotive Tier 1 programs with chassis stabilization modules.
United States
FAA airworthiness directives and NHTSA autonomous vehicle testing protocols mandate traceable calibration chains that freeze out mid-tier suppliers without established aviation heritage. Defense procurement programs in California and Arizona require ITAR-compliant supply chains for satellite and missile inertial reference systems. Honeywell International Inc. dominates high-reliability contracts through aerospace certification heritage anchored in Phoenix operations.
Japan
METI industrial automation initiatives are accelerating collaborative robot deployments in Nagoya and Osaka manufacturing belts. Japanese automotive component makers are displacing traditional distribution through direct sensor-data service contracts with fleet operators. STMicroelectronics sustains cost leadership through automotive-grade volume production serving Toyota and Honda engineering groups.
India
Production-linked incentive schemes for semiconductor packaging are attracting MEMS module assembly investments serving domestic automotive and defense procurement. CDSCO medical device regulations and BIS quality standards constrain supplier entry for patient-contact surgical robotics platforms. Bengaluru and Pune precision engineering clusters are emerging as assembly hubs for industrial vibration monitoring systems.
South Korea
Captive 200mm silicon-on-insulator wafer foundries in Suwon and Pyeongtaek control critical MEMS supply exposing automotive programs to single-source disruption risk. MFDS medical device regulations and KBA automotive safety standards shape qualification pathways for robotics and autonomous navigation components. Samsung and Hyundai engineering groups are consolidating vendor relationships around predictive maintenance analytics bundled with hardware.
Multi-Axis Sensor Market Competitive Landscape
On the supply side, the industry is structured around three distinct tiers: aerospace-certified specialists commanding premium positioning, automotive-scale MEMS fabricators driving unit economics, and industrial automation specialists serving precision robotics applications. Strategic archetypes include heritage aviation suppliers with multi-decade certification portfolios, captive foundry operators with backward integration into wafer processing, and sensor-as-a-service platform providers penetrating mid-market manufacturers. Dominant competitive moves center on strategic partnerships for asset-light manufacturing and portfolio diversification into edge-AI sensor fusion firmware.
Among heritage aviation suppliers, Honeywell International Inc. and Parker Hannifin exemplify the certification-intensive archetype that dominates defense and aerospace contracts through established FAA qualification pathways. STMicroelectronics sits within the captive foundry tier, leveraging automotive-grade volume production to sustain cost leadership across consumer and industrial segments. Bosch Sensortec anchors the consumer electronics vector with compact multi-axis inertial modules serving smartphone and wearable OEMs.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| STMicroelectronics |
| Parker Hannifin |
| Trimble Navigation |
| Bosch Sensortec |
| Analog Devices |
| NXP Semiconductors |
| ATI Industrial Automation |
| Interface Inc. |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor carries MEMS wafer shipments from Taiwan and South Korea foundries to European automotive assembly plants, with freight cost volatility compressing margins on consumer-grade inertial modules while amplifying price spreads between certified aerospace units and standard industrial sensors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with FAA-qualified aerospace IMUs commanding substantial premiums over automotive-grade volumes and consumer electronics modules facing relentless cost compression from wafer-scale integration. Price differentiation hinges on calibration traceability chains and NHTSA certification tiers, with automotive Tier 1 suppliers absorbing margin pressure from redundant sensing architectures for autonomous validation fleets. Pricing pressure stems from collapsing price bands between consumer and industrial IMU categories as monolithic MEMS-CMOS integration eliminates discrete assembly premiums. Consumer electronics manufacturers exhibit highest price sensitivity, while defense procurement programs demonstrate lowest elasticity due to ITAR compliance requirements and radiation-hardened packaging specifications.
Supply Chain Analysis
Extended payment terms from Korean automotive OEMs are squeezing working capital for Taiwanese MEMS foundries, forcing module assemblers to seek supply-chain finance facilities from regional banking consortia. Geographic concentration centers on Taiwan, South Korea, and Germany, with 200mm silicon-on-insulator wafer supply drawing from single-source captive fabs in Hsinchu and Suwon. Raw material dependencies include high-purity silicon substrates, rare-earth magnetic materials for Hall-effect sensors, and specialty ceramic packages for harsh-environment deployments. Single-source vulnerability poses acute structural risk, as earthquake disruption at any major foundry would freeze automotive IMU supply for eighteen months. Distribution runs through direct OEM contracts for high-reliability tiers and electronics distribution networks for consumer volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified cleanroom infrastructure for sub-1% cross-axis sensitivity calibration remains concentrated in Stuttgart, Tokyo, and Phoenix engineering corridors, creating structural bottlenecks that constrain supply expansion regardless of capital availability.
For Market Incumbents: Pre-empt displacement by optical sensing convergence in precision robotics through captive fiber-optic gyroscope partnerships or acquisition of ring-laser specialists, while reinforcing MEMS cost leadership via backward integration into 200mm silicon-on-insulator wafer supply. Lock in multi-year calibration service contracts with FAA-qualified repair stations to create switching costs against emerging Asian competitors. Prioritize certification investment in EU AI Act compliance for sensor data provenance services as a new revenue layer. For New Entrants and Emerging Players: Establish a beachhead in Indian automotive and defense procurement by leveraging PLI scheme subsidies for semiconductor packaging investments, targeting domestic OEMs seeking to reduce dependence on Taiwanese foundry supply. Penetrate the sensor-as-a-service leasing segment for mid-market industrial vibration monitoring, where asset-light subscription models bypass capital barriers that freeze out traditional hardware competitors. Lead with predictive maintenance analytics bundled with hardware as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized MEMS fabrication assets or dormant aerospace certification portfolios, particularly European manufacturers facing REACH compliance cost burdens. Long-term viability favors suppliers with multi-domain qualification across FAA, NHTSA, and FDA pathways, as harmonization gaps force redundant validation spending that advantages pre-certified incumbents. Watch for inflection signals in German precision manufacturing cluster expansion rates, where collaborative robot deployment velocity indicates six-axis force-torque sensor demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Domain Certification Investment | FAA-NHTSA-FDA qualification portfolios eliminate redundant validation spending for cross-vertical suppliers. |
| Captive MEMS Foundry Expansion | Backward integration into 200mm silicon-on-insulator wafer supply insulates automotive programs from Taiwan disruption risk. |
| Optical Sensing Acquisition | Fiber-optic gyroscope capability captures precision robotics applications where MEMS drift tolerance falls short. |
| Sensor-as-a-Service Platform Launch | Subscription models penetrate mid-market manufacturers lacking capital for upfront vibration monitoring hardware. |
| EU AI Act Compliance Service | Certified sensor data provenance addresses mandatory transparency requirements for autonomous decision systems. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the primary research phase, including MEMS fabrication engineers at captive foundries, automotive Tier 1 procurement directors, aerospace certification specialists, industrial automation system integrators, and medical robotics quality assurance leads. Secondary validation drew from FAA airworthiness directive filings, NHTSA autonomous vehicle testing protocol disclosures, SEC 10-K supply chain disclosures from listed sensor manufacturers, and EU REACH regulatory impact assessments. Bottom-up unit demand estimates from end-use applications were triangulated against top-down wafer supply projections from foundry capacity disclosures.
Calibration across historical shipment data and forward capacity announcements anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include sensor type, application vertical, end-user procurement authority, fabrication technology, and regional regulatory cluster. CAGRs were derived from slope-consistent growth trajectory analysis rather than endpoint anchoring. Industry-specific forecast inputs incorporated NHTSA autonomous vehicle deployment timelines and German precision manufacturing cluster expansion rates.
Stress conditions across MEMS foundry disruption scenarios, REACH chemical restriction enforcement intensity, and autonomous vehicle regulatory acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding wafer supply continuity and certification pathway harmonization progress. Macroeconomic contraction, geopolitical trade restriction expansion, or breakthrough optical sensing cost reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Pressure Transmitter Market
Sensors and Controls
Piezoelectric Materials Market
Sensors and Controls
Inertial Measurement Unit (IMU) Market
Sensors and Controls
Non-Contact Infrared Thermometer Market
Sensors and Controls
Global Wireless Brain Sensors Market
Sensors and Controls
Ozone Meter Market
Sensors and Controls
Middle East Robotic Sensors Market
Sensors and Controls
North America Occupancy Sensors Market
Sensors and Controls
Odor Sensor Market
Sensors and Controls
3D Sensors Market
Sensors and Controls
Water and Wastewater Sensors Market
Sensors and Controls
High-End Accelerometer Market
Sensors and Controls
Europe Electric Vehicle Sensor Market
Sensors and Controls
Middle East and Africa Temperature Sensors Market
Sensors and Controls
Electric Pipette Controllers Market
Sensors and Controls
Temperature Monitoring Devices Market