
 Global High Power Laser Systems Market | 2026-2036
Global High Power Laser Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Power Laser Systems Market Foresight
ISO 11553 safety certification for laser processing machines is rotating supplier eligibility across European defense and automotive procurement channels. TRUMPF leverages its captive supply of pump diodes and beam sources to control delivery timelines for multi-kilowatt systems. IPG Photonics Corporation anchors North American fiber laser output through its Oxford, Massachusetts manufacturing complex. Coherent competes in ultrafast amplifier segments where scientific research budgets sustain premium pricing.
High power laser systems generate coherent electromagnetic radiation exceeding one kilowatt of continuous-wave output or equivalent pulsed energy density, typically employing ytterbium-doped fiber gain media or CO2 gas discharge tubes to achieve the brightness required for metal melting and vaporization. Fiber lasers now dominate material processing installations due to wall-plug efficiency above thirty percent and minimal maintenance intervals compared to legacy CO2 resonators. Solid-state disk lasers occupy the highest-power niche in aerospace manufacturing, where thick-section titanium cutting demands beam quality unattainable through fiber architectures alone. Q-Switching technology leads defense applications requiring nanosecond pulse formats for target designation and countermeasure systems.
FDA laser product performance standards govern medical and cosmetic device classifications in the United States, while ECHA REACH restrictions on rare-earth processing chemicals constrain European supply chains for neodymium-doped gain media. China's GB standards for industrial laser safety, administered by SAMR, create non-tariff barriers for imported systems lacking domestic certification. Stakeholders must monitor divergence between EU F-Gas Regulation phase-down schedules and China's dual carbon implementation timelines, as refrigerant-dependent CO2 laser cooling architectures face asymmetric compliance costs across manufacturing footprints.
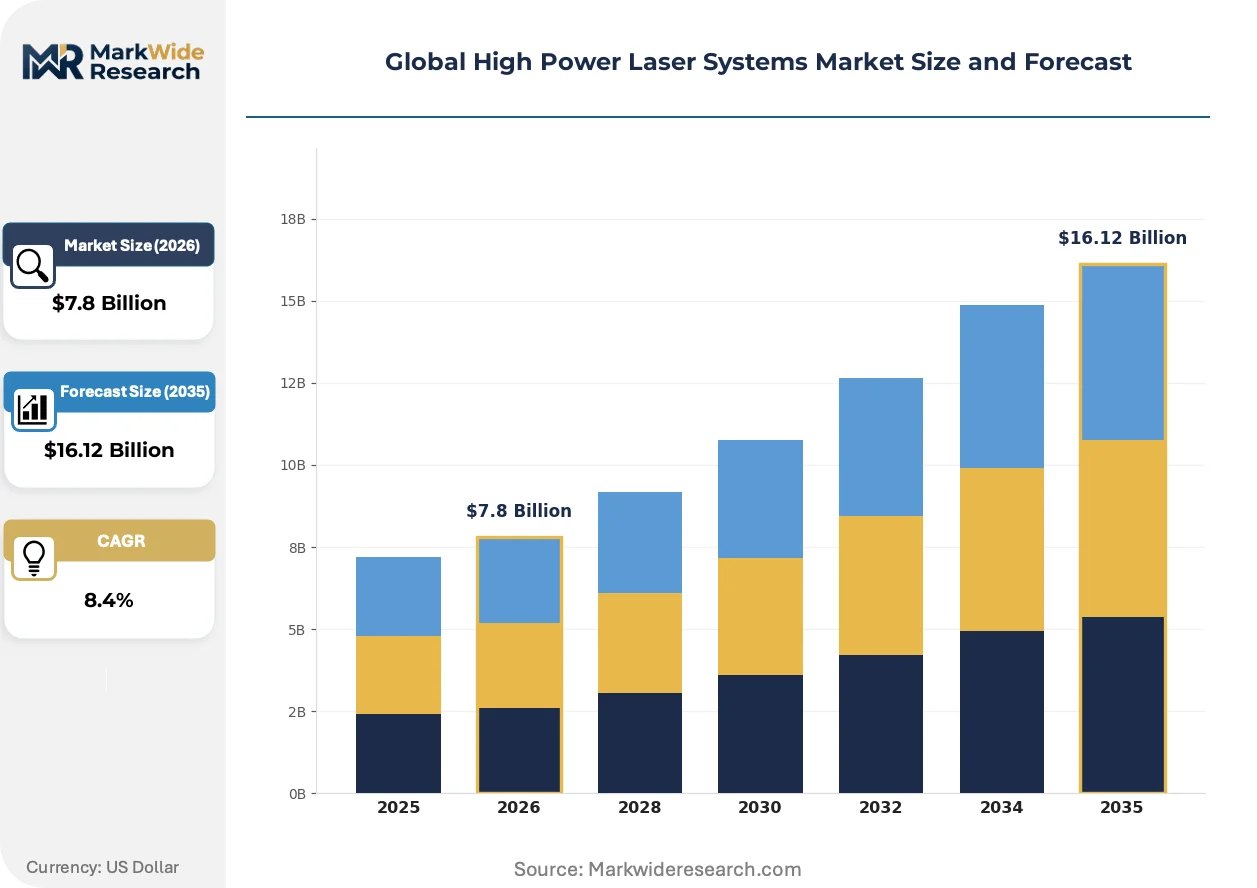
Market Dynamics
Defense procurement cycles and industrial decarbonization mandates are converging to redirect capital toward solid-state and fiber architectures, compressing demand for legacy CO2 resonators across NATO-aligned manufacturing bases.
Growth Catalysts
- EU F-Gas Regulation phase-down:Refrigerant restrictions on CO2 laser cooling systems are accelerating capital migration toward ytterbium-doped fiber platforms in German and Italian metal fabrication.
- China's dual carbon goals under MEE:Steel sector retrofit mandates are displacing plasma cutting with high-efficiency fiber lasers in Hebei and Jiangsu province fabrication clusters.
- Battery welding demand:Electric vehicle OEMs in Stuttgart and Munich are specifying multi-kilowatt fiber systems for aluminum cell tab joining, tightening delivery timelines for qualified suppliers.
Market Restraints
- Rare-earth supply concentration:Neodymium and ytterbium oxide processing is dominated by Chinese refiners, exposing European gain-media fabricators to export quota volatility and ECHA REACH compliance costs.
- Technical ceiling in thick-section cutting:Fiber beam quality degrades above 20 kilowatts for titanium aerospace plate, preserving solid-state disk laser incumbency in defense airframe programs.
- Capital intensity of beam source manufacturing:Pump diode foundry equipment requires billion-dollar fab investments, constraining new entrants and preserving TRUMPF's captive supply advantage.
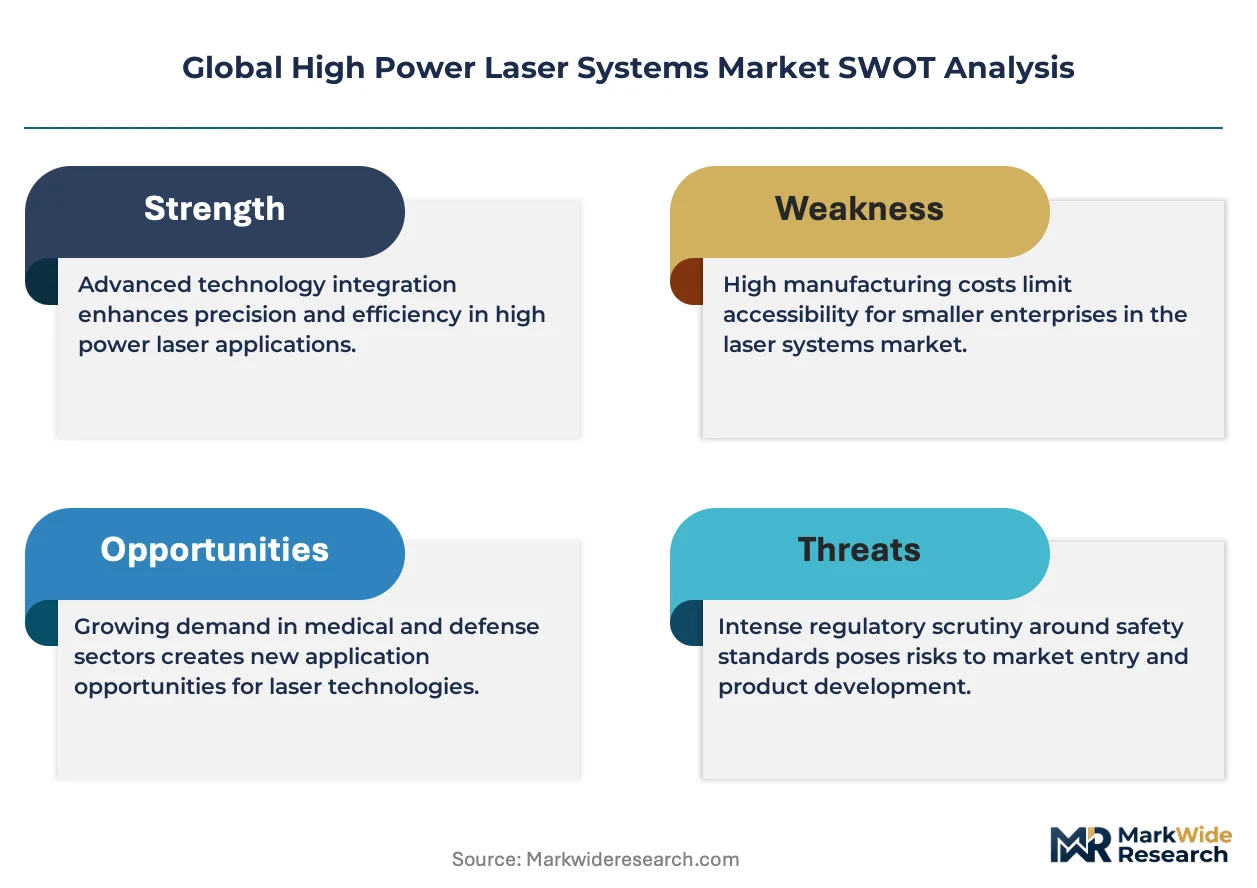
Strategic Opportunities
- India's PLI scheme for specialty steel:Domestic stainless and high-grade alloy production incentives are creating first-mover openings for fiber laser cutting system integrators in Gujarat and Maharashtra.
- Ultrafast amplifier convergence:Scientific research budgets in Max Planck and CNRS facilities are sustaining premium pricing for Coherent's chirped-pulse amplification platforms.
- Remote service channel innovation:Predictive maintenance subscriptions leveraging embedded beam-quality sensors are unbundling traditional after-sales contracts for automotive OEMs.
Industry Challenges
- ISO 11553 certification timeline:Safety validation for multi-axis processing machines extends 14-18 months, delaying supplier eligibility for European defense procurement channels.
- Optical engineer scarcity:Specialized expertise in non-linear optics and thermal lensing compensation is concentrating in Oxford, Massachusetts and Aachen research corridors, inflating compensation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Power Laser Systems Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Lasers, CO2 Lasers, Solid-State Lasers, Diode Lasers Technology: Q-Switching, Continuous Wave, Mode Locking, Pulsed, Disk Lasers Application: Material Processing, Scientific Research, Defense & Security, Communication, Additive Manufacturing End User Industry: Semiconductor Fabrication, Aerospace Manufacturing, Telecommunications, Oil & Gas Extraction |
| Companies Covered | TRUMPF, IPG Photonics Corporation, Coherent, Han's Laser Technology Industry Group, Prima Industrie, Bystronic, Lumentum Holdings, Jenoptik, MKS Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Power Laser Systems Market Shifts & Advancements
Beam delivery architectures and regulatory chemistry are forcing capital reallocation across the supplier base, while buyer consolidation in automotive and defense is compressing vendor qualification cycles.
Fiber laser platforms are decomposing the installed base of CO2 resonators in sheet metal processing. German automotive OEMs have specified fiber systems for 80 percent of new capacity additions since 2022. The technology is decomposing maintenance revenue pools that sustained legacy gas laser service networks for decades.
REACH restrictions on rare-earth processing chemicals are constraining European supply chains for neodymium-doped gain media. ECHA registration requirements for ytterbium and thulium compounds have extended raw material qualification timelines by 8-12 months. Solid-state disk laser manufacturers in Germany are responding by qualifying alternative dopant chemistries and securing long-term offtake agreements with non-EU refiners.
Automotive OEMs are consolidating vendor panels around suppliers with captive pump diode production. Tier-1 fabricators in Baden-Württemberg are unbundling equipment purchase from service contracts, favoring laser-as-a-service models with guaranteed uptime clauses. This pattern is most visible in Germany's precision manufacturing corridor, where battery welding specifications now mandate 99.5 percent beam stability over 10,000-hour operational windows.
Global High Power Laser Systems Market Segmentation
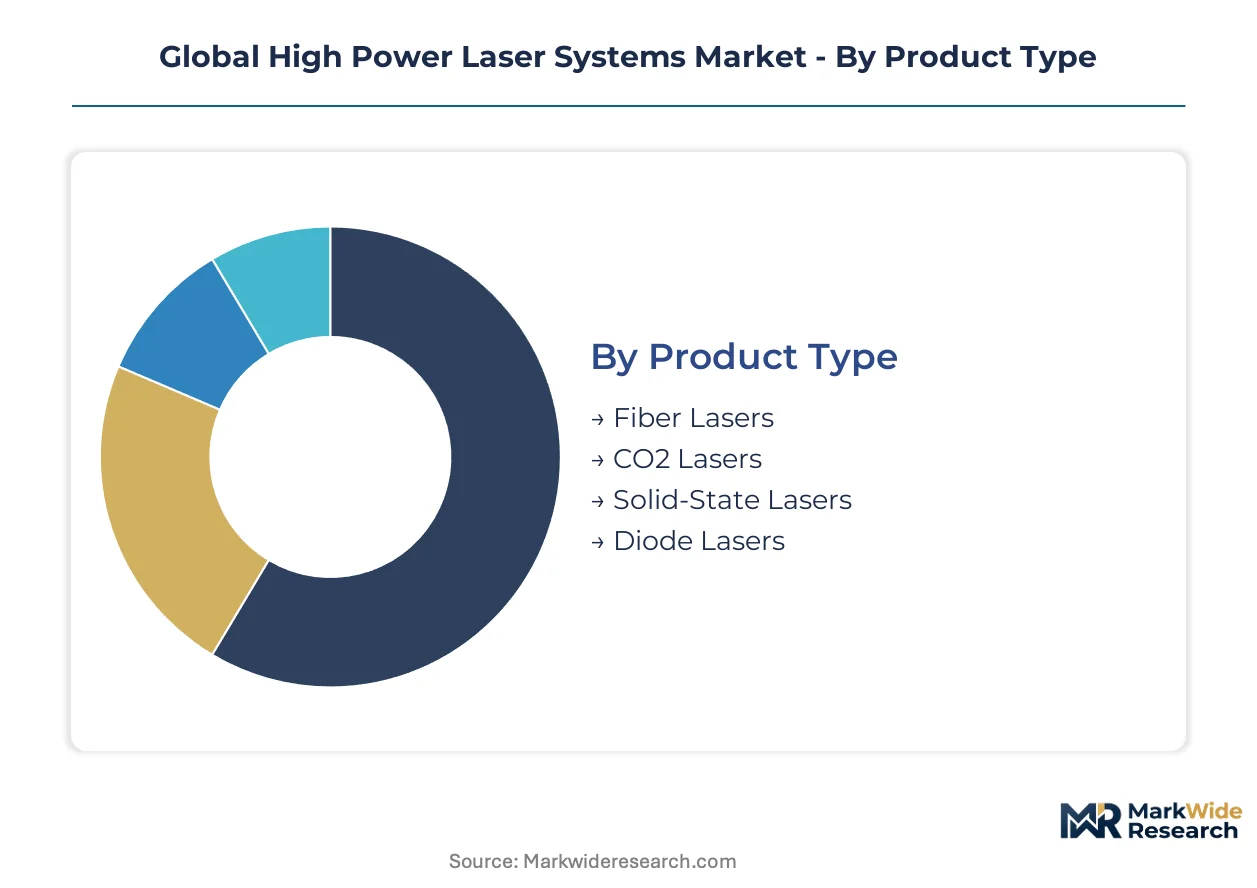
High power laser systems fragment across four distinct dimensions, each channeling procurement decisions through different validation requirements and margin structures. Product type determines capital intensity and service attach rates, while application context dictates regulatory compliance burdens and contract duration.
Product Type:
Channel mix varies sharply by product architecture, with fiber and CO2 platforms flowing through established industrial distributors while solid-state and diode systems require direct OEM engagement for specification support.
- Fiber Lasers:Ytterbium-doped fiber gain media deliver wall-plug efficiency exceeding thirty percent with minimal thermal management. Stuttgart and Munich automotive OEMs specify these systems for battery welding, tightening delivery timelines for qualified suppliers under ISO 11553 certification.
- CO2 Lasers:Gas discharge tubes operating at 10.6 micrometer wavelength retain installed base in thick-section acrylic and wood processing. EU F-Gas Regulation refrigerant restrictions are accelerating capital migration toward fiber platforms in German and Italian metal fabrication.
- Solid-State Lasers:Nd:YAG and thin-disk architectures dominate aerospace titanium cutting where beam quality requirements exceed fiber capabilities.
- Diode Lasers:Direct-emitting bars and stacks serve as pump sources and standalone cladding applications with lower brightness but superior electrical efficiency.
Fiber lasers dominate installed base. Solid-state platforms are where expansion concentrates in defense airframe programs.
Technology:
Cost tier stratification separates scientific research budgets from industrial procurement, with mode locking and disk architectures commanding premium pricing against volume-driven continuous wave systems.
- Q-Switching:Electro-optic or acousto-optic modulation generates nanosecond pulse formats for target designation and countermeasure systems. Defense procurement cycles across NATO member states sustain demand for this architecture in directed-energy weapon programs.
- Continuous Wave:Uninterrupted emission enables maximum average power delivery for cutting and welding speed. China's steel sector retrofit mandates under MEE dual carbon goals are displacing plasma cutting with high-efficiency fiber implementations in Hebei and Jiangsu provinces.
- Mode Locking:Ultrafast femtosecond pulse generation supports scientific research applications in Max Planck and CNRS facilities.
- Pulsed:Microsecond to millisecond duration pulses optimize heat-affected zone control in precision drilling applications.
- Disk Lasers:Thin-disk ytterbium architectures achieve multi-kilowatt output with diffraction-limited beam quality for aerospace plate cutting.
Continuous wave systems anchor volume shipments. Q-switching platforms are climbing the fastest in defense procurement channels.
Application:
Customer type segmentation separates capital equipment buyers from research grant recipients, with material processing and defense procurement following multiyear qualification cycles while scientific research operates on annual budget approvals.
- Material Processing:Cutting, welding, and surface treatment operations in metal fabrication and automotive manufacturing. German precision manufacturing corridors around Stuttgart specify multi-kilowatt systems for electric vehicle battery production with 99.5 percent beam stability requirements.
- Scientific Research:Spectroscopy, microscopy, and particle acceleration applications in national laboratory facilities. ECHA REACH restrictions on rare-earth processing chemicals constrain European supply chains for neodymium-doped gain media in research-grade systems.
- Defense & Security:Directed-energy weapons, target designation, and countermeasure systems. NATO member state procurement programs are expanding directed-energy weapon development.
- Communication:Free-space optical links and satellite-based laser terminals for secure data transmission.
- Additive Manufacturing:Powder bed fusion and directed energy deposition for aerospace component repair and production.
Material processing commands the largest equipment footprint. Additive manufacturing is gaining share fastest as aerospace OEMs qualify laser-based production methods.
End User Industry:
Geographic concentration of end users shapes regional service infrastructure requirements, with semiconductor fabrication clustering in East Asian manufacturing zones and aerospace manufacturing concentrated in defense procurement corridors.
- Semiconductor Fabrication:Annealing, doping, and inspection applications in wafer processing. India's PLI scheme for specialty steel is creating adjacent demand for precision cutting in Gujarat and Maharashtra fabrication clusters.
- Aerospace Manufacturing:Titanium and aluminum structural component processing for commercial and defense airframes. Thick-section titanium cutting demands beam quality unattainable through fiber architectures alone, preserving solid-state disk laser incumbency.
- Telecommunications:Undersea cable manufacturing and fiber optic component processing.
- Oil & Gas Extraction:Pipeline welding and hardfacing applications in upstream and midstream infrastructure.
Semiconductor fabrication drives highest average selling prices. Aerospace manufacturing is where supplier qualification cycles are compressing most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation refrigerant phase-downs and China's MEE dual carbon mandates are redirecting capital toward fiber architectures across major manufacturing economies. Procurement patterns diverge sharply between defense-heavy NATO corridors and industrial retrofit markets in East Asia.
United States
Defense procurement cycles sustain directed-energy weapon development across Pentagon research corridors. FDA laser product performance standards govern medical device classifications, creating compliance friction for imported systems. Oxford, Massachusetts anchors North American fiber laser manufacturing with concentrated pump diode fabrication capacity.
Germany
Automotive OEMs in Stuttgart and Munich specify multi-kilowatt fiber systems for electric vehicle battery welding with 99.5 percent beam stability requirements. ISO 11553 safety certification rotates supplier eligibility across defense and automotive procurement channels. Baden-Württemberg's precision manufacturing corridor concentrates demand for qualified system integrators.
China
Steel sector retrofit mandates under MEE dual carbon goals displace plasma cutting with high-efficiency fiber lasers in Hebei and Jiangsu province fabrication clusters. GB standards for industrial laser safety administered by SAMR create non-tariff barriers for imported systems lacking domestic certification. Rare-earth processing concentration for ytterbium and neodymium oxide exposes supply chains to export quota volatility.
India
PLI scheme incentives for specialty steel production create first-mover openings for fiber laser cutting system integrators. BIS certification requirements for industrial equipment extend qualification timelines for foreign suppliers. Gujarat and Maharashtra fabrication clusters concentrate emerging demand from domestic stainless and high-grade alloy producers.
Japan
METI industrial technology roadmaps prioritize solid-state architectures for aerospace component manufacturing. JIS standards for laser processing equipment create technical barriers for non-domestic suppliers. Nagoya aerospace manufacturing corridors sustain demand for disk laser platforms in titanium airframe applications.
Global High Power Laser Systems Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and certification depth. The vendor base stratifies between billion-dollar beam source fabricators and regional system integrators. Three archetypes dominate: captive diode producers controlling delivery timelines, scientific-grade specialists commanding premium pricing, and volume-driven Chinese fabricators exploiting domestic rare-earth access. M&A activity concentrates on pump diode foundry assets, while strategic partnerships bridge ISO certification gaps for emerging market entry.
Among German-headquartered incumbents, TRUMPF GmbH + Co. KG exemplifies the captive supply archetype through in-house pump diode production. IPG Photonics Corporation anchors North American positioning with Massachusetts-based manufacturing infrastructure. Coherent, Inc. occupies the scientific-research tier where ultrafast amplifier platforms sustain differentiated pricing. These three represent the structural poles—European industrial integration, North American scale manufacturing, and precision scientific instrumentation—around which competitive dynamics organize.
| Leading Market Players |
|---|
| TRUMPF |
| IPG Photonics Corporation |
| Coherent |
| Han's Laser Technology Industry Group |
| Prima Industrie |
| Bystronic |
| Lumentum Holdings |
| Jenoptik |
| MKS Instruments |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts for ytterbium and neodymium oxide lock in supply access for European gain-media fabricators while capping price volatility exposure from Chinese export quotas. These arrangements bind TRUMPF and IPG Photonics to multi-year purchase commitments, embedding raw material costs into equipment pricing and compressing margins for non-integrated competitors.
Pricing Analysis
Certification level (ISO 11553/FDA-grade) creates the primary spread between premium system integrators and commodity equipment vendors. Three-tier pricing structure across premium, standard, and economy levels separates TRUMPF's captive-diode platforms from regional assemblers sourcing pump sources externally. Cost compression in mid-tier fiber systems is intensifying because Chinese fabricators exploit domestic rare-earth access. Automotive OEMs in Stuttgart demonstrate lowest price sensitivity due to uptime-guarantee requirements, while Indian specialty steel fabricators under PLI schemes drive hardest bargain on capital outlay.
Supply Chain Analysis
Inventory buffers for pump diode foundry equipment extend 18-24 months, tethering delivery timelines to billion-dollar fab capacity in Germany, the United States, and China. Ytterbium-doped fiber, CO2 gas discharge tubes, and thin-disk gain media feed from geographically concentrated upstream nodes. Single-source vulnerability concentrates in Chinese rare-earth refiners dominating neodymium and ytterbium oxide processing. Distribution runs through direct OEM engagement for solid-state platforms and established industrial distributors for fiber and CO2 architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement cycles are lifting from trough levels as NATO member states accelerate directed-energy weapon programs, positioning the market for cyclical recovery alongside industrial retrofit mandates in Chinese steel fabrication.
For Market Incumbents: Compound captive supply advantages by securing long-term offtake agreements with non-EU rare-earth refiners ahead of ECHA REACH restriction tightening. Add beam-source capacity in Oxford, Massachusetts to defend against Chinese fiber laser volume entrants exploiting domestic ytterbium access. Prioritize ISO 11553 certification pipeline acceleration to maintain eligibility in European defense procurement channels. For New Entrants and Emerging Players: Differentiate on remote service channel innovation, unbundling predictive maintenance subscriptions from traditional equipment sales to bypass TRUMPF's delivery timeline control. Target India's PLI-driven specialty steel fabrication clusters in Gujarat and Maharashtra where first-mover openings exist for qualified system integrators. Lead with laser-as-a-service models featuring guaranteed uptime clauses to displace capital-intensive purchase decisions. For Investors and Strategic Acquirers: Pump diode foundry assets with captive ytterbium supply represent the highest-conviction acquisition archetype given billion-dollar fab barriers and concentrated optical engineering talent. Long-term viability hinges on exposure to defense procurement durability rather than industrial capital expenditure cyclicality. Watch divergence between EU F-Gas Regulation phase-down schedules and China's dual carbon implementation timelines as inflection indicator for CO2 laser obsolescence velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Pump Diode Capacity Expansion | TRUMPF's in-house foundry control locks delivery timelines for multi-kilowatt defense contracts. |
| ISO 11553 Certification Acceleration | Shortened validation cycles open European automotive and defense procurement channels faster. |
| Long-term Rare-earth Offtake Agreements | Non-EU refiner partnerships hedge ECHA REACH compliance cost inflation for gain-media fabricators. |
| Remote Service Channel Development | Predictive maintenance subscriptions unbundle after-sales revenue from equipment sales for automotive OEMs. |
| Laser-as-a-Service Model Deployment | Uptime-guarantee contracts reduce capital barriers for Indian PLI scheme beneficiaries in specialty steel. |
Research Methodology
Initial hypotheses were tested against primary input from defense procurement officers, automotive manufacturing engineers, laser system integrators, and rare-earth supply chain managers and refined through secondary validation. Primary fieldwork drew from equipment specification reviews, contract tender documentation, and technical qualification timelines. Secondary sources included SEC filings from listed beam-source manufacturers, ECHA REACH registration databases, EU defense procurement notices, and Chinese MEE policy implementation records. Bottom-up unit economics for fiber and solid-state platforms were triangulated against top-down market sizing from capital expenditure disclosures.
Variance decomposition across product architecture, application vertical, and geographic regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled encompassed laser type, pulse format technology, end-use application, and end-user industry concentration. CAGRs were derived from installed base evolution, replacement cycle acceleration, and penetration rate assumptions. Industry-specific forecast inputs incorporated EU F-Gas Regulation compliance cost trajectories and China's MEE dual carbon retrofit mandate implementation velocity.
The analysis sits within stated boundaries; outcomes outside sustained defense procurement commitment or rare-earth export quota stability would require recalibration. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory phase-down schedules. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Asia-Pacific Industrial Centrifuge Market
Industrial Equipment
Global Servo Presses Market
Industrial Equipment
Global Industrial Weighing Machines Market
Industrial Equipment
Diaphragm Coupling Market
Industrial Equipment
Mounted Bearing Market
Industrial Equipment
Laser Drilling Market
Industrial Equipment
Glass Washer Market
Industrial Equipment
Ceramic Roller Bearings Market
Industrial Equipment
UV Conveyor Systems Market
Industrial Equipment
Asia Pacific Industrial Embedded Systems Market
Industrial Equipment
Global Dosing Systems Market
Industrial Equipment
Glass Engraving Machines Market
Industrial Equipment
Global Safety Relays and Timers Market
Industrial Equipment
Global DC Drives Market
Industrial Equipment
Air Bearings Market
Industrial Equipment
Dust Extraction System Market