
 Tower Mounted Amplifier Market | 2026-2036
Tower Mounted Amplifier Market Size, Share, and Industry Trends Forecast 2026-2036
Tower Mounted Amplifier Market Outlook
The EU Green Deal is rebalancing capital allocation across European tower infrastructure, favoring amplifiers with lower thermal footprints and reduced power draw. CommScope leverages its integrated antenna-amplifier portfolio to capture upgrade cycles at major European operators. Kathrein sustains engineering leadership through precision-filtered multi-band designs that minimize intermodulation distortion. Rosenberger competes on connector-amplifier bundling, securing position at tier-one infrastructure vendors.
A tower mounted amplifier is an RF signal conditioning device installed at the antenna port of cellular base stations, typically operating across frequency ranges from 700 MHz to 3.5 GHz with noise figures below 2 dB to preserve uplink sensitivity. Its primary purpose is to compensate for cable losses between the antenna and baseband unit, extending coverage radius and improving data throughput in macro-cell deployments. Multi-band amplifiers command premium positioning as operators consolidate legacy and 5G spectrum onto single hardware platforms, while digital technology segments attract R&D investment for remote electrical tilt integration and software-defined gain control. Outdoor installation configurations dominate volume, though portable units gain traction in emergency response and temporary event coverage scenarios.
The FCC enforces RF emissions limits under OET-65 guidelines that directly constrain amplifier output power and spurious emission profiles in US deployments. ETSI harmonized standards across EU member states mandate CE marking for electromagnetic compatibility, creating a unified compliance threshold for cross-border equipment sales. India's TRAI tower radiation norms and BIS certification requirements add localized testing layers that filter out smaller non-compliant suppliers. Stakeholders must monitor spectrum auction schedules and corresponding band allocations to align amplifier development roadmaps with operator procurement timelines.
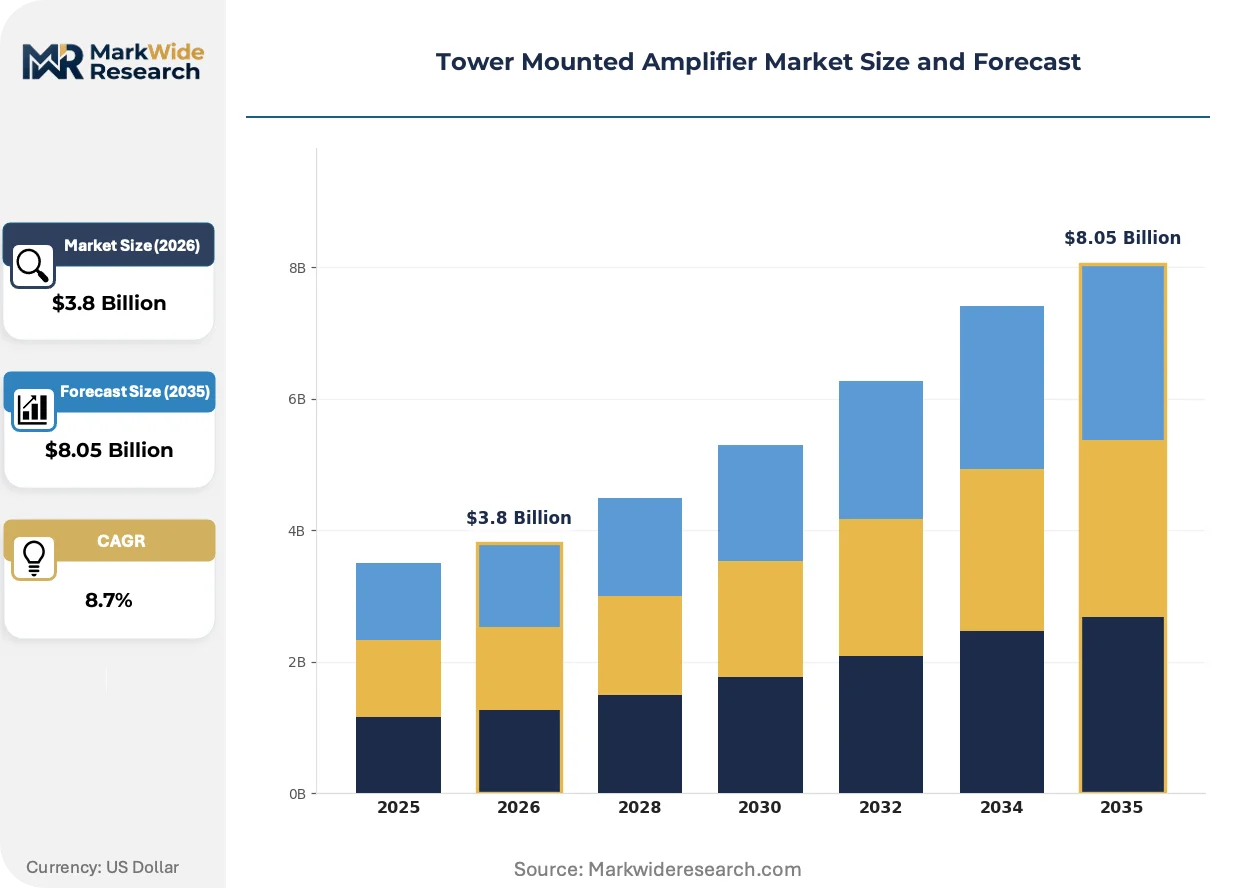
Market Dynamics
Wireless operators are consolidating multi-band spectrum onto single amplifier platforms, compressing procurement cycles and forcing hardware vendors to integrate digital control interfaces that enable remote electrical tilt and software-defined gain management.
Growth Catalysts
- 5G densification mandates:India's TRAI rural connectivity directives are amplifying tower infrastructure procurement volumes, with infrastructure sharing agreements reducing per-operator deployment costs.
- EU F-Gas Regulation:The European Union's phasedown of hydrofluorocarbon coolants is accelerating shifts toward thermally efficient RF amplification architectures with lower power draw.
- Multi-band consolidation:Baseband integration of legacy 4G and new 5G spectrum blocks onto unified hardware platforms is extending replacement cycles while expanding per-unit functionality.
Market Restraints
- GaN substrate supply concentration:Gallium nitride wafer production clusters in East Asian foundries, exposing amplifier manufacturers to single-source disruption risks and input price volatility.
- FCC OET-65 emission ceilings:The Federal Communications Commission's RF exposure limits constrain output power thresholds, forcing hardware derating that compresses effective coverage radius per unit.
- Copper coaxial cable persistence:Legacy feeder infrastructure at established macro-cell sites creates impedance-matching complexity that slows all-digital amplifier adoption.
Strategic Opportunities
- Emergency response portability:Rapid-deploy amplifier units for disaster recovery and temporary event coverage represent an underdeveloped application segment with premium pricing potential.
- Remote electrical tilt integration:Convergence of antenna-amplifier hardware with software-defined beam steering creates service-revenue streams beyond equipment sales.
- India PLI scheme alignment:Production-linked incentive frameworks for telecom equipment manufacturing are attracting component localization investments that reduce import duty exposure.
Industry Challenges
- RF systems engineering scarcity:Specialized expertise in intermodulation distortion mitigation and filter precision design concentrates at established vendors, constraining new entrant scale-up.
- Multi-certification timelines:Simultaneous FCC, CE marking, and BIS compliance testing extends product launch schedules by 8-14 months for multi-territory deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tower Mounted Amplifier Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Power Amplifiers, High Power Amplifiers, Dual Band Amplifiers, Multi Band Amplifiers End User: Telecommunications, Broadcasting, Public Safety, Wireless Service Providers Installation: Outdoor, Indoor, Portable, Fixed Technology: Analog, Digital, Hybrid, Software Defined |
| Companies Covered | CommScope, Amphenol Antenna Solutions, Kathrein, Kaelus, Rosenberger, Filtronic, Microdata Telecom, Comba Telecom, Westell Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tower Mounted Amplifier Market Strategic Shifts
Digital signal processing architectures are displacing analog amplification chains, enabling real-time gain adjustment and predictive maintenance while compressing hardware form factors and thermal footprints.
GaN-on-SiC power transistors are decentralizing base station amplifier design by enabling higher power density at reduced thermal dissipation. Tier-one infrastructure vendors in Germany and South Korea are adopting these wide-bandgap semiconductors for 3.5 GHz massive MIMO deployments. The technology is decentralizing thermal management costs from active cooling systems toward passive heat-sink designs that reduce operational expenditure.
The EU F-Gas Regulation is mandating refrigerant phase-downs that directly impact amplifier cooling system specifications. Equipment vendors serving European operators must now qualify alternative thermal architectures or absorb compliance retrofit costs. Macro-cell outdoor installations face the steepest redesign requirements, with several manufacturers accelerating heat-pipe and vapor-chamber development programs.
Operators are unbundling hardware procurement from long-term maintenance contracts, compressing vendor lock-in and expanding third-party service provider participation. Tower companies in India and Brazil are driving this shift, separating amplifier acquisition from installation and commissioning workflows. This restructuring is most visible in markets with active infrastructure-sharing frameworks, where neutral-host economics favor modular, multi-operator-compatible equipment.
Tower Mounted Amplifier Market Segmentation
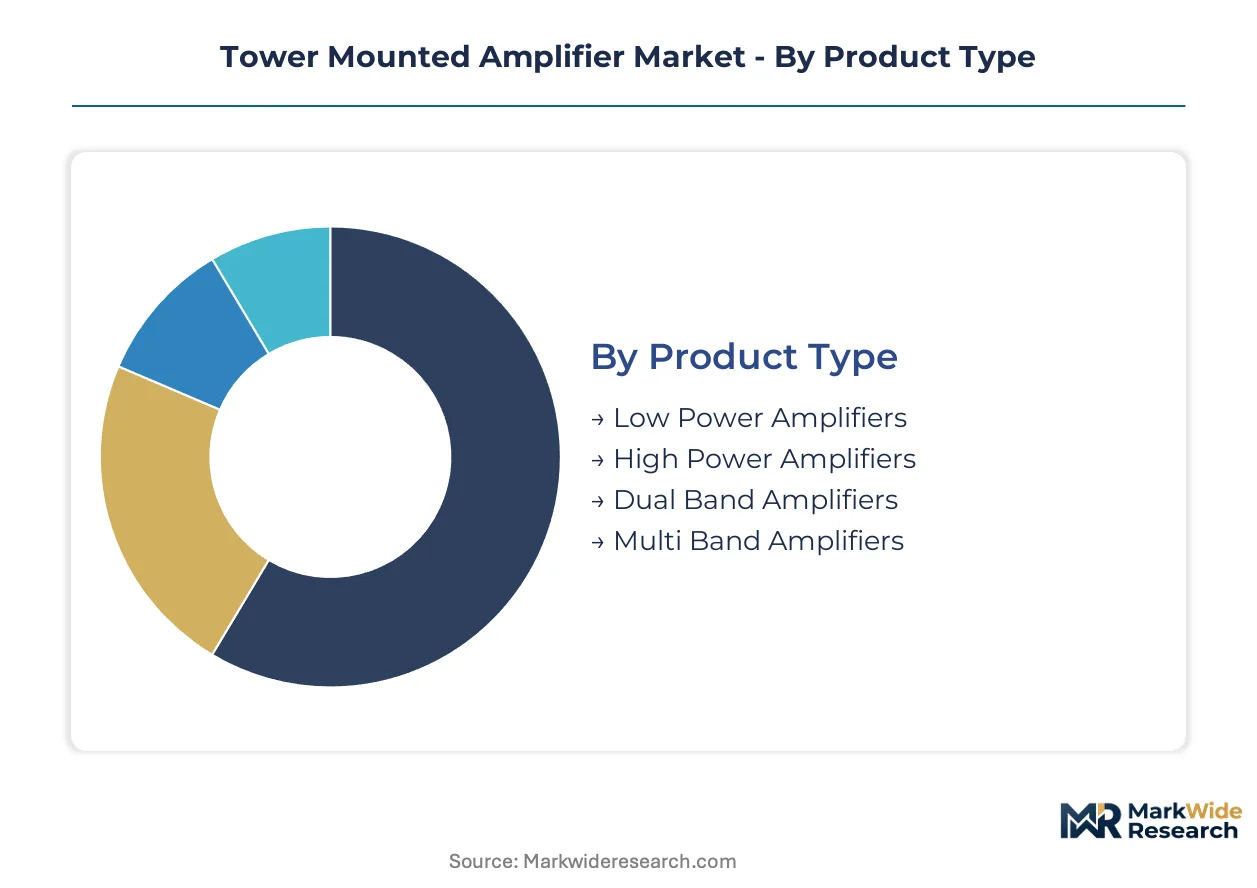
Segmentation in the tower mounted amplifier market reflects divergent capital deployment strategies across operator archetypes. Infrastructure sharing agreements and spectrum consolidation mandates are compressing procurement cycles for multi-capability hardware while elevating total cost of ownership scrutiny.
Product Type:
Capital intensity varies sharply across power classes and band integration levels, with multi-band platforms demanding the steepest upfront engineering investment.
- Multi Band Amplifiers:These platforms consolidate legacy 4G and 5G spectrum blocks onto unified hardware architectures with software-defined gain control. Indian tower companies under TRAI rural connectivity directives are procuring these units to reduce per-site equipment counts and simplify infrastructure sharing agreements.
- Dual Band Amplifiers:Operating across paired frequency ranges with integrated diplexers, these units balance coverage extension against hardware complexity. European operators subject to EU F-Gas Regulation thermal efficiency mandates are specifying these for macro-cell retrofits where full multi-band migration remains capital-constrained.
- High Power Amplifiers:GaN-on-SiC transistor designs deliver elevated output with reduced thermal dissipation.
- Low Power Amplifiers:Compact form factors target small-cell densification and indoor distributed antenna systems.
Multi Band Amplifiers absorb the bulk of installed capacity; Dual Band Amplifiers are expanding most quickly.
End User:
Procurement authority concentrates with entities controlling physical tower assets rather than spectrum licensees alone.
- Wireless Service Providers:These operators drive volume through direct ownership of macro-cell infrastructure, specifying amplifiers with remote electrical tilt integration and predictive maintenance telemetry. India's infrastructure sharing frameworks are shifting procurement toward neutral-host-compatible units that accommodate multiple tenants.
- Telecommunications:Incumbent fixed-line operators expanding wireless backhaul and fixed wireless access deployments require amplifiers optimized for point-to-multipoint transmission with stringent noise figure specifications.
- Public Safety:Mission-critical voice and data networks demand hardened amplifiers with redundant power architectures.
- Broadcasting:Terrestrial television and radio transmission uses specialized high-linearity amplification with intermodulation distortion suppression.
Wireless Service Providers command the dominant share of procurement volume; Public Safety exhibits the steepest expansion trajectory.
Installation:
Environmental exposure ratings and deployment velocity requirements create distinct total cost of ownership profiles across configuration types.
- Outdoor:Weather-sealed enclosures with passive thermal management dominate macro-cell deployments, absorbing the majority of capital expenditure in 5G densification programs. EU F-Gas Regulation compliance is accelerating heat-pipe and vapor-chamber adoption to eliminate refrigerant-dependent cooling.
- Portable:Rapid-deploy units with integrated power and backhaul modules serve emergency response and temporary event coverage, commanding premium pricing in disaster recovery scenarios.
- Fixed:Permanent installations with hardwired power and fiber connectivity provide baseline coverage.
- Indoor:Lower power ratings and reduced thermal output suit distributed antenna system integration.
Outdoor configurations represent the largest installed base; Portable units are climbing the fastest.
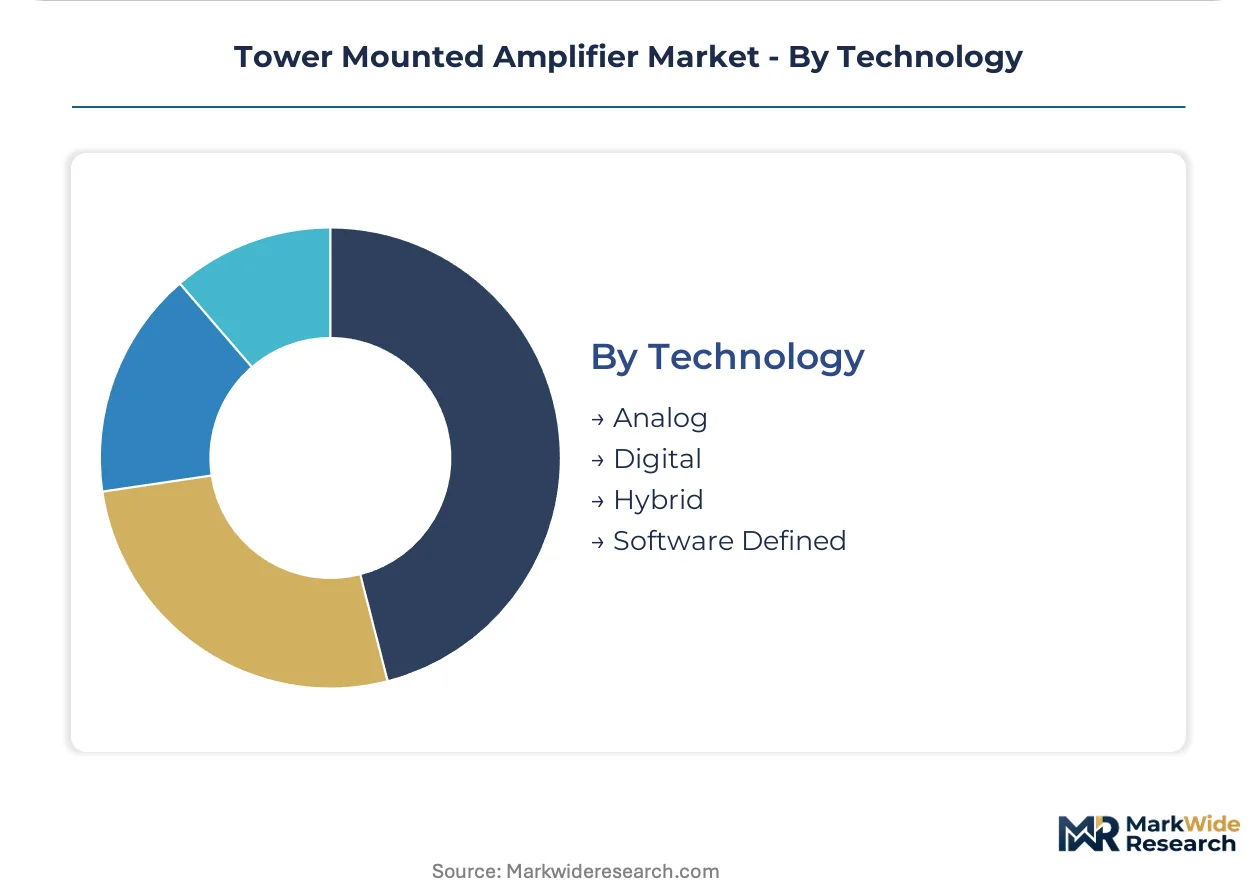
Technology:
Signal processing architecture determines upgrade pathway flexibility and long-term operational expenditure trajectories.
- Digital:Software-defined gain control and real-time adaptive filtering enable remote configuration and predictive maintenance, compressing field service requirements. Tier-one infrastructure vendors in Germany and South Korea are specifying these for 3.5 GHz massive MIMO deployments.
- Hybrid:Analog RF chains with digital predistortion and envelope tracking balance performance against power consumption, appealing to operators with mixed legacy and modern baseband equipment.
- Analog:Conventional amplification chains persist in cost-sensitive deployments with stable spectrum allocations.
- Software Defined:Fully programmable architectures enable dynamic reconfiguration across frequency bands and modulation schemes.
Digital platforms capture the majority of new procurement investment; Software Defined architectures are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of GaN-on-SiC substrates concentrates in East Asian foundries, while consumption tilts toward 5G densification markets in India, Germany, South Korea, and the United States where tower infrastructure procurement is accelerating.
United States
Wireless carriers are consolidating spectrum holdings across C-band and mmWave allocations, driving amplifier refresh cycles at macro-cell sites. FCC OET-65 emission limits constrain output power thresholds, forcing hardware derating that shapes procurement specifications. Tower clusters in Dallas-Fort Worth and Atlanta are seeing concentrated deployment of multi-band platforms as operators unify 4G and 5G infrastructure.
Germany
Deutsche Telekom and Vodafone are specifying thermally efficient amplifiers for 3.5 GHz massive MIMO rollouts under EU Green Deal capital allocation frameworks. The EU F-Gas Regulation mandates refrigerant phase-downs that eliminate conventional cooling systems from outdoor installations. Engineering activity concentrates in Bavaria, where precision-filtered amplifier designs are being qualified for cross-border EU deployments.
India
TRAI rural connectivity directives are amplifying tower infrastructure procurement volumes, with infrastructure sharing agreements reducing per-operator deployment costs. BIS certification requirements and tower radiation norms add localized testing layers that filter supplier participation. Manufacturing investments under the PLI scheme are clustering in Gujarat and Tamil Nadu, where component localization is reducing import duty exposure for tower-mounted hardware.
South Korea
SK Telecom and KT are deploying GaN-on-SiC amplifiers for dense urban 5G coverage in Seoul and Busan. National spectrum policy prioritizes 3.5 GHz and 28 GHz band utilization, creating demand for multi-band platforms with software-defined gain control. The Seongnam and Suwon corridor hosts concentrated R&D activity for antenna-amplifier integration with remote electrical tilt capabilities.
United Kingdom
EE and Vodafone are retrofitting macro-cell sites with dual-band amplifiers to balance coverage extension against capital constraints. Ofcom spectrum auctions are aligning procurement timelines with 700 MHz and 3.4-3.8 GHz band allocations. Deployment activity concentrates in the Midlands and Northern England, where rural coverage obligations are driving outdoor installation specifications with passive thermal management.
Tower Mounted Amplifier Market Competitive Environment
The competitive structure tilts toward integrated antenna-amplifier portfolios and multi-band platform consolidation. Tier-one infrastructure vendors command premium positioning through engineering relationships with major operators, while mid-scale specialists compete on certification agility and regional price positioning. Two strategic archetypes dominate: integrated system houses bundling antenna-amplifier hardware, and component specialists focusing on filter precision and thermal efficiency. Competitive moves center on technology licensing for GaN-on-SiC integration and geographic expansion into India PLI-aligned manufacturing.
Among integrated system houses, CommScope and Kathrein exemplify the antenna-amplifier convergence archetype, with CommScope representing North American engineering integration and Kathrein occupying a position within German precision-filtered design traditions. Rosenberger anchors the connector-amplifier bundling segment, sitting within European tier-one infrastructure supply chains. These three companies collectively illustrate how vendor positioning stratifies across bundled hardware platforms, precision RF engineering, and component-level integration strategies.
| Leading Market Players |
|---|
| CommScope |
| Amphenol Antenna Solutions |
| Kathrein |
| Kaelus |
| Rosenberger |
| Filtronic |
| Microdata Telecom |
| Comba Telecom |
| Westell Technologies |
| Others |
Value Chain & Pricing Dynamics
Captive backward integration into GaN-on-SiC transistor fabrication anchors supply security for tier-one amplifier vendors while compressing procurement leverage for non-integrated competitors. This integration choice concentrates pricing power with German and South Korean system houses that control thermal architecture design, leaving module assemblers exposed to East Asian foundry pricing volatility.
Pricing Analysis
Margin tightening in multi-band platforms reflects GaN substrate supply concentration in East Asian foundries and the engineering premium commanded by precision-filtered designs. Pricing stratifies across CE-marked premium tiers for EU F-Gas compliant thermal architectures, standard tiers for legacy cooling configurations, and economy tiers for single-band analog units. Cost-down pressure accelerates because Indian tower companies under TRAI directives are consolidating procurement volumes under infrastructure-sharing frameworks. Wireless service providers exhibit the highest price sensitivity due to capital cycle compression, while public safety networks tolerate premium positioning for hardened redundant architectures.
Supply Chain Analysis
Dual-sourcing requirements from tier-one infrastructure vendors mandate multi-foundry qualification for GaN-on-SiC substrates, compressing single-source exposure despite East Asian production gravity. Raw material dependencies center on gallium nitride wafers, silicon carbide substrates, and precision-filter ceramics. Supply chain risk hinges on tariff exposure from component import duties into India under non-PLI-aligned procurement. Distribution runs through tower company neutral-host aggregators in India and Brazil, bypassing direct operator relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation erects a compliance moat that filters non-thermal-efficient competitors from European macro-cell retrofits, consolidating procurement access for qualified vendors.
For Market Incumbents: To counter margin compression from GaN substrate price volatility, deepen captive supply control over heat-pipe and vapor-chamber thermal architectures while accelerating CE-marked product qualification for EU Green Deal capital allocation frameworks. For New Entrants and Emerging Players: The PLI scheme in India opens a window for component localization investments that reduce import duty exposure, targeting Gujarat and Tamil Nadu manufacturing clusters with BIS-certified multi-band platforms for rural connectivity mandates. For Investors and Strategic Acquirers: Exit pathways concentrate in precision-filtered RF engineering specialists with established operator relationships, where long-term viability rests on GaN-on-SiC integration capabilities and multi-certification agility. Watch TRAI spectrum auction schedules as inflection indicators for Indian procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Integration Partnership | Enables higher power density for Deutsche Telekom 3.5 GHz massive MIMO specifications. |
| CE Marking Acceleration Program | Compresses EU F-Gas compliance timelines for outdoor installation thermal retrofits. |
| India PLI Manufacturing Localization | Reduces BIS certification friction and import duty exposure for tower company procurement. |
| Remote Electrical Tilt Convergence | Creates service-revenue streams beyond equipment sales through software-defined beam steering. |
| Emergency Response Portable Unit Launch | Captures premium pricing in disaster recovery scenarios with rapid-deploy configurations. |
Study Parameters
Independent corroboration across RF systems engineering directors, tower company procurement leads, and regulatory affairs specialists at major operators underwrites the qualitative findings. Primary fieldwork engaged infrastructure vendor sales engineers, GaN foundry account managers, and TRAI policy researchers. Secondary validation drew from FCC OET-65 filing databases, ETSI harmonized standards documentation, BIS certification registries, and customs records for GaN substrate trade flows. Bottom-up amplifier shipment estimates triangulated against top-down tower infrastructure capex disclosures.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by product type, installation configuration, technology architecture, and end-user procurement authority. The modeling framework incorporates spectrum auction schedules, rural connectivity mandate timelines, and thermal efficiency regulatory phase-ins as demand-side drivers. CAGRs derive from installed base replacement cycles, densification program intensities, and multi-band consolidation penetration curves.
The model assumes a particular technology adoption path; alternative pathways for digital signal processing displacement of analog chains would alter the outlook. Forecasts reflect assumptions regarding EU F-Gas compliance adherence, GaN-on-SiC cost curves, and Indian infrastructure-sharing framework stability. Deviation in TRAI rural connectivity funding allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Electrolytic Capacitor Market
Electronic Components
Audio Amplifier Market
Electronic Components
Serial Device Servers Market
Electronic Components
Screw Washer Market
Electronic Components
Capacitor Kits Market
Electronic Components
Electric Fuse Market
Electronic Components
Trackpad Market
Electronic Components
Global Ethernet Controller Market
Electronic Components
Blockchain in Electronic Component Market
Electronic Components
Microspeaker Market
Electronic Components
Audio Power Amplifier Market
Electronic Components
Global Active Electronic Components Market
Electronic Components
High Precision Mechanical Machine Components Market
Electronic Components
Europe PCB Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
Capacitive Stylus Pen Market