
 Soldering Iron Market | 2026-2036
Soldering Iron Market Size, Share, and Industry Trends Forecast 2026-2036
Soldering Iron Market Analytics
Temperature-controlled precision tiers is unwinding legacy low-wattage dominance across professional electronics workflows. Hakko leverages Japanese ceramic heater engineering to sustain premium positioning in OEM supply chains. Miniware competes through compact USB-C powered stations that anchor maker-space and field-repair segments. YIHUA dominates entry-level programmable stations across Southeast Asian contract manufacturers.
A soldering iron is a hand tool that delivers localized thermal energy through a metal tip, typically copper alloy with iron plating, to melt solder alloy and create permanent electrical or mechanical joints between workpieces. Its primary industrial purpose spans printed circuit board assembly, semiconductor packaging, and precision metal joining where controlled heat application prevents substrate damage. Soldering station configurations command the strongest margin pools as integrated temperature feedback and sleep-mode functions reduce tip oxidation and energy consumption. Electric soldering iron units retain volume leadership in high-throughput electronics assembly, while induction heating technology captures attention in automotive wire-harness operations requiring rapid thermal recovery.
RoHS and REACH frameworks in Europe restrict hazardous substances in solder alloys and tip coatings, compelling alloy reformulation and supply chain documentation. The EU F-Gas Regulation indirectly shapes gas soldering iron viability as propellant chemistry faces phase-down schedules. In the United States, OSHA workplace exposure limits and FCC electromagnetic compatibility standards filter product entry for imported equipment. Stakeholders must weigh tip material compliance costs against thermal performance trade-offs when specifying equipment for regulated end markets.
Market Dynamics
REACH-mandated lead-free solder alloys are forcing wholesale reformulation of tip metallurgy and thermal recovery specifications across professional equipment lines. Shenzhen contract manufacturers now specify ceramic heater stations with sub-10-second thermal recovery as baseline procurement criteria.
Growth Catalysts
- Electronics assembly densification:Shenzhen and Dongguan fabs drive procurement of temperature-controlled stations with sleep-mode functions that reduce tip oxidation. Automotive wire-harness operations in Germany demand induction heating for rapid thermal recovery.
- REACH alloy compliance:ECHA restrictions on lead-based solder compositions push manufacturers toward iron-nickel tip alloys with documented supply chain traceability. This creates replacement demand across European industrial maintenance operations.
- USB-C power delivery:Field repair technicians and maker-space operators adopt compact stations powered by standard laptop chargers, eliminating dedicated bench power requirements.
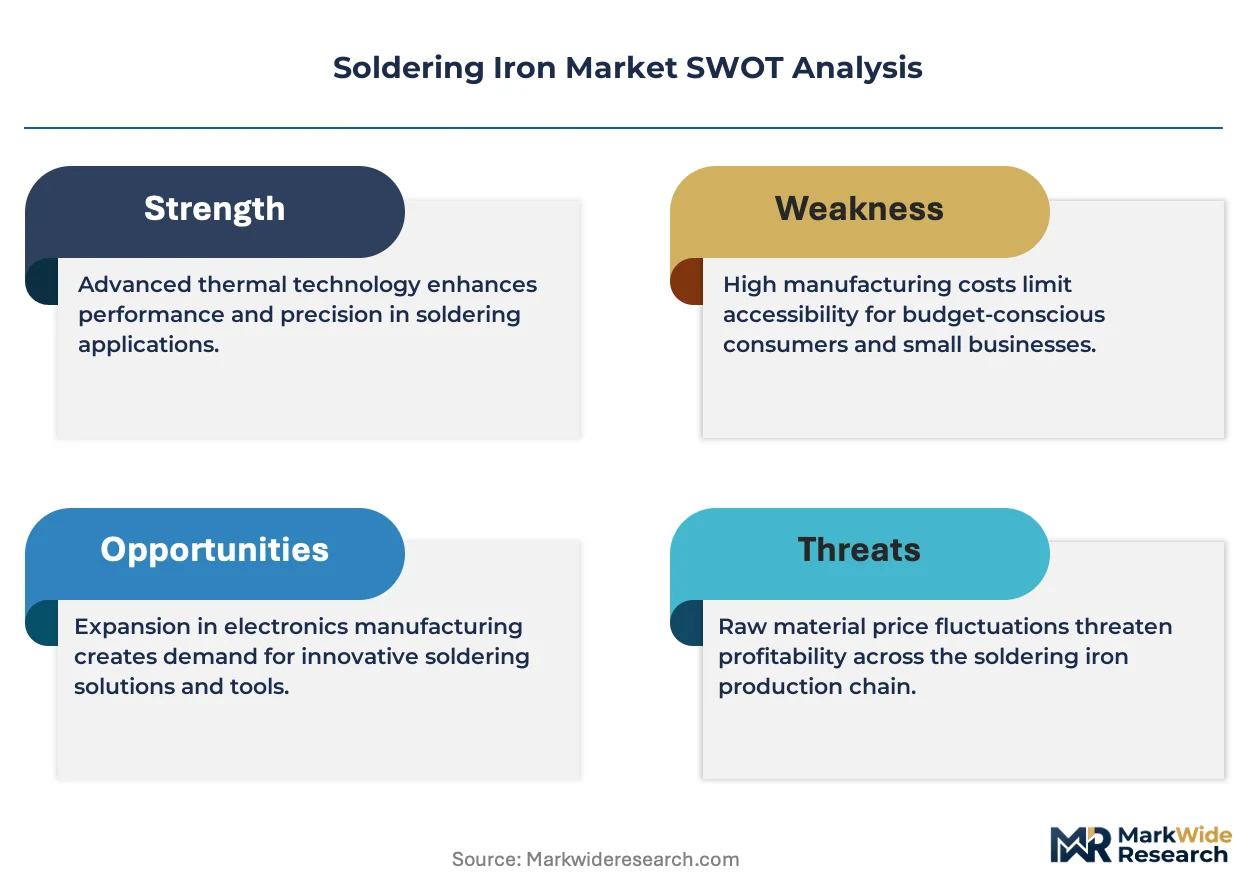
Market Restraints
- Copper price volatility:Tip manufacturing depends on copper alloy feedstock subject to LME price swings, compressing margin pools for mid-tier station producers.
- Heater element concentration:Japanese and Taiwanese suppliers dominate ceramic heater core production, creating single-source vulnerability for programmable station assemblers.
- Induction heating capital intensity:Automotive wire-harness adoption requires 3-5x equipment investment versus resistive heating, limiting penetration beyond Tier-1 suppliers.
Strategic Opportunities
- India electronics manufacturing:PLI scheme subsidies for mobile phone and component assembly create first-mover positioning for temperature-controlled station vendors in Noida and Sri City.
- EU F-Gas phase-down:Propellant restrictions on gas-powered portable irons create white space for battery-powered alternatives in European HVAC and refrigeration service channels.
- AI-assisted thermal profiling:Convergence of machine vision with closed-loop temperature control enables predictive tip-life management for high-mix electronics assembly.
Industry Challenges
- Lead-free soldering certification:IPC J-STD-001 qualification timelines stretch 12-18 months for new tip alloy formulations, delaying product launches.
- Legacy equipment integration:Smart station connectivity protocols conflict with 1990s-era factory automation infrastructure in Southeast Asian contract manufacturers.
- Tip geometry standardization:Proprietary cartridge designs lock buyers into single-vendor consumable streams, triggering procurement resistance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soldering Iron Market |
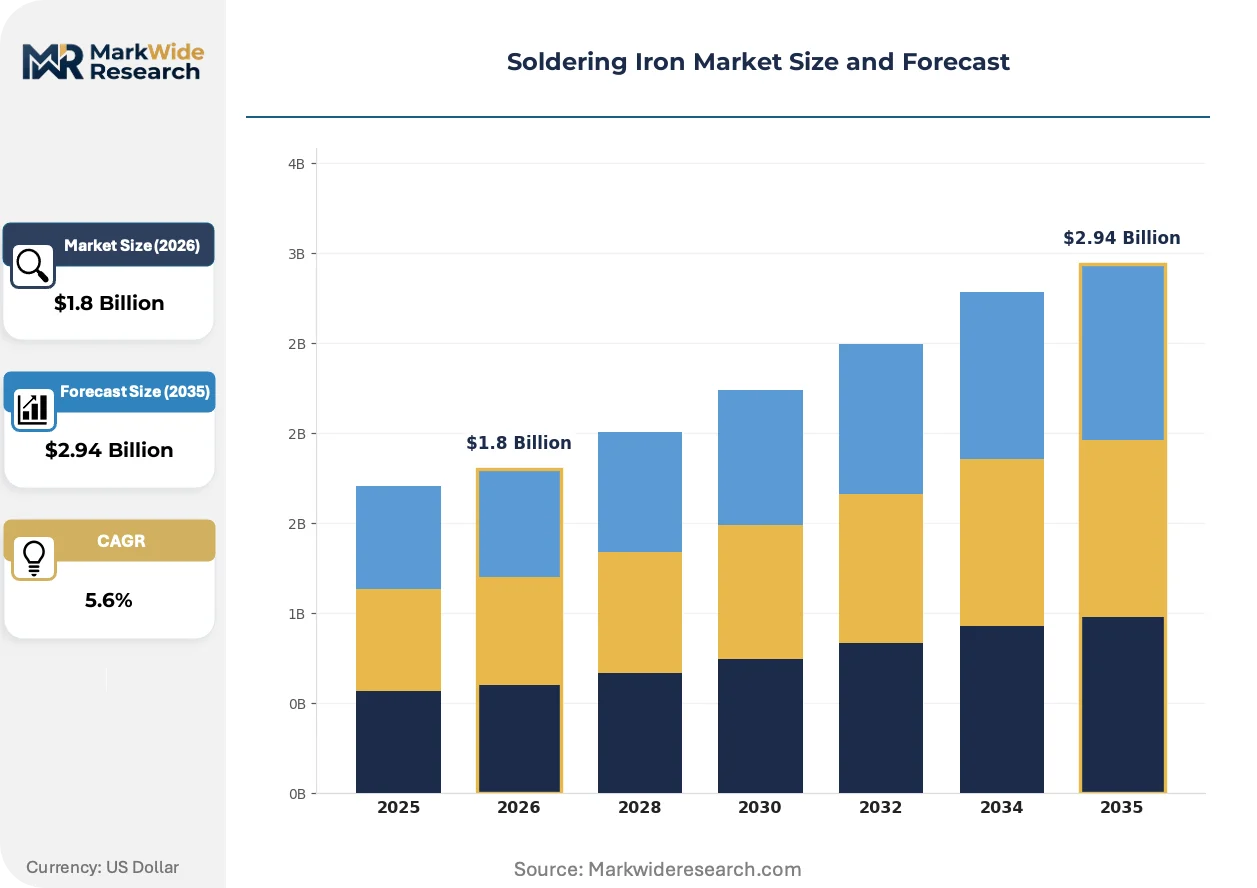
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Soldering Iron, Gas Soldering Iron, Soldering Station, Manual Soldering Tool Application: Electronics Assembly, Metalworking, Plumbing, DIY Projects End User: Manufacturers, Hobbyists, Technicians, Educational Institutions Technology: Thermal Conduction, Induction Heating, Temperature Control, Portable Heating |
| Companies Covered | FNIRSI, Miniware, Hakko, Hexacon, YIHUA, Weller, ALIENTEK, Antex, Pine64, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soldering Iron Market Evolving Landscape
Active thermal management intelligence is displacing fixed-wattage hardware across professional workflows. Ceramic heater engineering, closed-loop feedback systems, and predictive maintenance algorithms now define competitive differentiation.
Induction heating technology is displacing resistive element stations in automotive wire-harness operations. Tier-1 suppliers in Germany and the United States adopt these systems for 3-second thermal recovery during high-volume crimp-and-solder sequences. The technology compresses cycle times and reduces energy consumption per joint.
EU F-Gas Regulation phase-down schedules constrain propellant chemistry for gas-powered portable irons. HVAC service technicians across France and Germany face restricted access to traditional butane formulations. Battery-powered alternatives with USB-C charging are capturing field repair segments previously served by gas equipment.
Contract manufacturers now bundle station procurement with consumable tip contracts. Foxconn and Pegatron operations in Shenzhen negotiate multi-year agreements locking in cartridge supply alongside hardware deployment. This procurement consolidation squeezes standalone equipment vendors without captive consumable production.
Soldering Iron Market Segmentation
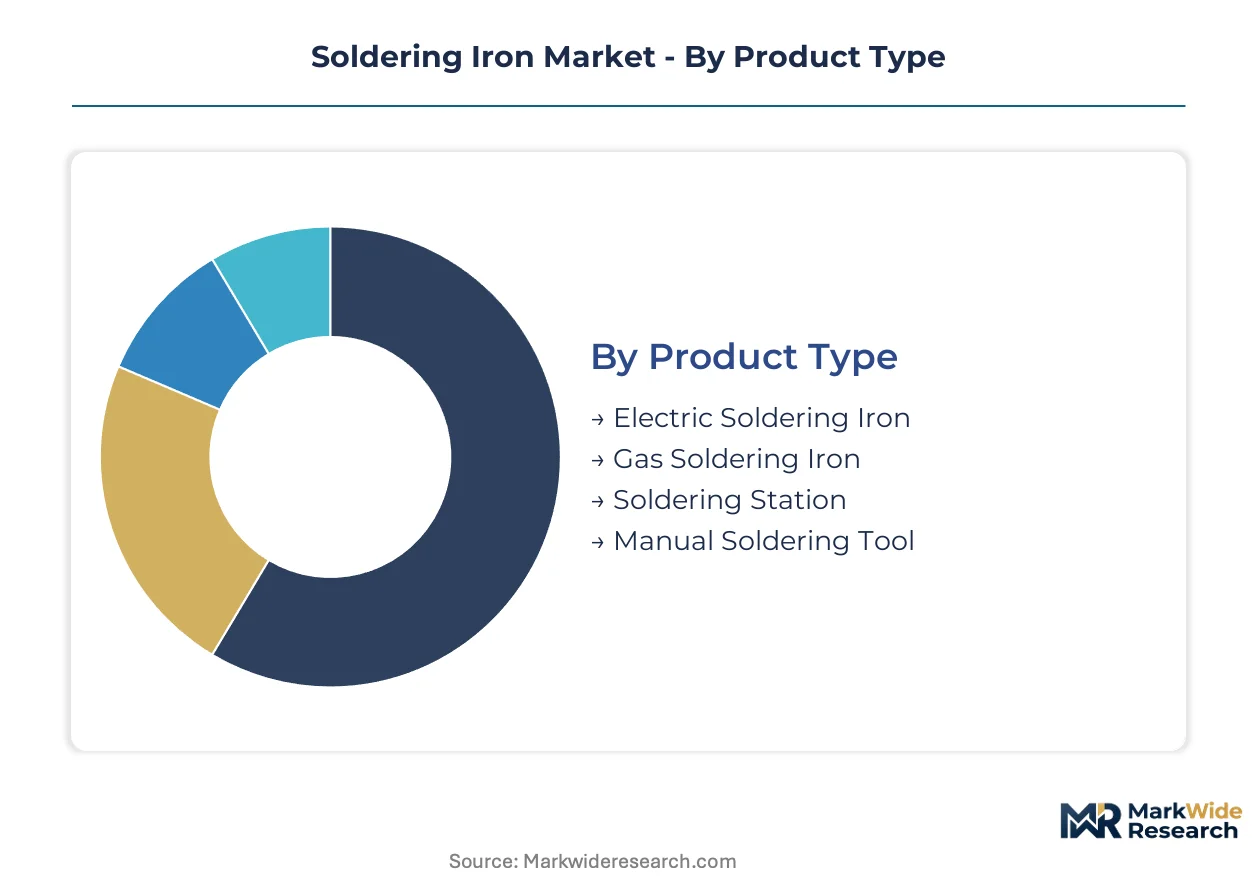
Soldering iron procurement patterns diverge sharply between high-volume contract manufacturing and intermittent field-service use. Equipment specifications, thermal recovery requirements, and consumable lock-in strategies vary dramatically across these deployment contexts.
Product Type:
Gas soldering irons face acute substitution pressure from USB-C powered alternatives as EU F-Gas Regulation restrictions tighten propellant chemistry availability.
- Electric Soldering Iron:Resistive element designs dominate high-throughput electronics assembly in Shenzhen and Dongguan fabs. Fixed-wattage units face displacement by temperature-controlled alternatives as IPC J-STD-001 certification requirements tighten.
- Soldering Station:Integrated ceramic heater systems with closed-loop feedback capture premium procurement from Foxconn and Pegatron operations. Sleep-mode functions reduce tip oxidation and energy consumption during shift changes.
- Gas Soldering Iron:Butane-powered portability serves HVAC technicians in European field service. REACH-compliant propellant reformulation compresses margin pools for legacy equipment vendors.
- Manual Soldering Tool:Unpowered copper-bit designs persist in plumbing and stained-glass applications. Artisan workshops in Germany and Japan sustain niche demand for traditional lead-tin solder work.
Electric soldering iron configurations retain volume leadership; soldering station systems hold the steepest expansion curve.
Application:
Electronics assembly commands the highest equipment specification density, with thermal profiling requirements cascading downstream to other segments.
- Electronics Assembly:Surface-mount and through-hole PCB operations demand sub-10-second thermal recovery. Shenzhen contract manufacturers specify ceramic heater stations with documented alloy traceability for REACH compliance.
- Metalworking:Jewelry fabrication and precision instrument repair utilize lower-wattage pencil irons. Artisan clusters in India and Thailand drive procurement of compact, voltage-switchable units.
- Plumbing:Copper pipe joining requires higher thermal mass tips with accelerated heat capacity. Building trades across the United States favor propane-fueled portable systems for site flexibility.
- DIY Projects:Maker-spaces and repair cafes adopt USB-C powered stations eliminating dedicated bench infrastructure. Compact form factors anchor demand from field technicians and hobbyist communities.
Electronics assembly captures the dominant revenue share; DIY project applications are climbing the fastest as portable power delivery standardizes.
End User:
Procurement consolidation among contract manufacturers is squeezing standalone equipment vendors without captive consumable production.
- Manufacturers:Foxconn and Pegatron operations negotiate multi-year agreements bundling station hardware with tip cartridge supply. Volume procurement locks in vendor relationships across shift rotations.
- Technicians:Field repair operators prioritize thermal recovery speed and tip geometry versatility. Automotive wire-harness specialists in Germany demand induction heating for crimp-and-solder sequences.
- Hobbyists:Maker-space operators and electronics enthusiasts drive compact station adoption. USB-C power delivery eliminates dedicated electrical installation for community workshop environments.
- Educational Institutions:Vocational training programs specify safety-certified equipment with documented compliance. European technical schools face ECHA pressure to transition lead-free soldering curricula.
Manufacturers dominate absolute unit procurement; educational institutions are gaining share fastest as technical training expands.
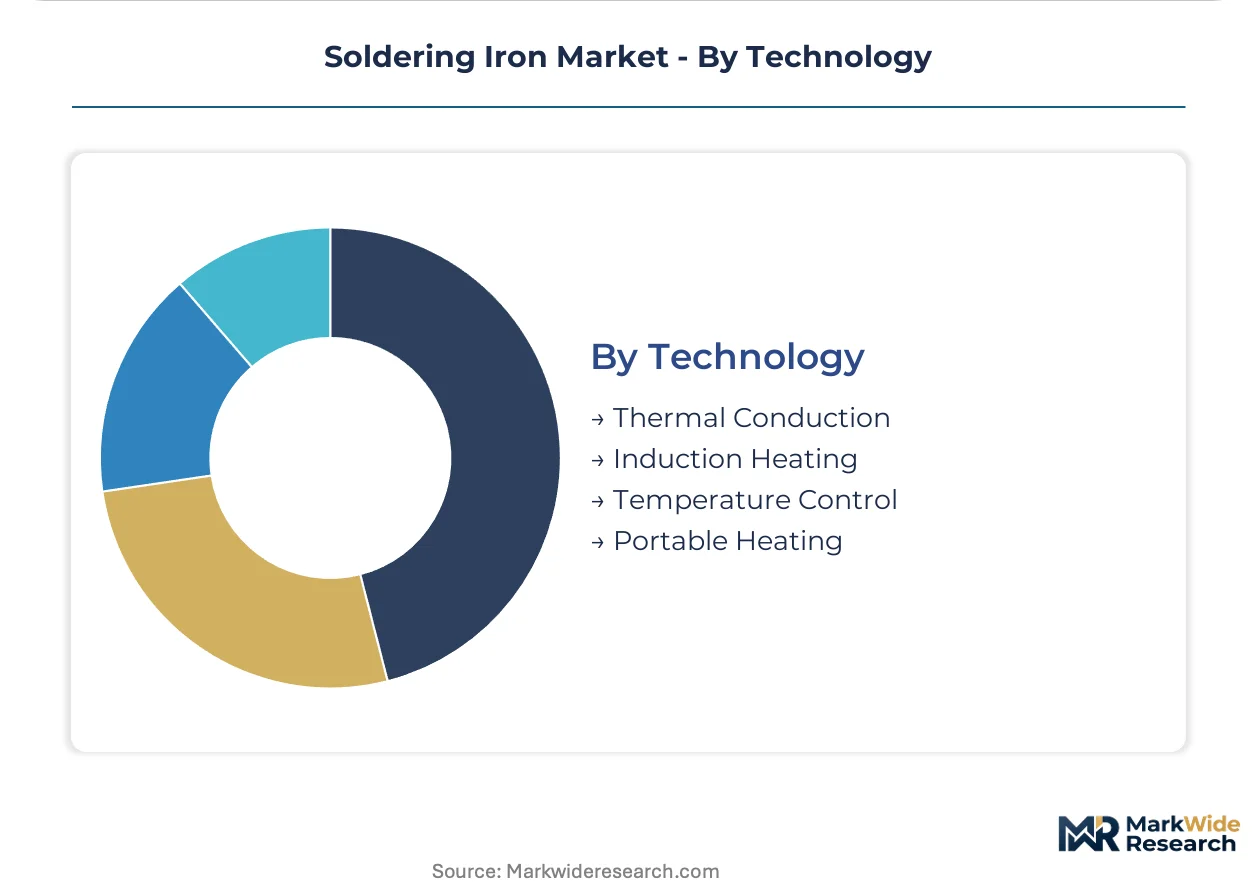
Technology:
Induction heating is displacing resistive element architectures in applications demanding rapid thermal cycling.
- Temperature Control:Closed-loop feedback systems with ceramic heater cores define professional-grade equipment. Japanese and Taiwanese suppliers dominate heater element production, creating supply concentration.
- Induction Heating:Electromagnetic field generation enables 3-second thermal recovery in automotive wire-harness operations. Tier-1 suppliers in Germany and the United States adopt these systems despite 3-5x capital intensity.
- Thermal Conduction:Traditional resistive element designs persist in cost-sensitive high-volume assembly. Copper alloy tip metallurgy faces reformulation pressure from lead-free solder compatibility requirements.
- Portable Heating:Battery and gas-powered alternatives serve field service technicians without mains access. EU F-Gas Regulation phase-down constrains butane chemistry viability in European HVAC channels.
Thermal conduction retains installed base dominance; induction heating commands the steepest technology transition trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Chinese manufacturing clusters dominate global soldering iron trade, while import demand concentrates in electronics assembly hubs across Germany, the United States, and India. Regional procurement patterns diverge sharply between high-volume contract manufacturing and precision industrial maintenance requirements.
China
Shenzhen and Dongguan fabs drive procurement of temperature-controlled stations with sub-10-second thermal recovery specifications. MIIT standards on industrial equipment safety shape product certification requirements for domestic and export-bound equipment. The Pearl River Delta manufacturing corridor concentrates Foxconn and Pegatron operations negotiating multi-year hardware-consumable bundle agreements.
Germany
Automotive wire-harness operations in Stuttgart and Wolfsburg demand induction heating systems for rapid thermal recovery during crimp-and-solder sequences. EU F-Gas Regulation phase-down schedules constrain butane-powered portable iron availability in HVAC service channels. Bavarian industrial maintenance providers specify REACH-compliant tip alloys with documented supply chain traceability.
United States
OSHA workplace exposure limits and FCC electromagnetic compatibility standards filter product entry for imported soldering equipment. Electronics assembly operations in Texas and California prioritize sleep-mode functions that reduce tip oxidation during shift changes. Midwest automotive suppliers adopt induction heating despite 3-5x capital intensity versus resistive alternatives.
India
PLI scheme subsidies for mobile phone and component assembly create first-mover positioning opportunities for station vendors in Noida and Sri City. BIS certification requirements delay product launches for imported equipment lacking domestic testing infrastructure. Tamil Nadu and Karnataka electronics manufacturing clusters specify ceramic heater stations with voltage-switchable compatibility.
Japan
METI industrial efficiency guidelines promote energy consumption reduction in manufacturing equipment procurement. Japanese ceramic heater engineering sustains premium positioning in OEM supply chains serving precision electronics workflows. Nagoya and Osaka industrial districts maintain demand for temperature-controlled precision tiers displacing legacy low-wattage hardware.
Soldering Iron Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and technology licensing dimensions. The vendor base stratifies between scale-driven equipment assemblers, captive consumable producers, and compact portable specialists. Three archetypes dominate: integrated station-consumable bundlers, precision ceramic heater engineers, and USB-C powered field-repair innovators. Competitive moves concentrate on multi-year procurement contracts and backward integration into heater core production.
Within the precision engineering tier, Hakko exemplifies Japanese ceramic heater expertise anchoring OEM supply chains. Miniware occupies a position among compact USB-C powered specialists targeting maker-space and field-repair segments. YIHUA represents the scale-driven programmable station segment serving Southeast Asian contract manufacturers. These three entities illustrate divergent strategic positioning across thermal recovery specifications, power delivery formats, and geographic procurement channels.
| Leading Market Players |
|---|
| FNIRSI |
| Miniware |
| Hakko |
| Hexacon |
| YIHUA |
| Weller |
| ALIENTEK |
| Antex |
| Pine64 |
| Others |
Value Network & Pricing Analysis
Iron-nickel tip alloy substitution for legacy copper-based metallurgy simultaneously shifts procurement geography toward Japanese and Taiwanese heater core suppliers and compresses margin pools for mid-tier station assemblers lacking backward integration into consumable production. This materials transition cascades through contract manufacturer procurement criteria, where REACH-compliant traceability documentation now gates vendor qualification.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ceramic heater engineering sophistication and IPC J-STD-001 certification tier, with Foxconn and Pegatron operations commanding volume discounts through multi-year hardware-consumable bundles. Cost compression in entry-level programmable stations is intensifying because YIHUA and Southeast Asian competitors sacrifice margin for procurement slotting. Contract manufacturers exhibit lowest price sensitivity due to bundled tip contracts, while independent field technicians face acute sensitivity to standalone station capital outlay.
Supply Chain Analysis
Container availability constraints on Shenzhen-to-Hamburg trade lanes elevate landed costs for European distributors sourcing temperature-controlled stations. Heater core production concentrates in Japan and Taiwan, while final assembly clusters in China and Vietnam. Copper alloy feedstock and ceramic substrate dependencies expose assemblers to LME price volatility and single-source vulnerability from Murata and NTK suppliers. Distribution runs through Foxconn and Pegatron captive procurement channels for high-volume electronics assembly, with aftermarket service flowing through industrial distributors and maker-space retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Contract manufacturer procurement consolidation into multi-year bundled agreements has shifted buyer power toward hardware-consumable integrators, squeezing standalone equipment vendors without captive tip production.
For Market Incumbents: Consolidate backward integration into ceramic heater core production to escape Japanese and Taiwanese supplier dependency. Lock in multi-year tip cartridge supply contracts with Shenzhen and Dongguan fabs before IPC J-STD-001 qualification timelines stretch procurement windows. Defend against USB-C powered field-repair entrants by embedding predictive maintenance algorithms in premium station firmware. For New Entrants and Emerging Players: Anchor in India's PLI-subsidized mobile phone assembly corridor, where BIS certification delays create first-mover windows for domestic testing infrastructure investments. Target European HVAC service channels facing EU F-Gas propellant restrictions with battery-powered alternatives. Pursue maker-space and repair-cafe distribution through compact USB-C form factors eliminating dedicated electrical installation. For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors consumable-captive station vendors over standalone hardware assemblers. Long-term viability hinges on heater core production control and REACH-compliant alloy traceability systems. Watch for induction heating adoption inflection in automotive wire-harness operations as the signal for premium tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heater Core Production | Murata and NTK supply concentration creates single-source vulnerability for programmable station assemblers. |
| REACH-Compliant Tip Alloy Certification | ECHA documentation requirements gate European industrial maintenance procurement and replacement cycles. |
| USB-C Power Delivery Platform Launch | Miniware and Pine64 anchor maker-space demand through laptop charger compatibility eliminating bench infrastructure. |
| Multi-Year Hardware-Consumable Bundling | Foxconn and Pegatron procurement consolidation locks vendor relationships across shift rotations in Shenzhen. |
| Induction Heating Technology Licensing | Tier-1 automotive suppliers in Stuttgart and Wolfsburg adopt 3-second thermal recovery for crimp-and-solder sequences. |
Research Methodology
A standing panel of electronics assembly plant managers, OEM procurement leads at Foxconn and Pegatron operations, ceramic heater engineering directors, and aftermarket service distributors provided ongoing calibration throughout the study. Primary interview findings were cross-validated against secondary sources including MIIT equipment safety filings, ECHA REACH substance registrations, EU F-Gas Regulation implementation schedules, and SEC 10-K disclosures from listed equipment vendors. Bottom-up station shipment data from Shenzhen and Dongguan manufacturing clusters was triangulated against top-down electronics assembly capital expenditure tracking.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product type, application, end user, and technology tier alongside voltage compatibility and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year market sizing, with inputs including contract manufacturer procurement cycle timing, IPC certification qualification durations, and PLI scheme subsidy disbursement patterns in India.
Material uncertainties — copper price volatility, heater core supply disruption, REACH alloy reformulation delays, and BIS certification timeline extensions — sit outside the modeled envelope. Forecasts reflect documented assumptions about procurement consolidation continuity and induction heating capital intensity thresholds. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
United States Fusion Splicer Market
Industrial Equipment
Global Pneumatic Actuators Market
Industrial Equipment
Precision Dispensing Accessories Market
Industrial Equipment
Screw Air End Market
Industrial Equipment
Ultrasonic Cleaning Equipment Market
Industrial Equipment
Linear Transfer System Market
Industrial Equipment
Cable Granulator Market
Industrial Equipment
Global Laboratory Vacuum Pumps Market
Industrial Equipment
Global DC Drives Market
Industrial Equipment
Automatic Laser Welding Machine Market
Industrial Equipment
Global High Power Laser Systems Market
Industrial Equipment
Industrial Tags Market
Industrial Equipment
Seal Inspection Equipment Market
Industrial Equipment
Glass Engraving Machines Market
Industrial Equipment
Global Industrial Enclosures Market
Industrial Equipment
Laser Marking Market