
 United States Ball Bearing Market | 2026-2036
United States Ball Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
United States Ball Bearing Market Intelligence
Market Context
The NHTSA Corporate Average Fuel Economy framework is recalibrating the cost-of-entry calculus for precision bearing suppliers serving Detroit automakers. Timken Co leverages its integrated steel-to-bearing manufacturing chain to sustain margin control across heavy-duty truck applications. RBC Bearings specializes in aerospace-grade thin-section bearings, dominating defense and satellite programs with ITAR-compliant production lines. NTN Corporation anchors its North American position through automated grinding facilities in Indiana that serve Toyota and Honda assembly plants.
Technical Definition and Segment Structure
A ball bearing is a rolling-element bearing that uses hardened spherical balls to maintain separation between inner and outer raceways, typically manufactured to ABEC precision grades with radial clearances measured in micrometers to minimize friction and support radial and axial loads in rotating machinery. Deep groove bearings occupy the volume core across industrial motors and appliances, while angular contact bearings command premium positioning in machine tool spindles where combined load capacity determines system rigidity. Ceramic material formulations, particularly silicon nitride hybrid constructions, represent the fastest-expanding segment as power density requirements in EV inverters and wind turbine gearboxes exceed the thermal limits of conventional chrome steel.
Regulatory Framework and Outlook
The EPA enforces lubricant discharge restrictions under the Clean Water Act that push bearing users toward sealed-for-life designs, while OSHA machine guarding standards mandate fail-safe bearing monitoring in metalworking equipment. The Department of Commerce maintains anti-dumping duties on Chinese ball bearings that protect domestic producers from price-driven import displacement. Stakeholders must monitor NHTSA rulemaking on heavy-duty vehicle emissions, as proposed torque-loss reduction targets would force widespread retrofit of low-friction bearing architectures across Class 8 truck fleets.
Market Dynamics
Electric vehicle powertrain densification is compressing bearing replacement cycles while forcing ceramic hybrid architectures into Detroit assembly lines at unprecedented scale.
Growth Catalysts
- NHTSA CAFE tightening:Fuel economy mandates are mandating torque-loss reductions across driveline components, forcing OEMs to specify low-friction angular contact bearings in transmission architectures.
- Silicon nitride hybrid formulations:Ceramic ball constructions tolerate thermal loads exceeding chrome steel limits, enabling inverter-mounted bearings to survive EV power density jumps.
- Great Lakes manufacturing corridor concentration:Proximity to Michigan, Ohio, and Indiana assembly plants shortens just-in-time delivery windows for Tier 1 bearing suppliers serving Detroit automakers.
Market Restraints
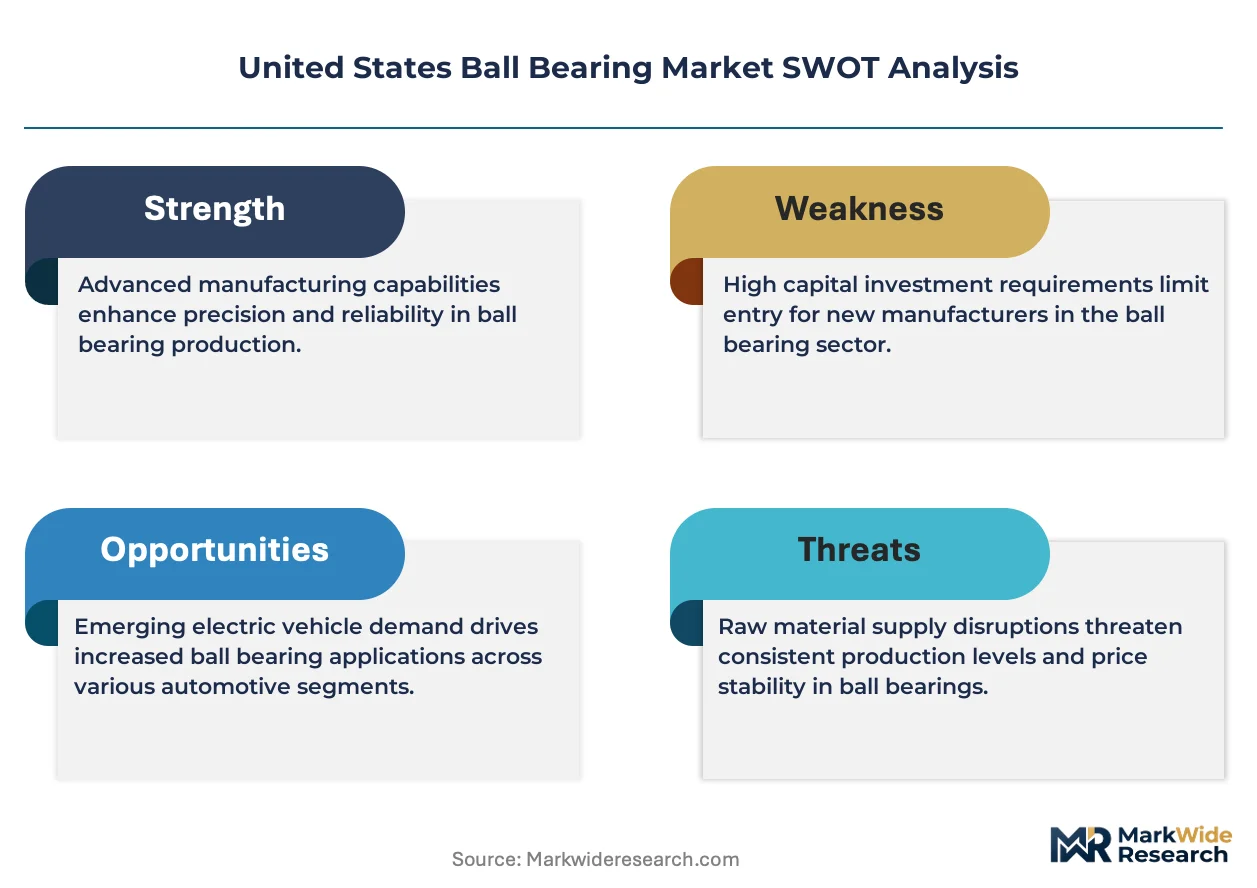
- Alloy steel input volatility:Chrome molybdenum prices fluctuate with scrap metal and energy costs, squeezing margin predictability for precision-grade bearing producers.
- Single-source ceramic powder supply:High-purity silicon nitride feedstock concentrates among Japanese and German chemical processors, exposing US manufacturers to trans-Pacific logistics risk.
- ABEC-7+ tolerance limitations:Sub-micron radial clearance consistency remains technically constrained in high-volume automated grinding, capping output rates for aerospace-grade thin-section bearings.
Strategic Opportunities
- Wind turbine gearbox aftermarket:Repowering cycles across Texas and Great Plains installations create replacement demand for hybrid ceramic main shaft bearings rated for 25-year service life.
- OSHA fail-safe monitoring mandates:Metalworking equipment guarding standards are driving sensor-integrated smart bearing adoption, opening embedded electronics revenue streams.
- Additive manufacturing convergence:Powder bed fusion of bearing cages with topology-optimized geometries promises weight reduction in satellite momentum wheel applications.
Industry Challenges
- Precision metrology skill scarcity:Roundness and waviness measurement expertise for ABEC-9 certification is concentrating among retiring technicians, constraining quality lab throughput.
- Clean Water Act compliance timelines:EPA lubricant discharge restrictions force rapid sealed-for-life design transitions, compressing R&D validation windows for legacy open-bearing platforms.
- ITAR-controlled production segregation:Defense and commercial bearing lines require physically separated facilities, duplicating capital intensity for dual-use suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Ball Bearing Market |
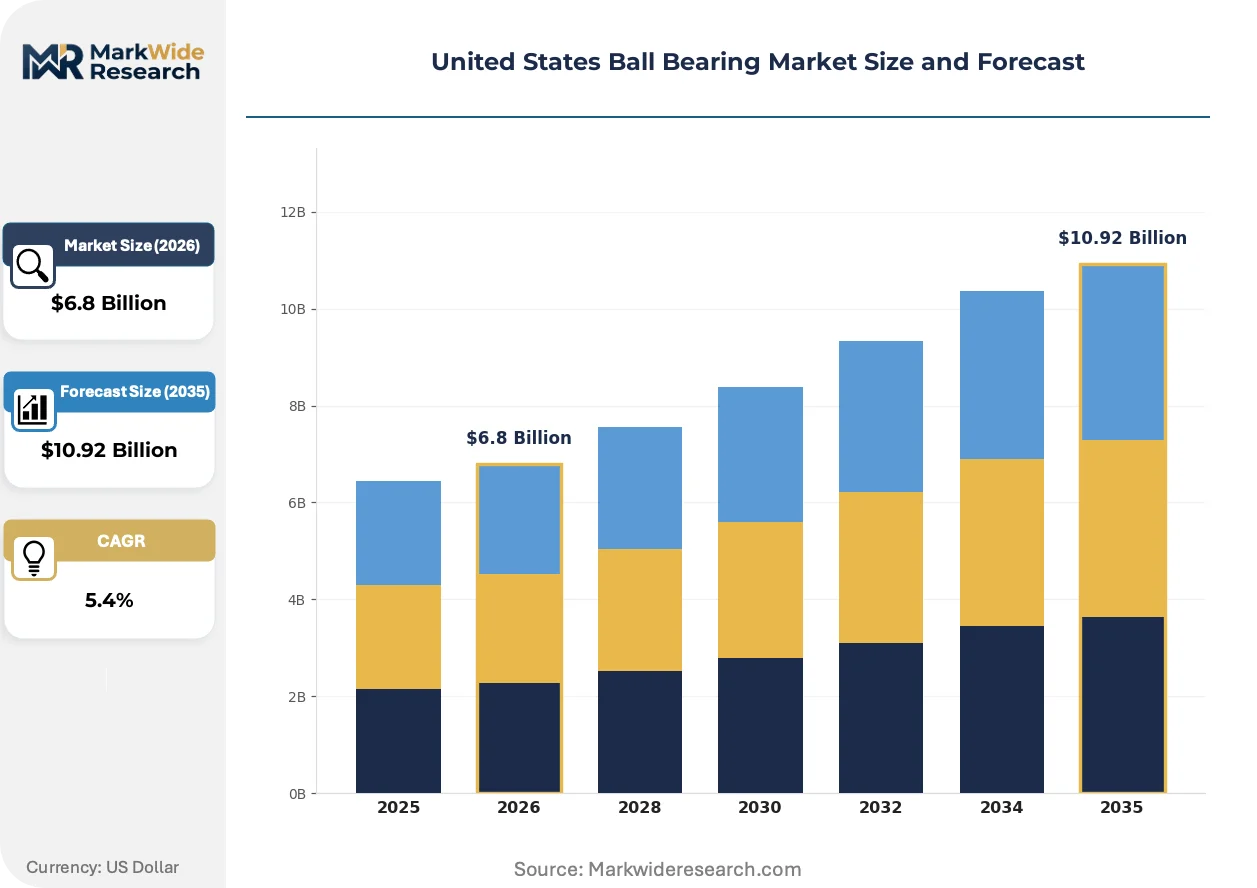
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deep Groove Bearings, Angular Contact Bearings, Self-Aligning Bearings, Thrust Bearings End User: Aerospace, Automotive OEMs, Industrial Machinery, Power Generation Material: Stainless Steel, Ceramic, Chrome Steel, Plastic Size: Miniature Bearings, Small Bearings, Medium Bearings, Large Bearings |
| Companies Covered | RBC Bearings, Kaydon Bearings, Timken Co, Bearing Service Co, American Roller Bearings, NTN Corporation, MRC Bearings, Frantz Manufacturing Co, Jtekt Corp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Ball Bearing Market Strategic Shifts & Innovations
Ceramic hybrid architectures are displacing conventional steel constructions across thermally stressed applications, while regulatory torque-loss mandates and smart sensor integration reshape supplier technical roadmaps.
Silicon nitride hybrid bearings tolerate operating temperatures exceeding 300°C in EV inverter housings, a thermal envelope that destroys chrome steel raceways within hours. Detroit automakers are qualifying these constructions for 800V powertrain programs at accelerated 18-month validation cycles. This material transition is electrifying supplier R&D priorities, compressing traditional steel-centric product development timelines.
NHTSA heavy-duty vehicle emissions rulemaking proposes torque-loss reduction targets that would force Class 8 truck fleet retrofits with low-friction bearing architectures. The proposed framework threatens existing driveline designs with obsolescence unless suppliers achieve sub-0.001 coefficient of friction in main shaft applications. Long-haul trucking corridors through Ohio and Indiana represent the most exposed geography, with fleet operators already pre-qualifying ceramic hybrid options.
Maintenance contracting is fragmenting from bundled service agreements toward component-level predictive replacement schedules. Industrial motor repair shops are acquiring vibration analysis capabilities to specify exact bearing replacement intervals rather than preventive overhaul cycles. This unbundling is most visible across Great Lakes automotive stamping plants, where unplanned downtime costs exceed $50,000 per hour and drive demand for sensor-integrated condition monitoring.
United States Ball Bearing Market Segmentation
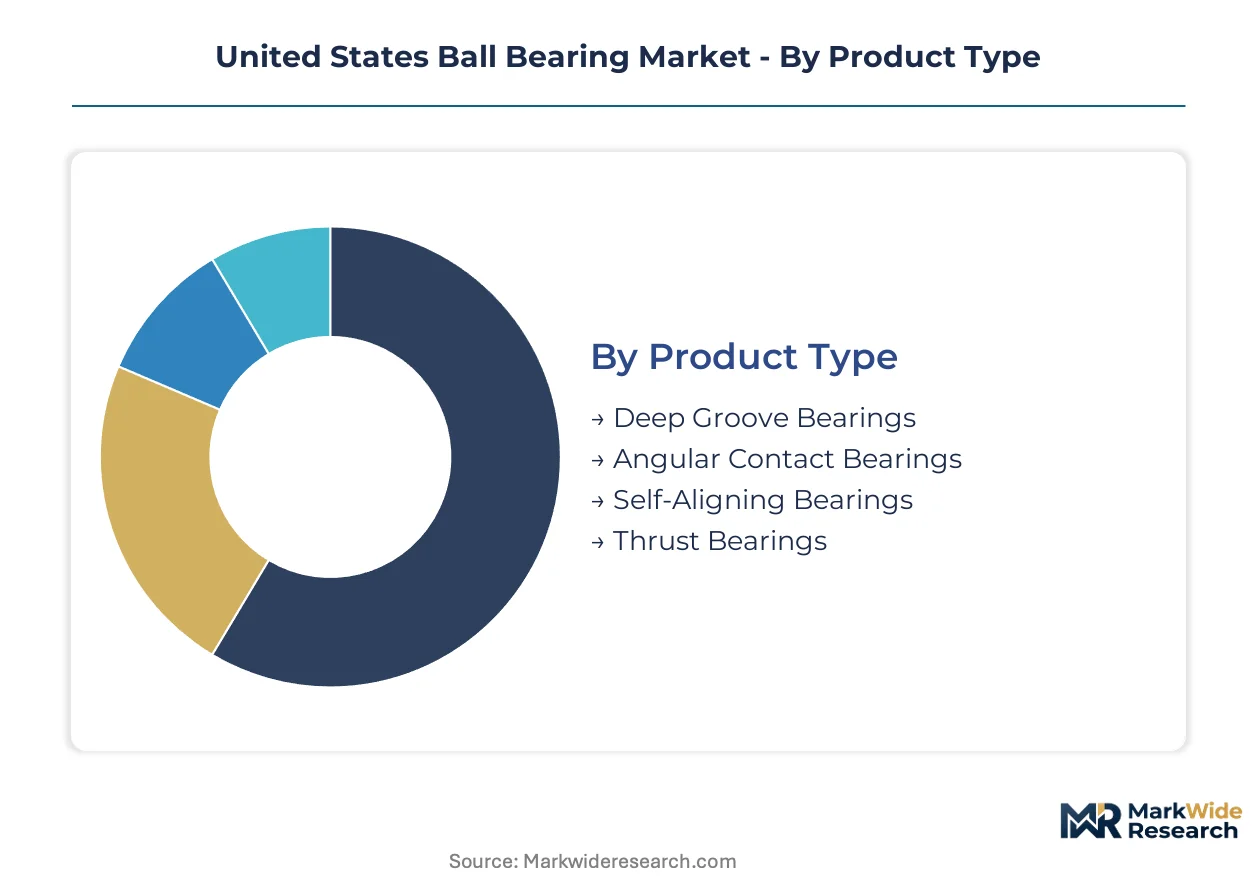
Ball bearing segmentation in the United States reflects divergent capital requirements across precision grades, material formulations, and end-use certifications. Suppliers must align grinding automation investments with the specific tolerance demands of each segment tier.
Product Type:
Deep groove configurations demand the heaviest upfront capital in automated raceway grinding lines, while angular contact architectures require specialized goniometric assembly stations.
- Deep Groove Bearings:These constructions utilize continuous raceway geometries optimized for radial load dominance across industrial motor shafts and appliance spindles. Michigan automotive stamping plants specify ABEC-5 variants for conveyor line rollers, prioritizing inventory standardization over precision premiums.
- Angular Contact Bearings:Designed with raceway offset angles enabling combined radial and axial load capacity, these configurations dominate machine tool spindle architectures. Ohio-based Tier 1 suppliers are qualifying low-friction variants for NHTSA CAFE-driven transmission retrofits.
- Self-Aligning Bearings:Spherical outer raceway designs accommodate shaft misalignment in agricultural equipment and material handling systems across Indiana manufacturing corridors.
- Thrust Bearings:Axial-load-optimized configurations serve vertical pump assemblies and helicopter rotor masts with segmented cage architectures.
Deep groove bearings absorb the bulk of installed capacity; angular contact bearings are expanding most quickly.
End User:
Procurement patterns diverge sharply between ITAR-regulated defense programs and high-volume automotive just-in-time contracts.
- Aerospace:Thin-section bearings for satellite momentum wheels and landing gear actuators require ABEC-7+ certification with 100% dimensional traceability.
- Automotive OEMs:Detroit powertrain programs are compressing ceramic hybrid bearing validation cycles to 18 months for 800V EV architectures.
- Industrial Machinery:OSHA-mandated fail-safe monitoring is driving sensor integration into metalworking spindle bearings across Great Lakes stamping plants.
- Power Generation:Wind turbine gearbox repowering cycles in Texas and the Great Plains specify 25-year-rated hybrid ceramic main shaft bearings.
Automotive OEMs command the greatest volume concentration; power generation is climbing the fastest on renewable repowering demand.
Material:
Raw material sourcing strategies separate commodity-grade producers from precision specialists.
- Stainless Steel:AISI 440C variants deliver corrosion resistance for food processing and marine applications without ceramic cost premiums.
- Ceramic:Silicon nitride hybrid constructions tolerate 300°C+ operating temperatures in EV inverter housings, though Japanese and German powder suppliers dominate feedstock access.
- Chrome Steel:52100 alloy remains the volume default across industrial motors, with pricing tethered to scrap metal and energy input volatility.
- Plastic:PEEK and PTFE cage materials reduce weight in medical imaging equipment and chemical processing pumps.
Chrome steel retains the largest installed base; ceramic is gaining share fastest on thermal performance requirements.
Size:
Dimensional scaling determines grinding automation feasibility and metrology throughput.
- Miniature Bearings:Sub-10mm bore diameters for medical devices and precision instruments require specialized micro-grinding spindles with limited supplier capacity.
- Small Bearings:10-30mm bore range dominates appliance and power tool applications with standardized ABEC-1 through ABEC-3 grades.
- Medium Bearings:30-90mm configurations serve industrial gearboxes and automotive auxiliary systems across Ohio and Indiana supplier networks.
- Large Bearings:90mm+ bore diameters for wind turbine main shafts and steel mill roll necks demand custom heat treatment furnaces and ring forging partnerships.
Medium bearings anchor production volume; miniature bearings face the steepest capacity constraints from metrology skill scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zone 43 in Indianapolis accelerates bearing imports through duty-deferred mechanisms, concentrating Midwest distribution networks around Great Lakes manufacturing demand.
Great Lakes Manufacturing Corridor
Automotive powertrain densification drives ceramic hybrid bearing procurement across Michigan, Ohio, and Indiana assembly plants. NHTSA Corporate Average Fuel Economy mandates tighten tolerance specifications for driveline components serving Detroit automakers. Indiana automated grinding facilities supply just-in-time contracts to Toyota and Honda plants in the Ohio River Valley.
Southeast Industrial Belt
Wind turbine gearbox repowering cycles generate aftermarket demand for 25-year-rated hybrid ceramic main shaft bearings across Texas and Oklahoma installations. EPA Clean Water Act lubricant discharge restrictions push sealed-for-life bearing designs into metalworking equipment throughout Georgia and Alabama automotive stamping plants. Dallas-Fort Worth logistics hubs distribute precision bearings to Gulf Coast petrochemical processors.
Pacific Northwest Technology Cluster
Electric vehicle battery manufacturing expansion in Washington and Oregon creates demand for thermal-tolerant inverter-mounted bearings. OSHA machine guarding standards mandate fail-safe bearing monitoring in aerospace machining operations around Seattle-Tacoma. Silicon nitride powder supply constraints from Japanese chemical processors expose regional manufacturers to trans-Pacific shipping volatility.
Northeast Defense Corridor
ITAR-compliant production lines for aerospace-grade thin-section bearings concentrate in Connecticut and Massachusetts satellite momentum wheel programs. Department of Commerce anti-dumping duties on Chinese ball bearings protect domestic producers serving New York and New Jersey port machinery rebuilders. Precision metrology skill scarcity for ABEC-9 certification constrains quality lab throughput across New England defense subcontractors.
Southwest Energy Zone
Oilfield equipment refurbishment cycles in Texas and Louisiana specify corrosion-resistant stainless steel bearings for offshore pump assemblies. FERC grid reliability standards drive generator bearing replacement schedules across Arizona and New Mexico utility-scale solar installations. El Paso maquiladora partnerships facilitate cross-border component finishing for medium-bore industrial gearbox applications.
United States Ball Bearing Market Key Industry Players
Domestic integrated manufacturers anchor one tier; Japanese and German precision specialists hold premium positioning through ceramic material expertise. The vendor base organizes around three strategic archetypes: steel-to-bearing integrated producers controlling heavy-duty margins, aerospace-grade thin-section specialists dominating ITAR-regulated programs, and automated high-volume suppliers serving automotive just-in-time contracts. Competitive moves concentrate on backward integration into alloy steel production and geographic proximity to Detroit assembly corridors.
Among domestic integrated producers, Timken Co exemplifies the steel-to-bearing manufacturing chain archetype, while RBC Bearings occupies a position within aerospace-grade thin-section specialization. NTN Corporation represents the automated high-volume supplier archetype through its Indiana-based grinding facilities. These three entities illustrate the competitive structure without exhausting the participant base.
| Leading Market Players |
|---|
| RBC Bearings |
| Kaydon Bearings |
| Timken Co |
| Bearing Service Co |
| American Roller Bearings |
| NTN Corporation |
| MRC Bearings |
| Frantz Manufacturing Co |
| Jtekt Corp |
| Others |
Cost & Logistics Intelligence
Precision metrology skill concentration in New England constrains ABEC-9 certification throughput, widening labor-cost spreads between premium aerospace-grade and standard industrial bearing tiers.
Pricing Analysis
Lead-time premiums reward rapid fulfillment while spot inventory discounts clear excess stock from automated grinding facilities. Three-tier pricing structure across premium, standard, and economy levels separates ABEC-7+ aerospace certifications from ABEC-5 automotive variants and ABEC-1 commodity grades. Price differentiation hinges on ceramic hybrid material costs and ITAR compliance overhead. Margins are tightening in chrome steel tiers due to scrap metal volatility, while automotive OEMs exhibit highest price sensitivity and defense contractors show least.
Supply Chain Analysis
ITAR qualification gates restrict supplier participation in defense programs to physically segregated production lines. High-purity silicon nitride powder concentrates in Japan and Germany, while chrome steel feedstock draws from domestic electric arc furnaces. Raw material dependencies span alloy steel billets, ceramic feedstock, and specialized grinding abrasives. Single-source ceramic powder vulnerability exposes US manufacturers to trans-Pacific logistics risk. Distribution runs through Foreign Trade Zone 43 in Indianapolis for duty-deferred import handling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States ball bearing market reads as a cost-of-compliance story where NHTSA torque-loss mandates erect regulatory moats favoring capitalized incumbents with validation infrastructure.
For Market Incumbents: Anticipate ceramic hybrid demand acceleration by securing long-term silicon nitride supply agreements with Japanese chemical processors before feedstock allocation tightens. Defend position by expanding automated grinding capacity in Indiana to capture Toyota and Honda just-in-time contracts. Prioritize ABEC-7+ metrology workforce development in Connecticut and Massachusetts before retiring technician expertise vanishes.
For New Entrants and Emerging Players: Industrial motor repair shops represent the most penetrable channel partner type for sensor-integrated smart bearing introductions. Target wind turbine gearbox aftermarket across Texas and Oklahoma repowering cycles where 25-year service life specifications favor new supplier qualification. Pursue OSHA fail-safe monitoring mandates as the go-to-market angle for embedded electronics revenue streams.
For Investors and Strategic Acquirers: Re-rating potential sits with aerospace-grade thin-section specialists given ITAR-controlled production segregation barriers. Long-term viability favors dual-use suppliers with physically separated defense and commercial lines. Monitor NHTSA heavy-duty vehicle emissions rulemaking finalization as the inflection signal for ceramic hybrid retrofit demand across Class 8 truck fleets.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Hybrid Validation Acceleration | Compresses 800V EV powertrain qualification cycles to 18 months for Detroit automaker contracts. |
| Backward Integration into Alloy Steel | Captures margin control over 52100 chrome molybdenum feedstock amid scrap metal volatility. |
| ITAR Facility Segregation Investment | Enables participation in Connecticut and Massachusetts satellite momentum wheel programs. |
| Smart Bearing Sensor Integration | Addresses OSHA fail-safe monitoring mandates across Great Lakes metalworking equipment. |
| Silicon Nitride Supply Partnership | Secures high-purity ceramic powder allocation from Japanese and German chemical processors. |
Research Approach
Independent corroboration across bearing plant managers, Tier 1 automotive procurement leads, aerospace program engineers, and aftermarket distribution channel heads underwrites the qualitative findings. Primary fieldwork combined with secondary validation from NHTSA rulemaking dockets, EPA enforcement actions, Department of Commerce anti-dumping duty records, and SEC filings from publicly traded bearing manufacturers. Bottom-up grinding capacity estimates triangulated against top-down automotive production forecasts.
Comparable-period anchoring linked projection horizons to historical ABEC certification adoption curves and ceramic hybrid penetration trajectories. The analytical framework segmented across product type, end user, material formulation, and dimensional scale throughout the forecast period. CAGRs derived from regression analysis against powertrain electrification content-per-vehicle trends and wind turbine repowering cycle schedules.
Caveats apply where NHTSA rulemaking delays, silicon nitride supply disruptions, or precision metrology skill scarcity could materially shift the outlook. Forecasts reflect assumptions about EV adoption velocity and renewable energy deployment trajectories. A model refresh is warranted upon material change in heavy-duty vehicle emissions standards or ceramic powder trade flow restrictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Smart Pneumatics Market
Industrial Equipment
Global Flat Glass Tempering Machines Market
Industrial Equipment
Global Special Purpose Machines Market
Industrial Equipment
North America Rental Chillers Market
Industrial Equipment
Electric Actuator Market
Industrial Equipment
China Ceramic Roller Bearings Market
Industrial Equipment
Digital Tachometer Market
Industrial Equipment
Global Industrial Centrifuges Market
Industrial Equipment
High-Speed Electric Spindle Market
Industrial Equipment
Battery Spot Welder Market
Industrial Equipment
Compositing Equipment Market
Industrial Equipment
Laser Marking Market
Industrial Equipment
Electro-Pneumatic Systems Market
Industrial Equipment
Commercial Refrigeration System Market
Industrial Equipment
Electronic Beam Machining Market
Industrial Equipment
Slewing Bearing Market