
 Seal Inspection Equipment Market | 2026-2036
Seal Inspection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Seal Inspection Equipment Market Insights
Aftermarket service revenue is fragmenting as equipment vendors diversify beyond hardware sales into predictive maintenance subscriptions and calibration contracts. Mettler Toledo leverages its weighing and inspection portfolio to anchor recurring revenue streams across pharmaceutical and food processing installations. Ishida competes through integrated checkweighing and seal verification lines that dominate high-speed packaging environments in Asia-Pacific manufacturing hubs.
Seal inspection equipment encompasses automated systems that detect leaks, verify closure integrity, and identify material defects in sealed containers and mechanical assemblies, typically operating at detection thresholds of 0.1 microns for vacuum applications and pressures ranging from vacuum to 700 bar for hydraulic testing. The primary industrial purpose centers on preventing contamination, ensuring product safety, and eliminating costly recalls in regulated production environments. Optical imaging technology leads installed base volumes due to mature camera sensor economics and straightforward integration with existing conveyor systems, while acoustic emission is gaining fastest in pipeline and subsea seal monitoring where non-contact detection matters. Ultrasonic detectors command premium margins in aerospace fastener applications where FAA airworthiness directives mandate zero-failure verification protocols.
FDA enforces container closure integrity testing under USP 1207 for sterile pharmaceutical products, compelling manufacturers to validate seal inspection methods against probabilistic microbial ingress models. EMA's Annex 1 revision on sterile manufacturing elevates automated visual inspection from recommendation to expectation across European production sites. EU MDR requirements for medical device packaging traceability further tighten verification standards for seal documentation. Stakeholders must weigh capital deployment between incremental optical upgrades and transformative acoustic or infrared platforms as regulatory divergence between FDA risk-based approaches and EU prescriptive mandates widens compliance architecture choices.
Market Dynamics
Pharmaceutical packaging lines are consolidating inspection stations under single-platform architectures, compressing capital deployment timelines while elevating software validation burdens. This platform consolidation is forcing equipment vendors to restructure R&D roadmaps around integrated compliance modules rather than standalone hardware increments.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates in sterile pharmaceutical manufacturing are accelerating automated seal inspection adoption across US production facilities.
- Optical imaging sensor economics:CMOS camera cost curves below $200 per unit are enabling high-resolution seal verification at conveyor speeds exceeding 600 units per minute.
- Germany precision engineering clusters:Concentrated automation expertise in Stuttgart and Munich corridors sustains premium equipment procurement for medical device packaging lines.
Market Restraints
- Helium tracer gas supply concentration:Russian and Qatari helium production dominance creates input cost volatility for leak detection calibration protocols.
- Acoustic emission detection thresholds:Sub-0.5 micron vacuum leak identification remains technically constrained in high-noise manufacturing environments.
- EU MDR documentation requirements:Extended validation timelines for seal traceability systems are lengthening equipment procurement cycles by 8-14 months.
Strategic Opportunities
- India pharmaceutical contract manufacturing:CDMO expansion in Hyderabad and Ahmedabad corridors is creating unmet demand for mid-speed automated inspection platforms.
- Infrared thermography convergence with machine vision:Combined thermal-seal mapping systems are opening diagnostic capabilities for heat-sealed flexible packaging.
- Japan METI carbon neutrality incentives:Subsidies for energy-efficient manufacturing equipment are redirecting capital toward low-power acoustic inspection systems.
Industry Challenges
- Validation engineer scarcity:FDA-compliant software documentation expertise commands 40% wage premiums, constraining vendor deployment capacity.
- Legacy PLC integration complexity:1990s-era packaging line controllers require custom gateway development for modern seal inspection data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seal Inspection Equipment Market |
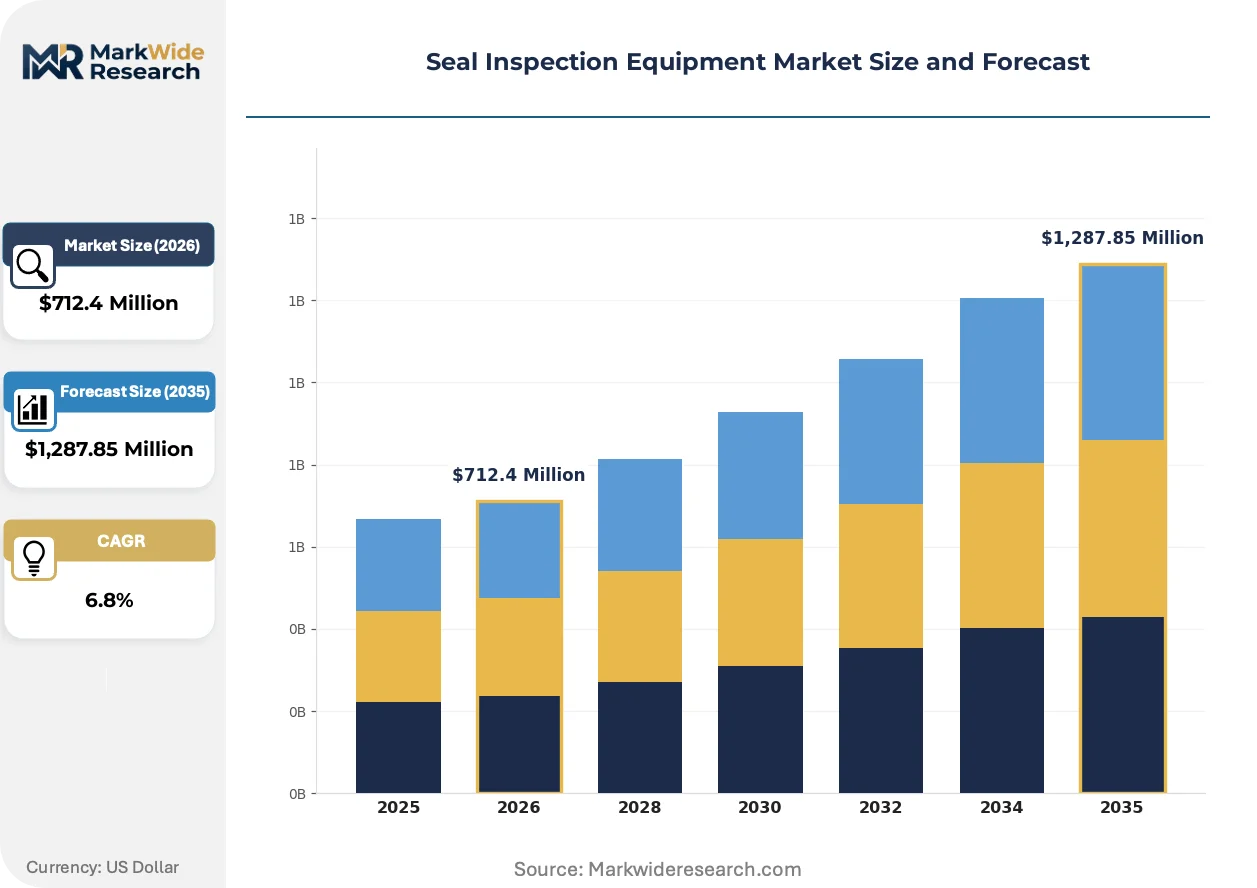
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,287.85 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Visual Inspection Systems, Ultrasonic Detectors, Pressure Testing Devices, Leak Detectors Technology: Optical Imaging, Acoustic Emission, Infrared Thermography, Vibration Analysis Application: Pipeline Seals, Hydraulic Systems, Vacuum Components, Aerospace Fasteners End User: Oil & Gas Firms, Manufacturing Plants, Aerospace Contractors, Chemical Processors |
| Companies Covered | Mettler Toledo, Antares Vision, Ishida, Syntegon Technology, INFICON, Teledyne Technologies, Wipotec-OCS, Presto Testing Instruments, Sepha, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seal Inspection Equipment Market Trends and Innovations
Digital twin architectures are redefining how seal inspection data flows from production floor to quality management systems, collapsing the latency between defect detection and batch disposition decisions.
Machine vision software is virtualizing hardware-dependent inspection logic, enabling pharmaceutical manufacturers to deploy algorithm updates without line shutdowns. Pfizer and Roche manufacturing divisions are piloting cloud-native vision platforms that separate image acquisition from analysis processing. This virtualization is compressing vendor lock-in durations and accelerating competitive displacement in installed base maintenance contracts.
EMA's Annex 1 revision on sterile manufacturing is elevating automated visual inspection from recommendation to mandatory expectation across European production sites. The regulation's 2023 implementation deadline forced batch record system overhauls, with seal integrity verification now requiring continuous data integrity proofs. Aseptic filling operations in Ireland and Switzerland are prioritizing platforms with embedded audit trail automation to preempt regulatory inspection findings.
Service contract unbundling is fragmenting traditional equipment vendor revenue models, with pharmaceutical quality departments now sourcing calibration and predictive maintenance from specialized third-party providers. This disintermediation is most pronounced in Germany, where Mittelstand calibration laboratories are capturing 25-30% of aftermarket value previously retained by original equipment manufacturers. Equipment vendors are responding with subscription-based software tiers to defend recurring revenue positions.
Seal Inspection Equipment Market Segmentation
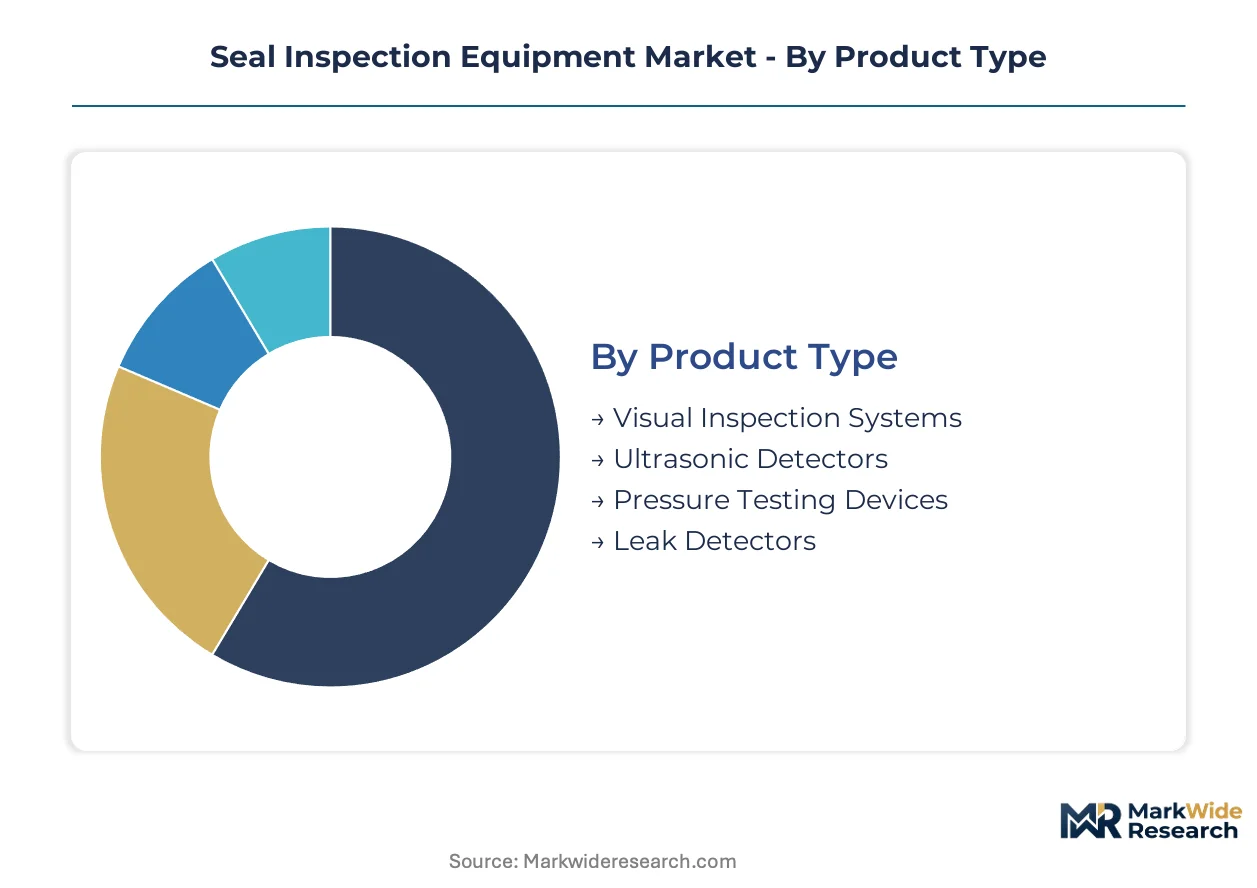
Seal inspection equipment procurement patterns diverge sharply across operational contexts. Cycle times for replacement and upgrade vary from quarterly calibration schedules in pharmaceutical lines to decade-long intervals in subsea pipeline infrastructure.
Product Type:
Replacement cycles stretch from months for portable leak detectors to years for integrated visual inspection architectures. Pressure testing devices occupy intermediate positions with annual recertification mandates driving recurring revenue.
- Visual Inspection Systems:High-resolution CMOS arrays capture seal surface anomalies at conveyor speeds exceeding 600 units per minute. Pharmaceutical packaging lines in Germany and Switzerland deploy these for continuous container closure integrity verification under EMA Annex 1 mandates.
- Leak Detectors:Helium mass spectrometry and tracer gas methods achieve detection thresholds of 0.1 microns for vacuum applications. Aerospace contractors in Toulouse and Hamburg specify these for FAA airworthiness compliance on critical fastener seals.
- Ultrasonic Detectors:Non-contact acoustic pulse analysis identifies subsurface delamination in composite seals.
- Pressure Testing Devices:Hydraulic validation systems operate from vacuum to 700 bar for pipeline commissioning protocols.
Visual Inspection Systems dominate installed base. Leak Detectors are where expansion concentrates.
Technology:
Cost tiers separate mature optical platforms from emerging acoustic and thermal modalities. Premium pricing attaches to aerospace-grade ultrasonic systems while pharmaceutical buyers prioritize standardized optical economics.
- Optical Imaging:Mature camera sensor economics below $200 per unit enable widespread deployment. Food processing facilities across the US Midwest and Northern Italy favor these for straightforward conveyor integration and minimal operator training requirements.
- Acoustic Emission:Piezoelectric sensors detect stress-wave emissions from crack propagation in rotating machinery seals. Subsea operators in the North Sea and Gulf of Mexico deploy these for non-contact pipeline monitoring where physical access is constrained.
- Infrared Thermography:Thermal gradient mapping identifies heat-seal defects in flexible packaging applications.
- Vibration Analysis:Frequency-domain signal processing monitors bearing seal degradation in predictive maintenance programs.
Optical Imaging commands volume leadership. Acoustic Emission is climbing the fastest on energy sector demand.
Application:
Volume concentration varies from mass-market pharmaceutical vials to specialized aerospace component batches. Pipeline and hydraulic applications drive the largest absolute unit deployments.
- Pipeline Seals:Automated inspection stations verify flange and valve integrity across transmission networks. Operators in Alberta and Kazakhstan deploy continuous monitoring systems for methane leak prevention under tightening environmental enforcement.
- Aerospace Fasteners:Zero-failure verification protocols mandate 100% inspection of critical structural seals. Tier-1 suppliers in Wichita and Broughton integrate ultrasonic stations directly into CNC machining cells for real-time quality gates.
- Hydraulic Systems:Pressure cycling validation ensures seal performance across construction and agricultural equipment.
- Vacuum Components:Semiconductor fabrication and scientific instrumentation require ultra-high integrity barriers.
Pipeline Seals anchor current procurement. Aerospace Fasteners are gaining share fastest on commercial aviation recovery.
End User:
Customer type determines specification rigor and contract structure. Oil and gas majors negotiate enterprise frameworks while manufacturing plants favor unit-based procurement.
- Oil & Gas Firms:Integrated supermajors specify explosion-proof inspection systems for upstream and midstream assets. Norwegian North Sea operators and Permian Basin independents both prioritize API-compliant platforms with embedded data logging for regulatory audit trails.
- Manufacturing Plants:Discrete automation buyers seek plug-and-play integration with existing PLC architectures. Automotive suppliers in Stuttgart and medical device contract manufacturers in Minneapolis drive demand for mid-speed platforms with simplified validation protocols.
- Aerospace Contractors:Prime manufacturers and tier suppliers enforce AS9100 quality system requirements on inspection equipment vendors.
- Chemical Processors:Hazardous area classifications dictate corrosion-resistant enclosure specifications.
Manufacturing Plants represent the broadest installed base. Oil & Gas Firms are where specification premiums concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes seal inspection equipment through precision-engineered pharmaceutical packaging lines, while the United States deploys identical hardware for FDA-regulated sterile manufacturing at substantially different throughput specifications. This consumption-mix differential reflects divergent regulatory enforcement intensity and automation maturity across Atlantic markets.
United States
FDA 21 CFR Part 11 electronic records mandates drive automated seal inspection adoption across sterile pharmaceutical facilities in New Jersey and Puerto Rico. The agency's USP 1207 enforcement on container closure integrity testing compels manufacturers to validate probabilistic microbial ingress models. Boston-area biotech clusters prioritize platforms with embedded audit trail automation for regulatory inspection readiness.
Germany
EMA Annex 1 revision elevates automated visual inspection from recommendation to mandatory expectation across Baden-Württemberg pharmaceutical sites. Stuttgart precision engineering clusters sustain premium equipment procurement for medical device packaging lines under EU MDR traceability requirements. Mittelstand calibration laboratories in Bavaria capture 25-30% of aftermarket value through disintermediated service contracts.
China
NMPA pharmaceutical packaging regulations tighten seal integrity verification protocols for domestic vaccine manufacturers in Jiangsu and Zhejiang provinces. The agency's alignment with PIC/S standards accelerates automated inspection substitution for manual sampling methods. Yangtze River Delta contract manufacturing expansion generates unmet demand for mid-speed validation-ready platforms.
Japan
METI carbon neutrality incentives redirect capital toward low-power acoustic inspection systems across Kansai region pharmaceutical packaging operations. PMDA sterile manufacturing guidelines mirror EMA Annex 1 technical expectations, driving platform consolidation under single-architecture compliance modules. Osaka-area equipment vendors integrate predictive maintenance subscriptions to defend recurring revenue positions.
India
CDSCO pharmaceutical manufacturing standards tighten container closure integrity requirements for export-oriented facilities in Hyderabad and Ahmedabad corridors. PLI scheme subsidies for active pharmaceutical ingredient production expand packaging line automation budgets. CDMO expansion in Telangana and Gujarat generates demand for simplified validation protocols on mid-speed inspection platforms.
Seal Inspection Equipment Market Competitive Landscape
Capability concentration sits with specialized inspection technology developers; scale advantage sits with diversified weighing and automation conglomerates. The market structures around three tiers: precision sensor specialists commanding aerospace and pharmaceutical premium segments; integrated packaging automation vendors bundling seal verification into line-wide architectures; and regional calibration service providers fragmenting aftermarket revenue. M&A activity concentrates on software validation capabilities, while portfolio diversification extends vendor reach from hardware sales into predictive maintenance subscriptions.
Among Swiss precision instrumentation groups, Mettler Toledo and INFICON exemplify the capability-concentrated tier, anchoring premium positioning through sensor technology integration. Japanese diversified automation manufacturers including Ishida occupy scale-advantaged positions across Asia-Pacific high-speed packaging environments. Vision technology specialists such as Antares Vision represent the software-virtualization archetype, separating image acquisition from analysis processing to compress vendor lock-in durations.
| Leading Market Players |
|---|
| Mettler Toledo |
| Antares Vision |
| Ishida |
| Syntegon Technology |
| INFICON |
| Teledyne Technologies |
| Wipotec-OCS |
| Presto Testing Instruments |
| Sepha |
| Others |
Pricing and Supply Chain Analysis
Stuttgart precision engineering clusters concentrate CMOS sensor and piezoelectric transducer production, translating localized component availability into pricing leverage for German equipment vendors serving pharmaceutical packaging lines under EMA Annex 1 mandates. This geographic supply density compresses logistics costs for optical inspection platforms while helium mass spectrometry systems remain exposed to Qatari and Russian tracer gas sourcing volatility.
Pricing Analysis
Long-term calibration and predictive maintenance contracts dominate revenue structures, with pharmaceutical quality departments locking in multi-year service tiers to satisfy FDA 21 CFR Part 11 audit trail requirements. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade ultrasonic systems from mid-speed food processing platforms. Cost compression in entry-level optical modules intensifies as CMOS sensor economics drop below $200 per unit. CDMOs in India's Hyderabad corridor exhibit highest price sensitivity, while German medical device packaging lines absorb premium positioning for embedded compliance automation.
Supply Chain Analysis
Extended payment terms from European pharmaceutical OEMs strain working capital for specialized sensor manufacturers, accelerating supply-chain finance facility adoption among Stuttgart and Munich corridor equipment vendors. Component sourcing concentrates in Germany, Japan, and the United States for precision optical arrays and acoustic transducers. Helium tracer gas, vacuum pumps, and high-grade aluminum enclosures constitute critical input dependencies. Single-source vulnerability in Russian helium supply channels threatens calibration protocol continuity. Distribution runs through direct OEM partnerships for integrated packaging lines and specialized distributors for aftermarket calibration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seal inspection equipment sits in early-cycle expansion as regulatory mandates transform automated visual inspection from recommendation to mandatory expectation across sterile pharmaceutical manufacturing. FDA 21 CFR Part 11 and EMA Annex 1 revisions compress adoption timelines for validation-ready platforms.
For Market Incumbents: Insulate recurring revenue positions by embedding predictive maintenance subscriptions within pharmaceutical quality management systems, countering third-party calibration laboratory disintermediation. Acquire software validation engineering capabilities to address 40% wage premiums constraining deployment capacity. Deepen backward integration into CMOS sensor supply relationships to defend margin compression from commoditizing optical economics. For New Entrants and Emerging Players: India's CDMO expansion in Telangana and Gujarat corridors offers the most penetrable white-space for mid-speed platforms with simplified validation protocols. Target food processing facilities across the US Midwest with plug-and-play optical systems requiring minimal operator training. Pursue cloud-native vision architectures that separate image acquisition from analysis processing to compress incumbent lock-in durations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-virtualization specialists over hardware-dependent incumbents as pharmaceutical manufacturers prioritize algorithm update deployment without line shutdowns. Long-term viability across the analysis window rests on regulatory compliance automation capabilities rather than sensor hardware differentiation. Watch for FDA enforcement intensity on USP 1207 probabilistic microbial ingress models as the inflection signal for platform consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Subscription | Defends recurring revenue against Mittelstand calibration laboratory disintermediation in German pharmaceutical clusters. |
| Software Validation Capability Acquisition | Addresses scarce FDA-compliant documentation expertise constraining vendor deployment timelines. |
| Cloud-Native Vision Platform Development | Enables Pfizer and Roche manufacturing divisions to deploy algorithm updates without production line shutdowns. |
| Mid-Speed Platform Localization | Captures CDMO expansion demand in Hyderabad and Ahmedabad corridors with simplified validation protocols. |
| Embedded Audit Trail Automation | Preempts regulatory inspection findings for aseptic filling operations in Ireland and Switzerland under EMA Annex 1. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with packaging line engineers, quality validation specialists, pharmaceutical manufacturing executives, and aftermarket service heads; and secondary validation against FDA 483 inspection observations, EMA GMP inspection databases, SEC equipment vendor filings, and pharmaceutical packaging trade association technical guidelines. Bottom-up triangulation across product type, technology modality, application segment, and end-user category reconciled with top-down market sizing from regulatory mandate penetration curves.
Forecast inputs considered optical imaging sensor cost trajectories, helium supply concentration risk premiums, and regulatory enforcement intensity differentials between FDA risk-based and EU prescriptive approaches across the projection horizon. Segmentation dimensions modeled include detection technology, inspection speed tier, compliance automation level, and regional regulatory cluster. CAGRs derived from equipment procurement cycle compression and aftermarket service contract unbundling trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native vision platform entrants or specialized calibration service providers would shift outcomes. Macroeconomic deviation in pharmaceutical capital expenditure cycles, regulatory enforcement intensity changes, or acoustic emission detection threshold breakthroughs would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Plasma Feeder Market
Industrial Equipment
Refrigeration Coolers Market
Industrial Equipment
Hot Runner Temperature Controller Market
Industrial Equipment
Jet Dispenser Market
Industrial Equipment
Precision Positioning Equipment Market
Industrial Equipment
Dust Collector Systems Market
Industrial Equipment
Latin America Explosion-Proof Equipment Market
Industrial Equipment
Cartridge Heaters Market
Industrial Equipment
Bellows Vacuum Suction Cup Market
Industrial Equipment
Global Dicing Blades Market
Industrial Equipment
Industrial Magnetrons Market
Industrial Equipment
Electric Cartridge Heaters Market
Industrial Equipment
Europe Ceramic Roller Bearings Market
Industrial Equipment
Press-Insertion Systems Market
Industrial Equipment
Machine Tool Cooling System Market
Industrial Equipment
Laser Drilling Market