
 Glass Engraving Machines Market | 2026-2036
Glass Engraving Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Engraving Machines Market Analysis
A capital-intensity divergence between players is bifurcating competitive dynamics across the glass engraving machines landscape. Trotec Laser GmbH leverages its Austrian engineering heritage to sustain premium positioning in CO2 and fiber laser platforms for architectural glass. Gravotech anchors European demand through integrated software-hardware workflows that dominate trophy and industrial marking segments. Wisely Laser Machinery Limited competes on manufacturing scale, occupying cost-sensitive tiers in Asia-Pacific export markets.
Glass engraving machines are precision systems that ablate, etch, or cut surface layers of glass substrates using laser, mechanical, or abrasive technologies, typically operating at wavelengths between 1064 nm and 10600 nm with positioning accuracies below 50 microns to achieve permanent decorative or functional markings. Laser engraving machines lead product type revenue due to contactless processing that eliminates tooling wear on brittle silica-based substrates. Mechanical engraving retains share in deep-relief architectural applications where tactile depth exceeds laser ablation thresholds. Waterjet technology represents the fastest-growing segment for thick laminated glass in commercial signage, though abrasive disposal costs compress margins relative to dry laser processes.
FDA regulations govern laser classification and operator safety protocols for glass engraving systems deployed in pharmaceutical packaging lines, while EU CE marking mandates electromagnetic compatibility and machinery directive compliance for equipment sold across member states. ISO 11553 laser safety standards shape product design requirements, forcing manufacturers to integrate interlocked enclosures and emission monitoring. Stakeholders must weigh wavelength selection against evolving substrate portfolios as borosilicate and chemically strengthened glasses expand beyond traditional soda-lime applications.
Market Dynamics
EU REACH compliance is forcing material traceability investments across decorated glass supply chains, compressing procurement timelines for engraving equipment while expanding laser system specifications for serialized marking. Equipment vendors now face accelerated R&D cycles to maintain certification alignment.
Growth Catalysts
- Laser wavelength diversification:Fiber and UV laser platforms are capturing pharmaceutical packaging lines as FDA safety protocols mandate permanent, non-contact marking for traceability. Equipment orders from drug manufacturers in Germany and Switzerland are accelerating system upgrades.
- REACH material mandates:EU regulations on chemical disclosure are pushing luxury perfume and spirits brands toward laser-engraved decorative glass, eliminating inks and coatings that trigger compliance audits. French and Italian packaging houses are leading procurement.
- Architectural glass specification:Deep-relief mechanical engraving systems are seeing renewed demand from Middle Eastern commercial developments seeking tactile surface treatments for interior glazing. Dubai and Riyadh project pipelines are driving order backlogs.
Market Restraints
- Optics supply concentration:High-power CO2 laser resonators and precision galvo scanners concentrate among German and Japanese component suppliers, exposing equipment assemblers to extended lead times and input cost volatility.
- Technical ablation thresholds:Laser systems face fundamental limitations achieving tactile depth beyond 2mm in borosilicate substrates, preserving mechanical engraving's niche in deep-relief architectural applications despite slower throughput.
- Waterjet abrasive disposal:Thick laminated glass processing generates significant garnet waste streams, with disposal compliance costs compressing margins relative to dry laser processes in commercial signage production.
Strategic Opportunities
- India pharmaceutical expansion:CDSCO serialization mandates for exported drug packaging are creating first-time laser engraving demand among domestic glass container manufacturers, with Mumbai and Hyderabad clusters representing untapped equipment penetration.
- AI-integrated vision systems:Machine learning-based defect detection converging with laser positioning controllers is enabling real-time quality adjustment, opening premium pricing tiers for zero-defect pharmaceutical marking contracts.
- Service unbundling:Equipment vendors are separating hardware sales from software licensing and maintenance contracts, creating recurring revenue streams through cloud-based design libraries and remote diagnostic subscriptions.
Industry Challenges
- Laser safety engineering talent:ISO 11553 compliance expertise remains scarce among system integrators, extending certification timelines and forcing vendors to retain specialized consultants for interlock design and emission monitoring integration.
- Legacy mechanical system integration:Hybrid production lines combining laser and mechanical engraving require complex workflow orchestration, with pharmaceutical manufacturers reporting 6-9 month commissioning periods for validated multi-process cells.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Engraving Machines Market |
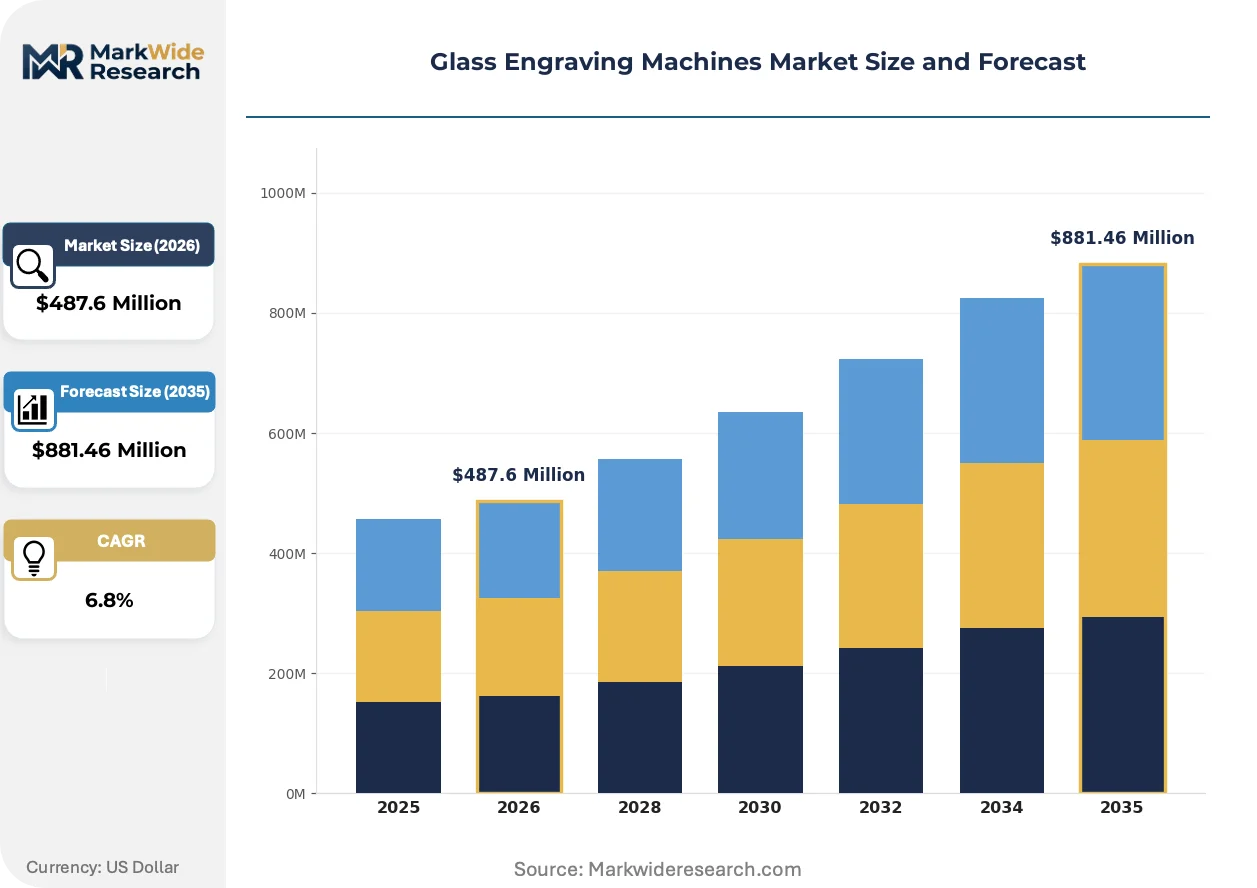
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CNC Engraving Machines, Laser Engraving Machines, Handheld Engraving Tools, Rotary Engraving Machines Technology: Laser, Mechanical, Waterjet, Sandblasting Application: Architectural Decor, Personalized Gifts, Awards and Trophies, Signage End User: Artisans, Manufacturers, Retailers, Commercial Businesses |
| Companies Covered | Universal Laser Systems, Trotec Laser GmbH, Gravotech, Epilog Laser, LaserStar Technologies Corporation, GCC, Kern Laser Systems, Vytek Laser Systems, Wisely Laser Machinery Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Engraving Machines Market Emerging Trajectories
Glass engraving technology is bifurcating between high-speed laser platforms for serialized industrial marking and precision mechanical systems for tactile decorative applications, with software-defined control architectures enabling rapid format switching between these modes.
Ultrafast picosecond laser sources are fragmenting competitive positioning in high-value pharmaceutical and electronics glass applications. Swiss and German medical device manufacturers are adopting these systems for cold ablation of chemically strengthened cover glass without microcrack propagation. The technology is fragmenting vendor tiers, separating premium-positioned suppliers with in-house ultrafast source development from assemblers dependent on external component procurement.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are reshaping cooling system specifications for high-power CO2 laser platforms. Equipment manufacturers must now certify alternative refrigerant circuits or liquid cooling architectures to maintain CE marking eligibility. German and Austrian laser system builders are accelerating thermal management R&D to preserve European market access ahead of phasedown deadlines.
Brand owners are consolidating approved vendor lists for decorated glass packaging, compressing qualification timelines and demanding outcome-based performance guarantees rather than equipment specifications alone. French luxury goods houses and Italian spirits brands are piloting throughput-commitment contracts where engraving system suppliers assume operational risk for line efficiency. This restructuring is most visible in Champagne and Prosecco bottling corridors, where packaging speed directly ties to seasonal revenue realization.
Glass Engraving Machines Market Segmentation
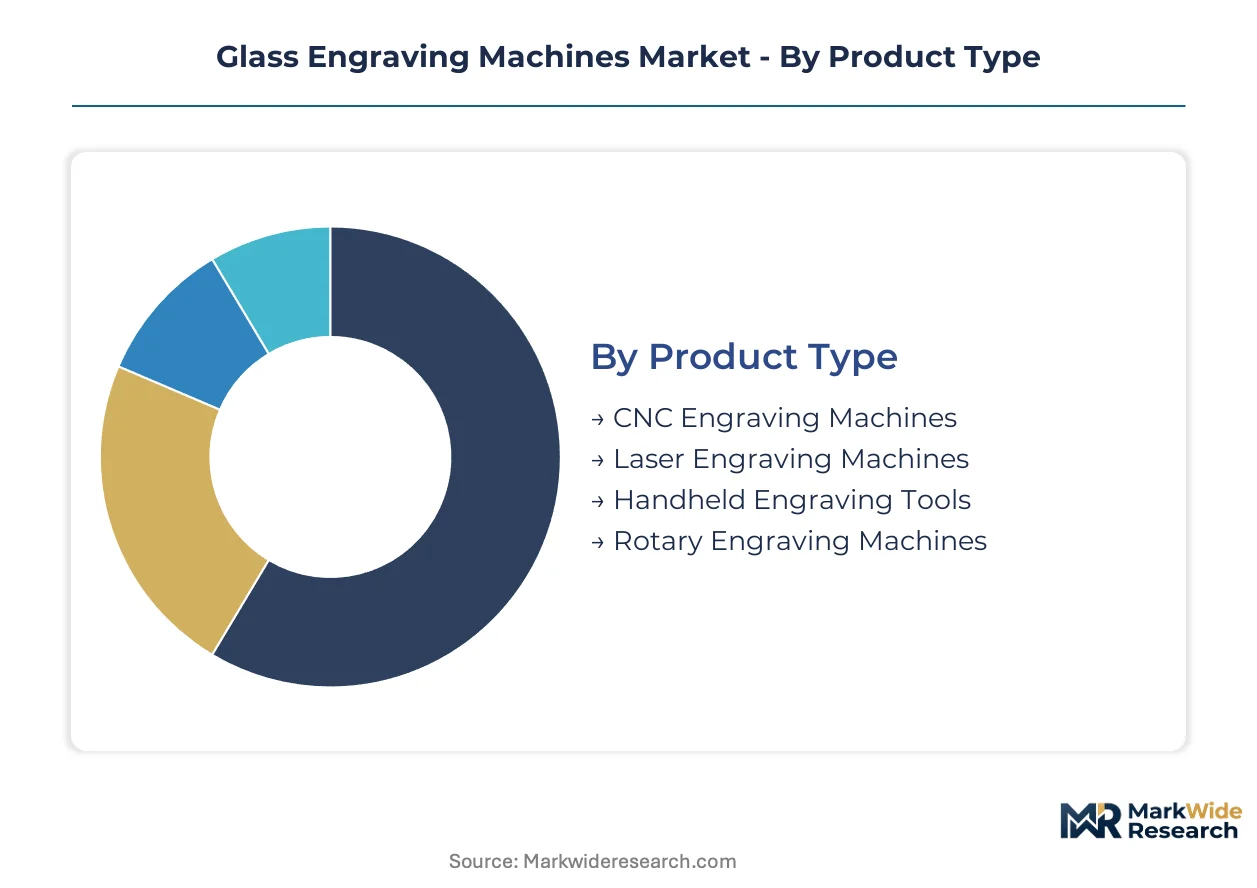
Technology and application boundaries in glass engraving machines are blurring as multi-modal systems gain traction. Vendors now configure platforms around specific wavelength-engineering combinations rather than rigid product categories, forcing buyers to evaluate total cost of ownership across substrate portfolios.
Product Type:
Margin pools concentrate in systems offering software-defined control architectures that enable rapid reconfiguration between decorative and industrial marking modes without hardware swaps.
- Laser Engraving Machines:These systems deploy fiber, CO2, or UV sources at wavelengths between 1064 nm and 355 nm with galvo-steered beam delivery achieving positioning accuracies below 50 microns. Pharmaceutical packaging lines in Germany and Switzerland are driving procurement as FDA safety protocols mandate permanent, non-contact serialization for traceability compliance.
- CNC Engraving Machines:Computer-numerical-control platforms execute deep-relief cutting through diamond-tipped or carbide tooling on spindle systems with multi-axis positioning. Demand concentrates in Middle Eastern commercial developments where Dubai and Riyadh project pipelines require tactile surface treatments exceeding 2mm depth thresholds that laser ablation cannot achieve.
- Rotary Engraving Machines:Mechanical systems employing rotating cutters for cylindrical glass surfaces.
- Handheld Engraving Tools:Portable pneumatic or electric devices for artisan-scale customization.
Laser Engraving Machines hold installed capacity. CNC Engraving Machines is rotating up the share rankings.
Technology:
Cost tier stratification separates capital-intensive laser platforms from abrasive processes burdened by consumable and disposal economics.
- Laser:Contactless photothermal or photochemical ablation using fiber, CO2, or ultrafast sources eliminates tooling wear on brittle silica substrates. EU F-Gas Regulation restrictions on fluorinated refrigerants are forcing thermal management redesigns in high-power CO2 systems to preserve CE marking eligibility.
- Mechanical:Physical material removal through diamond drag, rotary cutting, or milling preserves dominance in architectural deep-relief applications where tactile depth requirements exceed laser thresholds. French luxury packaging houses specify these systems for premium spirits bottle engraving where surface texture conveys brand positioning.
- Waterjet:Abrasive-laden high-pressure streams process thick laminated glass for commercial signage.
- Sandblasting:Propelled abrasive media for matte surface finishing on architectural panels.
Mechanical technology holds installed capacity. Laser is rotating up the share rankings.
Application:
Volume concentration tracks the seasonal production cycles of beverage packaging and the project-based rhythms of commercial construction.
- Awards and Trophies:Precision marking of crystal and optical glass for recognition products demands high-contrast, permanent engraving without subsurface damage. Gravotech's integrated software-hardware workflows dominate this segment through automated design-to-production pipelines that reduce per-unit processing time.
- Architectural Decor:Large-format glazing treatments for interior and exterior building applications require systems handling sheet sizes up to 3 meters with consistent depth control. Middle Eastern developments in Dubai and Riyadh are driving order backlogs for deep-relief mechanical systems capable of tactile surface treatments.
- Signage:Commercial display and wayfinding applications on flat and curved glass substrates.
- Personalized Gifts:Small-batch customization for consumer retail channels.
Awards and Trophies holds installed capacity. Architectural Decor is rotating up the share rankings.
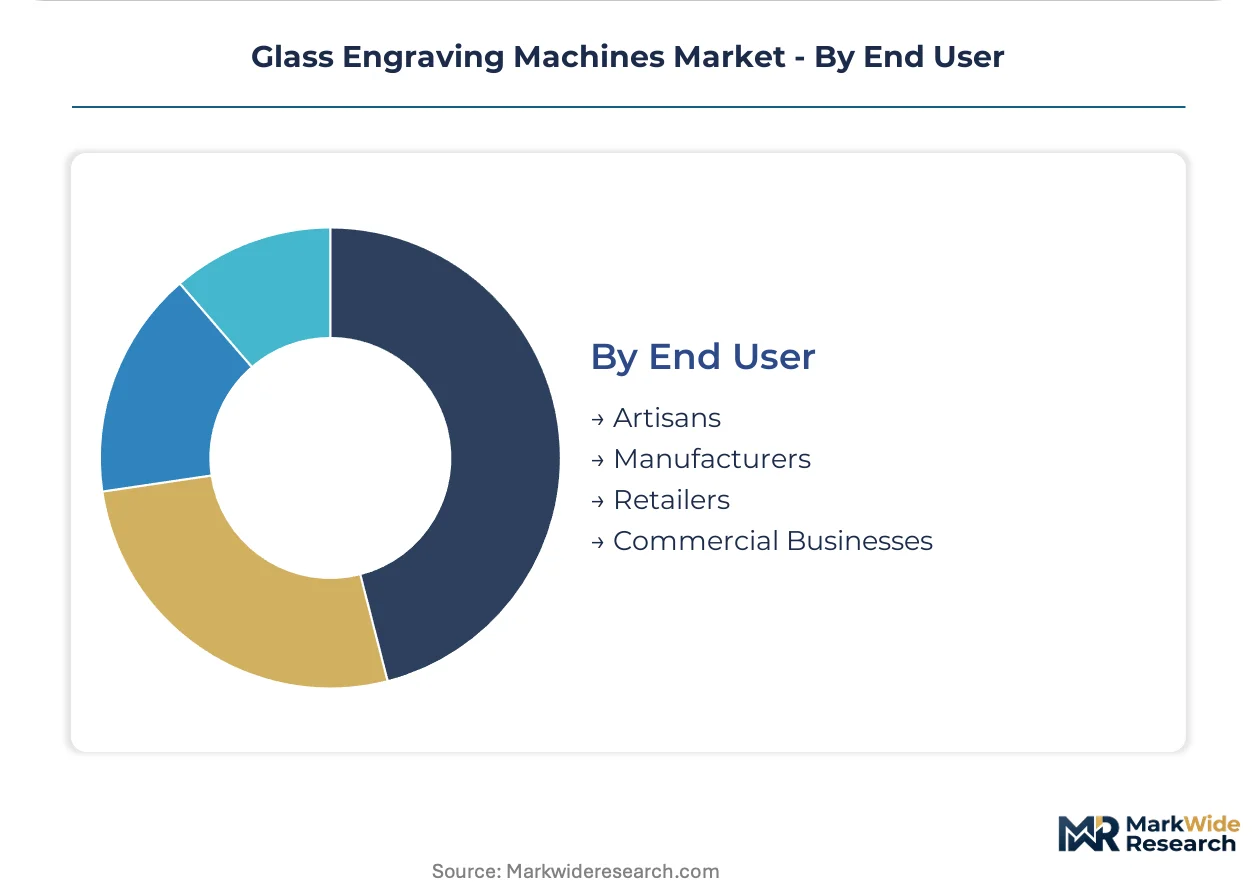
End User:
Customer type determines purchasing authority structure, with manufacturers demanding validated production cells and artisans prioritizing capital accessibility.
- Manufacturers:Industrial-scale producers of glass containers, automotive glazing, and electronics cover glass require throughput-optimized systems with integrated vision inspection. CDSCO serialization mandates for exported drug packaging are creating first-time laser engraving demand among domestic glass container manufacturers in Mumbai and Hyderabad clusters.
- Commercial Businesses:Signage producers, interior design firms, and brand experience agencies purchase mid-tier systems for project-based revenue generation. These buyers are consolidating approved vendor lists and demanding outcome-based performance guarantees rather than equipment specifications alone.
- Artisans:Independent craftspeople and small studios serving personalized gift and restoration markets.
- Retailers:Consumer-facing engraving services in mall kiosks and specialty stores.
Manufacturers holds installed capacity. Commercial Businesses is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement contexts. German pharmaceutical manufacturers absorb premium laser system costs for FDA-validated production lines, while Indian packaging converters prioritize capital efficiency amid first-time serialization equipment purchases.
Germany
Precision engineering clusters around Stuttgart and Munich sustain demand for high-throughput fiber laser platforms serving automotive glazing and pharmaceutical container serialization. EU CE marking and machinery directive compliance shape equipment specifications, with interlocked safety enclosures now mandatory. The Baden-Württemberg precision optics corridor concentrates galvo scanner and resonator component supply.
United States
FDA laser classification protocols govern pharmaceutical packaging line deployments, driving system upgrades for permanent traceability marking. OSHA workplace safety standards intersect with state-level environmental regulations on abrasive waste disposal for waterjet operations. Arizona and California house concentrated demand from craft spirits producers and architectural glass fabricators.
India
CDSCO serialization mandates for exported drug packaging are creating first-time laser engraving demand among domestic glass container manufacturers. BIS certification requirements for imported industrial equipment extend procurement timelines. Mumbai and Hyderabad pharmaceutical packaging clusters represent untapped equipment penetration opportunities.
United Arab Emirates
MOHAP pharmaceutical traceability regulations are aligning with Gulf standardization initiatives, expanding laser marking specifications for regional drug distribution. Dubai commercial development pipelines require deep-relief mechanical engraving systems for tactile architectural glazing treatments. Riyadh project backlogs in neighboring Saudi Arabia spill over into UAE equipment procurement channels.
Switzerland
Swissmedic medical device regulations mandate cold ablation capabilities for chemically strengthened cover glass processing, accelerating ultrafast picosecond laser adoption. Geneva and Basel pharmaceutical manufacturing corridors demand zero-defect marking contracts with AI-integrated vision systems. Precision watchmaking heritage supports adjacent glass engraving competency clusters.
Glass Engraving Machines Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the glass engraving machines landscape. European specialists anchor premium tiers through precision engineering heritage and integrated software-hardware workflows. Asian manufacturers occupy volume-driven segments through manufacturing scale advantages. Competitive dynamics center on wavelength diversification R&D and service unbundling into recurring revenue streams.
Among Austrian and European engineering-based specialists, Trotec Laser GmbH exemplifies premium-tier positioning through CO2 and fiber laser platform development. Gravotech represents integrated workflow dominance in trophy and industrial marking segments. Wisely Laser Machinery Limited occupies the scale-driven manufacturing tier serving Asia-Pacific export markets. These three archetypes illustrate the capital-intensity divergence bifurcating procurement channels.
| Leading Market Players |
|---|
| Universal Laser Systems |
| Trotec Laser GmbH |
| Gravotech |
| Epilog Laser |
| LaserStar Technologies Corporation |
| GCC |
| Kern Laser Systems |
| Vytek Laser Systems |
| Wisely Laser Machinery Limited |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation compliance gates both supplier qualification and price differentiation simultaneously, forcing equipment vendors to absorb thermal management R&D costs or forfeit CE marking eligibility while buyers face tiered access based on refrigerant certification status. This regulatory filter compresses margins for non-compliant assemblers and concentrates pricing power among German and Austrian system builders with in-house cooling architectures.
Pricing Analysis
After-sales revenue tiers—spanning cloud-based design libraries, remote diagnostic subscriptions, and extended maintenance contracts—now drive lifetime value beyond hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical production cells from trophy-shop fiber lasers and artisan-scale mechanical engravers. Cost compression in mid-tier CO2 platforms is intensifying because galvo scanner lead times from Baden-Württemberg suppliers extend procurement cycles. Artisans and small studios exhibit highest price sensitivity, while Swiss pharmaceutical manufacturers absorb premium positioning for zero-defect marking contracts.
Supply Chain Analysis
Germany and Japan anchor precision component fabrication, with Stuttgart optics corridors producing high-power resonators and galvo scanners while Japanese suppliers concentrate ultraviolet source manufacturing. Equipment assemblers draw from borosilicate substrate specialists, rare-earth doped fiber suppliers, and precision motion control vendors. Single-source vulnerability in ultrafast picosecond laser diodes exposes European system integrators to allocation constraints. Distribution runs through OEM-direct channels for pharmaceutical validators and regional distributor networks for commercial signage producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass engraving machines occupy early-cycle expansion territory as serialization mandates across pharmaceutical packaging create first-time equipment demand in India and the Middle East. Regulatory tailwinds from FDA traceability protocols and EU REACH material disclosure accelerate replacement cycles beyond traditional decorative applications.
For Market Incumbents: Fortify wavelength diversification R&D to preserve premium positioning against Asian scale competitors entering fiber laser tiers. Backward integration into galvo scanner production mitigates lead time volatility from Baden-Württemberg component suppliers. ISO 11553 compliance expertise scarcity extends certification timelines—captive safety engineering teams accelerate time-to-market for pharmaceutical validators.
For New Entrants and Emerging Players: Differentiate on AI-integrated vision systems that enable real-time quality adjustment during laser ablation. Mumbai and Hyderabad pharmaceutical packaging clusters represent penetrable white space amid CDSCO serialization mandates. Target outcome-based performance contracts where suppliers assume operational risk for line efficiency, mirroring Champagne corridor procurement pilots.
For Investors and Strategic Acquirers: EU F-Gas Regulation phasedown deadlines reshape the acquisition landscape toward thermal management competency and alternative refrigerant certification. Long-term viability centers on software-defined control architectures enabling rapid format switching between decorative and industrial modes. Acquisition targets include mid-cap specialists with in-house ultrafast source development. The signal to watch is consolidation of approved vendor lists by French luxury goods houses and Italian spirits brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Wavelength Diversification R&D | Fiber and UV platforms capture pharmaceutical serialization mandates from FDA and Swissmedic. |
| AI-Vision System Integration | Machine learning defect detection opens premium pricing tiers for zero-defect pharmaceutical contracts. |
| Service Revenue Unbundling | Cloud-based design libraries and remote diagnostics create recurring revenue streams beyond hardware sales. |
| Backward Integration into Optics | In-house galvo scanner production reduces dependency on Stuttgart and Japanese component suppliers. |
| Geographic Expansion to India | CDSCO mandates create first-time demand among Mumbai and Hyderabad glass container manufacturers. |
Methodological Framework
A spread of perspectives from equipment procurement managers at pharmaceutical packaging houses, aftermarket service directors, laser safety engineering consultants, and precision optics component suppliers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC filings of listed laser system vendors, EU F-Gas Regulation implementation guidance, FDA laser classification databases, and CDSCO serialization directive documents. Bottom-up equipment shipment estimates triangulated against top-down addressable market calculations across the analysis window.
Segmentation dimensions modeled include technology type, product platform, application vertical, end-user category, and geographic regulatory cluster. Value outputs reflect unit economics derived from disclosed system pricing tiers and attach rates for software licensing and maintenance contracts. CAGRs were computed from trajectory fitting across the projection horizon. Industry-specific forecast inputs incorporated pharmaceutical serialization mandate timelines and commercial development pipelines in Dubai and Riyadh.
Material uncertainties—regulatory enforcement intensity, component allocation constraints, and substrate portfolio shifts toward chemically strengthened glass—sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline standardization and buyer consolidation of approved vendor lists. Recalibration cycles align with material shifts in EU F-Gas phasedown schedules and CDSCO mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Vacuum Furnaces Market
Industrial Equipment
Mounted Bearing Market
Industrial Equipment
Bellows Vacuum Suction Cup Market
Industrial Equipment
Electron Beam Welding Systems Market
Industrial Equipment
Ultrasonic Atomizer Market
Industrial Equipment
Global Dicing Blades Market
Industrial Equipment
Machine Tool Cooling System Market
Industrial Equipment
Global Twister Winder Market
Industrial Equipment
Seal Inspection Equipment Market
Industrial Equipment
North America Fans and Blowers Market
Industrial Equipment
Parts and Equipment Market
Industrial Equipment
Industrial Refrigeration Systems Market
Industrial Equipment
Laser Processing Market
Industrial Equipment
Compositing Equipment Market
Industrial Equipment
Digital Load Indicator Market
Industrial Equipment
Electric Actuator Market