
 Global Industrial Actuators Market | 2026-2036
Global Industrial Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Actuators Market Outlook
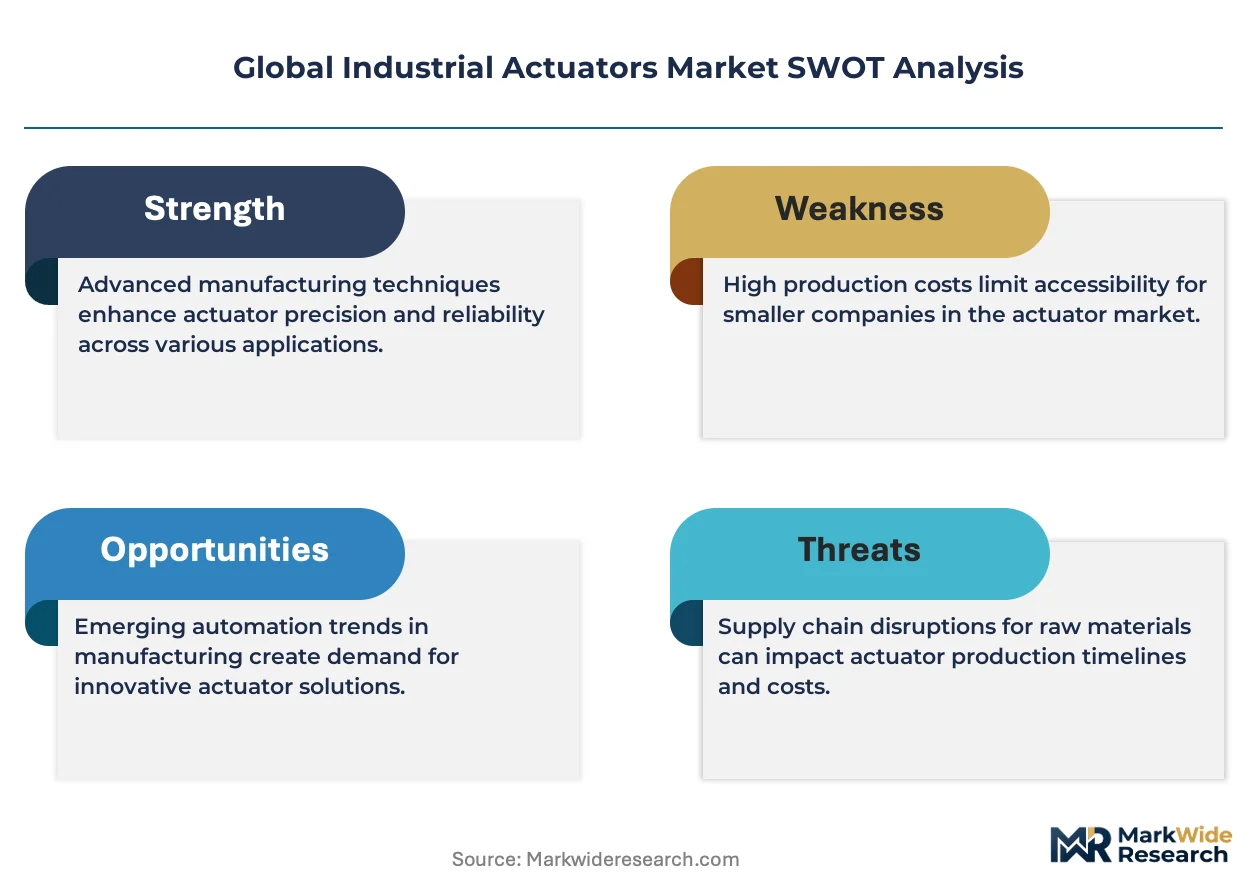
The EU Green Deal is decoupling carbon-intensive pneumatic systems from new facility approvals across European process industries. Rockwell Automation leverages its integrated automation portfolio to capture retrofit demand in energy-intensive sectors. Festo AG & Co. KG anchors its position through pneumatic-to-electric transition programs for automotive OEMs. Emerson Electric Co. competes on valve-actuator integration for critical oil and gas infrastructure.
Industrial actuators are electromechanical, pneumatic, or hydraulic devices that convert energy into mechanical motion to position valves, dampers, or other process control elements, typically operating at pressures from 20 to 150 psi for pneumatic variants and torque outputs spanning 10 to 100,000 Nm for electric models. Their primary industrial purpose is enabling precise, remote, or automated control of fluid and gas flows in continuous and batch manufacturing operations. Electric actuators are capturing margin pools as Industry 4.0 architectures demand position feedback and predictive maintenance integration. Smart actuators are outpacing conventional variants in growth velocity as embedded sensors and IO-Link connectivity become standard specifications.
The EPA enforces emissions controls that compel oil and gas operators to replace manual valves with automated actuators for fugitive methane reduction, while ISO 5211 governs mounting interface standards that determine product interoperability across valve manufacturers. China's MIIT promotes domestic actuator substitution through GB standard harmonization and dual carbon goals that favor electric over pneumatic drive technologies. Stakeholders must weigh the capital intensity of smart actuator platforms against the operational savings from predictive failure detection and reduced unplanned downtime.
Market Dynamics
The EU Green Deal is decoupling carbon-intensive pneumatic systems from new facility approvals, forcing process industries toward electric actuation architectures. This regulatory pivot is compressing technology transition timelines and rewiring supplier-customer relationships across European manufacturing corridors.
Growth Catalysts
- Water treatment infrastructure modernization:Municipal operators are expanding actuator deployments for remote valve control in aging distribution networks. Federal infrastructure programs in the US and similar frameworks in Germany are accelerating capital allocation.
- REACH and F-Gas Regulation compliance:Chemical processors must replace pneumatic drives to meet fluorinated gas phase-down mandates. Electric actuators eliminate compressor-dependent leakage pathways.
- Industry 4.0 architecture mandates:Automotive OEMs in Germany's industrial corridor require precision motion control with embedded position feedback. Smart actuators with IO-Link connectivity satisfy predictive maintenance integration specifications.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet motors in high-torque electric actuators depend on neodymium processing dominated by Chinese refiners. Geopolitical friction threatens input cost stability.
- Capital intensity of smart platforms:Embedded sensor arrays and edge computing modules raise unit costs versus conventional pneumatic alternatives. Small and mid-size process operators defer replacement cycles.
- Pneumatic system installed base inertia:Compressed air infrastructure in legacy plants represents sunk capital that electric retrofit projects must write off. Facility engineers prioritize incremental upgrades over line-wide replacement.
Strategic Opportunities
- India process automation underpenetration:The country's specialty chemical sector operates with manual valve prevalence exceeding developed-market benchmarks. BIS standard harmonization under PLI incentives lowers import barriers for certified electric suppliers.
- Offshore platform electrification:North Sea operators are eliminating pneumatic supply vessels to reduce carbon intensity. Subsea electric actuators with pressure-compensated housings capture valve control contracts.
- ISO 5211 integration services:Valve-actuator mounting interface standardization creates aftermarket attachment and calibration revenue streams. System integrators bundle interoperability verification with commissioning contracts.
Industry Challenges
- Mechatronics skill scarcity:Electric actuator maintenance requires competencies spanning motor control, sensor diagnostics, and network protocols. Technical training programs lag deployment velocity in industrial clusters.
- Legacy DCS integration complexity:Smart actuators with digital positioners must interface with analog-era distributed control systems through protocol converters. Commissioning timelines extend when verification testing reveals signal compatibility gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Actuators Market |
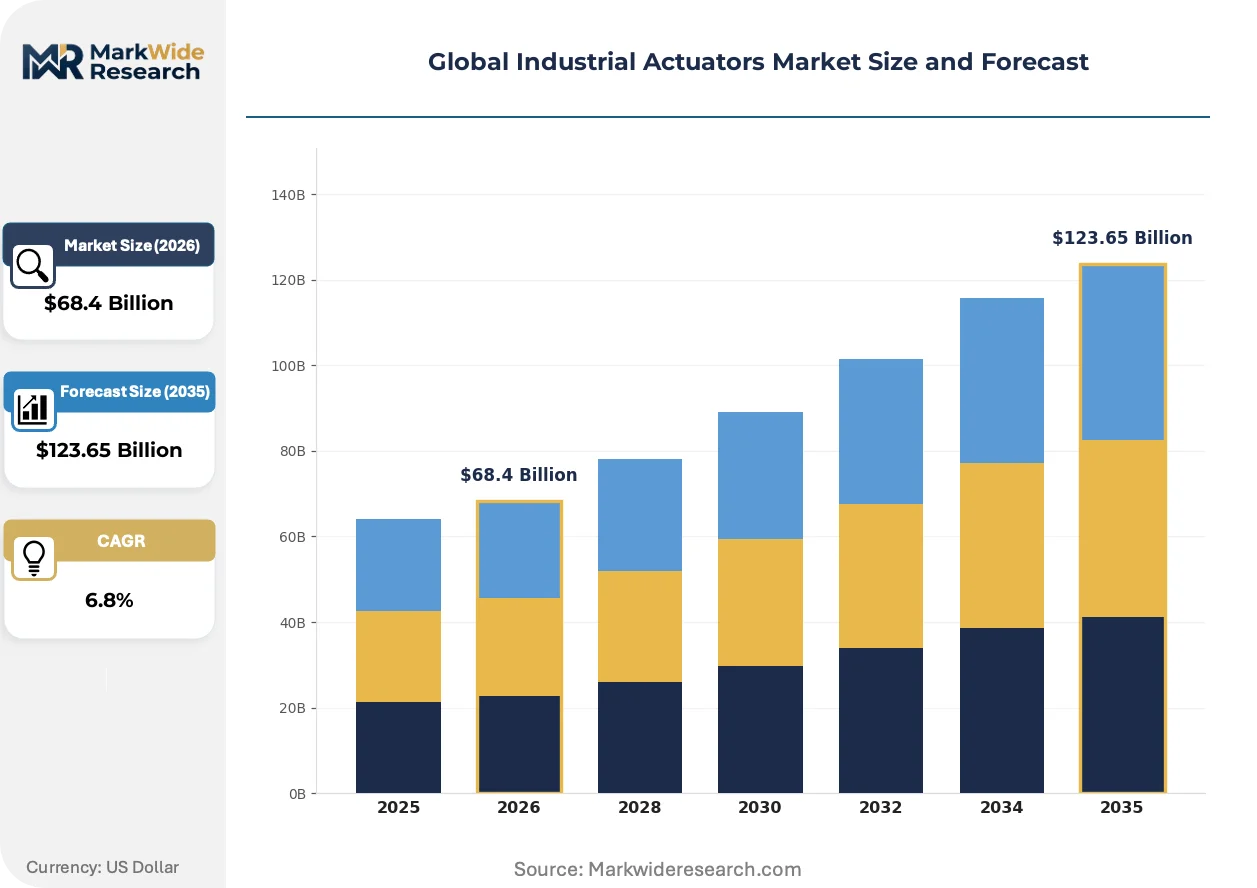
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic Actuators, Hydraulic Actuators, Electric Actuators, Mechanical Actuators Industry Vertical: Manufacturing, Oil & Gas, Automotive, Aerospace End User: Industrial Machinery, Energy, Transportation, Automation Technology: Smart Actuators, Conventional Actuators, Low Power Actuators, Servo Actuators |
| Companies Covered | Rockwell Automation, Festo AG & Co. KG, Emerson Electric Co., Rotork plc, Flowserve Corporation, Parker Hannifin Corp, SMC Corporation, Moog Inc., ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Actuators Market Strategic Shifts
Digital positioner technology is unifying sensing, control, and communication functions within single actuator housings. This convergence is compressing the distinction between motion devices and edge computing nodes.
Intelligent valve controllers with embedded diagnostics are unifying vibration monitoring, stroke-time analysis, and friction profiling into continuous health assessment streams. Oil and gas operators in the US Gulf Coast are deploying these units to satisfy EPA fugitive methane monitoring mandates. The technology is unifying maintenance scheduling with emissions compliance reporting, eliminating separate inspection workflows.
China's MIIT dual carbon policy framework is mandating electric drive substitution in new process facility approvals. GB standard harmonization for actuator efficiency ratings is creating technical barriers for imported pneumatic equipment. Domestic manufacturers are capturing substitution demand through localized servo motor production.
Asset-as-a-service contracting is restructuring capital deployment patterns among water utilities. Municipal buyers are deferring actuator ownership in favor of performance-guaranteed availability contracts. This shift concentrates vendor risk and accelerates predictive analytics adoption in Germany's municipal infrastructure sector.
Global Industrial Actuators Market Segmentation
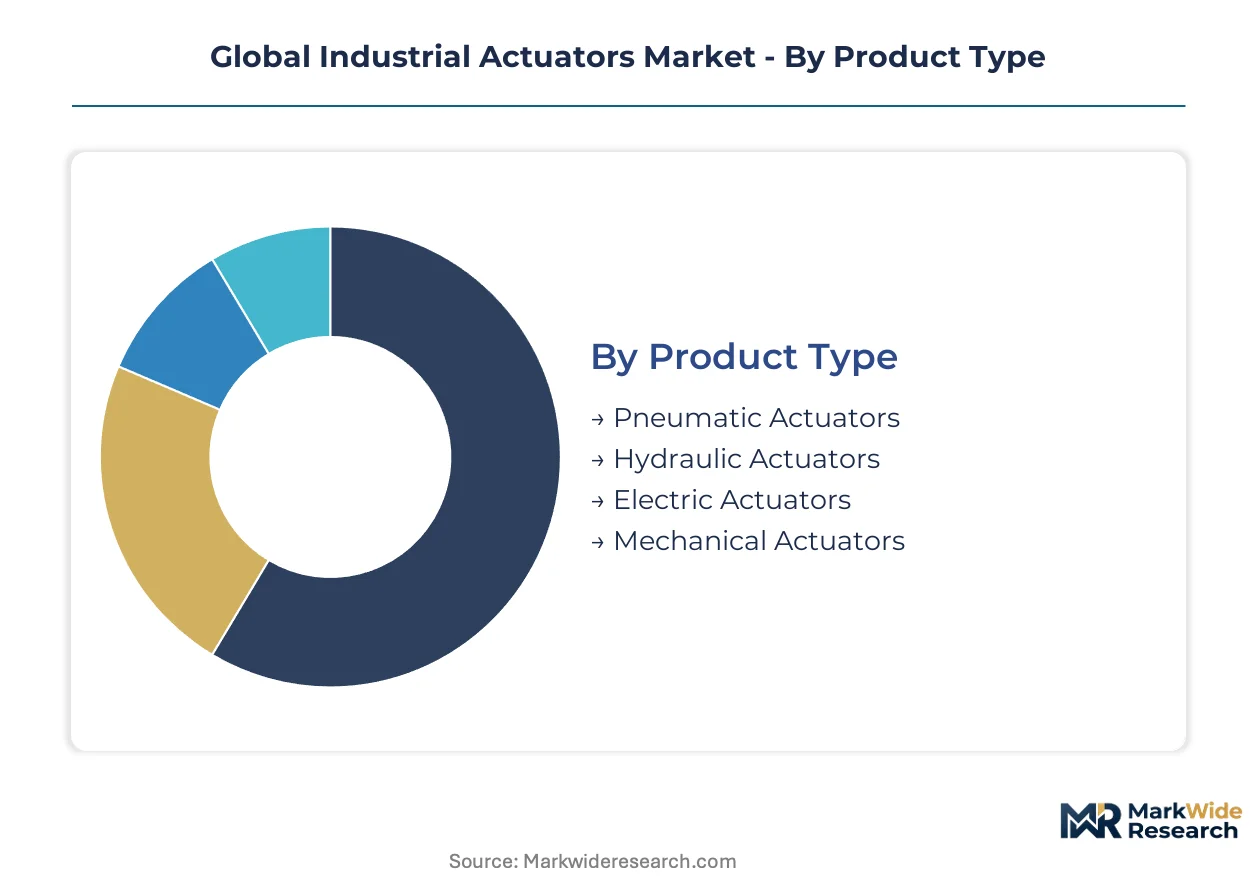
Industrial actuator procurement splits sharply between standardized commodity units for bulk replacement and engineered-to-order systems for critical process applications. Specification complexity varies dramatically across product architectures, with electric and smart variants demanding deeper integration services than pneumatic alternatives. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume flows.
Product Type:
The customization-to-standardization spectrum runs widest here, with pneumatic units representing mature catalog products while electric systems require torque-range matching and control protocol configuration.
- Electric Actuators:Permanent magnet synchronous motors deliver precise positioning with encoder feedback for closed-loop control. Demand concentrates in Germany's automotive manufacturing corridor where Industry 4.0 architectures mandate IO-Link connectivity and predictive maintenance integration. The EU Green Deal's decoupling of pneumatic systems from new facility approvals accelerates specification shifts.
- Pneumatic Actuators:Compressed air-driven piston or diaphragm mechanisms operate at 20-150 psi with simple on/off or modulating control. Volume persists in legacy chemical processing facilities across the US Gulf Coast where sunk compressed air infrastructure delays electric retrofit economics. EPA fugitive methane rules nonetheless force automated valve upgrades even within pneumatic architectures.
- Hydraulic Actuators:Oil-pressure systems generating 10,000+ psi for extreme force applications in heavy machinery and offshore equipment.
- Mechanical Actuators:Screw, lever, or gear-based motion conversion without external power, specified where electrical hazards prohibit powered alternatives.
Most installed capacity flows through pneumatic actuators. Expansion is steepest in electric actuators.
Industry Vertical:
Cost tier segmentation dominates here, with oil and gas commanding premium-specification units while manufacturing procurement optimizes for lifecycle cost.
- Oil & Gas:Explosion-proof enclosures and SIL-rated fail-safe mechanisms for wellhead and pipeline valve control. Demand localizes to the US Permian Basin and North Sea platforms where EPA and EU methane regulations compel automated leak detection. Subsea electrification projects specify pressure-compensated housings.
- Manufacturing:General-purpose linear and rotary actuators for material handling and process equipment. Germany's process automation upgrade cycle drives specification toward smart actuators with embedded diagnostics.
- Automotive:High-speed precision actuation for robotic welding and assembly lines.
- Aerospace:Lightweight, high-reliability units for flight control surface and landing gear mechanisms.
Highest average selling prices attach to oil and gas specifications. Fastest volume expansion occurs in manufacturing verticals.
End User:
Customer type segmentation separates owner-operators with captive maintenance capabilities from outsourcing-dependent utilities.
- Energy:Power generation and distribution operators requiring grid-stability-responsive valve control. Germany's municipal utilities are adopting asset-as-a-service contracting models that transfer actuator ownership risk to vendors.
- Industrial Machinery:OEM equipment builders specifying actuators for original integration. China's MIIT dual carbon policies favor domestic electric actuator suppliers through GB standard harmonization.
- Transportation:Rail and marine applications with shock-resistant and corrosion-proof requirements.
- Automation:System integrators bundling multi-vendor actuator packages with commissioning services.
Energy sector procurement concentrates the largest project values. Automation channel sales are climbing fastest.
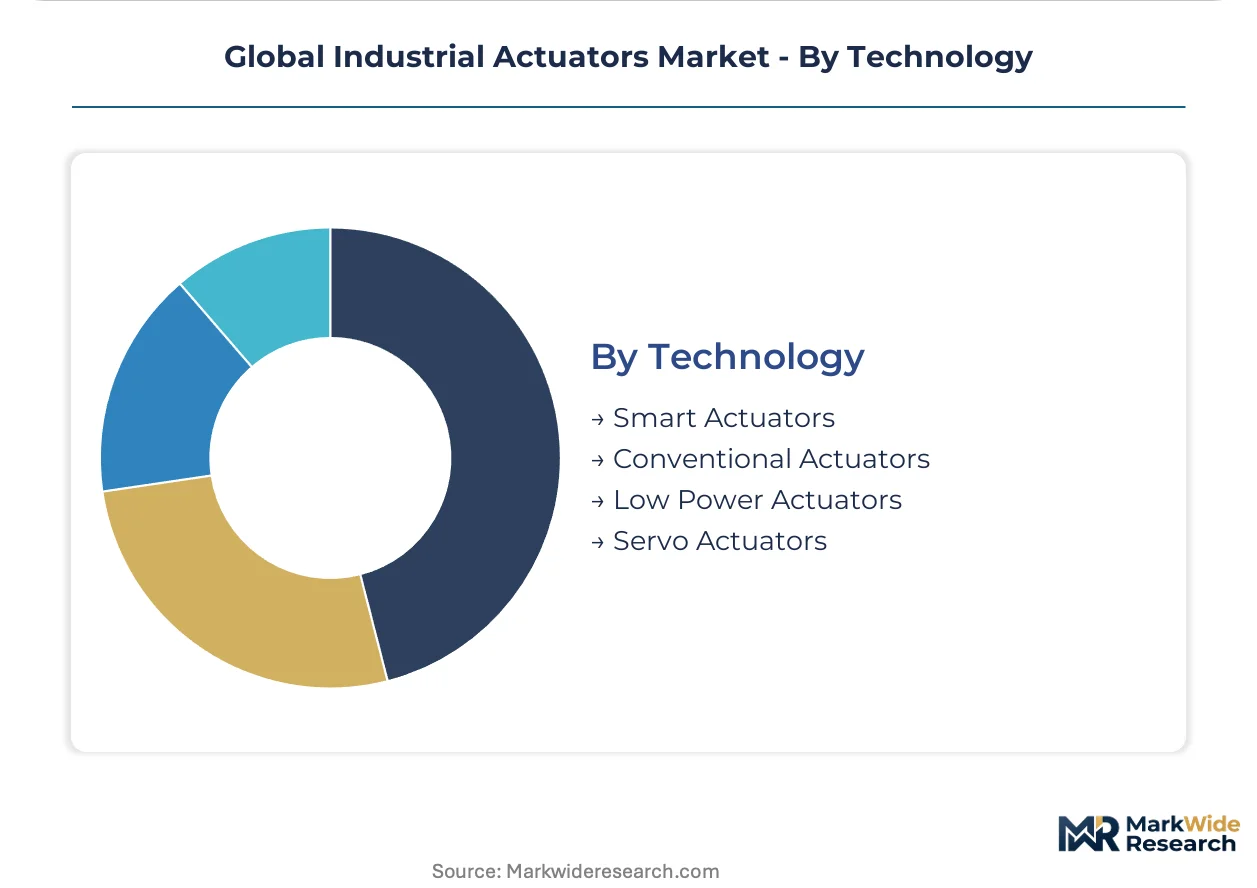
Technology:
Maturity-stage segmentation distinguishes legacy architectures from digitally native designs with embedded intelligence.
- Smart Actuators:Integrated sensor arrays, edge computing, and wireless connectivity enabling condition monitoring and autonomous calibration. US water treatment infrastructure operators deploy these for remote valve control in aging distribution networks. Federal infrastructure programs accelerate capital allocation.
- Conventional Actuators:Basic electromechanical or pneumatic motion without embedded diagnostics. Installed base predominates in facilities with analog-era distributed control systems requiring protocol converter integration.
- Low Power Actuators:Energy-harvesting or battery-operated units for isolated or mobile applications.
- Servo Actuators:High-dynamic-response closed-loop systems for precision motion profiles.
Conventional technology retains the largest installed base. Smart actuators demonstrate the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial actuator manufacturing traces its modern lineage to German engineering clusters that standardized pneumatic valve control during post-war industrialization. The technology diffused through North American process industries and Japanese automotive automation before electrification architectures reshaped regional competitive positions.
United States
Water treatment infrastructure operators deploy smart actuators for remote valve control in aging municipal distribution networks. EPA fugitive methane regulations compel oil and gas operators across the Permian Basin and Gulf Coast to replace manual valves with automated systems. Federal infrastructure programs accelerate capital allocation toward electric actuation in public utilities.
Germany
Automotive OEMs in the industrial corridor demand precision motion control with embedded position feedback for Industry 4.0 integration. The EU Green Deal decouples carbon-intensive pneumatic systems from new facility approvals, forcing process industries toward electric architectures. Municipal utilities in the Ruhr and Bavaria adopt asset-as-a-service contracting models that transfer actuator ownership risk to vendors.
China
MIIT dual carbon policies mandate electric drive substitution in new process facility approvals through GB standard harmonization. Domestic manufacturers capture substitution demand through localized servo motor production. The Yangtze River Delta industrial cluster concentrates actuator assembly for export markets while serving domestic chemical and automotive verticals.
India
Specialty chemical sector operators maintain manual valve prevalence exceeding developed-market benchmarks, creating underpenetrated demand. BIS standard harmonization under PLI incentives lowers import barriers for certified electric suppliers. Gujarat and Maharashtra industrial zones drive procurement growth as process automation upgrades accelerate in pharmaceutical and petrochemical facilities.
United Kingdom
North Sea offshore platform operators eliminate pneumatic supply vessels to reduce carbon intensity, specifying subsea electric actuators with pressure-compensated housings. REACH and F-Gas Regulation compliance forces chemical processors in the Humber and Teesside clusters to replace pneumatic drives. Aberdeen and London-based system integrators bundle valve-actuator interoperability verification with commissioning contracts.
Global Industrial Actuators Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the actuator value chain, creating a tiered market structure where integrated automation portfolios face specialized component suppliers. The vendor base splits between diversified industrial conglomerates and focused motion control specialists. Three archetypes dominate: full-stack automation providers, pneumatic-to-electric transition specialists, and valve-actuator integration experts. Competitive moves concentrate on strategic partnerships for Industry 4.0 connectivity and portfolio diversification into predictive maintenance services.
Among diversified automation providers, Rockwell Automation exemplifies the integrated portfolio archetype through its control systems and motion platforms. Festo AG & Co. KG anchors the pneumatic-to-electric transition specialist tier with its German engineering heritage. Emerson Electric Co. occupies a position within the valve-actuator integration segment, reflecting North American process industry roots. These three represent distinct strategic postures without implying specific market shares or operational metrics.
| Leading Market Players |
|---|
| Rockwell Automation |
| Festo AG & Co. KG |
| Emerson Electric Co. |
| Rotork plc |
| Flowserve Corporation |
| Parker Hannifin Corp |
| SMC Corporation |
| Moog Inc. |
| ABB |
| Others |
Value Chain & Pricing Dynamics
Captive servo motor production in China's Yangtze River Delta anchors both supply security and pricing power for electric actuator manufacturers serving process automation markets. This backward integration choice insulates domestic producers from rare earth magnet cost volatility while compressing landed costs for export-competitive positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates SIL-certified explosion-proof units for oil and gas from general-purpose electric actuators and legacy pneumatic alternatives. Price differentiation hinges on certification grade and after-sales service bundling, with predictive maintenance contracts commanding sustained premiums. Cost compression in the standard tier is intensifying because Chinese domestic suppliers are scaling localized permanent magnet motor output. Municipal water utilities exhibit highest price sensitivity due to budget-constrained procurement cycles, while offshore platform operators demonstrate lowest sensitivity given total-cost-of-ownership engineering specifications.
Supply Chain Analysis
Neodymium magnet supply rests on Chinese refiners controlling permanent magnet processing for high-torque electric actuator motors. Raw material dependencies span copper windings, aluminum housings, and precision-machined gear trains. Single-source vulnerability concentrates in rare earth processing capacity, with geopolitical friction threatening input cost stability. Distribution runs through OEM equipment builders and system integrators bundling valve-actuator packages with commissioning services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric actuator substitution is compressing pneumatic margins while expanding premium-tier pools for smart platforms with embedded diagnostics. This margin-expansion story rests on predictive maintenance service attach rates climbing alongside hardware specification shifts.
For Market Incumbents: Lock in aftermarket revenue streams through ISO 5211 integration services that bundle interoperability verification with commissioning contracts. Deepen backward integration into permanent magnet motor production to defend against Chinese rare earth supply leverage. Prioritize certification investment in SIL-rated fail-safe mechanisms for oil and gas verticals where regulatory compliance creates switching costs.
For New Entrants and Emerging Players: Launch via asset-as-a-service contracting models that transfer actuator ownership risk to municipal water utilities in Germany and the United States. Target India's specialty chemical sector where manual valve prevalence exceeds developed-market benchmarks and BIS standard harmonization lowers import barriers. Pursue white-space capture in subsea electric actuators for North Sea platform electrification projects eliminating pneumatic supply vessels.
For Investors and Strategic Acquirers: Consolidation pressure builds where mechatronics skill scarcity constrains electric actuator maintenance capacity expansion in industrial clusters. Long-term viability favors vendors with captive servo motor production and predictive analytics platforms. Acquisition target archetype: mid-cap specialists with valve-actuator integration expertise and established system integrator relationships. Watch EPA methane enforcement intensity and EU Green Deal facility approval timelines as inflection indicators for electric substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motor Production | Captive permanent magnet motor manufacturing insulates margins from Chinese rare earth supply concentration. |
| Predictive Maintenance Platform Development | Embedded diagnostics with IO-Link connectivity satisfy Industry 4.0 mandates in Germany's automotive corridor. |
| Asset-as-a-Service Contracting Launch | Performance-guaranteed availability contracts transfer ownership risk and concentrate vendor accountability. |
| ISO 5211 Integration Services Expansion | Valve-actuator mounting standardization creates recurring aftermarket attachment and calibration revenue. |
| Subsea Electric Actuator Certification | Pressure-compensated housings capture North Sea platform electrification contracts eliminating pneumatic systems. |
Study Parameters
Multiple input streams — primary interviews with plant engineers and OEM procurement teams, secondary validation through customs data and automation industry association reports, and technical specification analysis — were reconciled through bottom-up and top-down triangulation. Conversations with maintenance directors, aftermarket service heads, and system integrators supplied operational deployment patterns. Secondary sources included SEC filings from diversified automation providers, trade flow databases tracking actuator imports, and regulatory filings with EPA and EU ECHA.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass product architecture, industry vertical, end-user type, and technology maturity stage. CAGRs were derived from installed base replacement velocity analysis and greenfield facility approval trajectories. Forecast inputs incorporated EU Green Deal facility approval timelines, EPA methane enforcement intensity, and MIIT dual carbon policy implementation pacing.
Several conditions sit outside the modeled scope, including speculative rare earth export restriction scenarios and breakthrough hydraulic actuator efficiency improvements. Forecasts reflect assumptions about regulatory enforcement continuity and supply chain disruption recovery trajectories. A small set of named triggers warrants ongoing watch: neodymium export licensing changes, REACH fluorinated gas phase-down acceleration, and Industry 4.0 architecture mandate expansion beyond automotive into chemical processing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Cable Granulator Market
Industrial Equipment
Asia Pacific Industrial Embedded Systems Market
Industrial Equipment
United States Ball Bearing Market
Industrial Equipment
Global Laboratory Vacuum Pumps Market
Industrial Equipment
CNC Tool Storage System Market
Industrial Equipment
Middle-East Fans and Blowers Market
Industrial Equipment
Asia-Pacific Electro Hydraulic Servo Valve Market
Industrial Equipment
North America Industrial Embedded Systems Market
Industrial Equipment
Laser Plastic Welding Market
Industrial Equipment
Fiber Laser Market
Industrial Equipment
Europe Ceramic Roller Bearings Market
Industrial Equipment
Ultrasonic Cleaning Equipment Market
Industrial Equipment
Microbubble Cleaning Device Market
Industrial Equipment
Photography Panoramic Tripod Heads Market
Industrial Equipment
Global Ultrasonic Cleaning Market
Industrial Equipment
Global Servo Presses Market