
 Dust Collector Systems Market | 2026-2036
Dust Collector Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Dust Collector Systems Market Analytics
The capital-intensity gap between turnkey system integrators and component suppliers is collapsing as end-users demand single-source accountability for compliance outcomes. Donaldson Company leverages its vertically integrated filter media production to capture aftermarket replacement cycles. Schenck Process GmbH anchors its position through proprietary pneumatic conveying integration that bundles dust collection with material handling. Nederman Holding AB competes via modular extraction arms and centralized vacuum architectures tailored to automotive welding lines.
Dust collector systems are engineered air-pollution-control devices that separate particulate matter from industrial gas streams using mechanical, electrostatic, or wet-scrubbing separation principles, with filtration efficiencies ranging from 99% for standard baghouses to 99.97% for HEPA-integrated configurations. Their primary purpose is to protect worker health, maintain process equipment integrity, and ensure regulatory compliance across heavy manufacturing environments. Baghouse technology dominates installed base value due to its tolerance for high temperatures and abrasive dust loads in cement and metallurgical operations. Wet scrubber applications are expanding fastest in pharmaceutical and food processing sectors where explosive dust hazards and hygienic surface requirements coexist. Electrostatic precipitator technology occupies a mature margin pool in coal-fired power and bulk minerals processing where extremely large gas volumes justify capital-intensive installations.
EPA enforcement of National Ambient Air Quality Standards and OSHA's substance-specific exposure limits are reshaping procurement specifications toward continuous emissions monitoring integration. China's MEE and provincial environmental protection bureaus are accelerating retrofits through differentiated discharge permits that penalize PM2.5 exceedances with production curtailments. Stakeholders must monitor how regulatory convergence on ultrafine particulate thresholds redirects R&D investment from conventional fabric filtration toward hybrid electrostatic-fiber composite architectures.
Market Dynamics
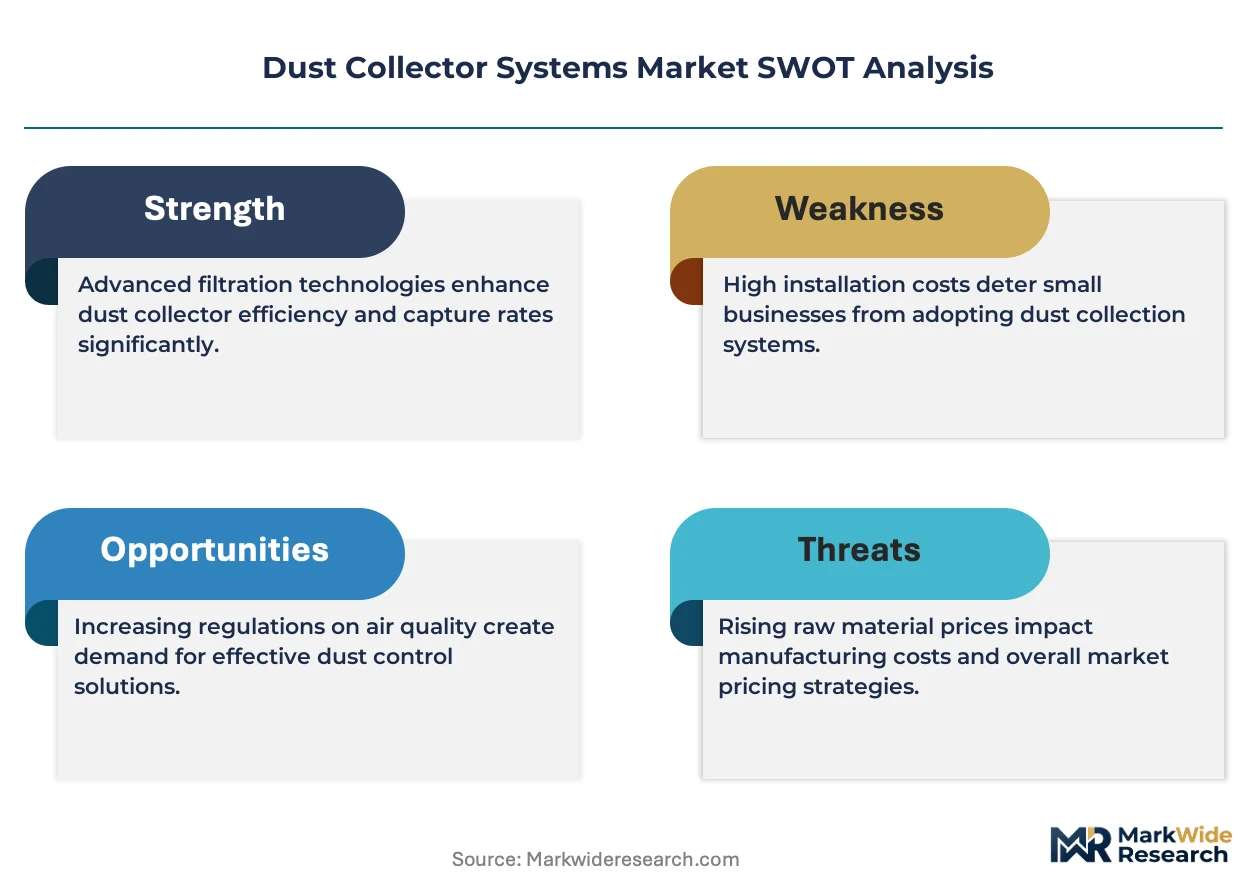
OSHA's substance-specific exposure limits for respirable crystalline silica and beryllium are forcing heavy manufacturing facilities into accelerated retrofit cycles, collapsing the traditional replacement timeline for legacy baghouse installations.
Growth Catalysts
- Silica Compliance Mandates:OSHA's updated permissible exposure limits for crystalline silica compel cement and steel plants to deploy high-efficiency baghouse systems with continuous emissions monitoring integration.
- Provincial PM2.5 Standards:China's environmental protection bureaus in industrial corridor cities enforce discharge thresholds stricter than national baselines, accelerating system upgrades across metallurgical operations.
- Wet Scrubber Technology:Pharmaceutical and food processing sectors adopt wet scrubber configurations to manage explosive dust hazards while maintaining hygienic surface requirements.
Market Restraints
- Specialized Filter Media Costs:High-temperature resistant fabric and HEPA-grade membrane materials face supply concentration among captive producers, inflating replacement cycle expenditures.
- Electrostatic Precipitator Lock-in:Coal-fired power and bulk minerals operations remain tethered to existing ESP installations due to gas volume scale requirements that baghouses cannot economically replicate.
- REACH Chemical Compliance:European filter media manufacturers absorb elevated certification costs for chemical substance registration, compressing margin pools on aftermarket component sales.
Strategic Opportunities
- Hybrid Electrostatic-Fiber Architectures:Convergence of electrostatic charging with nanofiber surface filtration enables sub-micron capture efficiency without the pressure-drop penalties of conventional HEPA configurations.
- Automotive Welding Automation:Centralized vacuum architectures with modular extraction arms penetrate electric vehicle battery pack assembly lines where fume generation intensifies with laser welding adoption.
- India's PLI Manufacturing Push:Production-linked incentive schemes for specialty steel and cement capacity create installed base expansion for dry filtration systems in Gujarat and Odisha industrial clusters.
Industry Challenges
- Pneumatic Conveying Integration Complexity:End-users demand single-source accountability for dust collection bundled with material handling, forcing component suppliers to acquire system integration capabilities or exit turnkey procurement channels.
- Continuous Emissions Monitoring Certification:EPA enforcement of National Ambient Air Quality Standards requires facility operators to validate real-time particulate measurement accuracy, extending commissioning timelines and technical qualification burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dust Collector Systems Market |
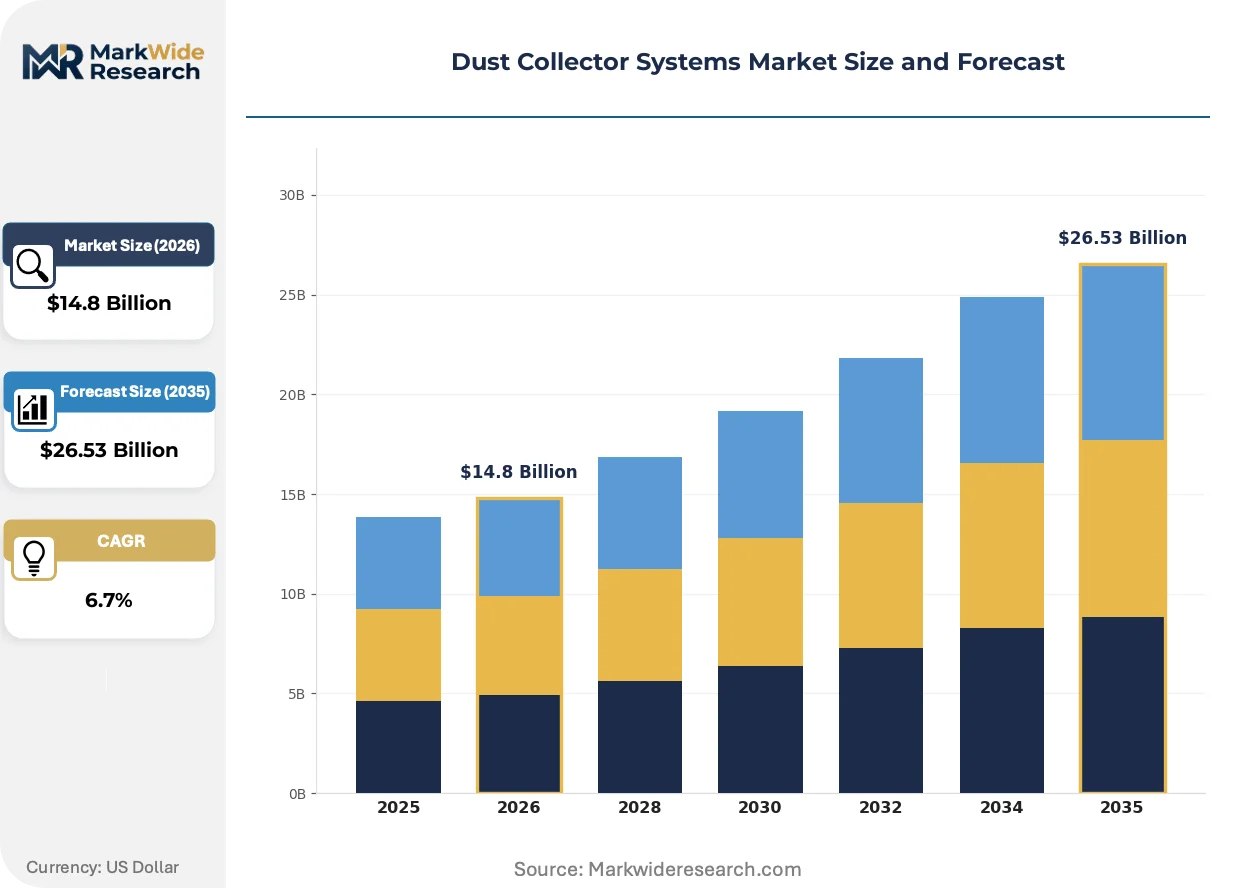
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baghouse, Cartridge, Cyclone, Wet Scrubber Application: Industrial Manufacturing, Mining, Pharmaceutical, Food Processing End User: Automotive, Aerospace, Construction, Electronics Technology: Electrostatic Precipitator, Vacuum, High-Efficiency Particulate Air (HEPA), Others |
| Companies Covered | Parker Hannifin Corporation, Schenck Process GmbH, Donaldson Company, Inc., SPX Flow, Inc., Munters Group AB, Nederman Holding AB, FLSmidth & Co. A/S, Sly Incorporated, Camfil AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dust Collector Systems Market Evolving Landscape
Filtration media engineering and regulatory telemetry integration are compressing the performance gap between standard baghouse configurations and capital-intensive electrostatic precipitator installations.
Nanofiber surface-loading technology is supplanting depth-loading fabric media in high-humidity applications. Food processing and pharmaceutical facilities adopt these composite filters to prevent moisture-induced blinding. The shift enables shorter filter replacement cycles without sacrificing capture efficiency, compressing aftermarket revenue timing for traditional media suppliers.
REACH authorization requirements for per- and polyfluoroalkyl substances are accelerating fluoropolymer membrane substitution in European filter manufacturing. Industrial laundries face restricted discharge of PTFE-laden wash water from filter cleaning operations. German and French system integrators respond by specifying PTFE-free membrane alternatives for food-contact applications.
Service contract unbundling disrupts the traditional bundled aftermarket model. Cement and steel operators separate filter replacement from system maintenance, awarding media supply to specialized distributors while retaining mechanical service in-house. This bifurcation concentrates procurement leverage among large-volume filter consumers in China's Shandong and Hebei provinces.
Dust Collector Systems Market Segmentation
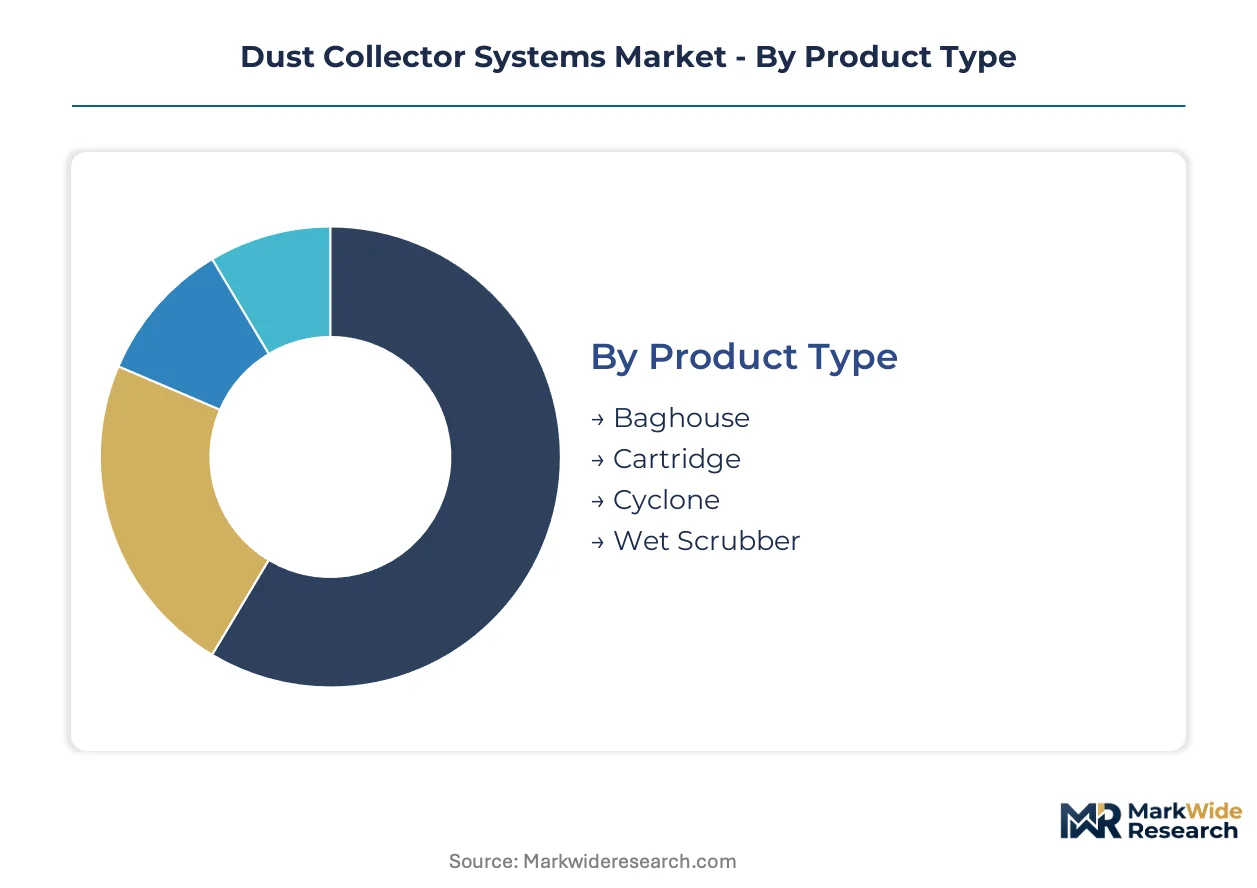
Segmentation in dust collector systems reveals how procurement specifications diverge between heavy industrial retrofit cycles and precision manufacturing greenfield installations. Understanding these divides exposes where component suppliers can capture aftermarket value versus where turnkey integrators dominate.
Product Type:
Margin pools concentrate in filter media replacement cycles and high-temperature fabric specifications rather than initial equipment sales.
- Baghouse:Fabric filtration systems using woven or felt media with pulse-jet or reverse-air cleaning mechanisms tolerate abrasive dust loads up to 500°F. Cement kilns in China's Shandong province and steel electric arc furnaces in Gujarat deploy these for silica and heavy-metal capture under tightening MEE discharge permits.
- Wet Scrubber:Liquid-based particulate separation using venturi or packed-bed configurations neutralizes explosive dust hazards. Pharmaceutical tablet coating lines and spray-drying operations in FDA-regulated facilities specify these for simultaneous particulate and volatile organic compound control.
- Cartridge:Pleated media elements deliver higher filtration area per unit volume than bag configurations. Metal fabrication shops with space constraints favor cartridge retrofits.
- Cyclone:Centrifugal separation removes coarse particulate as pre-filtration stage. Mining crushing circuits deploy cyclones upstream of fabric collectors to extend primary filter life.
Baghouse holds installed capacity. Wet Scrubber is rotating up the share rankings.
Application:
Application-driven procurement splits between facilities facing OSHA substance-specific mandates and those managing hygienic surface requirements.
- Industrial Manufacturing:Welding fume extraction and metal grinding operations generate respirable particulate demanding source-capture architectures. Automotive stamping plants in Michigan and battery assembly lines in Nevada specify centralized vacuum systems with continuous emissions monitoring integration.
- Pharmaceutical:OSD (oral solid dosage) manufacturing and API synthesis require containment systems meeting FDA cGMP standards for cross-contamination prevention. Potent compound handling suites specify HEPA-integrated isolators with single-pass airflow design.
- Mining:Crushing, conveying, and material handling operations produce coarse and fine respirable dust. Copper concentrators in Chile and iron ore operations in Western Australia deploy dry collection for tailings management.
- Food Processing:Grain milling, sugar refining, and spice handling generate combustible dust hazards. NFPA 654 compliance drives explosion venting and suppression integration.
Industrial Manufacturing commands current procurement volume. Pharmaceutical is climbing the fastest.
End User:
End-user concentration patterns follow capital expenditure cycles in durable goods manufacturing and infrastructure deployment.
- Construction:Cement production and ready-mix operations face crystalline silica exposure limits driving baghouse upgrades. Mexico's Cemex and India's UltraTech retrofit aging pulse-jet installations with membrane filter technology.
- Automotive:EV battery pack laser welding generates metal oxide fumes requiring high-volume extraction. Gigafactory-scale facilities in Texas and Berlin specify modular extraction arms with automated positioning.
- Aerospace:Composite machining and coating operations demand controlled environments for carbon fiber and solvent particulate. Boeing and Airbus supplier networks enforce AS9100 quality system integration.
- Electronics:Semiconductor wafer fabrication and PCB assembly require ultra-low particulate environments. Cleanroom-compatible vacuum systems with ISO 14644-1 compliance specify sub-micron capture efficiency.
Construction dominates legacy installed base. Automotive is expanding most quickly.
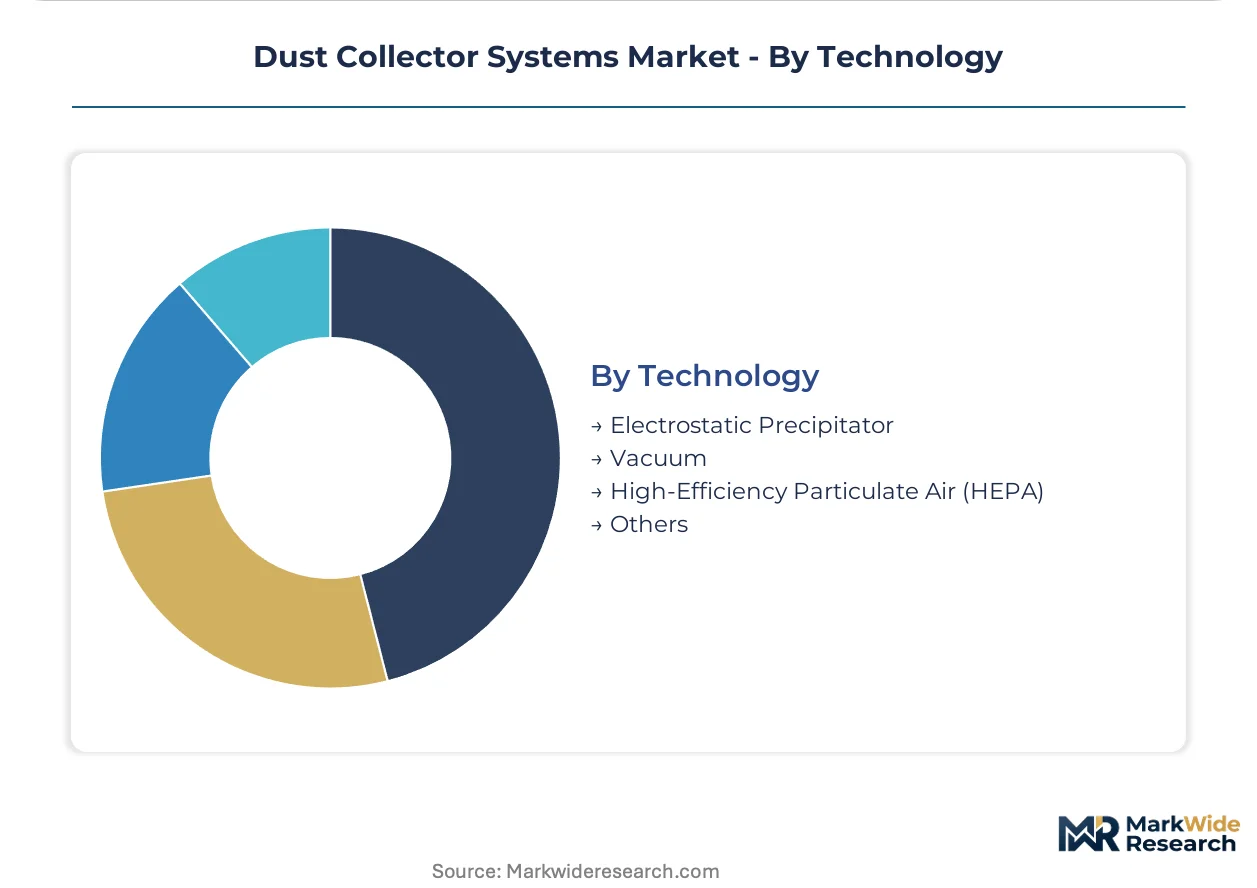
Technology:
Technology selection hinges on gas volume scale, particulate size distribution, and tolerance for pressure drop across the filtration train.
- Electrostatic Precipitator:Ionization-based particulate charging and collection handles gas volumes exceeding one million cubic feet per minute. Coal-fired power plants in Poland and bulk cement preheater towers retain ESP architectures despite fabric filtration efficiency advantages.
- High-Efficiency Particulate Air (HEPA):99.97% capture at 0.3 micron for critical containment applications. Biosafety laboratories and aseptic pharmaceutical filling lines specify HEPA as terminal filtration.
- Vacuum:Negative pressure source-capture systems with articulated extraction arms. Shipyard welding and maintenance operations deploy portable vacuum units for confined space compliance.
- Others:Emerging hybrid architectures combining electrostatic charging with nanofiber surface loading. R&D investment targets sub-micron efficiency without HEPA pressure-drop penalties.
Electrostatic Precipitator retains large-scale installed base. HEPA is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China's industrial corridor cities exhibit the lowest price elasticity as provincial environmental bureaus enforce discharge standards stricter than national baselines. Conversely, operators in India's emerging manufacturing clusters remain highly sensitive to capital expenditure thresholds despite tightening compliance mandates.
United States
Cement and steel facilities face accelerated retrofit cycles as OSHA's updated permissible exposure limits for crystalline silica and beryllium take effect. EPA enforcement of National Ambient Air Quality Standards compels continuous emissions monitoring integration across heavy manufacturing. Michigan automotive stamping plants and Nevada battery assembly lines specify centralized vacuum systems with real-time particulate validation.
Germany
REACH authorization requirements for per- and polyfluoroalkyl substances accelerate fluoropolymer membrane substitution in filter manufacturing. German system integrators specify PTFE-free membrane alternatives for food-contact applications as industrial laundries face restricted discharge of PTFE-laden wash water. The Ruhr industrial region and Bavarian manufacturing corridors drive demand for hybrid electrostatic-fiber composite architectures.
China
Provincial environmental protection bureaus in Shandong and Hebei provinces enforce PM2.5 discharge thresholds that exceed national baselines, collapsing traditional replacement timelines for legacy baghouse installations. The Ministry of Ecology and Environment accelerates retrofits through differentiated discharge permits that penalize exceedances with production curtailments. Metallurgical operations in the Yangtze River Delta and cement kilns in Shandong deploy high-efficiency fabric filtration with continuous monitoring integration.
India
Production-linked incentive schemes for specialty steel and cement capacity create installed base expansion for dry filtration systems. The Central Electricity Authority and state pollution control boards tighten particulate discharge norms for thermal power and clinker production. Gujarat and Odisha industrial clusters witness concentrated procurement as UltraTech and other cement operators retrofit aging pulse-jet installations with membrane filter technology.
Poland
Coal-fired power plants retain electrostatic precipitator architectures despite fabric filtration efficiency advantages, constrained by gas volume scale requirements. EU Green Deal alignment pressures and Industrial Emissions Directive compliance drive selective upgrades to hybrid configurations. The Upper Silesian industrial basin and Łódź manufacturing region concentrate demand for large-scale particulate control retrofits.
Dust Collector Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the capital-intensity gap between turnkey system integrators and component suppliers collapsing as end-users demand single-source accountability. The market structure bifurcates between vertically integrated filter media producers and pneumatic conveying specialists that bundle dust collection with material handling. Three archetypes dominate: captive media manufacturers, conveying-integrated system houses, and modular extraction specialists. Competitive moves center on backward integration into filter media production and acquisition of system integration capabilities to defend turnkey procurement channel access.
Within the integrated leader tier, Donaldson Company, Inc. and Schenck Process GmbH occupy positions that exemplify divergent strategic anchors. Donaldson represents the captive media production archetype, leveraging in-house filter manufacturing to capture aftermarket replacement cycles. Schenck Process anchors the conveying-integrated model, bundling dust collection with proprietary pneumatic material handling systems. Nederman Holding AB sits within the modular extraction specialist tier, serving automotive welding lines through centralized vacuum architectures. Component suppliers lacking integration capabilities face narrowing procurement access as facility operators consolidate vendor accountability.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Schenck Process GmbH |
| Donaldson Company, Inc. |
| SPX Flow, Inc. |
| Munters Group AB |
| Nederman Holding AB |
| FLSmidth & Co. A/S |
| Sly Incorporated |
| Camfil AB |
| Others |
Value Network & Pricing Analysis
Capacity utilization at high-temperature fabric mills in Germany and the United States shapes both supply concentration and aftermarket price floors for replacement filter media. OEMs with captive membrane production capture margin pools that independent distributors cannot match, while buyers in China's Shandong province face inelastic demand curves under provincial PM2.5 enforcement.
Pricing Analysis
Aftermarket filter replacement contracts drive lifetime value, with three-tier pricing structure across premium, standard, and economy levels differentiating HEPA-integrated configurations from standard baghouse media. Price differentiation rests on certification grade (OSHA silica compliance tier) and volume scale, with cost compression in standard fabric intensifying as Chinese membrane producers expand capacity. Cement operators in Hebei province exhibit lowest price sensitivity due to production curtailment penalties, while Indian PLI-scheme entrants remain highly sensitive to capital expenditure thresholds.
Supply Chain Analysis
China and Germany anchor high-temperature fabric manufacturing, with the United States retaining specialized HEPA membrane production. Supply chains draw from PTFE resin, fiberglass yarn, and nanofiber substrate inputs, with REACH authorization requirements for per- and polyfluoroalkyl substances creating regulatory restriction exposure for European laundries handling filter cleaning discharge. Distribution runs through system integrators bundling dust collection with pneumatic conveying, compressing component supplier access to turnkey procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dust collector systems represent an early-cycle expansion story as OSHA silica mandates and China's provincial PM2.5 standards force retrofit waves across heavy manufacturing, collapsing traditional replacement timelines and accelerating installed base turnover.
For Market Incumbents: Secure backward integration into nanofiber membrane production to defend aftermarket revenue pools against Chinese membrane entrants. Acquire pneumatic conveying capabilities to maintain turnkey channel access as end-users consolidate vendor accountability, and invest in continuous emissions monitoring certification to extend commissioning service contracts.
For New Entrants and Emerging Players: Anchor in India's Gujarat and Odisha industrial clusters where PLI-scheme cement and steel capacity creates greenfield demand for dry filtration systems. Target pharmaceutical wet scrubber applications in FDA-regulated facilities where explosive dust hazards and hygienic requirements coexist, and pursue white-label membrane supply agreements with European system integrators seeking PTFE-free alternatives.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated filter media producers with captive aftermarket replacement cycles. Long-term viability favors archetypes combining in-house membrane manufacturing with system integration capabilities, with inflection signals appearing in hybrid electrostatic-fiber architecture adoption rates and service contract unbundling patterns among Chinese cement operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Media | Captive membrane production locks in aftermarket replacement cycles against Chinese entrants. |
| Hybrid Architecture R&D Investment | Electrostatic-fiber composites target sub-micron efficiency without HEPA pressure-drop penalties. |
| Pneumatic Conveying Acquisition | System integration capabilities defend turnkey procurement channel access. |
| Continuous Monitoring Certification | EPA NAAQS enforcement extends commissioning timelines and technical service contracts. |
| PTFE-Free Membrane Development | REACH authorization requirements accelerate fluoropolymer substitution in European food-contact applications. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads; and secondary validation through EPA enforcement records, OSHA silica compliance filings, MEE discharge permit databases, and customs trade data. Bottom-up triangulation against top-down market sizing anchored volume and value estimates across the projection horizon.
Across the analysis window, forecasts modeled product type, application, end-user industry, and technology architecture dimensions. CAGRs derived from regression analysis of installed base turnover rates and replacement cycle compression under regulatory mandates, with inputs including provincial PM2.5 enforcement intensity and PLI-scheme capacity commissioning schedules.
Material uncertainties — regulatory threshold revisions, membrane supply disruptions, or hybrid technology adoption inflections — sit outside the modeled envelope. Forecasts reflect assumptions about enforcement continuity and technology substitution elasticities. Recalibration cycles align with material shifts in OSHA substance-specific rulemaking and MEE discharge permit differentiation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Dynamic Scales Market
Industrial Equipment
Magnetizing Equipment Market
Industrial Equipment
Photography Panoramic Tripod Heads Market
Industrial Equipment
Industrial Linear Accelerator Market
Industrial Equipment
Seal Inspection Equipment Market
Industrial Equipment
Machine Mounts Market
Industrial Equipment
Diaphragm Coupling Market
Industrial Equipment
Industrial Monitor Market
Industrial Equipment
Digital Tachometer Market
Industrial Equipment
Industrial Polishing Machine Market
Industrial Equipment
Anti-Vibration Mounts Market
Industrial Equipment
Global Laser Material Market
Industrial Equipment
Cleanroom Equipment Market
Industrial Equipment
Robotic Ultrasonic NDT Cells for Weld and Pressure Vessel Inspection Market
Industrial Equipment
Middle East and Africa Industrial Centrifuge Market
Industrial Equipment
Fusion Splicer Market