
 Special Function Data Convertors Market | 2026-2036
Special Function Data Convertors Market Size, Share, and Industry Trends Forecast 2026-2036
Special Function Data Convertors Market Analysis
The gap between precision-grade and standard-function data converters is repositioning procurement strategies across the semiconductor value chain. Texas Instruments leverages its broad analog portfolio to sustain dominance in high-resolution industrial applications. Analog Devices anchors its position through proprietary sigma-delta architectures that command premium positioning in medical and aerospace segments.
Special function data convertors are mixed-signal integrated circuits that translate electrical signals between analog and digital domains, typically achieving resolutions from 8-bit to 24-bit with sampling rates spanning kilohertz to gigahertz ranges; these devices serve as critical interfaces in sensor networks, control systems, and communication infrastructure where signal fidelity determines system performance. Analog to Digital converters capture the largest revenue pool in industrial automation and telecommunications infrastructure, while voltage level converters are gaining share fastest as automotive 48V mild-hybrid architectures proliferate and create demand for robust level-shifting solutions. Integrated circuit technology dominates unit economics through CMOS scaling, though hybrid technology commands superior margins in radiation-hardened and extreme-temperature deployments.
The FDA enforces electromagnetic compatibility standards for medical devices incorporating data acquisition subsystems, directly shaping converter noise and isolation specifications. REACH and RoHS frameworks in Europe restrict hazardous substances in semiconductor packaging materials, altering substrate and plating choices for converters sold into automotive and consumer end-use segments. Stakeholders must monitor how emerging functional safety standards for autonomous systems redefine accuracy and fault-tolerance requirements across converter product lines.
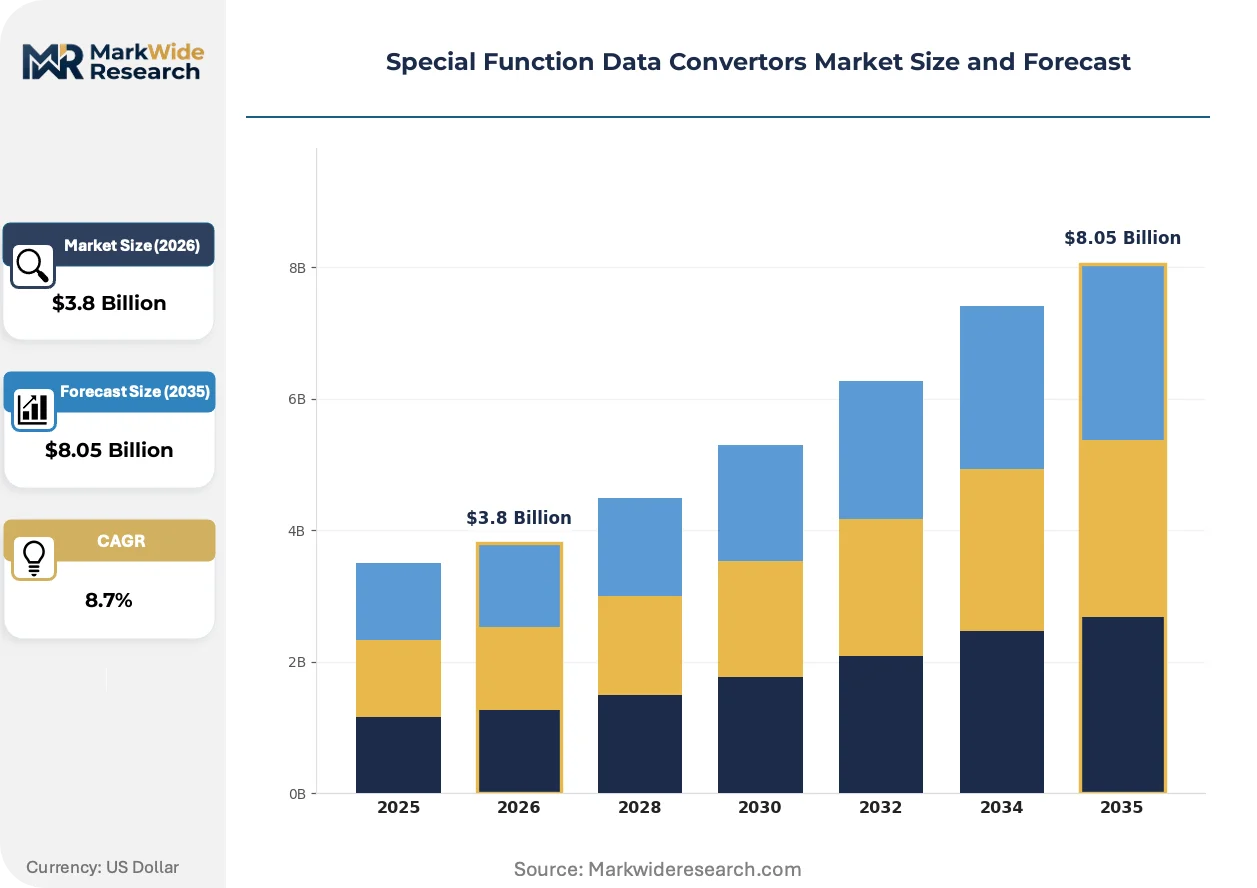
Market Dynamics
Precision requirements in portable medical diagnostics and automotive 48V architectures are compressing converter design cycles while fragmenting supplier qualification pathways across multiple regulatory jurisdictions.
Growth Catalysts
- Medical device portability:Portable diagnostic equipment manufacturers in Germany and the United States are expanding procurement of precision analog-to-digital converters to enable point-of-care testing workflows.
- REACH and RoHS compliance:European hazardous substance restrictions are accelerating substrate material transitions in semiconductor packaging, creating replacement demand for certified converter components.
- Automotive 48V electrification:Mild-hybrid powertrain architectures across Bavaria and Baden-Württemberg manufacturing clusters are driving voltage level converter volumes for robust level-shifting in battery management systems.
Market Restraints
- Raw material concentration:Specialized semiconductor substrates and high-purity plating materials face supply concentration from East Asian refining operations, exposing converter manufacturers to input cost volatility.
- Electromagnetic compatibility certification:FDA guidance tightening for medical electronics signal integrity components extends product qualification timelines and raises non-recurring engineering costs for new converter designs.
- Silicon carbide displacement:Wide-bandgap power electronics in next-generation automotive inverters threaten traditional voltage converter architectures in high-temperature powertrain applications.
Strategic Opportunities
- Functional safety standards:Emerging autonomous system mandates for accuracy and fault-tolerance are opening premium converter tiers in aerospace and automotive sensor fusion applications.
- Industrial automation clusters:Factory control system upgrades in German industrial corridors present concentrated demand for precision data acquisition interfaces.
- Radiation-hardened deployments:Hybrid converter technology for extreme-temperature and space environments commands superior margins through limited qualified supplier bases.
Industry Challenges
- Mixed-signal design expertise:Shortage of analog-digital interface specialists capable of optimizing sigma-delta architectures for medical and aerospace noise specifications constrains product development velocity.
- Legacy system integration:Industrial automation retrofit projects require backward-compatible voltage level translation, complicating firmware and hardware co-design for converter suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Special Function Data Convertors Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog to Digital, Digital to Analog, Voltage Level Converter, Frequency Converter End User: Consumer Electronics, Automotive, Industrial Automation, Telecommunications Technology: Integrated Circuit, Discrete Component, Hybrid Technology, Software-Based Application: Signal Processing, Data Acquisition, Robotics, Medical Devices |
| Companies Covered | Texas Instruments, Analog Devices, Infineon Technologies, STMicroelectronics, Microchip Technology, Skyworks Solutions, NXP Semiconductors, Renesas Electronics Corporation, Maxim Integrated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Special Function Data Convertors Market Emerging Trajectories
Sigma-delta modulation architectures are compressing precision converter development timelines while regulatory electromagnetic compatibility mandates reshape component qualification pathways across medical and automotive supply chains.
Sigma-delta analog-to-digital converters with noise-shaping quantization are overtaking successive-approximation architectures in medical imaging and industrial sensor networks. OEMs in diagnostic equipment and factory automation are adopting 24-bit resolution variants at accelerated procurement cycles. This architectural shift is overtaking traditional pipeline converter market positions in precision instrumentation segments.
The FDA's updated electromagnetic compatibility guidance for medical electronics is tightening signal integrity certification requirements for data acquisition subsystems. Converter manufacturers must now demonstrate enhanced isolation and noise specifications before device integration approval. Medical device OEMs in the United States are responding by consolidating supplier qualification to pre-certified analog component vendors.
Certification-driven supplier consolidation is compressing converter procurement cycles among tier-one automotive and medical device manufacturers. Long-tail distributor networks are losing share to authorized direct channels with documented traceability and regulatory documentation packages. German automotive OEMs and Bavarian industrial automation clusters exhibit the most pronounced channel consolidation behavior.
Special Function Data Convertors Market Segmentation
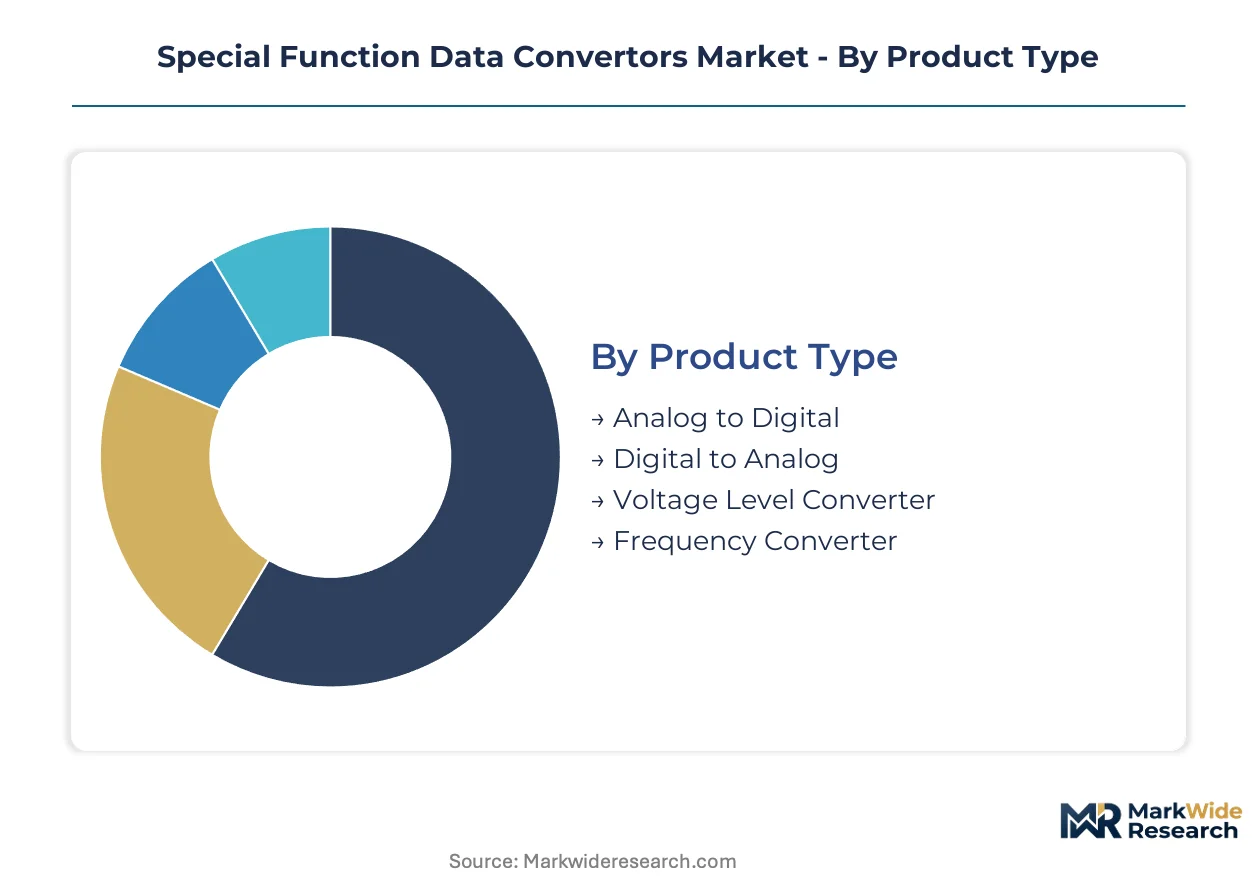
Converter procurement decisions in this market hinge on resolution requirements, environmental operating conditions, and regulatory certification tiers rather than unit cost alone. Buyers segment suppliers across precision grades that determine qualification pathways for medical and automotive end-uses.
Product Type:
Buyers prioritize resolution specifications and sampling bandwidth when selecting converter architectures for specific signal chain positions.
- Analog to Digital:These converters translate continuous voltage signals into discrete digital codes, achieving resolutions from 8-bit to 24-bit with sampling rates spanning kilohertz to gigahertz ranges. Demand concentrates in German industrial automation corridors and United States medical device manufacturing, where FDA electromagnetic compatibility guidance tightens noise and isolation specifications for diagnostic equipment signal acquisition subsystems.
- Voltage Level Converter:Bi-directional level-shifting circuits enable communication between devices operating at disparate supply voltages, critical for 48V mild-hybrid battery management systems. Bavarian and Baden-Württemberg automotive OEMs source these components in volume for electric powertrain architectures, with procurement accelerating as 48V electrification proliferates across European passenger vehicle platforms.
- Digital to Analog:Precision voltage or current output devices reconstruct analog waveforms from digital input streams for audio and control applications.
- Frequency Converter:Signal conditioning circuits translate between clock domains or modulate carrier frequencies for RF and timing subsystems.
Volume sits with Analog to Digital converters; growth tilts toward Voltage Level Converter solutions.
End User:
Application-specific certification requirements and operating environment tolerances determine supplier selection across vertical markets.
- Automotive:Functional safety mandates for autonomous sensor fusion and 48V powertrain electrification drive demand for fault-tolerant converter architectures with extended temperature ratings. German OEM procurement clusters in Bavaria and Baden-Württemberg specify automotive-grade voltage level converters for battery management and motor control interfaces.
- Medical Devices:Portable diagnostic equipment manufacturers require precision analog-to-digital converters with enhanced isolation specifications to satisfy FDA electromagnetic compatibility guidance for point-of-care testing workflows. United States device OEMs consolidate supplier qualification to pre-certified analog component vendors with documented traceability packages.
- Industrial Automation:Factory control system upgrades in German industrial corridors demand backward-compatible precision data acquisition interfaces with robust noise immunity.
- Telecommunications:Infrastructure equipment deploys high-speed converters for signal processing in baseband and RF front-end subsystems.
- Consumer Electronics:Cost-optimized converter integration serves audio, display, and sensor interface functions in mass-market devices.
Procurement volume clusters in Automotive; Medical Devices exhibit the steepest expansion trajectory as portable diagnostics proliferate.
Technology:
Manufacturing process selection trades off unit economics against environmental resilience and radiation tolerance requirements.
- Integrated Circuit:CMOS scaling dominates unit economics through high-volume wafer fabrication, enabling cost-optimized converter solutions for consumer and automotive mass markets. Process nodes below 40nm achieve competitive power efficiency for battery-operated portable medical diagnostics.
- Hybrid Technology:Multi-chip module constructions combining semiconductor die with passive components command superior margins in radiation-hardened and extreme-temperature deployments. Limited qualified supplier bases protect pricing power for aerospace and satellite applications.
- Discrete Component:Board-level converter implementations serve legacy system retrofits and specialized laboratory instrumentation requiring manual calibration.
- Software-Based:Digital signal processing algorithms emulate conversion functions in FPGA and software-defined radio platforms.
Integrated Circuit technology captures dominant unit volumes; Hybrid Technology delivers the highest margin expansion potential.
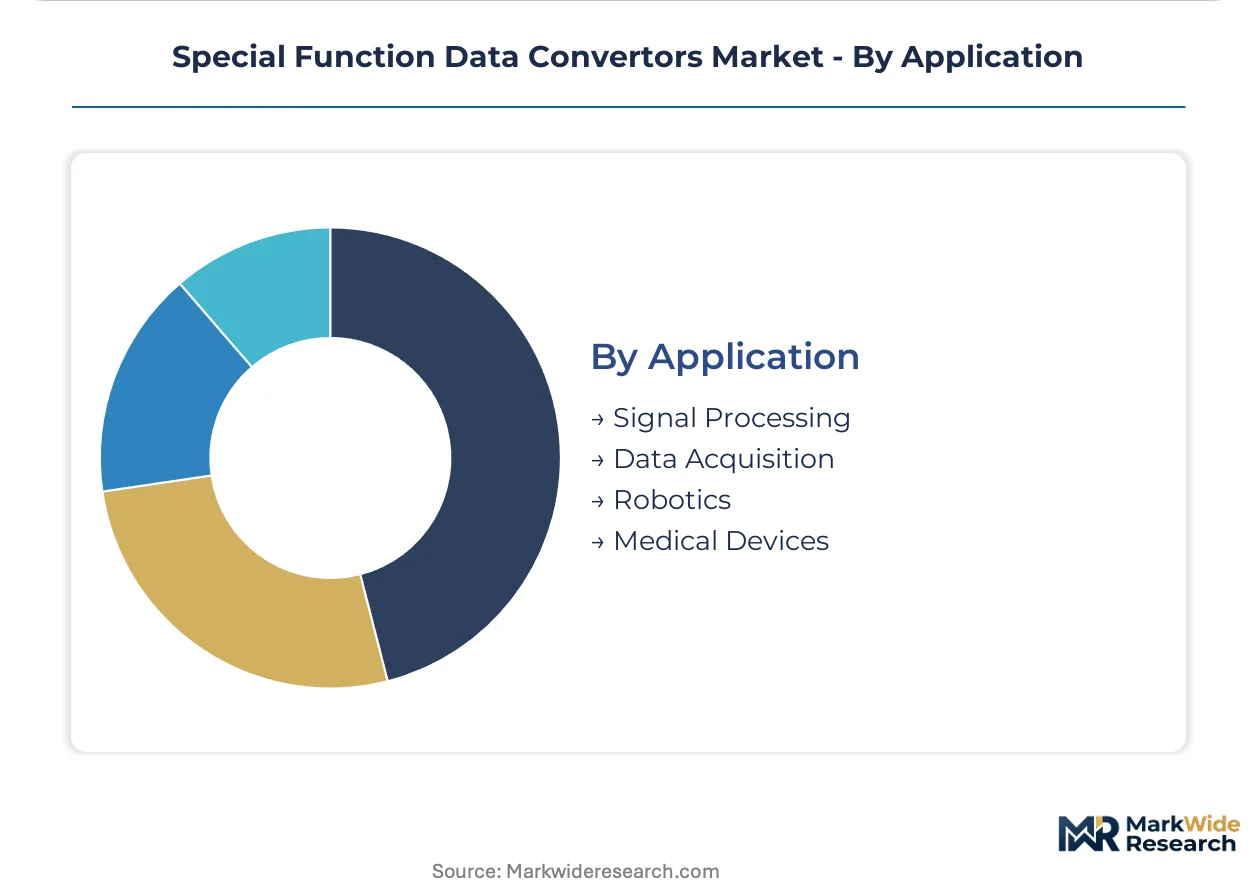
Application:
System-level performance requirements dictate converter precision grades and architectural selection across deployment contexts.
- Signal Processing:Real-time analog-to-digital and digital-to-analog conversion enables filtering, modulation, and waveform generation in communications and audio subsystems. Telecommunications infrastructure and industrial control networks deploy high-speed pipeline architectures for low-latency signal chains.
- Data Acquisition:Multi-channel precision measurement interfaces serve sensor networks and test instrumentation with synchronized sampling requirements. German factory automation clusters source 24-bit sigma-delta variants for vibration monitoring and process control applications.
- Medical Devices:Diagnostic imaging and patient monitoring equipment demands sigma-delta analog-to-digital converters with noise-shaping quantization for high-resolution physiological signal capture.
- Robotics:Motor drive and sensor fusion subsystems in autonomous systems require deterministic conversion latency for closed-loop control stability.
Data Acquisition commands the largest installed base; Medical Devices are gaining share fastest as point-of-care testing workflows expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavarian automotive clusters in Munich and Ingolstadt anchor converter procurement for 48V mild-hybrid powertrains, while FDA electromagnetic compatibility guidance tightens certification requirements for United States medical device manufacturers.
United States
Portable diagnostic equipment manufacturers in Massachusetts and California expand precision analog-to-digital converter procurement for point-of-care testing workflows. FDA electromagnetic compatibility guidance tightens signal integrity certification requirements for data acquisition subsystems. Boston-area medical device OEMs consolidate supplier qualification to pre-certified analog component vendors with documented traceability packages.
Germany
Automotive OEMs and industrial automation clusters in Bavaria and Baden-Württemberg source specialized voltage level converters for electric powertrain and factory control systems. REACH and RoHS frameworks restrict hazardous substances in semiconductor packaging materials, altering substrate choices for automotive-grade components. Stuttgart manufacturing corridors drive procurement acceleration as 48V electrification proliferates across European passenger vehicle platforms.
China
Telecommunications infrastructure deployment and industrial sensor network expansion drive demand for high-speed data converters in the Yangtze River Delta and Pearl River Delta. GB standards and MIIT regulations shape electromagnetic compatibility specifications for domestic equipment integration. Shenzhen and Shanghai electronics manufacturing clusters concentrate procurement of cost-optimized CMOS converter solutions for mass-market consumer and automotive applications.
Japan
Industrial automation retrofits and robotics sensor fusion applications in the Kanto and Kansai regions require precision data acquisition interfaces with deterministic conversion latency. METI industrial policy frameworks support domestic semiconductor supply chain resilience for critical mixed-signal components. Nagoya-area automotive suppliers integrate voltage level converters into battery management systems for hybrid electric vehicle platforms.
South Korea
Seoul Capital Area electronics manufacturers deploy high-resolution converters in display driver and mobile sensor interface applications. MFDS medical device regulations align with international electromagnetic compatibility standards for diagnostic equipment signal integrity. Busan-Ulsan industrial corridors source precision analog-to-digital converters for semiconductor test equipment and factory automation upgrades.
Special Function Data Convertors Market Vendor Landscape
Capital-heavy integrated device manufacturers compete with asset-light fabless designers across converter market tiers. The vendor base concentrates among diversified analog semiconductor portfolios and specialized mixed-signal specialists. Two strategic archetypes dominate: broad-line suppliers leveraging manufacturing scale and precision-architecture specialists commanding premium positioning. Competitive moves center on sigma-delta IP licensing partnerships and electromagnetic compatibility pre-certification investments.
Within the diversified analog tier, Texas Instruments and Analog Devices occupy anchor positions representing scale-driven and precision-architecture archetypes respectively. Infineon Technologies exemplifies European automotive-focused converter supply. These three companies sit within distinct competitive vectors: broad portfolio coverage, proprietary modulation architectures, and powertrain electrification specialization.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| Infineon Technologies |
| STMicroelectronics |
| Microchip Technology |
| Skyworks Solutions |
| NXP Semiconductors |
| Renesas Electronics Corporation |
| Maxim Integrated |
| Others |
Supply Flow & Price Mechanics
Resolution-grade bifurcation between precision 24-bit sigma-delta architectures and commodity 8-bit successive-approximation converters manifests in divergent pricing power and supply chain sourcing strategies across medical and industrial procurement channels.
Pricing Analysis
Value-based pricing anchors on functional safety certification tiers and electromagnetic compatibility pre-qualification status. Three-tier pricing structure across automotive-grade, medical-grade, and industrial-grade certification levels separates premium sigma-delta IP holders from standard-function competitors. Cost compression in industrial-grade CMOS converters is intensifying because foundry capacity allocation favors advanced automotive nodes. Medical device OEMs exhibit lowest price sensitivity given FDA qualification switching costs, while consumer electronics buyers drive aggressive unit-cost negotiations.
Supply Chain Analysis
Single-source vulnerability sits with East Asian high-purity silicon wafer and specialty plating material suppliers. Converter manufacturing draws from Taiwan, South Korea, and Japan for advanced CMOS foundry services, with Germany and the United States contributing precision analog process expertise. Raw material dependencies span high-resistivity silicon substrates, gold wire bonding, and ceramic packaging materials. Tariff exposure on semiconductor equipment imports threatens margin stability for European packaging operations. Distribution runs through authorized direct channels with documented traceability for automotive and medical tiers, while industrial and consumer segments retain fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified sigma-delta design capacity constraints prop pricing power for pre-certified vendors as medical and automotive OEMs consolidate supplier bases to reduce electromagnetic compatibility qualification risk.
For Market Incumbents: Extend electromagnetic compatibility pre-certification investments to capture FDA and automotive functional safety consolidation trends. Deepen backward integration into high-resistivity silicon substrate sourcing to offset East Asian refining concentration. Prioritize captive sigma-delta IP development to defend against fabless competitors licensing modular architectures.
For New Entrants and Emerging Players: Authorized distributors with established medical device traceability documentation represent the most viable channel entry point. Target industrial automation retrofit applications in German Bavarian corridors where backward-compatible voltage level translation requirements create specification gaps. Pursue radiation-hardened hybrid converter niches with limited qualified supplier bases and superior margin profiles.
For Investors and Strategic Acquirers: Re-rating potential sits with precision-architecture specialists given emerging autonomous system functional safety mandates. Long-term viability favors mixed-signal design houses with proprietary modulation IP and established medical-automotive certification portfolios. Watch sigma-delta architecture licensing deal velocity as inflection indicator for competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Electromagnetic Compatibility Pre-Certification Investment | Reduces FDA qualification timelines for medical device OEMs consolidating supplier bases. |
| Sigma-Delta IP Licensing Partnership | Accelerates time-to-market for fabless entrants targeting precision instrumentation segments. |
| Automotive Functional Safety Certification | Enables access to 48V mild-hybrid battery management procurement in German manufacturing clusters. |
| Backward Integration into Substrate Sourcing | Insulates margin stability from East Asian high-purity silicon refining concentration. |
| Radiation-Hardened Product Line Expansion | Captures premium pricing in aerospace and satellite applications with limited qualified competition. |
Methodological Framework
Independent corroboration across converter design engineers, medical device procurement managers, and automotive Tier 1 supplier quality directors underwrites the qualitative findings. Primary fieldwork engaged biomedical engineers at Massachusetts and California diagnostic equipment manufacturers, platform engineers at Bavarian automotive OEMs, and analog semiconductor product managers at integrated device manufacturers. Secondary validation drew from FDA electromagnetic compatibility guidance documents, SEC 10-K filings of listed analog semiconductor suppliers, and customs trade data for converter component imports. Bottom-up unit shipment estimates triangulated against top-down semiconductor industry revenue allocations.
Comparable-period anchoring to historical medical device and automotive electronics production cycles established baseline demand patterns across the modeling period. Segmentation dimensions modeled include converter architecture type, resolution grade, certification tier, end-use vertical, and regional manufacturing cluster. CAGRs derived from regression analysis of procurement volume trends against electrification and diagnostic equipment deployment indicators. Industry-specific inputs encompassed 48V mild-hybrid platform ramp schedules and portable diagnostic equipment FDA submission trajectories.
Caveats apply where raw material supply disruptions or accelerated silicon carbide power electronics adoption could materially shift the outlook. Forecasts assume stable electromagnetic compatibility regulatory frameworks and continued automotive electrification investment. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Printed Circuit Board Market
Electronic Components
High-Voltage Capacitor Market
Electronic Components
North America Miniature Ball Bearing Market
Electronic Components
Digital Isolator Market
Electronic Components
Single Layer Capacitors Market
Electronic Components
Efuse Market
Electronic Components
Audio CODEC Market
Electronic Components
China Data Converter Market
Electronic Components
Electronic Wipe Market
Electronic Components
USB Retimer Market
Electronic Components
Operational Amplifier Market
Electronic Components
Coaxial Attenuators Market
Electronic Components
Motherboard Market
Electronic Components
Aluminum Electrolytic Capacitor Market
Electronic Components
VPX SBC Market
Electronic Components
Circuit Protection Kits Market