
 Industrial Tags Market | 2026-2036
Industrial Tags Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Tags Market Foresight
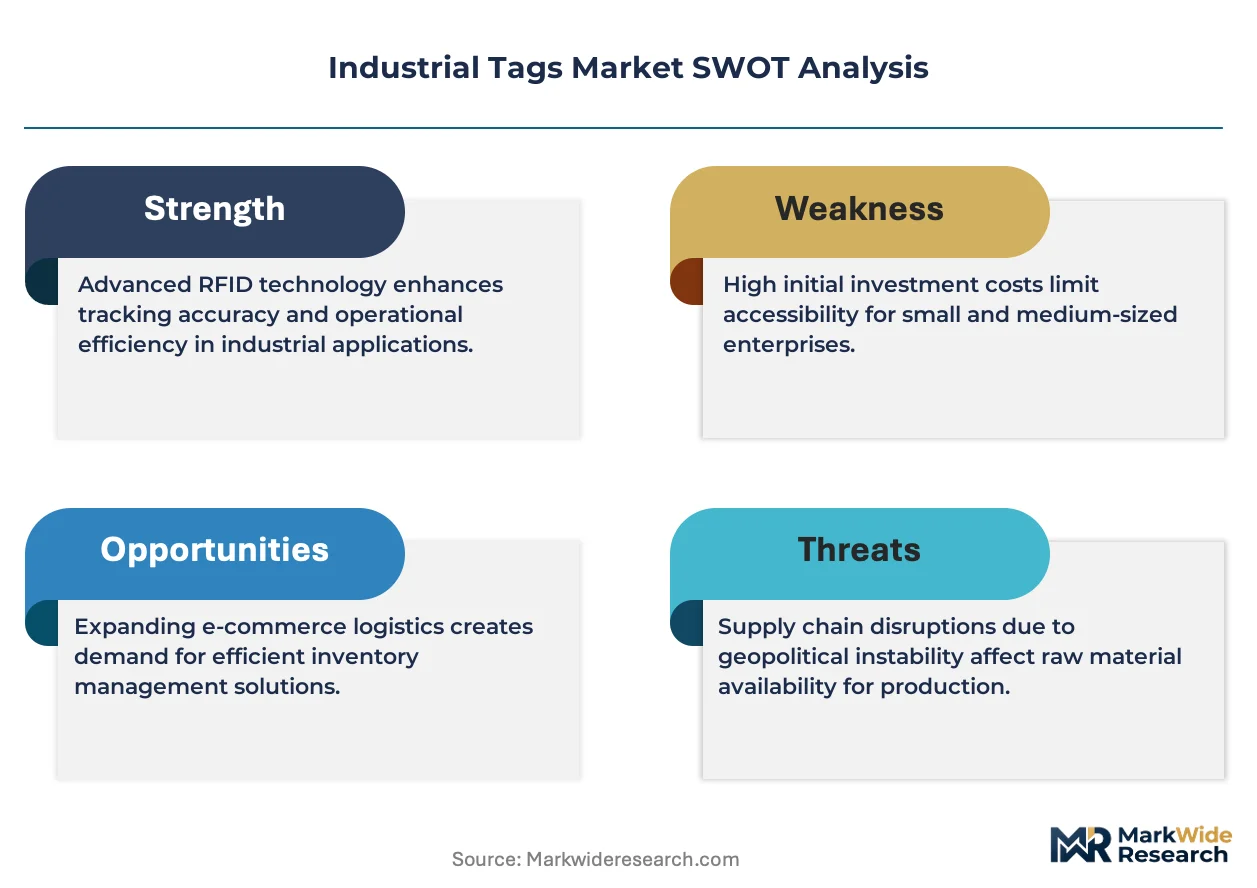
Cloud-based tag management software is decoupling hardware sales from recurring revenue streams across the industrial tags value chain. Zebra Technologies leverages its end-to-end visibility platform to sustain enterprise subscription attach rates. Avery Dennison Corporation anchors global manufacturing scale through its materials science and converting infrastructure. Brady Corporation specializes in harsh-environment identification products that command premium positioning in energy and aerospace verticals.
Industrial tags are encoded or printed identifiers affixed to assets, inventory, or equipment, typically manufactured through thermal transfer, digital printing, or inlay insertion processes with operating temperatures ranging from negative forty to three hundred degrees Celsius depending on substrate and adhesive specification. RFID Tags dominate high-value asset tracking applications where automated read ranges exceed ten meters without line-of-sight requirements. Barcode Labels occupy mature, cost-sensitive inventory lanes where laser or imager scanning suffices. Metal substrates command margin pools in oil and gas deployments where chemical resistance and mechanical durability are non-negotiable.
The Federal Communications Commission governs RFID spectrum allocation in the United States, while the European Chemicals Agency enforces REACH compliance on adhesive and substrate chemistries entering EU industrial supply chains. China's Ministry of Industry and Information Technology coordinates GB standards for automatic identification equipment interoperability. ISO 18000-6C and GS1 EPCglobal frameworks shape cross-border tag data architecture, creating compliance barriers for suppliers lacking certified encoding capabilities. Stakeholders must weigh hardware-versus-software revenue mix, regulatory certification timelines, and regional standard fragmentation when allocating capital across product development and geographic expansion.
Market Dynamics
EPC Gen 2 RFID mandates from major retailers are compressing compliance timelines upstream through industrial supply chains, forcing tag manufacturers to certify encoding capabilities against GS1 EPCglobal frameworks before contract eligibility.
Growth Catalysts
- Retailer Mandate Cascade:Big-box retailers in the United States now require pallet-level RFID tagging, pushing compliance requirements onto third-party logistics providers and contract manufacturers who must upgrade inlay insertion capacity.
- Real-Time Asset Visibility:Manufacturing end users deploy active RFID and sensor-integrated tags to track work-in-process inventory through production lines, reducing search time and line stoppages.
- REACH Compliance Infrastructure:The European Chemicals Agency's substance restrictions on adhesive chemistries have created certified supplier lists that favor incumbent converters with pre-validated substrate portfolios.
Market Restraints
- Silicon Inlay Supply Concentration:Semiconductor fabrication for RFID chips concentrates among a limited set of foundry operators in East Asia, exposing tag assemblers to allocation risk during capacity crunches.
- Substrate Cost Volatility:Petrochemical-derived films and adhesives fluctuate with crude oil indices, compressing gross margins for standard barcode label producers who lack pricing power with price-sensitive buyers.
- Metal Interference Limitations:Passive UHF RFID performance degrades on liquid-filled containers and metallic surfaces without specialized antenna design, restricting deployment in chemical and automotive parts tracking.
Strategic Opportunities
- Cold Chain Expansion:Temperature-logging RFID tags are penetrating pharmaceutical distribution networks in Germany where GDP compliance requires documented custody records across last-mile handoffs.
- GB Standards Alignment:China's Ministry of Industry and Information Technology is harmonizing automatic identification equipment certification, creating a unified addressable market for foreign tag suppliers with MIIT-approved encoding systems.
- Cloud-Platform Convergence:Tag management software integrating with enterprise ERP systems is expanding into subscription revenue models that decouple hardware margins from recurring service income.
Industry Challenges
- Certification Timeline Compression:ISO 18000-6C and regional spectrum compliance testing requires 4-6 month validation cycles that delay product launches and tie up engineering resources.
- Legacy System Integration Friction:Industrial facilities with decades-old WMS infrastructure face middleware complexity when bridging RFID data streams to existing inventory databases without wholesale replacement.
- RF Engineering Talent Scarcity:Antenna design and RF simulation expertise concentrates among a narrow specialist pool, inflating compensation costs for tag developers pursuing custom form factors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Tags Market |
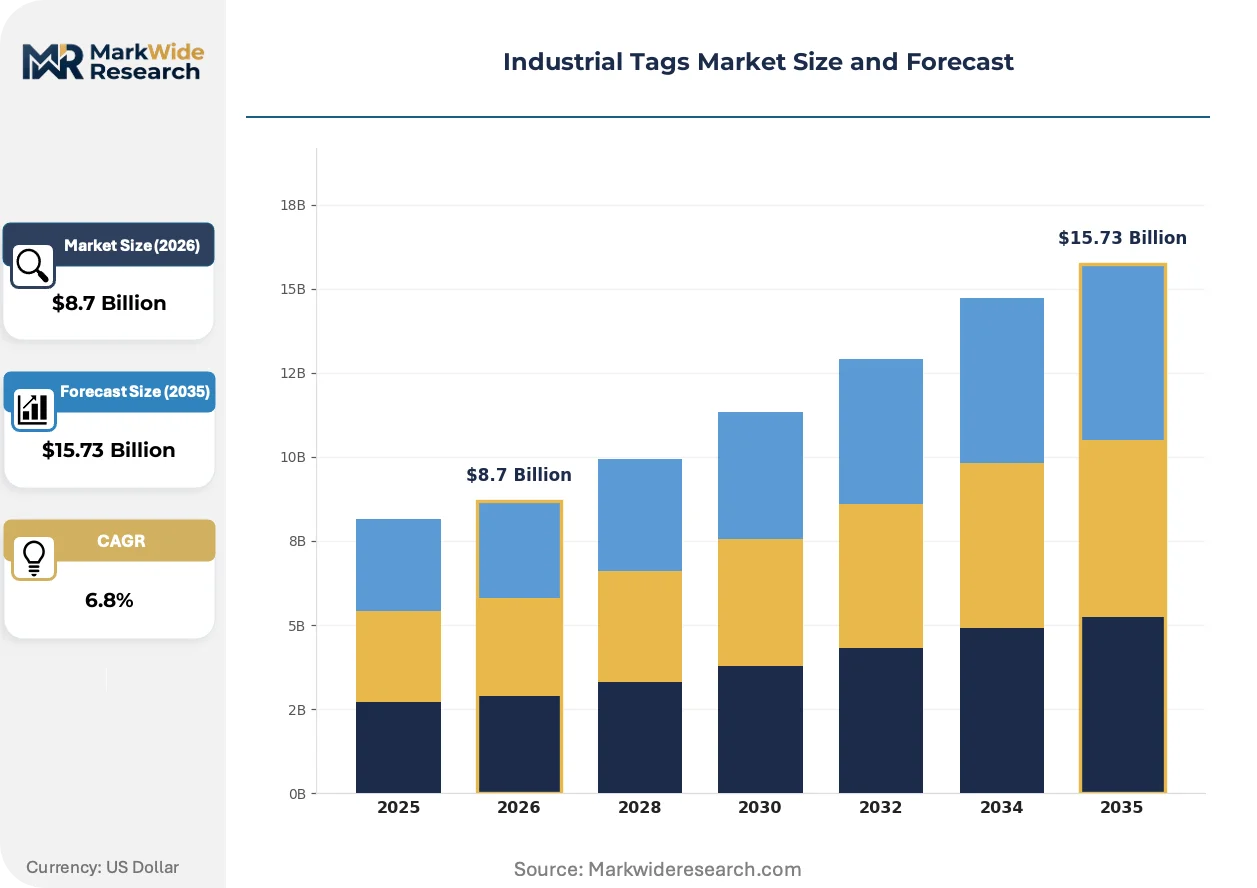
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RFID Tags, Barcode Labels, QR Code Tags, Magnetic Tags Material: Plastic, Paper, Metal, Laminate Application: Inventory Management, Asset Tracking, Product Labeling, Supply Chain End User: Manufacturing, Logistics, Retail, Healthcare |
| Companies Covered | Avery Dennison Corporation, Zebra Technologies, Brady Corporation, 3M Company, CCL Industries, HID Global, Honeywell International Inc., UPM Raflatac, SATO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Tags Market Shifts & Advancements
Sensor-integrated passive tags are collapsing the boundary between identification and environmental monitoring, enabling condition-aware supply chains without battery maintenance overhead.
Printed electronics using conductive inks are expanding into flexible antenna substrates that conform to curved pharmaceutical vials and irregular automotive components. Medical device manufacturers in Switzerland adopt these form factors for unit-level serialization under EU MDR traceability requirements. The technology is expanding into applications where mechanical durability and chemical resistance previously demanded etched metal or rigid PCB constructions.
The FCC's recent spectrum reallocations for unlicensed RFID operation in the 915 MHz band are tightening coexistence requirements with industrial IoT deployments. Equipment vendors must now certify against updated Part 15 rules that limit spurious emissions in dense reader environments. Warehouse operators in the United States are responding by upgrading to Gen 2 V2 protocol readers with improved interference rejection.
Buyer consolidation among third-party logistics providers is compressing vendor qualification cycles and demanding outcome-based tag performance guarantees rather than unit pricing. Large 3PLs in the Netherlands now specify read-rate thresholds and failure replacement terms in master service agreements. This restructuring is most visible in European pharmaceutical distribution where GDP compliance liability concentrates with fewer handling partners.
Industrial Tags Market Segmentation
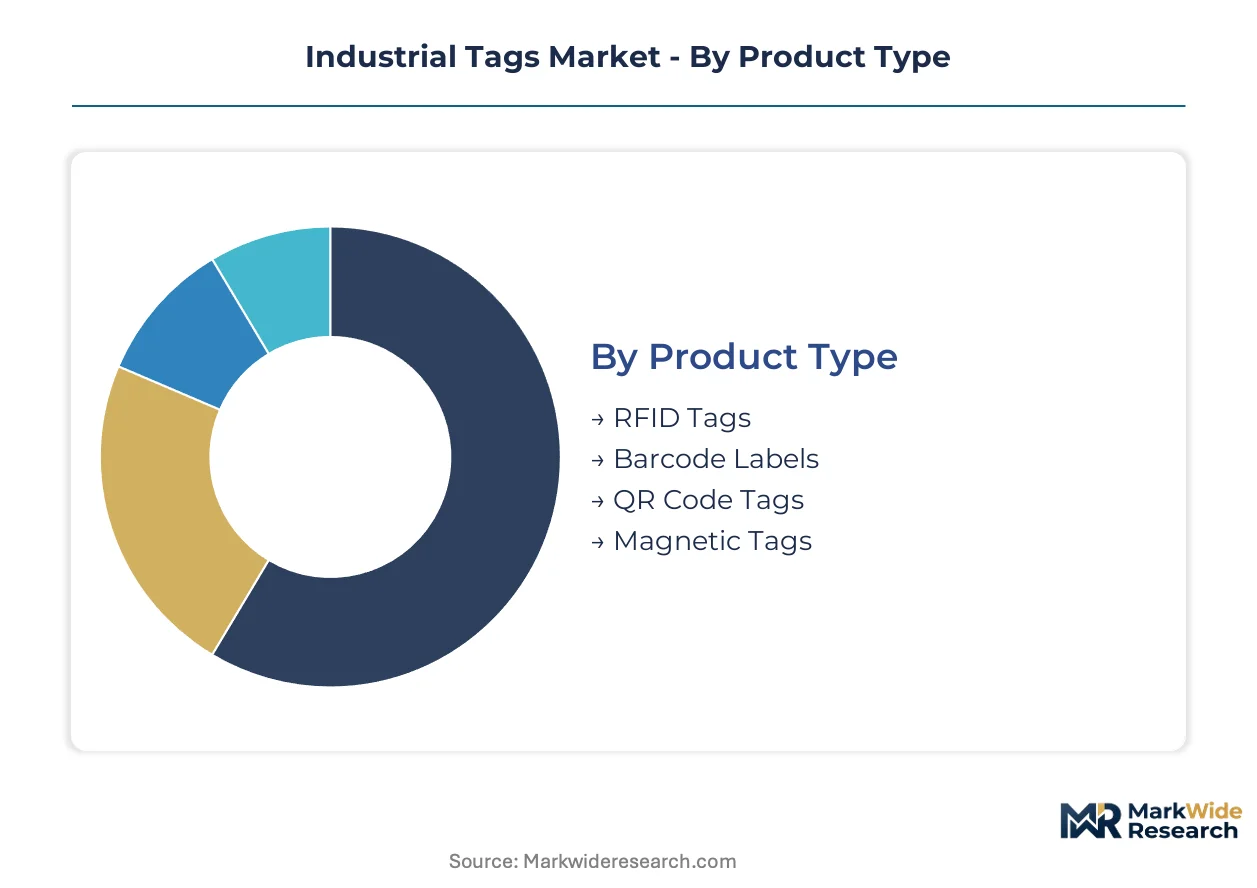
Industrial tag buyers segment procurement by technical performance thresholds, environmental exposure limits, and integration complexity with incumbent scanning infrastructure. Supplier portfolios must map precisely to these decision criteria to secure specification wins in enterprise RFPs.
Product Type:
Supply concentration in semiconductor fabrication and inlay assembly tilts competitive advantage toward converters with captive chip sourcing or long-term foundry allocations.
- RFID Tags:Passive UHF inlays with EPC Gen 2 encoding dominate high-velocity distribution centers where automated portal reads eliminate manual scanning labor. Demand concentrates in United States third-party logistics networks where retailer mandate cascades require pallet-level compliance. Silicon supply constraints during foundry allocation crunches expose non-integrated assemblers to delivery risk.
- Barcode Labels:Thermal transfer and direct thermal substrates serve cost-sensitive inventory lanes where laser or imager scanning suffices for one-dimensional symbology. Paper and synthetic film demand clusters in German automotive supplier parks where work-in-process tracking requires disposable identifiers at unit economics below RFID thresholds.
- QR Code Tags:Two-dimensional matrix symbologies encode larger data payloads in compact footprints for direct part marking and maintenance documentation.
- Magnetic Tags:Ferromagnetic strip or ferrite-core identifiers serve specialized access control and tool crib applications where electromagnetic detection replaces optical scanning.
Today's leader: RFID Tags. Tomorrow's challenger: QR Code Tags.
Material:
Raw material selection locks in performance boundaries for temperature exposure, chemical resistance, and mechanical durability across deployment environments.
- Metal:Etched aluminum or stainless steel substrates with permanent adhesives or mechanical fastening withstand offshore platform exposure and refinery process conditions. Oil and gas operators in the United States specify metal tags for valve and pipeline identification where flame resistance and corrosion immunity are non-negotiable. Premium positioning supports margin pools unavailable to polymer alternatives.
- Plastic:Polyester, polyimide, and vinyl films dominate general industrial labeling with thermal transfer print receptivity and moderate chemical resistance. Logistics providers in China specify PET substrates for warehouse rack labeling where abrasion resistance must balance cost against replacement frequency.
- Paper:Uncoated and coated stocks serve short-lifecycle applications including shipping labels and temporary inventory markers where moisture exposure is controlled.
- Laminate:Multi-layer constructions fuse protective films to core substrates, extending service life in washdown and UV-exposed environments.
Metal commands premium positioning. Plastic delivers volume scale.
Application:
Use-case complexity determines whether buyers prioritize unit economics, read reliability, or environmental sensing integration.
- Asset Tracking:Active RFID and sensor-integrated tags monitor location and condition of high-value mobile equipment across distributed facilities. Manufacturing campuses in Germany deploy battery-assisted tags on tooling and fixtures to eliminate search delays and production line stoppages. Real-time visibility software integration creates recurring revenue attachment for hardware suppliers.
- Inventory Management:Cycle counting and stock location verification drive demand for passive RFID and barcode solutions with rapid bulk-read capability. Retail distribution centers in the United States mandate RFID pallet tagging to compress receiving dock processing times.
- Product Labeling:Regulatory compliance and brand protection requirements specify serialization and authentication features for consumer-facing identifiers.
- Supply Chain:Multi-party handoff tracking spans inbound logistics through outbound fulfillment, requiring interoperability across incompatible enterprise systems.
Asset Tracking is expanding most quickly. Inventory Management holds installed base dominance.
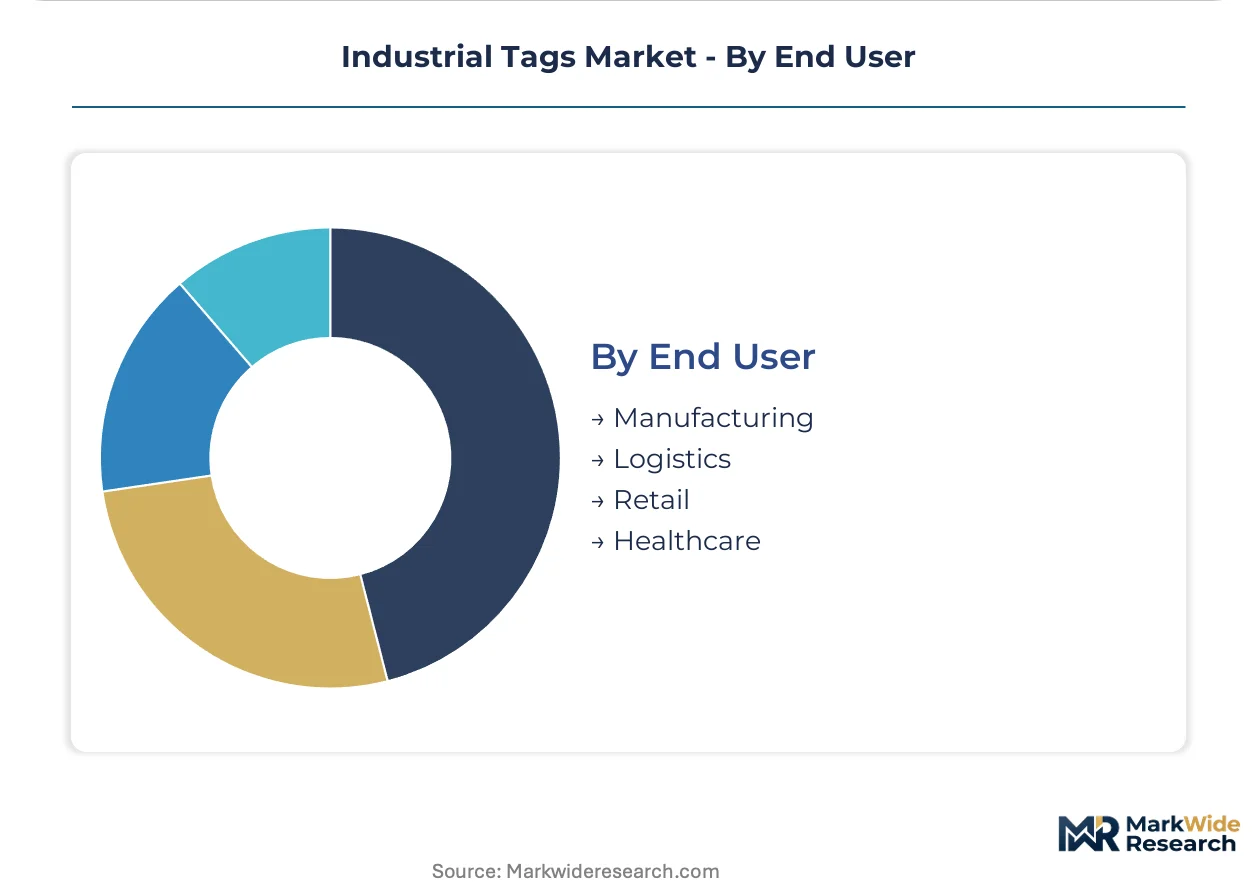
End User:
Buyer sophistication and technical specification authority vary sharply across vertical procurement organizations.
- Manufacturing:Discrete and process manufacturers specify tags for work-in-process visibility, quality traceability, and maintenance documentation. Automotive OEMs in Germany require GS1-compliant RFID for just-in-sequence component delivery to assembly lines. Engineering teams wield specification authority with limited procurement price pressure.
- Logistics:Third-party providers and parcel carriers demand read-rate guarantees and outcome-based pricing in master service agreements. Large 3PLs in the Netherlands now specify failure replacement terms rather than unit pricing for pharmaceutical distribution contracts.
- Retail:Big-box and apparel merchants drive upstream compliance through EPC Gen 2 mandate cascades to supplier bases.
- Healthcare:Hospital systems and pharmaceutical distributors require temperature-logging tags for cold chain custody documentation under GDP and FDA regulations.
Manufacturing anchors specification authority. Healthcare is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive supplier parks generate denser tag consumption per square kilometer than China's Yangtze River Delta logistics hubs, yet both markets now mandate incompatible encoding standards that fragment procurement specifications.
United States
Big-box retailer EPC Gen 2 mandates cascade through third-party logistics networks, forcing pallet-level RFID compliance upstream. The FCC governs 915 MHz spectrum allocation with updated Part 15 coexistence rules. Dallas-Fort Worth distribution clusters concentrate demand from pharmaceutical and apparel fulfillment centers requiring real-time inventory visibility.
Germany
Automotive OEMs specify GS1-compliant RFID for just-in-sequence component delivery, while REACH substance restrictions on adhesive chemistries favor pre-validated substrate suppliers. The European Chemicals Agency enforces certified supplier lists for industrial supply chains. Stuttgart and Wolfsburg manufacturing corridors anchor work-in-process tagging demand from powertrain and assembly operations.
China
MIIT coordinates GB standards harmonization for automatic identification equipment, creating unified certification pathways for foreign encoding systems. Warehouse rack labeling in Shanghai and Shenzhen logistics parks drives PET substrate volume at cost points below RFID thresholds. The Yangtze River Delta concentrates converter capacity serving domestic e-commerce fulfillment networks.
Netherlands
Third-party logistics consolidation compresses vendor qualification cycles toward outcome-based performance guarantees. GDP compliance liability for pharmaceutical distribution concentrates with fewer handling partners in Rotterdam and Amsterdam corridors. Large 3PLs now specify read-rate thresholds and failure replacement terms rather than unit pricing in master service agreements.
Industrial Tags Market Competitive Landscape
Top-tier vendors anchor enterprise subscription platforms, while mid-scale converters compete on materials science differentiation and regional regulatory certification speed. The vendor base stratifies across three archetypes: end-to-end visibility platform operators, specialized harsh-environment identification producers, and global materials science converters with captive inlay sourcing. Dominant competitive moves include cloud-platform convergence decoupling hardware from recurring revenue, and strategic partnerships with semiconductor foundries securing allocation priority during capacity crunches.
Within the platform-operator archetype, Zebra Technologies and Honeywell International Inc. exemplify enterprise software attachment strategies that sustain subscription revenue independent of hardware refresh cycles. Avery Dennison Corporation occupies a position representing global converting scale anchored through materials science infrastructure and long-term foundry relationships. Brady Corporation sits within the specialist tier exemplifying premium positioning in energy and aerospace verticals where chemical resistance and mechanical durability command specification authority.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Zebra Technologies |
| Brady Corporation |
| 3M Company |
| CCL Industries |
| HID Global |
| Honeywell International Inc. |
| UPM Raflatac |
| SATO |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up converter specialists across the United States and Europe have consolidated fragmented regional players, tightening working capital discipline and compressing quote-to-cash cycles for standard barcode substrates while preserving premium pricing power in certified harsh-environment grades.
Pricing Analysis
Capacity additions in China are reshaping price floors for PET film substrates and thermal transfer ribbons, forcing legacy Western converters toward three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on REACH-certified adhesive portfolios and ISO 18000-6C encoding validation. Cost compression in economy-grade barcode labels is intensifying because Chinese e-commerce fulfillment networks demand disposable unit economics below RFID thresholds. Third-party logistics providers exhibit the highest price sensitivity, while oil and gas operators accept substantial premiums for flame-resistant metal tag specifications.
Supply Chain Analysis
Single-source vulnerability sits with semiconductor foundry operators in Taiwan and South Korea, where silicon wafer fabrication for RFID inlays concentrates among a handful of captive suppliers. Raw material procurement draws from petrochemical-derived films, pressure-sensitive adhesives, and etched aluminum substrates. Tariff exposure on Chinese-converted substrates threatens margin stability for North American label assemblers. Distribution runs through converter-direct relationships with large enterprise accounts, supplemented by industrial distribution channels serving mid-market maintenance shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through sensor-integrated tag architectures that collapse identification and environmental monitoring into single-SKU premium offerings, offsetting commodity pressure in passive RFID and barcode tiers.
For Market Incumbents: Acquire cloud-based tag management software platforms to decouple recurring subscription revenue from hardware refresh cycles. Defensive consolidation of regional converter assets in Germany and the United States secures REACH-certified substrate portfolios against emerging Asian competitors. Threat substitution from printed electronics antenna technology demands accelerated R&D investment in flexible form factors for pharmaceutical serialization. For New Entrants and Emerging Players: MIIT harmonization of GB standards in China opens a window for foreign encoding system suppliers to capture warehouse automation demand in Shanghai and Shenzhen logistics corridors. White-space penetration targets include temperature-logging RFID for pharmaceutical GDP compliance in European distribution networks. Go-to-market execution should anchor on outcome-based performance guarantees rather than unit pricing to bypass incumbent procurement lock-in. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale converters with captive inlay sourcing but underdeveloped software attachment revenue. Long-term viability over the analysis window favors platform operators with enterprise ERP integration capabilities and recurring revenue visibility. Acquisition target archetypes include specialist harsh-environment identification producers in energy and aerospace verticals. Watch for foundry allocation crunches as inflection signals for margin compression in non-integrated assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Platform Convergence | Zebra Technologies demonstrates enterprise subscription attach rates decoupled from hardware refresh cycles. |
| Backward Integration into Semiconductor Sourcing | Avery Dennison's foundry relationships secure allocation priority during silicon capacity crunches. |
| REACH Certification Investment | Pre-validated substrate portfolios create procurement preference under ECHA substance restrictions. |
| Sensor-Integrated Tag Development | Condition-aware supply chains command premium positioning without battery maintenance overhead. |
| GB Standards Alignment | MIIT-approved encoding systems unlock unified addressable market access across Chinese logistics networks. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary fieldwork encompassed interviews with plant engineers at automotive OEMs, procurement leads at third-party logistics providers, technical R&D directors at adhesive converters, and aftermarket service heads at industrial distribution channels. Secondary validation drew from FCC spectrum allocation filings, ECHA REACH substance databases, MIIT GB standard harmonization notices, and SEC 10-K disclosures from listed identification technology vendors. Triangulation between demand-side deployment data and supply-side capacity announcements ensures cross-verified volume and value estimates.
Input-output matrices map tag unit consumption across manufacturing, logistics, retail, and healthcare verticals against inlay insertion capacity, substrate converting throughput, and software platform subscription attach rates. Segmentation dimensions include product type, material substrate, application complexity, and end-user procurement sophistication. CAGRs derive from regression analysis of historical deployment trajectories projected against retailer mandate cascade timelines and regulatory compliance deadline clustering. Industry-specific forecast inputs incorporate EPC Gen 2 mandate penetration curves and pharmaceutical GDP serialization requirements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under foundry allocation disruptions, petrochemical price volatility, or regional spectrum reallocation decisions. Forecasts reflect documented assumptions regarding retailer compliance deadline adherence and cloud-platform adoption elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
UV Conveyor Systems Market
Industrial Equipment
Precision Dispensing Accessories Market
Industrial Equipment
Electrode Slag Remelting (ESR) Furnace Market
Industrial Equipment
Dustless Workstations Market
Industrial Equipment
Laser Drilling Market
Industrial Equipment
Magnetizing Equipment Market
Industrial Equipment
Demagnetizer Market
Industrial Equipment
Global Abrasive Waterjet Cutting Machine Market
Industrial Equipment
Vibration Isolation Tables Market
Industrial Equipment
Fume Extractor Market
Industrial Equipment
Grading and Batching Systems Market
Industrial Equipment
TIG Torch Market
Industrial Equipment
Machine Tool Cooling System Market
Industrial Equipment
Equipment Cases Market
Industrial Equipment
United States Fusion Splicer Market
Industrial Equipment
Small Harmonic Reducer Market