
 Laser Drilling Market | 2026-2036
Laser Drilling Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Drilling Market Outlook
The laser drilling equipment landscape is restructuring around a sharp split between ultrafast femtosecond systems commanding premium pricing and commodity nanosecond platforms serving high-volume electronics. TRUMPF GmbH + Co. KG dominates European precision applications with vertically integrated beam source production. IPG Photonics Corporation anchors fiber laser supply chains through captive diode manufacturing. Han's Laser Technology Industry Group Co., Ltd. competes aggressively on cost for Asian electronics contract manufacturers.
Laser drilling uses focused coherent light to ablate material and create holes with diameters from microns to millimeters, typically achieving aspect ratios exceeding 10:1 in metals and ceramics while maintaining sub-micron positional accuracy. Fiber lasers now lead industrial installations due to superior wall-plug efficiency and maintenance intervals. Solid-state lasers retain dominance in medical device stent drilling where pulse energy stability governs regulatory acceptance. Ultrafast laser processing represents the fastest-growing technology segment as heat-affected zone minimization becomes critical for next-generation semiconductor packaging.
FDA device manufacturing regulations and EU MDR quality system requirements shape validation protocols for medical laser drilling installations. China's GB standards and NMPA medical device directives govern import substitution programs for domestic equipment suppliers. REACH compliance on processed material effluents increasingly constrains European automotive drilling operations. Stakeholders must monitor how evolving semiconductor export controls and carbon border adjustments recalibrate equipment sourcing strategies across major manufacturing clusters.
Market Dynamics
Fiber laser technology is displacing solid-state systems across precision manufacturing, driven by wall-plug efficiency gains and extended maintenance intervals that compress total cost of ownership for high-volume operators.
Growth Catalysts
- Aerospace turbine cooling:Next-generation jet engines require 50,000+ precisely angled cooling holes per blade. Femtosecond laser systems from Germany and the United States now dominate this specification tier.
- EU MDR compliance pathways:Medical device stent manufacturers must validate heat-affected zone dimensions under updated quality system requirements, locking in ultrafast laser adoption for coronary applications.
- Semiconductor packaging miniaturization:Through-silicon via drilling at sub-10 micron diameters demands beam stability that only fiber-amplified sources deliver at production scale.
Market Restraints
- Diode supply concentration:High-power pump diodes for fiber laser resonators source primarily from Chinese and German foundries, creating single-point vulnerability for equipment builders.
- Technical limitation in ceramics:Alumina and silicon nitride substrates exhibit unpredictable fracture propagation under nanosecond pulse regimes, constraining electronics substrate applications.
- Substitution by electrical discharge machining:Deep-hole drilling in superalloys above 20:1 aspect ratio remains more cost-effective via EDM for non-cooling-hole geometries in legacy aerospace programs.
Strategic Opportunities
- Indian defense manufacturing:The country's PLI scheme for aerospace components creates first-mover advantage for laser drilling system suppliers establishing local service infrastructure.
- Battery electrode perforation:Solid-state battery architectures require precisely patterned micro-holes for electrolyte infiltration, opening volume demand from Korean and Japanese cell manufacturers.
- Carbon border adjustment alignment:European automotive suppliers sourcing drilled components from China face Scope 3 reporting requirements that favor regional laser processing capacity expansion.
Industry Challenges
- Multiphysics simulation expertise:Predictive modeling of melt ejection dynamics in high-aspect-ratio drilling requires rare combinations of optical physics and computational fluid dynamics competency.
- FDA 510(k) validation timelines:Medical device contract manufacturers face 18-24 month clearance cycles for new laser drilling installations, compressing equipment depreciation schedules.
- Legacy CNC integration:Brownfield aerospace machine shops struggle to synchronize femtosecond laser positioning systems with existing five-axis motion controllers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Drilling Market |
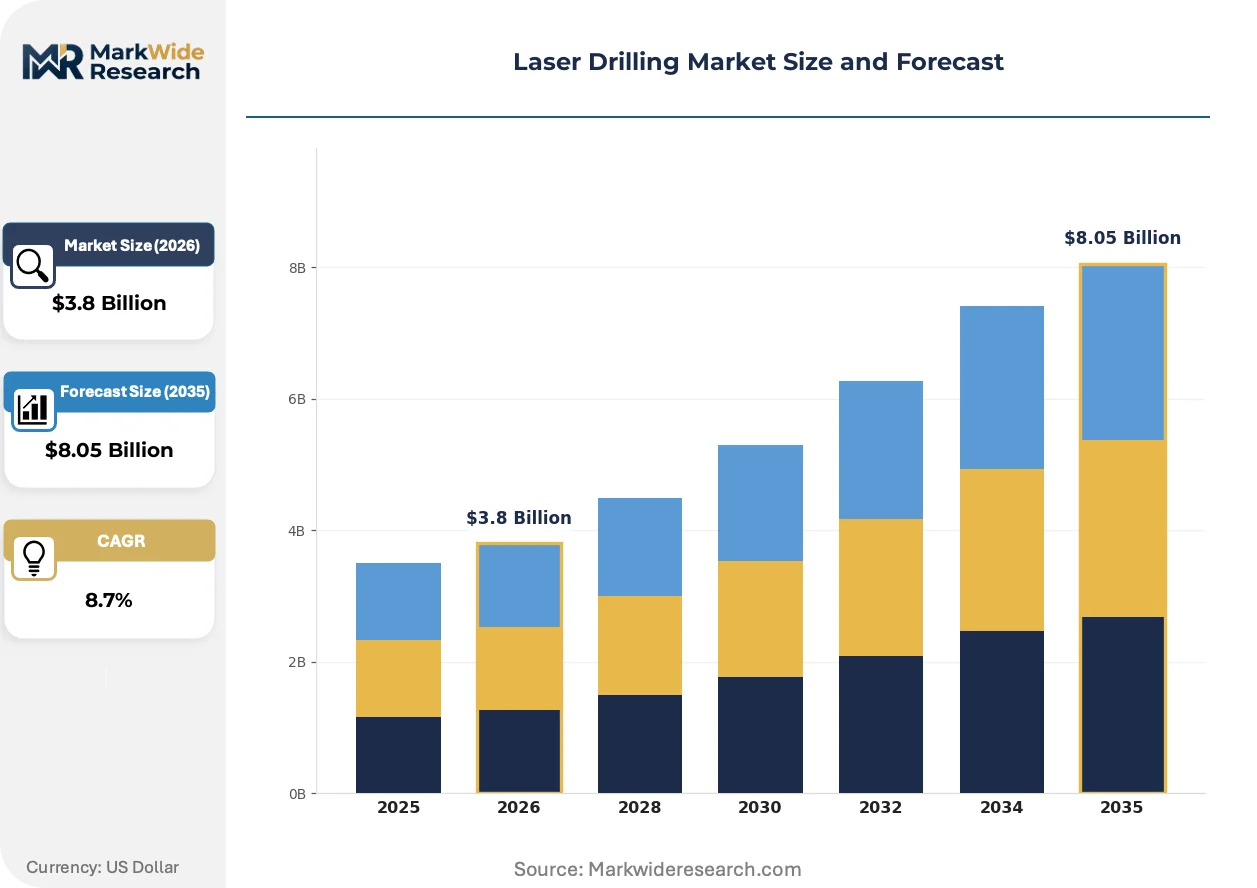
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Lasers, Solid-State Lasers, Fiber Lasers, Diode Lasers Technology: Ultrafast Laser Processing, Continuous Wave Laser, Pulsed Laser, Hybrid Laser Systems End User: Aerospace, Automotive, Electronics, Medical Devices Application: Micro-Hole Drilling, Engraving, Cutting, Material Processing |
| Companies Covered | Han's Laser Technology Industry Group Co., Ltd., nLIGHT, Inc., TRUMPF GmbH + Co. KG, Mitsubishi Electric Corporation, Amada Co., Ltd., IPG Photonics Corporation, Jenoptik AG, Laserline GmbH, Coherent, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Drilling Market Strategic Shifts
Beam delivery architectures and process monitoring systems are undergoing simultaneous transformation, collapsing the historical separation between optical hardware and real-time quality assurance.
Femtosecond laser systems are converging with inline coherent imaging for depth-resolved ablation monitoring. Medical stent manufacturers in Switzerland and Germany deploy these combined platforms to eliminate post-process inspection bottlenecks. The integration is compressing validation documentation burdens under EU MDR technical file requirements.
REACH compliance on processed material effluents is forcing automotive drilling operations toward closed-loop filtration. German Tier-1 suppliers now specify vacuum extraction systems with 99.97% particulate capture as mandatory bid qualifications. The regulation is accelerating replacement cycles for legacy open-air processing cells across European manufacturing clusters.
Equipment-as-a-service contracting is displacing capital purchase models among Asian electronics contract manufacturers. Korean and Taiwanese semiconductor packaging houses now lease fiber laser drilling capacity with per-hole pricing tied to yield guarantees. The shift concentrates fleet ownership among TRUMPF and IPG Photonics captive financing arms, locking out smaller regional distributors from high-volume accounts.
Laser Drilling Market Segmentation
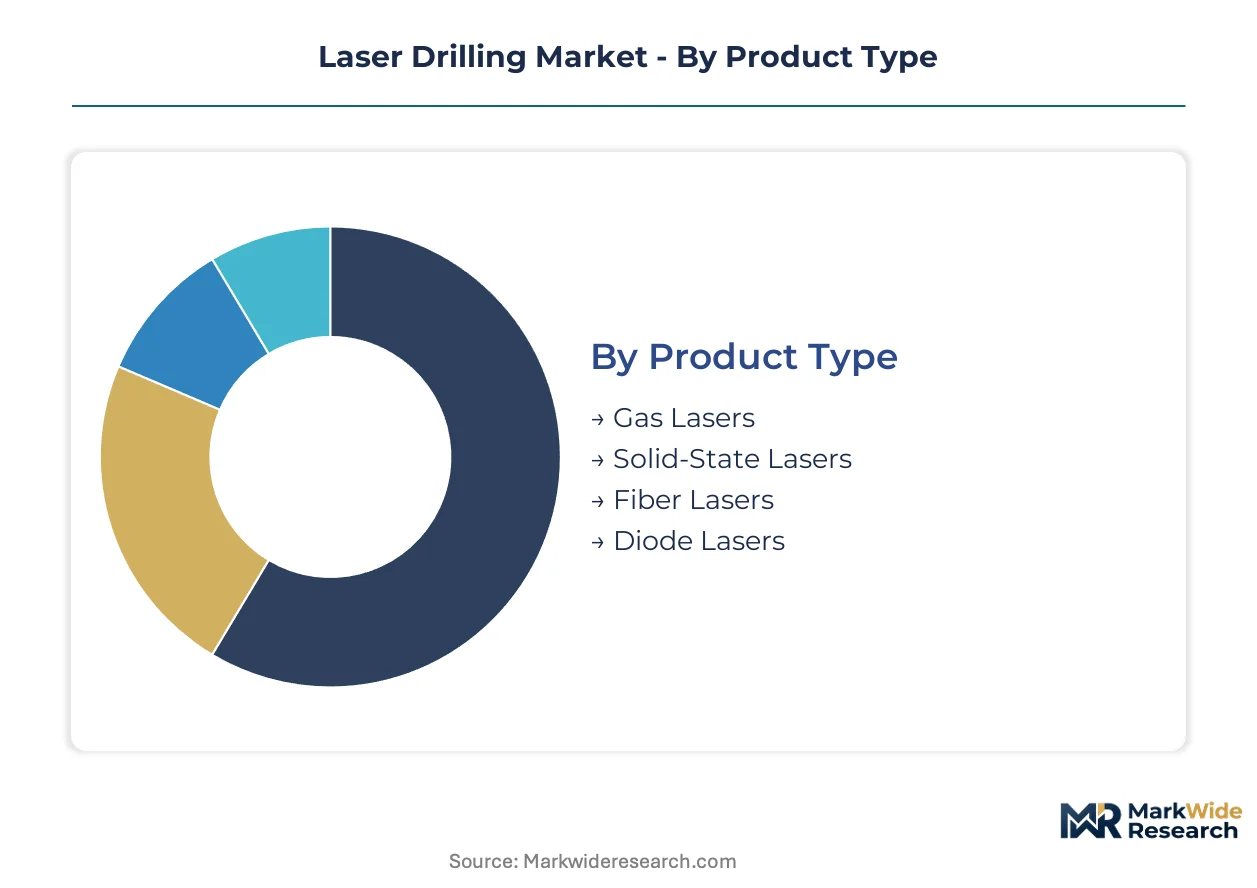
Laser drilling equipment procurement hinges on matching pulse regime to material response. Buyers weigh wall-plug efficiency against heat-affected zone requirements across aerospace, medical, and electronics verticals. The following segmentation maps how technical specifications translate into purchasing decisions.
Product Type:
Purchase decisions here pivot on total cost of ownership calculations for high-volume versus precision applications.
- Fiber Lasers:These systems amplify light through rare-earth-doped silica fibers, achieving wall-plug efficiencies above 30 percent. German automotive suppliers and Chinese electronics contract manufacturers now specify fiber platforms for production-scale turbine blade and printed circuit board drilling.
- Solid-State Lasers:Nd:YAG and similar crystal-based resonators deliver pulse energy stability critical for FDA-validated medical device manufacturing. Swiss and German stent producers retain these systems despite higher maintenance burdens because regulatory submissions lock in process parameters.
- Gas Lasers:CO2 platforms remain relevant for thick-section organic material processing where infrared absorption characteristics matter.
- Diode Lasers:Direct-emitting systems serve cost-sensitive marking and shallow engraving applications with minimal capital outlay.
Fiber lasers lead on scale across industrial installations; solid-state lasers lead on momentum within medical validation pipelines.
Technology:
Technology selection determines which defect modes dominate and whether post-process inspection can be reduced.
- Ultrafast Laser Processing:Femtosecond and picosecond systems ablate material through multiphoton ionization rather than thermal vaporization. Semiconductor packaging houses in Taiwan and Korea deploy these for through-silicon via drilling where sub-micron heat-affected zones prevent interconnect failure.
- Pulsed Laser:Nanosecond and microsecond regimes balance throughput and precision for aerospace cooling hole fabrication. United States and German turbine blade suppliers standardize on these platforms for angled hole arrays exceeding 50,000 per component.
- Continuous Wave Laser:Uninterrupted beam output suits deep penetration welding and cutting where hole geometry tolerances relax.
- Hybrid Laser Systems:Combined beam architectures integrate multiple pulse regimes for sequential roughing and finishing operations.
Pulsed laser platforms anchor current installed base; ultrafast processing climbs fastest on semiconductor miniaturization demand.
End User:
End-use verticals impose distinct certification burdens and throughput requirements that reshape equipment specifications.
- Aerospace:Turbine blade cooling hole fabrication demands femtosecond precision for angled micro-holes in thermal barrier coatings. FAA airworthiness directives and OEM process specifications lock suppliers into validated laser platforms with traceable beam parameter records.
- Electronics:Printed circuit board and semiconductor packaging applications prioritize speed and positional accuracy over pulse energy stability. Asian contract manufacturers drive volume demand for fiber-amplified systems with automated vision alignment.
- Medical Devices:Coronary stent and orthopedic implant drilling requires EU MDR technical file documentation of heat-affected zone dimensions.
- Automotive:Fuel injector nozzle and sensor housing applications balance cost targets with emerging carbon border adjustment reporting requirements.
Electronics commands the largest equipment fleet; aerospace exhibits steepest expansion trajectory on next-generation engine programs.
Application:
Application scope defines whether systems sell as standalone capital equipment or integrated production cells.
- Micro-Hole Drilling:Diameter control from microns to millimeters with aspect ratios exceeding 20:1 in superalloys. This capability tier commands premium pricing and requires synchronized five-axis motion control.
- Cutting:Through-thickness material separation with kerf width optimization for subsequent joining operations.
- Engraving:Surface texture modification for part identification and aesthetic finishing with minimal material removal.
- Material Processing:Broad category encompassing surface treatment, texturing, and additive repair applications.
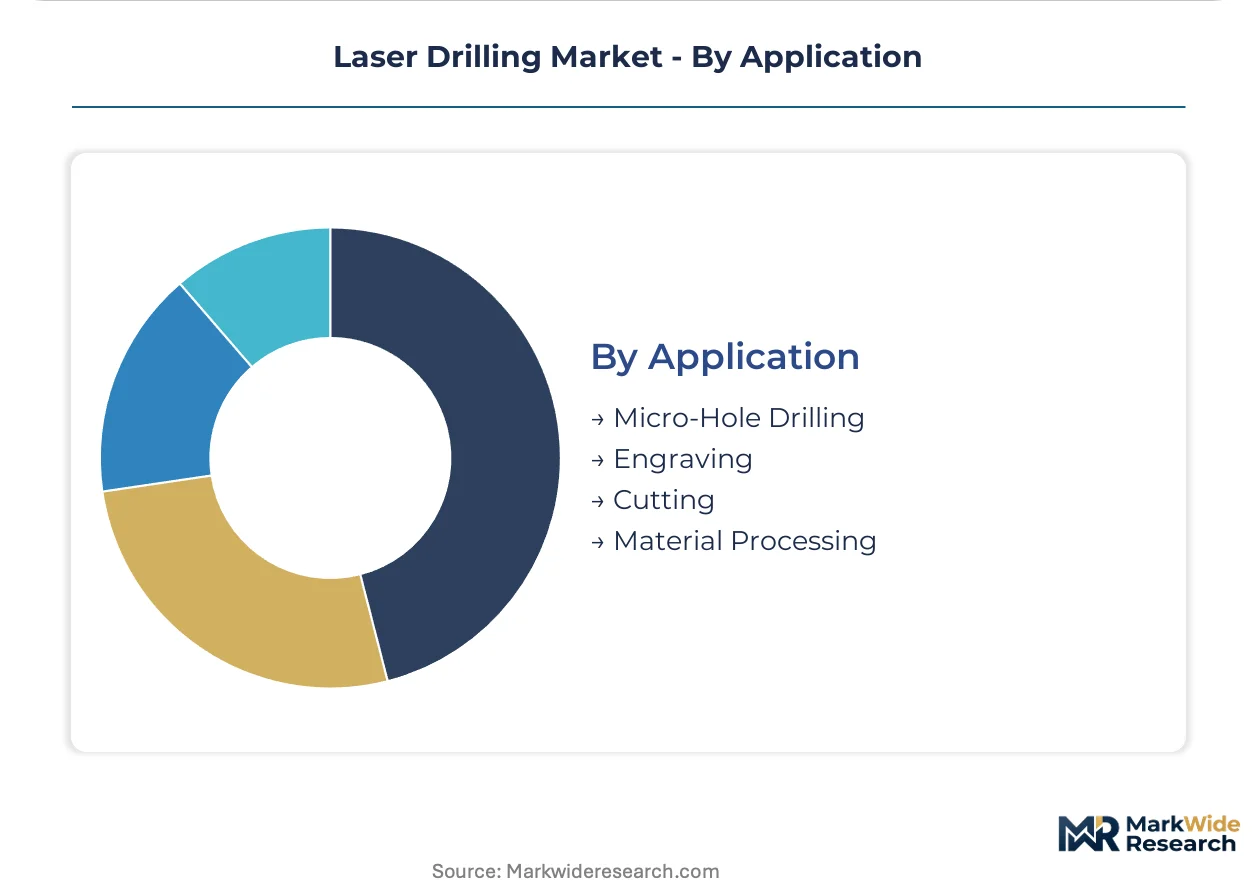
Micro-hole drilling concentrates value capture; cutting applications expand fastest on electric vehicle battery component demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical engineering talent pools in Germany, the United States, and China anchor global laser drilling capacity. These three countries concentrate femtosecond beam source development, precision motion control manufacturing, and high-volume electronics contract production respectively.
Germany
Stuttgart and Munich host the densest concentrations of ultrafast laser source manufacturers serving aerospace turbine blade programs. EU MDR compliance requirements for medical device stent drilling lock German OEMs into validated production protocols. The country's REACH regulations on processed material effluents now mandate closed-loop filtration systems for automotive drilling operations.
United States
FAA airworthiness directives for next-generation jet engines drive demand for angled cooling hole fabrication exceeding 50,000 holes per blade. FDA 510(k) validation timelines constrain medical device contract manufacturers to 18-24 month equipment clearance cycles. Connecticut and Arizona industrial clusters concentrate femtosecond system integration for defense and semiconductor packaging applications.
China
Shenzhen and Suzhou electronics contract manufacturers drive volume demand for fiber-amplified drilling systems with automated vision alignment. NMPA medical device directives and GB standards govern import substitution programs for domestic equipment suppliers. The country's dual carbon goals accelerate replacement of legacy solid-state platforms in automotive component plants.
Japan
Osaka and Nagoya precision tool builders supply hybrid laser-EDM systems for superalloy applications above 20:1 aspect ratios. METI industrial technology roadmaps prioritize through-silicon via drilling for advanced semiconductor packaging. JIS certification requirements lock domestic automotive suppliers into traceable beam parameter documentation.
South Korea
Suwon and Pyeongtaek semiconductor packaging houses deploy fiber laser drilling for sub-10 micron diameter through-silicon vias. MFDS medical device quality system requirements shape validation protocols for coronary stent manufacturers. Equipment-as-a-service contracting with per-hole pricing now dominates fleet procurement among major electronics contract manufacturers.
Laser Drilling Market Competitive Environment
Top-tier vendors anchor premium ultrafast and fiber laser system supply, while mid-tier regional fabricators compete on cost for standard nanosecond platforms. German and Chinese manufacturers concentrate beam source production through backward integration into diode manufacturing. Three archetypes dominate: vertically integrated photonics conglomerates with captive component supply, precision system integrators specializing in five-axis motion synchronization, and volume-focused contract equipment suppliers serving Asian electronics manufacturing. Competitive moves center on strategic partnerships for local service infrastructure and technology licensing to bypass capital-intensive resonator development.
Within the premium-tier vector, TRUMPF GmbH + Co. KG and IPG Photonics Corporation exemplify contrasting integration strategies. TRUMPF anchors European precision applications through in-house beam source production, while IPG Photonics occupies a position defined by captive diode manufacturing for fiber laser supply chains. Han's Laser Technology Industry Group Co., Ltd. represents the scale-driven archetype among Shenzhen-based electronics equipment suppliers, competing aggressively on cost for high-volume contract manufacturing accounts.
| Leading Market Players |
|---|
| Han's Laser Technology Industry Group Co., Ltd. |
| nLIGHT, Inc. |
| TRUMPF GmbH + Co. KG |
| Mitsubishi Electric Corporation |
| Amada Co., Ltd. |
| IPG Photonics Corporation |
| Jenoptik AG |
| Laserline GmbH |
| Coherent, Inc. |
| Others |
Value Chain & Pricing Dynamics
Fiber laser platform migration simultaneously compresses operating costs for high-volume electronics manufacturers and concentrates beam source supply among German and Chinese diode foundries. This technological shift tightens margin structures for mid-tier system integrators while amplifying pricing power for vertically integrated resonator producers.
Pricing Analysis
Equipment-as-a-service bundling now separates premium femtosecond installations from commodity nanosecond platforms. Price differentiation hinges on EU MDR certification tier and per-hole yield guarantees, with Asian contract manufacturers driving cost compression through consolidated fleet procurement. Aerospace turbine blade suppliers exhibit lowest price sensitivity due to FAA-mandated process validation lock-in.
Supply Chain Analysis
Dual-sourcing requirements for high-power pump diodes now mandate qualification across Chinese and German foundries to mitigate single-point vulnerability. The supply chain draws from rare-earth fiber preforms, precision motion control hardware, and vacuum extraction systems. Tariff exposure on semiconductor-grade optics threatens cost predictability. Distribution runs through captive financing arms of major OEMs and regional service distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Laser Drilling Market functions as a geographic-arbitrage play where EU MDR compliance costs in Germany and Switzerland exceed NMPA pathway expenses in China by substantial margins, redirecting volume stent manufacturing toward Asian contract facilities.
For Market Incumbents: Acquire femtosecond beam source development capabilities to counter IPG Photonics' captive diode advantages. Lock in aerospace OEMs through multi-year service contracts with traceable beam parameter documentation. Expand local service infrastructure in India ahead of PLI scheme aerospace component manufacturing scale-up. For New Entrants and Emerging Players: Ultrafast laser-EDM hybrid architectures offer entry points into superalloy applications above 20:1 aspect ratios where pure laser systems face technical constraints. Target Korean solid-state battery electrode perforation demand as first commercial anchor. Pursue equipment-as-a-service partnerships with Taiwanese semiconductor packaging houses to bypass capital-intensive resonator development. For Investors and Strategic Acquirers: Roll-up economics work for precision motion control specialists because five-axis synchronization expertise remains scarce relative to fiber resonator commoditization. Five-to-ten year viability favors mid-tier integrators with validated medical device installation records. Watch FDA 510(k) clearance timeline compression as inflection signal for medical contract manufacturing consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diode Manufacturing | Captive pump diode production insulates TRUMPF and IPG Photonics from Chinese-German foundry concentration risk. |
| Equipment-as-a-Service Fleet Leasing | Per-hole pricing with yield guarantees locks Korean and Taiwanese semiconductor packaging houses into long-term contracts. |
| Local Service Infrastructure Expansion | Indian defense aerospace PLI scheme rewards first-mover laser drilling suppliers with maintenance presence. |
| Femtosecond-Inline Coherent Imaging Integration | Swiss and German stent manufacturers deploy combined platforms to compress EU MDR technical file validation burdens. |
| Closed-Loop Filtration System Mandate | German Tier-1 automotive suppliers specify 99.97% particulate capture to satisfy REACH effluent compliance. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with laser system procurement managers, aerospace manufacturing engineers, medical device quality assurance leads, and semiconductor packaging operations directors against secondary validation through SEC filings, customs trade data, FDA 510(k) clearance databases, and EU MDR technical file registries. Bottom-up equipment shipment tallies and top-down end-use demand estimates were cross-referenced for triangulation.
Segment-weighting across fiber, solid-state, gas, and diode laser platforms combined with ultrafast, pulsed, continuous wave, and hybrid technology categories shaped the analytical framework. End-use verticals modeled included aerospace turbine blade fabrication, electronics contract manufacturing, medical device stent production, and automotive component processing. CAGRs were derived from installed base evolution and replacement cycle analysis, with semiconductor packaging miniaturization and EU MDR compliance timelines as primary forecast inputs.
The model holds under stable semiconductor export control regimes and sustained aerospace engine program funding; deviation in pump diode supply disruption or carbon border adjustment enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Cartridge Heaters Market
Industrial Equipment
Global High Power Laser Systems Market
Industrial Equipment
Fiber Laser Coding System Market
Industrial Equipment
Fiber Laser Market
Industrial Equipment
Electric Soldering Iron Gun Market
Industrial Equipment
Automatic Laser Welding Machine Market
Industrial Equipment
Global Liquid Handling Systems Market
Industrial Equipment
Precision Positioning Equipment Market
Industrial Equipment
Mounted Bearing Market
Industrial Equipment
Global Cryostat Market
Industrial Equipment
Global Refrigeration Compressor Market
Industrial Equipment
Equipment Cases Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
Electrodynamic Shaker Systems Market
Industrial Equipment
Electronic Beam Machining Market
Industrial Equipment
Global Laboratory Vacuum Pumps Market