
 Portable Laser Cleaning Machine Market | 2026-2036
Portable Laser Cleaning Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Laser Cleaning Machine Market Insights
Multi-source component procurement is decoupling from traditional single-vendor laser system dependencies across the portable cleaning equipment supply base. IPG Photonics leverages its fiber laser source dominance to anchor downstream machine partnerships in North America and Europe. Han's Laser competes on manufacturing scale, sustaining cost advantages in mid-power system categories that serve China's automotive supplier networks.
A portable laser cleaning machine directs a focused, pulsed or continuous-wave laser beam onto a substrate to ablate contaminants, oxides, or coatings through thermal shock and vaporization, typically operating at power levels between 50W and 2,000W with fiber-coupled beam delivery. Its primary industrial purpose replaces chemical baths, abrasive blasting, and manual grinding with a non-contact, residue-free process that preserves base material integrity. Fiber laser systems dominate unit shipments due to superior wall-plug efficiency and maintenance intervals, while robotic technology configurations command premium positioning as automotive and aerospace end users integrate these units into existing production lines for repeatable quality outcomes.
EPA air-emission standards and OSHA workplace exposure limits constrain traditional abrasive and chemical cleaning methods, directly elevating laser-based alternatives in US manufacturing facilities. REACH substance restrictions and the EU Green Deal's industrial decarbonization targets similarly redirect European surface-treatment spending toward dry processes that eliminate solvent disposal liabilities. Stakeholders must weigh power-source compatibility against automation readiness as capital allocation decisions increasingly favor systems that bridge standalone portability with future robotic integration pathways.
Market Dynamics
REACH substance restrictions and EPA air-emission standards are systematically eliminating solvent-based and abrasive surface preparation methods, redirecting capital toward fiber-laser systems that eliminate chemical disposal liabilities and media waste streams while preserving substrate integrity.
Growth Catalysts
- Aerospace Maintenance Mandates:Turbine blade restoration protocols now specify non-contact cleaning to preserve thermal barrier coatings. MRO facilities in Germany and the United States are retrofitting hangars with portable units.
- REACH Chemical Phase-Outs:ECHA restrictions on chlorinated solvents and hexavalent chromium processes force European metal finishers toward dry ablation technologies that eliminate hazardous waste reporting.
- Automotive Supplier Integration:China's NEV battery tray manufacturers deploy pulsed fiber systems for aluminum oxide removal prior to welding, replacing mechanical brushing in Shenzhen and Ningbo production clusters.
Market Restraints
- Fiber Laser Source Concentration:High-power single-mode pump diodes and ytterbium-doped gain fibers concentrate among German and American specialty photonics suppliers, creating input bottlenecks during demand surges.
- Capital Intensity Threshold:Entry-level 500W systems require substantial upfront outlay compared to abrasive blasting rigs, compressing adoption among small-scale job shops and independent restoration contractors.
- Technical Limitation on Reflective Substrates:Copper and highly polished aluminum surfaces scatter 1,064nm radiation, requiring wavelength-tuned MOPA architectures that inflate system complexity and maintenance protocols.
Strategic Opportunities
- Underpenetrated Heritage Conservation:Italian marble restoration studios and French monument conservation agencies remain reliant on micro-abrasive methods, creating white space for low-fluence laser systems with integrated debris extraction.
- EU Green Deal Industrial Decarbonization:CSRD-aligned capital expenditure programs subsidize dry process transitions, positioning laser cleaning as qualifying technology for scope 3 emission reductions in European manufacturing.
- Robotic Integration Pathways:Collaborative robot arm compatibility is converging with portable chassis designs, enabling automotive OEMs to redeploy units across stamping, paint, and assembly lines without dedicated station infrastructure.
Industry Challenges
- Laser Safety Officer Certification Delays:OSHA and IEC 60825 compliance requires site-specific hazard assessments and operator training programs that extend deployment timelines by four to eight weeks.
- Legacy ERP Integration Friction:Standalone portable units lack standardized OPC-UA or MQTT connectivity, forcing manual data entry into MES systems and disrupting digital thread continuity in smart factory environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Laser Cleaning Machine Market |
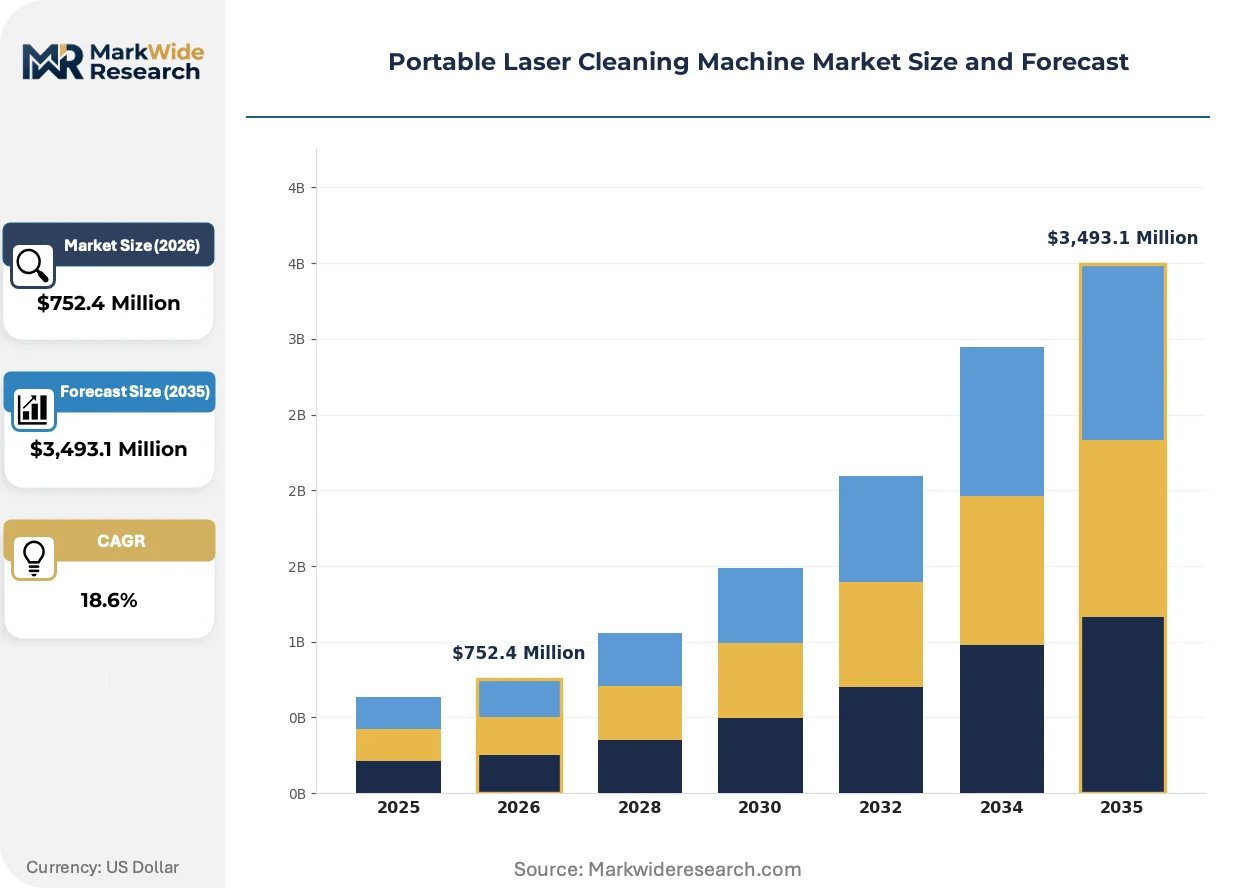
| Market Size in 2026 | $752.4 Million |
| Market Size in 2035 | $3,493.1 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Laser, Solid-State Laser, Diode Laser, Others Application: Metal Surface Cleaning, Paint Removal, Rust Removal, Industrial Component Maintenance End User: Aerospace, Automotive, Manufacturing, Shipbuilding Technology: Manual, Automated, Robotic, Remote Operated |
| Companies Covered | CleanLASER, IPG Photonics, Han's Laser, Trumpf, Laserax, MaxWave, Cleantech, Raymond Laser, Senfeng, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Laser Cleaning Machine Market Trends and Innovations
Portable laser cleaning architecture is pivoting from isolated handheld units toward modular platforms that accommodate robotic end-effector mounting and real-time process monitoring through embedded spectrometers.
Pulsed MOPA fiber laser engines are converging with on-board LIBS spectroscopy for real-time substrate identification and automatic parameter adjustment. Automotive paint shops in Stuttgart and Wolfsburg deploy these configurations to distinguish primer layers from base metal without operator intervention. The convergence is compressing process development cycles from weeks to hours while reducing rework rates.
EPA National Emission Standards for Hazardous Air Pollutants are tightening controls on abrasive blasting particulate matter and chemical stripping volatile organic compounds. Metal fabrication facilities in Michigan and Ohio face compliance deadlines that elevate laser alternatives above traditional methods. The affected segment—structural steel surface preparation—is responding through phased equipment replacement programs tied to facility upgrade timelines.
Buyer preference is rotating from capital purchase toward performance-guaranteed service contracts where equipment vendors retain ownership and charge per square meter cleaned. German automotive supplier networks and Japanese precision component manufacturers are piloting these arrangements. The shift is most visible in Bavaria's industrial corridor, where mid-tier subcontractors outsource capital risk to preserve balance sheet capacity.
Portable Laser Cleaning Machine Market Segmentation
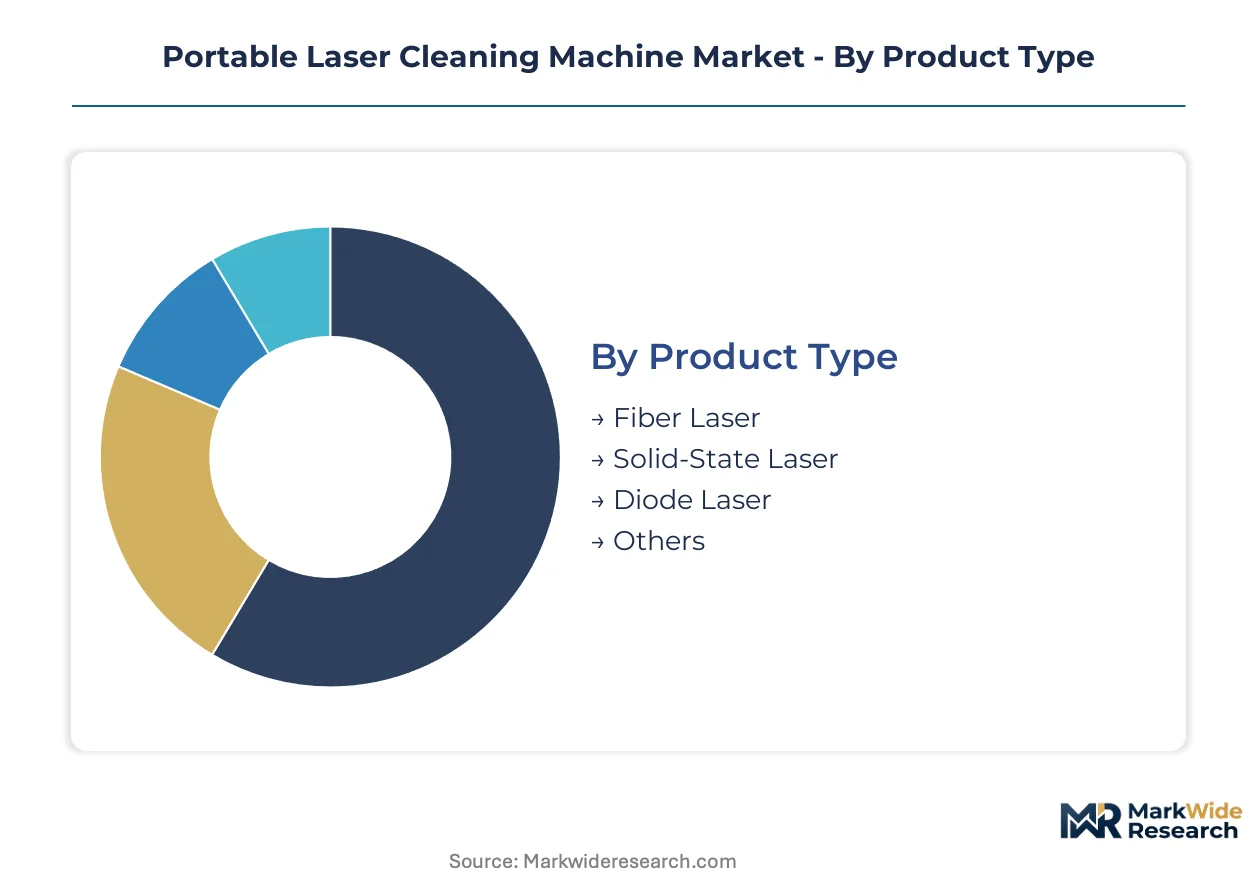
Segmentation reveals how power source selection, automation level, and end-use severity dictate equipment specifications and supplier margins. Buyers in aerospace and automotive verticals prioritize beam quality and repeatability over upfront cost, while general manufacturing segments drive volume through standardized fiber platforms.
Product Type:
Fiber lasers command unit volume through superior wall-plug efficiency and maintenance intervals, while solid-state architectures retain premium positioning for specialized wavelength requirements.
- Fiber Laser:Ytterbium-doped fiber cores deliver 1,064nm output with electro-optical conversion exceeding 30%, enabling compact chassis designs. Demand concentrates in China's automotive supplier networks, where NEV battery tray manufacturers prioritize throughput over capital cost recovery timelines. IPG Photonics and nLIGHT anchor supply through captive diode and fiber production.
- Solid-State Laser:Nd:YAG and vanadate crystals generate shorter pulse durations for heat-sensitive substrates. Heritage conservation studios in Italy and France specify these systems for marble and sandstone restoration where thermal damage thresholds constrain fiber alternatives. Unit economics favor rental service models over direct purchase.
- Diode Laser:Direct-emitting bars offer cost efficiency below 500W for light oxide removal. German job shops deploy these for tool cleaning and mold maintenance.
- Others:Excimer and CO2 variants address polymer ablation and organic coating removal. Semiconductor fabrication facilities in South Korea utilize these for photoresist stripping.
Mature deployment sits with fiber laser systems. Newer deployment is concentrated in solid-state architectures for wavelength-tuned heritage applications.
Application:
Surface preparation severity determines power scaling, with heavy corrosion demanding pulsed MOPA engines and light contamination tolerating continuous-wave diode configurations.
- Metal Surface Cleaning:Oxide and scale removal from steel, aluminum, and titanium substrates constitutes the foundational use case. Michigan and Ohio structural steel fabricators replace abrasive blasting under EPA National Emission Standards deadlines. Process parameters center on fluence thresholds that vaporize contaminants without base metal melting.
- Paint Removal:Multi-layer automotive and aerospace coating systems require selective ablation depth control. Stuttgart paint shops deploy LIBS-integrated systems to distinguish primer from base metal automatically. Thermal barrier coating preservation in turbine blade MRO drives specification stringency.
- Rust Removal:Heavy corrosion on marine and infrastructure steel demands high-pulse-energy configurations. Shipyards in Hamburg and Rotterdam phase in portable units for dockside hull maintenance.
- Industrial Component Maintenance:Preventive cleaning of molds, dies, and tooling emphasizes minimal downtime. Japanese precision component manufacturers integrate these systems into scheduled maintenance windows.
Volume concentration rests with metal surface cleaning. Paint removal commands the steepest expansion trajectory as automotive OEMs retrofit lines for NEV platform flexibility.
End User:
Capital allocation authority and technical sophistication vary sharply across buyer categories, with aerospace mandating certified processes and manufacturing prioritizing payback period.
- Aerospace:FAA and EASA repair station approvals require documented process validation for turbine blade restoration. German MRO facilities in Hamburg and Frankfurt lead hangar retrofit programs. Non-contact cleaning preserves thermal barrier coatings that mechanical methods damage.
- Automotive:Battery tray welding preparation and paint line maintenance dominate procurement. Shenzhen and Ningbo production clusters in China's NEV corridor specify pulsed fiber systems for aluminum oxide removal prior to laser welding.
- Manufacturing:General metal fabrication and job shops drive standardized mid-power system demand. REACH compliance pressures European finishers toward dry process conversion.
- Shipbuilding:Hull preparation and deck maintenance applications favor high-power mobile platforms. Korean and Chinese yards evaluate robotic integration for block assembly lines.
Procurement maturity sits with aerospace end users. Manufacturing segments represent the fastest volume scaling as regulatory deadlines compress adoption timelines.
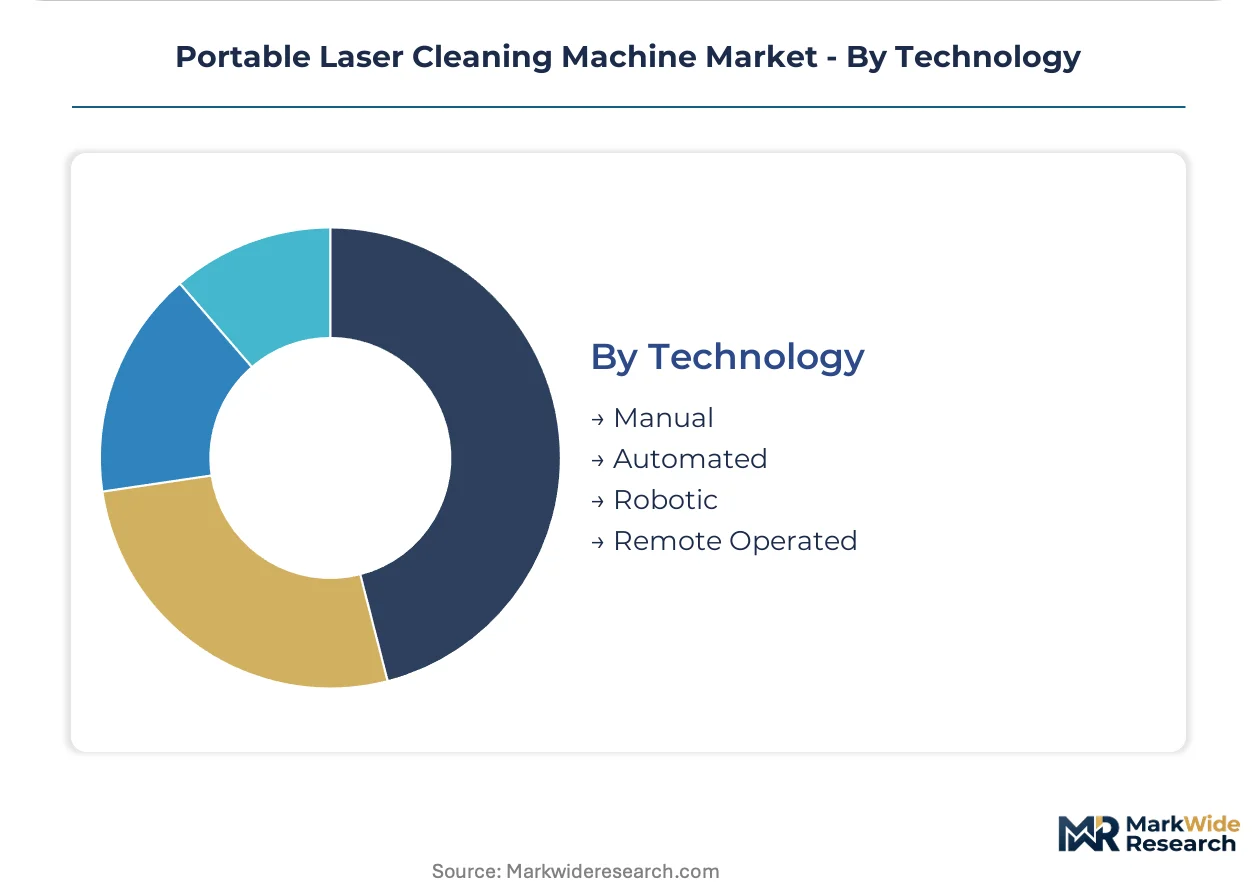
Technology:
Automation readiness separates price-competitive handheld units from premium robotic configurations that integrate into existing production infrastructure.
- Manual:Handheld guns with joystick or trigger control suit field maintenance and irregular geometries. Independent restoration contractors and small job shops dominate this tier.
- Automated:CNC-programmed scanning heads enable repeatable coverage on flat or cylindrical surfaces. German automotive suppliers deploy these for batch processing of stampings and castings.
- Robotic:Collaborative arm mounting with force-torque sensing permits redeployment across stamping, paint, and assembly lines. Wolfsburg and Stuttgart OEMs pilot these configurations for line-flexibility gains.
- Remote Operated:Tethered or wireless control extends reach into hazardous environments. Nuclear decommissioning and chemical tank maintenance drive niche specification.
Installed base concentration rests with manual systems. Robotic configurations are climbing the fastest as automotive OEMs prioritize capital equipment utilization rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates most visibly in Germany's precision engineering corridor and China's expanding automotive component sector, with regulatory pressure in both markets accelerating substitution away from chemical and abrasive methods.
United States
EPA National Emission Standards for Hazardous Air Pollutants are tightening controls on abrasive blasting particulate matter across Michigan and Ohio structural steel fabricators. Metal fabrication facilities face compliance deadlines that elevate laser alternatives above traditional methods. Detroit-area automotive stamping plants now pilot portable units for die maintenance and weld preparation.
Germany
REACH substance restrictions on chlorinated solvents and hexavalent chromium processes force metal finishers toward dry ablation technologies. ECHA regulatory pressure eliminates hazardous waste reporting liabilities for adopters. Hamburg and Frankfurt MRO facilities lead hangar retrofit programs for turbine blade restoration protocols.
China
NEV battery tray manufacturers in Shenzhen and Ningbo deploy pulsed fiber systems for aluminum oxide removal prior to welding. The country's dual carbon goals redirect surface-treatment spending toward processes that eliminate solvent disposal. Automotive supplier networks in the Yangtze River Delta specify mid-power systems for production line integration.
Italy
Heritage conservation studios in Florence and Rome remain reliant on micro-abrasive methods for marble restoration, creating white space for low-fluence laser systems. ANSM oversight of cultural heritage interventions shapes equipment certification requirements. Monument conservation agencies in Lazio evaluate portable units with integrated debris extraction for cathedral façade maintenance.
South Korea
Semiconductor fabrication facilities utilize excimer and CO2 variants for photoresist stripping applications. MFDS alignment with international safety standards accelerates adoption in precision manufacturing. Busan shipyards phase in portable units for dockside hull maintenance under tightening maritime environmental regulations.
Portable Laser Cleaning Machine Market Competitive Landscape
Strategic partnerships dominate the current landscape as fiber laser source suppliers anchor downstream machine partnerships to secure volume commitments. The vendor base stratifies between photonics specialists with captive component production and system integrators sourcing from open catalogs. Three archetypes define positioning: vertically integrated source-to-system manufacturers, regional fabrication specialists, and application-focused solution providers. Technology licensing and geographic expansion represent the dominant competitive vectors as players seek to decouple from single-source dependencies.
Within the integrated photonics tier, IPG Photonics exemplifies source-to-system vertical control, while Trumpf occupies a position bridging industrial laser platforms with portable configurations. Among Asia-Pacific fabricators, Han's Laser and Senfeng represent scale-driven manufacturing archetypes. CleanLASER anchors the European specialist segment.
| Leading Market Players |
|---|
| CleanLASER |
| IPG Photonics |
| Han's Laser |
| Trumpf |
| Laserax |
| MaxWave |
| Cleantech |
| Raymond Laser |
| Senfeng |
| Others |
Pricing and Supply Chain Analysis
Power-tier bifurcation between robotic-integrated MOPA systems and handheld continuous-wave units manifests in both margin structures and component sourcing strategies, with German and Chinese buyers facing divergent total-cost-of-ownership calculations under REACH and dual carbon compliance pressures.
Pricing Analysis
Volume-margins split sharply between mid-power fiber platforms serving China's automotive supplier networks and premium robotic configurations for German aerospace MRO facilities. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—FAA/EASA repair station approvals command substantial premiums over CE-marked job shop units. Cost compression in standard-tier handheld systems is intensifying because diode laser source commoditization erodes hardware differentiation. Small-scale independent restoration contractors exhibit highest price sensitivity, while German automotive OEMs prioritize performance-guaranteed service contracts that transfer capital risk to vendors.
Supply Chain Analysis
Refurbishment flows for ytterbium-doped fiber gain modules and pump diode assemblies are emerging as critical margin recovery mechanisms for North American and European system integrators. Component manufacturing concentrates in Germany, the United States, and China, with high-power single-mode pump diodes drawing from specialty photonics suppliers in Bavaria and California. Supply chain vulnerability centers on single-source dependencies for ytterbium-doped gain fibers during demand surges. Distribution runs through direct OEM sales for robotic configurations and regional fabrication specialists for portable handheld units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as fiber laser source suppliers capture downstream machine partnerships to secure volume commitments, while system integrators pursue backward integration into diode and fiber production to escape input bottlenecks.
For Market Incumbents: Deepen captive production of ytterbium-doped gain fibers and high-power pump diodes to insulate margins from German and American specialty photonics supply constraints. Anchor downstream partnerships with Shenzhen NEV battery tray manufacturers through performance-guaranteed service contracts that lock out emerging Chinese fabricators. Certification investment in FAA and EASA repair station approvals preserves premium positioning against mid-power commoditization threats. For New Entrants and Emerging Players: The mid-tier price-point gap between IPG Photonics premium robotic systems and economy diode handhelds offers entry space for MOPA fiber platforms with integrated LIBS spectroscopy. Italian marble restoration studios and French monument conservation agencies represent the most penetrable vertical, with ANSM certification pathways creating defendable positioning against established industrial laser vendors. Heritage-focused rental service models bypass capital intensity barriers that constrain direct purchase adoption. For Investors and Strategic Acquirers: Re-rating potential sits with application-focused solution providers given CSRD-aligned capital expenditure programs subsidizing dry process transitions across European manufacturing. Long-term viability hinges on robotic integration readiness and collaborative arm compatibility rather than standalone handheld volume. Monitor ECHA substance restriction expansion timelines and EPA National Emission Standards enforcement intensity as inflection indicators for substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Laser Sources | Captive ytterbium-doped fiber production eliminates German and American specialty photonics bottlenecks during demand surges. |
| Performance-Guaranteed Service Contract Rollout | Per-square-meter pricing transfers capital risk to vendors while penetrating Bavarian automotive supplier networks. |
| LIBS Spectroscopy Platform Integration | Real-time substrate identification compresses Stuttgart paint shop process development cycles from weeks to hours. |
| Collaborative Robot Arm Certification | Force-torque sensing compatibility enables Wolfsburg OEMs to redeploy units across stamping, paint, and assembly lines. |
| Heritage Conservation Application Development | Low-fluence solid-state systems with debris extraction target ANSM-certified Italian marble restoration studios. |
Research Methodology
Independent corroboration across maintenance directors at German MRO facilities, procurement leads at Chinese NEV battery tray manufacturers, and aftermarket service heads at Japanese precision component makers underwrites the qualitative findings. Primary fieldwork with plant engineers in Michigan structural steel fabrication and technical R&D directors at European photonics suppliers combined with secondary validation from EPA enforcement databases, ECHA restriction timelines, and SEC filings of listed laser system vendors. Bottom-up unit shipment estimates triangulated against top-down capital expenditure tracking across automotive and aerospace verticals.
Comparable-period anchoring to historical fiber laser adoption curves in industrial cutting and welding informed the projection horizon trajectory. The analytical framework modeled segmentation across power source architecture, automation readiness tier, and end-use severity classification throughout the forecast period. CAGRs derived from installed base replacement cycles, regulatory compliance deadline clustering, and robotic integration adoption curves. Industry-specific inputs incorporated REACH substance restriction phase-out schedules and dual carbon policy implementation intensity across Chinese provincial manufacturing clusters.
Inputs from ECHA regulatory filings and EPA National Emission Standards enforcement records were available through the study window; gaps in real-time Chinese provincial subsidy disbursement data introduce uncertainty bands around NEV supplier adoption timelines. Forecasts reflect assumptions on MOPA fiber laser cost reduction trajectories and collaborative robot arm price elasticity. Practitioners should monitor ECHA restriction expansion announcements, EPA hazardous air pollutant enforcement actions, and Chinese MIIT equipment subsidy qualification changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Cryostat Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
Electron Beam Welding Systems Market
Industrial Equipment
Ultrasonic Atomizer Market
Industrial Equipment
Global Electro Hydraulic Servo Valve Market
Industrial Equipment
Fiber Laser Coding System Market
Industrial Equipment
Photography Panoramic Tripod Heads Market
Industrial Equipment
Global Industrial Centrifuges Market
Industrial Equipment
Global Safety Relays and Timers Market
Industrial Equipment
Linear Motion (LM) Shaft Market
Industrial Equipment
Mounted Bearing Market
Industrial Equipment
Air Filters Market
Industrial Equipment
Spherical Roller Bearings Market
Industrial Equipment
Microwave Equipment Market
Industrial Equipment
Precision Dispensing Accessories Market
Industrial Equipment
Semiconductor Cartridge Heaters Market