
 Spot Curing System Market | 2026-2036
Spot Curing System Market Size, Share, and Industry Trends Forecast 2026-2036
Spot Curing System Market Analytics
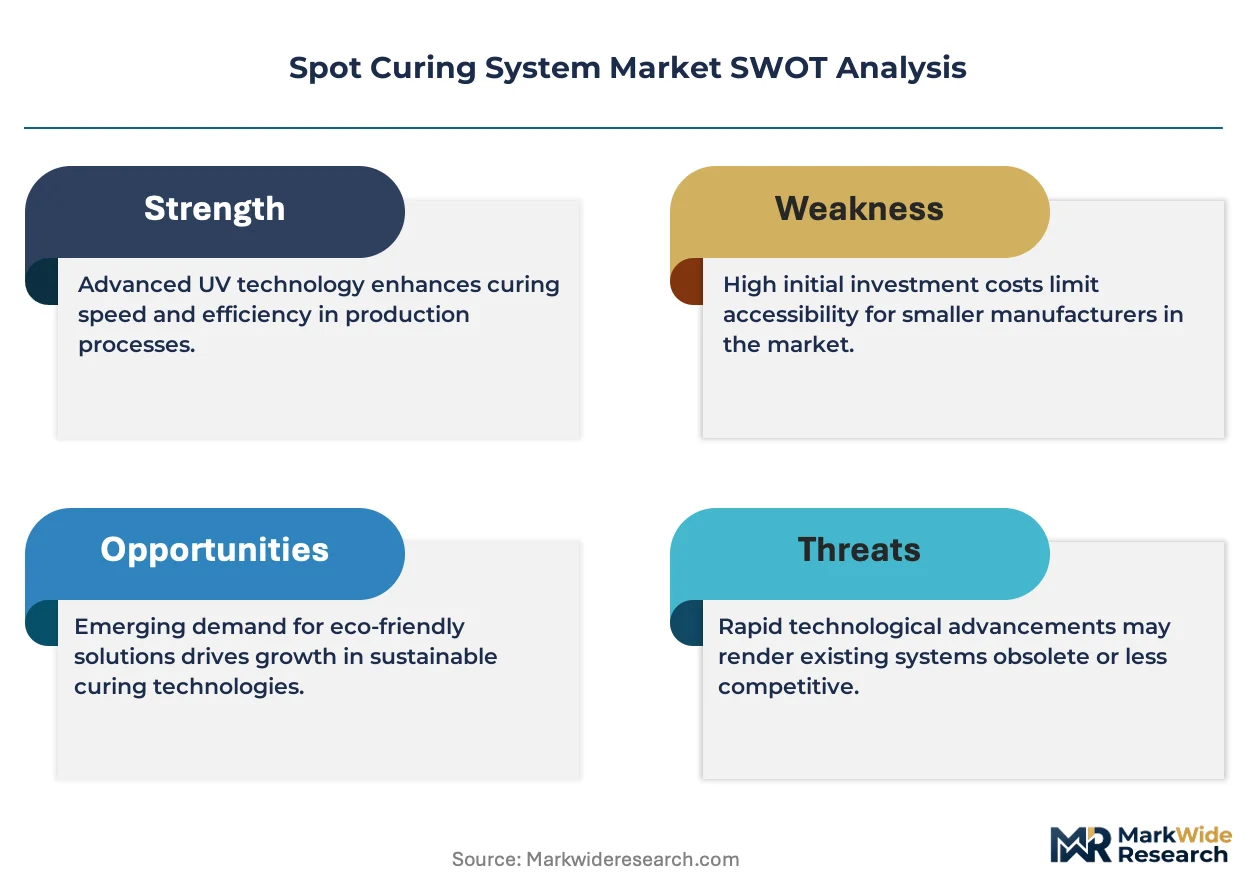
ISO 9001 quality management certification is reorganizing supplier qualification across the spot curing system value chain. Nordson Corporation leverages its fluid dispensing heritage to control channel access for integrated curing solutions. Dymax Corporation specializes in light-curable adhesives, anchoring its position in medical device assembly workflows. Excelitas Technologies Corp. competes through photonic component depth, sustaining R&D intensity in LED engine design.
A spot curing system delivers localized, high-intensity energy to polymerize adhesives, coatings, or inks in seconds, typically operating at wavelengths of 365 nm to 405 nm for UV-LED variants or broadband mercury-arc spectra for conventional UV systems. The equipment serves precision manufacturing where full-area curing risks thermal damage to sensitive substrates. LED-curing technology leads product type segmentation due to mercury-ban pressures and energy efficiency mandates, while UV Systems retain margin pools in legacy automotive paint lines. Electronics Assembly anchors application demand as miniaturization forces tighter bond-line control in smartphone and semiconductor packaging workflows.
REACH restrictions on mercury-containing lamps and RoHS substance limits are accelerating LED conversion timelines across European manufacturing bases. EPA air quality standards and OSHA permissible exposure limits for ultraviolet radiation shape equipment design specifications and operator safety protocols in US facilities. FDA device manufacturing regulations enforce process validation requirements that elevate spot curing system documentation burdens in medical device contract manufacturing. Stakeholders must weigh wavelength specificity against capital retrofit costs as regulatory phase-outs harden.
Market Dynamics
LED-curing technology is compressing equipment replacement cycles as mercury-arc lamp bans harden across industrialized manufacturing corridors. REACH substance restrictions and energy efficiency mandates are forcing capital reallocation toward solid-state photonic engines in precision assembly workflows.
Growth Catalysts
- RoHS substance limits:Electronics manufacturers in Germany and South Korea are retiring mercury-vapor systems ahead of compliance deadlines, creating equipment refresh demand in semiconductor packaging lines.
- Miniaturization imperatives:Smartphone and wearable device assembly requires bond-line control below 50 microns, pulling high-precision spot curing into microelectronics workflows.
- East Asian electronics clusters:Contract manufacturers in Shenzhen and Ho Chi Minh City are scaling UV-curing adoption for camera module and display bonding operations.
Market Restraints
- LED engine cost premiums:Solid-state UV sources command 40-60% capital premiums over legacy mercury systems, extending payback periods for mid-volume producers.
- German optics supply concentration:High-performance LED collimation lenses and reflector assemblies concentrate among specialized photonics suppliers in Baden-Württemberg.
- Wavelength specificity limitations:Narrow-band LED emission (365 nm or 395 nm peak) fails to activate certain photoinitiator chemistries optimized for broadband mercury spectra.
Strategic Opportunities
- India medical device manufacturing:CDSCO quality mandates and production-linked incentive schemes are attracting contract manufacturers requiring validated curing processes for catheter and diagnostic device assembly.
- Hybrid curing architectures:Convergence of UV-LED and thermal snap-cure modules enables processing of temperature-sensitive substrates in automotive sensor packaging.
- Service-unbundled revenue models:Equipment vendors are separating hardware sales from photonic engine subscription programs, penetrating capital-constrained small-batch producers.
Industry Challenges
- Process validation documentation:FDA 21 CFR Part 820 and EU MDR requirements impose extensive IQ/OQ/PQ protocol burdens on medical device contract manufacturers.
- Photonics integration expertise:Shortage of engineers combining optical system design with adhesive chemistry knowledge constrains OEM internal development teams.
- Legacy system interoperability:Retrofitting LED engines into existing conveyor and robotic cell architectures requires custom mechanical and control interface engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spot Curing System Market |
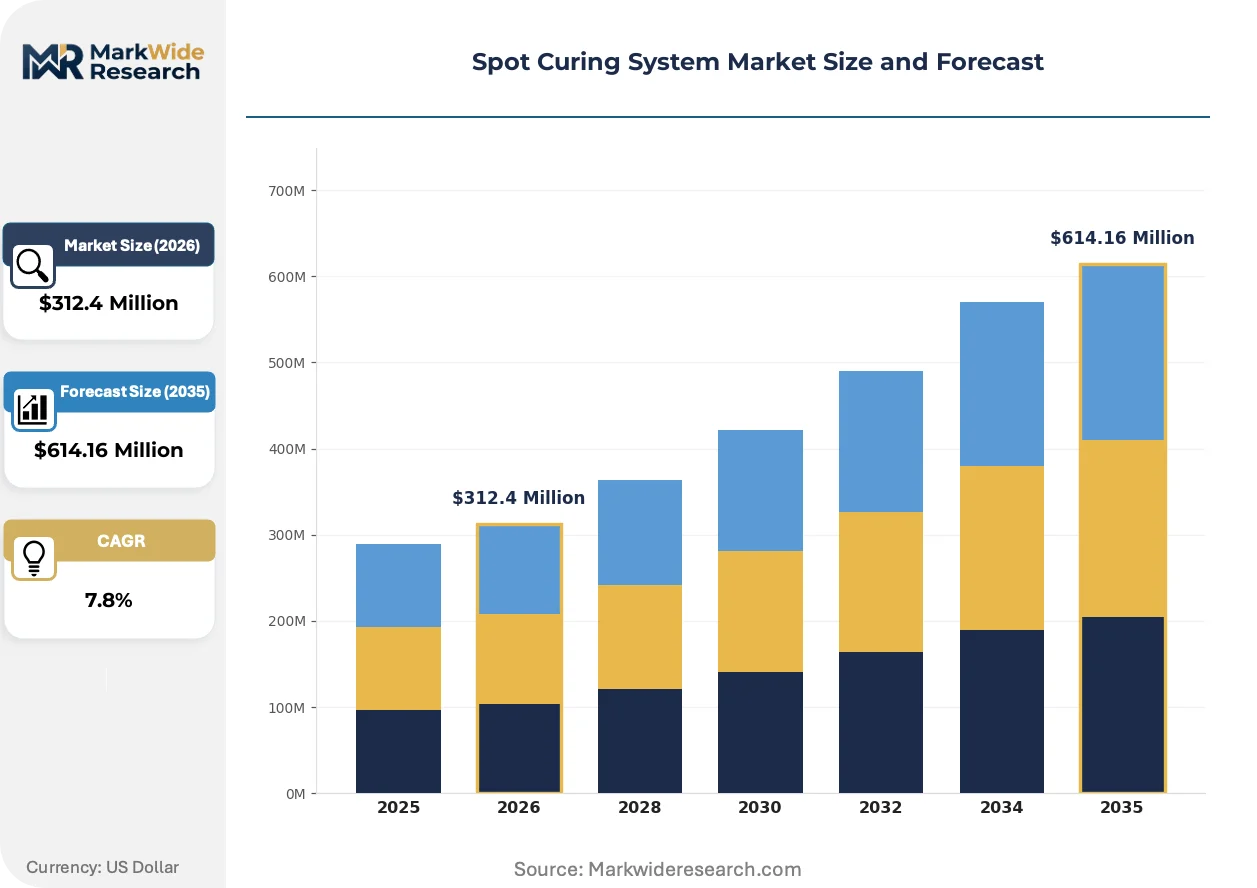
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $614.16 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Systems, UV Systems, Thermal Systems, Hybrid Systems Application: Automotive Manufacturing, Electronics Assembly, Medical Devices, Optical Coatings End User: Manufacturers, Research Institutions, Contract Manufacturers, Repair Shops Technology: UV-Curing, Electron-Beam Curing, LED-Curing, Infrared Curing |
| Companies Covered | Excelitas Technologies Corp., Nordson Corporation, Dymax Corporation, IST METZ GmbH, Phoseon Technology, American Ultraviolet, Heraeus Noblelight GmbH, Dr. Hönle AG, Baldwin Technology Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spot Curing System Market Evolving Landscape
Photonic engine architectures are fragmenting into application-specific wavelength configurations as process engineers demand tighter spectral control. Equipment vendors are reconfiguring R&D roadmaps around solid-state light source modularity.
UV-LED spot curing systems are miniaturizing into palm-sized form factors for robotic end-effector integration. Smartphone camera module manufacturers in Japan and Taiwan are adopting these compact units for in-line bond-line processing. The footprint compression is enabling multi-head arrays that cure multiple joints simultaneously without thermal damage to adjacent CMOS sensors.
REACH Annex XVII mercury restrictions are eliminating broadband UV lamp options for new equipment placements across EU manufacturing bases. Automotive paint shops in Stuttgart and Wolfsburg face forced LED conversion timelines despite incomplete photoinitiator reformulation for body-in-white coatings. Tier-1 suppliers are pressuring adhesive vendors to accelerate 395 nm-optimized chemistry development.
Medical device assemblers are consolidating supplier relationships around vertically integrated curing-adhesive combinations. Contract manufacturers in Massachusetts and Minnesota now specify bonded validation packages rather than discrete equipment procurement. The bundled model reduces qualification burden but locks buyers into single-source adhesive-curing system pairings for multi-year contract horizons.
Spot Curing System Market Segmentation
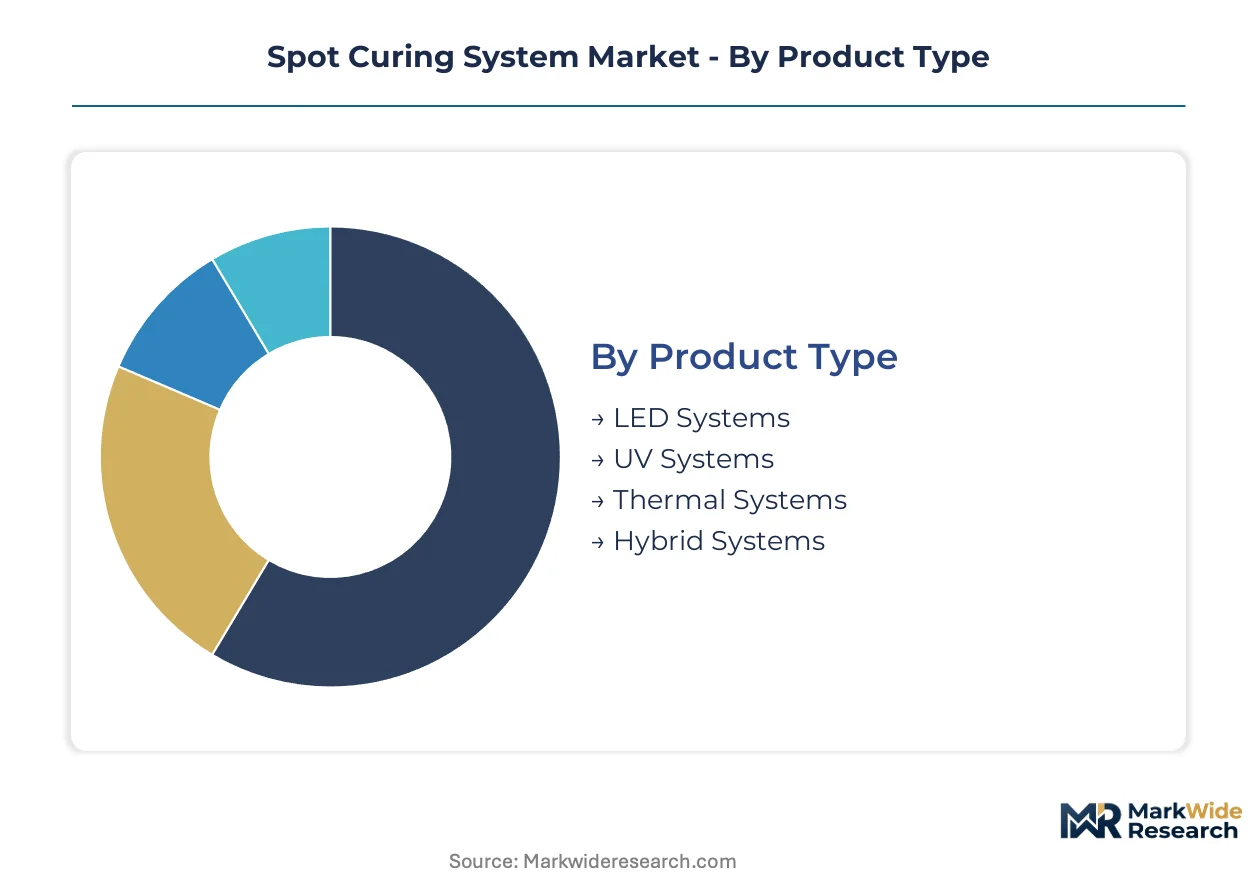
Segmentation in spot curing systems separates equipment procurement patterns by photonic source maturity, assembly precision requirements, and regulatory validation burdens. Buyers optimize capital allocation across wavelength technologies and integration architectures based on substrate sensitivity and throughput targets.
Product Type:
Margin pools concentrate in solid-state photonic engines where mercury-ban compliance creates replacement premiums and energy efficiency mandates sustain pricing power.
- LED Systems:Solid-state UV sources operating at 365 nm or 395 nm peak wavelength deliver instant on-off capability and 50,000+ hour operational life. Demand concentrates in Germany's automotive component belt where REACH Annex XVII mercury restrictions force equipment refresh in paint and adhesive lines.
- UV Systems:Broadband mercury-arc lamps emit 200-450 nm spectra activating legacy photoinitiator chemistries. Retained margin pools persist in legacy automotive paint lines where incomplete 395 nm chemistry reformulation delays LED conversion timelines.
- Thermal Systems:Infrared and conductive heating modules for temperature-tolerant substrates in heavy industrial bonding.
- Hybrid Systems:Converged UV-LED and thermal snap-cure architectures processing temperature-sensitive automotive sensor packages.
UV Systems holds installed capacity. LED Systems is rotating up the share rankings.
Application:
Volume concentration tracks electronics miniaturization imperatives where bond-line control below 50 microns pulls precision curing into smartphone and semiconductor workflows.
- Electronics Assembly:Camera module bonding, display lamination, and semiconductor packaging require sub-micron positional accuracy. Shenzhen and Ho Chi Minh City contract manufacturers are scaling adoption for wearable device microassembly.
- Automotive Manufacturing:Sensor encapsulation, headlamp sealing, and interior trim bonding demand thermal management in high-throughput lines. Stuttgart and Wolfsburg paint shops face forced LED conversion despite photoinitiator gaps.
- Medical Devices:Catheter assembly and diagnostic device bonding require FDA 21 CFR Part 820 process validation with extensive IQ/OQ/PQ documentation.
- Optical Coatings:Lens hardcoating and anti-reflective layer curing for precision optics manufacturers.
Electronics Assembly dominates unit shipments. Medical Devices is climbing the fastest on validation-bundled procurement models.
End User:
Customer type determines specification intensity, with validated manufacturers commanding premium pricing against price-sensitive repair channels.
- Contract Manufacturers:EMS providers in East Asia and Mexico consolidate supplier relationships around vertically integrated curing-adhesive validation packages, locking multi-year contract horizons.
- Manufacturers:OEM captive assembly lines specify discrete equipment procurement with internal process development.
- Research Institutions:Universities and national labs piloting next-generation photonic chemistries and substrate combinations.
- Repair Shops:Low-volume aftermarket operators prioritizing capital cost over spectral precision or energy efficiency.
Manufacturers retain legacy installed base. Contract Manufacturers is expanding most quickly on bundled validation demand.
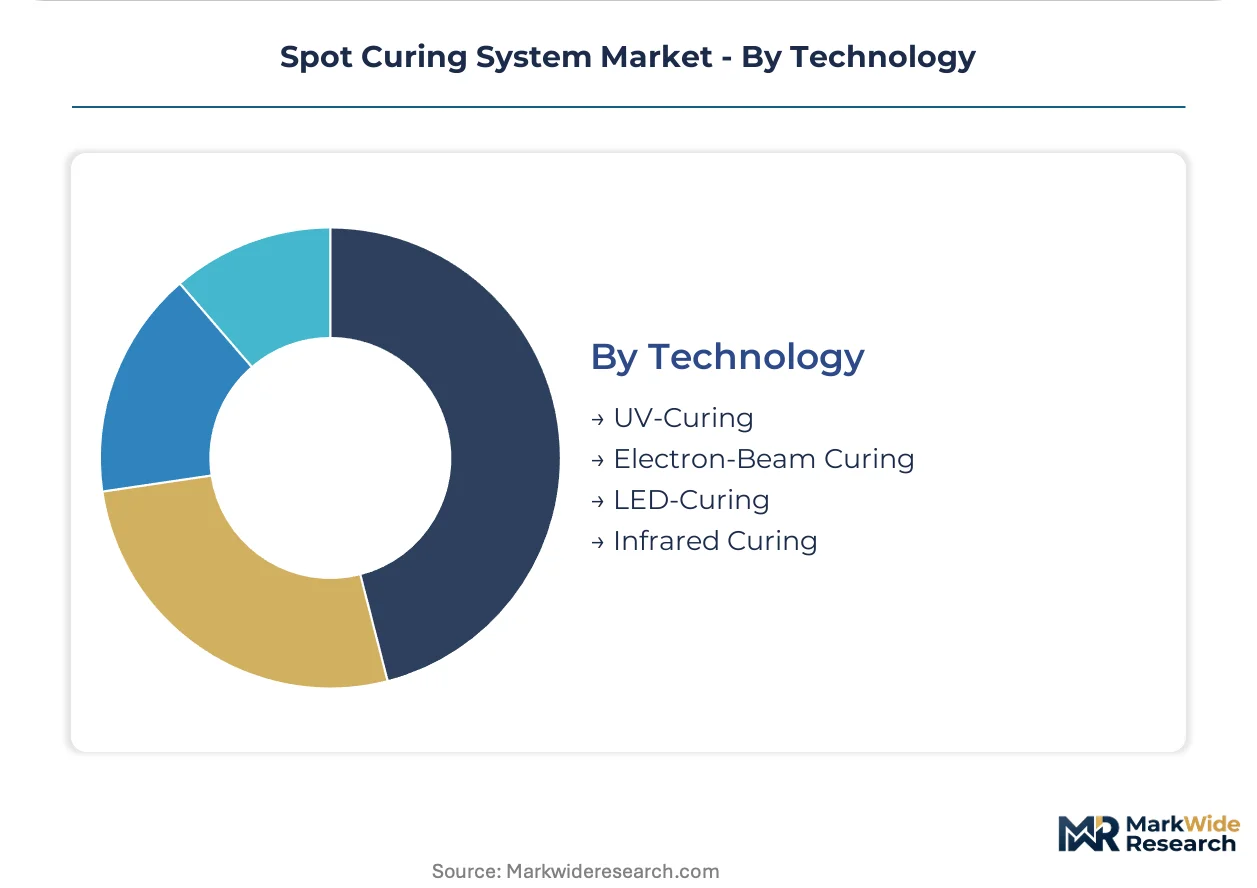
Technology:
Technology selection hinges on photoinitiator chemistry compatibility and substrate thermal tolerance, with solid-state sources displacing legacy arc lamps.
- LED-Curing:Narrow-band emission at discrete wavelengths enables precise energy dosing without infrared bleed. Japan and Taiwan smartphone camera module manufacturers adopt palm-sized robotic end-effector units for in-line processing.
- UV-Curing:Broadband mercury spectra retain activation breadth for legacy adhesive formulations pending chemistry reformulation.
- Electron-Beam Curing:High-energy electron penetration curing thick coatings without photoinitiator dependence for specialized industrial applications.
- Infrared Curing:Thermal radiation sources for opaque substrates and moisture-cure hybrid systems.
UV-Curing maintains legacy chemistry compatibility. LED-Curing is gaining share fastest on regulatory phase-out timelines and energy efficiency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes and REACH Annex XVII mercury restrictions are redirecting capital toward LED-curing infrastructure across precision manufacturing corridors. National regulators enforce divergent phase-out timelines that fragment equipment procurement cycles. Industrial clusters in Germany, China, the United States, Japan, and South Korea concentrate demand validation and chemistry co-development.
Germany
Automotive sensor packaging and paint shop operations drive equipment refresh demand as REACH mercury bans eliminate broadband UV lamp options. ECHA substance restrictions force Tier-1 suppliers in Stuttgart and Wolfsburg to accelerate 395 nm photoinitiator reformulation. Baden-Württemberg optics suppliers control high-performance LED collimation lens production for precision assembly workflows.
China
Shenzhen contract manufacturers scale UV-curing adoption for smartphone camera module bonding and display lamination operations. MIIT energy efficiency mandates and dual carbon goals compress LED conversion timelines in electronics assembly lines. Yangtze River Delta clusters in Suzhou and Shanghai pilot palm-sized robotic end-effector units for sub-50 micron bond-line control.
United States
FDA 21 CFR Part 820 process validation requirements elevate documentation burdens for catheter and diagnostic device assemblers in Massachusetts and Minnesota. EPA air quality standards shape equipment design specifications for ultraviolet radiation exposure protocols. OSHA permissible exposure limits enforce operator safety retrofits in legacy automotive paint facilities across Michigan and Ohio.
Japan
Smartphone camera module manufacturers in Tokyo and Nagoya adopt miniaturized UV-LED spot curing systems for in-line CMOS sensor processing. METI industrial efficiency programs subsidize solid-state photonic engine adoption in precision electronics workflows. Kansai region optical component suppliers specialize in multi-head array configurations for simultaneous joint curing without thermal damage.
South Korea
Semiconductor packaging lines in Suwon and Pyeongtaek retire mercury-vapor systems ahead of RoHS compliance deadlines, creating concentrated equipment replacement demand. MFDS quality mandates for medical device contract manufacturing attract validation-bundled procurement from domestic EMS providers. Seoul Capital Area clusters integrate LED-curing modules into automated robotic cells for wearable device microassembly.
Spot Curing System Market Competitive Landscape
Player mix skews toward diversified industrial equipment conglomerates with fluid handling or photonic component heritage. Market structure concentrates margin capture among three to five integrated solution providers controlling channel access and adhesive-chemistry validation partnerships. Strategic archetypes include photonic engine specialists, dispensing-integrated system houses, and vertically bundled adhesive-curing combination suppliers. Dominant competitive moves center on adhesive vendor co-validation agreements and LED engine subscription program unbundling.
Among North American equipment houses, Nordson Corporation and Dymax Corporation exemplify divergent specialization paths. Nordson leverages fluid dispensing heritage to anchor integrated curing-dispensing solution positioning. Dymax occupies the light-curable adhesive specialist tier, bundling chemistry validation with equipment specification to lock medical device contract manufacturing relationships. Excelitas Technologies Corp. represents the photonic component depth archetype, sustaining LED engine design intensity through captive semiconductor fabrication capabilities. IST METZ GmbH and Dr. Hönle AG sit within the German optics-industrial equipment nexus, reflecting Baden-Württemberg and Bavaria regional supply chain concentration.
| Leading Market Players |
|---|
| Excelitas Technologies Corp. |
| Nordson Corporation |
| Dymax Corporation |
| IST METZ GmbH |
| Phoseon Technology |
| American Ultraviolet |
| Heraeus Noblelight GmbH |
| Dr. Hönle AG |
| Baldwin Technology Co. |
| Others |
Value Network & Pricing Analysis
Ninety-day lead times for high-performance LED collimation lenses from Baden-Württemberg suppliers concentrate pricing power among German optics houses, forcing equipment vendors to absorb cost volatility or pass through premiums to medical device contract manufacturers locked in multi-year validation contracts.
Pricing Analysis
Certification level creates the primary spread between ISO 9001-validated systems and standard industrial equipment. Pricing stratifies across FDA-grade, CE-marked, and uncertified economy tiers based on documentation burden and process validation support. Cost compression in mid-volume equipment segments is intensifying because contract manufacturers in Shenzhen and Ho Chi Minh City consolidate procurement around bundled adhesive-curing validation packages. Repair shops remain most price-sensitive, prioritizing capital cost over spectral precision or energy efficiency.
Supply Chain Analysis
Inventory buffers for mercury-arc lamp components have collapsed as REACH Annex XVII phase-outs accelerate, exposing equipment vendors to single-source vulnerability for specialized reflector assemblies. German, Japanese, and Chinese suppliers dominate photonic engine production, with Baden-Württemberg controlling precision optics and Yangtze River Delta clusters feeding LED die fabrication. Distribution runs through direct OEM relationships for high-specification medical and automotive lines, while aftermarket channels serve price-sensitive repair operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward East Asian contract manufacturers as EMS consolidation in Shenzhen and Ho Chi Minh City concentrates procurement volume among fewer validation-demanding customers.
For Market Incumbents: Compound adhesive-chemistry validation partnerships to lock medical device contract manufacturing relationships against emerging photonic engine specialists. Deepen captive supply of LED collimation optics from Baden-Württemberg suppliers to defend margin position against Tier-1 automotive customers accelerating 395 nm chemistry reformulation timelines. For New Entrants and Emerging Players: FDA 510(k) fast-track certification for catheter assembly applications opens white-space penetration in Massachusetts and Minnesota medical device clusters. Target India's CDSCO-mandated medical device manufacturing expansion under production-linked incentive schemes with validation-bundled equipment-adhesive packages. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized photonic component divisions. Long-term viability hinges on solid-state engine subscription revenue models displacing transactional hardware sales. Watch for LED engine cost parity with mercury systems as the inflection signal for accelerated replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Adhesive-Chemistry Co-Validation Partnership | Locks multi-year procurement relationships with FDA-regulated medical device contract manufacturers. |
| LED Engine Subscription Unbundling | Penetrates capital-constrained small-batch producers in Ho Chi Minh City electronics clusters. |
| Baden-Württemberg Optics Supply Control | Secures captive access to high-performance collimation lenses for precision assembly workflows. |
| Hybrid Curing Architecture Development | Enables processing of temperature-sensitive automotive sensor packages in Stuttgart manufacturing lines. |
| India CDSCO Validation Package Entry | Captures production-linked incentive demand from catheter and diagnostic device contract manufacturers. |
Research Methodology
Desk research of trade customs data, ECHA regulatory filings, and SEC equipment vendor disclosures preceded structured interviews with plant engineers at automotive Tier-1 suppliers, procurement leads at East Asian EMS providers, biomedical engineers at medical device contract manufacturers, and aftermarket service heads. Primary fieldwork combined with secondary validation across patent databases and photonics industry association reports. Bottom-up equipment shipment estimates triangulated against top-down adhesive consumption models.
Variance decomposition separates volume growth from pricing and mix effects across the projection horizon. Segmentation dimensions modeled include photonic source type, application precision requirement, regulatory validation burden, and regional manufacturing cluster. CAGRs derive from equipment replacement cycle compression and chemistry reformulation timelines. Forecast inputs incorporate REACH Annex XVII mercury ban phase-out schedules and MIIT energy efficiency mandate compliance deadlines.
Decision-makers should treat outputs as directional under assumptions of sustained LED engine cost reduction and stable photoinitiator chemistry reformulation progress; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
North America Industrial Centrifuge Market
Industrial Equipment
Fiber Laser Coding System Market
Industrial Equipment
North America Fans and Blowers Market
Industrial Equipment
Japan Ceramic Roller Bearings Market
Industrial Equipment
Magnetic Chip Conveyors Market
Industrial Equipment
Sterile Tubing Welder Market
Industrial Equipment
Middle East and Africa Industrial Centrifuge Market
Industrial Equipment
Laser Marking Machine Market
Industrial Equipment
Industrial Monitor Market
Industrial Equipment
Cash Sorting Machines Market
Industrial Equipment
CNC Tool Storage System Market
Industrial Equipment
Seismic Data Acquisition Equipment Market
Industrial Equipment
Industrial Joysticks Market
Industrial Equipment
Global High Power Laser Systems Market
Industrial Equipment
Global Cold Plate Market
Industrial Equipment
Fluid Dispensing Equipment Market