
 Global Servo Motor Market | 2026-2036
Global Servo Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Servo Motor Market Outlook
Aftermarket service revenue is reconfiguring profit pools away from unit sales across the servo motor supply chain. Yaskawa Electric Corporation leverages its Japan-based manufacturing scale to dominate replacement parts logistics. Siemens AG anchors European demand through its integrated drive-train service contracts. Bosch Rexroth AG specializes in hydraulic-to-electric conversion programs that extend machine life cycles.
A servo motor is a rotary actuator that uses closed-loop feedback control to achieve precise angular position, velocity, and torque output, typically employing rare-earth permanent magnets and resolver or encoder feedback devices rated for IP65 environmental protection. Its primary commercial purpose is to deliver sub-millimeter positioning accuracy in automated machinery where stepper motors lack dynamic response. AC servo motors command the largest installed base across CNC machines and industrial robotics due to superior power density and regenerative braking capability. Linear servo motors are gaining share in semiconductor wafer handling and flat-panel display manufacturing where direct-drive elimination of mechanical transmission improves throughput and reduces maintenance intervals. Integrated servo motors that embed drives and controllers into the motor housing are reshaping conveyor system architectures by collapsing cabinet space requirements and shortening commissioning times.
The EU F-Gas Regulation and REACH compliance frameworks are restricting fluorinated greenhouse gas use in motor cooling systems while mandating material traceability for rare-earth supply chains. The US Department of Energy's motor efficiency standards under EPICA are pushing OEMs toward IE4 and IE5 efficiency classes that require advanced servo control algorithms. China's GB 18613 motor efficiency standards and dual carbon goals are accelerating domestic replacement of induction motors with servo systems in high-precision applications. Stakeholders must monitor how regional efficiency mandates diverge on test methods and certification requirements, as this fragmentation will determine which product architectures achieve cross-border scale.
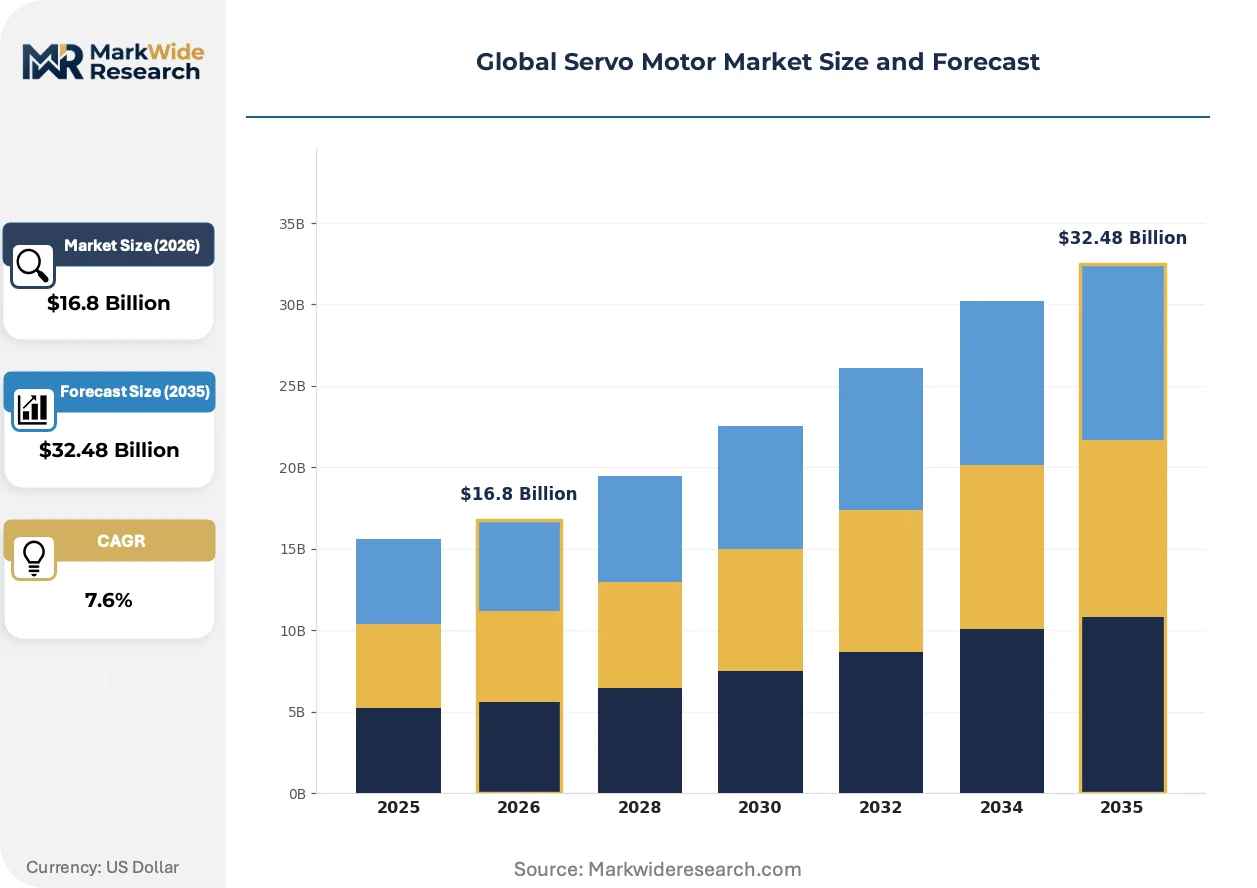
Market Dynamics
Aftermarket service revenue is reconfiguring profit pools away from unit sales across the servo motor supply chain, with integrated drive-train contracts and predictive maintenance subscriptions displacing transactional hardware margins.
Growth Catalysts
- EU Green Deal energy-efficiency mandates:Germany's precision manufacturing corridor is accelerating permanent magnet motor adoption to meet IE4 and IE5 efficiency thresholds in automotive assembly automation.
- Rare-earth supply chain traceability requirements:REACH compliance frameworks are forcing OEMs to document NdFeB magnet provenance, creating captive sourcing advantages for vertically integrated producers.
- Semiconductor wafer handling automation:Linear servo motors are displacing ball-screw mechanisms in flat-panel display fabrication lines across South Korea and Taiwan.
Market Restraints
- Neodymium price volatility:Rare-earth oxide concentrate costs from Chinese separation facilities swing 30-40% annually, compressing permanent magnet motor margins.
- Resolver encoder supply concentration:High-precision optical encoders rely on Japanese component suppliers, creating single-source vulnerability for IP65-rated feedback systems.
- Induction motor residual stock:China's GB 18613 replacement cycles lag in low-precision material handling, delaying servo penetration in cost-sensitive conveyor applications.
Strategic Opportunities
- India's PLI scheme for industrial automation:Domestic manufacturing incentives are attracting servo system assembly for textile and packaging machinery in Gujarat and Tamil Nadu.
- Hydraulic-to-electric conversion programs:Press and injection molding retrofits in Germany's Ruhr industrial belt offer 15-20 year machine life extension revenue.
- Edge computing convergence with servo drives:Embedded controllers with real-time vibration analysis are collapsing cabinet space requirements in warehouse robotics.
Industry Challenges
- Motion control engineering talent scarcity:Tuning PID loops for high-dynamic response requires specialized expertise that vocational programs in the US and Europe have deprioritized.
- Multi-vendor integration complexity:EtherCAT, PROFINET, and CC-Link IE fieldbus incompatibilities extend commissioning timelines for mixed-automation environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Servo Motor Market |
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $32.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Servo Motors, DC Servo Motors, Integrated Servo Motors, Linear Servo Motors End User: Automotive, Aerospace, Robotics, Manufacturing Technology: Closed-loop Control, Open-loop Control, Synchronous, Stepper Application: Positioning Systems, CNC Machines, Industrial Automation, Conveyor Systems |
| Companies Covered | Yaskawa Electric Corporation, Siemens AG, Mitsubishi Electric Corporation, ABB Ltd., Rockwell Automation, Inc., FANUC Corporation, Delta Electronics, Inc., Schneider Electric SE, Bosch Rexroth AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Servo Motor Market Strategic Shifts
Digital twin architectures are compressing commissioning cycles and enabling predictive failure modeling before physical installation, shifting competitive advantage toward software-integrated hardware platforms.
AI-driven auto-tuning algorithms are digitizing servo parameter optimization that previously required manual commissioning by specialized field engineers. Automotive battery assembly lines in Hungary and Poland are deploying these self-configuring drives to accommodate frequent product changeovers. The technology is digitizing the traditional service revenue model by collapsing on-site calibration visits into cloud-based remote diagnostics.
The US Department of Energy's motor efficiency standards under EPICA are mandating IE4 minimums for motors above 0.75 kW from 2027. OEMs are responding by embedding advanced flux-weakening algorithms that extend constant-power speed ranges without magnet grade upgrades. The regulation most acutely affects material handling integrators serving California and New York state markets where utility rebate programs stack with federal mandates.
Buying organizations are unbundling after-sales service from initial hardware procurement, forcing suppliers to compete on transparent hourly rates and guaranteed uptime contracts rather than bundled maintenance packages. German automotive tier-1 suppliers are piloting this model for body-in-white welding lines, with Siemens and Bosch Rexroth establishing standalone service entities. The shift is most visible in Bavaria's automotive supplier cluster where total cost of ownership metrics dominate capital allocation committees.
Global Servo Motor Market Segmentation
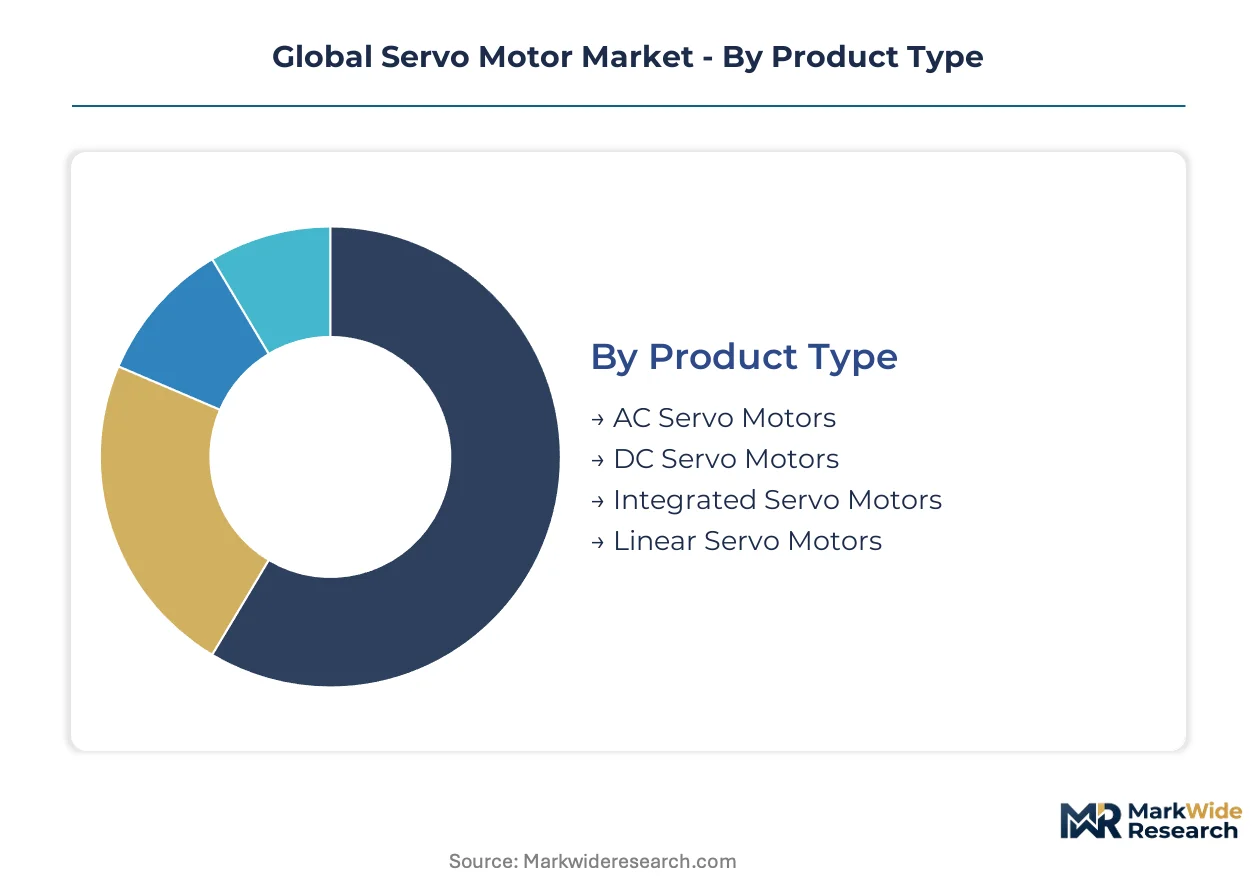
Servo motor architectures diverge sharply across precision requirements, power density needs, and integration complexity. Each segmentation axis reveals distinct procurement patterns and margin structures that suppliers must navigate.
Product Type:
The use-case spectrum spans from high-inertia metal cutting to cleanroom semiconductor handling, with motor topology determining achievable acceleration and thermal performance.
- AC Servo Motors:Three-phase permanent magnet synchronous machines with resolver or encoder feedback achieve IE4 efficiency ratings through field-oriented control algorithms. Demand concentrates in Germany's automotive stamping lines where regenerative braking recovers energy from high-inertia press cycles.
- Linear Servo Motors:Direct-drive electromagnetic thrust modules eliminate ball-screw backlash for sub-micron positioning accuracy. South Korean flat-panel display fabs in Gyeonggi Province are displacing mechanical transmissions to improve wafer-handling throughput.
- DC Servo Motors:Brushed or brushless designs with analog tachometer feedback persist in legacy retrofit applications.
- Integrated Servo Motors:Drive electronics embedded within the motor housing collapse control cabinet footprints for warehouse robotics.
The dominant share belongs to AC Servo Motors, while Linear Servo Motors are closing the gap fastest.
End User:
Cost tier differentiation separates capital-intensive precision manufacturing from price-sensitive material handling.
- Automotive:Body-in-white welding robots and battery assembly lines demand IP65-rated motors with SIL3 functional safety certification. Hungary's supplier parks near Győr are expanding servo procurement for electric vehicle platform flexibility.
- Robotics:Collaborative robot joints require high torque density with force-limiting control modes. Collaborative arm manufacturers in Denmark and Japan are specifying frameless torque motors for compact six-axis designs.
- Aerospace:Flight control surface actuation and fuel valve positioning require DO-178C software certification and extended temperature ranges.
- Manufacturing:General automation spans packaging machinery, textile looms, and food processing equipment with varying precision needs.
Automotive commands the largest procurement volumes, with Robotics expanding most quickly through collaborative automation adoption.
Technology:
Control architecture maturity determines commissioning complexity and maintenance protocol standardization.
- Closed-loop Control:Encoder or resolver feedback enables real-time position correction with <±0.01mm repeatability. CNC machine tool builders in Taiwan's Taichung Precision Machinery cluster specify dual-loop controls for thermal compensation.
- Synchronous:Permanent magnet rotor designs align with EU Green Deal efficiency mandates for IE4 and IE5 motor classes.
- Open-loop Control:Stepper-derived architectures without feedback devices persist in cost-constrained indexing applications.
- Stepper:Hybrid stepper motors with microstepping drives serve low-speed positioning where servo dynamics are unnecessary.
Closed-loop Control holds the installed base majority, though Synchronous designs are gaining share fastest through efficiency regulation compliance.
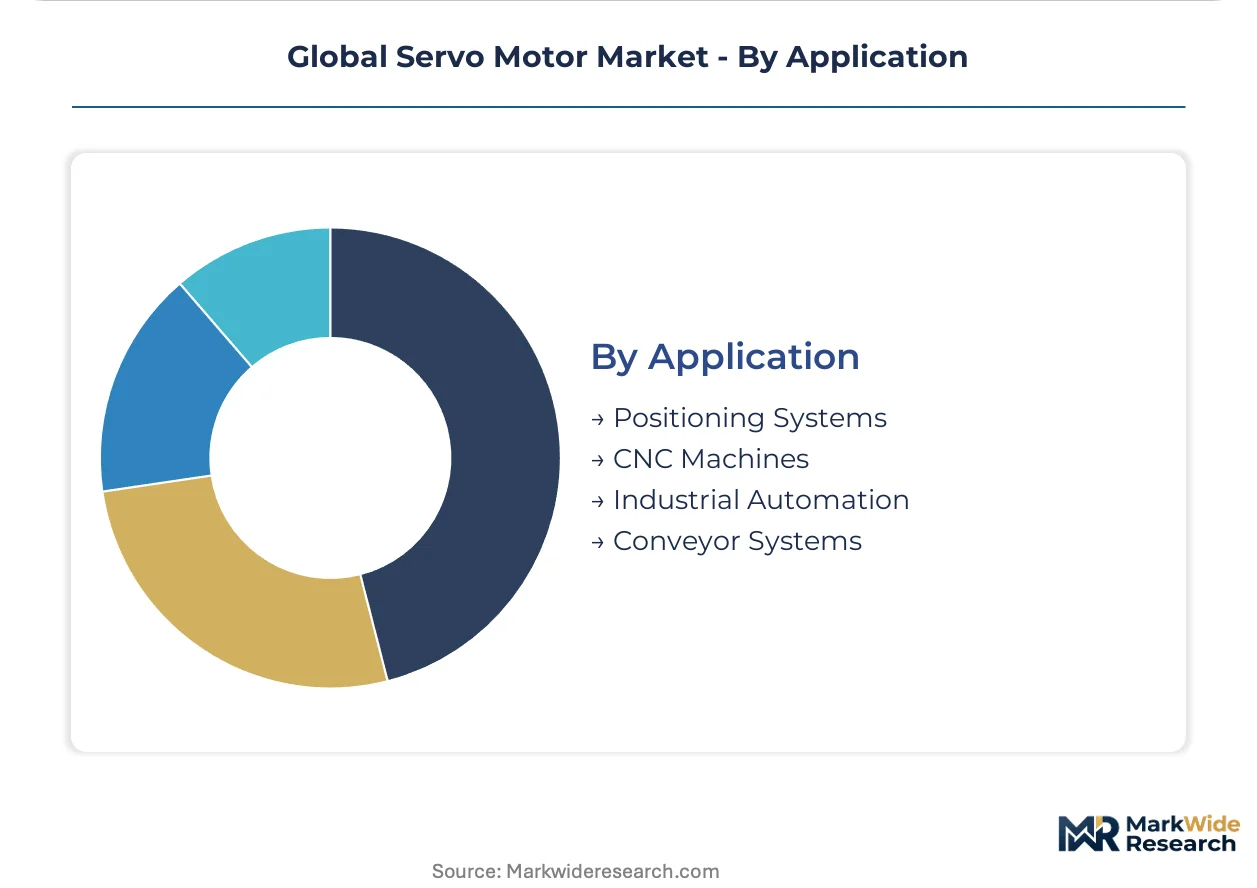
Application:
Volume concentration varies with machine replacement cycles and retrofit intensity across industrial verticals.
- CNC Machines:Multi-axis milling and turning centers require spindle and axis servos with wide constant-power speed ranges. Japanese machine tool OEMs in Nagoya prefecture are embedding flux-weakening algorithms to avoid rare-earth magnet upgrades.
- Industrial Automation:Pick-and-place, packaging, and assembly systems constitute the broadest deployment category.
- Positioning Systems:Semiconductor lithography and metrology stages demand nanometer-scale motion control with active vibration damping.
- Conveyor Systems:Belt and roller drive applications favor integrated servo motors for decentralized control architectures.
CNC Machines retain the highest per-unit value concentration, while Conveyor Systems are climbing the fastest through integrated motor-drive adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth magnet processing clusters in China and precision manufacturing hubs in Germany concentrate upstream supply capacity. Japanese encoder component suppliers anchor feedback device availability. South Korean flat-panel fabrication lines drive linear servo motor procurement intensity.
China
GB 18613 motor efficiency standards and dual carbon goals are accelerating induction-to-servo replacement in Yangtze River Delta machine tool factories. MIIT mandates IE4 minimums for industrial motors above 0.75 kW from 2024. Shenzhen and Suzhou clusters are embedding flux-weakening algorithms to reduce rare-earth magnet dependency in CNC spindle applications.
Germany
EU Green Deal IE4 and IE5 efficiency thresholds are forcing permanent magnet adoption in Bavarian automotive body-in-white welding lines. REACH compliance frameworks require NdFeB magnet provenance documentation across the supply chain. The Ruhr industrial belt is retrofitting hydraulic presses with electric servo systems under 15-20 year life extension contracts.
Japan
METI efficiency roadmaps and JIS standards are driving high-precision encoder integration in Nagoya prefecture machine tool builds. Resolver and optical feedback device suppliers concentrate in Aichi and Tokyo metropolitan manufacturing corridors. Collaborative robot joint motor demand from Osaka-based automation OEMs is accelerating frameless torque motor procurement.
South Korea
Flat-panel display fabrication expansion in Gyeonggi Province is displacing ball-screw mechanisms with linear servo direct-drive systems. National industrial competitiveness programs prioritize semiconductor wafer handling automation upgrades. Busan-Ulsan shipbuilding clusters are testing integrated servo motors for decentralized crane control architectures.
United States
EPICA motor efficiency standards under the Department of Energy mandate IE4 minimums from 2027, affecting California and New York material handling integrators. Utility rebate programs stack with federal mandates in Pacific Northwest warehouse robotics deployments. Michigan automotive battery assembly lines are deploying AI-driven auto-tuning drives for electric vehicle platform flexibility.
Global Servo Motor Market Competitive Environment
Vertically integrated conglomerates and specialized motion control firms split the market between captive magnet sourcing and precision feedback integration. The structure consolidates around three tiers: rare-earth supply chain owners, drive-train system integrators, and component specialists. Dominant competitive moves include hydraulic-to-electric conversion program expansion and predictive maintenance subscription bundling.
Within the integrated drive-train tier, Yaskawa Electric Corporation and Siemens AG exemplify scale-driven service contract positioning. Bosch Rexroth AG occupies a specialist niche in machine life cycle extension programs. These three anchors demonstrate how Japanese manufacturing scale, European system integration depth, and German retrofit expertise respectively represent distinct competitive vectors.
| Leading Market Players |
|---|
| Yaskawa Electric Corporation |
| Siemens AG |
| Mitsubishi Electric Corporation |
| ABB Ltd. |
| Rockwell Automation, Inc. |
| FANUC Corporation |
| Delta Electronics, Inc. |
| Schneider Electric SE |
| Bosch Rexroth AG |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese rare-earth magnet separation facilities is compressing NdFeB pricing power while forcing Japanese encoder suppliers to maintain premium positioning through IP65-rated feedback device specialization. This utilization asymmetry between upstream material processing and downstream precision component manufacturing creates divergent margin trajectories across the servo motor value chain.
Pricing Analysis
The EU F-Gas Regulation and REACH compliance frameworks dictate the pricing tier structure across the Global Servo Motor Market, with IE4 and IE5 efficiency certification separating premium permanent magnet synchronous designs from standard induction motor replacements. Three-tier pricing structure across premium, standard, and economy levels reflects magnet grade quality, resolver encoder precision, and after-sales service bundling intensity. Cost compression in economy-tier material handling applications is intensifying because Chinese GB 18613 replacement cycles lag in low-precision conveyor deployments. Automotive battery assembly buyers in Hungary and Poland exhibit the least price sensitivity due to SIL3 functional safety requirements, while textile machinery OEMs in India's PLI scheme zones demonstrate acute cost consciousness.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for NdFeB magnet procurement, forcing OEMs to qualify secondary sourcing corridors. Rare-earth oxide concentrate processing concentrates in China, Japan, and Germany, while high-precision optical encoder manufacturing rests on Japanese component suppliers in Aichi and Tokyo metropolitan corridors. Neodymium price volatility from Chinese separation facilities and single-source vulnerability for IP65-rated resolver feedback devices constitute the primary structural risks. Distribution runs through integrated drive-train service contracts in Germany's precision manufacturing corridor and transactional hardware channels for Southeast Asian packaging machinery OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Servo Motor Market represents a high-growth disruption anchored by AI-driven auto-tuning algorithms collapsing commissioning timelines and predictive maintenance subscriptions displacing transactional hardware margins. The EU Green Deal's IE4 and IE5 efficiency mandates constitute the regulatory inflection accelerating permanent magnet motor adoption across automotive assembly automation.
For Market Incumbents: Build predictive maintenance subscription moats to capture recurring revenue from Germany's Ruhr industrial belt hydraulic-to-electric conversion programs. Defensive consolidation requires backward integration into rare-earth magnet sourcing to mitigate NdFeB price volatility from Chinese separation facilities, alongside capacity addition in India's Gujarat and Tamil Nadu PLI scheme zones to serve textile and packaging machinery demand. The threat of motion control engineering talent scarcity in US and European vocational programs necessitates embedded controller R&D investment to digitize PID loop tuning. For New Entrants and Emerging Players: India's domestic manufacturing incentives under the PLI scheme for industrial automation represent the most penetrable geographic entry corridor. White-space targets include frameless torque motor supply for collaborative robot joint manufacturers in Denmark and Japan, plus edge computing convergence with servo drives for warehouse robotics in the Pacific Northwest. A direct sales model to automotive tier-1 suppliers in Bavaria's automotive cluster, unbundling after-sales service from initial hardware procurement, offers the clearest go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated drive-train service contract providers with predictive maintenance capabilities. Long-term viability over the five-to-ten year window favors suppliers with captive rare-earth sourcing and software-integrated hardware platforms. Acquisition target archetypes include hydraulic-to-electric conversion specialists in Germany's precision manufacturing corridor and linear servo motor manufacturers serving South Korean flat-panel display fabs. The signal to watch is multi-vendor fieldbus integration complexity resolution, as EtherCAT, PROFINET, and CC-Link IE compatibility standardization would indicate inflection toward consolidated platform dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Hydraulic-to-Electric Conversion Program Expansion | Bosch Rexroth AG's machine life extension contracts in Germany's Ruhr belt demonstrate 15-20 year revenue visibility. |
| Predictive Maintenance Subscription Bundling | Siemens AG's standalone service entities for Bavarian automotive tier-1 suppliers capture total cost of ownership metrics. |
| Rare-Earth Magnet Backward Integration | Vertically integrated producers gain captive sourcing advantages under REACH compliance traceability mandates. |
| AI-Driven Auto-Tuning Algorithm Deployment | Automotive battery assembly lines in Hungary and Poland leverage self-configuring drives for platform flexibility. |
| Linear Servo Direct-Drive System Adoption | South Korean flat-panel display fabs in Gyeonggi Province displace ball-screw mechanisms for throughput gains. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with industry stakeholders and systematic secondary validation across regulatory and trade databases. Primary engagement encompassed plant engineers at German automotive stamping lines, aftermarket service heads at Japanese machine tool OEMs, OEM procurement teams in South Korean flat-panel fabrication facilities, and maintenance directors at US warehouse robotics deployments. Secondary sources included MIIT efficiency standard filings, ECHA REACH compliance documentation, US Department of Energy EPICA regulatory texts, SEC 10-K disclosures from listed motion control suppliers, and customs trade data tracking rare-earth oxide concentrate flows. Bottom-up unit economics triangulated against top-down market sizing across product type, end user, technology, and application dimensions.
Forecast inputs considered efficiency mandate implementation timelines, replacement cycle dynamics for induction-to-servo upgrades, and semiconductor capital equipment spending patterns across the analysis window. Segmentation modeling spanned motor topology, control architecture, precision requirements, and regional regulatory clusters. CAGRs were derived from installed base growth rates, technology substitution curves, and service revenue mix shifts. Industry-specific inputs incorporated rare-earth magnet price elasticity, encoder component lead time variability, and fieldbus protocol adoption trajectories.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, rare-earth export quota policies, or automotive production volumes would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and technology substitution pace. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Industrial Enclosures Market
Industrial Equipment
Global Refrigeration Compressor Market
Industrial Equipment
Global DC Drives Market
Industrial Equipment
Global Dicing Blades Market
Industrial Equipment
Rotary Scroll Air Compressor Market
Industrial Equipment
Fluid Dispensing Equipment Market
Industrial Equipment
Cash Sorting Machines Market
Industrial Equipment
Sorter Machines Market
Industrial Equipment
Slewing Bearing Market
Industrial Equipment
Global Industrial Actuators Market
Industrial Equipment
Semiconductor Cartridge Heaters Market
Industrial Equipment
Latin America Explosion-Proof Equipment Market
Industrial Equipment
Precision Positioning Equipment Market
Industrial Equipment
Industrial Magnetrons Market
Industrial Equipment
Global Liquid Handling Systems Market
Industrial Equipment
Fusion Splicer Market