
 Separation Systems for Commercial Biotechnology Market | 2026-2036
Separation Systems for Commercial Biotechnology Market Size, Share, and Industry Trends Forecast 2026-2036
Separation Systems for Commercial Biotechnology Market Intelligence
Pharmaceutical-grade separation specifications is collapsing the gap between research-scale and commercial-scale equipment, forcing vendors to redesign platforms for continuous bioprocessing. Thermo Fisher Scientific leverages its life sciences distribution network to sustain installed-base loyalty across North America and Europe. Sartorius AG specializes in single-use membrane filtration systems that anchor its position in cell harvesting workflows. Danaher Corporation controls a broad chromatography portfolio that competes on automation integration and regulatory compliance documentation.
Separation systems for commercial biotechnology encompass engineered equipment that isolates, purifies, and concentrates biological molecules from complex feedstreams using pressure-driven, gravitational, or chemically selective methods, with operating parameters typically spanning 0.1 to 10 bar differential pressure and pore ratings from 0.02 to 0.45 micrometers for sterile filtration stages. These systems serve the primary industrial purpose of ensuring product safety, yield recovery, and batch consistency in monoclonal antibody, vaccine, and cell therapy manufacturing. Chromatography units capture the deepest margin pools due to resin replacement cycles and method development services, while membrane filtration leads in unit volume because of its ubiquity across harvest clarification and final fill steps. Tangential flow filtration is accelerating fastest as bioprocessors adopt intensified perfusion cultures requiring higher cell density retention.
FDA enforces viral clearance validation through ICH Q5A guidance, compelling manufacturers to demonstrate log reduction values across multiple orthogonal separation steps before biologics license approval. EMA's MDR and Annex 1 revisions on sterile manufacturing push European biopharmaceutical producers toward closed-system separation architectures with automated cleaning validation. China's NMPA alignment with PIC/S standards is forcing multinational sponsors to harmonize separation platform qualification across manufacturing sites in Suzhou and Shanghai. Stakeholders must monitor how regulatory divergence on extractables and leachables testing for single-use assemblies reshapes equipment procurement criteria and supplier qualification timelines.
Market Dynamics
Continuous bioprocessing architectures are collapsing traditional batch-scale economics, forcing separation equipment vendors to reengineer platforms for real-time mass transfer rather than discrete volume processing. This shift compresses capital deployment timelines while raising performance validation thresholds across monoclonal antibody and cell therapy manufacturing.
Growth Catalysts
- ICH Q5A viral clearance mandates:FDA and EMA enforcement of log reduction validation across orthogonal separation steps compels manufacturers to upgrade chromatography and filtration trains before biologics license approval.
- Perfusion culture intensification:Tangential flow filtration systems anchor cell retention at densities exceeding 100 million cells per milliliter, enabling higher-titer harvests in stainless steel and single-use bioreactors alike.
- Suzhou-Shanghai manufacturing corridor:China's NMPA alignment with PIC/S standards drives multinational sponsors to harmonize separation platform qualification across domestic and export-bound production lines.
Market Restraints
- Protein A resin cost volatility:Chromatography capture steps depend on recombinant protein A ligands whose supply concentrates among three specialized chemical manufacturers, exposing margin structures to input price shocks.
- Single-use extractables testing burden:EMA's MDR and Annex 1 revisions on sterile manufacturing extend supplier qualification timelines for film-based assemblies, delaying facility startup schedules.
- Membrane fouling limitations:High cell density harvest streams exceed nominal flux capacities of standard polyethersulfone membranes, forcing premature replacement cycles or oversized system footprints.
Strategic Opportunities
- India's CDMO buildout:PLI scheme incentives for biopharmaceutical manufacturing attract separation system deployments in Hyderabad and Bangalore clusters previously dominated by small-molecule API production.
- Automated cleaning validation:Closed-system architectures with integrated conductivity and TOC sensors address EMA's Annex 1 emphasis on eliminating manual intervention in aseptic processing.
- Multi-column periodic counter-current chromatography:This process intensification approach converges continuous capture with resin productivity gains, reducing buffer consumption by half in validated antibody purification workflows.
Industry Challenges
- Process analytical technology integration:Real-time release testing demands spectroscopic sensors and multivariate models that few facility engineering teams possess, creating recruitment bottlenecks for data science-enabled bioprocess engineers.
- Legacy stainless steel retrofit complexity:Brownfield sites with fixed piping and tank geometries face mechanical constraints when adopting single-use separation skids, requiring custom manifold designs that extend validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Separation Systems for Commercial Biotechnology Market |
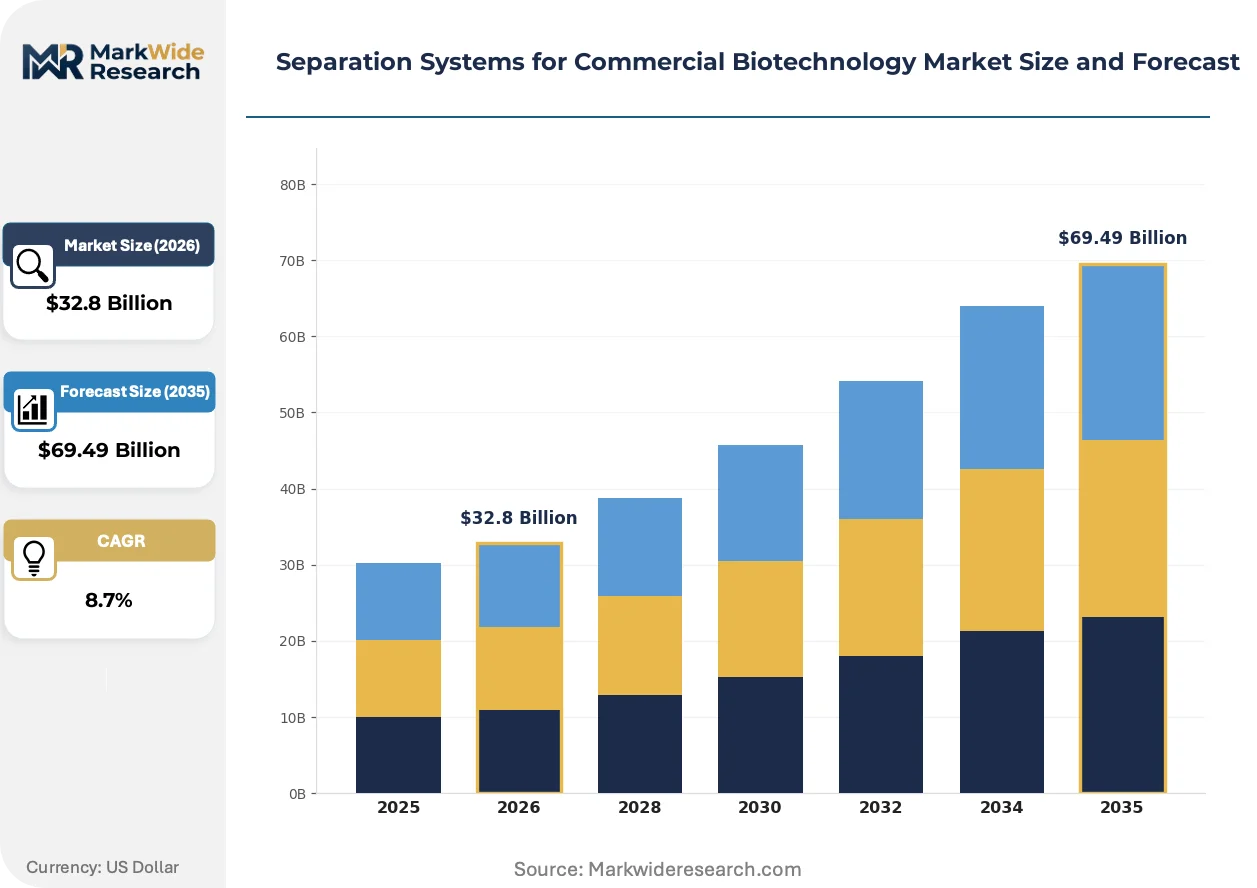
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $69.49 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Filtration, Centrifugation Systems, Chromatography Units, Precipitation Equipment Technology: Crossflow Filtration, Affinity Chromatography, Tangential Flow Filtration, Electrophoresis Application: Protein Purification, Cell Harvesting, Harvest Clarification, Viral Clearance End User: Biopharmaceutical Manufacturers, Contract Manufacturing Organizations, Research Institutes, Vaccine Producers |
| Companies Covered | QIAGEN, Agilent Technologies, Inc., Thermo Fisher Scientific Inc., Merck KGaA, Waters Corporation, Danaher Corporation, Sartorius AG, Shimadzu Corporation, Bio-Rad Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Separation Systems for Commercial Biotechnology Market Strategic Shifts & Innovations
Digital twin architectures and model predictive control are migrating from pilot plants to licensed commercial facilities, compressing the feedback loop between separation performance deviation and corrective action. This convergence of process equipment and computational infrastructure redefines vendor-customer relationships around uptime guarantees rather than hardware transactions.
Single-use depth filtration media is decomposing the dominance of centrifugation in harvest clarification workflows. Contract manufacturers operating multi-product facilities adopt disposable disc stacks to eliminate cross-contamination validation between campaigns. This technology is decomposing capital allocation patterns that previously favored durable equipment with decade-long depreciation schedules.
EMA's Annex 1 revision on sterile manufacturing mandates barrier isolation and automated decontamination for aseptic processing zones. European biopharmaceutical producers retrofit existing cleanrooms with restricted access barrier systems and vaporized hydrogen peroxide generators. Fill-finish operations for cell therapies and mRNA vaccines face the steepest compliance costs due to their open manipulations and low-tolerance for microbial excursions.
Biopharmaceutical procurement teams now unbundle after-sales service contracts from initial equipment purchases, negotiating multi-vendor maintenance agreements based on mean time between failure metrics rather than OEM loyalty. This behavior concentrates in North American and German manufacturing sites where internal engineering capabilities support mixed-fleet operations. CDMOs with limited technical staff retain bundled service models, creating a bifurcated channel structure across customer segments.
Separation Systems for Commercial Biotechnology Market Segmentation
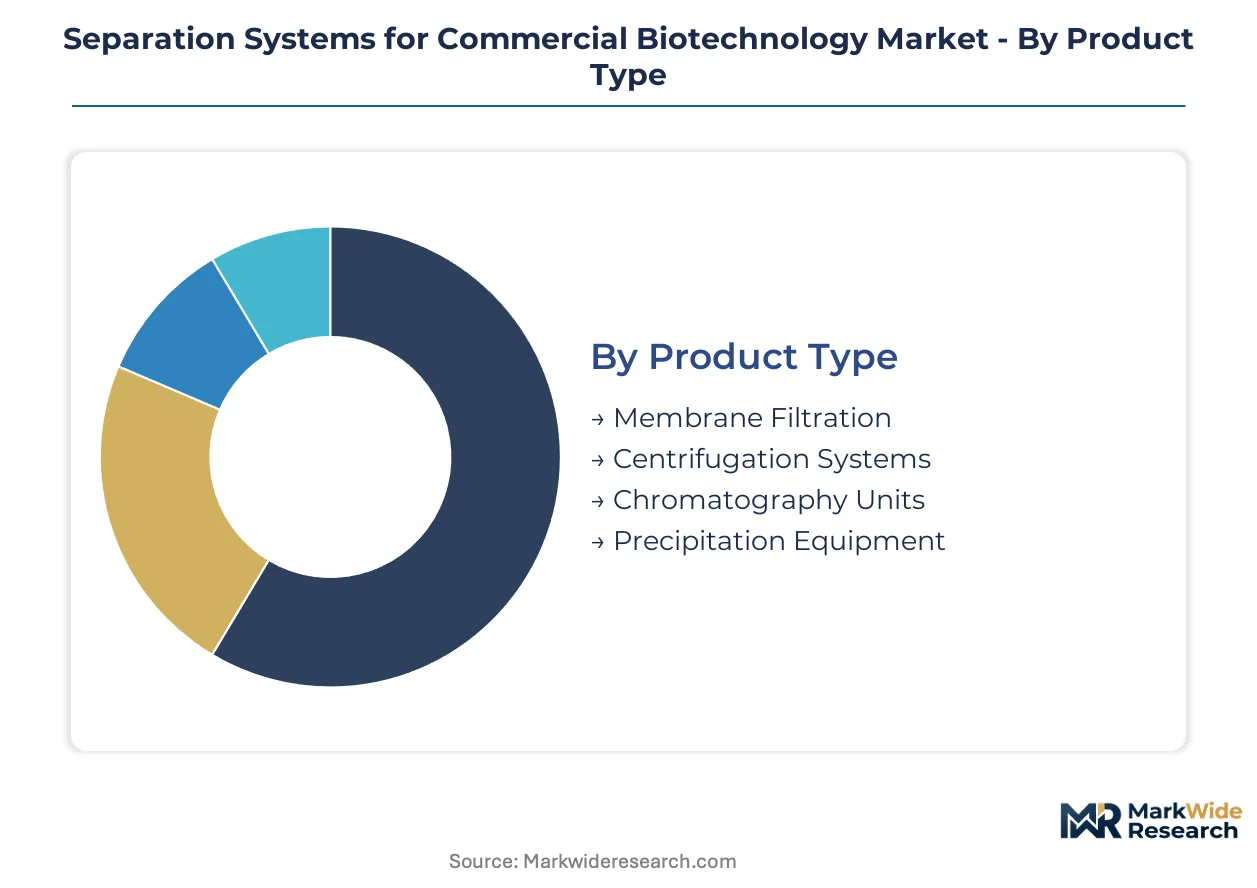
Segmentation in separation systems reveals how equipment specifications diverge across bioprocessing workflows. Procurement patterns vary sharply between mAb manufacturers prioritizing viral clearance validation and CDMOs optimizing campaign turnover speed.
Product Type:
Domestic production concentrates membrane filtration and chromatography units in Germany and the United States, while centrifugation systems see heavier export flow to India's emerging CDMO clusters.
- Membrane Filtration:Polyethersulfone and polyvinylidene fluoride membranes dominate sterile filtration and bioburden reduction steps. Demand clusters in United States monoclonal antibody facilities where single-use configurations accelerate batch turnaround. FDA's ICH Q5A enforcement drives specification upgrades for viral retention assurance.
- Chromatography Units:Protein A capture columns and multimodal polishing skids command premium positioning through resin replacement cycles. German biopharmaceutical manufacturers anchor European demand for automated cleaning validation under EMA Annex 1 revisions.
- Centrifugation Systems:Disk-stack and tubular bowl designs serve high-cell-density harvest clarification in stainless steel facilities.
- Precipitation Equipment:Selective precipitation skids support plasma fractionation and vaccine antigen recovery workflows.
Chromatography units hold the largest share; momentum sits with membrane filtration as single-use adoption accelerates across perfusion culture intensification.
Technology:
Cost tiering separates validated platform technologies from emerging methods still navigating regulatory qualification timelines.
- Tangential Flow Filtration:Recirculating flow configurations retain cells and concentrate product streams without membrane fouling. China's NMPA-aligned facilities in Suzhou deploy these systems for high-density perfusion cultures exceeding 100 million cells per milliliter.
- Affinity Chromatography:Protein A ligand chemistry enables selective monoclonal antibody capture from complex harvest matrices. Supply concentration among three specialized resin manufacturers exposes margin structures to input cost volatility.
- Crossflow Filtration:Tangential flow variants for microfiltration and ultrafiltration permeate control dominate harvest clarification.
- Electrophoresis:Capillary and preparative-scale separation methods serve analytical characterization and rare protein isolation.
Affinity chromatography captures the deepest margin pools; tangential flow filtration is climbing the fastest as continuous bioprocessing architectures displace batch-scale economics.
Application:
Volume concentration follows the manufacturing intensity of approved biologics, with viral clearance and protein purification commanding disproportionate equipment deployment.
- Viral Clearance:Orthogonal separation trains combining nanofiltration and low-pH inactivation demonstrate log reduction values for FDA biologics license approval. EMA's tightening MDR requirements extend validation documentation burdens for European facilities.
- Protein Purification:Multi-step chromatography workflows isolate therapeutic antibodies, fusion proteins, and blood factors to specification-grade purity. United States contract manufacturers unbundle service contracts to optimize mean time between failure metrics.
- Cell Harvesting:Centrifugation and depth filtration combinations recover biomass from bioreactor effluent streams.
- Harvest Clarification:Primary separation removes cells and debris before downstream purification trains.
Protein purification holds the largest share; viral clearance is expanding most quickly as regulatory agencies mandate demonstrable safety margins for gene therapy vectors.
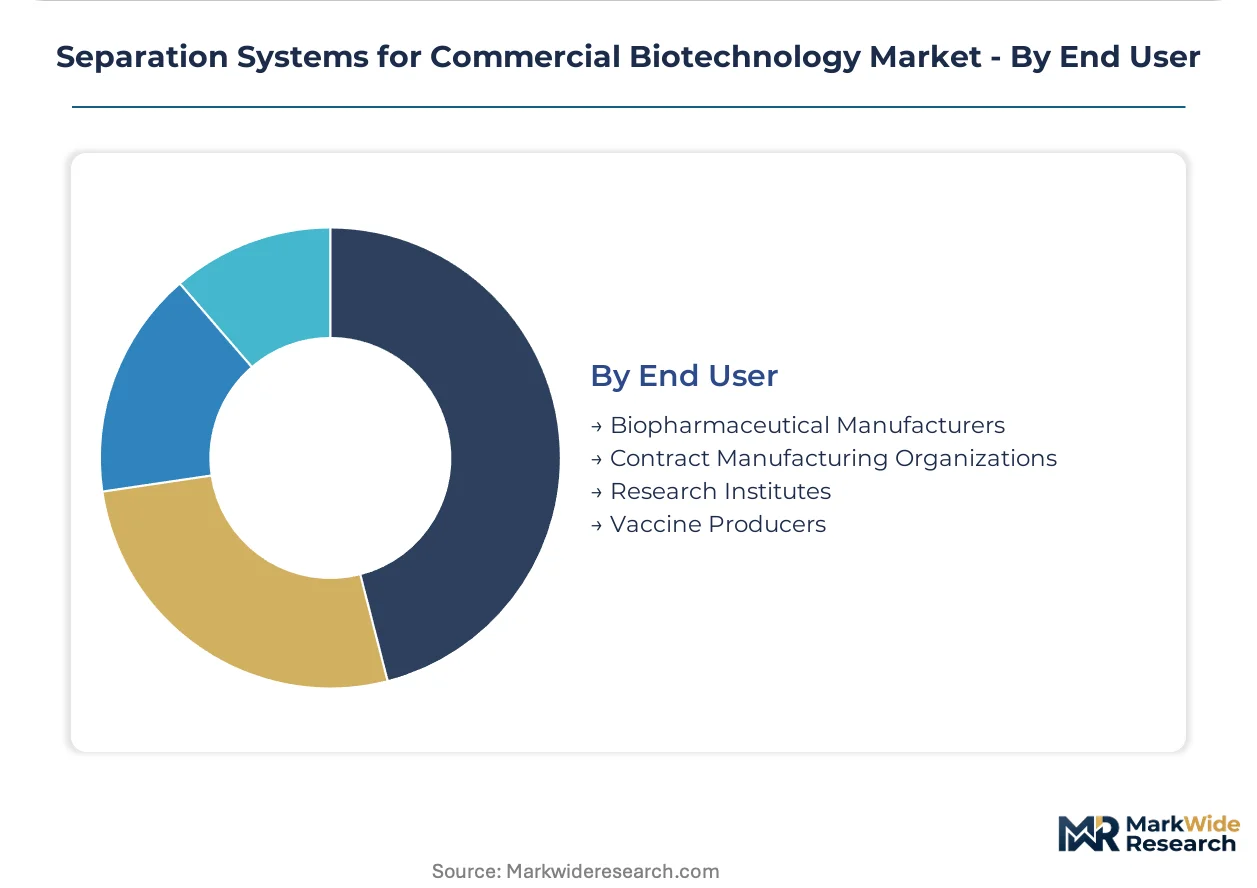
End User:
Customer type determines procurement sophistication, with biopharmaceutical manufacturers demanding integrated automation and CDMOs prioritizing campaign flexibility.
- Biopharmaceutical Manufacturers:Integrated companies deploy captive separation infrastructure across stainless steel and single-use platforms. Internal engineering capabilities in North American and German sites support mixed-fleet operations with multi-vendor maintenance agreements.
- Contract Manufacturing Organizations:CDMOs serving multi-product portfolios favor disposable depth filtration and chromatography skids to eliminate cross-contamination validation between campaigns. India's PLI scheme incentives attract separation system deployments to Hyderabad and Bangalore clusters.
- Vaccine Producers:Inactivated and mRNA vaccine manufacturing requires specialized viral clearance and sterile filtration configurations.
- Research Institutes:Academic and government laboratories operate at pilot scale with lower throughput requirements.
Biopharmaceutical manufacturers hold the largest share; contract manufacturing organizations are gaining share fastest as outsourced biologics production concentrates in Asia-Pacific and European hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German separation system exports flow primarily to United States biopharmaceutical facilities, while Chinese manufacturing clusters absorb Japanese precision filtration components for domestic mAb production.
United States
FDA's ICH Q5A enforcement drives viral clearance validation upgrades across monoclonal antibody facilities. The Biologics License Application process mandates demonstrable log reduction values before commercial approval. Greater Boston hosts concentrated demand for single-use chromatography skids serving cell therapy manufacturing.
Germany
EMA's Annex 1 revisions on sterile manufacturing push biopharmaceutical producers toward closed-system architectures. Automated cleaning validation requirements extend supplier qualification timelines for membrane filtration assemblies. Baden-Württemberg anchors European chromatography resin production and precision equipment fabrication.
China
NMPA alignment with PIC/S standards compels multinational sponsors to harmonize separation platform qualification across Suzhou and Shanghai manufacturing sites. Perfusion culture intensification exceeds 100 million cells per milliliter in domestic bioreactor deployments. The Yangtze River Delta concentrates single-use filtration demand for export-bound production lines.
India
PLI scheme incentives for biopharmaceutical manufacturing attract separation system deployments to Hyderabad and Bangalore clusters. CDSCO regulatory convergence with international standards accelerates validation documentation for contract manufacturers. Karnataka's biotech corridor transitions from small-molecule API toward biologics infrastructure.
Switzerland
Swissmedic maintains stringent viral clearance documentation requirements exceeding baseline ICH guidelines. Precision engineering capabilities support high-value chromatography skid fabrication for global export. Basel's pharmaceutical manufacturing ecosystem sustains demand for automated polishing train integration.
Separation Systems for Commercial Biotechnology Market Key Industry Players
Listed leaders compete with private specialists across regulatory compliance documentation and automation integration capabilities. The vendor base organizes into three tiers: diversified life sciences conglomerates with captive distribution networks, mid-scale filtration specialists with membrane chemistry expertise, and precision instrumentation houses with analytical chromatography legacies. Strategic moves concentrate on M&A for resin technology access and capacity expansion for single-use assembly manufacturing.
Among diversified conglomerates, Danaher Corporation and Thermo Fisher Scientific exemplify scale-driven platform providers with broad chromatography and filtration portfolios. Sartorius AG occupies a specialist position within membrane-based separation architectures. These three entities represent distinct competitive archetypes: the integrated automation house, the life sciences distribution giant, and the single-use technology pure-play.
| Leading Market Players |
|---|
| QIAGEN |
| Agilent Technologies, Inc. |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Waters Corporation |
| Danaher Corporation |
| Sartorius AG |
| Shimadzu Corporation |
| Bio-Rad Laboratories, Inc. |
| Others |
Cost & Logistics Intelligence
Long-term resin supply offtakes lock in chromatography platform access while anchoring price visibility across multi-year biologics manufacturing campaigns. Biopharmaceutical procurement teams negotiate these contracts against EMA extractables testing timelines and FDA viral clearance validation schedules, forcing suppliers to absorb qualification cost risk upfront.
Pricing Analysis
Next-generation continuous chromatography skids command 40-60% premiums over batch-scale legacy units, while prior-generation stainless steel systems trade at distressed valuations in secondary markets. Three-tier pricing structure across premium, standard, and economy levels separates automated multi-column systems from semi-manual skids and refurbished equipment. Pricing pressure stems from protein A resin cost volatility concentrated among three specialized chemical manufacturers. CDMOs exhibit highest price sensitivity due to campaign turnover economics, while integrated biopharmaceutical manufacturers prioritize total cost of ownership over unit capital expenditure.
Supply Chain Analysis
Protein A ligand synthesis concentrates in Germany, South Korea, and the United States, creating single-source vulnerability for affinity chromatography capture steps. Supply chains draw from recombinant fermentation feedstocks, precision-engineered valve manifolds, and gamma-irradiated film assemblies. Tariff exposure runs through specialty chemical imports subject to ECHA REACH registration requirements. Distribution runs through OEM direct sales for large-scale installations and distribution partners for consumables and aftermarket service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous bioprocessing architectures are redefining this market as a platform-economics inflection, with interoperability between single-use separation skids and distributed control systems determining vendor stickiness. Ecosystem momentum favors suppliers offering integrated process analytical technology bundles over point-equipment vendors.
For Market Incumbents: Fortify resin technology positions through captive ligand manufacturing or exclusive fermentation partnerships, as protein A supply concentration exposes margin structures to input price shocks. Expand automated cleaning validation documentation to preempt EMA Annex 1 compliance delays. Anchor installed-base loyalty through predictive maintenance contracts tied to mean time between failure guarantees rather than transactional equipment sales.
For New Entrants and Emerging Players: FDA Breakthrough Device designation fast-tracks regulatory qualification for novel viral clearance technologies, opening white-space in nanofiltration and low-pH inactivation systems. India's PLI scheme incentives for biopharmaceutical manufacturing create penetrable geography in Hyderabad and Bangalore CDMO clusters previously dominated by small-molecule API production. Lead with modular single-use skids enabling rapid campaign turnaround for multi-product contract manufacturers.
For Investors and Strategic Acquirers: Capital is best deployed toward membrane chemistry specialists with proprietary polyethersulfone or polyvinylidene fluoride formulations, as material science differentiation underpins filtration performance in high-cell-density perfusion cultures. Long-term viability rests on regulatory compliance automation capabilities rather than hardware scale. Watch for NMPA-PIC/S harmonization completion as inflection signal for China manufacturing corridor equipment replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Resin Technology Acquisition | Protein A ligand supply concentration creates defensive moats for integrated chromatography vendors. |
| Single-Use Assembly Capacity Expansion | EMA Annex 1 sterile manufacturing mandates accelerate demand for gamma-irradiated film-based systems. |
| Process Analytical Technology Integration | FDA ICH Q5A viral clearance enforcement requires real-time release testing sensor deployment. |
| India CDMO Corridor Partnership | PLI scheme incentives attract biologics infrastructure investment to Hyderabad and Bangalore clusters. |
| Automated Cleaning Validation Platform | Closed-system architectures with integrated conductivity sensors address EMA manual intervention elimination. |
Research Approach
A spread of perspectives from bioprocess engineering directors, regulatory affairs leads at multinational sponsors, CDMO procurement managers, and chromatography resin technical specialists converged on the working assumptions. Secondary validation drew from FDA Biologics License Application filings, EMA scientific advice letters, NMPA drug master file submissions, and PIC/S inspection observation databases. Bottom-up equipment deployment tallies triangulated against top-down biologics capacity expansion announcements.
Segmentation dimensions modeled include separation technology type, bioprocessing application workflow, end-user operational scale, and regional regulatory cluster alignment. Growth trajectories across the analysis window reflect intensity of perfusion culture adoption, viral clearance validation burden expansion, and single-use platform penetration rates. Forecast inputs incorporated bioreactor capacity expansion pipelines and CDMO facility commissioning timelines without year-specific anchoring.
Underlying assumptions cover sustained ICH Q5A enforcement stringency, protein A resin supply stability, and NMPA-PIC/S convergence completion, with deviation risk concentrated in extractables testing timeline extensions and trade policy shifts affecting specialty chemical feedstocks. Practitioners should keep alternative scenarios live as continuous bioprocessing regulatory qualification pathways and single-use film chemistry innovations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Fluidized-Bed Bioreactors Market
Biotechnology Equipment
Mammalian Cell Fermentation Technology Market
Biotechnology Equipment
Global Cell Culture Sampling Device Market
Biotechnology Equipment
Automated Colony Picking Systems Market
Biotechnology Equipment
Real-Time Bioprocess Raman Analyzer Market
Biotechnology Equipment
Automated Cell Counting Market
Biotechnology Equipment
Lab Automation for in-Vitro Diagnostics Market
Biotechnology Equipment
US Cell Culture Media Market
Biotechnology Equipment
Bioprocess Analyzers and Technology Market
Biotechnology Equipment
Cell Lysis Market
Biotechnology Equipment
Global Biotechnology Instruments Market
Biotechnology Equipment
Bioprocessing Systems Market
Biotechnology Equipment
Measurement Technologies in Downstream Processing Market
Biotechnology Equipment
Global Bioreactor Market
Biotechnology Equipment
RNA Isolation and Enrichment Reagent Market
Biotechnology Equipment
Global Cryostat Microbiome Equipment Market