
 Lab Automation for in-Vitro Diagnostics Market | 2026-2036
Lab Automation for in-Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Lab Automation for in-Vitro Diagnostics Market Foresight
Hospital-based reference laboratories is unwinding the historical dominance of small independent diagnostic labs in instrument procurement. Thermo Fisher Scientific leverages its end-to-end workflow portfolio to anchor multi-year automation contracts with consolidated health systems. Danaher Corporation competes through Beckman Coulter's installed base density, while Roche Holding AG differentiates via cobas platform integration with its proprietary assay menu.
Lab automation for in-vitro diagnostics encompasses electromechanical systems that execute specimen processing, reagent handling, and analytical measurement with throughput specifications exceeding hundreds of tests per hour and coefficient-of-variation targets below five percent, primarily serving clinical decision-making by reducing manual pipetting errors and turnaround times. Automated analyzers occupy the largest installed base due to chemistry and immunoassay volume concentration, while microfluidics technology leads growth acceleration through miniaturized reaction chambers that slash reagent consumption per test. Software automation increasingly captures margin pools as laboratories prioritize interoperability with laboratory information systems and middleware analytics.
The FDA regulates automated diagnostic devices under 21 CFR Part 820 quality system requirements, while the Clinical Laboratory Improvement Amendments establish personnel and proficiency standards that shape instrument design complexity; European laboratories navigate the In Vitro Diagnostic Regulation's performance evaluation and post-market surveillance obligations. ISO 15189 accreditation frameworks drive standardization in emerging markets, tightening competitive access for non-compliant suppliers. Stakeholders must monitor evolving software-as-a-medical-device classifications that could reclassify automation control platforms and trigger additional validation burdens.
Market Dynamics
Hospital consolidation across the United States is concentrating purchasing power into fewer procurement desks, forcing automation vendors to restructure go-to-market strategies around multi-year enterprise agreements rather than individual instrument sales.
Growth Catalysts
- CLIA personnel standards:The Clinical Laboratory Improvement Amendments mandate qualified personnel for high-complexity testing, compelling laboratories to deploy automated systems that reduce manual intervention requirements and staffing dependencies.
- Chemistry and immunoassay volume concentration:Diagnostic networks processing hundreds of tests per hour require continuous-flow analyzers to maintain turnaround-time commitments for emergency departments and intensive care units.
- Microfluidics miniaturization:Reaction chamber scaling slashes reagent consumption per test, enabling mid-volume laboratories to access throughput capabilities previously restricted to reference laboratory scale.
Market Restraints
- Capital intensity of installed base transitions:Replacing legacy chemistry analyzers requires seven-figure capital commitments that strain hospital capital expenditure budgets and extend procurement cycles beyond thirty-six months.
- Reagent lock-in effects:Proprietary consumable ecosystems tether laboratories to original equipment manufacturers, suppressing competitive bidding and inflating lifetime cost of ownership calculations.
- FDA software-as-a-medical-device reclassification risk:Evolving guidance on automation control platforms threatens additional validation burdens and timeline extensions for middleware analytics integration.
Strategic Opportunities
- India's laboratory accreditation expansion:ISO 15189 framework adoption in emerging diagnostic chains creates demand for standardized automation platforms that satisfy international quality benchmarks.
- Interoperability premium capture:Middleware solutions enabling seamless laboratory information system integration command margin pools as health systems prioritize data liquidity across enterprise imaging and pathology networks.
- Decentralized point-of-care automation:Microfluidic cartridge systems deployed in retail clinic settings extend diagnostic access beyond traditional hospital laboratory footprints.
Industry Challenges
- Biomedical engineering talent scarcity:Field service technicians capable of maintaining electromechanical systems with sub-five-percent coefficient-of-variation specifications command premium compensation and extend vendor response commitments.
- Legacy middleware integration complexity:Health systems operating heterogeneous analyzer fleets from multiple manufacturers face protocol harmonization burdens when consolidating data streams into unified laboratory information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lab Automation for in-Vitro Diagnostics Market |
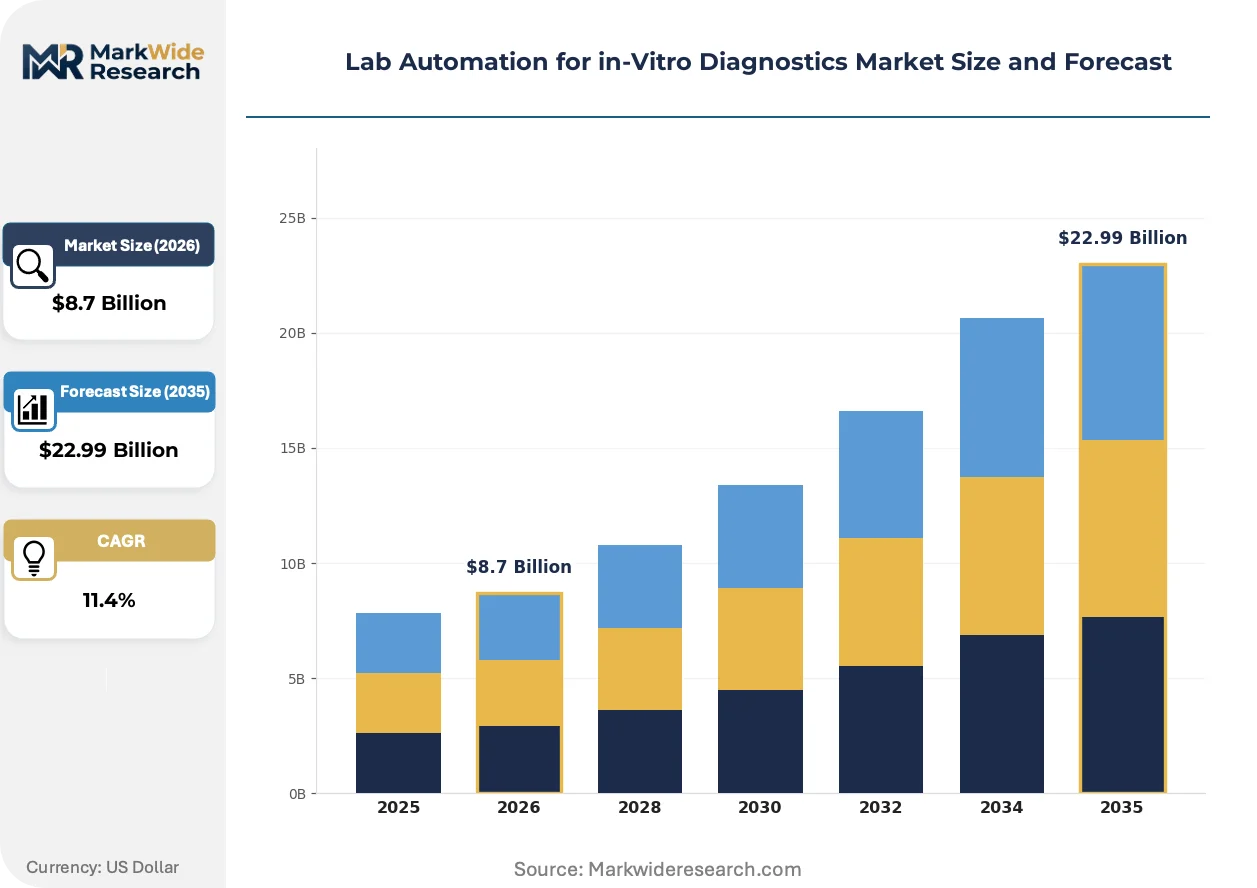
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Analyzers, Liquid Handlers, Robotic Systems, Sample Preprocessors Application: Clinical Laboratories, Research Institutions, Pharmaceutical Companies, Diagnostic Centers Technology: Magnetic Bead Technology, Microfluidics, Optical Detection, Software Automation End User: Healthcare Providers, Laboratories, Biotechnology Firms, Academic Institutions |
| Companies Covered | Thermo Fisher Scientific Inc, Danaher Corporation, Roche Holding AG, Siemens Healthineers AG, Abbott Laboratories, Agilent Technologies Inc, PerkinElmer Inc, Becton, Dickinson and Company, Tecan Group Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lab Automation for in-Vitro Diagnostics Market Shifts & Advancements
Automation architectures are bifurcating between centralized high-throughput platforms serving consolidated health systems and distributed microfluidic systems penetrating ambulatory settings, reshaping vendor R&D allocation and service model design.
Microfluidic cartridge technology is fragmenting the historical dichotomy between centralized reference laboratories and physician office laboratories. Retail health clinics and urgent care networks in the United States are adopting palm-sized disposable cartridge systems that execute immunoassay protocols without continuous-flow plumbing. This diffusion is compressing addressable market definitions for traditional analyzer manufacturers and forcing portfolio diversification into consumable-centric revenue models.
The European Union's In Vitro Diagnostic Regulation imposes performance evaluation and post-market surveillance obligations that extend product registration timelines by eighteen to twenty-four months. Manufacturers serving European laboratories must maintain technical documentation and clinical evidence packages that exceed predecessor directive requirements. Mid-tier automation vendors without dedicated regulatory affairs infrastructure are withdrawing from CE-marked product lines, concentrating competitive supply among enterprises with established notified body relationships.
Consolidated health systems in the United States are unbundling after-sales service contracts from instrument procurement agreements, negotiating third-party maintenance or in-house biomedical engineering coverage. This disintermediation compresses vendor service revenue streams and forces equipment manufacturers to compete on reliability metrics and remote diagnostic capabilities rather than captive service attach rates. Academic medical centers with established engineering departments are pioneering this separation, establishing templates that community hospital systems are replicating.
Lab Automation for in-Vitro Diagnostics Market Segmentation
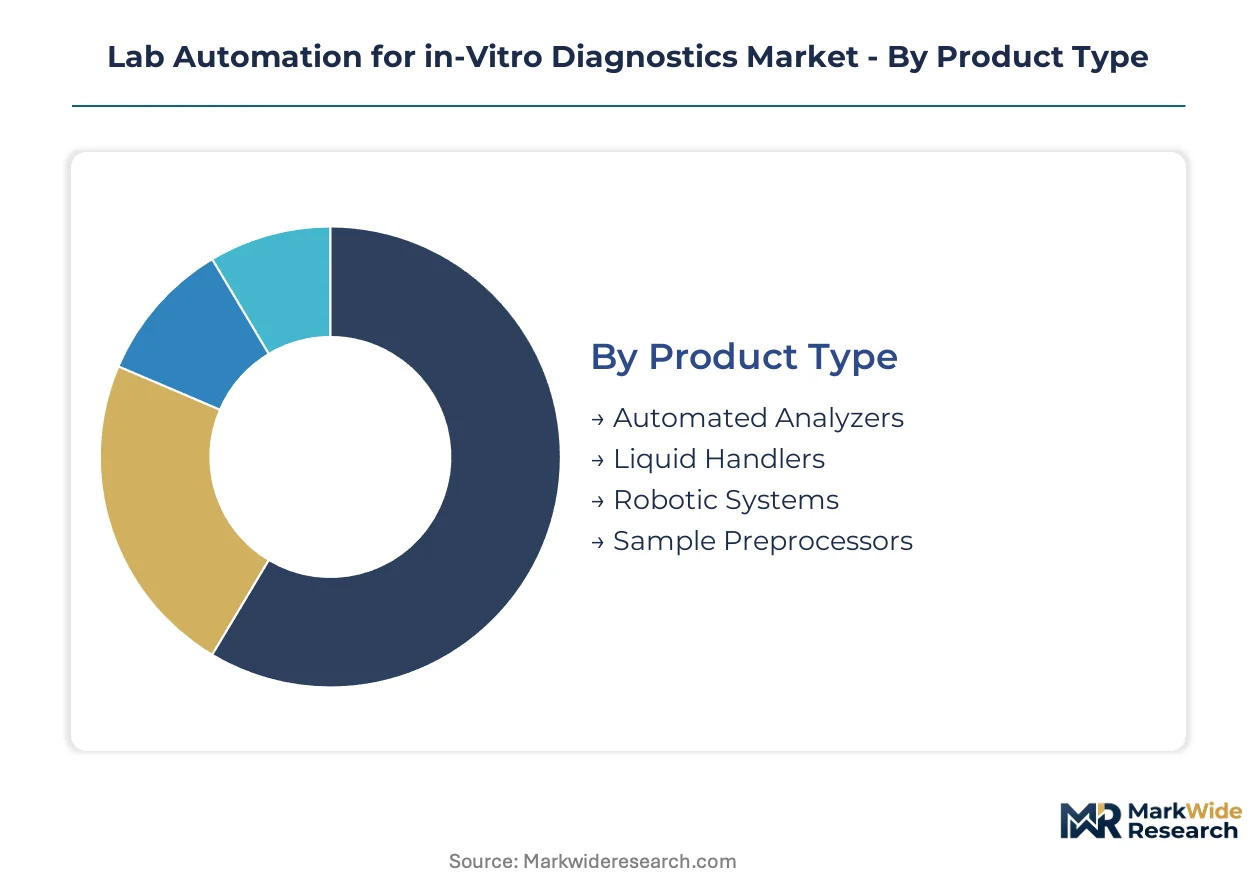
Automation architectures fragment across specimen throughput tiers, reagent consumption models, and regulatory compliance burdens. Vendors configure product portfolios around these divides to capture margin pools in consolidated health systems while defending installed base positions.
Product Type:
FDA 21 CFR Part 820 quality system requirements impose divergent validation burdens across electromechanical complexity tiers, shaping vendor R&D allocation and service model design.
- Automated Analyzers:Continuous-flow chemistry and immunoassay platforms process hundreds of tests per hour with coefficient-of-variation targets below five percent. Hospital-based reference laboratories in the United States concentrate procurement here to meet emergency department turnaround-time commitments.
- Liquid Handlers:Electromechanical pipetting workstations execute reagent dispensing and sample aliquoting with nanoliter precision. Research institutions deploy these for high-throughput screening protocols where protocol flexibility outweighs speed optimization.
- Robotic Systems:Articulated arm configurations integrate specimen transport with analytical modules.
- Sample Preprocessors:Centrifugation, decapping, and aliquoting modules standardize pre-analytical workflows.
Established volume favors automated analyzers; emerging adoption favors robotic systems.
Application:
Capital intensity and reimbursement pathways concentrate demand differently across institutional settings.
- Clinical Laboratories:Hospital laboratories and independent diagnostic chains process routine chemistry, immunoassay, and hematology panels under CLIA high-complexity standards. Consolidated health systems in the United States anchor procurement volume through multi-year enterprise agreements.
- Research Institutions:Academic medical centers and government laboratories prioritize protocol configurability over throughput specifications. Funding cycles and grant dependencies extend procurement timelines beyond commercial clinical settings.
- Pharmaceutical Companies:Drug development pipelines require automation for biomarker validation and companion diagnostic assays.
- Diagnostic Centers:Outpatient networks and retail health clinics seek compact footprints with minimal plumbing requirements.
Reimbursement concentration favors clinical laboratories; protocol diversity favors research institutions.
Technology:
Reagent consumption economics and miniaturization capabilities differentiate competitive positioning.
- Microfluidics:Miniaturized reaction chambers slash reagent volumes per test from milliliters to microliters. Mid-volume laboratories and point-of-care settings adopt cartridge-based systems to access throughput capabilities without continuous-flow infrastructure.
- Software Automation:Middleware platforms and laboratory information system integration command margin pools as health systems prioritize data liquidity. FDA software-as-a-medical-device reclassification threats hang over validation timelines.
- Magnetic Bead Technology:Solid-phase separation enables automated nucleic acid extraction and immunoassay workflows.
- Optical Detection:Spectrophotometric and chemiluminescent readouts anchor quantitative measurement in chemistry analyzers.
Reagent efficiency favors microfluidics; interoperability premiums favor software automation.
End User:
Technical staffing depth and maintenance outsourcing preferences shape vendor service contract structures.
- Healthcare Providers:Hospital systems with established biomedical engineering departments disaggregate instrument procurement from after-sales service, negotiating third-party maintenance or in-house coverage. Academic medical centers pioneer this separation.
- Laboratories:Independent diagnostic chains and reference laboratories prioritize uptime guarantees and remote diagnostic capabilities over captive service attach rates.
- Biotechnology Firms:Cell therapy and molecular diagnostic developers require automation for process analytical technology integration.
- Academic Institutions:Grant-funded researchers balance capital constraints against protocol flexibility requirements.
Service disintermediation favors healthcare providers; standardization pressure favors laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturers cluster near major diagnostic demand centers and regulatory approval hubs. Hospital consolidation in the United States, IVD regulation in Germany, and accreditation expansion in India concentrate procurement activity in three distinct geographies.
United States
Hospital system mergers concentrate purchasing power into fewer procurement desks across consolidated networks. FDA 21 CFR Part 820 quality system requirements shape instrument design complexity for manufacturers seeking 510(k) clearance. Academic medical centers in Boston and the Research Triangle pioneer third-party maintenance models that community systems replicate.
Germany
Reference laboratories in Baden-Württemberg and North Rhine-Westphalia anchor European demand for high-throughput chemistry platforms. The In Vitro Diagnostic Regulation extends product registration timelines by eighteen to twenty-four months, favoring enterprises with established notified body relationships. Siemens Healthineers maintains proximity to clinical partners in Erlangen and Munich.
China
Domestic diagnostic chains accelerate automation adoption to manage rising test volumes in tier-one cities. NMPA medical device registration requirements tighten clinical evidence standards for imported systems. Manufacturing clusters in Suzhou and Shenzhen supply microfluidic cartridge components to mid-volume laboratories.
India
ISO 15189 accreditation expansion in diagnostic chains creates demand for standardized automation platforms. CDSCO medical device rules classify automated analyzers based on risk tier, shaping import registration strategies. Mumbai and Bangalore house emerging reference laboratories consolidating previously fragmented testing capacity.
Japan
Aging demographics drive demand for high-throughput immunoassay systems in metropolitan hospital networks. PMDA quality management system requirements align with global harmonization standards while maintaining domestic specificity. Tokyo and Osaka academic centers prioritize middleware interoperability with legacy laboratory information systems.
Lab Automation for in-Vitro Diagnostics Market Competitive Landscape
Concentration sits with diversified life science conglomerates and specialized diagnostic equipment manufacturers. Thermo Fisher Scientific, Danaher Corporation, and Roche Holding AG anchor the top tier through installed base density and reagent ecosystem lock-in. Mid-tier automation vendors compete on modular configurations and regional service proximity. Strategic moves center on multi-year enterprise agreements with consolidated health systems and portfolio diversification into consumable-centric revenue models.
Among diversified conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify end-to-end workflow strategies that capture multi-year contracts. Roche Holding AG occupies a differentiated position through proprietary assay menu integration. Specialists including Tecan Group Ltd and PerkinElmer Inc represent modular flexibility archetypes targeting research institutions and mid-volume clinical settings where protocol configurability outweighs throughput specifications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc |
| Danaher Corporation |
| Roche Holding AG |
| Siemens Healthineers AG |
| Abbott Laboratories |
| Agilent Technologies Inc |
| PerkinElmer Inc |
| Becton, Dickinson and Company |
| Tecan Group Ltd |
| Others |
Supply & Pricing Matrix
FDA 21 CFR Part 820 quality system requirements gate both supplier qualification and price differentiation simultaneously, as manufacturers must absorb validation burdens that smaller vendors cannot shoulder while laboratories pay premiums for compliant systems that satisfy CLIA personnel standards.
Pricing Analysis
FDA 21 CFR Part 820 dictates the pricing tier structure across the Lab Automation for in-Vitro Diagnostics Market, separating premium-tier systems with full assay-menu integration from standard configurations with limited reagent compatibility. Price differentiation centers on throughput specifications and middleware interoperability certifications. Cost compression in mid-volume analyzer segments is intensifying because hospital consolidation concentrates purchasing power into fewer procurement desks. Independent diagnostic chains exhibit the highest price sensitivity, while consolidated health systems with captive biomedical engineering departments prioritize reliability metrics over upfront capital expenditure.
Supply Chain Analysis
Container availability constraints on trans-Pacific trade lanes elevate inbound logistics costs for electromechanical components sourced from East Asian manufacturing clusters. Supply concentration centers on Germany for precision optical detection modules, Switzerland for robotic articulation systems, and China for microfluidic cartridge substrates. Raw material dependencies include high-purity reagent-grade chemicals, precision-machined aluminum extrusions, and specialized photodetector arrays. Single-source vulnerability persists in laser diode supply for chemiluminescent readout systems. Distribution runs through authorized distributor networks serving hospital procurement committees and GPO contracts managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Lab Automation for in-Vitro Diagnostics Market represents an early-cycle expansion story, as ISO 15189 accreditation adoption in emerging diagnostic chains creates standardized demand that outpaces installed base replacement cycles in mature markets.
For Market Incumbents: Fortify installed base positions by deepening reagent ecosystem lock-in through exclusive assay-menu partnerships that raise switching costs for consolidated health systems. Accelerate remote diagnostic capability deployment to offset third-party maintenance disintermediation threats from academic medical centers with established biomedical engineering departments. Prioritize backward integration into microfluidic cartridge manufacturing to capture consumable-centric revenue pools as point-of-care automation fragments historical volume concentration.
For New Entrants and Emerging Players: Differentiate on modular configurability targeting research institutions where protocol flexibility outweighs throughput specifications and procurement timelines extend beyond commercial clinical settings. Penetrate India's emerging reference laboratory networks in Mumbai and Bangalore by offering ISO 15189-compliant platforms with localized service proximity. Deploy direct field engineering teams rather than distributor-dependent coverage models to overcome incumbent density advantages in hospital consolidation corridors.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software automation segments as laboratories prioritize middleware interoperability over electromechanical system replacement. Long-term viability over a five-to-ten year window favors enterprises with diversified revenue streams spanning instruments, consumables, and service contracts. Acquisition targets should demonstrate established notified body relationships for European IVD Regulation compliance. The signal to watch is FDA software-as-a-medical-device reclassification guidance that would elevate validation burdens and timeline extensions for automation control platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year enterprise agreements with consolidated networks anchor procurement volume and extend replacement cycles. |
| Software Companion Development | Middleware analytics integration commands margin pools as health systems prioritize laboratory information system interoperability. |
| CE Marking Pathway | European IVD Regulation compliance extends product registration timelines, favoring enterprises with dedicated regulatory infrastructure. |
| Reimbursement Strategy | Alignment with CMS Medicare coverage determinations shapes capital expenditure justification for hospital procurement committees. |
| Backward Integration | In-house production of microfluidic cartridges captures recurring revenue streams as point-of-care automation penetrates retail clinic settings. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearance databases, hospital procurement records, and GPO contract disclosures. Primary interviews engaged laboratory directors, biomedical engineering managers, diagnostic chain operations executives, and regulatory affairs specialists at instrument manufacturers. Secondary validation drew from CLIA proficiency testing data, ISO 15189 accreditation registries, and SEC filings of publicly traded life science conglomerates. Bottom-up triangulation of installed base estimates against top-down market sizing from capital expenditure surveys ensures analytical coherence.
Segmentation dimensions modeled include product type tiers, application settings, technology platforms, and end-user categories across the projection horizon. The analytical framework incorporates throughput specifications, reagent consumption economics, and regulatory compliance burdens as industry-specific forecast inputs. CAGRs derive from weighted average replacement cycles, accreditation expansion trajectories, and hospital consolidation velocity assumptions.
The analysis sits within stated boundaries; outcomes outside sustained hospital capital expenditure commitments and stable regulatory classification frameworks would require recalibration. Forecasts reflect documented assumptions regarding CLIA personnel standard enforcement intensity and FDA software-as-a-medical-device guidance evolution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
SDS Poly Acrylamide Gel Electrophoresis Market
Biotechnology Equipment
Low Endotoxin Gelatin Market
Biotechnology Equipment
Robotic Arms in Laboratories Market
Biotechnology Equipment
Automated Cell Counting Market
Biotechnology Equipment
Life Science Instrumentation Market
Biotechnology Equipment
Global Polymerase Chain Reaction (PCR) Consumables Market
Biotechnology Equipment
Cryogenic Vial Rack Market
Biotechnology Equipment
Plasmid Kits Market
Biotechnology Equipment
Global Biotechnology Instruments Market
Biotechnology Equipment
Global Biotechnology Market
Biotechnology Equipment
Cellular Localization Kits Market
Biotechnology Equipment
Middle East and Africa Transfection Reagent and Equipment Market
Biotechnology Equipment
Histology Equipment Market
Biotechnology Equipment
Cryopreservation Freezer Market
Biotechnology Equipment
Rocking Bioreactors Market
Biotechnology Equipment
DNA/RNA Extraction Market