
 Measurement Technologies in Downstream Processing Market | 2026-2036
Measurement Technologies in Downstream Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Measurement Technologies in Downstream Processing Market Foresight
EU MDR is rebalancing the cost-of-entry calculus for sensor suppliers serving European biopharma customers. Thermo Fisher Scientific leverages its chromatography instrumentation footprint to bundle optical sensors with purification skids. Sartorius anchors its position through membrane filtration systems that embed mass flow measurement at the cassette level. PendoTECH specializes in single-use pressure sensors that compete on validation documentation speed for contract manufacturers.
Measurement technologies in downstream processing encompass inline and at-line analytical instruments that monitor critical quality attributes during biologics purification, including protein concentration, turbidity, conductivity, and pH within chromatography and tangential flow filtration steps. These systems transmit real-time data to distributed control systems, enabling automated feedback loops that reduce batch cycle times and deviation rates. Optical sensors lead installed base across mAb and gene therapy processes, while data analytics applications represent the fastest-expanding segment as manufacturers deploy machine learning models on historical batch records to predict yield outcomes. Flow meters command premium pricing in continuous bioprocessing configurations where pulsation-free measurement stabilizes residence time distributions.
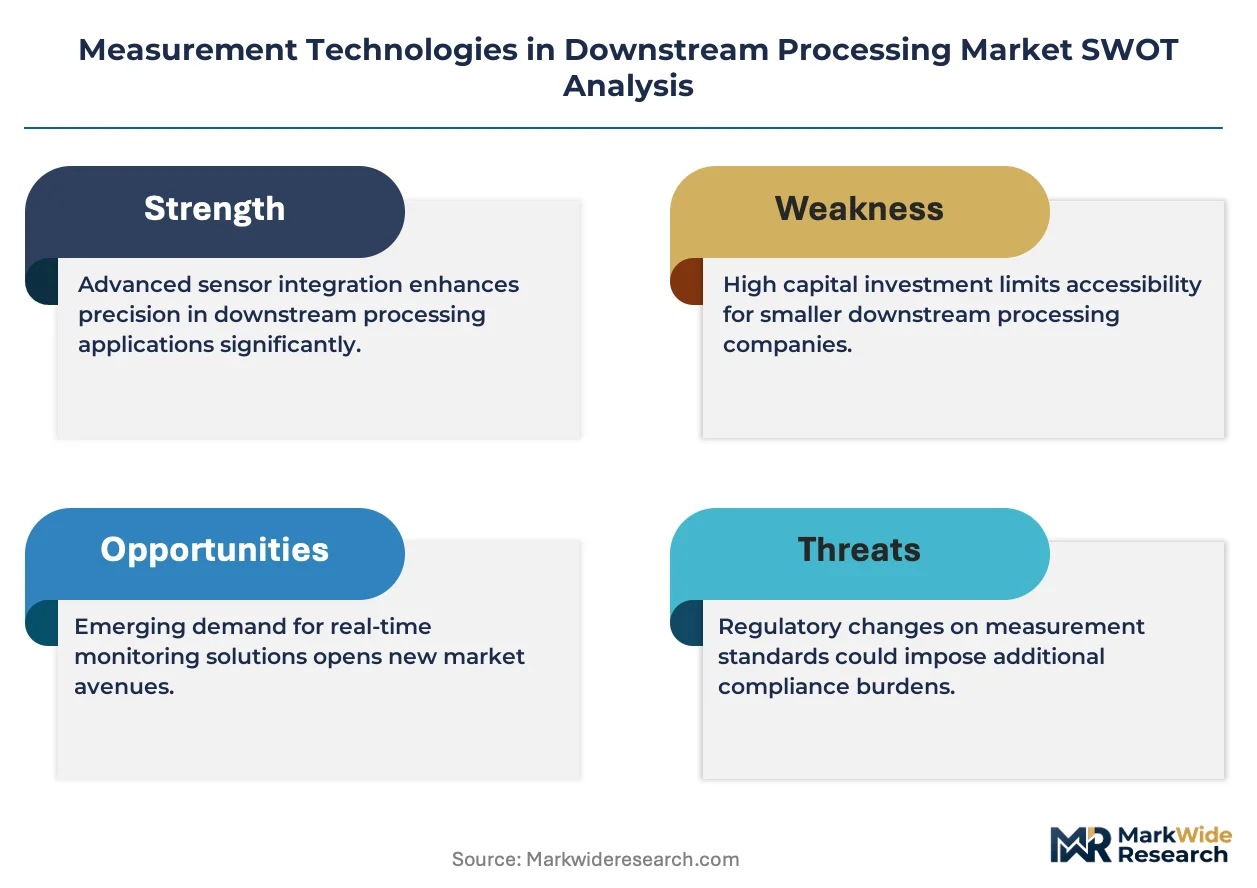
FDA process analytical technology guidance and EU GMP Annex 15 both mandate documented evidence that inline measurements correlate with reference methods, shaping R&D priorities for sensor calibration protocols. EMA's evolving stance on real-time release testing creates compliance complexity for multinationals operating across Atlantic jurisdictions. ISO 13485 certification requirements for device components further filter the supplier base. Stakeholders must monitor whether FDA advances toward fully validated real-time release pathways or preserves confirmatory testing requirements that sustain traditional quality control workflows.
Market Dynamics
Continuous bioprocessing adoption is compressing batch cycle timelines and forcing sensor suppliers to redesign calibration protocols for unsteady-state operating conditions. This shift favors vendors with embedded analytics capabilities over standalone instrument providers.
Growth Catalysts
- EU MDR validation requirements:Tightened documentation standards for real-time measurement systems are accelerating replacement of legacy offline quality control workflows with inline alternatives.
- Gene therapy manufacturing expansion:Viral vector purification complexity demands multi-parameter optical monitoring that legacy protein bioprocessing sensors cannot deliver.
- German CDMO retrofit activity:Contract manufacturers in Baden-Württemberg and Bavaria are integrating sensor networks into existing chromatography skids to enable real-time release testing.
Market Restraints
- Platinum-group metal input volatility:Electrochemical sensor electrodes depend on ruthenium and iridium supply concentrated in South African and Russian mining operations.
- Single-use sensor validation burden:Each gamma-sterilized pressure transducer requires lot-specific calibration certificates that extend procurement lead times.
- Reference method correlation costs:FDA process analytical technology guidance mandates parallel offline testing during qualification phases, doubling analytical labor requirements.
Strategic Opportunities
- Indian biopharma contract manufacturing:CDMOs in Hyderabad and Bengaluru lack integrated sensor infrastructure and present retrofit demand for at-line protein concentration analyzers.
- Machine learning yield prediction:Convergence of historical batch record databases with Raman spectroscopy models enables preemptive deviation correction.
- Continuous downstream trains:Connected chromatography and tangential flow filtration systems require synchronized multi-point flow measurement that batch configurations omit.
Industry Challenges
- Metrology talent scarcity:Bioprocessing engineers with combined expertise in GMP compliance and chemometric model development command premium compensation.
- Legacy distributed control system integration:1990s-vintage DeltaV and Wonderware installations lack native digital communication protocols for wireless sensor networks.
- ISO 13485 certification timelines:Device component suppliers face 18-24 month quality management system audits before qualifying for biopharma procurement lists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Measurement Technologies in Downstream Processing Market |
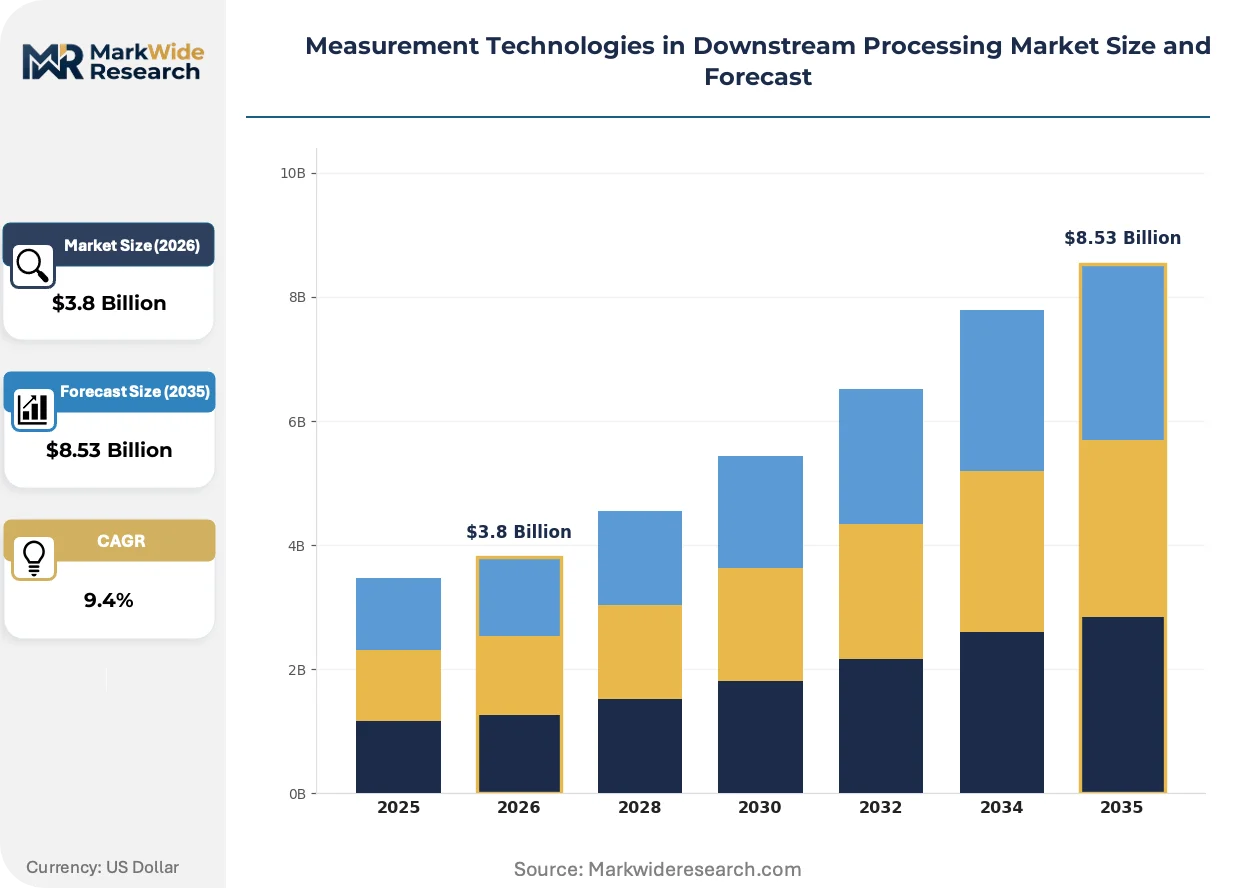
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Optical Sensors, Flow Meters, Pressure Sensors, Temperature Sensors Application: Bioprocess Monitoring, Quality Control, Process Optimization, Data Analytics End User: Pharmaceuticals, Biotechnology, Food & Beverage, Chemicals Measurement Type: Mass Flow, Volume Flow, Level Measurement, Temperature Measurement |
| Companies Covered | Thermo Fisher Scientific, Hamilton Company, Mettler Toledo, Endress+Hauser, PendoTECH, optek-Danulat, Broadley-James, Sartorius, Applikon Biotechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Measurement Technologies in Downstream Processing Market Shifts & Advancements
Real-time analytical capabilities are migrating from quality control laboratories directly into purification skids, collapsing the traditional separation between process monitoring and release testing. This integration demands new sensor architectures that survive CIP/SIP cycles while maintaining drift stability.
Raman spectroscopy is automating protein concentration and aggregate quantification during chromatography elution steps. Biopharma manufacturers with approved biologics license applications are retrofitting existing protein A capture columns with immersion probes. The technology is automating feedback control loops that previously required manual fraction pooling decisions, compressing batch release timelines from days to hours.
EMA's evolving real-time release testing framework is creating compliance complexity for multinationals operating across Atlantic jurisdictions. The guidance requires documented evidence that inline measurements correlate with pharmacopeial reference methods for every critical quality attribute. Small-molecule manufacturers with legacy quality control departments face the steepest organizational adaptation costs.
Service unbundling is separating sensor hardware from validation documentation and ongoing calibration support. CDMO procurement teams now source pressure transducers from one supplier while contracting third-party metrology firms for IQ/OQ protocol execution. This pattern concentrates in North American contract manufacturing where headcount flexibility outweighs integrated vendor relationships.
Measurement Technologies in Downstream Processing Market Segmentation
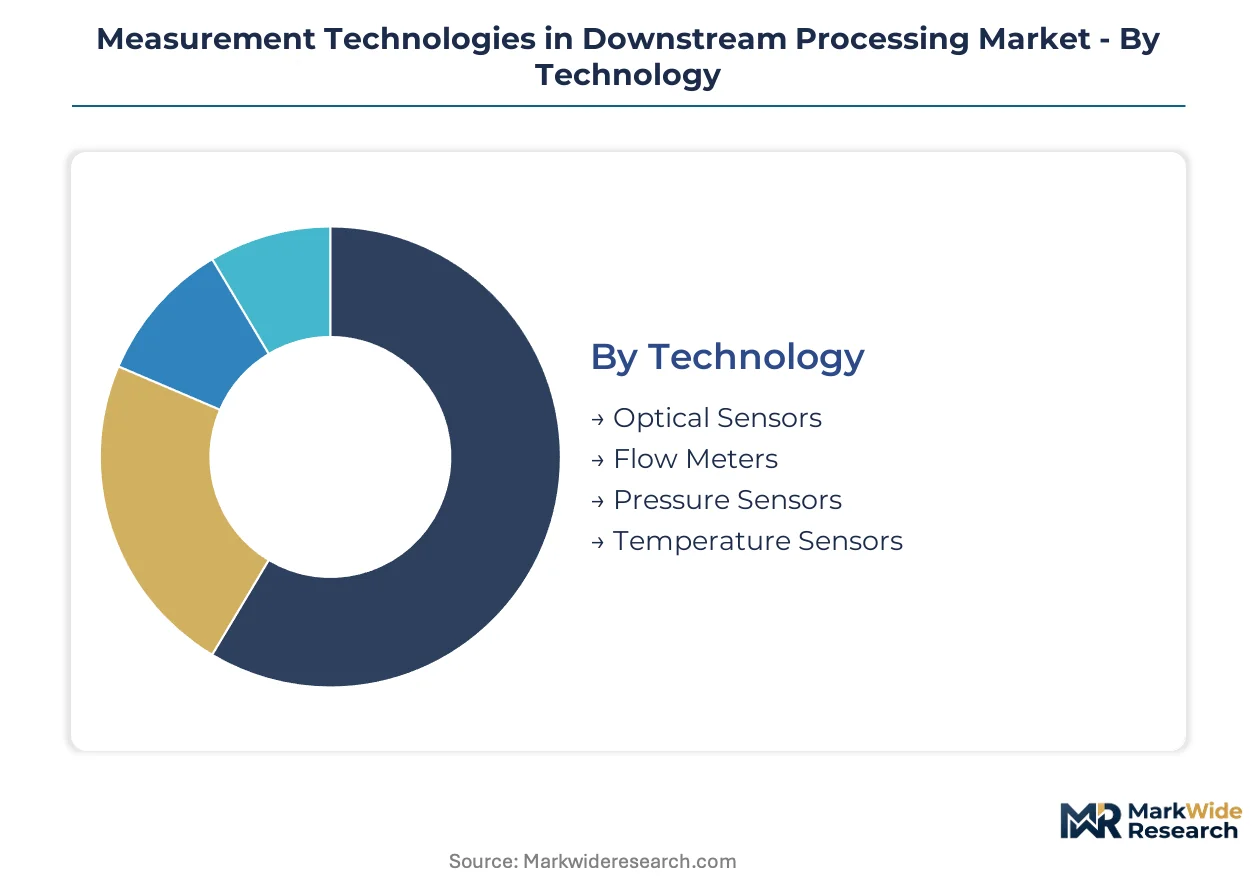
Downstream processing measurement technologies fragment across sensor physics, analytical purpose, and manufacturing context. Each dimension shapes procurement criteria, validation burden, and integration complexity for biopharma operators retrofitting purification infrastructure.
Technology:
Cost tier separates sensor categories: optical systems command premium positioning for multi-parameter analytics, while electrochemical alternatives compete on unit economics for single-point monitoring.
- Optical Sensors:Raman and UV-Vis probes deliver real-time protein concentration, aggregate detection, and buffer composition analysis during chromatography elution. mAb manufacturers in Germany and Massachusetts concentrate procurement for protein A capture monitoring, driven by FDA process analytical technology guidance demanding correlation with offline reference methods.
- Flow Meters:Coriolis and ultrasonic designs measure mass transfer with pulsation-free precision essential for continuous bioprocessing residence time control. CDMOs in Baden-Württemberg prioritize these for connected chromatography-TFF trains where unsteady-state calibration protocols differ from batch configurations.
- Pressure Sensors:Single-use piezoelectric transducers monitor transmembrane pressure in tangential flow filtration cassettes. PendoTECH competes here on validation documentation velocity for contract manufacturers facing compressed batch release timelines.
- Temperature Sensors:RTD and thermocouple probes track thermal stability during CIP/SIP cycles and protein elution steps. Chemical manufacturers leverage these for simpler thermal compliance versus biopharma's multi-attribute requirements.
Optical sensors lead volumes today; flow meters are gaining share fastest in continuous processing retrofits.
Application:
Maturity gradient distinguishes segments: established process monitoring commands installed base, while emerging data analytics applications reshape competitive requirements.
- Bioprocess Monitoring:Inline pH, conductivity, and turbidity sensors transmit real-time data to distributed control systems for automated feedback loops. Gene therapy viral vector purification in Bavaria demands multi-parameter optical monitoring that legacy protein bioprocessing infrastructure cannot deliver.
- Quality Control:At-line protein concentration analyzers and aggregate detection systems bridge process monitoring and release testing. EU MDR validation documentation requirements accelerate replacement of offline workflows with inline alternatives.
- Process Optimization:Sensor networks enabling yield prediction and deviation correction through historical batch record analysis. Machine learning model deployment concentrates among large biopharma with decade-plus manufacturing databases.
- Data Analytics:Chemometric software platforms processing Raman spectroscopy signals for real-time critical quality attribute prediction. CDMO procurement teams increasingly unbundle this from hardware, contracting third-party metrology firms for algorithm validation.
Bioprocess monitoring anchors current deployment; data analytics is expanding most quickly as manufacturers deploy machine learning on accumulated batch records.
End User:
Regulatory stringency stratifies buyers: pharmaceutical and biotechnology operators face GMP validation burdens that food and chemical segments avoid.
- Pharmaceuticals:mAb and small-molecule manufacturers retrofitting legacy purification trains with integrated sensor networks for real-time release testing. EMA's evolving framework creates compliance complexity for multinationals operating across Atlantic jurisdictions.
- Biotechnology:Gene therapy developers building greenfield viral vector facilities with native continuous processing configurations. Hyderabad and Bengaluru CDMOs present retrofit demand lacking integrated sensor infrastructure.
- Food & Beverage:Protein and enzyme purification operations with simpler validation requirements and faster procurement cycles. These buyers prioritize cost efficiency over documentation depth.
- Chemicals:Specialty chemical and catalyst recovery processes employing robust industrial sensor designs without biopharma-specific calibration protocols. Temperature and pressure monitoring dominate here versus multi-parameter optical analytics.
Pharmaceuticals command revenue concentration today; biotechnology is climbing the fastest on gene therapy manufacturing expansion.
Measurement Type:
Integration depth varies: mass flow measurement requires synchronized multi-point coordination in continuous trains, while single-point temperature monitoring remains technically straightforward.
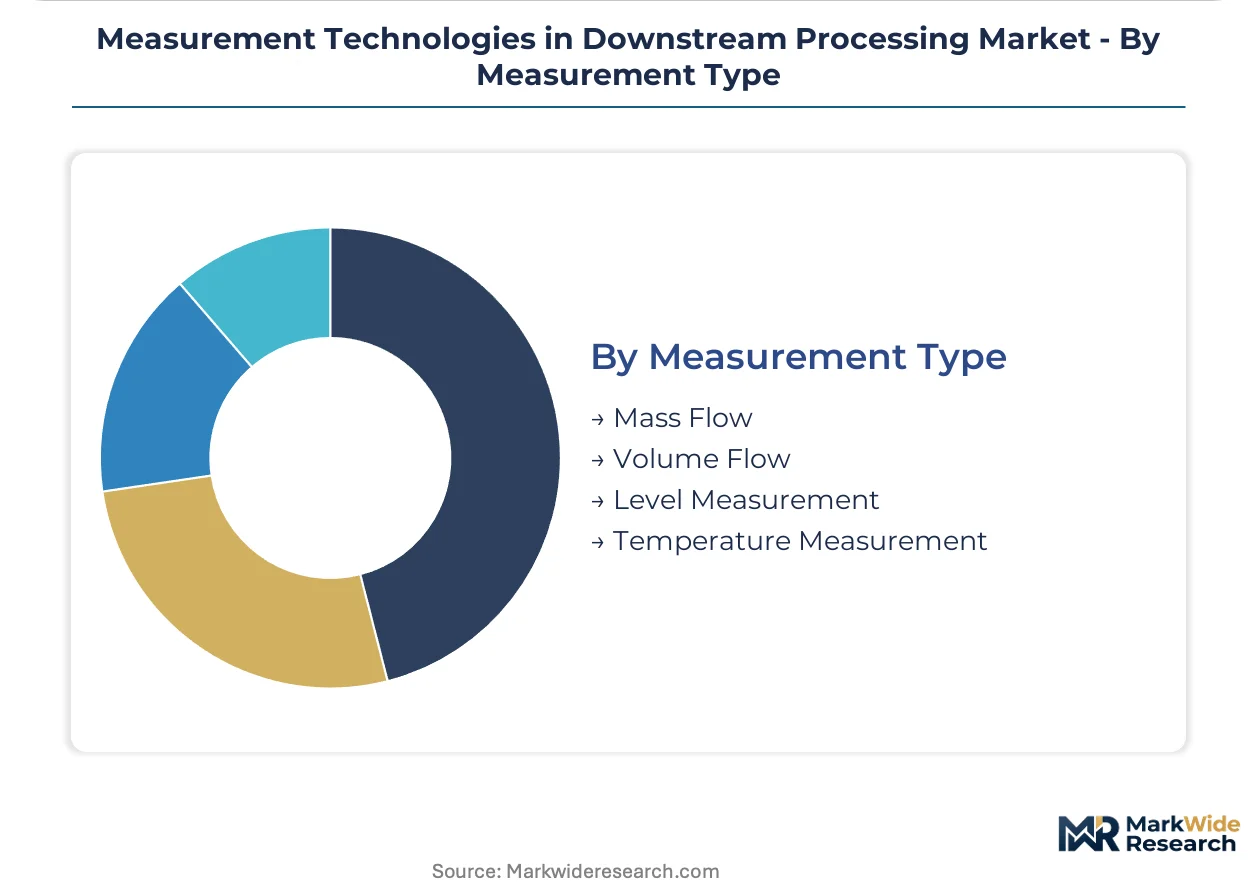
- Mass Flow:Coriolis meters measuring density-corrected mass transfer for precise buffer exchange and protein concentration control. Continuous downstream configurations demand this where batch processing relied on volumetric approximations.
- Volume Flow:Ultrasonic and electromagnetic sensors tracking pump output and column loading rates. Simpler calibration protocols suit legacy distributed control system integration where 1990s-vintage DeltaV installations lack native digital communication for advanced alternatives.
- Level Measurement:Radar and guided-wave sensors monitoring hold tank volumes and chromatography column packing integrity. Chemical manufacturers deploy these for basic inventory management versus biopharma's critical quality attribute linkage.
- Temperature Measurement:RTD probes with drift stability through repeated CIP/SIP cycles. ISO 13485 certification requirements for device components filter supplier base, extending quality management system audit timelines.
Mass flow measurement dominates premium pricing; volume flow sensors see steepest expansion trajectory in retrofit applications prioritizing compatibility with legacy infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metrology talent scarcity concentrates in Germany's Baden-Württemberg and Bavaria clusters, where CDMOs retrofit legacy purification trains with integrated sensor networks. Bioprocessing engineers command premium compensation for combined GMP compliance and chemometric expertise.
Germany
Contract manufacturers in Baden-Württemberg and Bavaria drive demand for multi-parameter optical monitoring in viral vector purification. EU MDR validation documentation requirements accelerate replacement of offline quality control workflows with inline alternatives. Stuttgart and Munich industrial corridors anchor retrofit activity for real-time release testing capabilities.
United States
Massachusetts and California biotech clusters expand gene therapy manufacturing with native continuous processing configurations. FDA process analytical technology guidance mandates parallel offline testing during qualification phases, doubling analytical labor requirements. Greater Boston CDMOs unbundle sensor hardware from validation documentation, contracting third-party metrology firms for IQ/OQ protocol execution.
India
Hyderabad and Bengaluru CDMOs present retrofit demand lacking integrated sensor infrastructure for at-line protein concentration analyzers. The country's national pharmaceutical regulator tightens validation requirements for real-time measurement systems in contract manufacturing. Genome Valley and Electronic City clusters attract foreign sensor suppliers seeking volume scale in biopharma contract manufacturing.
Switzerland
Swissmedic oversight of device component quality management systems filters supplier base through ISO 13485 certification timelines. Basel and Zurich pharmaceutical corridors concentrate demand for optical sensors in mAb purification. Local precision engineering heritage supports drift-stable RTD probes surviving repeated CIP/SIP cycles.
Japan
PMDA alignment with FDA process analytical technology guidance creates compliance complexity for multinationals operating across Pacific jurisdictions. Kansai and Kanto industrial regions deploy Raman spectroscopy for automated feedback control in protein A capture columns. Osaka and Tokyo biotech clusters compress batch release timelines from days to hours through inline analytics.
Measurement Technologies in Downstream Processing Market Competitive Landscape
The competitive structure tilts toward diversified instrumentation conglomerates with chromatography footprints bundling optical sensors. The vendor base spans three tiers: premium-tier integrated system suppliers, mid-tier single-use specialists competing on validation velocity, and industrial sensor fabricators serving adjacent chemical markets. Dominant competitive moves include strategic partnerships between sensor hardware providers and third-party metrology firms, plus backward integration into chemometric software platforms.
Within the diversified instrumentation tier, Thermo Fisher Scientific and Sartorius occupy positions anchoring purification skid integration. PendoTECH exemplifies the single-use specialist archetype competing on documentation speed for contract manufacturers. Mettler Toledo and Endress+Hauser represent industrial sensor fabricators with biopharma-adjacent positioning, while Hamilton Company and Broadley-James sit within the electrochemical probe segment serving legacy distributed control system installations.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Hamilton Company |
| Mettler Toledo |
| Endress+Hauser |
| PendoTECH |
| optek-Danulat |
| Broadley-James |
| Sartorius |
| Applikon Biotechnology |
| Others |
Supply & Pricing Matrix
Captive sensor production by chromatography system integrators anchors supply positions and pricing power for premium optical probes, while contract manufacturers sourcing standalone pressure transducers face procurement lead time extensions from gamma-sterilization validation documentation. This integration divergence separates bundled instrumentation providers competing on skid-level compliance from unbundled component suppliers racing on certificate velocity.
Pricing Analysis
Service unbundling splits the market between hardware-procurement-only transactions and validation-inclusive bundles. Pricing stratifies across premium optical multi-parameter systems, standard electrochemical single-point monitors, and economy-grade temperature probes differentiated by ISO 13485 certification tier and after-sales calibration support. Cost compression in the mid-tier is intensifying because CDMO procurement teams now source sensors from one supplier while contracting third-party metrology firms for IQ/OQ documentation. Biotechnology greenfield developers show least price sensitivity due to real-time release testing mandates; chemical manufacturers demonstrate highest sensitivity with simpler validation requirements.
Supply Chain Analysis
Platinum-group metal electrodes for electrochemical sensors rest on South African and Russian mining operations concentrated in a narrow supplier base. Ruthenium and iridium feedstock, gamma-sterilizable polymer housings, and precision optical fiber assemblies constitute critical input dependencies. Single-source vulnerability concentrates in noble metal refining capacity subject to export restriction risk. Distribution runs through direct OEM relationships for integrated skid manufacturers and distributor networks for standalone component procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EU MDR documentation requirements and FDA process analytical technology guidance are displacing legacy offline workflows with premium inline alternatives.
For Market Incumbents: Extend calibration protocol development capabilities to capture unbundled validation service demand from CDMOs facing compressed batch release timelines. Backward integration into chemometric software platforms defends against standalone analytics entrants. Capacity addition in Baden-Württemberg and Bavaria clusters addresses metrology talent scarcity constraining German retrofit activity.
For New Entrants and Emerging Players: Enter via Hyderabad and Bengaluru CDMO retrofit demand lacking integrated sensor infrastructure for at-line protein concentration analyzers. Machine learning yield prediction applications present white-space opportunity among large biopharma with decade-plus manufacturing databases. Partner with third-party metrology firms for algorithm validation rather than building captive compliance capabilities.
For Investors and Strategic Acquirers: Roll-up economics work for single-use sensor specialists because validation documentation velocity constitutes a defendable moat in contract manufacturing procurement. Platform consolidation across pressure, flow, and optical probe categories captures CDMO preference for reduced vendor management overhead. Watch FDA advancement toward fully validated real-time release pathways as inflection indicator for traditional quality control workflow displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chemometric Software | Captures unbundled analytics demand from CDMOs separating hardware from algorithm validation. |
| ISO 13485 Certification Investment | Qualifies device component suppliers for biopharma procurement lists with 18-24 month audit timelines. |
| Continuous Processing Configuration Partnership | Positions flow meter suppliers for synchronized multi-point measurement in connected chromatography-TFF trains. |
| Third-Party Metrology Firm Alliance | Addresses service unbundling trend where procurement teams source hardware and validation separately. |
| Gene Therapy Viral Vector Application Development | Targets multi-parameter optical monitoring demand that legacy protein bioprocessing sensors cannot deliver. |
Research Methodology
Direct dialogue with bioprocessing engineers, CDMO procurement managers, regulatory affairs specialists, and chromatography system integrators grounded qualitative findings in operational reality. Secondary validation drew from FDA process analytical technology guidance documents, EMA real-time release testing frameworks, ISO 13485 certification databases, and SEC filings of diversified instrumentation providers. Bottom-up sensor shipment analysis triangulated against top-down biopharma capital expenditure patterns across the analysis window.
Segmentation outputs by technology type, application purpose, end-user industry, and measurement integration depth structured the quantitative framework. CAGRs were derived from modeled sensor replacement cycles in legacy retrofit installations versus greenfield continuous processing configurations. Input assumptions incorporated EU MDR implementation timelines, gene therapy manufacturing capacity expansion trajectories, and platinum-group metal price volatility bands.
Inputs from regulatory filing databases and CDMO capital expenditure disclosures were available through the study window; gaps in real-time release testing adoption rates at individual facility level introduce uncertainty bands around biotechnology segment projections. Forecasts reflect documented assumptions regarding calibration protocol standardization and distributed control system integration complexity. A small set of named triggers—FDA real-time release pathway finalization, South African mining export policy shifts, and German metrology talent pipeline expansion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Global DNA/RNA Extraction Kit Market
Biotechnology Equipment
Small-Scale Bioreactors Market
Biotechnology Equipment
Fluorescence Immunoassay Analyzers Market
Biotechnology Equipment
Tissue Microarrayer Market
Biotechnology Equipment
SDS Poly Acrylamide Gel Electrophoresis Market
Biotechnology Equipment
Ultracentrifuges Market
Biotechnology Equipment
Analytical Instrumentation in Life Science Market
Biotechnology Equipment
Restriction Endonucleases Products (REP) Market
Biotechnology Equipment
Micro-Bioreactors Market
Biotechnology Equipment
Plant Genotyping Equipment Market
Biotechnology Equipment
Global Polymerase Chain Reaction (PCR) Consumables Market
Biotechnology Equipment
Cell and Tissue Culture Supplies Market
Biotechnology Equipment
Global Bioprocess Container Market
Biotechnology Equipment
Global Cell Separation Technology Market
Biotechnology Equipment
ELISA POT Assay Kits Market
Biotechnology Equipment
Gel Column Agglutination Test System Market