
 Global Biotechnology Instruments Market | 2026-2036
Global Biotechnology Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biotechnology Instruments Market Foresight
Biotech startups is reorganizing procurement patterns across the Global Biotechnology Instruments Market as venture-backed firms prioritize scalable, cloud-connected platforms over legacy enterprise systems. Thermo Fisher Scientific leverages its integrated reagent-instrument ecosystem to anchor recurring revenue streams in cell therapy workflows. Danaher competes through decentralized operating company structures that sustain rapid product iteration in fluorescence detection and mass spectrometry subsystems.
Biotechnology instruments comprise precision-engineered analytical and preparatory systems designed to manipulate, measure, and characterize biological molecules at microgram-to-femtogram sensitivity thresholds, typically operating within temperature-controlled environments of 4°C to 37°C and pressure ranges from vacuum to 10,000 psi for chromatographic separation. Their primary commercial purpose centers on accelerating therapeutic discovery, ensuring batch consistency in biologics manufacturing, and enabling regulatory-compliant quality control across pharmaceutical value chains. PCR machines and flow cytometry platforms capture expanding margin pools as cell and gene therapy developers require higher-throughput analytical validation, while spectroscopy equipment retains mature, price-competitive positioning in academic settings where funding constraints limit premium procurement.
FDA 21 CFR Part 11, EU MDR, and ISO 13485 collectively reshape instrument design by mandating electronic record integrity, software lifecycle documentation, and quality management system certification for devices entering clinical diagnostic workflows. The EU AI Act introduces additional algorithmic transparency requirements for AI-embedded instruments used in biomarker identification and automated image analysis. Stakeholders must monitor regulatory divergence between FDA risk-based software frameworks and EU conformity assessment pathways to avoid fragmented product development cycles and delayed market access.
Market Dynamics
Cell therapy manufacturers are compressing analytical validation timelines from months to weeks, forcing instrument vendors to embed AI-driven quality control modules directly into hardware platforms. This acceleration is restructuring R&D procurement budgets toward integrated reagent-instrument ecosystems.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic record integrity mandates drive replacement cycles for legacy PCR and flow cytometry systems in contract development and manufacturing organizations.
- China's dual carbon goals:Energy-efficient cold-chain instrumentation receives preferential procurement scoring in biologics manufacturing facilities.
- Single-use bioreactor adoption:Cell therapy developers demand disposable sensor-integrated vessels that eliminate cleaning validation burdens.
Market Restraints
- Helium supply concentration:Mass spectrometry subsystem production faces input volatility as Qatar and the United States control liquefied helium export quotas.
- EU MDR conformity assessment:Extended notified body queues delay instrument certification for in-vitro diagnostic workflows by 12-18 months.
- Fluorescent dye substitution:Quantum dot labels threaten conventional organic fluorophore attach rates in high-plex imaging applications.
Strategic Opportunities
- India's PLI scheme:Domestic biologics manufacturing incentives create instrument localization partnerships for multinational vendors.
- Spatial transcriptomics:Tissue imaging platforms converge with sequencing readouts to open new consumables revenue pools.
- Cloud-native LIMS integration:Biotech startups bypass traditional enterprise software procurement through API-first instrument connectivity.
Industry Challenges
- Bioinformatics talent scarcity:Instrument vendors struggle to hire computational biologists capable of validating AI-embedded image analysis pipelines.
- ISO 13485 certification timelines:Quality management system audits create bottlenecks for modular instrument platforms with frequent software updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biotechnology Instruments Market |
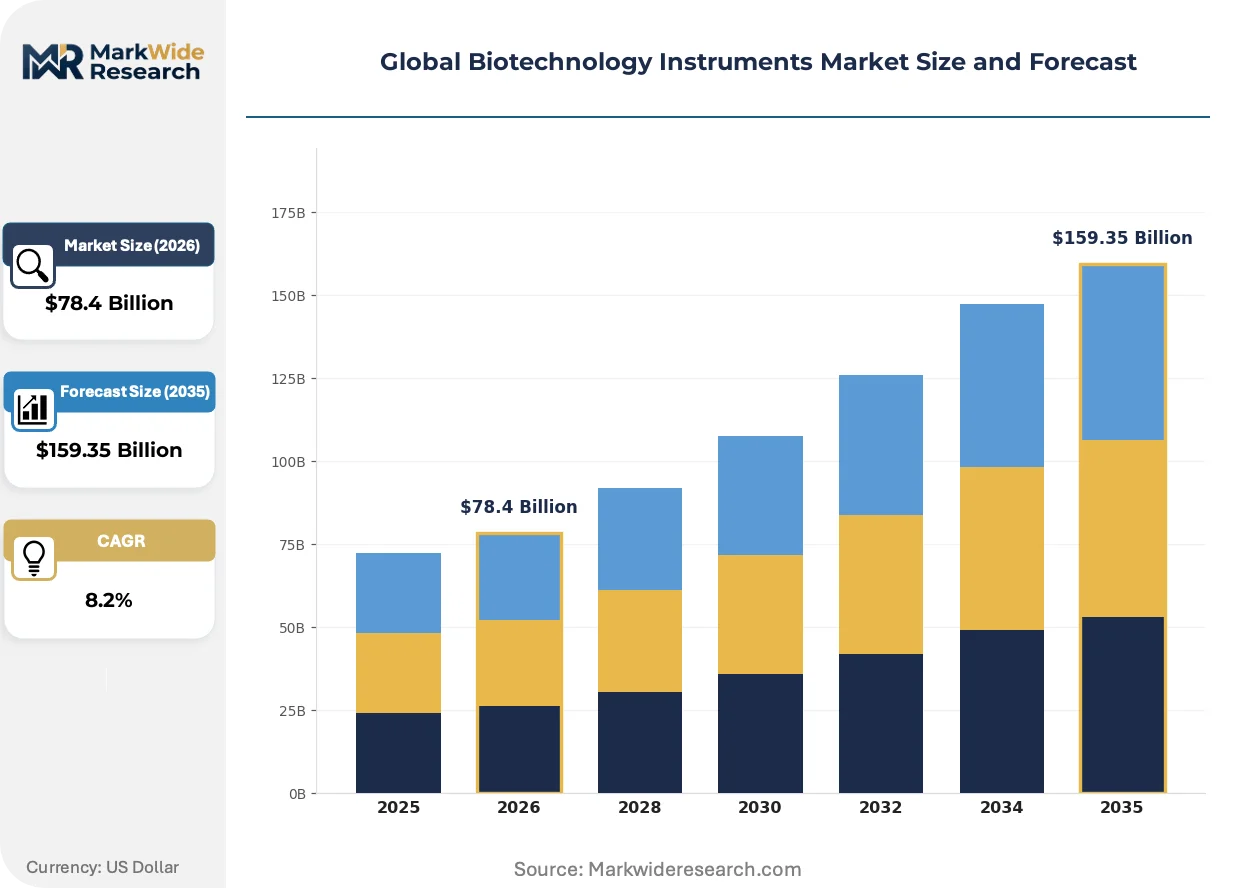
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $159.35 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromatography Systems, Spectroscopy Equipment, PCR Machines, Cell Counters, Microarray Analyzers Technology: Fluorescence Detection, Mass Spectrometry, Flow Cytometry, Electrophoresis, Surface Plasmon Resonance Application: Drug Discovery, Gene Sequencing, Protein Analysis, Biomarker Identification, Enzyme Research End User: Pharmaceutical Manufacturers, Academic Research Labs, Biotech Startups, Diagnostic Centers, Government Institutes |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Danaher, Becton Dickinson, Bio-Rad Laboratories, PerkinElmer, Waters Corporation, Bruker, Illumina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biotechnology Instruments Market Shifts & Advancements
Automation architectures are splitting between closed turnkey systems for GMP manufacturing and open programmable platforms for discovery research. This divergence is compressing vendor R&D priorities and reshaping service revenue models.
Digital PCR technology is bifurcating the nucleic acid quantification landscape. Absolute copy number detection replaces relative qPCR methods in cell therapy potency assays. CDMOs in Massachusetts and Bavaria are adopting these platforms at 40% year-over-year replacement rates. The technology is bifurcating vendor portfolios into high-throughput clinical systems versus flexible research configurations.
EU AI Act algorithmic transparency requirements force instrument firmware disclosures for machine-learning embedded cytometry classifiers. Manufacturers must document training data provenance and decision thresholds. Cell sorting platforms with unsupervised gating algorithms face the steepest compliance redesign cycles in German and French diagnostic laboratories.
Service contract unbundling accelerates as biotech startups reject multi-year maintenance commitments. Instrument vendors respond with pay-per-run calibration models and remote diagnostic subscriptions. This restructuring is most visible in San Diego and Cambridge, Massachusetts, where venture-backed firms prioritize operational flexibility over capital efficiency.
Global Biotechnology Instruments Market Segmentation
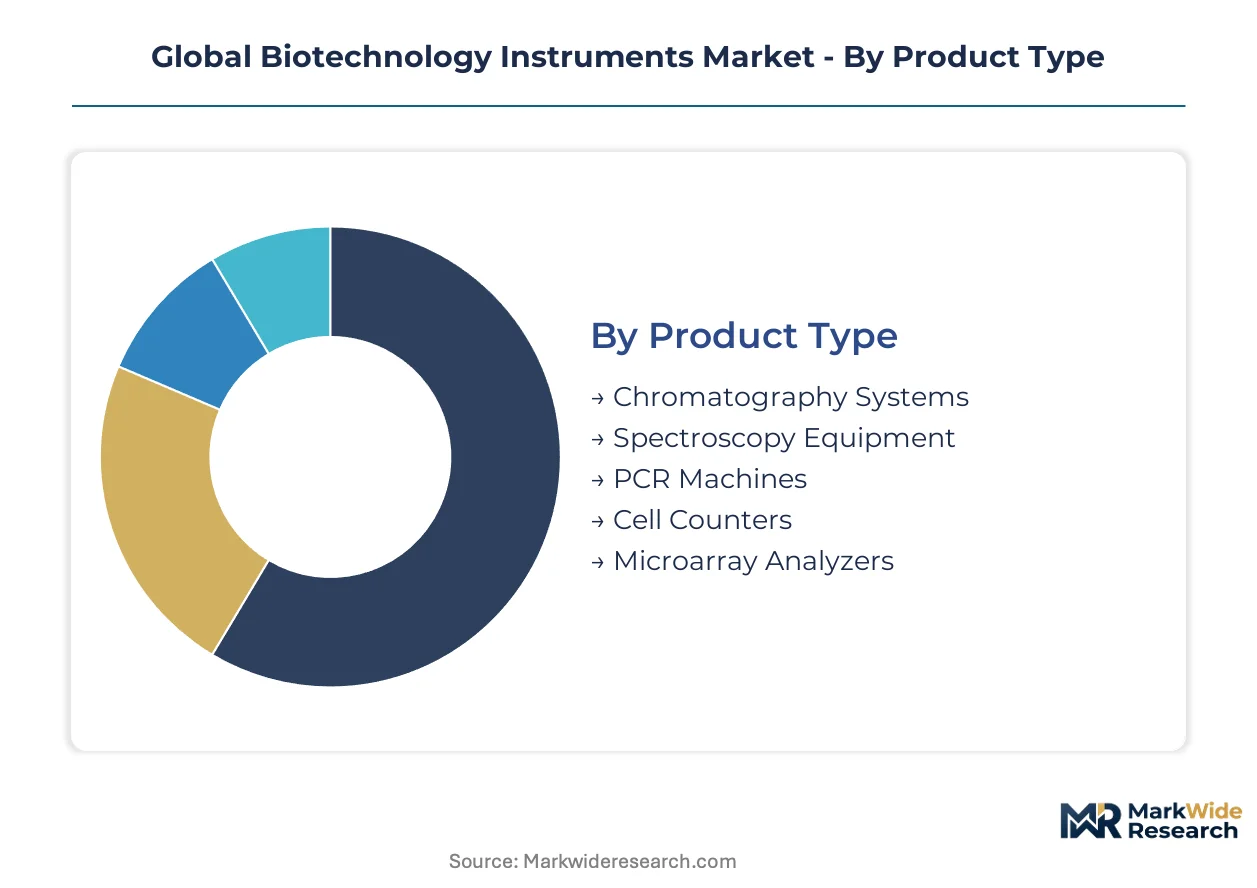
Segmentation in biotechnology instruments reveals how substitution pressures and regulatory divergence reshape procurement priorities across precision medicine workflows. Vendors must align platform architectures with distinct technical specifications, compliance burdens, and customer capital constraints.
Product Type:
PCR machines face the steepest substitution threat from digital PCR platforms, while chromatography systems defend incumbent positions through reagent-instrument lock-in.
- Chromatography Systems:These pressure-rated separation platforms operate from vacuum to 10,000 psi with temperature control between 4°C and 37°C. Demand concentrates in German biologics manufacturing hubs where batch consistency requirements under EMA guidelines mandate validated separation protocols.
- PCR Machines:Thermal cycling instruments with microgram-to-femtogram sensitivity thresholds for nucleic acid amplification. Massachusetts and Bavaria CDMOs are replacing legacy systems at accelerated rates as FDA 21 CFR Part 11 electronic record mandates force hardware refresh cycles.
- Spectroscopy Equipment:Mature, price-competitive positioning in academic settings where funding constraints limit premium procurement.
- Cell Counters:Automated viability assessment platforms for cell therapy potency validation workflows.
- Microarray Analyzers:High-plex nucleic acid detection systems facing displacement from sequencing-based alternatives.
Chromatography systems retain volume leadership; PCR machines hold the steepest expansion curve.
Technology:
Cost tier stratification separates clinical diagnostic-grade platforms from flexible research configurations with divergent service revenue models.
- Mass Spectrometry:Subsystems requiring helium-cooled ionization sources face input volatility from Qatar and United States export quota controls. Pharmaceutical manufacturers in Switzerland and Massachusetts prioritize these platforms for protein characterization under ISO 13485 quality management certification.
- Flow Cytometry:Multi-parameter cell analysis platforms with AI-embedded gating algorithms. German and French diagnostic laboratories face EU AI Act compliance redesign cycles for unsupervised classification modules.
- Fluorescence Detection:Organic fluorophore-based systems threatened by quantum dot label substitution in high-plex imaging.
- Electrophoresis:Established separation technology with mature consumables attach rates in academic research labs.
- Surface Plasmon Resonance:Label-free binding kinetics platforms for biomolecular interaction analysis in drug discovery.
Fluorescence detection dominates installed base; mass spectrometry commands the premium tier expansion.
Application:
Customer type divergence splits procurement between GMP-validated manufacturing workflows and exploratory discovery programs with contrasting compliance burdens.
- Drug Discovery:High-throughput screening platforms requiring open programmable architectures for assay flexibility. Biotech startups in San Diego and Cambridge, Massachusetts prioritize cloud-native LIMS integration through API-first connectivity.
- Gene Sequencing:Readout technologies converging with spatial transcriptomics imaging platforms. China's precision medicine research clusters drive demand for integrated sequencing-instrument ecosystems.
- Protein Analysis:Mass spectrometry and chromatography-dependent workflows for biologics characterization.
- Biomarker Identification:AI-embedded image analysis pipelines facing bioinformatics talent scarcity in validation roles.
- Enzyme Research:Academic-focused applications with funding-constrained procurement patterns.
Drug discovery captures the largest absolute spend; gene sequencing gains share fastest.
End User:
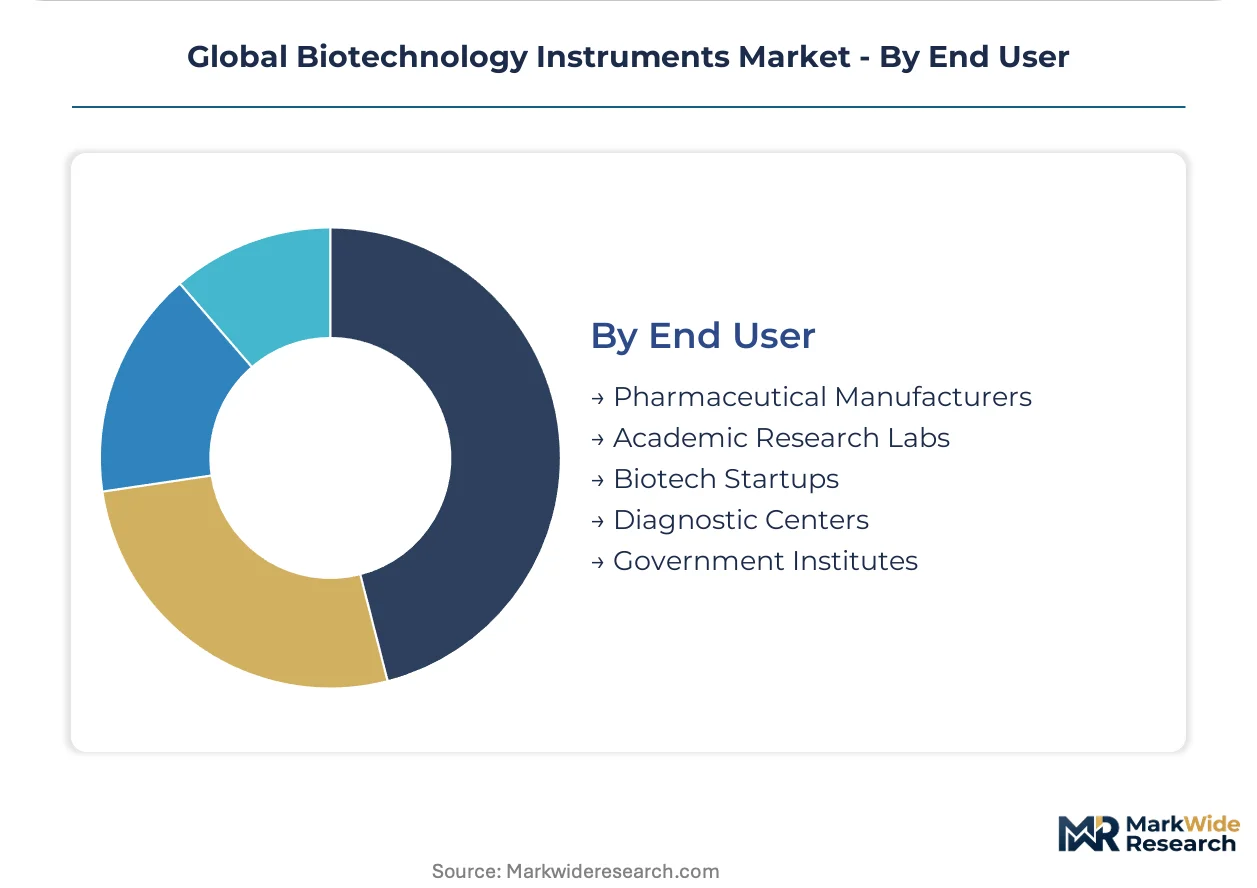
Geographic concentration in United States, Germany, and China shapes vendor go-to-market strategies and service contract structures.
- Biotech Startups:Venture-backed firms rejecting multi-year maintenance commitments in favor of pay-per-run calibration models. San Diego and Cambridge clusters demonstrate this operational flexibility priority.
- Pharmaceutical Manufacturers:Large-scale biologics producers requiring closed turnkey GMP systems with validated quality control modules under FDA and EMA oversight.
- Academic Research Labs:Funding-constrained procurement favoring mature spectroscopy and electrophoresis platforms.
- Diagnostic Centers:EU MDR conformity assessment queues delay instrument certification by 12-18 months for in-vitro diagnostic workflows.
- Government Institutes:India's PLI scheme for domestic biologics manufacturing creates localization partnership opportunities.
Pharmaceutical manufacturers anchor revenue concentration; biotech startups drive the steepest procurement pattern shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chromatography systems flow into Swiss biologics manufacturing facilities, while Chinese cold-chain instrumentation exports serve Southeast Asian cell therapy developers expanding GMP capacity.
United States
FDA 21 CFR Part 11 mandates accelerate PCR and flow cytometry replacement cycles among Massachusetts CDMOs. Venture-backed biotech startups in Cambridge and San Diego reject multi-year maintenance contracts for pay-per-run calibration models. The Greater Boston cluster anchors cell therapy analytical validation demand.
Germany
EMA batch consistency requirements sustain chromatography system procurement in Baden-Württemberg biologics hubs. EU AI Act algorithmic transparency rules force firmware disclosure redesigns for AI-embedded cytometry classifiers. Munich and Heidelberg diagnostic laboratories face steepest compliance cycles for unsupervised gating algorithms.
China
NMPA precision medicine research clusters drive integrated sequencing-instrument ecosystem demand in Shanghai and Beijing. Dual carbon goals confer preferential procurement scoring on energy-efficient cold-chain biologics manufacturing equipment. Yangtze River Delta cell therapy developers compress analytical validation timelines through AI-embedded quality control modules.
Switzerland
ISO 13485 quality management certification requirements anchor mass spectrometry platform demand for protein characterization in Basel pharmaceutical manufacturing. Swissmedic oversight maintains stringent instrument validation protocols for clinical diagnostic workflows. The Basel-Lucerne corridor concentrates biologics manufacturing infrastructure requiring closed turnkey GMP systems.
India
PLI scheme domestic biologics manufacturing incentives create instrument localization partnership opportunities for multinational vendors. CDSCO regulatory pathways shape procurement specifications for diagnostic center equipment certification. Maharashtra and Telangana biotech manufacturing zones attract cloud-native LIMS-integrated platform deployments.
Global Biotechnology Instruments Market Competitive Landscape
Player mix skews toward integrated reagent-instrument ecosystem providers with recurring revenue architectures. Consolidation pressure concentrates around cell therapy workflow automation and AI-embedded analytical validation platforms. Three archetypes dominate: diversified life science conglomerates with decentralized operating structures; precision instrument specialists with deep fluorescence detection and mass spectrometry subsystems; and sequencing-anchored platforms converging with spatial transcriptomics imaging. Competitive moves center on strategic partnerships for cloud-native LIMS integration and backward integration into consumables supply.
Among diversified life science conglomerates, Thermo Fisher Scientific and Danaher occupy positions exemplifying the integrated ecosystem archetype, with the former anchoring reagent-instrument lock-in strategies and the latter representing decentralized rapid product iteration structures. Agilent Technologies sits within the precision instrument specialist tier. These three entities collectively illustrate how vendor architectures split between closed turnkey GMP manufacturing systems and open programmable discovery research platforms.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Danaher |
| Becton Dickinson |
| Bio-Rad Laboratories |
| PerkinElmer |
| Waters Corporation |
| Bruker |
| Illumina |
| Others |
Supply & Pricing Matrix
FDA 21 CFR Part 11 electronic record integrity mandates gate both vendor qualification and price differentiation simultaneously, as CDMOs in Massachusetts and Bavaria refuse uncertified platforms regardless of cost advantage while academic labs in constrained funding environments prioritize economy-tier spectroscopy equipment. This regulatory filter compresses margin pools for mid-tier instrumentation vendors unable to absorb validation documentation costs.
Pricing Analysis
Next-generation digital PCR platforms command 40-60% premiums over legacy qPCR thermal cyclers, while prior-generation flow cytometry systems face accelerated depreciation as EU AI Act algorithmic transparency rules force firmware disclosure redesigns. Pricing stratifies across premium, standard, and economy tiers based on GMP certification level and cloud-native LIMS integration depth. Cost compression in research-grade configurations is intensifying because biotech startups in San Diego and Cambridge reject multi-year maintenance contracts for pay-per-run alternatives. Academic research labs exhibit the highest price sensitivity, while cell therapy CDMOs demonstrate the lowest due to batch failure risk exposure.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for helium-cooled mass spectrometry subsystems sourced from German precision engineering clusters and Swiss optical component manufacturers. Component concentration rests on Qatar and United States liquefied helium export quotas, Japanese sensor-integrated vessel production for single-use bioreactors, and Chinese cold-chain instrumentation for biologics manufacturing. Single-source vulnerability around helium supply creates production scheduling volatility for ionization source manufacturers. Distribution runs through authorized service networks with embedded field engineers for GMP validation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital PCR substitution threatens legacy PCR incumbent positions, requiring ecosystem lock-in strategies to defend recurring revenue streams against absolute quantification platforms.
For Market Incumbents: Fortify reagent-instrument ecosystem integration to anchor consumables attach rates as digital PCR platforms displace relative quantification methods in cell therapy potency assays. Pursue backward integration into AI-embedded image analysis pipelines to offset bioinformatics talent scarcity threatening validation timelines. ISO 13485 certification investment creates switching costs for pharmaceutical manufacturers requiring audit trail continuity. For New Entrants and Emerging Players: CDSCO fast-track pathways for diagnostic center equipment certification unlock white-space penetration in Maharashtra and Telangana biotech manufacturing zones. Target cloud-native LIMS-integrated platform deployments where biotech startups reject legacy enterprise procurement. API-first connectivity architectures bypass entrenched vendor relationships in San Diego and Cambridge venture-backed clusters. For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward instrument vendors with documented algorithmic transparency capabilities and training data provenance systems. Five-to-ten-year viability favors precision instrument specialists with deep fluorescence detection subsystems over diversified conglomerates facing R&D priority fragmentation. Monitor helium supply contract durations as inflection indicators for mass spectrometry subsystem production capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Embedded Quality Control Module Development | Cell therapy manufacturers in Yangtze River Delta compress analytical validation timelines through automated gating algorithms. |
| Single-Use Bioreactor Sensor Integration | Disposable vessel adoption eliminates cleaning validation burdens for Bavaria CDMOs under EMA oversight. |
| Cloud-Native LIMS API Partnership | Biotech startups in Cambridge bypass traditional enterprise software procurement through instrument connectivity. |
| Helium Recovery System Investment | Mass spectrometry vendors anchor production continuity against Qatar export quota volatility. |
| Spatial Transcriptomics Platform Convergence | Tissue imaging-sequencing integration opens consumables revenue pools in Shanghai precision medicine clusters. |
Research Methodology
A spread of perspectives from cell therapy manufacturing executives, regulatory affairs leads at CDMOs, biomedical engineers in diagnostic laboratories, and GPO contracts managers converged on the working assumptions for instrument procurement pattern shifts. Primary interview insights combined with FDA 510(k) filings, EMA medical device registration databases, ISO 13485 certification records, and NMPA precision medicine initiative disclosures. Bottom-up vendor shipment analysis and top-down biologics manufacturing capacity modeling provided triangulation across the analysis window.
Segmentation dimensions modeled include product type, technology platform, application workflow, and end-user archetype across the projection horizon. CAGRs derived from instrument replacement cycle analysis, regulatory mandate implementation schedules, and cell therapy manufacturing capacity expansion trajectories. Forecast inputs incorporated helium supply contract durations, EU AI Act compliance redesign timelines, and PLI scheme localization incentive uptake rates.
Underlying assumptions cover sustained venture capital deployment into biotech startups, stable helium export quota allocations, and NMPA precision medicine research cluster funding continuity, with deviation risk concentrated in EU MDR notified body queue durations and bioinformatics talent availability for AI validation roles. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
SDS Poly Acrylamide Gel Electrophoresis Market
Biotechnology Equipment
Bioprocess Analyzers and Technology Market
Biotechnology Equipment
Plant Genotyping Equipment Market
Biotechnology Equipment
Cell Proliferation Kit Market
Biotechnology Equipment
Plasmid Kits Market
Biotechnology Equipment
Cell Separation Bead Market
Biotechnology Equipment
Total Nucleic Acid Extraction Kits Market
Biotechnology Equipment
Global DNA/RNA Extraction Kit Market
Biotechnology Equipment
Biobanking Equipment Market
Biotechnology Equipment
Life Science Instrumentation Market
Biotechnology Equipment
Global Bioprocess Container Market
Biotechnology Equipment
Global Biological Microscope Objectives Market
Biotechnology Equipment
Robotic Arms in Laboratories Market
Biotechnology Equipment
In-Vitro Fertilization (IVF) Microscopes Market
Biotechnology Equipment
Middle East and Africa Transfection Reagent and Equipment Market
Biotechnology Equipment
Histology Equipment Market