
 Tissue Engineered Skin Substitute Market | 2026-2036
Tissue Engineered Skin Substitute Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Engineered Skin Substitute Market Intelligence
The rising prevalence of diabetic ulcers and other chronic wounds is realigning market focus away from primarily burn treatment. This shift influences product development and commercial strategies. Integra LifeSciences Corporation leverages its portfolio in regenerative medicine for both surgical reconstruction and chronic wound care. Organogenesis Inc. specializes in bio-active wound healing products, while Smith & Nephew plc competes with its advanced wound management solutions.
Tissue engineered skin substitutes are advanced medical products designed to replace or promote the regeneration of damaged skin. These constructs can be acellular, using a scaffold to guide host cell integration, or cellular, containing living keratinocytes and fibroblasts. Their primary purpose is to provide temporary or permanent coverage for wounds. Acellular matrices represent a significant product segment due to their longer shelf life, while allogeneic grafts are critical in burn centers for immediate, large-area coverage.
Regulatory pathways for these biologics are stringent, governed by bodies like the US FDA and the EMA in Europe. In Japan, the PMDA oversees approval, with all agencies demanding extensive clinical data on safety and efficacy. These regulations directly impact time-to-market and development costs for new products. Navigating the different reimbursement policies for cellular versus acellular products will determine commercial success for manufacturers.
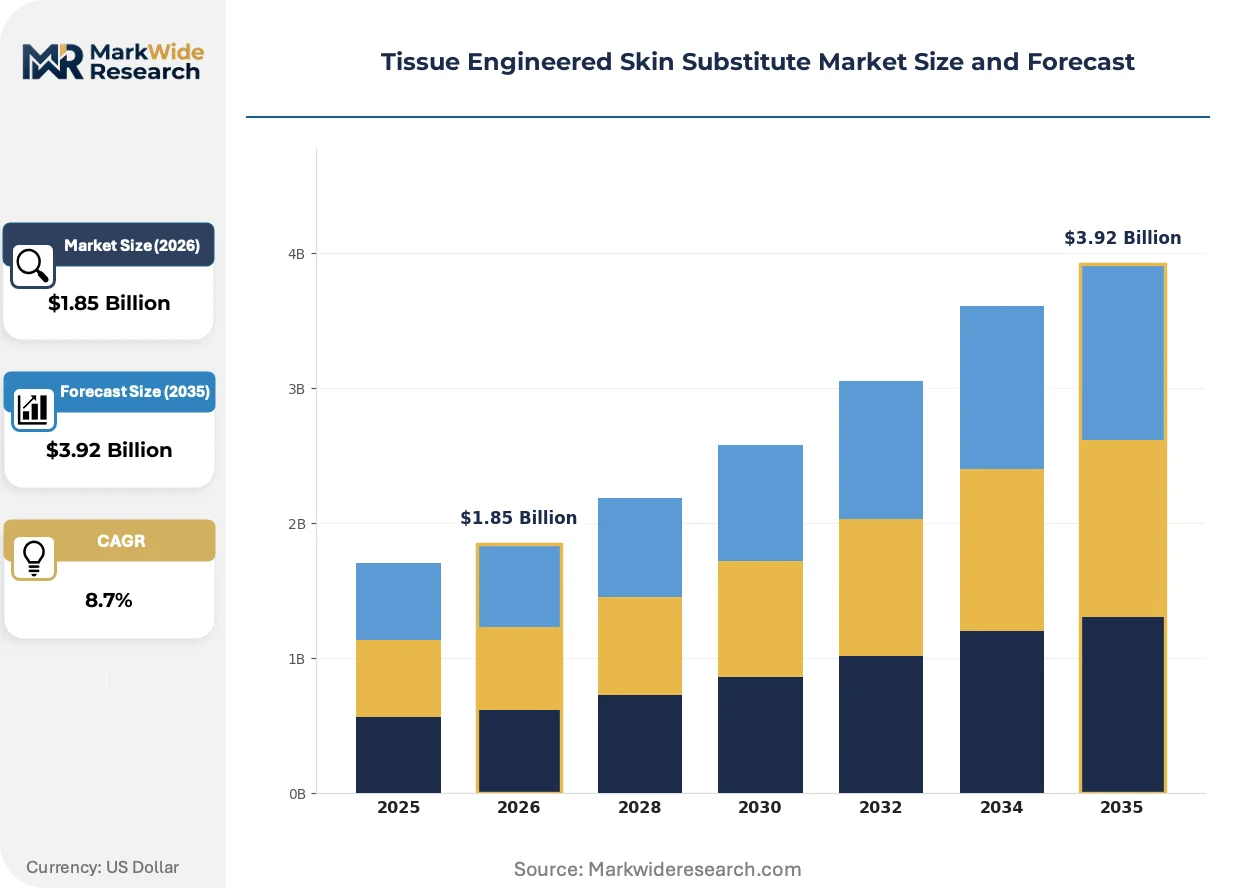
Market Dynamics
The market's central dynamic is the growing clinical demand for chronic wound solutions, particularly for diabetic ulcers, which is pulling product development away from its historical focus on acute burn care and toward scalable, longer-shelf-life products.
Growth Catalysts
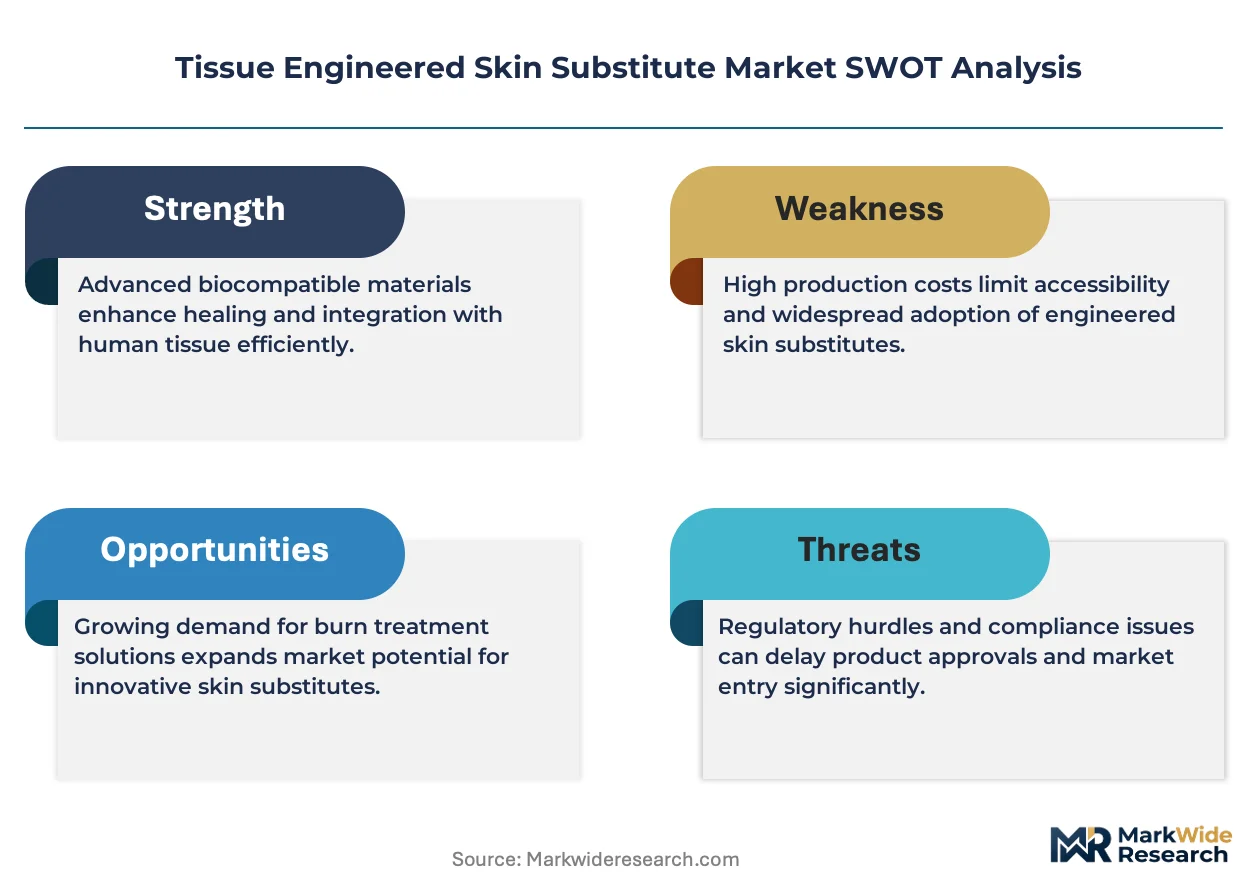
- 3D Bioprinting:This technology enables vascularized, multi-layered skin constructs, improving outcomes for complex wounds and moving beyond simple bilayer grafts.
- Chronic Wound Burden:Rising global diabetes prevalence directly increases the patient population for diabetic foot ulcers, driving sustained demand in specialized wound care centers.
- Regulatory Incentives:The US FDA's RMAT designation offers an expedited pathway for regenerative therapies, shortening time-to-market for novel skin substitutes.
Market Restraints
- High Production Cost:The manufacturing complexity of cellular grafts leads to high prices, restricting adoption to cases with strong reimbursement support.
- Stringent Regulations:Extensive clinical data required by the FDA and EMA for biologics approval creates a lengthy and expensive barrier to entry.
- Logistical Constraints:Cellular products have a short shelf-life and require cryogenic storage, complicating inventory management for hospitals outside major hubs.
Strategic Opportunities
- New Geographies:Expanding into Latin American and Southeast Asian markets with improving healthcare infrastructure offers significant growth potential beyond established regions.
- Novel Applications:Adapting tissue engineering platforms for non-dermal uses like corneal regeneration or oral mucosal repair opens new high-value therapeutic areas.
- Combination Therapies:Integrating antimicrobial agents into scaffolds creates next-generation products with enhanced healing properties and clear product differentiation.
Industry Challenges
- Reimbursement Navigation:Inconsistent reimbursement policies for cellular versus acellular products across different healthcare systems in the US and Europe create significant commercialization challenges.
- Clinical Skills Gap:A shortage of clinicians trained in the application and post-operative management of advanced biologics limits the adoption of these products outside of major burn centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Engineered Skin Substitute Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autologous Grafts, Allogeneic Grafts, Xenografts, Composite Substitutes, Acellular Matrices Application: Burn Treatment, Chronic Wound Healing, Surgical Reconstruction, Cosmetic Procedures, Dermatological Therapy End User: Burn Centers, Trauma Clinics, Plastic Surgery Units, Dermatology Clinics, Research Institutes Deployment Mode: Inpatient Facilities, Outpatient Clinics, Specialized Skin Banks, Home Care Settings, Telemedicine Platforms |
| Companies Covered | 3M, Tissue Regenix, Integra LifeSciences Corporation, ConvaTec Group plc, MiMedx Group, Organogenesis Inc, Mölnlycke Health Care, Kerecis, Smith & Nephew plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Engineered Skin Substitute Market Strategic Shifts & Innovations
The convergence of advanced biomaterials with digital manufacturing techniques is transforming tissue engineering. This evolution enables the development of more personalized and biologically functional skin substitutes, shifting the market toward patient-specific solutions for complex wound pathologies.
Three-dimensional (3D) bioprinting allows precise, layer-by-layer deposition of cells and biomaterials to create patient-specific grafts. Specialized research hospitals are pioneering its use for complex reconstructive cases. The technology is expanding into the creation of functional skin appendages like hair follicles, moving beyond simple wound coverage.
Regulatory frameworks from the European Medicines Agency (EMA) for Advanced Therapy Medicinal Products (ATMPs) govern these products. This structure provides harmonized EU market access but demands rigorous long-term follow-up data. Cellular product manufacturers are most impacted, adapting trial designs to meet post-market surveillance requirements.
Hospital purchasing is evolving from upfront unit cost to a total cost-of-care analysis. This shift disrupts traditional sales channels by involving clinical teams and value analysis committees in procurement. The trend is most pronounced in the United States and Germany, where value-based healthcare models incentivize outcomes.
Tissue Engineered Skin Substitute Market Segmentation
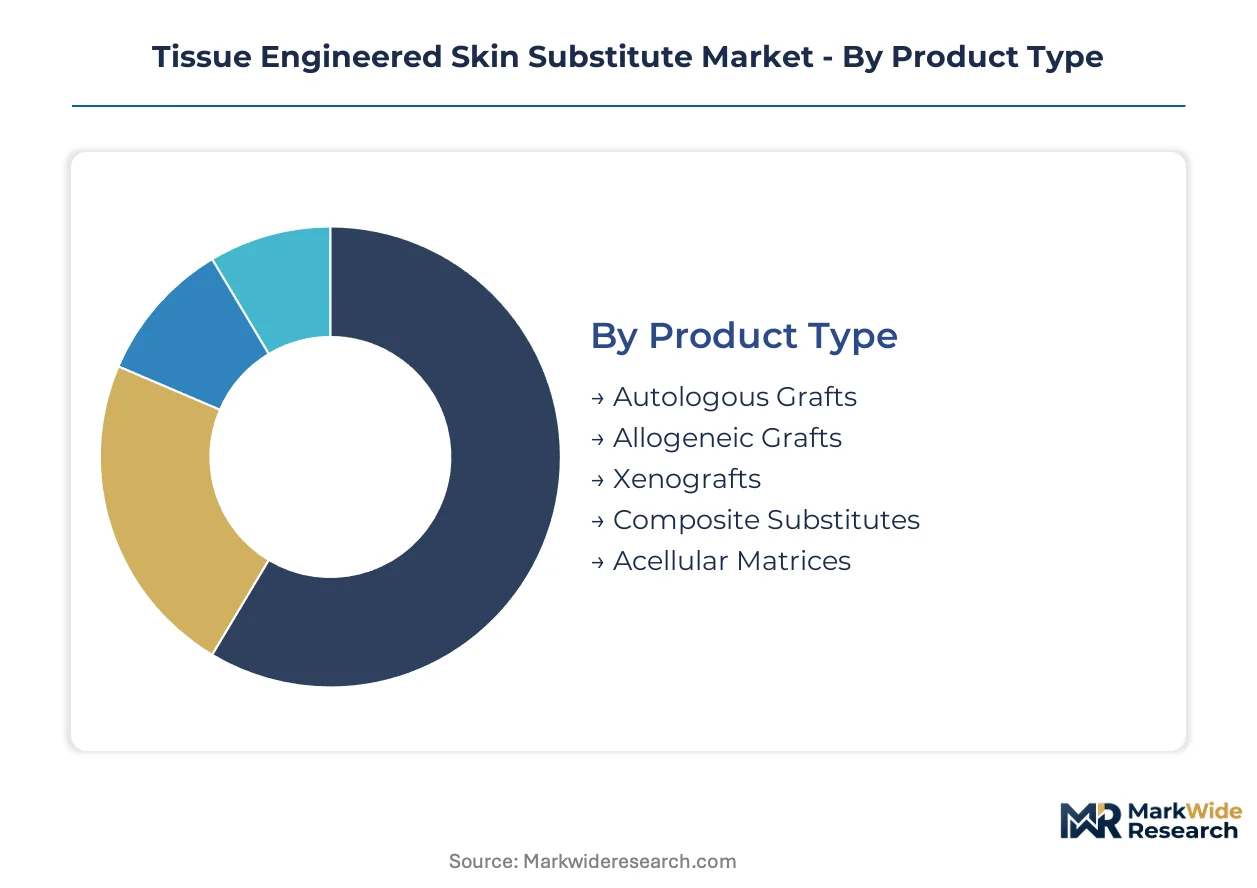
The Tissue Engineered Skin Substitute Market exhibits distinct segmentation reflecting diverse product functionalities and clinical applications. Understanding these segments is crucial for manufacturers to tailor product development and commercial strategies effectively. This market analysis delineates key distinctions across product types, applications, end-users, and deployment modes.
Product Type:
Product type segmentation highlights the trade-off between immediate availability and long-term integration, often correlating with volume versus premium pricing structures.
- Allogeneic Grafts:These cellular products are derived from human donors, providing immediate, large-area wound coverage, particularly critical in burn centers. Demand concentrates in acute care settings due to their ability to rapidly close extensive wounds.
- Acellular Matrices:These constructs utilize decellularized dermal scaffolds from human or animal sources, offering a longer shelf life and guiding host tissue regeneration. Demand is significant in chronic wound healing due to their versatility and reduced immunological response.
- Autologous Grafts:These involve harvesting a patient's own skin cells, cultured for personalized wound repair.
- Composite Substitutes:These combine cellular components with acellular scaffolds, aiming for enhanced biological function and structural integrity.
- Xenografts:Derived from animal sources, typically porcine, these serve as temporary biological dressings for wound protection.
Mature deployment sits with Allogeneic Grafts for acute burn cases. Newer deployment is concentrated in Composite Substitutes, pushing advanced regenerative outcomes.
Application:
Application segmentation reveals the broad clinical utility of skin substitutes, ranging from urgent life-saving interventions to elective cosmetic enhancements, reflecting varying levels of clinical urgency.
- Chronic Wound Healing:This segment addresses persistent wounds like diabetic foot ulcers and pressure ulcers, requiring prolonged treatment and specialized dressings. Demand is driven by the global rise in diabetes prevalence, particularly in specialized wound care centers.
- Burn Treatment:This application focuses on severe thermal injuries, where rapid skin coverage is essential to prevent infection and fluid loss. Demand remains critical in specialized burn units, where allogeneic grafts provide immediate, temporary closure.
- Surgical Reconstruction:This involves using skin substitutes for post-surgical defect repair and trauma reconstruction.
- Dermatological Therapy:These products are utilized for treating various skin conditions and non-healing lesions.
- Cosmetic Procedures:This niche application includes aesthetic skin regeneration and scar revision techniques.
Chronic Wound Healing represents the fastest-growing trajectory, driven by an aging population and increasing chronic disease burden.
End User:
End user segmentation illustrates the diverse healthcare settings where skin substitutes are applied, reflecting varying levels of infrastructure and specialized medical expertise required for product utilization.
- Burn Centers:These highly specialized facilities manage severe burn injuries, requiring immediate access to large quantities of allogeneic and composite skin substitutes. Demand is concentrated in regions with advanced trauma care infrastructure like Germany and Japan.
- Trauma Clinics:These clinics handle acute injuries requiring rapid wound closure and infection prevention, utilizing various skin substitute types. Demand is expanding with the need for efficient wound management in emergency settings.
- Research Institutes:These academic and private institutions focus on developing novel tissue engineering techniques and products.
- Plastic Surgery Units:These units apply skin substitutes for reconstructive procedures and aesthetic enhancements.
- Dermatology Clinics:These clinics use advanced dressings for chronic skin conditions and non-healing wounds.
Volume concentration for complex cases remains with Burn Centers, while Research Institutes drive future product innovation.
Deployment Mode:
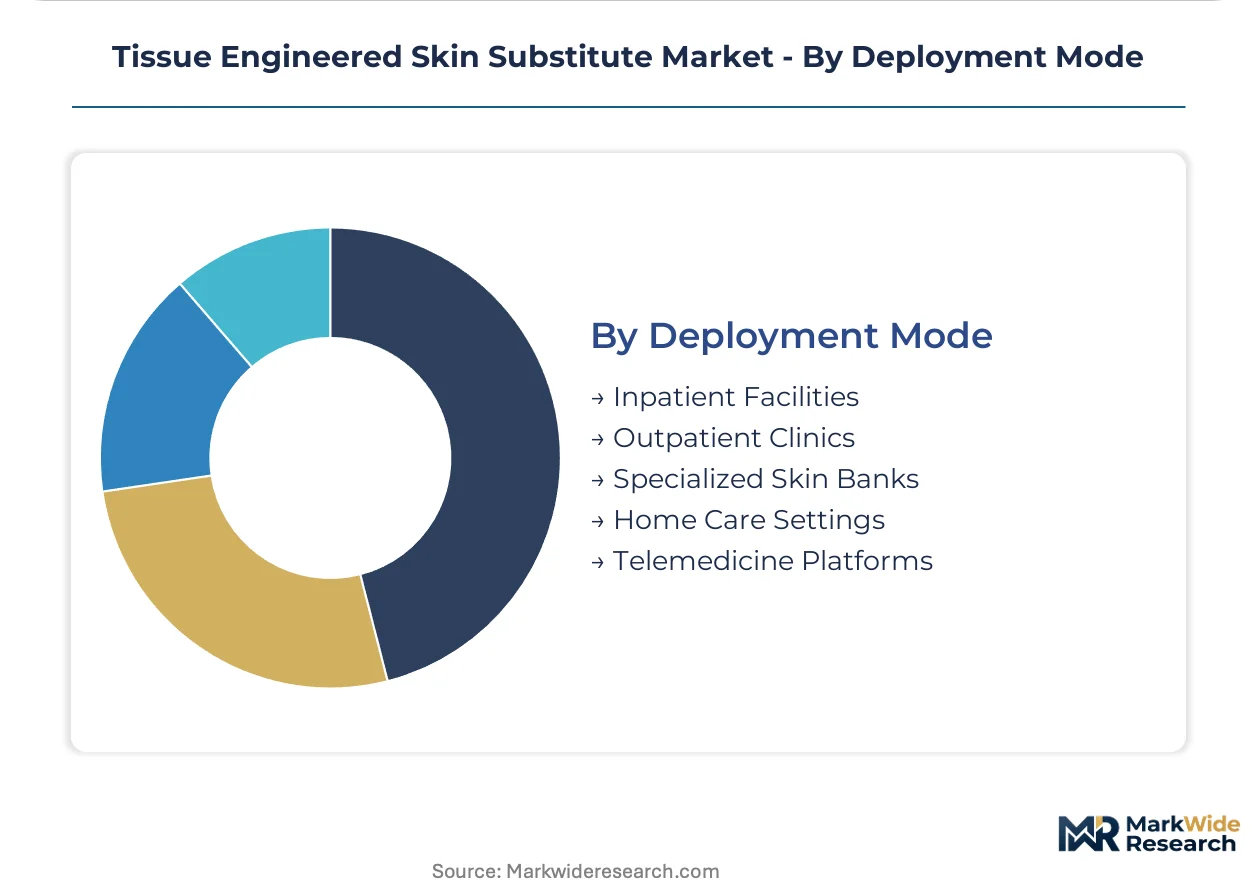
Deployment mode segmentation highlights the evolving landscape of patient care, balancing the need for specialized clinical environments with increasing demands for accessibility and convenience in wound management.
- Inpatient Facilities:These settings, including hospitals and specialized units, manage severe wounds requiring intensive medical oversight and complex application procedures. Demand is primary for critical care and post-operative recovery of extensive injuries.
- Outpatient Clinics:These facilities provide treatment for less severe wounds and follow-up care, offering a more cost-effective and accessible option for patients. Demand is expanding for chronic wound management, particularly diabetic foot ulcers.
- Specialized Skin Banks:These facilities procure, process, and store donated human skin for allograft applications.
- Home Care Settings:This mode involves product application and monitoring by trained caregivers for less complex or recovering wounds.
- Telemedicine Platforms:These platforms facilitate remote consultation and monitoring for wound care, improving access in underserved areas.
Efficiency and patient convenience are driving growth in Outpatient Clinics and Home Care Settings for routine wound management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global tissue engineered skin substitute market demonstrates a distinct production-consumption divide, with advanced economies driving significant demand for specialized treatments. While innovation in regenerative medicine often originates in established research hubs, the burden of chronic wounds is expanding across diverse geographies. This creates specific regional dynamics for product uptake and regulatory adaptation.
United States
The United States market exhibits robust demand for advanced skin substitutes, driven by high diabetic foot ulcer prevalence and an aging population. The US FDA's RMAT designation expedites pathways for novel regenerative therapies. Biotech clusters in Boston and the San Francisco Bay Area concentrate R&D for next-generation skin constructs.
Germany
Germany shows strong demand within its specialized burn centers, reflecting advanced healthcare infrastructure. The EMA stringently oversees the regulatory pathway for biologics, impacting market access for cellular products. Medical technology hubs in Bavaria and North Rhine-Westphalia foster collaborations between research institutions and manufacturers.
Japan
Japan's market for skin substitutes centers on advanced burn treatment and an aging demographic requiring sophisticated wound care. The PMDA stringently regulates these biologics, demanding extensive clinical data for approval. Medical device innovation clusters in Tokyo and Osaka drive development and adoption of new tissue engineering platforms.
China
China presents significant growth due to its large and increasing diabetic population, creating substantial demand for chronic wound solutions. The NMPA's evolving regulatory framework balances innovation with patient safety. Biotech manufacturing centers in the Yangtze River Delta and Pearl River Delta are scaling up domestic production.
India
India experiences a substantial chronic wound burden, particularly from diabetic ulcers, driving demand for accessible skin substitute options. The CDSCO is developing clearer guidelines for regenerative medicine products. Medical technology startups in Bengaluru and Hyderabad explore cost-effective manufacturing techniques and novel biomaterials.
Tissue Engineered Skin Substitute Market Key Industry Players
Top-tier vendors anchor the premium segment, while specialized companies address niche applications and emerging markets. The market exhibits a tiered structure, with established players leveraging broad portfolios and smaller innovators focusing on specific technological advancements. Diversified healthcare corporations and regenerative medicine specialists represent key strategic archetypes. Companies primarily engage in portfolio diversification and strategic partnerships to expand their market reach.
Specialists in regenerative medicine solutions, Integra LifeSciences Corporation and Organogenesis Inc., exemplify companies driving innovation in both chronic wound care and surgical reconstruction. Integra LifeSciences Corporation represents a diversified player, leveraging its broad portfolio across multiple therapeutic areas, from surgical reconstruction to chronic wound management. Organogenesis Inc. occupies a position as a dedicated bio-active wound healing product developer, focusing on advanced cellular and acellular therapies. Concurrently, Smith & Nephew plc sits within the advanced wound management solutions segment, offering comprehensive products for complex wound pathologies globally. These entities collectively anchor the market's focus on advanced biological solutions and patient outcomes across their respective niches, influencing product development trajectories and commercial strategies.
| Leading Market Players |
|---|
| 3M |
| Tissue Regenix |
| Integra LifeSciences Corporation |
| ConvaTec Group plc |
| MiMedx Group |
| Organogenesis Inc |
| Mölnlycke Health Care |
| Kerecis |
| Smith & Nephew plc |
| Others |
Cost & Logistics Intelligence
Biomaterial input costs, influenced by specialized processing and purification, cascade through the tissue engineered skin substitute supply chain, creating distinct pricing tiers for cellular versus acellular products. These costs significantly impact the final product's market accessibility.
Pricing Analysis
Pricing pressure intensifies in the cellular graft segment as manufacturing complexity and stringent regulatory requirements drive up production costs. The market primarily operates on a value-based pricing model, with significant differentiation stemming from the product's functional complexity and regulatory approvals from bodies like the FDA and EMA. Hospitals acquiring allogeneic grafts for acute burn cases exhibit lower price sensitivity due to immediate clinical urgency. Conversely, chronic wound care centers show higher price sensitivity, particularly for longer-term solutions, favoring cost-effective acellular matrices.
Supply Chain Analysis
Skilled workforce availability for advanced biomanufacturing in the United States, Germany, and Japan critically impacts tissue engineered skin substitute supply. The supply chain relies heavily on human donor tissue and specialized biomaterials for scaffold creation. Logistical constraints, particularly the short shelf-life and cryogenic storage requirements for cellular products, present a significant structural risk. Distribution runs through specialized medical device distributors and direct sales channels targeting burn centers and advanced wound care clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tissue engineered skin substitute market is fundamentally a cost-of-compliance story, where stringent regulatory pathways, such as the EMA's ATMP framework, create a significant barrier-to-entry moat for compliant manufacturers. This regulatory rigor ensures product safety and efficacy, shaping competitive dynamics.
For Market Incumbents: Extend existing regenerative medicine portfolios into chronic wound care to mitigate reliance on acute burn treatment, which faces reimbursement challenges. Diversify R&D investments into advanced 3D bioprinting technologies to counter emerging specialist threats. Reinforce channel control by offering comprehensive clinical training and support, thereby leveraging certification investment in new product types. This strategy defends against margin pressure from new technology entrants.
For New Entrants and Emerging Players: Begin with targeted market entry into new geographies like Latin America and Southeast Asia, focusing on chronic wound healing. Penetrate the market by offering cost-effective acellular matrices or novel combination therapies with antimicrobial agents. Focus on specific non-dermal applications, such as corneal regeneration, to establish high-value niches. This approach allows new players to build market share without directly confronting established players in mature burn care segments.
For Investors and Strategic Acquirers: Distressed-cycle entries favor innovative bioprinting startups in the United States and Germany with strong intellectual property. The market shows robust long-term viability over the next decade, driven by chronic wound burden and continuous technological advancements. Target acquisition archetypes include specialized firms with advanced 3D bioprinting platforms or those with novel cellular products nearing EMA or FDA approval. Watch for significant shifts in reimbursement policies for cellular products as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market access for novel cellular constructs requiring extensive safety data. |
| Manufacturing Scale-Up | Reduces per-unit costs for complex grafts, improving market accessibility. |
| Strategic Partnership | Leverages established distribution networks for broader product reach in new regions. |
| Portfolio Diversification | Expands revenue streams beyond burn treatment into high-growth chronic wound care. |
| Reimbursement Strategy | Optimizes market uptake by securing favorable coverage for advanced products. |
Research Approach
Independent corroboration across FDA filings, EMA submissions, and clinical trial registries underwrites the qualitative findings of this study. Primary interviews with R&D directors, regulatory affairs leads, and hospital procurement managers provided critical insights. This data was triangulated with secondary research from healthcare expenditure databases and academic literature. A robust blend of bottom-up and top-down approaches validated market size and growth projections.
Rate-of-change decomposition formed the basis of the analytical framework across the analysis window. The market was segmented by product type, application, end-user, deployment mode, and regional regulatory framework. Compound annual growth rates were derived from historical trends and projected future demand. Key forecast inputs included global diabetes prevalence rates and severe burn injury incidence, directly impacting market trajectory.
Regulatory changes, reimbursement policy shifts, and unforeseen technological breakthroughs are the dominant revision risks for these forecasts. The projections reflect current market assumptions and anticipated developments. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Bioprosthetics Market
Biomedical Engineering
Bioartificial Renal Assist Devices Market
Biomedical Engineering
Bio-Engineered Stent Market
Biomedical Engineering
Bioactive Bone Grafts Market
Biomedical Engineering
Global Bovine-Based Collagen for Biomedical Applications Market
Biomedical Engineering
Medical Biomimetics Market
Biomedical Engineering
Bioabsorbable Osteosynthesis Devices Market
Biomedical Engineering
North America Lab-On-A-Chip and Microarrays (Biochip) Market
Biomedical Engineering
Tissue Expansion Market
Biomedical Engineering
Bionic Eye Market
Biomedical Engineering
Next-Generation Biomanufacturing Market
Biomedical Engineering
Protein Engineering Market
Biomedical Engineering
Argentina Artificial Organs and Bionic Implants Market
Biomedical Engineering
Biological Derived Devices Market
Biomedical Engineering
Self-Inflating Tissue Expander Market
Biomedical Engineering
Europe Bioresorbable Vascular Scaffold Market