
 Mammalian Cell Fermentation Technology Market | 2026-2036
Mammalian Cell Fermentation Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Mammalian Cell Fermentation Technology Market Insights
The capital-intensity divergence between single-use and stainless-steel platform providers is rotating competitive advantage toward flexible manufacturing architectures. Thermo Fisher Scientific leverages its integrated bioproduction portfolio to anchor downstream purification workflows for gene therapy applications. Lonza sustains leadership in contract mammalian cell manufacturing through dedicated large-scale bioreactor capacity across multiple continents. Sartorius AG differentiates via single-use fermentation technologies that reduce cross-contamination risks in multi-product facilities.
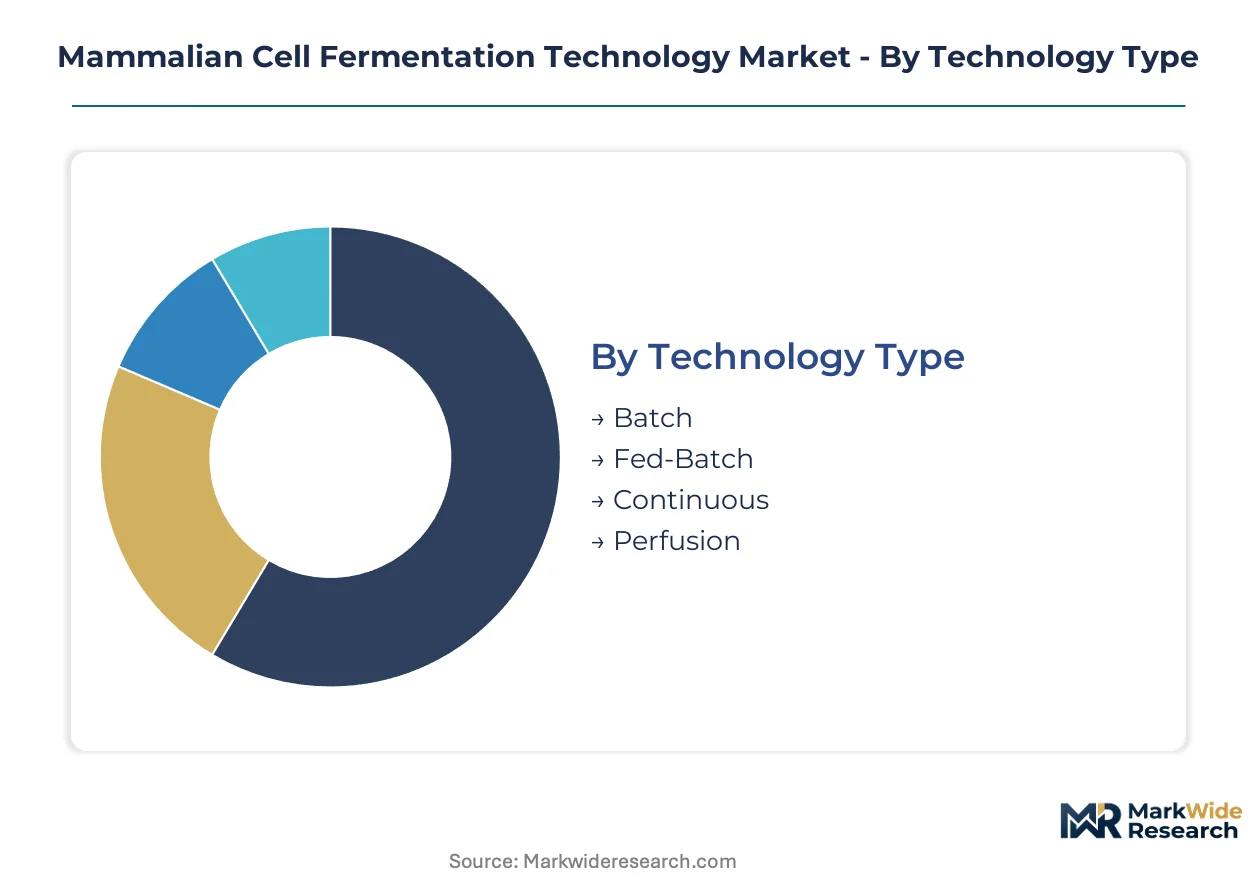
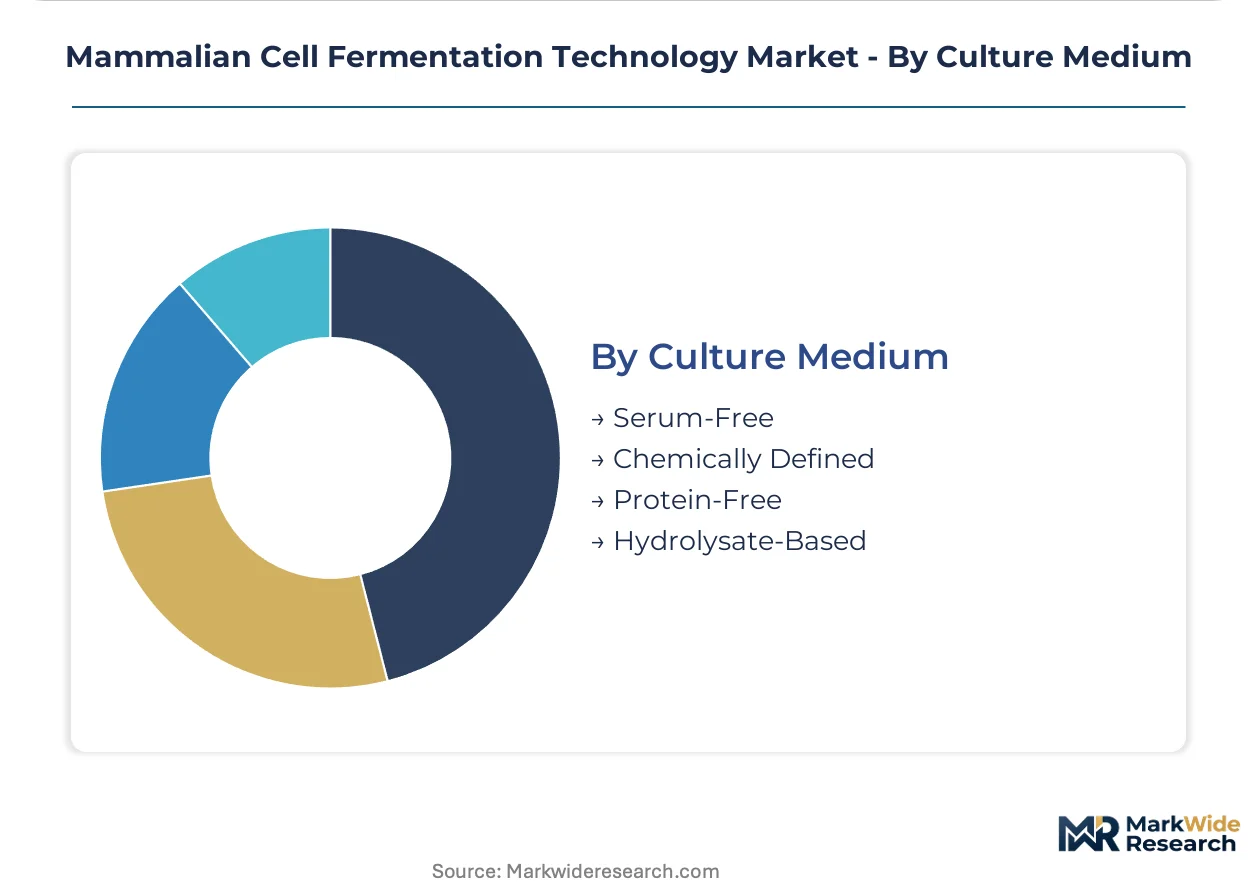
Mammalian cell fermentation technology deploys Chinese hamster ovary (CHO) cells and other mammalian hosts within controlled bioreactor environments to produce complex glycoproteins requiring post-translational modifications unavailable in microbial systems. Fed-batch technology dominates current commercial manufacturing due to established process control and regulatory familiarity, while perfusion systems represent the fastest-expanding segment as manufacturers pursue higher volumetric productivity for antibody-drug conjugates. Chemically defined media formulations are capturing margin pools as serum-free platforms become mandatory for regulatory submissions in major markets.
FDA's process validation guidance and EMA's good manufacturing practice standards for advanced therapy medicinal products shape facility design and quality management requirements for mammalian cell operations. China's NMPA has aligned biomanufacturing inspection protocols with ICH Q5D guidelines on cell line characterization, tightening market access for imported production platforms. Stakeholders must monitor emerging continuous manufacturing guidance from multiple regulators and assess whether perfusion adoption timelines justify capital redeployment from conventional batch infrastructure.
Market Dynamics
Perfusion-based continuous manufacturing is bifurcating competitive advantage between legacy fed-batch incumbents and agile CDMOs willing to redeploy capital into higher-volumetric-productivity platforms. This technology transition compresses batch cycle times while demanding entirely new facility footprints and workforce competencies.
Growth Catalysts
- Antibody-drug conjugate pipeline expansion:Oncology biologics requiring mammalian glycosylation patterns are pulling capacity investments toward CHO-based platforms. Contract manufacturers in the United States, China, and Germany are expanding dedicated suites to capture this demand.
- EMA advanced therapy medicinal product standards:The regulatory framework for cell and gene therapies mandates mammalian production hosts for certain viral vector applications. This creates mandatory platform specifications that microbial systems cannot satisfy.
- Single-use technology maturation:Pre-sterilized, disposable bioreactor assemblies eliminate CIP/SIP validation burdens. Multi-product facilities in Switzerland and Singapore are retrofitting stainless steel suites to reduce cross-contamination risk profiles.
Market Restraints
- Serum and growth factor cost volatility:Chemically defined media formulations require recombinant insulin and transferrin inputs. Supply concentration among a limited supplier base creates margin pressure during raw material shortages.
- Large-scale stainless steel asset stranding:Existing 10,000L+ bioreactor installations face utilization risk as perfusion systems achieve equivalent output at smaller scale. Depreciation schedules now misalign with technology obsolescence timelines.
- Prokaryotic expression system substitution:Microbial platforms from E. coli and yeast continue capturing simpler, non-glycosylated protein markets. This caps mammalian fermentation expansion in biosimilar insulin and growth hormone segments.
Strategic Opportunities
- India biomanufacturing infrastructure gap:CDSCO alignment with ICH Q5D guidelines has not yet translated into domestic large-scale mammalian capacity. Early movers establishing GMP-compliant facilities can capture export-oriented biologics production.
- Continuous manufacturing regulatory tailwind:FDA's emerging guidance on real-time release testing creates precedent for perfusion-based quality assurance. Platforms demonstrating process analytical technology integration gain accelerated review pathways.
- Gene therapy vector production convergence:Adeno-associated virus and lentiviral vector manufacturing requires mammalian host cells. Viral vector demand from clinical-stage gene therapy developers is creating dedicated capacity shortages.
Industry Challenges
- Cell line development scientist scarcity:CHO engineering and clone screening expertise concentrates among experienced bioprocess professionals. Training pipelines have not expanded to match facility construction timelines.
- Legacy MES integration complexity:Perfusion automation requires real-time data architecture that conflicts with established batch record systems. Facility retrofits face validation timeline extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mammalian Cell Fermentation Technology Market |
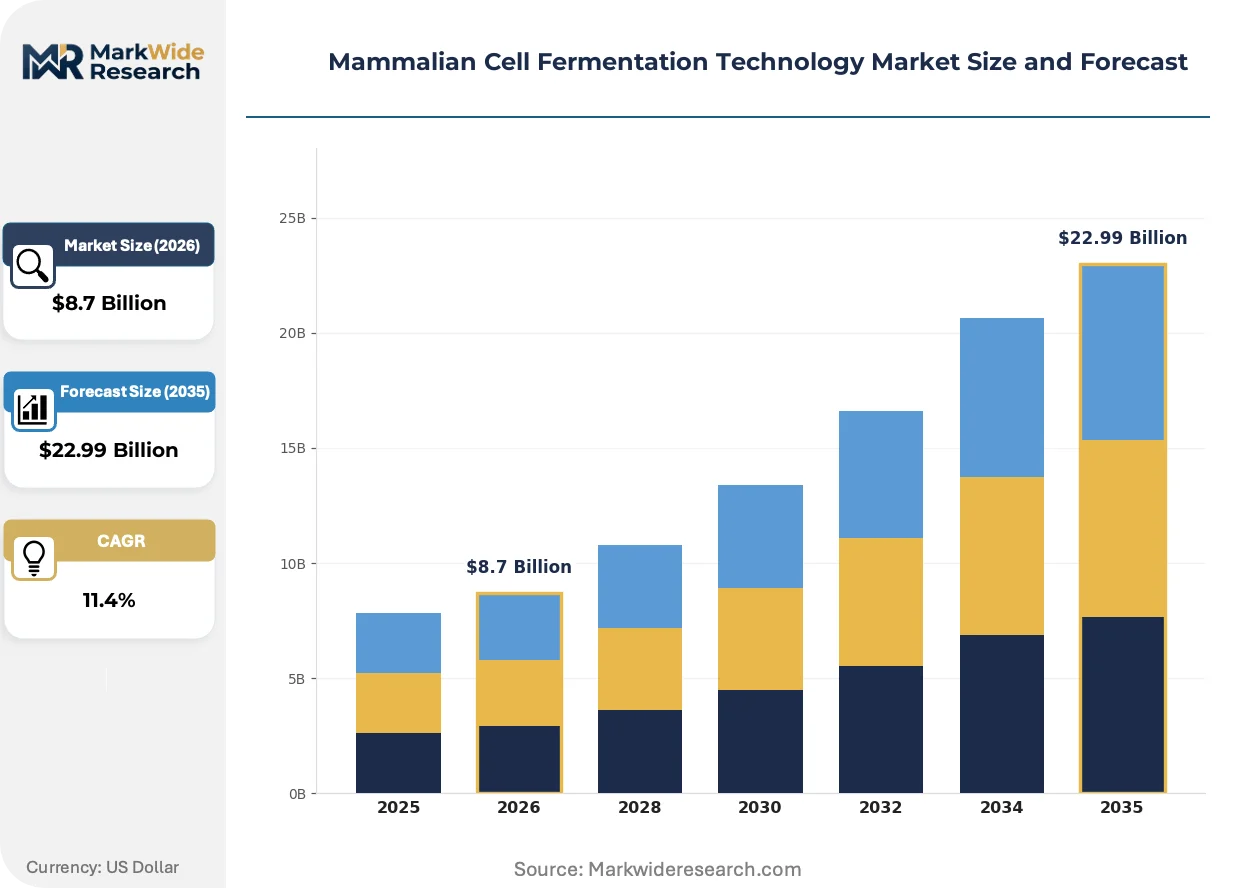
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Batch, Fed-Batch, Continuous, Perfusion Application: Monoclonal Antibodies, Recombinant Proteins, Vaccines, Gene Therapy Products End User: Biopharmaceutical Companies, Contract Development Organizations, Research Institutions, Biosimilar Manufacturers Culture Medium: Serum-Free, Chemically Defined, Protein-Free, Hydrolysate-Based |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Danaher, Lonza, F. Hoffmann-La Roche, Sartorius AG, AstraZeneca, Bristol-Myers Squibb, Amgen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mammalian Cell Fermentation Technology Market Trends and Innovations
Process intensification architectures are compressing facility footprints while multiplying output per square meter. The competitive frontier now centers on who can operationalize continuous processing at commercial scale before regulatory guidance fully crystallizes.
Single-use bioreactor technology is bifurcating the installed base between flexible, multi-product CDMOs and dedicated large-scale stainless steel facilities. Gene therapy developers and emerging biotechs are adopting 2,000L single-use trains for speed-to-clinic priorities. This shift is compressing the economic viability window for conventional batch infrastructure in mid-scale antibody production.
FDA process validation guidance on continuous manufacturing is forcing facility design revisions before final rulemaking. The draft framework requires extended process performance qualification datasets that extend validation timelines. Perfusion adopters in Massachusetts and North Carolina are front-loading statistical process control investments to preempt compliance gaps.
CDMO selection criteria now weight geographic redundancy and dual-sourcing capabilities above unit cost. Large pharma procurement teams are disaggregating master and working cell bank storage across multiple jurisdictions. This pattern is most visible among sponsors with commercial-stage antibody portfolios seeking supply chain resilience against single-site disruption risks.
Mammalian Cell Fermentation Technology Market Segmentation
Technology selection in mammalian cell fermentation carries regulatory permanence. Process changes post-approval trigger comparability protocols that extend timelines and inflate costs. Segmentation strategy must therefore anticipate validation requirements before platform commitment.
Technology Type:
FDA process validation guidance and EMA good manufacturing practice standards differentiate acceptable control strategies across platform architectures.
- Fed-Batch:Dominates commercial antibody manufacturing through established process control frameworks. CHO cell lines in 10,000L stainless steel bioreactors anchor capacity investments across Massachusetts, North Carolina, and Switzerland due to regulatory familiarity with batch record systems.
- Perfusion:Achieves higher volumetric productivity through continuous nutrient exchange and cell retention. Massachusetts and North Carolina facilities are front-loading process analytical technology investments to capture FDA emerging guidance on real-time release testing for continuous manufacturing.
- Batch:Limited to early-stage process development and small-scale clinical supply. Simpler control requirements suit academic technology transfer scenarios.
- Continuous:Represents integrated end-to-end processing architectures combining upstream perfusion with continuous capture chromatography. Regulatory precedent remains under development.
Established volume favors fed-batch; emerging adoption favors perfusion.
Application:
Margin concentration tracks glycosylation complexity requirements that exclude microbial expression alternatives.
- Monoclonal Antibodies:Account for the dominant revenue share requiring mammalian N-linked glycosylation for effector function. Oncology biologics and antibody-drug conjugates are pulling capacity investments toward dedicated CHO-based suites in the United States, China, and Germany.
- Gene Therapy Products:Viral vector manufacturing for adeno-associated virus and lentiviral applications requires mammalian host cells. Clinical-stage gene therapy developers are creating dedicated capacity shortages that command premium pricing.
- Recombinant Proteins:Encompasses erythropoietins, blood factors, and enzyme replacement therapies with established biosimilar competition.
- Vaccines:Cell culture-based influenza and recombinant subunit vaccines utilize mammalian platforms for proper antigen folding.
Commercial maturity concentrates in monoclonal antibodies; pipeline velocity concentrates in gene therapy products.
End User:
Procurement authority is shifting toward large pharma supply chain resilience mandates.
- Contract Development Organizations:Capture demand from emerging biotechs lacking captive manufacturing infrastructure. CDMO selection criteria now weight geographic redundancy and dual-sourcing capabilities above unit cost, with disaggregated master and working cell bank storage across multiple jurisdictions.
- Biopharmaceutical Companies:Vertically integrated manufacturers prioritize process control and intellectual property protection for blockbuster antibody portfolios.
- Biosimilar Manufacturers:Face compressed margins that favor lower-cost platform technologies and open-source cell line alternatives.
- Research Institutions:Drive early-stage process development with limited commercial scale requirements.
Capacity expansion concentrates in contract development organizations; process control investment concentrates in biopharmaceutical companies.
Culture Medium:
Regulatory submission requirements in major markets are eliminating serum-dependent formulations.
- Chemically Defined:Formulations with fully characterized component identities are becoming mandatory for regulatory submissions. Recombinant insulin and transferrin inputs create supply concentration risk among limited supplier bases.
- Serum-Free:Eliminates lot-to-lot variability and infectious agent screening burdens. Transition timing varies by facility validation status and product lifecycle stage.
- Protein-Free:Minimizes immunogenicity risk for certain therapeutic protein applications requiring minimal exogenous protein burden.
- Hydrolysate-Based:Plant-derived peptone mixtures offer cost advantages but introduce characterization complexity that conflicts with regulatory guidance on process consistency.
Regulatory compliance favors chemically defined; cost containment favors hydrolysate-based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and India demonstrate acute price sensitivity toward media formulations and single-use consumables, while purchasers in Switzerland and the United States prioritize regulatory compliance and supply chain redundancy over unit economics.
United States
FDA process validation guidance on continuous manufacturing is accelerating perfusion system adoption among Massachusetts and North Carolina biomanufacturing clusters. The agency's emerging real-time release testing framework is forcing extended process performance qualification timelines. Greater Boston facilities are front-loading statistical process control investments to preempt compliance gaps in viral vector production.
Germany
EMA good manufacturing practice standards for advanced therapy medicinal products are mandating mammalian host specifications that microbial platforms cannot satisfy. The country's national pharmaceutical regulator has tightened inspection protocols for multi-product facilities. North Rhine-Westphalia CDMOs are expanding dedicated large-scale bioreactor capacity to capture antibody-drug conjugate demand from European sponsors.
China
NMPA alignment with ICH Q5D guidelines on cell line characterization is tightening market access for imported production platforms. Domestic biopharmaceutical companies are scaling CHO-based infrastructure for monoclonal antibody biosimilars. Shanghai and Suzhou industrial parks are attracting CDMO investments targeting export-oriented biologics production.
Switzerland
Swissmedic oversight of gene therapy manufacturing is creating premium pricing for GMP-compliant viral vector capacity. The country's contract manufacturers command geographic redundancy premiums from large pharma procurement teams. Basel-region facilities are disaggregating master and working cell bank storage across multiple jurisdictions to mitigate single-site disruption risks.
India
CDSCO alignment with ICH Q5D guidelines has not yet translated into domestic large-scale mammalian capacity, creating infrastructure gaps for export-oriented biologics. The country's national pharmaceutical regulator is intensifying GMP inspections for contract manufacturers. Maharashtra and Telangana are emerging as early-mover destinations for biomanufacturing investments targeting regulated markets.
Mammalian Cell Fermentation Technology Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding end-to-end bioproduction portfolios and the latter dominating single-use fermentation niches. The structure rewards scale in downstream purification workflows while penalizing stainless-steel incumbents facing asset stranding risks. Three archetypes prevail: integrated life sciences conglomerates, dedicated CDMOs with geographic redundancy capabilities, and precision equipment specialists. Competitive moves concentrate on capacity expansion in high-regulation jurisdictions and strategic partnerships for continuous manufacturing technology access.
Among integrated life sciences conglomerates, Thermo Fisher Scientific and Danaher occupy positions spanning upstream fermentation through downstream purification, exemplifying portfolio breadth strategies. Lonza represents the dedicated CDMO archetype with multi-continental large-scale bioreactor deployments. Sartorius AG sits within the precision equipment specialist tier, anchoring single-use technology differentiation for flexible manufacturing architectures.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Danaher |
| Lonza |
| F. Hoffmann-La Roche |
| Sartorius AG |
| AstraZeneca |
| Bristol-Myers Squibb |
| Amgen |
| Others |
Pricing and Supply Chain Analysis
Ninety-day media formulation lead times concentrate pricing power among recombinant insulin and transferrin suppliers in the United States and Germany, forcing CDMOs to absorb cost volatility or pass through to biopharmaceutical sponsors. This inventory exposure shapes contract structures and dual-sourcing mandates across mammalian cell fermentation procurement.
Pricing Analysis
After-sales service contracts for bioreactor validation and process analytical technology integration drive lifetime value in this market. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified continuous manufacturing suites from fed-batch clinical supply and early-stage development batches. Cost compression in standard-tier fed-batch services is intensifying because CDMO capacity expansion in China and India expands competitive supply. Emerging biotechs demonstrate acute price sensitivity toward media formulations and single-use consumables, while large pharma sponsors prioritize regulatory compliance and geographic redundancy over unit economics.
Supply Chain Analysis
Recombinant protein additive production concentrates in the United States, Germany, and Switzerland, creating single-source vulnerability for chemically defined media formulations. The supply chain draws from Chinese stainless-steel bioreactor fabrication, German precision sensor manufacturing, and Singaporean single-use assembly sterilization. Tariff exposure on imported bioproduction equipment is amplifying regional sourcing mandates. Distribution runs through direct OEM relationships for large-scale installations and distributor networks for consumables and spare parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where perfusion technology interoperability with legacy batch record systems determines competitive survival. Ecosystem consolidation around continuous manufacturing standards is reshaping vendor selection criteria.
For Market Incumbents: Consolidate control over downstream purification workflows to anchor gene therapy and antibody-drug conjugate production against agile CDMO entrants. Acquire perfusion automation capabilities to preempt FDA real-time release testing compliance gaps. Lock in long-term media supply contracts before recombinant protein input costs escalate further.
For New Entrants and Emerging Players: Viral vector manufacturing capacity shortages in Switzerland and the United States present immediate white-space opportunity for GMP-compliant facility investment. Target India biomanufacturing infrastructure gaps before CDSCO enforcement of ICH Q5D guidelines accelerates. Pursue strategic partnerships with established cell line development scientists to overcome talent scarcity barriers.
For Investors and Strategic Acquirers: Long-term, this sits as a capacity-constrained infrastructure play because regulatory compliance requirements create durable moats around GMP-certified mammalian fermentation assets. Acquisition targets should demonstrate integrated perfusion-to-purification workflows or proprietary chemically defined media formulations. Watch FDA finalization of continuous manufacturing guidance as the signal for capital redeployment timing into perfusion platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Perfusion Technology Adoption | Front-loading process analytical technology investments captures FDA emerging guidance on real-time release testing. |
| Geographic Redundancy Expansion | Disaggregating master cell bank storage across Massachusetts, North Carolina, and Switzerland mitigates single-site disruption risks. |
| Chemically Defined Media Transition | Eliminating serum-dependent formulations satisfies NMPA, FDA, and EMA regulatory submission mandates. |
| Viral Vector Capacity Buildout | Dedicated mammalian host facilities command premium pricing from clinical-stage gene therapy developers. |
| Continuous Manufacturing Partnership | Strategic alliances for perfusion-to-capture chromatography integration accelerate commercial scale validation timelines. |
Research Methodology
Initial hypotheses were tested against primary input from bioprocess engineers, regulatory affairs leads at CDMOs, biopharmaceutical procurement directors, and cell line development scientists and refined through secondary validation. Sources included FDA guidance documents, EMA good manufacturing practice standards, NMPA inspection protocols, and biomanufacturing facility construction permits. Bottom-up capacity modeling and top-down demand segmentation triangulated market sizing across the analysis window.
Variance decomposition tracked technology type, application segment, end-user category, and regional regulatory cluster as primary segmentation dimensions. CAGRs were derived from installed base evolution, capacity utilization trends, and pipeline velocity indicators. Forecast inputs incorporated perfusion adoption curves, media formulation transition timelines, and viral vector demand projections from gene therapy clinical trial registrations.
Forecasts assume regulatory continuity in FDA, EMA, and NMPA biomanufacturing oversight regimes; material policy shifts would require re-modeling technology adoption timelines and facility investment returns. Practitioners should keep alternative scenarios live as continuous manufacturing guidance finalization and raw material supply concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Biobanking Equipment Market
Biotechnology Equipment
Global Large Molecule Bioanalytical Technologies Market
Biotechnology Equipment
Biologic Imaging Reagents Market
Biotechnology Equipment
Portable Bioprocessing Bioreactors Market
Biotechnology Equipment
Global Transfection Reagents and Equipment Market
Biotechnology Equipment
Global Biotechnology Instruments Market
Biotechnology Equipment
Cell Separation Bead Market
Biotechnology Equipment
Upstream Bioprocessing Equipment Market
Biotechnology Equipment
Global Lab Automation in Protein Engineering Market
Biotechnology Equipment
Fermentation Equipment Market
Biotechnology Equipment
Cryopreservation Equipment Market
Biotechnology Equipment
Plasmid Kits Market
Biotechnology Equipment
Global Competent Cells Market
Biotechnology Equipment
Cryopreservation Freezer Market
Biotechnology Equipment
Automated Cell Culture Equipment Market
Biotechnology Equipment
Laboratory Filtration Devices Market