
 Recombinant Human Endostatin Market | 2026-2036
Recombinant Human Endostatin Market Size, Share, and Industry Trends Forecast 2026-2036
Recombinant Human Endostatin Market Analytics
Chinese biologics manufacturing capacity is hardening as domestic producers expand GMP-compliant fermentation suites. Hengrui Pharmaceuticals anchors its position through backward integration into recombinant protein production. Yantai Medgenn Ltd. specializes in endostatin-specific purification protocols for the oncology channel. Thermo Fisher Scientific extends its global distribution network for research-grade recombinant proteins across academic buyers.
Recombinant human endostatin is a 184-amino-acid protein fragment derived from collagen XVIII that inhibits vascular endothelial growth factor signaling and suppresses tumor angiogenesis; manufacturers produce it through E. coli or yeast expression systems with subsequent refolding and endotoxin removal steps. Injectable formulations dominate clinical demand due to bioavailability requirements in hospital oncology wards, while lyophilized presentations capture shelf-life-sensitive procurement in research labs. Subcutaneous delivery modes gain traction in outpatient clinic settings where patient self-administration reduces infusion chair occupancy.
China's NMPA biologics registration framework and the FDA's CBER oversight of recombinant protein therapeutics both mandate extensive immunogenicity profiling before market authorization, which shapes R&D budget allocation and timeline planning. The EU's EMA MDR requirements for traceability and post-market surveillance add compliance layers for European hospital tenders. Stakeholders must monitor evolving pharmacovigilance obligations across major jurisdictions to anticipate qualification burdens for new manufacturing sites.
Market Dynamics
China's NMPA biologics pathway is compressing approval timelines for domestic recombinant protein manufacturers, redistributing competitive advantage toward GMP-certified fermentation capacity holders.
Growth Catalysts
- Anti-angiogenic protocol expansion:Oncology departments in tertiary hospitals are integrating endostatin into first-line combination therapies, driving infusion infrastructure utilization.
- NMPA biologics registration framework:China's streamlined biosimilar pathway accelerates market entry for recombinant protein producers with validated E. coli expression systems.
- East Asian hospital network concentration:Established chemotherapy centers in Japan, South Korea, and China concentrate demand for injectable formulations with cold-chain logistics.
Market Restraints
- Endotoxin removal cost structure:Pyrogen clearance for parenteral-grade recombinant proteins consumes 15-20% of downstream processing budgets.
- Single-source fermentation equipment:Stainless steel bioreactor supply concentrates among German and Swiss engineering firms, creating procurement bottlenecks.
- Immunogenicity profiling mandates:FDA CBER and EMA MDR requirements extend preclinical timelines by 18-24 months for novel expression hosts.
Strategic Opportunities
- Subcutaneous delivery formulation:Outpatient clinic networks seek self-administration options to reduce infusion chair occupancy and hospital labor costs.
- Research-grade lyophilized presentations:Academic procurement channels favor shelf-stable formats for multi-site oncology studies.
- Dual carbon compliance incentives:China's MEE environmental standards favor manufacturers with energy-efficient fermentation and captive water recycling.
Industry Challenges
- Refolding specialist scarcity:Protein chemists with recombinant inclusion body solubilization expertise command premium compensation in biologics hubs.
- GMP suite capex intensity:New fermentation capacity requires $50-80 million facility investments with 4-5 year construction timelines.
- Multi-jurisdiction pharmacovigilance integration:Post-market surveillance obligations across FDA, EMA, and NMPA systems strain quality assurance staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recombinant Human Endostatin Market |
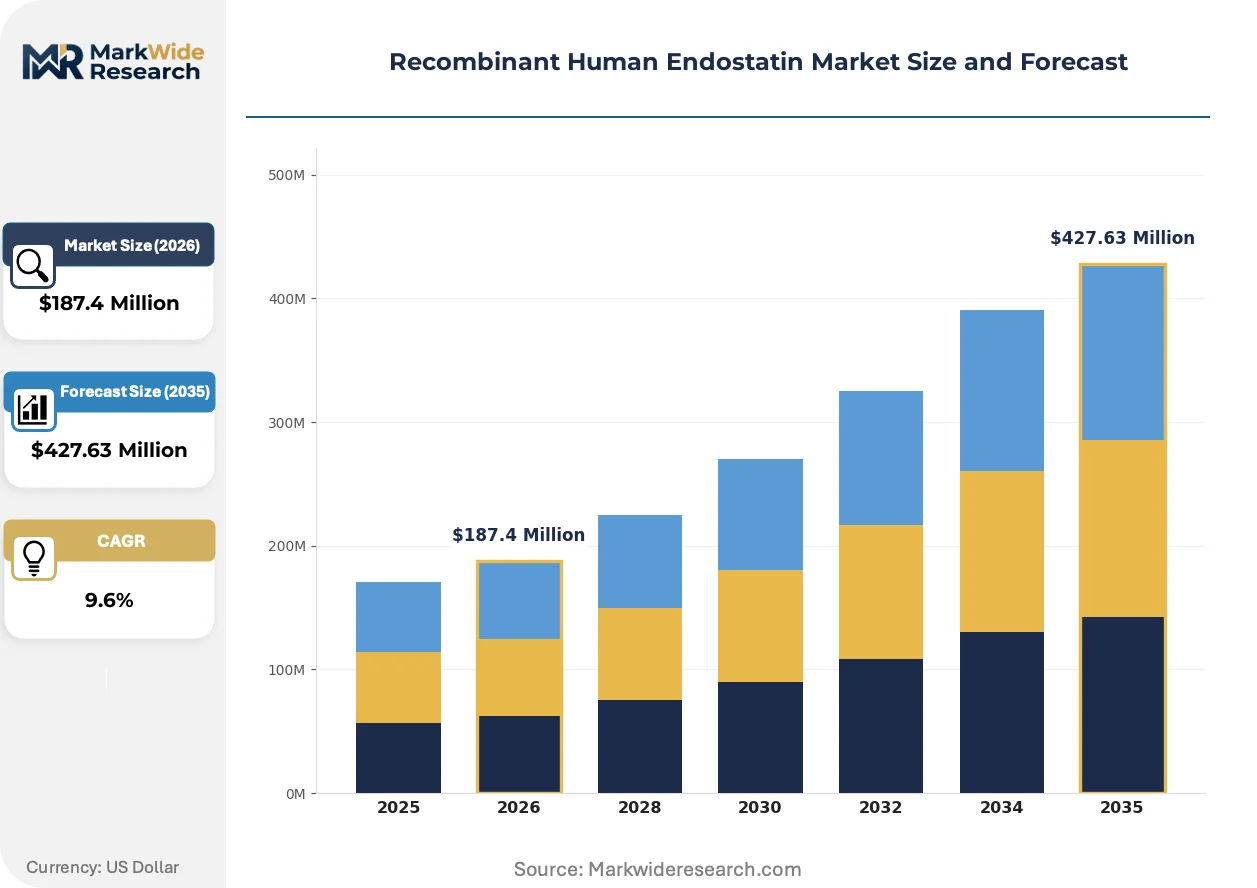
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $427.63 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Infusion, Lyophilized, Oral Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Local End User: Hospitals, Clinics, Research Labs, Pharmaceutical Companies Application: Oncology, Vascular Diseases, Autoimmune Disorders, Rare Diseases |
| Companies Covered | Thermo Fisher Scientific, PeproTech, Pfizer Inc., Novus Biologicals, Biocon, Yantai Medgenn Ltd., FUJIFILM KYOWA KIRIN BIOLOGICS Co., Ltd., Hengrui Pharmaceuticals, 3SBio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recombinant Human Endostatin Market Evolving Landscape
Continuous bioprocessing architectures are displacing batch fermentation in recombinant protein manufacturing, compressing capital intensity while raising yield consistency.
Single-use bioreactor technology is modularizing downstream purification trains. Contract manufacturers in Singapore and South Korea are adopting disposable contact surfaces to reduce cross-contamination risk between endostatin campaigns. This shift is modularizing facility design, enabling 40% faster changeover between recombinant protein products.
EMA MDR traceability requirements are mandating serialization at the vial level for biologics distributed in European hospital tenders. Manufacturers must deploy aggregation stations linking primary packaging to pallet-level codes. High-volume oncology buyers in Germany and France are prioritizing suppliers with verified digital chain-of-custody documentation.
Hospital procurement consortia are consolidating recombinant protein purchasing across multi-site networks. Group purchasing organizations in China's provincial health systems now negotiate annual volume commitments for anti-angiogenic therapies. This concentration is compressing supplier margins while rewarding manufacturers with dedicated account management and just-in-time replenishment capabilities.
Recombinant Human Endostatin Market Segmentation
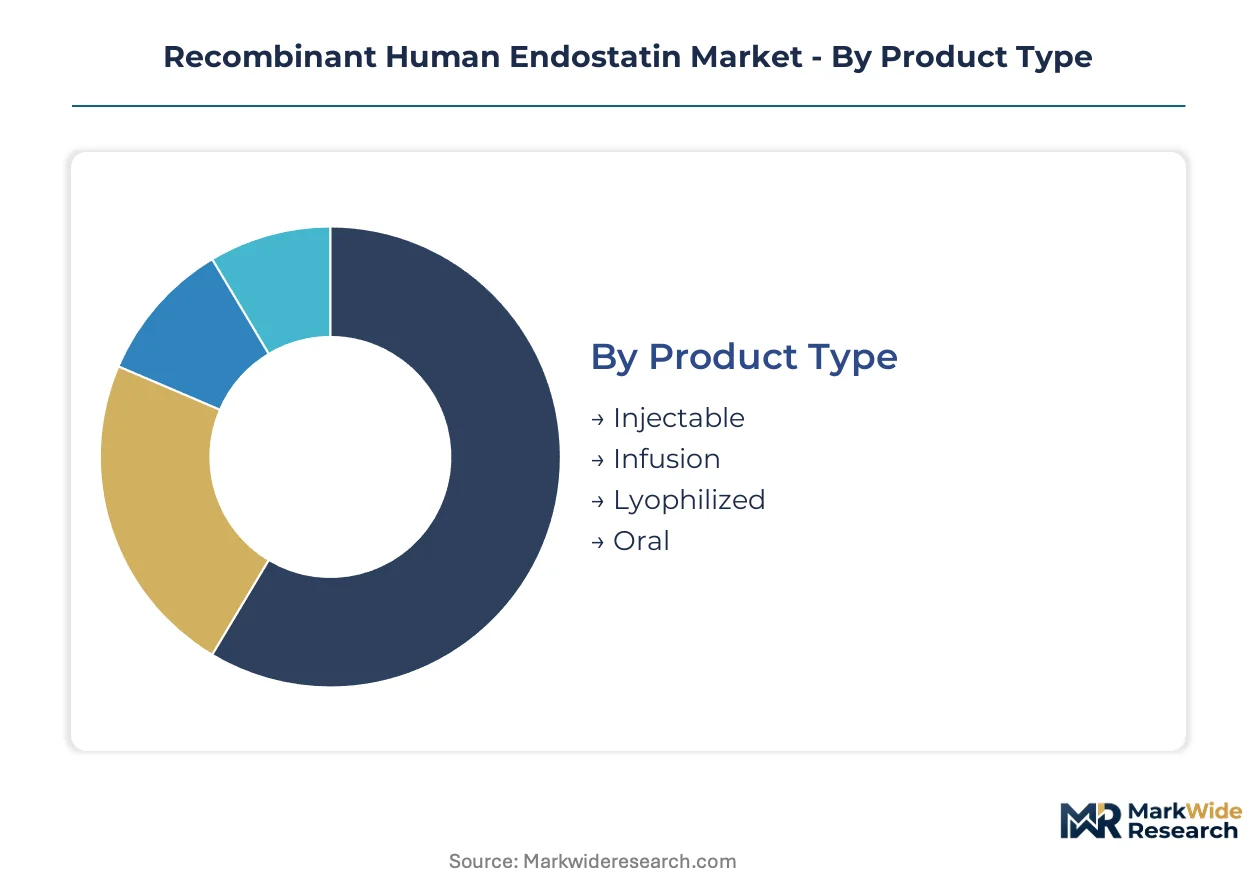
Endostatin procurement patterns diverge sharply across clinical versus research channels, with formulation stability and administration infrastructure dictating segment-level economics. Manufacturers configure production campaigns around these divides, optimizing either for hospital infusion workflows or shelf-stable research supply.
Product Type:
Upgrade cycles in oncology wards favor formulations that reduce preparation time and cold-chain burden, pushing procurement toward ready-to-use presentations over legacy formats.
- Injectable:Liquid-filled vials for immediate intravenous administration dominate tertiary hospital procurement in China and Japan. East Asian oncology networks prioritize this format to maximize infusion chair throughput and minimize pharmacy compounding labor.
- Lyophilized:Freeze-dried presentations extend shelf stability for research labs and remote clinic deployments. Academic buyers across multi-site oncology studies favor this format for reduced cold-chain dependency during international shipment.
- Infusion:Pre-mixed bag presentations streamline hospital pharmacy workflows but require validated aseptic filling partnerships with contract manufacturers.
- Oral:Bioavailability challenges limit clinical adoption; development concentrates in preclinical research channels exploring gastrointestinal protection strategies.
Volume placements concentrate in Injectable formats; the faster expansion belongs to Lyophilized presentations.
Delivery Mode:
Cost tier differentiation separates hospital-based administration from emerging outpatient self-management protocols, with reimbursement structures reinforcing the divide.
- Intravenous:Infusion center protocols in Chinese and Japanese tertiary hospitals standardize on this delivery mode for combination anti-angiogenic therapy. Established nursing infrastructure and reimbursement codes lock in institutional preference.
- Subcutaneous:Pen-device and autoinjector development targets South Korean and Singaporean outpatient clinic networks seeking to reduce labor costs and infusion chair occupancy. Patient self-administration protocols are expanding fastest in these markets.
- Intramuscular:Limited adoption for endostatin due to tissue irritation profiles; occasional use in veterinary oncology research applications.
- Local:Intralesional delivery for accessible tumors remains experimental, with demand concentrated in specialized dermatology-oncology research centers.
Procurement volume clusters in Intravenous administration; Subcutaneous formats are climbing the fastest as outpatient protocols mature.
End User:
Customer type determines pricing tolerance and technical specification intensity, with hospitals demanding GMP-grade documentation and research labs prioritizing batch consistency over regulatory filing support.
- Hospitals:Tertiary oncology departments in China, Japan, and South Korea drive GMP-certified demand through centralized provincial procurement consortia. NMPA and PMDA traceability mandates shape supplier qualification requirements.
- Research Labs:Academic oncology programs across East Asia favor research-grade material with comprehensive certificate of analysis documentation for publication requirements. Multi-site collaboration networks prioritize lot-to-lot consistency.
- Clinics:Outpatient oncology centers seek flexible volume commitments and just-in-time replenishment for smaller patient cohorts.
- Pharmaceutical Companies:Preclinical and clinical trial material supply requires extensive regulatory filing support and audit access to manufacturing sites.
Revenue concentration sits with Hospital networks; Research Labs are expanding most quickly as academic endostatin protocols proliferate.
Application:
Maturity gradients separate established anti-angiogenic oncology from exploratory therapeutic areas, with clinical evidence depth determining reimbursement access and manufacturing scale allocation.
- Oncology:Non-small cell lung cancer and gastric carcinoma protocols in Chinese hospital networks anchor commercial demand. Combination therapy with platinum-based regimens drives infusion infrastructure utilization.
- Vascular Diseases:Diabetic retinopathy and age-related macular degeneration research programs in Japanese ophthalmology centers explore localized delivery formulations. Clinical evidence accumulation remains preliminary.
- Autoimmune Disorders:Rheumatoid arthritis and psoriasis research channels investigate anti-inflammatory mechanisms; no approved indications currently exist.
- Rare Diseases:Hereditary hemorrhagic telangiectasia and other orphan indications attract niche research funding with limited commercial scale.
Manufacturing scale concentrates in Oncology supply; Vascular Diseases research is gaining share fastest as ophthalmology protocols advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Collagen XVIII feedstock availability and E. coli expression system expertise concentrate manufacturing activity in East Asian fermentation clusters. Tertiary hospital networks in China, Japan, and South Korea anchor clinical demand through provincial procurement consortia. Regulatory acceleration in China's NMPA pathway is redistributing competitive advantage toward domestic GMP-certified producers.
China
NMPA biologics registration compresses approval timelines for domestic recombinant protein manufacturers with validated fermentation capacity. Provincial health system consortia in Jiangsu and Shandong negotiate annual volume commitments for anti-angiogenic therapies. Hengrui Pharmaceuticals anchors production in Lianyungang with backward integration into recombinant protein manufacturing.
Japan
PMDA traceability mandates shape supplier qualification for tertiary oncology departments in Tokyo and Osaka metropolitan areas. Combination therapy protocols for non-small cell lung cancer drive infusion infrastructure investment in Kanto region hospitals. FUJIFILM KYOWA KIRIN BIOLOGICS exemplifies domestic biologics manufacturing capacity serving hospital networks.
South Korea
MFDS oversight of recombinant protein therapeutics shapes R&D budget allocation for Seoul-based biotech firms. Outpatient clinic networks in Busan-Ulsan seek subcutaneous delivery formats to reduce infusion chair occupancy. Contract manufacturers in Songdo adopt single-use bioreactor technology for modular campaign flexibility.
United States
FDA CBER immunogenicity profiling mandates extend preclinical timelines for novel expression hosts in Boston and San Francisco biotech clusters. Research-grade procurement from academic oncology programs concentrates demand in National Cancer Institute-designated centers. Thermo Fisher Scientific extends distribution networks across university buyers seeking certificate of analysis documentation.
Germany
EMA MDR serialization requirements at the vial level mandate digital chain-of-custody documentation for European hospital tenders. Group purchasing organizations in Bavaria and North Rhine-Westphalia consolidate recombinant protein purchasing across multi-site networks. Stainless steel bioreactor supply from German engineering firms creates procurement dependencies for fermentation capacity expansion.
Recombinant Human Endostatin Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue subcutaneous delivery formulation and continuous bioprocessing architectures. The vendor base stratifies across three tiers: integrated pharmaceutical conglomerates with captive biologics capacity, specialized recombinant protein manufacturers with purification expertise, and research-grade suppliers serving academic channels. Two dominant competitive moves are reshaping positioning: GMP suite capacity expansion in East Asian fermentation hubs, and strategic partnerships between domestic manufacturers and global distribution networks.
Among China-based biologics specialists, Hengrui Pharmaceuticals and Yantai Medgenn Ltd. exemplify the integrated manufacturing archetype with fermentation-to-fill capabilities. Thermo Fisher Scientific occupies a position in the research-grade supply tier, anchoring global distribution for academic and preclinical buyers. These three entities represent distinct competitive vectors: domestic clinical-grade production, regional purification specialization, and international research-channel reach.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| PeproTech |
| Pfizer Inc. |
| Novus Biologicals |
| Biocon |
| Yantai Medgenn Ltd. |
| FUJIFILM KYOWA KIRIN BIOLOGICS Co., Ltd. |
| Hengrui Pharmaceuticals |
| 3SBio |
| Others |
Value Network & Pricing Analysis
Endotoxin removal costs cascade through recombinant protein production tiers, with pyrogen clearance consuming 15-20 percent of downstream processing budgets before reaching hospital procurement consortia or research lab buyers. This cost structure stratifies pricing across GMP-certified clinical supply and research-grade material, compressing margins for manufacturers lacking captive fermentation capacity while rewarding integrated producers with backward control over E. coli expression systems.
Pricing Analysis
After-sales service bundling separates clinical-grade supply from research-channel transactions, with GMP-certified manufacturers including regulatory filing support and pharmacovigilance documentation in hospital contracts while research-grade suppliers unbundle these elements. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with NMPA-validated material commanding premiums over research-use-only grades. Cost compression in standard tiers is intensifying because provincial health system consortia negotiate annual volume commitments. Research labs exhibit highest price sensitivity due to grant-funded procurement constraints, while tertiary hospital networks prioritize supply security over unit cost.
Supply Chain Analysis
China's domestic-content mandates for biologics manufacturing are reshaping sourcing patterns, with NMPA registration pathways favoring GMP-certified local fermentation capacity over imported material. Supply concentration centers on China, South Korea, and Japan, with stainless steel bioreactor fabrication drawing from German and Swiss engineering specialists. Raw material dependencies include collagen XVIII feedstock, pharmaceutical-grade fermentation media, and single-use bioreactor consumables. Single-source vulnerability in bioreactor engineering creates procurement bottlenecks for capacity expansion. Distribution runs through provincial health system consortia in China and group purchasing organizations in Japan and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around GMP-certified fermentation capacity holders, with NMPA biologics pathway acceleration forcing subscale producers toward contract manufacturing or exit.
For Market Incumbents: Anchor market position through captive capacity expansion in Jiangsu and Shandong fermentation clusters, securing provincial health system volume commitments before competitors qualify alternative suppliers. Invest in continuous bioprocessing architectures to compress unit costs against emerging single-use technology adopters. Defend against subcutaneous delivery format disruptors by accelerating pen-device development partnerships with Seoul-based outpatient clinic networks. For New Entrants and Emerging Players: Begin with research-grade lyophilized presentations for multi-site academic oncology studies, where publication-grade certificate of analysis documentation commands pricing power without GMP certification burden. Target Singaporean and South Korean contract manufacturing channels seeking modular campaign flexibility for recombinant protein portfolios. Pursue go-to-market alliances with Thermo Fisher Scientific's global distribution network for academic buyer access. For Investors and Strategic Acquirers: NMPA approval timeline compression for domestic manufacturers is the leading indicator that East Asian fermentation assets will appreciate faster than Western biologics capacity. Frame long-term viability around 5-10 year provincial health system consolidation windows, with integrated fermentation-to-fill producers outperforming purification-specialist targets. Monitor subcutaneous delivery formulation partnerships as inflection signals for outpatient protocol expansion.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Suite Capacity Expansion | NMPA-validated fermentation infrastructure secures provincial health system procurement contracts in Jiangsu and Shandong. |
| Subcutaneous Delivery Development | Pen-device formats reduce infusion chair occupancy in South Korean outpatient clinic networks. |
| Continuous Bioprocessing Adoption | Perfusion-based E. coli expression systems compress capital intensity while raising endostatin yield consistency. |
| Research-Grade Distribution Partnership | Academic channel alliances with global suppliers capture multi-site oncology study procurement. |
| Dual Carbon Compliance Investment | MEE environmental standards favor manufacturers with energy-efficient fermentation and captive water recycling. |
Research Methodology
Document review covered NMPA biologics registration filings, PMDA traceability mandates, ClinicalTrials.gov endostatin protocols, and EMA MDR serialization requirements, complemented by interviews with fermentation facility directors, oncology formulary managers, and recombinant protein procurement leads. Secondary validation drew from provincial health system tender databases, GMP inspection records, and academic publication citation patterns. Bottom-up demand modeling across hospital, research lab, and pharmaceutical company channels triangulated against top-down market sizing from biologics capacity utilization data.
Cross-reference between historical approval timeline analysis and expert panel input shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type, delivery mode, end user, and application with regional regulatory cluster differentiation. CAGRs derived from volume placement trajectories in injectable versus lyophilized formats, infusion infrastructure expansion rates, and subcutaneous protocol adoption curves in outpatient settings. Forecast inputs incorporated NMPA pathway acceleration effects and single-use bioreactor technology diffusion rates.
Regulatory pathway delays, immunogenicity profiling requirement expansion, and stainless steel bioreactor supply constraints are the dominant revision risks to modeled outputs. Forecasts reflect assumptions around NMPA timeline compression sustainability and East Asian hospital network consolidation pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Cell Culture Market
Medical Biotechnology
Europe Cell Culture Market
Medical Biotechnology
Cyclin-Dependent Kinase Inhibitor Market
Medical Biotechnology
Galectin Inhibitor Therapeutics Market
Medical Biotechnology
Global Metformin-Pioglitazone Market
Medical Biotechnology
Alcohol Dehydrogenase Enzymes Market
Medical Biotechnology
Global Antisense and Rnai Therapeutics Market
Medical Biotechnology
Global Microalbumin Test Market
Medical Biotechnology
Global Ornithine-Transcarbamylase Deficiency Market
Medical Biotechnology
Cancer Monoclonal Antibodies Market
Medical Biotechnology
T Cell-Specific Surface Glycoprotein CD28 Antibody Market
Medical Biotechnology
Muscular Dystrophy Drugs Market
Medical Biotechnology
Global Preimplantation Genetic Diagnosis (PGD) Market
Medical Biotechnology
Mecobalamin Injection Market
Medical Biotechnology
Global Small Interfering RNA (Sirna) Therapeutics Market
Medical Biotechnology
Asparaginase Market