
 Automated Cell Counting Market | 2026-2036
Automated Cell Counting Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Cell Counting Market Analytics
Deep learning integration into image-based cytometry is tilting instrument architectures toward AI-native platforms. Thermo Fisher Scientific anchors its position through backward integration into fluorescence optics and cloud analytics infrastructure. Bio-Rad Laboratories differentiates via CRISPR-compatible counting workflows and open-system reagent architectures. Danaher Corporation leverages its life sciences conglomerate structure to cross-sell automated counters into existing diagnostics footprints.
Automated cell counting encompasses instruments that quantify viable and non-viable cells through optical, electrical, or microfluidic detection methods, typically resolving concentrations from 1x10^4 to 1x10^7 cells per milliliter with coefficients of variation below 5%. These systems serve bioprocess monitoring, clinical hematology, and preclinical drug safety assessment where manual hemocytometer methods introduce unacceptable variability. Hematology analyzers and flow cytometers currently command the largest installed bases, though cell imaging systems with label-free AI segmentation represent the fastest-expanding margin pool as pharmaceutical companies seek to eliminate fluorescent dye costs. Microfluidics-based electrical impedance platforms are displacing legacy Coulter principles in point-of-care settings due to reduced sample volumes and disposability.
FDA enforces 21 CFR Part 11 electronic records requirements for cell counting in GMP bioproduction, while EMA's ATMP guidelines mandate traceable viability metrics for autologous therapies. China's NMPA now requires domestic biologics manufacturers to validate automated counting methods under revised pharmacopeial standards. Stakeholders must monitor how harmonization between FDA, EMA, and NMPA data integrity expectations reshapes instrument software validation burdens and aftermarket service revenue models.
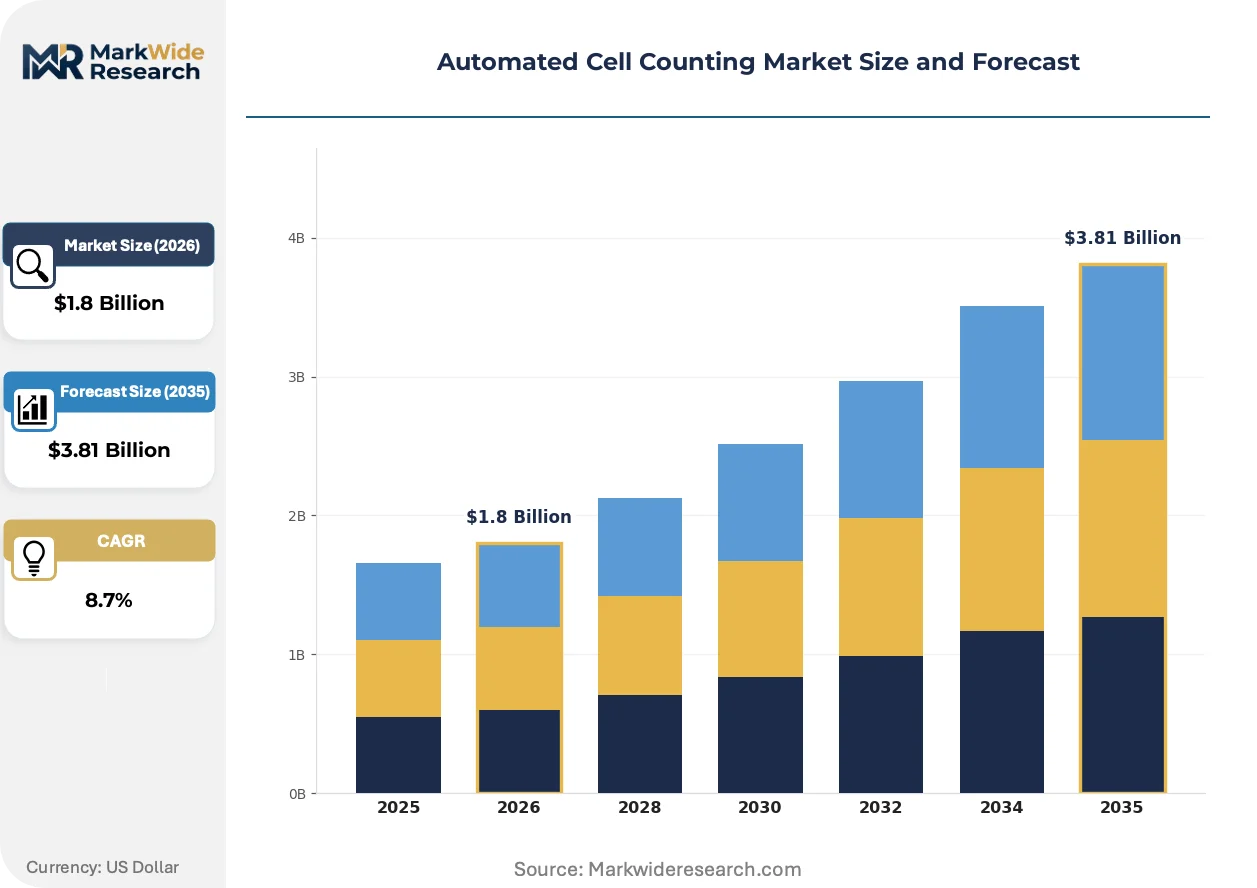
Market Dynamics
AI-native image segmentation is compressing instrument replacement cycles as pharmaceutical manufacturers eliminate fluorescent reagent costs and revalidate workflows around label-free architectures.
Growth Catalysts
- ATMP Manufacturing Mandates:EMA's traceable viability requirements for autologous therapies force bioproducers to replace manual hemocytometers with validated automated systems.
- Fluorescent Dye Cost Compression:Label-free AI segmentation eliminates consumable spend exceeding $50,000 annually per high-throughput screening facility.
- China Biologics Expansion:NMPA pharmacopeial validation requirements for domestic manufacturers accelerate instrument procurement across Shanghai and Suzhou bioclusters.
Market Restraints
- Optics Supply Concentration:High-numerical-aperture objective lenses concentrate among Japanese and German precision optics suppliers, creating 16-24 week lead times.
- 21 CFR Part 11 Validation Burden:FDA electronic records requirements extend software validation timelines for GMP bioproduction deployments by 4-6 months.
- Manual Method Persistence:Academic research laboratories retain hemocytometer workflows due to capital constraints and protocol inertia in grant-funded settings.
Strategic Opportunities
- Point-of-Care Microfluidics:Electrical impedance platforms with disposable cartridges address unmet demand in decentralized clinical hematology across India and Brazil.
- Cloud Analytics Integration:Remote instrument monitoring and predictive maintenance contracts unlock recurring revenue streams from installed base expansion.
- CRISPR Workflow Compatibility:Open-system architectures capturing gene-editing cell therapy quality control represent underpenetrated white space in contract development organizations.
Industry Challenges
- AI Model Validation Expertise:Shortage of computational biologists capable of training and validating deep learning segmentation models for GMP environments constrains deployment velocity.
- Legacy System Integration:Bioproducers with established flow cytometry infrastructure face workflow disruption costs when migrating to image-based platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Cell Counting Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Cytometers, Hematology Analyzers, Cell Imaging Systems, Automated Cell Counters End User: Research Laboratories, Hospitals, Diagnostic Centers, Pharmaceutical Companies Technology: Image-Based Analysis, Electrical Impedance, Laser-Based Detection, Microfluidics Application: Clinical Diagnostics, Drug Discovery, Basic Research, Biotechnology |
| Companies Covered | Agilent Technologies Inc., ChemoMetec A/S, Thermo Fisher Scientific Inc., Merck KGaA, Sysmex Corporation, Danaher Corporation, Bio-Rad Laboratories Inc., Olympus Corporation, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Cell Counting Market Evolving Landscape
Deep learning architectures are restructuring competitive advantage around software-enabled differentiation rather than hardware specifications alone.
Label-free brightfield imaging combined with convolutional neural networks is digitizing cell viability assessment by eliminating fluorescent staining protocols. Biopharmaceutical quality control departments are adopting these systems at replacement cycles compressed from seven to four years. The technology is digitizing instrument architectures toward AI-native platforms where algorithm performance determines purchasing decisions.
EMA's revised ATMP guidelines mandate electronic batch records with traceable viability metrics for each patient-specific therapy lot. This regulatory pressure forces instrument manufacturers to embed audit trail functionality and digital signature capabilities into firmware. Cell therapy contract manufacturers in Germany and the Netherlands are selecting vendors based on pre-validated software packages.
Service contract unbundling is fragmenting traditional instrument procurement as buyers separate hardware acquisition from validation support and reagent supply. Large molecule bioproducers now negotiate cloud analytics subscriptions independently from capital equipment purchases. This pattern is most pronounced among CDMOs in the United States seeking operational flexibility across multi-product facilities.
Automated Cell Counting Market Segmentation
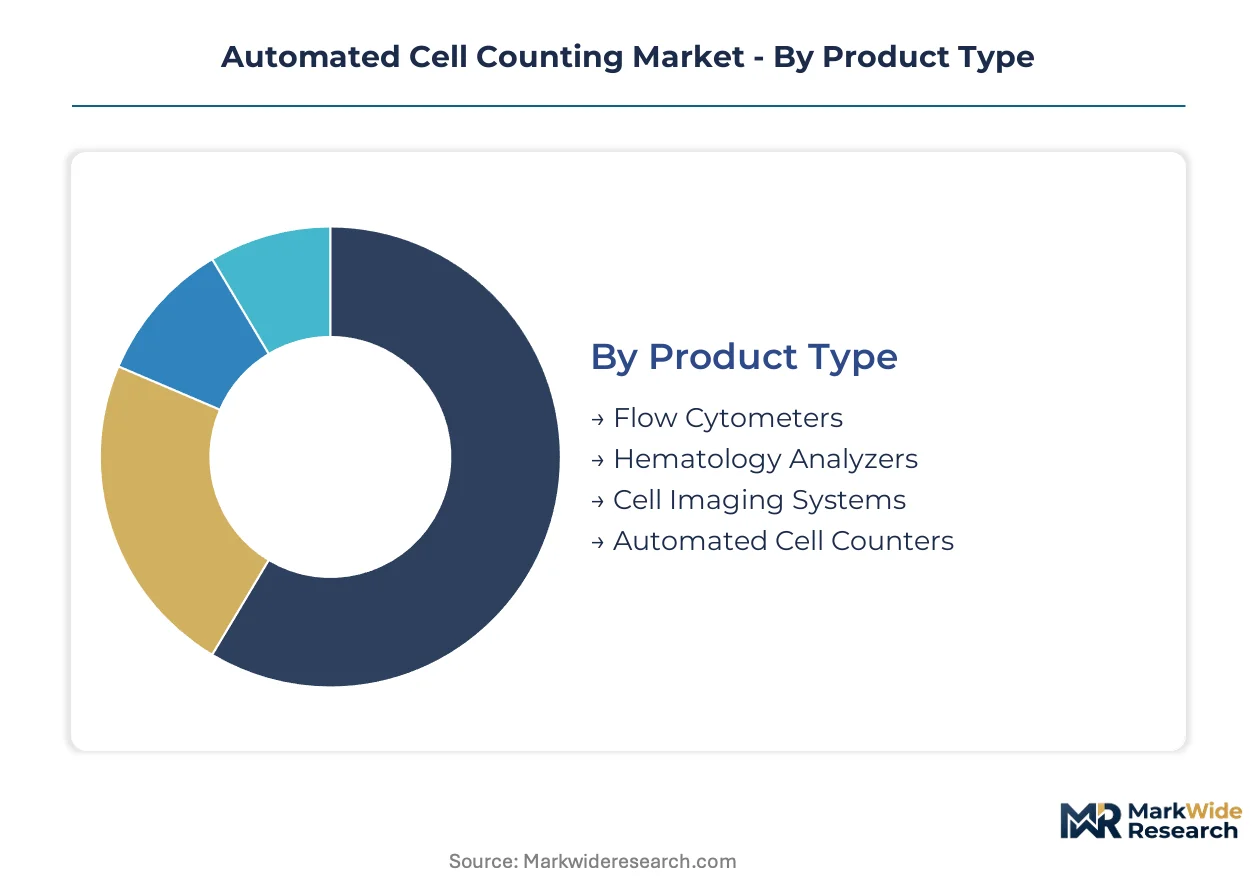
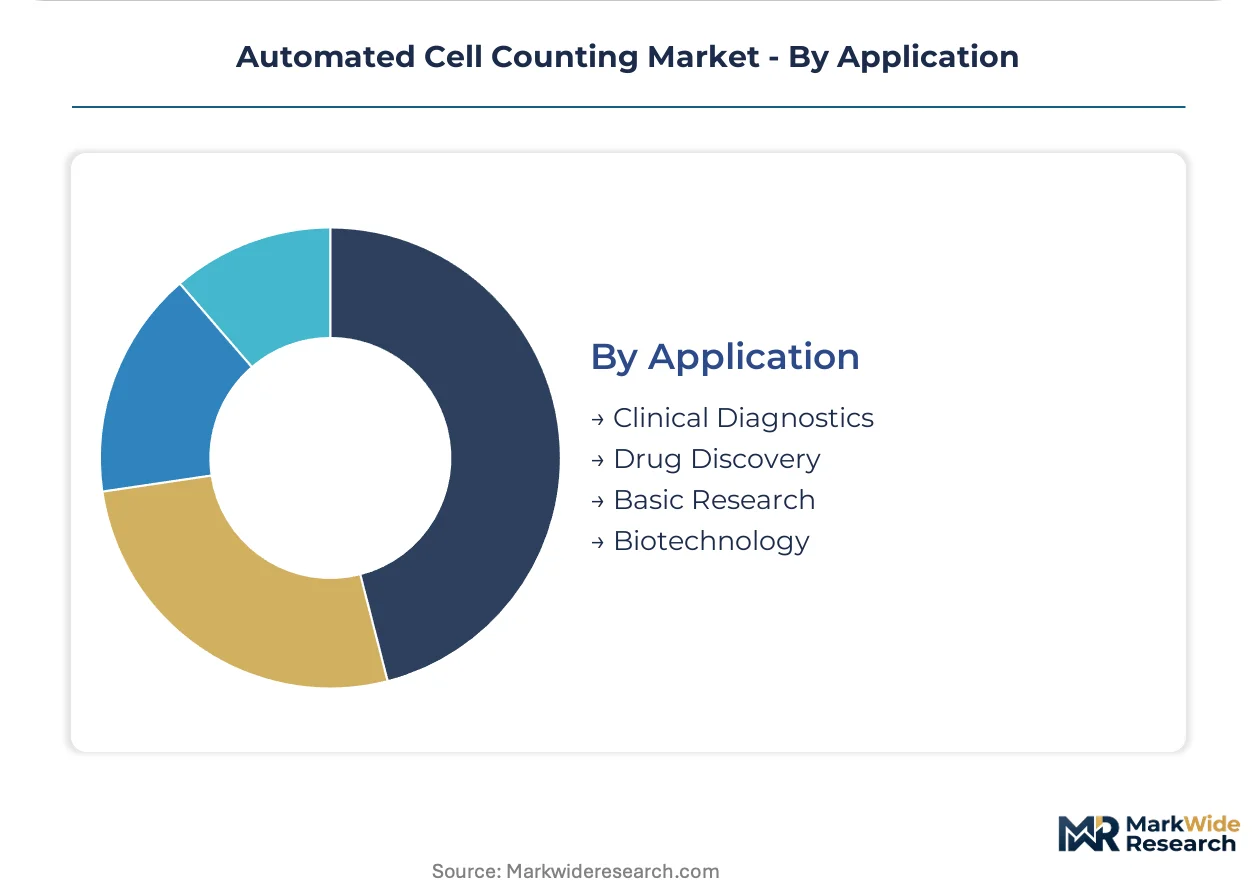
Automated cell counting instruments serve distinct workflow requirements across bioproduction, clinical diagnostics, and academic research. Segmentation reveals how optical architectures, sample throughput demands, and regulatory validation burdens concentrate purchasing decisions among specific customer profiles.
Product Type:
Cost tier separates installed base economics from replacement cycle velocity across instrument categories.
- Flow Cytometers:Multi-parameter fluorescence detection systems resolve cell surface markers and intracellular proteins simultaneously. Pharmaceutical companies in Massachusetts and California deploy these for CAR-T cell therapy characterization where FDA mandates multi-color compensation validation.
- Hematology Analyzers:Benchtop electrical impedance platforms process whole blood samples for complete blood count parameters. Hospitals across Germany standardize on these for clinical hematology where EMA IVDR compliance drives five-year replacement schedules.
- Cell Imaging Systems:Label-free brightfield microscopy with AI segmentation eliminates fluorescent reagent costs for high-content screening facilities.
- Automated Cell Counters:Compact Coulter principle devices serve bioprocess monitoring with GMP-compliant viability metrics.
Hematology analyzers hold installed capacity. Cell imaging systems are rotating up the share rankings.
End User:
Application maturity determines capital allocation patterns and service contract structures across customer types.
- Research Laboratories:Grant-funded academic settings prioritize open-system architectures compatible with custom protocols. NIH-funded institutions in Maryland and California retain hemocytometer workflows for low-throughput applications where capital constraints override automation benefits.
- Pharmaceutical Companies:GMP bioproduction facilities demand validated electronic batch records and audit trail functionality. EMA's ATMP traceability requirements force these buyers toward pre-validated software packages from vendors with European service infrastructure.
- Hospitals:Clinical laboratories integrate automated counters into centralized hematology workflows with LIS connectivity.
- Diagnostic Centers:Decentralized testing networks in India and Brazil seek point-of-care microfluidics with disposable cartridges.
Pharmaceutical companies hold installed capacity. Diagnostic centers are rotating up the share rankings.
Technology:
Volume throughput requirements and sample preparation constraints differentiate detection methodologies.
- Image-Based Analysis:Convolutional neural networks segment individual cells from brightfield or fluorescence micrographs without staining protocols. Biotechnology firms in Shanghai and Suzhou adopt these for stem cell therapy manufacturing where NMPA pharmacopeial validation now applies.
- Microfluidics:Electrical impedance sensing through precision-molded disposable cartridges reduces sample volumes to microliters. Point-of-care deployments across São Paulo and Mumbai favor this architecture for decentralized clinical access.
- Electrical Impedance:Coulter principle counting remains standard for hematology analyzers with established calibration traceability.
- Laser-Based Detection:Flow cytometry light scatter measurements enable simultaneous size and granularity discrimination.
Electrical impedance holds installed capacity. Microfluidics is rotating up the share rankings.
Application:
Customer type concentration shapes feature prioritization between throughput, multiplexing, and regulatory compliance.
- Clinical Diagnostics:Hospital laboratories require CAP-accredited quality control with inter-laboratory proficiency testing. The United States dominates this segment where CLIA regulations enforce biannual calibration verification.
- Drug Discovery:High-throughput screening facilities prioritize walkaway automation and 384-well compatibility. Contract research organizations in Massachusetts and North Carolina drive demand for integrated liquid handling and imaging platforms.
- Basic Research:Academic investigators value modular upgrade paths and open software APIs for custom analysis pipelines.
- Biotechnology:Cell therapy manufacturers seek closed-system processing with patient-specific lot tracking.
Clinical diagnostics holds installed capacity. Biotechnology is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical manufacturers in the United States, Germany, and China drive instrument procurement as FDA, EMA, and NMPA tighten cell therapy quality standards. Each market exhibits distinct regulatory validation burdens and biocluster concentrations.
United States
CAR-T cell therapy producers in Massachusetts and California require multi-color compensation validation for FDA-mandated characterization workflows. FDA enforces 21 CFR Part 11 electronic records requirements that extend software validation timelines by 4-6 months. The Greater Boston biocluster hosts contract development organizations selecting vendors based on pre-validated software packages.
Germany
EMA's ATMP traceability requirements for autologous therapies force replacement of manual hemocytometers with validated automated systems. EMA IVDR compliance drives five-year replacement schedules for clinical hematology analyzers in hospital laboratories. The Munich-Stuttgart corridor concentrates cell therapy contract manufacturers demanding audit trail functionality and digital signature capabilities.
China
NMPA pharmacopeial validation requirements now apply to domestic biologics manufacturers across Shanghai and Suzhou bioclusters. NMPA revised standards mandate automated counting method validation for stem cell therapy manufacturing. Biotechnology firms in the Yangtze River Delta adopt label-free AI segmentation systems to eliminate fluorescent reagent costs.
Japan
PMDA guidelines for regenerative medicine products require traceable viability metrics for induced pluripotent stem cell therapies. METI funding programs accelerate adoption of electrical impedance platforms with disposable cartridges in point-of-care settings. The Kansai region around Osaka hosts precision optics suppliers supplying high-numerical-aperture objective lenses with 16-24 week lead times.
India
CDSCO's tightening biologics manufacturing standards push diagnostic centers toward decentralized testing networks. The country's national pharmaceutical regulator now requires validation documentation for imported automated counting instruments. Mumbai and Bengaluru clusters exhibit unmet demand for microfluidics-based platforms with microliter sample volumes.
Automated Cell Counting Market Competitive Landscape
Channel-controlling players compete with product-specialist players across instrument categories with distinct service contract structures. Life sciences conglomerates leverage installed diagnostics footprints for cross-selling, while standalone cytometry vendors emphasize open-system architectures. Two strategic archetypes dominate: diversified conglomerates with backward integration into fluorescence optics, and focused specialists with CRISPR-compatible workflows. Competitive moves concentrate on cloud analytics integration and predictive maintenance contract unbundling.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc. and Danaher Corporation exemplify channel control through life sciences infrastructure ownership. Among optics-integrated specialists, Olympus Corporation occupies a position shaped by precision imaging heritage. The focused cytometry specialist archetype includes ChemoMetec A/S and Bio-Rad Laboratories Inc., representing open-system reagent architectures. Agilent Technologies Inc. sits within the analytical instrumentation conglomerate category with cross-platform compatibility emphasis. Sysmex Corporation anchors the hematology analyzer segment with established calibration traceability. Merck KGaA exemplifies European-based diversified chemical-pharmaceutical positioning with reagent supply integration. Becton, Dickinson and Company represents the clinical diagnostics conglomerate archetype with hospital laboratory channel access.
| Leading Market Players |
|---|
| Agilent Technologies Inc. |
| ChemoMetec A/S |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Sysmex Corporation |
| Danaher Corporation |
| Bio-Rad Laboratories Inc. |
| Olympus Corporation |
| Becton, Dickinson and Company |
| Others |
Value Network & Pricing Analysis
Japanese and German precision optics suppliers concentrate high-numerical-aperture objective lens production, anchoring margin capture upstream while instrument manufacturers downstream compete on software-enabled differentiation and service contract structures.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate instrument procurement between biopharmaceutical manufacturers and OEM vendors. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated GMP systems from research-grade configurations. Pricing pressure stems from fluorescent dye cost compression as label-free AI segmentation eliminates consumable spend. Academic research laboratories exhibit highest price sensitivity due to grant funding constraints, while cell therapy contract manufacturers prioritize validation assurance over unit cost.
Supply Chain Analysis
Tariff exposure between Japan and the United States dominates supply chain risk planning for precision optics components. Manufacturing concentration in Japan, Germany, and China feeds instrument assembly operations in Massachusetts, California, and the Munich-Stuttgart corridor. Critical dependencies include high-numerical-aperture objective lenses, fluorescence filter sets, and disposable microfluidic cartridges. Distribution runs through direct OEM sales teams for GMP-validated systems and laboratory distributors for research-grade instruments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automated cell counting market is entering a cyclical recovery phase as biopharmaceutical capital expenditure cycles turn following pandemic-era capacity overbuild, with EMA and FDA regulatory mandates forcing replacement demand regardless of macro conditions.
For Market Incumbents: Entrench installed base positions through predictive maintenance contract unbundling and cloud analytics subscription tiers that capture recurring revenue from existing footprints. Backward integration into fluorescence optics reduces exposure to Japanese supplier lead time volatility. Prioritize pre-validated software packages for EMA ATMP compliance to defend against emerging AI-native platform entrants.
For New Entrants and Emerging Players: Build out point-of-care microfluidics capabilities for decentralized clinical hematology across India and Brazil where CDSCO tightening creates instrument procurement windows. CRISPR-compatible open-system architectures represent the most penetrable white space in contract development organizations. Lead with disposable cartridge economics and microliter sample volume advantages against legacy Coulter principle incumbents.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed laboratory instrumentation platforms seeking add-on cytometry capabilities to round out diagnostics footprints. Five-to-ten year viability hinges on AI model validation expertise scarcity resolving through computational biology talent pipeline expansion. Watch for harmonization between FDA, EMA, and NMPA data integrity standards as the inflection signal for software-enabled margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Analytics Integration | Thermo Fisher and Danaher leverage existing diagnostics footprints to cross-sell remote monitoring subscriptions. |
| Label-Free AI Platform Launch | Bio-Rad and ChemoMetec eliminate fluorescent reagent costs while compressing customer replacement cycles. |
| Point-of-Care Microfluidics Expansion | Sysmex and emerging entrants address unmet demand in Mumbai and São Paulo decentralized testing networks. |
| Pre-Validated Software Packaging | EMA ATMP traceability requirements force Munich-Stuttgart contract manufacturers toward audit trail-embedded firmware. |
| Backward Optics Integration | Olympus and precision optics suppliers defend margin positions through captive supply of high-NA objective lenses. |
Research Methodology
Desk research of FDA 483 observations, EMA ATMP guideline revisions, and NMPA pharmacopeial standards preceded structured interviews with bioprocess engineering directors, GMP quality assurance leads, and laboratory procurement managers across Massachusetts, California, Germany, and Shanghai-Suzhou bioclusters. Secondary validation drew from SEC 10-K instrument revenue disclosures, CDSCO import registration databases, and patent filings in AI segmentation architectures. Bottom-up instrument shipment modeling and top-down biopharmaceutical capital expenditure analysis were triangulated against service contract revenue disclosures.
Assumptions held fixed include regulatory harmonization velocity between FDA, EMA, and NMPA, while variables tested included fluorescent dye cost trajectories and computational biology talent supply elasticity. Segmentation modeling spanned product type, end user archetype, detection technology, and application workflow across the analysis window. CAGRs were derived from instrument replacement cycle compression rates and biologics manufacturing capacity expansion pipelines. Industry-specific inputs incorporated CAR-T therapy approval volumes and stem cell therapy manufacturing facility commissioning data.
Stress conditions across precision optics lead time volatility, AI model validation timeline extensions, and grant funding cyclicality for academic research laboratories were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and biopharmaceutical capital allocation priorities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Fermentation Equipment Market
Biotechnology Equipment
Ultracentrifuges Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
Fetal Bovine Serum Market
Biotechnology Equipment
Small-Scale Bioreactors Market
Biotechnology Equipment
Biotechnology Instrumentation Market
Biotechnology Equipment
Cartridges for RT-PCR Automatic Systems Market
Biotechnology Equipment
Middle East and Africa Transfection Reagent and Equipment Market
Biotechnology Equipment
Separation Systems for Commercial Biotechnology Market
Biotechnology Equipment
Global Laboratory Centrifuge Market
Biotechnology Equipment
PCR Master Mix Market
Biotechnology Equipment
Restriction Endonucleases Products (REP) Market
Biotechnology Equipment
Global Bioprocess Container Market
Biotechnology Equipment
Fluorescence Immunoassay Analyzers Market
Biotechnology Equipment
ELISA POT Assay Kits Market
Biotechnology Equipment
Low Endotoxin Gelatin Market