
 Global Bio Decontamination Market | 2026-2036
Global Bio Decontamination Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bio Decontamination Market Foresight
Pharmaceutical manufacturing is consolidating its position as the dominant demand vertical for bio decontamination systems, displacing legacy chemical fogging in food processing corridors. STERIS plc leverages its installed base of vapor hydrogen peroxide generators across North American and European contract manufacturing sites. Ecolab Inc. anchors its competitive position through integrated service contracts that bundle equipment deployment with validated cycle development. Getinge AB differentiates via automated isolator-integrated decontamination suites for aseptic filling lines.
Bio decontamination encompasses the inactivation or removal of viable microorganisms from surfaces, equipment, and enclosed environments through chemical agents, physical irradiation, or gaseous oxidative processes, typically achieving six-log reduction of bacterial endospores under validated parameters. Hydrogen peroxide vapor dominates current equipment revenue due to its material compatibility profile and rapid aeration characteristics, while ultraviolet radiation installations accelerate in laboratory settings where residue-free operation matters. Chlorine dioxide retains niche utility in aeronautics applications where low-temperature penetration of complex geometries outweighs corrosion management costs.
FDA sterile drug manufacturing guidance, EMA Annex 1 revision, and WHO prequalification standards collectively elevate validation documentation burdens and drive replacement of manual decontamination with automated systems. The EU Green Deal chemical sustainability framework further constrains formaldehyde utilization in European pharmaceutical facilities. Stakeholders must monitor evolving regulatory divergence between FDA process validation requirements and EMA environmental monitoring expectations when configuring multi-territory equipment portfolios.
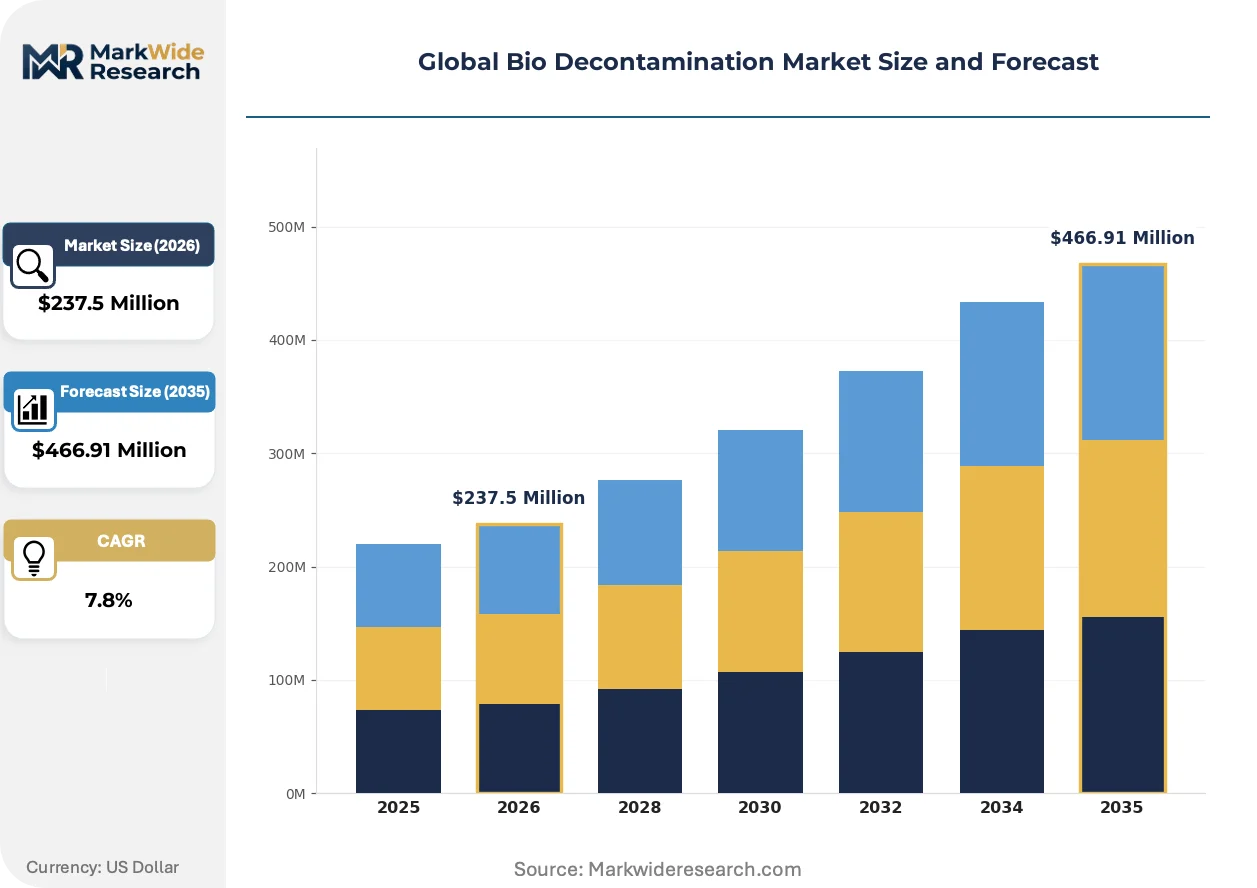
Market Dynamics
Pharmaceutical manufacturers face escalating pressure to validate six-log sporicidal reduction under tightened FDA and EMA sterile processing guidelines, forcing wholesale replacement of manual fogging protocols with automated vapor hydrogen peroxide systems across aseptic filling corridors.
Growth Catalysts
- EMA Annex 1 Revision:The 2022 revision mandates continuous environmental monitoring and risk-based contamination control strategies, compelling European sterile drug facilities to upgrade legacy decontamination infrastructure with validated automated cycles.
- Cell and Gene Therapy Expansion:Commercial-scale manufacturing of CAR-T therapies and viral vectors requires isolator-integrated bio decontamination suites capable of rapid turnaround between patient-specific batches.
- Hydrogen Peroxide Vapor:Its material compatibility with electronics and rapid aeration profile below 1 ppm residual threshold accelerates displacement of formaldehyde in cleanroom environments.
Market Restraints
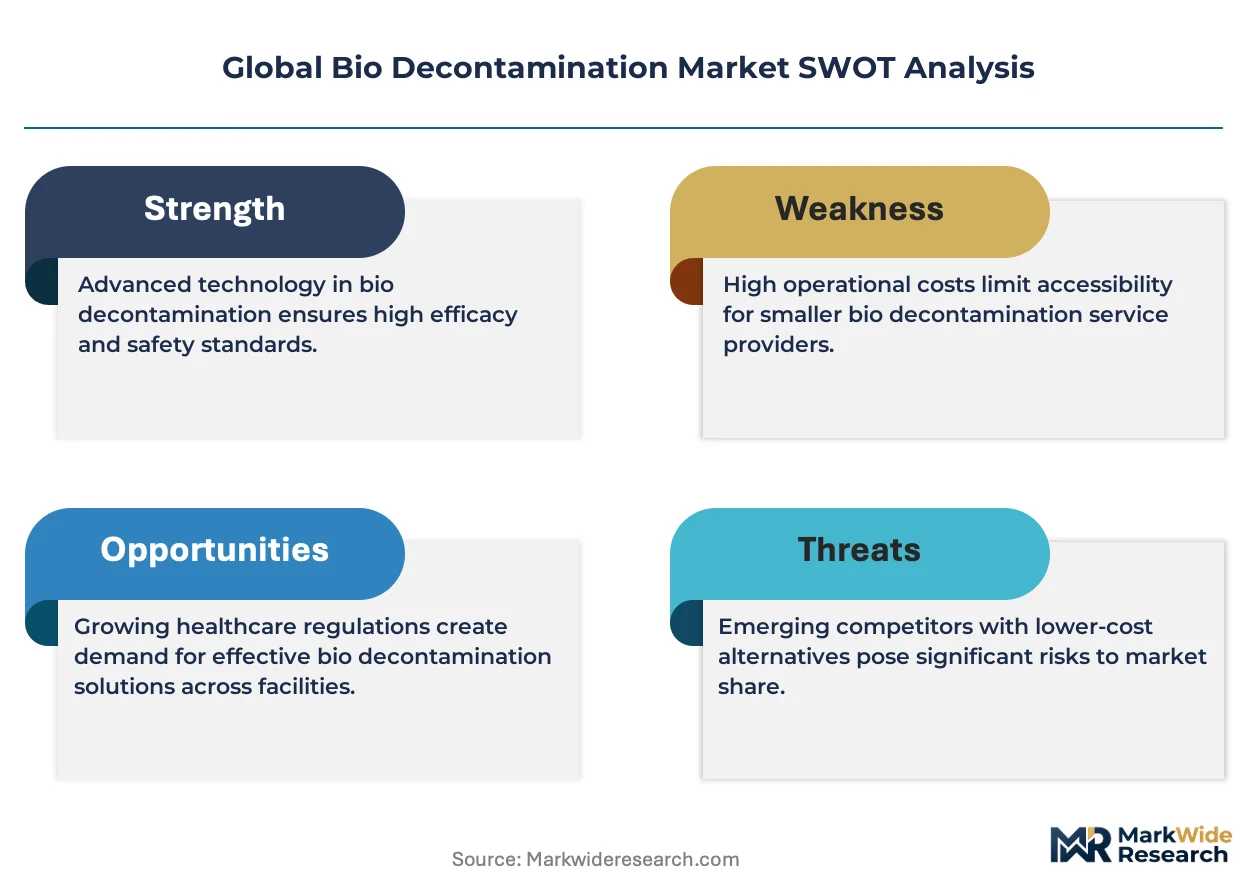
- Platinum Catalyst Supply Concentration:Vapor hydrogen peroxide generators depend on platinum-group catalysts for decomposition control, with refining capacity concentrated in South Africa and Russia creating input volatility.
- Corrosion Management Costs:Chlorine dioxide systems impose accelerated degradation on aluminum and copper components, elevating total cost of ownership in aerospace decontamination applications despite superior penetration.
- Validation Documentation Burden:FDA process validation requirements and EMA environmental monitoring expectations diverge on acceptable biological indicator placement and cycle development protocols, complicating multi-territory equipment deployment.
Strategic Opportunities
- Indian Pharmaceutical Manufacturing:CDSCO's alignment with PIC/S standards and the PLI scheme for active pharmaceutical ingredients create demand for export-compliant sterile processing infrastructure in Hyderabad and Ahmedabad clusters.
- UV-C LED Convergence:Solid-state ultraviolet sources combined with robotic positioning systems enable residue-free decontamination of laboratory equipment where hydrogen peroxide vapor risks oxidative damage to sensitive optics.
- EU Green Deal Chemical Sustainability Framework:Formaldehyde restriction timelines accelerate replacement cycles in European vaccine production facilities, opening equipment procurement windows through 2030.
Industry Challenges
- Cycle Development Expertise Gap:Validated bio decontamination protocols require specialized knowledge in computational fluid dynamics modeling and biological indicator kill curve analysis, with qualified personnel concentrated among original equipment manufacturers.
- Legacy Building Integration:Retrofitting vapor hydrogen peroxide systems into existing pharmaceutical facilities requires HVAC reengineering to manage pressure differentials and exhaust scrubbing, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bio Decontamination Market |
| Market Size in 2026 | $237.5 Million |
| Market Size in 2035 | $466.91 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogen Peroxide Vapor, Ultraviolet Radiation, Ozone, Formaldehyde, Chlorine Dioxide Application: Pharmaceutical Manufacturing, Food Processing, Laboratory Settings, Public Transportation, Aeronautics End User: Hospitals, Biotechnology Firms, Research Institutes, Government Agencies, Commercial Buildings Deployment: Automated Systems, Manual Operation, Semi-Automated Solutions, Portable Units, Stationary Units |
| Companies Covered | STERIS plc, Ecolab Inc., TOMI Environmental Solutions, Inc., JCE Biotechnology, Fedegari Autoclavi SpA, ClorDiSys Solutions, Inc., Zhejiang TAILIN Bioengineering Co., Ltd., Getinge AB, Noxilizer, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bio Decontamination Market Shifts & Advancements
Automation architectures are displacing manual intervention in sterile processing environments, while regulatory divergence between FDA process validation and EMA environmental monitoring forces equipment suppliers to engineer configurable compliance modules. These shifts compress deployment cycles and elevate service contract value capture.
Modular vapor hydrogen peroxide generators are integrating isolator-agnostic docking interfaces that enable rapid reconfiguration between filling line types. Contract manufacturing organizations in Germany and the United States deploy these systems to service multiple client protocols without dedicated capital equipment per product. This flexibility is compressing equipment utilization rates and forcing suppliers toward throughput-based pricing models.
REACH restrictions on formaldehyde under the EU Green Deal chemical sustainability framework are eliminating legacy fumigation protocols in vaccine and biologics manufacturing. Pharmaceutical facilities in Belgium and Ireland face mandated transition timelines, redirecting capital expenditure toward hydrogen peroxide vapor and nitrogen dioxide alternatives. Equipment suppliers are responding with validated cycle libraries that accelerate regulatory submission packages.
Service unbundling is fragmenting traditional equipment-procurement relationships in North American hospital pharmacy settings. Health system purchasing coalitions now separate capital acquisition from cycle development and ongoing validation support, creating openings for specialized service providers. This pattern is most pronounced in academic medical centers where internal engineering capacity supports self-managed equipment operation.
Global Bio Decontamination Market Segmentation
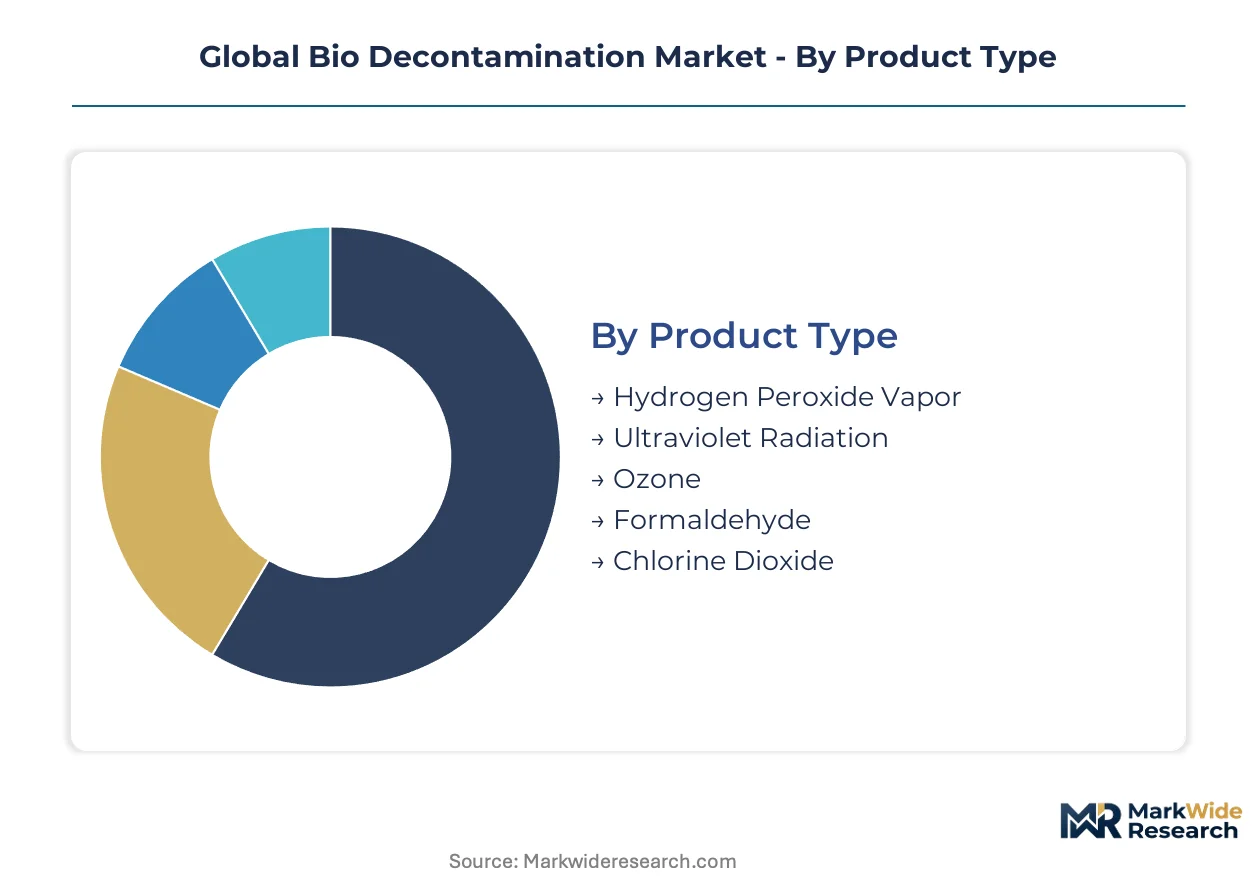
Bio decontamination procurement patterns diverge sharply between high-throughput pharmaceutical corridors and fragmented facility maintenance budgets. Equipment specifications cascade from regulatory validation requirements down to material compatibility constraints, creating distinct tiered demand pools across sterilization technologies.
Product Type:
Volume concentration sits with hydrogen peroxide vapor systems, while premium pricing attaches to emerging ultraviolet LED platforms and specialized gas alternatives.
- Hydrogen Peroxide Vapor:Oxidative biocide delivered as vapor-phase solution achieves six-log sporicidal reduction at 30-35% concentration with rapid catalytic decomposition to water and oxygen. German and Japanese pharmaceutical manufacturers dominate procurement volumes as EMA Annex 1 and PMDA sterile processing guidelines mandate validated automated cycles.
- Ultraviolet Radiation:UV-C emission at 254 nanometers disrupts microbial DNA without chemical residue, positioning solid-state LED sources for laboratory optics and electronics decontamination where oxidative damage risks exclude vapor methods. Research institutes in the United States accelerate installations where FDA validation pathways for residue-free operation streamline approval.
- Ozone:Triatomic oxygen generated via corona discharge or UV irradiation penetrates complex geometries at low temperatures.
- Formaldehyde:Alkylating agent retains niche utility in legacy vaccine production facilities facing EU Green Deal phase-out timelines.
- Chlorine Dioxide:Selective oxidizer penetrates biofilm layers in aerospace applications where corrosion management costs are absorbable.
Today's leader: Hydrogen Peroxide Vapor. Tomorrow's challenger: Ultraviolet Radiation.
Application:
Pharmaceutical corridors absorb capital-intensive automated systems while food processing and transit applications trade validation depth for operational throughput.
- Pharmaceutical Manufacturing:Aseptic filling lines and isolator-integrated suites demand six-log reduction documentation under FDA process validation and EMA environmental monitoring protocols. CAR-T therapy commercialization in the United States and Belgium drives isolator-agnostic vapor system deployment for rapid batch turnaround.
- Food Processing:Conveyor belt and packaging line decontamination favors chlorine dioxide fogging where organic load tolerance outweighs material corrosion concerns.
- Laboratory Settings:Biosafety cabinet and fume hood sterilization concentrates demand for UV-C LED systems with robotic positioning.
- Public Transportation:Rolling stock and station decontamination deploys portable hydrogen peroxide units for overnight cycle completion.
- Aeronautics:Aircraft cabin and cargo hold sterilization applies low-temperature gas penetration for complex interior geometries.
Pharmaceutical Manufacturing commands equipment margins; Laboratory Settings are climbing the fastest as research infrastructure expands.
End User:
Biotechnology firms and hospitals split procurement between validated production suites and clinical pharmacy compounding, with research institutes anchoring mid-tier volumes.
- Biotechnology Firms:Viral vector and cell therapy manufacturers in Boston and Basel clusters drive isolator-integrated system specifications with rapid aeration requirements.
- Hospitals:Health system purchasing coalitions in the United States unbundle capital acquisition from cycle development, fragmenting traditional supplier relationships.
- Research Institutes:Academic medical centers deploy UV-C LED systems for residue-free laboratory equipment decontamination.
- Government Agencies:Defense and public health facilities maintain stockpiled vapor generators for emergency response protocols.
- Commercial Buildings:HVAC-integrated systems address indoor air quality in high-occupancy corporate and hospitality environments.
Biotechnology Firms lead premium procurement; Research Institutes are gaining share fastest through federal funding expansion.
Deployment:
Automated systems capture pharmaceutical validation premiums while portable and semi-automated configurations serve fragmented maintenance budgets.
- Automated Systems:PLC-controlled vapor generators with integrated biological indicator validation and data logging satisfy FDA and EMA documentation requirements for commercial sterile drug production.
- Semi-Automated Solutions:Operator-initiated cycles with automated aeration bridge validation depth and capital constraints in mid-scale biotechnology facilities.
- Manual Operation:Fogging and wipe-down protocols persist in food processing and commercial building maintenance where regulatory burden remains lighter.
- Portable Units:Wheeled vapor generators enable multi-room deployment in hospital pharmacy and research institute settings.
- Stationary Units:Fixed-installation systems anchor dedicated cleanroom and isolator infrastructure in pharmaceutical manufacturing corridors.
Automated Systems dominate revenue; Semi-Automated Solutions represent the steepest expansion trajectory as mid-tier biotechnology manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting sterile drug manufacturing investment toward jurisdictions where validation costs and environmental compliance burdens create operational advantages for multi-territory producers. Facilities in Germany, the United States, India, Japan, and Belgium absorb disproportionate capital flows as FDA, EMA, and PMDA standards diverge on documentation intensity.
United States
CAR-T therapy commercialization and viral vector manufacturing in Boston and San Francisco clusters drive isolator-integrated vapor system procurement. FDA process validation requirements for sterile drug production mandate automated cycle documentation. Maryland and North Carolina biotech corridors concentrate contract manufacturing organization capacity.
Germany
EMA Annex 1 revision enforcement compels Baden-Württemberg and Bavaria pharmaceutical facilities to replace legacy formaldehyde protocols. EU Green Deal chemical sustainability timelines accelerate hydrogen peroxide vapor deployment. Frankfurt-Rhine-Main contract manufacturing sites service pan-European sterile processing demand.
India
CDSCO alignment with PIC/S standards and PLI scheme incentives for active pharmaceutical ingredients reshape Hyderabad and Ahmedabad manufacturing clusters. Export-compliant sterile processing infrastructure attracts multinational facility investment. Domestic biotechnology scale-up creates mid-tier equipment demand.
Japan
PMDA sterile processing guidelines and METI industrial policy support vapor hydrogen peroxide system adoption in Kansai and Kanto pharmaceutical corridors. Aging domestic facility stock requires replacement cycles. Osaka-Tokyo biologics manufacturing concentrates premium equipment procurement.
Belgium
Vaccine production facilities in Flanders face mandated EU Green Deal formaldehyde phase-out timelines through 2030. EMA environmental monitoring expectations exceed baseline WHO prequalification standards. Antwerp-Leuven biotech cluster redirects capital expenditure toward validated alternative chemistries.
Global Bio Decontamination Market Competitive Landscape
Portfolio diversification dominates the current landscape as equipment suppliers extend from vapor generator hardware into validated cycle development and ongoing compliance services. Market structure concentrates among three to five integrated multinationals with established pharmaceutical regulatory relationships, while regional specialists occupy mid-tier price points. Strategic archetypes separate into full-service validation providers, modular equipment fabricators, and niche gas chemistry specialists. M&A activity and technology licensing agreements represent the primary competitive vectors as scale advantages consolidate.
Within the full-service validation tier, STERIS plc and Ecolab Inc. exemplify integrated service contract models that bundle equipment deployment with regulatory documentation support. Getinge AB occupies a position among modular system architects targeting isolator-integrated decontamination suites. Among Asian fabricators, Zhejiang TAILIN Bioengineering Co., Ltd. represents regional specialist archetypes focused on cost-optimized equipment configurations for emerging market pharmaceutical corridors.
| Leading Market Players |
|---|
| STERIS plc |
| Ecolab Inc. |
| TOMI Environmental Solutions, Inc. |
| JCE Biotechnology |
| Fedegari Autoclavi SpA |
| ClorDiSys Solutions, Inc. |
| Zhejiang TAILIN Bioengineering Co., Ltd. |
| Getinge AB |
| Noxilizer, Inc. |
| Others |
Supply & Pricing Matrix
EMA Annex 1 validation mandates and FDA process documentation requirements are compressing procurement timelines for pharmaceutical facilities, forcing equipment suppliers to absorb cycle development costs upfront and recover margins through multi-year service contracts rather than hardware premiums.
Pricing Analysis
Distributor margins in North American hospital pharmacy channels have compressed from traditional equipment-procurement markups to thin facilitation fees as health system purchasing coalitions unbundle capital acquisition from validation support. Three-tier pricing structure across premium isolator-integrated suites, standard vapor generators, and economy portable units stratifies by automation depth and regulatory documentation bundled. Pricing pressure stems from mid-tier biotechnology manufacturers in India and Germany demanding throughput-based models over capital expenditure. Academic medical centers exhibit highest price sensitivity due to internal engineering capacity; commercial sterile drug manufacturers show lowest sensitivity given FDA validation risk premiums.
Supply Chain Analysis
Specialized workforce availability in precision welding and PLC programming concentrates equipment fabrication in Germany, the United States, and Japan, constraining capacity expansion for modular vapor generator architectures. Platinum-group catalyst refining for hydrogen peroxide decomposition draws from South African and Russian supply, creating single-source vulnerability for vapor system manufacturers. Stainless steel chamber production and biological indicator fabrication rest on established pharmaceutical equipment supply bases in Italy and Switzerland. Distribution runs through OEM-direct channels for pharmaceutical validation tiers and regional distributor networks for portable hospital units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between FDA process validation intensity and EMA environmental monitoring documentation creates geographic-arbitrage opportunities for contract manufacturing organizations siting facilities in Belgium and Ireland where EU Green Deal timelines accelerate equipment replacement cycles ahead of US compliance pressure.
For Market Incumbents: Deepen vertical integration into biological indicator manufacturing and computational fluid dynamics cycle development services to capture recurring revenue streams as hardware margins compress. Defend against modular equipment fabricators by embedding isolator-agnostic docking protocols that increase switching costs for contract manufacturing organizations operating multi-client protocols. Prioritize certification investment in CDSCO-aligned validation packages for Indian pharmaceutical corridor expansion. For New Entrants and Emerging Players: Contract manufacturing organization procurement managers represent the most accessible channel partner type for mid-tier vapor generator penetration without established regulatory relationships. Target semi-automated solution demand in scaling Boston and Basel biotechnology clusters where capital constraints exceed validation depth requirements. Pursue white-space in UV-C LED laboratory decontamination where residue-free operation specifications exclude incumbent vapor chemistry portfolios. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing validated cycle libraries for EU Green Deal formaldehyde replacement timelines and established CDSCO regulatory submission pathways. Long-term viability favors acquisition targets combining equipment fabrication with captive cycle development expertise rather than pure hardware manufacturers exposed to pricing compression. Watch EMA-FDA regulatory convergence negotiations as inflection signal for multi-territory equipment portfolio valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biological Indicator Manufacturing | Captures recurring validation revenue streams and reduces supplier dependency for critical cycle development inputs. |
| Isolator-Agnostic Docking Protocol Development | Enables rapid reconfiguration between filling line types, compressing equipment utilization rates at contract manufacturing sites. |
| EU Green Deal Validated Cycle Library Expansion | Accelerates regulatory submission packages for Belgian and Irish vaccine facilities facing formaldehyde phase-out mandates. |
| CDSCO-Aligned Validation Package Investment | Opens procurement channels in Hyderabad and Ahmedabad pharmaceutical corridors under PLI scheme incentives. |
| UV-C LED Robotic Positioning System Launch | Addresses laboratory optics decontamination where hydrogen peroxide vapor risks oxidative damage to sensitive equipment. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with sterile processing engineers, regulatory affairs leads at pharmaceutical manufacturers, hospital procurement managers, and aftermarket service heads with secondary validation against FDA 483 inspection observations, EMA Annex 1 revision documentation, and WHO prequalification standards. Bottom-up equipment shipment tallies and top-down pharmaceutical capital expenditure estimates were triangulated to anchor market sizing.
Segment-weighting approaches modeled hydrogen peroxide vapor, ultraviolet radiation, and gas-based alternatives across pharmaceutical manufacturing, food processing, laboratory, and transit applications, with deployment mode and end-user granularity. CAGRs were derived from regulatory mandate timelines and replacement cycle analysis across the projection horizon. Forecast inputs incorporated EMA-FDA regulatory divergence indices and EU Green Deal chemical restriction phase-out schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to platinum-group catalyst supply disruptions, regulatory harmonization negotiations, and biotechnology manufacturing scale-up rates. Material deviation in EMA Annex 1 enforcement intensity or CDSCO-PIC/S alignment pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Biotechnology
Plastic-Eating Bacteria Market
Environmental Biotechnology
Blue Biotechnology Market
Environmental Biotechnology
North America Biosolids Market
Environmental Biotechnology
Bioremediation Market
Environmental Biotechnology
Bio-Detection Market
Environmental Biotechnology
Enzymatic Cleaning Market
Environmental Biotechnology
Global Anaerobic Digestion Market
Environmental Biotechnology
Europe Anaerobic Digestion Market