
 Middle East and Africa Plasma Fractionation Market | 2026-2036
Middle East and Africa Plasma Fractionation Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Plasma Fractionation Market Foresight
Plasma-derived product maintenance and cold-chain service contracts is hardening into a core revenue layer for fractionators serving the Middle East and Africa. CSL Limited leverages its integrated logistics network to sustain temperature-controlled distribution across Gulf and sub-Saharan corridors. Grifols, S.A. anchors its regional presence through specialized albumin and immunoglobulin supply partnerships with tertiary hospitals. Kedrion Biopharma competes by concentrating on coagulation factor concentrates for hemophilia treatment centers in North and East Africa.
Plasma fractionation is the industrial separation of blood plasma into purified protein fractions—albumin, immunoglobulins, and coagulation factors—through sequential precipitation, chromatography, and viral inactivation at controlled pH and temperature parameters. These fractions serve as essential therapeutics for clotting disorders, immune deficiencies, and critical care volume replacement. Immunoglobulin commands the deepest margin pools across the Middle East and Africa due to rising diagnostic rates of primary immunodeficiency and expanding off-label neurology applications. Albumin remains the volume anchor in therapeutic uses, particularly in liver cirrhosis and burn management protocols at major hospitals. Coagulation factor concentrates represent the fastest-growing product category as national hemophilia registries in Saudi Arabia and South Africa improve patient identification and prophylaxis access.
The Saudi Food and Drug Authority enforces viral safety and Good Manufacturing Practice standards that shape import authorization timelines for plasma-derived products. South Africa's Medicines Control Council and the UAE's Ministry of Health and Prevention apply parallel pharmacovigilance and batch-release requirements that filter which fractionators gain sustainable market access. Stakeholders must monitor how national blood policy shifts toward local plasma collection versus import dependence will reshape supply security and pricing dynamics across the region.
Market Dynamics
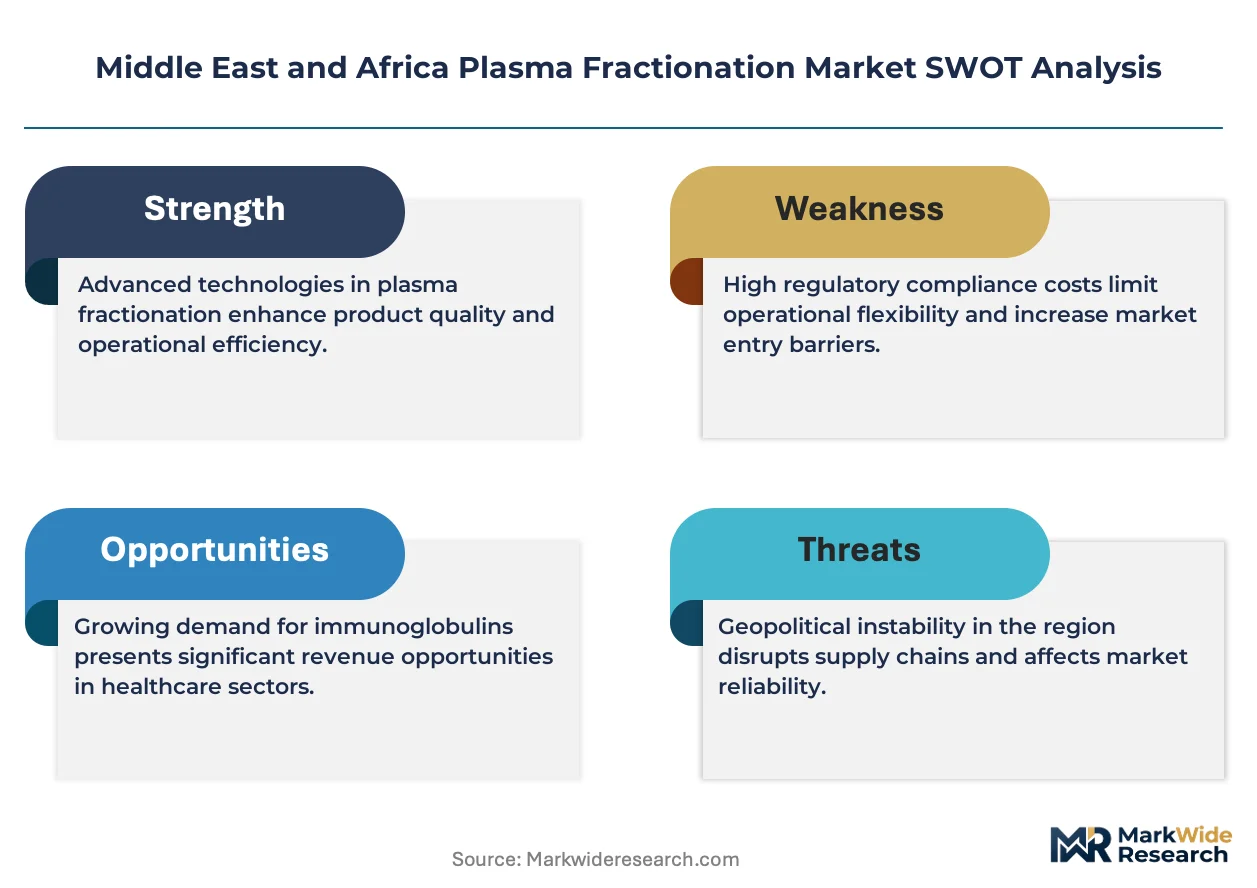
Cold-chain infrastructure gaps and regulatory divergence between Gulf and sub-Saharan jurisdictions are fragmenting supply security for plasma-derived therapeutics across the Middle East and Africa.
Growth Catalysts
- SFDA viral-inactivation mandates:Saudi Arabia's tightened batch-release standards are filtering out lower-tier suppliers and elevating certified fractionators into preferred procurement tiers at tertiary hospitals.
- Hemophilia center expansion:National patient registries in South Africa and Saudi Arabia are identifying undiagnosed cases and expanding prophylaxis access for coagulation factor concentrates.
- Immunoglobulin neurology off-label use:Neurology departments at UAE teaching hospitals are driving demand for intravenous immunoglobulin beyond approved immunodeficiency indications.
Market Restraints
- Import dependency concentration:Over 90% of plasma-derived products in the Gulf and sub-Saharan Africa originate from European and North American fractionators, creating supply vulnerability during geopolitical disruptions.
- Albumin price volatility:Raw plasma collection costs in source markets fluctuate with donor compensation regulations, compressing margins for regional distributors locked into annual hospital contracts.
- Sub-Saharan cold-chain gaps:Temperature excursions during last-mile distribution to East African hemophilia treatment centers degrade product potency and trigger regulatory rejection.
Strategic Opportunities
- Ethiopian hemophilia network:The country's nascent national bleeding disorder registry and partnership with the World Federation of Hemophilia creates first-mover access for coagulation factor suppliers.
- Mobile cold-chain units:Solar-powered refrigeration trailers are enabling temperature-controlled distribution to remote South African and Kenyan treatment centers previously unreachable by conventional logistics.
- MOHAP fast-track authorization:The UAE's streamlined pathway for plasma products with prior FDA or EMA approval accelerates market entry timelines for certified fractionators.
Industry Challenges
- Specialized biologics logistics talent:Shortages of cold-chain validation engineers and pharmacovigilance officers with plasma product expertise delay facility certifications across the Gulf.
- Legacy blood bank integration:Hospital information systems at South African public hospitals require expensive middleware upgrades to track lot-level plasma product inventory and adverse event reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Plasma Fractionation Market |
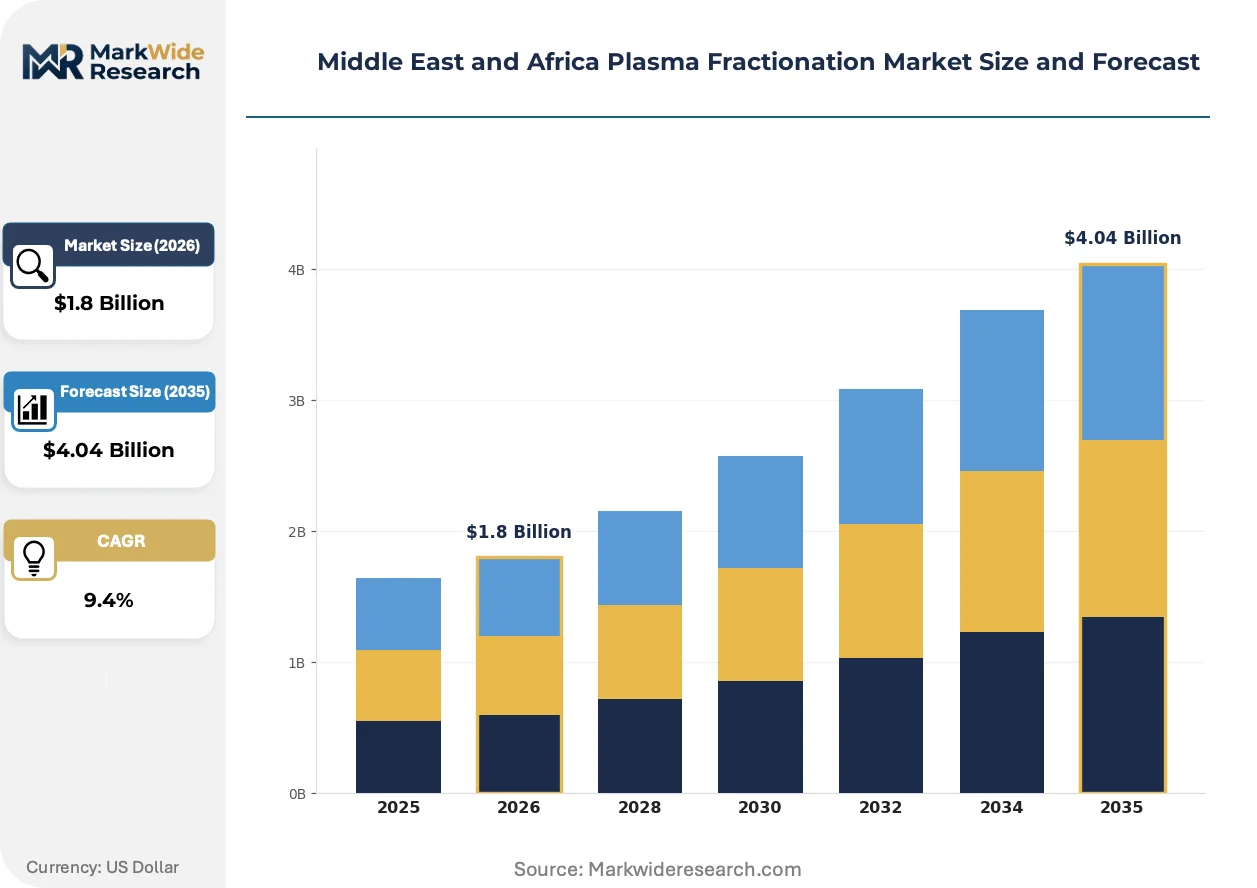
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coagulation Factor Concentrates, Albumin, Immunoglobulin, Other Plasma Products End User: Hospitals, Blood Banks, Research Laboratories, Pharmaceutical Companies Technology: Affinity Chromatography, Precipitation, Filtration, Centrifugation Application: Therapeutic Uses, Immunotherapy, Hemophilia Treatment, Hyperimmune Globulin Therapy |
| Companies Covered | Bharat Serums and Vaccines Limited, Bio Products Laboratory Ltd., Biotest AG, CSL Limited, Grifols, S.A., Kedrion Biopharma, Octapharma AG, Takeda Pharmaceutical Company Limited, LFB, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Plasma Fractionation Market Shifts & Advancements
Fractionators are embedding digital traceability and modular production technologies to satisfy divergent regulatory demands while extending reach into underpenetrated African markets.
Chromatography-based viral inactivation is integrating nanofiltration membranes with solvent-detergent treatment to achieve higher pathogen clearance rates without denaturing heat-sensitive coagulation factors. Saudi tertiary hospitals are specifying this dual-technology standard in procurement tenders. The shift is integrating premium safety specifications into contract eligibility criteria and excluding fractionators with single-method inactivation.
SFDA and MOHAP are synchronizing pharmacovigilance reporting formats with EMA standards to reduce duplicate documentation for fractionators holding European marketing authorizations. This regulatory convergence compresses post-approval compliance costs for multi-jurisdiction suppliers. Hemophilia treatment centers in Dubai and Riyadh are benefiting from accelerated adverse event response protocols as a result.
Hospital procurement departments are consolidating plasma-derived product purchasing into multi-year framework agreements with integrated logistics providers. Single-source contracts covering albumin, immunoglobulin, and coagulation factors are displacing fragmented supplier relationships. South Africa's largest private hospital groups are piloting this model in Gauteng and Western Cape provinces.
Middle East and Africa Plasma Fractionation Market Segmentation
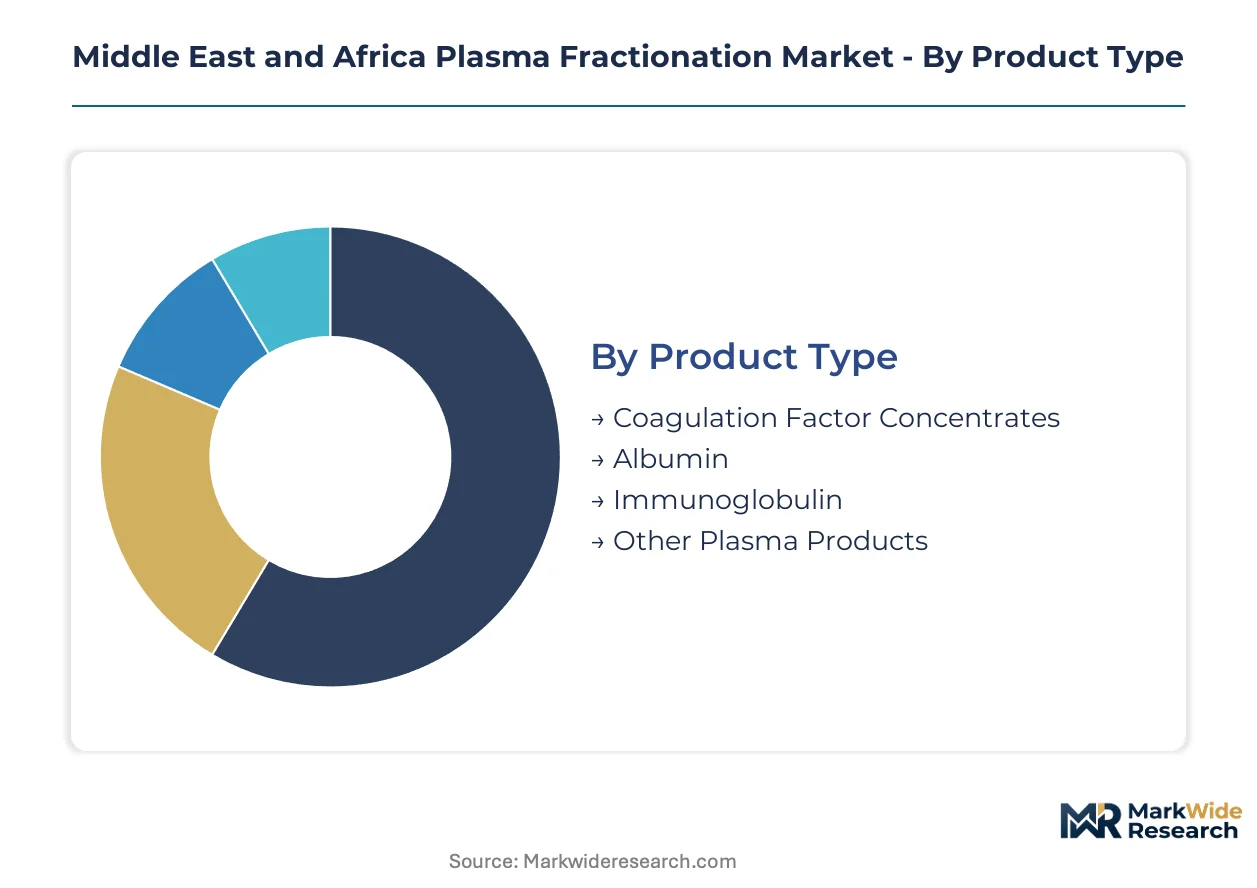
Plasma fractionation markets segment across therapeutic protein categories, clinical settings, purification technologies, and disease indications. Each dimension shapes procurement patterns, margin structures, and regulatory compliance burdens for suppliers operating across Gulf and sub-Saharan corridors.
Product Type:
Standalone therapeutic proteins command premium positioning against embedded multi-product formulations, with margin profiles diverging sharply across purification complexity and viral safety certification tiers.
- Immunoglobulin:Polyclonal antibody preparations derived from pooled plasma donations undergo caprylate precipitation and anion exchange chromatography to achieve therapeutic purity. Demand concentrates in tertiary immunology units at Saudi Arabian and UAE teaching hospitals, where neurology departments are expanding intravenous immunoglobulin protocols beyond primary immunodeficiency into off-label autoimmune indications. Diagnostic expansion for common variable immunodeficiency across Gulf Cooperation Council states is deepening hospital formulary placement.
- Coagulation Factor Concentrates:Recombinant and plasma-derived clotting factors VIII, IX, and von Willebrand factor undergo nanofiltration and solvent-detergent viral inactivation. Hemophilia treatment centers in Johannesburg, Riyadh, and Dubai are driving procurement volume as national patient registries identify previously undiagnosed cases and expand prophylaxis access programs.
- Albumin:Heat-treated plasma protein fraction serves volume expansion and protein replacement in critical care settings across South African public hospitals and Gulf private hospital chains.
- Other Plasma Products:C1 esterase inhibitors, alpha-1 antitrypsin, and fibrin sealants address niche indications with concentrated demand at specialized surgical centers.
Volume placements concentrate in Albumin; the faster expansion belongs to Coagulation Factor Concentrates.
End User:
Customer type determines contract structure, with centralized procurement at hospital networks contrasting fragmented purchasing at independent blood banks and research facilities.
- Hospitals:Tertiary medical centers across Saudi Arabia, South Africa, and the UAE operate specialized hemophilia treatment centers, immunology units, and burn centers that drive concentrated demand for albumin, immunoglobulin, and coagulation factors. South Africa's largest private hospital groups are consolidating plasma-derived product purchasing into multi-year framework agreements covering Gauteng and Western Cape provinces.
- Blood Banks:National blood services in Saudi Arabia and South Africa manage plasma collection, testing, and distribution to fractionators, with limited on-site fractionation capacity creating dependency on imported finished products.
- Research Laboratories:Academic medical centers in Cairo, Nairobi, and Lagos conduct clinical trials and basic research on plasma protein therapeutics, generating specialized demand for small-batch, high-purity fractions.
- Pharmaceutical Companies:Regional distributors and local affiliates of multinational fractionators manage importation, cold-chain logistics, and hospital contracting across Gulf and sub-Saharan markets.
Procurement scale peaks at Hospitals; Research Laboratories are gaining share fastest as clinical trial activity expands.
Technology:
Purification method selection determines viral safety profiles, yield efficiency, and capital intensity, with Saudi and UAE regulators specifying dual-technology standards in procurement tenders.
- Affinity Chromatography:Ligand-based separation achieves high specificity for immunoglobulin and coagulation factor isolation, with protein A and protein G resins commanding premium positioning in high-purity therapeutic manufacturing.
- Precipitation:Ethanol fractionation remains the volume workhorse for albumin and immunoglobulin production, with Cohn and Kistler-Nitschmann process variants dominating legacy fractionation facilities.
- Filtration:Nanofiltration membranes integrate with chromatography and precipitation trains to achieve viral clearance, with Saudi tertiary hospitals specifying this dual-technology standard in procurement eligibility criteria.
- Centrifugation:Density gradient separation supports plasma component isolation in blood bank processing and early-stage fractionation, with continuous-flow centrifugation enabling high-throughput operations.
Deployment breadth spans Precipitation; capability investment is concentrating most heavily in Filtration.
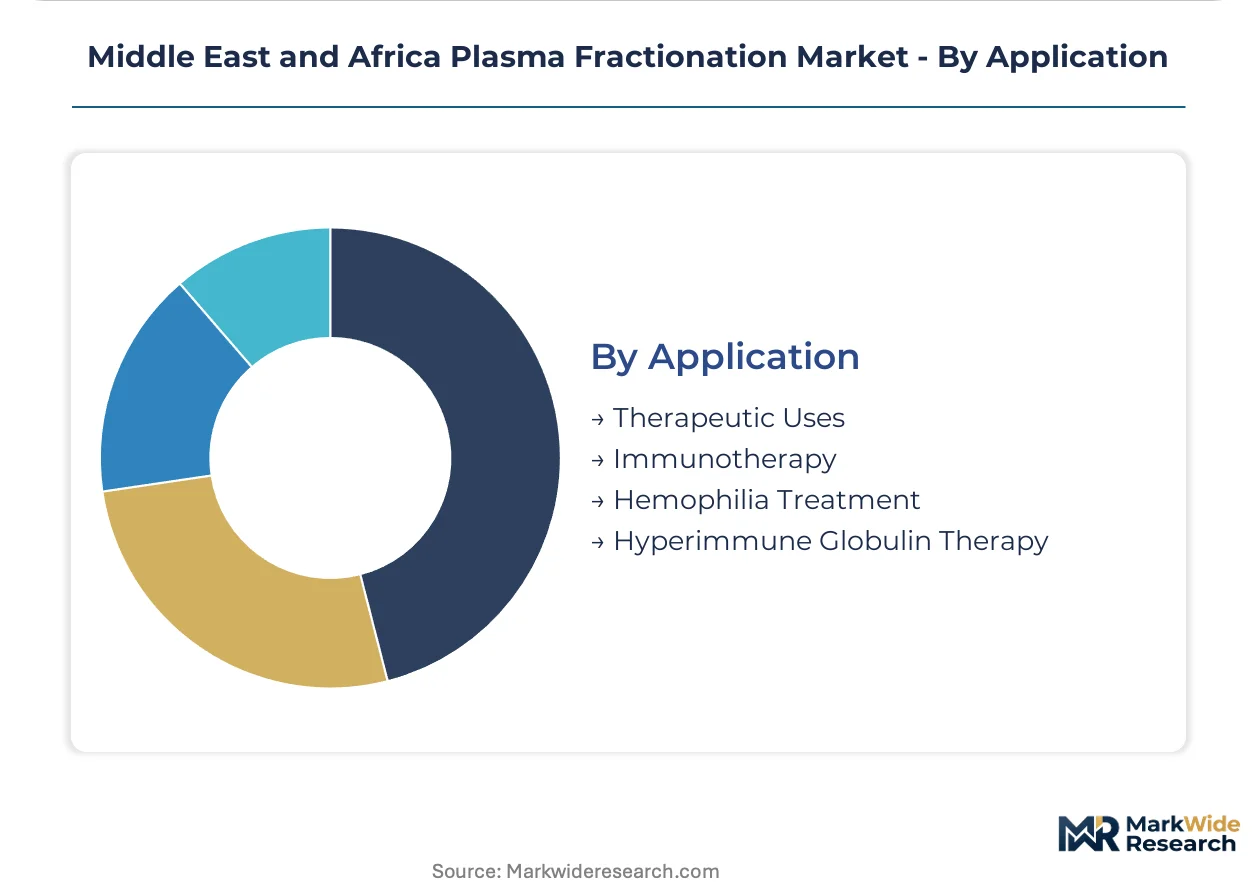
Application:
Clinical indication shapes dosing protocols, reimbursement pathways, and prescriber specialization requirements across the region's expanding therapeutic access programs.
- Hemophilia Treatment:Factor replacement therapy for hemophilia A and B patients requires specialized coagulation factor concentrates, with prophylaxis protocols expanding at treatment centers in Riyadh, Dubai, and Johannesburg as national registries improve case identification.
- Therapeutic Uses:Albumin administration for hypovolemia, hypoalbuminemia, and burn management represents the highest-volume application across Middle East and Africa hospital systems.
- Immunotherapy:Intravenous and subcutaneous immunoglobulin for primary and secondary immunodeficiency, with neurology departments at UAE teaching hospitals driving off-label expansion into autoimmune neurological conditions.
- Hyperimmune Globulin Therapy:Pathogen-specific antibody preparations for tetanus, hepatitis B, and rabies post-exposure prophylaxis serve concentrated demand at trauma and infectious disease centers.
Patient volume concentrates in Therapeutic Uses; protocol expansion is accelerating most rapidly in Hemophilia Treatment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh anchors plasma fractionation procurement across the Gulf, with King Faisal Specialist Hospital operating one of the region's largest hemophilia treatment centers and driving concentrated demand for coagulation factor concentrates.
Saudi Arabia
Specialized immunology units at King Saud University Medical City and King Fahad Medical City are expanding intravenous immunoglobulin protocols for neurological indications. The Saudi Food and Drug Authority enforces dual-technology viral inactivation standards that filter procurement eligibility at tertiary hospitals. Jeddah's private hospital corridor is consolidating multi-year framework agreements covering albumin, immunoglobulin, and coagulation factors.
United Arab Emirates
Dubai's Cleveland Clinic Abu Dhabi and Mediclinic City Hospital are driving demand for albumin in critical care and burn management protocols. The Ministry of Health and Prevention operates a fast-track authorization pathway for plasma products with prior FDA or EMA approval, compressing market entry timelines. Abu Dhabi's Sheikh Khalifa Medical City is piloting solar-powered mobile cold-chain units for remote distribution.
South Africa
Johannesburg's Charlotte Maxeke Academic Hospital and Chris Hani Baragwanath Hospital operate specialized hemophilia treatment centers expanding prophylaxis access for previously undiagnosed patients. The Medicines Control Council applies parallel pharmacovigilance and batch-release requirements that shape which fractionators gain sustainable market access. Cape Town's private hospital groups are consolidating plasma-derived product purchasing into integrated logistics contracts.
Egypt
Cairo's Ain Shams University Hospital and National Cancer Institute generate specialized demand for small-batch, high-purity plasma fractions in clinical trial and research applications. The country's national pharmaceutical regulator maintains import authorization timelines that favor fractionators with established cold-chain partnerships. Alexandria's teaching hospitals are expanding diagnostic capacity for primary immunodeficiency disorders.
Ethiopia
Addis Ababa's Tikur Anbessa Specialized Hospital anchors the country's nascent national bleeding disorder registry in partnership with the World Federation of Hemophilia. The national health ministry is developing plasma collection infrastructure to reduce import dependence for coagulation factor concentrates. Regional treatment centers in Hawassa and Bahir Dar remain dependent on temperature-controlled distribution from the capital.
Middle East and Africa Plasma Fractionation Market Competitive Landscape
Capital-heavy integrated fractionators compete with specialized plasma product distributors across Middle East and Africa corridors. The supplier base concentrates around European and North American parent companies with regional logistics affiliates, creating tiered access based on viral safety certification and cold-chain capability. Three archetypes dominate: vertically integrated multinationals with captive plasma collection, specialized immunoglobulin and coagulation factor suppliers, and regional distributors managing importation and hospital contracting. Competitive positioning hinges on multi-year framework agreements with tertiary hospital networks and regulatory synchronization with SFDA and MOHAP standards.
Among the integrated multinational tier, CSL Limited and Grifols, S.A. exemplify archetypes built on captive plasma supply and temperature-controlled distribution infrastructure. Kedrion Biopharma occupies a specialized position within the coagulation factor segment, reflecting the strategic concentration on hemophilia treatment center partnerships. These three entities represent distinct competitive vectors—integrated logistics, hospital supply partnerships, and therapeutic specialization—that structure procurement dynamics across Gulf and sub-Saharan markets.
| Leading Market Players |
|---|
| Bharat Serums and Vaccines Limited |
| Bio Products Laboratory Ltd. |
| Biotest AG |
| CSL Limited |
| Grifols, S.A. |
| Kedrion Biopharma |
| Octapharma AG |
| Takeda Pharmaceutical Company Limited |
| LFB |
| Others |
Supply & Pricing Matrix
Dual-technology viral inactivation certification separates premium plasma product tiers from commodity-grade alternatives across Middle East and Africa procurement channels. This bifurcation concentrates pricing power with European and North American fractionators holding SFDA and MOHAP approvals while locking regional distributors into annual hospital contracts with thin margin buffers. Cold-chain service bundling increasingly determines contract eligibility, embedding logistics costs into landed pricing structures for Gulf and sub-Saharan deliveries.
Pricing Analysis
Margin tightening in standard-grade albumin reflects raw plasma collection cost volatility in European and North American source markets. Contract-based long-term offtake agreements dominate hospital procurement, with pricing stratifying across premium dual-technology certified, standard single-method, and economy-grade tiers based on viral safety documentation and cold-chain assurance. Cost-down pressure on regional distributors accelerates because Saudi and UAE tertiary hospitals are consolidating purchasing into multi-year framework agreements with integrated logistics providers. Public hospital buyers in South Africa exhibit highest price sensitivity due to constrained national health budgets, while private hospital chains in Dubai and Riyadh prioritize certification tier over unit cost.
Supply Chain Analysis
Workforce shortages of cold-chain validation engineers and pharmacovigilance officers in Saudi Arabia and the UAE delay facility certifications and extend import authorization timelines. Supply concentrates in Germany, Switzerland, and the United States as primary manufacturing geographies for plasma-derived therapeutics entering Middle East and Africa markets. Raw material dependencies center on source plasma collections from compensated donor programs in the United States and European voluntary donation networks. Single-source vulnerability characterizes regional risk profiles, with over ninety percent of finished products originating from a concentrated base of certified fractionators. Distribution runs through temperature-controlled logistics networks anchored at Jeddah, Dubai, and Johannesburg hubs, with last-mile solar-powered refrigeration units penetrating previously unreachable East African treatment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chromatography-based viral inactivation paired with nanofiltration membranes is displacing legacy single-method inactivation across Saudi and UAE procurement specifications, rewarding fractionators with dual-technology capabilities and excluding suppliers with outdated purification trains.
For Market Incumbents: Extend dual-technology certification coverage across all product lines to maintain preferred supplier status at SFDA-regulated tertiary hospitals. Consolidate cold-chain partnerships with regional logistics affiliates in Jeddah and Dubai to defend against emerging distributors offering bundled service contracts. Prioritize pharmacovigilance officer recruitment in Riyadh and Abu Dhabi to accelerate adverse event response protocols and differentiate from competitors facing workforce constraints. For New Entrants and Emerging Players: Mobile cold-chain technology offers a technology-first wedge into Ethiopian and Kenyan hemophilia treatment centers previously unreachable by conventional distribution. Target the nascent national bleeding disorder registry in Addis Ababa as the most penetrable geography, where first-mover relationships with the World Federation of Hemophilia create procurement pathway advantages. Pursue MOHAP fast-track authorization leveraging prior FDA or EMA approvals to compress market entry timelines against established regional distributors. For Investors and Strategic Acquirers: Re-rating potential sits with specialized coagulation factor suppliers given expanding prophylaxis access programs at Saudi and South African hemophilia treatment centers. Long-term viability over the projection horizon favors fractionators with captive plasma collection and integrated logistics infrastructure over pure-play distributors exposed to import dependency concentration. Monitor national blood policy shifts toward local plasma collection as the critical inflection indicator for supply security and pricing dynamics across the region.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Technology Viral Inactivation Certification | SFDA procurement eligibility now mandates combined chromatography and nanofiltration standards at Saudi tertiary hospitals. |
| Solar-Powered Mobile Cold-Chain Deployment | Abu Dhabi's Sheikh Khalifa Medical City pilot extends temperature-controlled distribution to remote East African centers. |
| Multi-Year Framework Agreement Consolidation | South African private hospital groups in Gauteng and Western Cape integrate albumin, immunoglobulin, and coagulation factor purchasing. |
| Pharmacovigilance Reporting Synchronization | SFDA and MOHAP alignment with EMA standards reduces duplicate documentation for European-authorized fractionators. |
| National Bleeding Disorder Registry Partnership | Ethiopia's collaboration with the World Federation of Hemophilia creates first-mover access for coagulation factor suppliers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis of Middle East and Africa plasma fractionation markets. Primary interviews with fractionation supply chain directors, hospital procurement managers at Saudi and South African tertiary centers, cold-chain logistics specialists, and national blood service administrators combined with secondary validation from SFDA and MOHAP regulatory databases, EMA marketing authorization documentation, and World Federation of Hemophilia registry publications. Bottom-up patient population modeling and top-down import volume triangulation established market size boundaries across the analysis window.
Segmentation granularity operated at product type, end user, purification technology, and clinical application dimensions, with regional regulatory cluster and cold-chain infrastructure tier as additional plasma-specific modeling layers. CAGRs derived from patient registry expansion rates, prophylaxis protocol penetration curves, and hospital procurement contract renewal patterns across Saudi Arabia, UAE, South Africa, Egypt, and Ethiopia. Forecast inputs incorporated hemophilia treatment center expansion timelines and national blood policy evolution toward local plasma collection versus import dependence.
Several conditions sit outside the modeled scope, including geopolitical disruptions affecting European and North American plasma collection, abrupt regulatory rejection of established viral inactivation methods, and catastrophic cold-chain failures degrading product potency at sub-Saharan distribution points. Forecasts reflect assumptions regarding sustained import authorization pathways and stable donor compensation regulations in source markets. Material deviation in SFDA batch-release timelines, national blood policy direction, or Gulf-sub-Saharan logistics corridor stability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
Global Drug Discovery Market
Biopharmaceuticals
Interleukin-6 (IL-6) Inhibitors Market
Biopharmaceuticals
1-Step RT-PCR Kits Market
Biopharmaceuticals
North America Diabetes Drugs Market
Biopharmaceuticals
Global Carboprost Tromethamine Market
Biopharmaceuticals
Norethisterone Enanthate API Market
Biopharmaceuticals
Protein Therapeutics Market
Biopharmaceuticals
Global Branded Generics Market
Biopharmaceuticals
Generic Oncology Drugs Market
Biopharmaceuticals
Global Biopharmaceutical Fermentation Systems Market
Biopharmaceuticals
Europe Insulin Pens Market
Biopharmaceuticals
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market
Biopharmaceuticals
Recombinant Human Interferon Protein Market
Biopharmaceuticals
North America Biotechnology Market
Biopharmaceuticals
Oseltamivir Market