
 Global Bioreactor Market | 2026-2036
Global Bioreactor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bioreactor Market Analysis
Market Context
GMP-grade stainless steel specifications is collapsing the historical cost gap with single-use alternatives for campaigns above two thousand liters. Merck KGaA leverages its MabSolute platform to anchor high-titer perfusion contracts across European CDMO networks. Danaher Corporation sustains instrumentation pull-through via its Pall Allegro single-use ecosystem. Thermo Fisher Scientific dominates North American service bundling by integrating bioreactor hardware with cell-line development and media formulation.
Technical Definition and Structural Segments
A bioreactor is a closed vessel engineered to maintain controlled temperature, pH, dissolved oxygen, and agitation for the cultivation of microbial, mammalian, or plant cells, typically operating at working volumes from one liter to twenty thousand liters with sterile boundary integrity maintained via steam-in-place or gamma-irradiated film barriers. Its primary commercial purpose is the scalable production of monoclonal antibodies, recombinant proteins, viral vectors, and cell therapies under reproducible quality parameters. Stirred-tank systems retain the largest installed base across protein production applications due to decades of operational familiarity and established scale-up correlations, while single-use bioreactors capture the fastest expansion in gene therapy manufacturing where campaign changeover speed and cross-contamination risk reduction override per-unit consumable costs. Continuous flow bioreactors occupy an emerging margin pool as perfusion process analytical technology matures, though regulatory filing complexity limits near-term penetration beyond biosimilar and contract manufacturing settings.
Regulatory Frame and Outlook
The FDA enforces process validation guidance under ICH Q5A through Q11, while the EMA's MDR and Annex 1 revisions impose stricter closed-system requirements for aseptic bioprocessing; China's NMPA accelerates biologics approval pathways but demands localized manufacturing data for imported systems. These frameworks collectively elevate barrier-to-entry for new bioreactor vendors and compel incumbent suppliers to maintain dual validation documentation across FDA and EMA jurisdictions. Stakeholders must monitor how the EU AI Act and emerging FDA guidance on real-time release testing reshape sensor integration and software qualification requirements for next-generation smart bioreactor platforms.
Market Dynamics
Perfusion process analytical technology is collapsing batch-cycle economics across mammalian cell culture, forcing stainless steel incumbents and single-use challengers into direct capacity competition for high-titer monoclonal antibody contracts.
Growth Catalysts
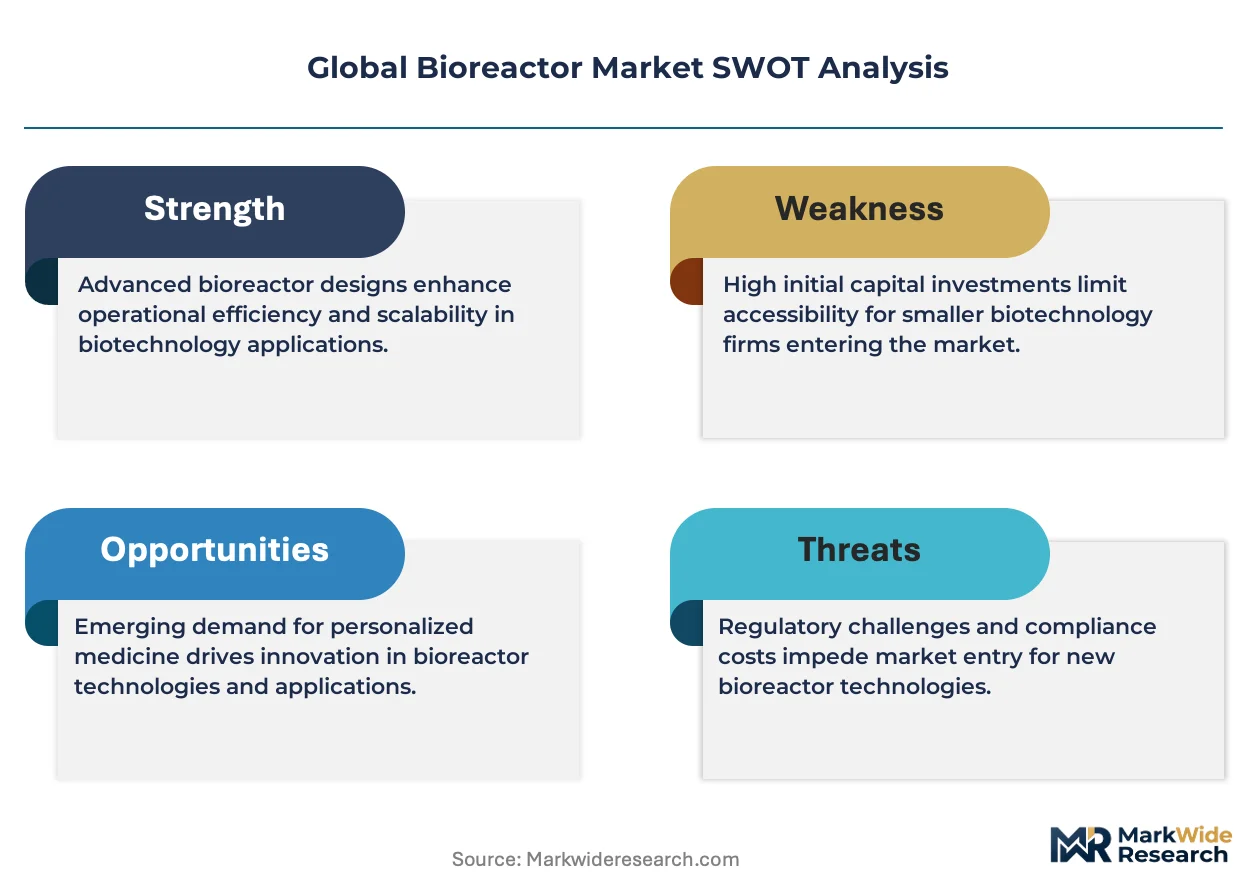
- EMA Annex 1 closed-system mandates:The 2022 revision compels aseptic bioprocessing upgrades across European sterile manufacturing facilities, accelerating replacement demand for legacy open-vessel systems.
- Gene therapy manufacturing scale-up:Viral vector production requirements for AAV and lentivirus platforms are pulling single-use bioreactor capacity into multi-thousand-liter configurations previously dominated by stainless steel.
- Continuous processing validation frameworks:ICH Q13 implementation harmonizes real-time release testing protocols, reducing regulatory filing friction for perfusion-based commercial campaigns.
Market Restraints
- Gamma-irradiated film supply concentration:Single-use bioreactor assembly depends on five specialized polymer suppliers concentrated in Germany and the United States, creating input vulnerability for CDMO fleet expansions.
- Steam-in-place infrastructure lock-in:Existing stainless steel facilities face stranded asset risk from twenty-year depreciation schedules that conflict with single-use transition timelines.
- Skilled bioprocess engineer scarcity:Perfusion operation demands specialized metabolic flux modeling expertise that outpaces university training pipeline output in China and India.
Strategic Opportunities
- Brazilian biosimilar localization:ANVISA's abbreviated approval pathway for monoclonal antibody copies creates first-mover advantage for bioreactor vendors establishing Sao Paulo service infrastructure.
- Digital twin integration:Convergence of computational fluid dynamics with machine learning process control enables predictive scale-up modeling that reduces validation batch requirements.
- Modular facility deployment:Prefabricated cleanroom pods with pre-qualified single-use bioreactor trains compress facility construction timelines for emerging biotech entrants.
Industry Challenges
- Cross-platform sensor standardization:Proprietary dissolved oxygen and pH probe interfaces from dominant instrumentation vendors complicate multi-supplier bioreactor fleet integration.
- Extractables and leachables documentation:Film qualification for single-use contact materials demands eighteen-month stability studies that delay new product introduction timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bioreactor Market |
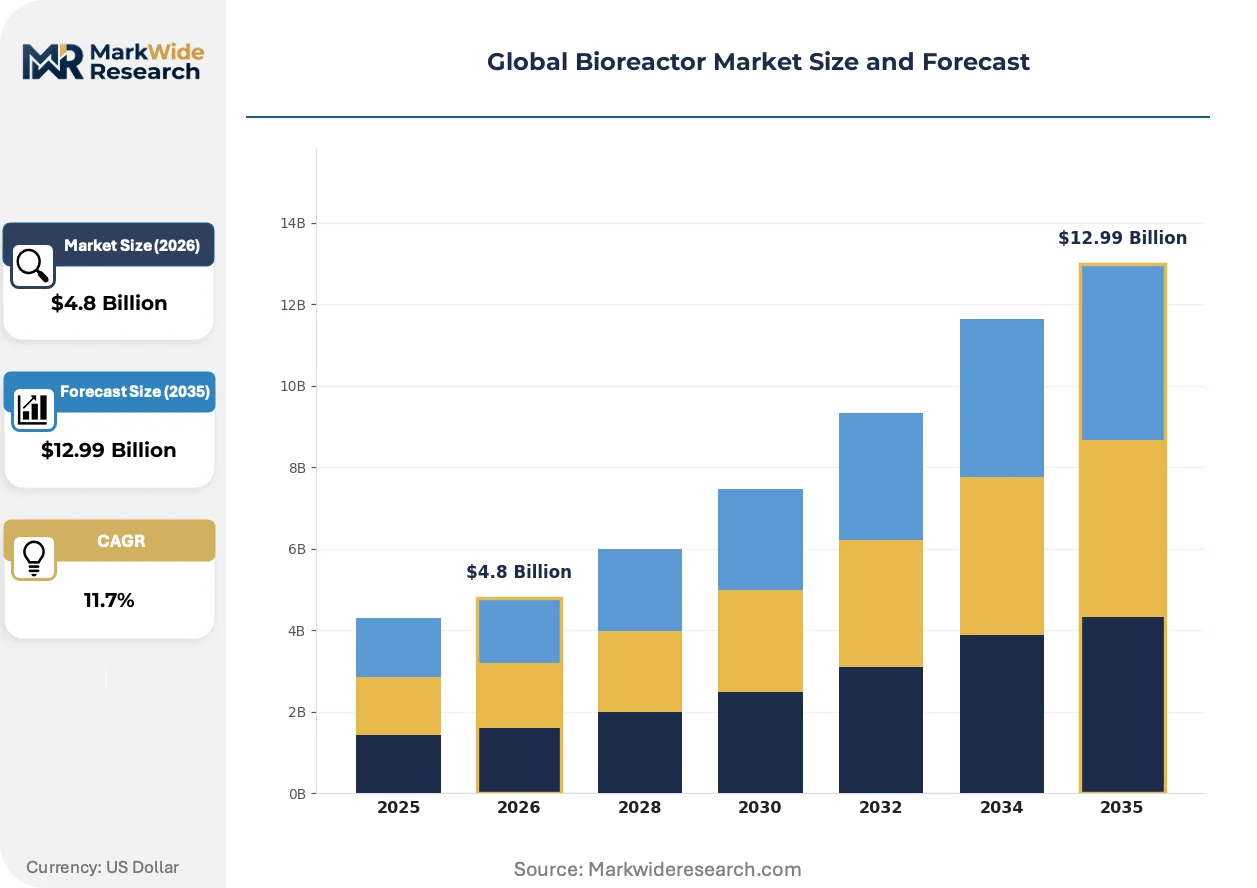
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stirred Tank, Wave Bioreactor, Single-Use, Continuous Flow End User: Pharmaceutical Companies, Academic Institutions, Biotechnology Firms, Research Laboratories Material: Glass, Stainless Steel, Polypropylene, Silicone Application: Protein Production, Cell Culture, Vaccine Development, Gene Therapy |
| Companies Covered | Merck KGaA, GE Healthcare, Danaher Corporation, Praj Industries Limited, Solaris Biotech, Thermo Fisher Scientific, Eppendorf AG, Applikon Biotechnology, Sartorius AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bioreactor Market Emerging Trajectories
Bioreactor architecture is bifurcating between high-throughput perfusion platforms for complex biologics and flexible single-use trains for multi-product CDMO operations, with software-defined process control emerging as the decisive differentiation layer.
Micro-bioreactor scale-down models are fragmenting traditional pilot-scale validation workflows. Ambr 15 and 250 systems from Sartorius enable parallel design-of-experiments screening that compresses cell line and media optimization timelines. Contract manufacturers now deploy these systems as competitive weapons to secure early-phase biotech partnerships, displacing conventional five-liter glass vessel campaigns.
FDA's emerging guidance on real-time release testing is reshaping sensor integration requirements for commercial bioreactor installations. The draft framework mandates redundant in-line analytics for critical quality attributes, elevating capital costs for new stainless steel facilities. Multi-product CDMOs in the United States are responding by front-loading process analytical technology investments into single-use platforms to preserve campaign flexibility.
Biopharma procurement teams are consolidating bioreactor hardware, media, and cell-line development under single-source service contracts. Thermo Fisher Scientific and Danaher Corporation capture this bundled demand through integrated offering structures that lock out standalone equipment vendors. The shift is most pronounced among mid-cap biotechs in Massachusetts and California seeking to outsource manufacturing risk without managing multiple supplier relationships.
Global Bioreactor Market Segmentation
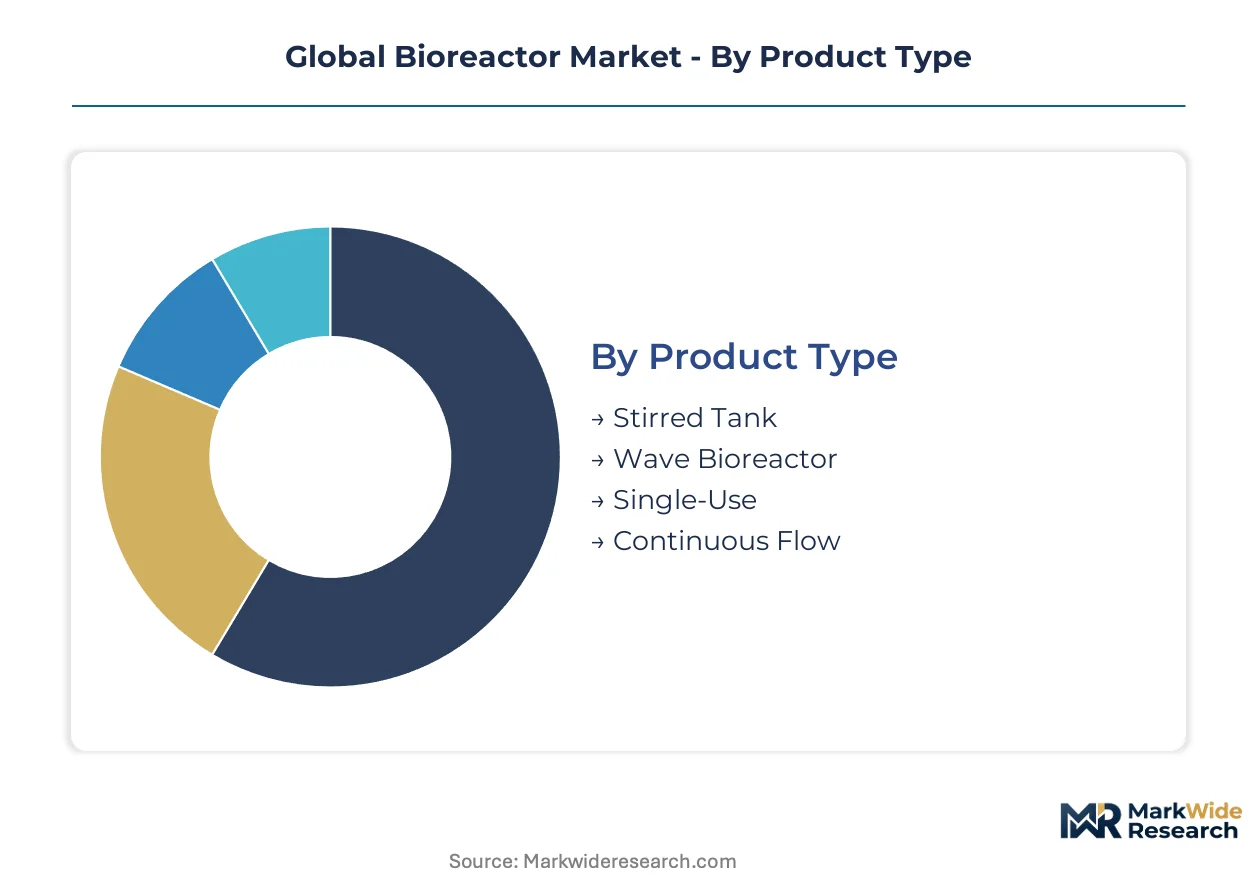
Bioreactor procurement patterns diverge sharply across product architectures and end-use contexts. CDMOs prioritize single-use flexibility against stainless steel scale economics, while gene therapy developers drive material specifications that differ fundamentally from traditional protein manufacturers.
Product Type:
Channel flow splits between capital-intensive stainless steel installations and consumables-driven single-use fleets, with perfusion platforms emerging as a hybrid third channel.
- Stirred Tank:Mechanical agitation systems with impeller-driven mixing and jacketed temperature control dominate commercial-scale monoclonal antibody production. Demand concentrates among established pharmaceutical manufacturers in Germany and the United States seeking twenty-thousand-liter campaign volumes where per-batch economics override cleaning validation burdens.
- Single-Use:Gamma-irradiated polymer film vessels eliminate steam-in-place infrastructure and enable four-hour campaign changeovers. Gene therapy CDMOs in Massachusetts and California are pulling capacity into two-thousand-liter configurations previously reserved for stainless steel, driven by viral vector manufacturing timelines.
- Wave Bioreactor:Rocking-motion platforms with disposable cell culture bags serve as entry-level mammalian culture systems for academic and emerging biotech settings.
- Continuous Flow:Perfusion bioreactors with cell retention devices enable steady-state operation at elevated cell densities, capturing process development interest despite regulatory filing complexity.
Stirred tank systems dominate installed base. Single-use configurations are where expansion concentrates.
End User:
Customer scale and technical sophistication determine whether bioreactor sales flow through direct OEM relationships or distribution partnerships.
- Pharmaceutical Companies:Multinational drug manufacturers with captive biologics capacity specify validated stainless steel trains for blockbuster antibody portfolios. Internal engineering teams demand extensive FAT/SAT documentation and decade-long spare parts guarantees.
- Biotechnology Firms:Venture-backed developers outsource manufacturing risk to CDMOs or deploy modular single-use facilities for asset-specific production. Boston and San Diego clusters show highest concentration of sub-thousand-liter flexible installations.
- Academic Institutions:University research programs purchase small-scale glass and single-use systems through laboratory supply distributors, prioritizing grant-funded capital constraints over throughput optimization.
- Research Laboratories:Government and private research institutes operate bench-top and pilot-scale vessels for early-stage cell line characterization and media screening studies.
Pharmaceutical companies anchor revenue concentration. Biotechnology firms are climbing the fastest.
Material:
Material selection locks manufacturers into specific supply chain and validation pathways with divergent cost structures.
- Stainless Steel:Electropolished 316L grade with Ra surface finishes below 0.8 micrometers satisfies FDA and EMA aseptic processing requirements for multi-year commercial campaigns. German and Swiss precision fabricators control high-purity welding and passivation expertise.
- Glass:Borosilicate vessels with magnetic drive seals enable visual process monitoring for laboratory-scale optimization and teaching applications.
- Polypropylene:Gamma-stable thermoformed films constitute single-use bioreactor contact layers, with specialized polymer suppliers concentrated in Germany and the United States creating input bottlenecks.
- Silicone:Platinum-cured tubing and gasket materials provide flexible connections in hybrid stainless steel installations requiring single-use downstream integration.
Stainless steel commands capital expenditure share. Polypropylene is gaining share fastest.
Application:
Application-specific process requirements reshape bioreactor specification priorities across therapeutic modalities.
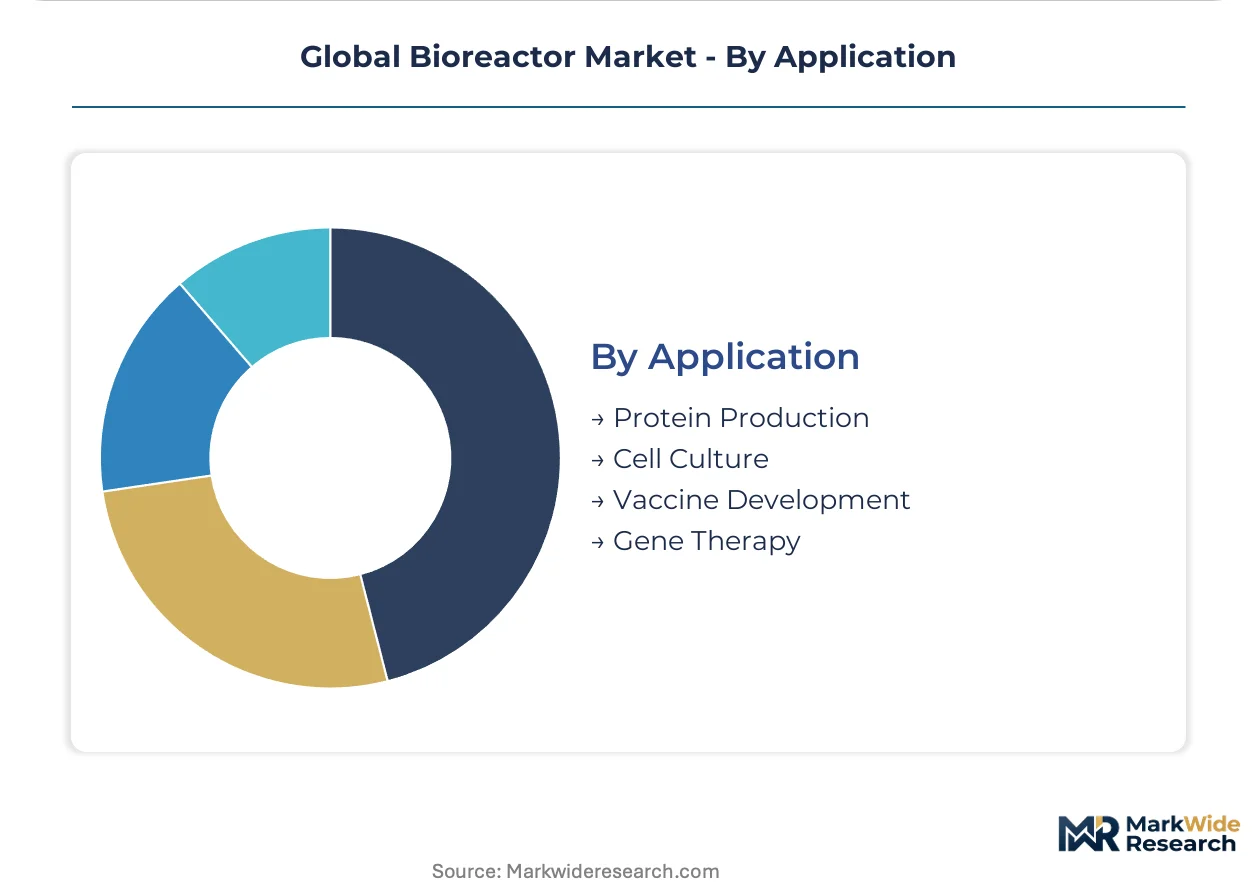
- Protein Production:Fed-batch and perfusion mammalian cell culture for monoclonal antibodies and recombinant proteins represents the largest addressable volume, with Chinese hamster ovine cell lines driving standardized platform approaches.
- Gene Therapy:Viral vector manufacturing for adeno-associated virus and lentivirus platforms demands specialized shear-sensitive mixing and low-oxygen control profiles that strain conventional stirred-tank designs.
- Vaccine Development:Egg-free cell culture vaccine production accelerates pandemic response timelines, with single-use adoption rising among emerging market manufacturers seeking rapid capacity deployment.
- Cell Culture:Stem cell and primary cell expansion applications require surface-coated vessels and precise metabolic control, limiting stainless steel suitability.
Protein production anchors current revenue. Gene therapy is where steepest expansion trajectory resides.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bioreactor trade flows reflect asymmetric manufacturing capabilities between established pharmaceutical clusters and emerging biologics markets. The United States and Germany maintain substantial export surpluses in high-value stainless steel systems and single-use assemblies. Import dependency concentrates among countries accelerating domestic biologics capacity under localized regulatory pressure.
United States
FDA's Quality by Design initiative and accelerated approval pathways for gene therapies sustain demand for flexible single-use manufacturing infrastructure. The Massachusetts and California biotech clusters anchor CDMO fleet expansions into multi-thousand-liter viral vector capacity. Boston-area contract manufacturers are consolidating process analytical technology investments to support real-time release testing mandates.
Germany
EMA Annex 1 closed-system requirements are compelling sterile manufacturing upgrades across Bavarian and Baden-Württemberg pharmaceutical facilities. German precision fabricators control electropolished 316L welding expertise for GMP-grade stainless steel vessels. The Rhine-Main biopharma corridor is witnessing replacement demand for legacy open-vessel systems ahead of regulatory deadlines.
China
NMPA biologics approval acceleration demands localized manufacturing data for imported bioreactor systems, driving joint venture formation with Western vendors. Yangtze River Delta pharmaceutical clusters are deploying perfusion platforms for biosimilar monoclonal antibody production. Shanghai-based CDMOs are expanding stainless steel capacity to capture export contract manufacturing from multinational sponsors.
Switzerland
Swissmedic stringent aseptic processing guidelines elevate validation documentation requirements for commercial-scale installations. Basel-area biopharma headquarters sustain captive manufacturing investments in high-titer perfusion trains. Swiss precision engineering firms are specializing in cell retention device technologies for continuous flow applications.
India
CDSCO biologics licensing reforms and PLI scheme incentives are attracting single-use bioreactor deployments for export-oriented vaccine manufacturing. Hyderabad and Bangalore biotech clusters are scaling mammalian cell culture capacity for biosimilar contract development. Indian engineering contractors are developing indigenous stirred-tank fabrication capabilities to reduce import dependency.
Global Bioreactor Market Vendor Landscape
Concentration sits with diversified life science conglomerates controlling integrated hardware, consumables, and service ecosystems. Market structure tilts toward tiered competition where full-stack vendors capture bundled procurement contracts while specialized equipment fabricators defend niche performance segments. Two strategic archetypes dominate: platform-integrated conglomerates leveraging instrumentation pull-through, and precision engineering specialists anchoring high-purity stainless steel fabrication. Competitive moves center on CDMO fleet partnership lock-ins and digital twin software qualification to reduce customer validation burdens.
Among diversified life science platforms, Danaher Corporation and Thermo Fisher Scientific exemplify the integrated ecosystem archetype, bundling bioreactor hardware with downstream purification and analytical instrumentation. Sartorius AG occupies a position bridging single-use consumables dominance with modular facility design services. German-origin precision engineering specialists including Merck KGaA and Eppendorf AG represent the premium-tier stainless steel and laboratory-scale vessel segment, anchoring validation-intensive pharmaceutical manufacturing relationships.
| Leading Market Players |
|---|
| Merck KGaA |
| GE Healthcare |
| Danaher Corporation |
| Praj Industries Limited |
| Solaris Biotech |
| Thermo Fisher Scientific |
| Eppendorf AG |
| Applikon Biotechnology |
| Sartorius AG |
| Others |
Supply Flow & Price Mechanics
FDA process validation guidance and EMA Annex 1 closed-system mandates simultaneously gate supplier qualification and stratify price tiers across GMP-grade bioreactor procurement. Certification documentation burdens concentrate pricing power with validated incumbents while compressing margins for unqualified challengers attempting stainless steel or single-use market entry.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the bioreactor market. Pharmaceutical manufacturers purchasing twenty-thousand-liter stainless steel trains face least price sensitivity due to decade-long depreciation schedules and validation lock-in, while emerging biotechs deploying modular single-use facilities exhibit highest elasticity. Price differentiation stems from GMP certification tier and after-sales service bundling. Cost compression in mid-scale single-use configurations is intensifying because gamma-irradiated film suppliers are consolidating polymer formulation expertise.
Supply Chain Analysis
Inventory lead times for electropolished 316L stainless steel vessels extend eighteen to twenty-four months due to German and Swiss precision fabricator order backlogs. Gamma-stable polypropylene films draw from specialized polymer suppliers concentrated in Germany and the United States, creating single-source vulnerability for CDMO fleet expansions. Supply chain risk centers on tariff exposure for Chinese-sourced magnetic drive seals and platinum-cured silicone tubing. Distribution runs through direct OEM relationships for pharmaceutical captives and distribution partnerships serving academic procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across gene therapy manufacturing infrastructure as viral vector production demands diverge fundamentally from established monoclonal antibody platform economics. This demand-side modality shift creates specialist niches unconstrained by incumbent stainless steel scale advantages.
For Market Incumbents: Fortify validation documentation archives against EMA MDR and FDA real-time release testing guidance acceleration. Lock CDMO fleet partnerships through multi-year consumables offtake agreements that embed single-use bioreactor hardware at negative gross margin. Prioritize backward integration into gamma-irradiated film polymer supply to neutralize input concentration risk from German and United States suppliers.
For New Entrants and Emerging Players: Lead with perfusion platform specialization targeting biosimilar contract manufacturers in China and India where regulatory filing complexity has delayed incumbent penetration. Brazilian biosimilar localization under ANVISA abbreviated pathways represents the most penetrable geography for first-mover service infrastructure. Deploy digital twin software qualification as primary go-to-market angle to reduce customer validation batch burdens.
For Investors and Strategic Acquirers: ICH Q13 continuous processing validation harmonization reshapes the acquisition landscape toward perfusion technology specialists with commercial-scale reference installations. Five-to-ten year viability favors precision engineering firms controlling cell retention device fabrication. Target acquisition archetype: Swiss-origin stainless steel fabricators with proprietary electropolishing IP. Signal to monitor: FDA draft guidance finalization timeline on redundant in-line analytics mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| CDMO Fleet Partnership Lock-in | Multi-year consumables contracts embed hardware and displace standalone equipment vendors. |
| Digital Twin Software Qualification | Predictive scale-up modeling reduces validation batch requirements for emerging biotech entrants. |
| Perfusion Platform Specialization | Continuous flow expertise captures biosimilar manufacturing contracts ahead of regulatory filing simplification. |
| Backward Integration into Polymer Supply | Captive gamma-irradiated film production neutralizes five-supplier concentration risk. |
| Modular Facility Pre-qualification | Prefabricated cleanroom pods compress construction timelines for venture-backed biotech manufacturing deployment. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 483 observations, EMA inspection databases, and CDSCO biologics approval records. Interviews with bioprocess engineering directors, CDMO procurement leads, regulatory affairs specialists, and stainless steel fabrication plant managers informed demand-side and supply-side validation. Secondary sources include ICH guidance documents, GMP facility inspection trend analyses, and trade flow data from German and United States customs authorities. Bottom-up capacity installation tracking triangulates against top-down pharmaceutical capital expenditure disclosures.
Segmentation dimensions modeled span product architecture, end-user scale, material specification, and therapeutic application across the projection horizon. CAGRs derive from installed base evolution analysis and replacement cycle acceleration under regulatory deadline pressure. Forecast inputs incorporate perfusion process analytical technology maturity curves and single-use bioreactor campaign changeover velocity assumptions.
The analysis sits within stated boundaries; outcomes outside sustained biologics approval acceleration or polymer supply disruption scenarios would require recalibration. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and CDMO capacity expansion intentions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Portable Bioprocessing Bioreactors Market
Biotechnology Equipment
Cell Lysis Market
Biotechnology Equipment
Fluorescence Immunoassay Analyzers Market
Biotechnology Equipment
Cell Disruption Market
Biotechnology Equipment
Global Polymerase Chain Reaction (PCR) Consumables Market
Biotechnology Equipment
PCR Consumables Market
Biotechnology Equipment
Qpcr Instruments Market
Biotechnology Equipment
Life Science Instrumentation Market
Biotechnology Equipment
Plasmid Kits Market
Biotechnology Equipment
Lab Scale Bioreactors Market
Biotechnology Equipment
Cell Harvesting Systems Market
Biotechnology Equipment
Biochemistry Analyzers Market
Biotechnology Equipment
Fermentation Equipment Market
Biotechnology Equipment
Measurement Technologies in Downstream Processing Market
Biotechnology Equipment
Separation Systems for Commercial Biotechnology Market
Biotechnology Equipment
Global Laboratory Centrifuge Market