
 Rad-Hard Mosfets Market | 2026-2036
Rad-Hard Mosfets Market Size, Share, and Industry Trends Forecast 2026-2036
Rad-Hard Mosfets Market Insights
Modular power-subsystem packaging is rebalancing how satellite prime contractors evaluate Rad-Hard MOSFET suppliers against discrete component sourcing. Infineon Technologies AG anchors European supply security through its Munich-based fab network and ESCC-qualified product lines. STMicroelectronics leverages Grenoble R&D intensity to sustain dual-use technology leadership across civilian space and defense programs. Texas Instruments Incorporated competes through Dallas-based vertical integration into epitaxial wafer production for enhanced dose-rate hardness.
Rad-Hard MOSFETs are metal-oxide-semiconductor field-effect transistors engineered with total ionizing dose tolerance typically exceeding 100 krad(Si) and single-event upset immunity for operation in proton and heavy-ion environments. These devices switch and regulate power in spacecraft bus electronics, payload systems, and launch vehicle avionics where cosmic radiation would degrade standard commercial-grade semiconductors. Power MOSFETs and RF MOSFETs represent the dominant product categories, with silicon carbide technology gaining traction as satellite operators prioritize efficiency-to-mass ratios for electric propulsion and high-power radar. Aerospace applications command the largest value share, though space exploration programs are expanding fastest as lunar gateway and deep-mission architectures multiply qualification orders.
FAA launch licensing requirements and NASA-STD-8739 reliability specifications shape component traceability and lot acceptance testing protocols for U.S. suppliers. ESA's ESCC 5000 specification series and the EU Space Programme Agency's procurement rules govern European market access, while China's SAMR and MIIT enforce indigenous qualification pathways for domestic constellation builds. Stakeholders must monitor how export control expansions under U.S. ITAR and emerging EU strategic autonomy frameworks reshape cross-border component flows before committing to multi-year foundry agreements.
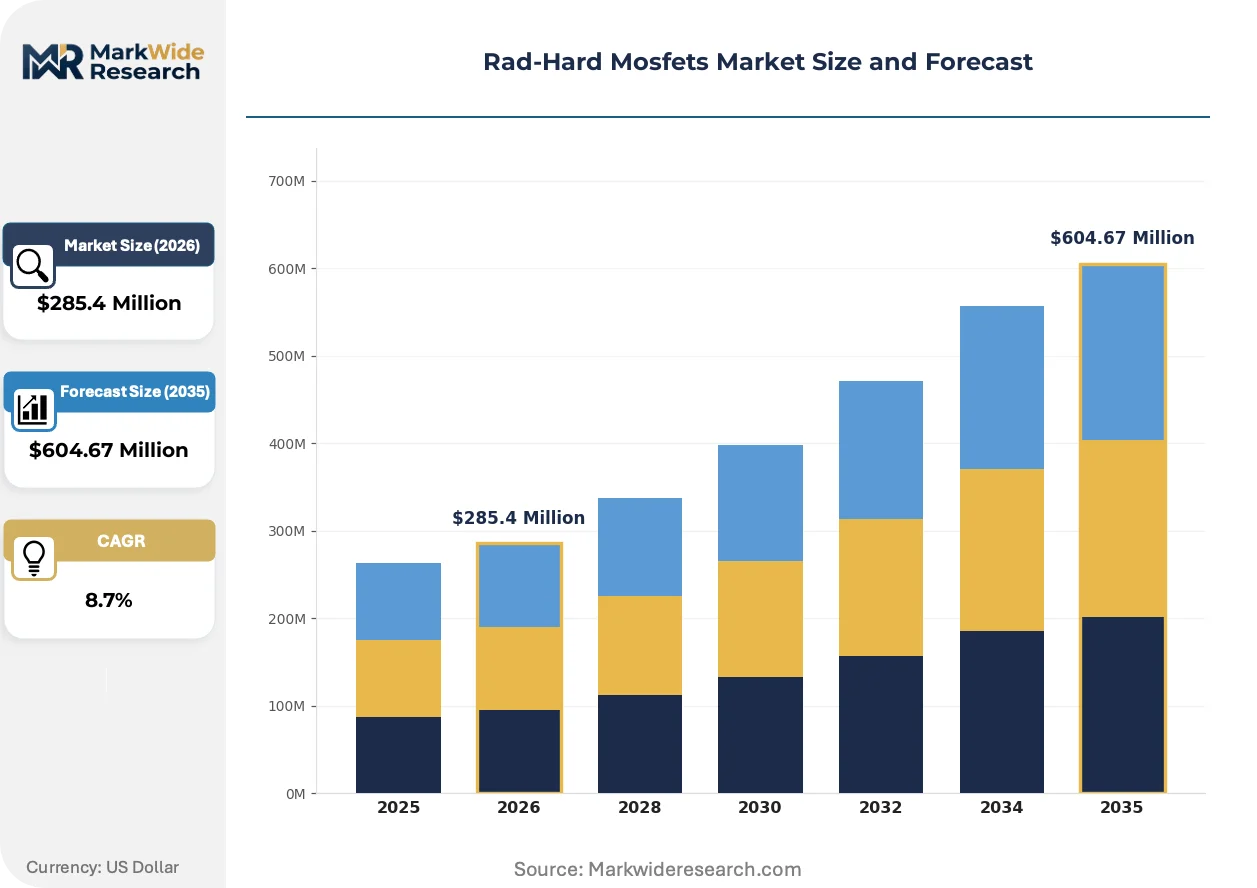
Market Dynamics
Constellation-scale procurement is compressing supplier qualification timelines while tightening radiation-hardness verification protocols. SpaceX and OneWeb volume commitments are forcing foundries to reconcile MIL-STD-883 lot traceability with commercial-scale throughput.
Growth Catalysts
- Artemis Program Procurement:NASA's lunar lander competitions are generating qualification orders for 100+ krad(Si) MOSFETs in power distribution units. Prime contractors must dual-source under federal acquisition regulations.
- REACH and RoHS Alignment:European satellite builders are specifying lead-free packaging that meets ESCC 5000 series standards. This creates specification pull for qualified European foundries.
- Silicon Carbide Epitaxy:GaN-on-SiC and pure SiC MOSFETs are displacing silicon in electric propulsion systems. Satellite operators prioritize specific impulse efficiency over heritage component costs.
Market Restraints
- Epitaxial Wafer Concentration:Six-inch SiC substrate supply concentrates among Japanese and US producers. Foundry capacity for radiation-hardened epitaxy remains captive to defense prime verticals.
- MIL-STD-883 Test Cost Burden:Total ionizing dose and single-event effect qualification runs $50,000-$150,000 per lot. Small satellite builders absorb this cost or accept commercial-off-the-shelf risk.
- ITAR Export Control Friction:US State Department jurisdiction over radiation-hardened power electronics restricts component flow to non-US satellite constellations. European and Asian buyers accelerate indigenous qualification.
Strategic Opportunities
- Indian Constellation Builds:ISRO's commercial arm and private launch ventures are establishing domestic qualification pathways. Suppliers with BIS and DGFT compliance can capture procurement from the Indian National Space Promotion and Authorization Center.
- On-Orbit Servicing Architectures:Mission extension vehicles and debris removal tugs require fault-tolerant power switching for rendezvous operations. This application demands enhanced single-event burnout immunity beyond standard satellite bus requirements.
- EU Strategic Autonomy Funding:The European Space Programme Agency's procurement rules now prioritize ESCC-qualified European suppliers. Foundries in Grenoble and Munich can access sovereign capability grants.
Industry Challenges
- Radiation Effects Modeling Talent Scarcity:TCAD simulation for heavy-ion strike response requires specialized expertise concentrated at national laboratories. Commercial foundries compete for limited personnel.
- Qualification Timeline Compression:Constellation deployment schedules demand 12-18 month qualification cycles versus traditional 36-48 month military programs. Suppliers must parallelize design validation with process qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rad-Hard Mosfets Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RF Mosfets, Linear Mosfets, Power Mosfets, High Voltage Mosfets Application: Aerospace, Defense, Industrial, Space Exploration Technology: Silicon, Silicon Carbide, Gallium Nitride, GaAs End User: OEMs, Tier-1 Suppliers, Contractors, Research Institutions |
| Companies Covered | Microchip Technology Inc., Infineon Technologies AG, STMicroelectronics, BAE Systems, Honeywell International Inc., Renesas Electronics Corporation, Texas Instruments Incorporated, Teledyne Technologies Inc., Advanced Micro Devices, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rad-Hard Mosfets Market Trends and Innovations
Power semiconductor architectures are bifurcating between heritage silicon qualification paths and wide-bandgap material adoption for next-generation missions. This tension is restructuring how prime contractors evaluate supplier roadmaps.
Silicon carbide MOSFETs are integrating into satellite electric propulsion systems as operators prioritize thrust-to-mass ratios. Thales Alenia Space and Airbus Defence and Space are specifying 650V and 1200V SiC devices for Hall-effect thruster power processing units. This material transition is integrating radiation-hardened foundries with commercial automotive SiC supply chains for substrate sourcing.
ESA's ESCC 5000 specification series is tightening single-event upset screening requirements for COTS components used in NewSpace applications. European prime contractors must now document heavy-ion test data for commercial-grade power electronics flown on demonstration missions. Small satellite builders in Germany and France are responding by pre-qualifying component lots through funded irradiation campaigns.
Buyer concentration among megaconstellation operators is compressing supplier negotiation leverage. SpaceX vertical integration into avionics design is displacing traditional component distributor channels for high-volume procurement. Tier-2 satellite builders in the United Kingdom and Italy are maintaining discrete component sourcing to preserve design flexibility for specialized payloads.
Rad-Hard Mosfets Market Segmentation
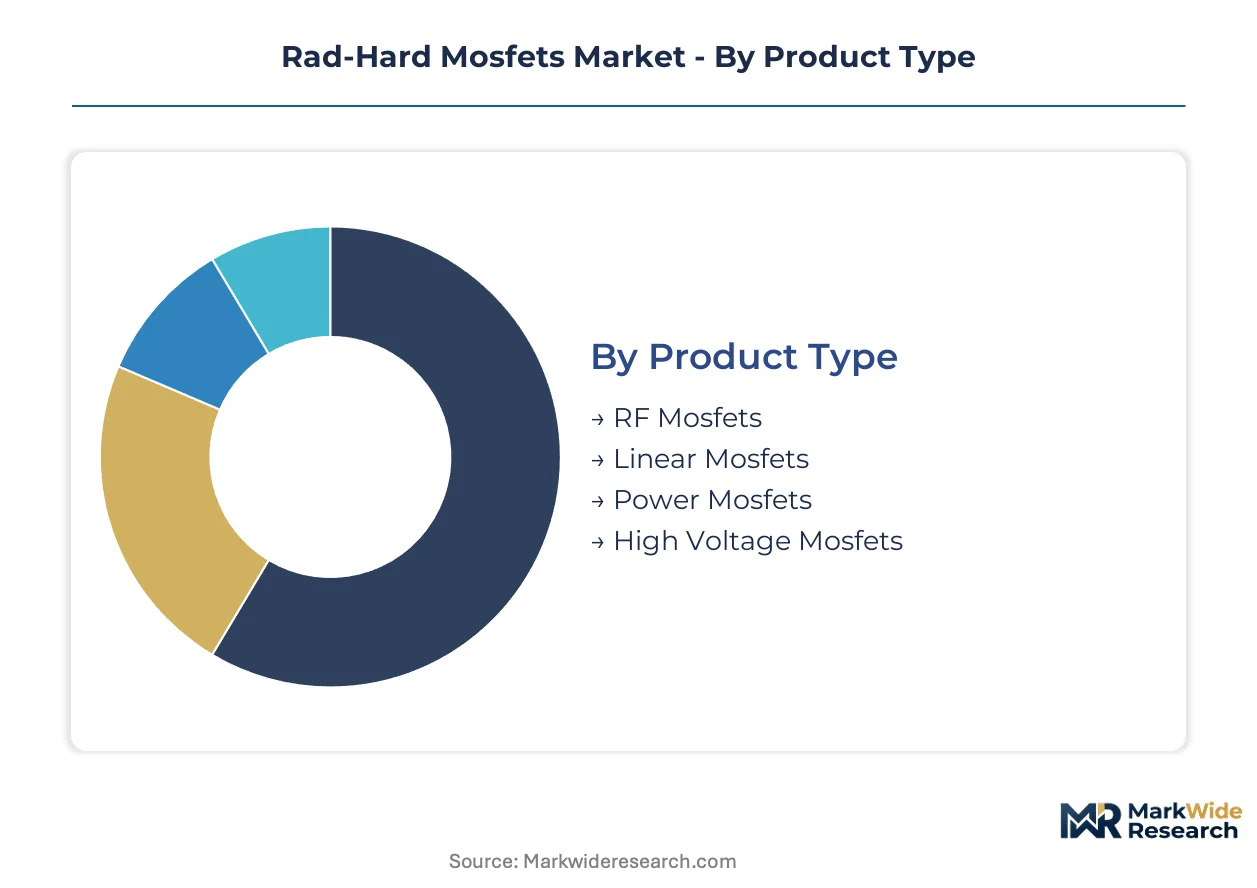
Rad-Hard MOSFET procurement splits across certification grades, mission profiles, and supply chain tiers. Each segmentation axis imposes distinct qualification burdens and margin structures on suppliers.
Product Type:
MIL-STD-883 and ESCC 5000 series requirements vary sharply by switching topology and frequency regime, with RF and power segments carrying the heaviest test documentation loads.
- Power Mosfets:These devices handle bus voltage regulation and load switching in spacecraft power distribution units. Demand concentrates in geostationary satellite builds where 100+ krad(Si) tolerance is mandatory and NASA-STD-8739 traceability applies.
- RF Mosfets:High-frequency power amplification for radar and communications payloads requires single-event gate rupture immunity beyond standard specifications. SpaceX Starship avionics and military satellite programs are tightening screening protocols for these parts.
- Linear Mosfets:Analog signal conditioning applications in scientific instruments.
- High Voltage Mosfets:Electric propulsion power processing units and solar array regulation.
Leading the category by volume: Power Mosfets. Growing fastest: RF Mosfets.
Application:
End-use environments dictate radiation hardness thresholds, with lunar surface and deep-space missions multiplying total ionizing dose requirements against low-Earth orbit baselines.
- Space Exploration:Artemis lunar landers and deep-space probes demand 300+ krad(Si) tolerance and enhanced single-event burnout immunity. NASA Commercial Lunar Payload Services contracts are accelerating qualification orders for these extreme environments.
- Aerospace:Geostationary communications satellites and navigation constellations form the procurement baseline. ESA Copernicus expansion and OneWeb constellation replenishment sustain European foundry output.
- Defense:Missile defense interceptors and nuclear-hardened command systems.
- Industrial:High-altitude drones and nuclear facility instrumentation.
Highest qualification burden: Space Exploration. Steepest order volume climb: Aerospace.
Technology:
Material platform selection determines foundry compatibility, with wide-bandgap devices requiring specialized epitaxial capabilities that concentrate among defense-captive suppliers.
- Silicon:Mature 100-200V and 500-600V planar and trench architectures dominate heritage satellite bus designs. U.S. Space Force procurement sustains domestic foundry investment in these qualified processes.
- Silicon Carbide:650V and 1200V devices are displacing silicon in Hall-effect thruster power processing units. Thales Alenia Space and Airbus Defence and Space specifications are pulling automotive SiC supply chains into radiation-hardened qualification.
- Gallium Nitride:RF power amplification at X-band and higher frequencies.
- GaAs:Legacy microwave applications in phased array systems.
Widest installed base: Silicon. Gaining share fastest: Silicon Carbide.
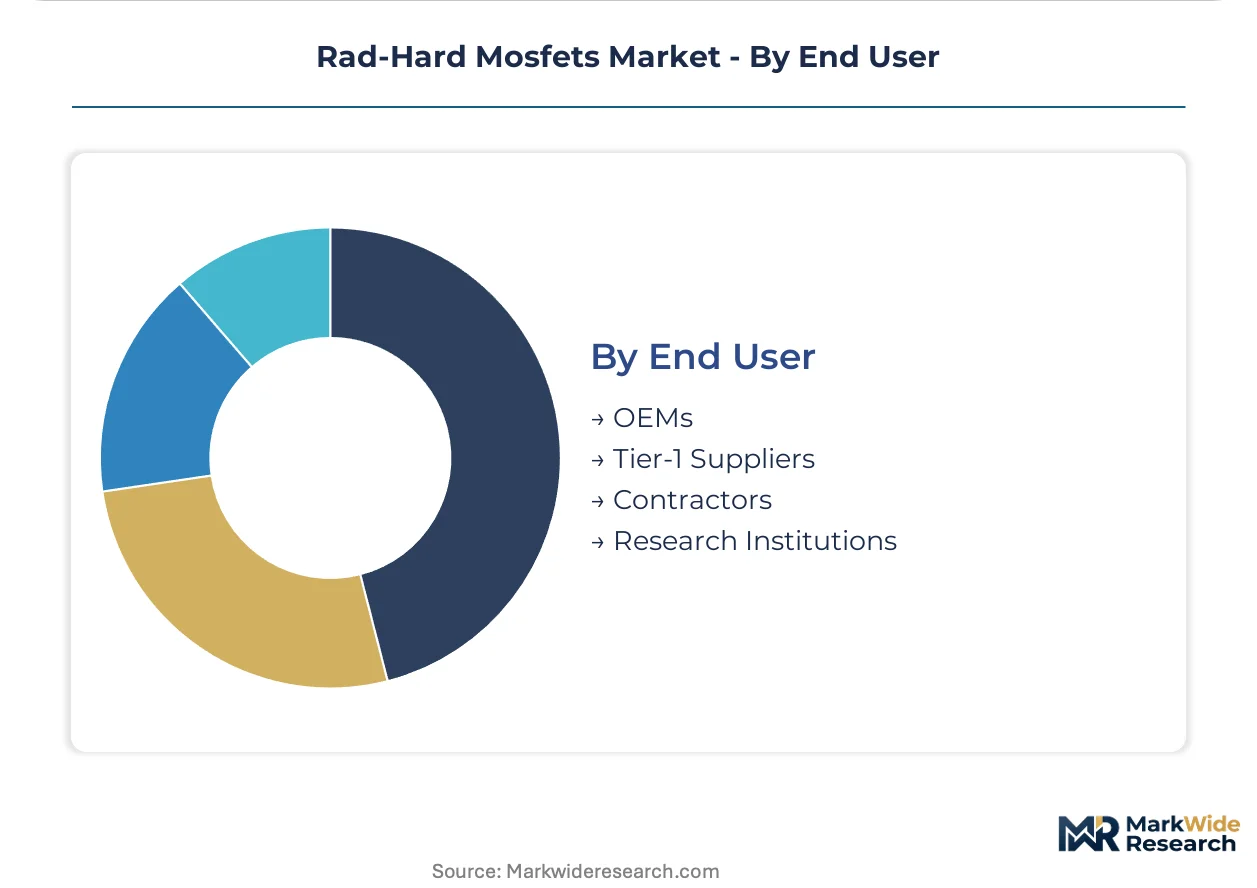
End User:
Customer tier determines contract structure, with OEM direct procurement displacing distributor channels for constellation-scale programs while research institutions sustain small-lot qualification activity.
- OEMs:SpaceX, Lockheed Martin, and Northrop Grumman internalize component specification and source directly from qualified foundries. These buyers compress supplier margins through volume commitments but absorb qualification cost burdens.
- Tier-1 Suppliers:Satellite prime contractors in Germany, France, and Italy maintain discrete component sourcing to preserve payload design flexibility. These firms balance ESCC qualification requirements against schedule pressure from constellation operators.
- Contractors:Subsystem integrators serving defense and civil space programs.
- Research Institutions:University and laboratory demonstration missions with limited procurement scale.
Dominant procurement volume: OEMs. Expanding contract flow: Tier-1 Suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rad-Hard MOSFET production clusters in defense-captive foundries across the United States and Europe, while consumption concentrates in satellite constellation operators headquartered in these same markets. This geographic alignment of supply and demand shapes qualification pathway fragmentation and export control enforcement.
United States
The Space Force procurement budget and NASA Artemis program sustain domestic foundry output for 100+ krad(Si) devices. FAA launch licensing requirements and NASA-STD-8739 reliability specifications govern component traceability protocols. Dallas-based vertical integration into epitaxial wafer production anchors Texas as a concentration point for dose-rate hardness capabilities.
Germany
Airbus Defence and Space specifications for electric propulsion systems pull demand for 650V and 1200V SiC MOSFETs. ESA's ESCC 5000 specification series and EU Space Programme Agency procurement rules prioritize qualified European suppliers. Munich-based fab networks anchor continental supply security for ESCC-qualified product lines.
France
Thales Alenia Space Hall-effect thruster programs specify wide-bandgap power processing units for satellite operators. REACH and RoHS alignment requirements create specification pull for lead-free packaging meeting ESCC standards. Grenoble R&D intensity sustains dual-use technology leadership across civilian space and defense programs.
United Kingdom
Tier-2 satellite builders maintain discrete component sourcing to preserve payload design flexibility for specialized missions. Export control expansions under emerging EU strategic autonomy frameworks reshape cross-border component flows. British prime contractors balance heritage silicon qualification against NewSpace schedule compression pressures.
India
ISRO's commercial arm and private launch ventures establish domestic qualification pathways for constellation builds. BIS and DGFT compliance requirements create procurement filters for the Indian National Space Promotion and Authorization Center. Indigenous satellite production is accelerating orders for radiation-hardened power electronics from qualified international suppliers.
Rad-Hard Mosfets Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Rad-Hard MOSFET market, creating a tiered structure where defense prime vertical integration meets commercial foundry scale. The vendor base separates between heritage qualification holders and wide-bandgap technology entrants. Three archetypes dominate: defense-captive suppliers with MIL-STD-883 process heritage, European ESCC-qualified foundries serving dual-use programs, and commercial semiconductor houses adapting automotive SiC supply chains for space applications. Capacity expansion and strategic partnerships represent the dominant competitive moves as constellation-scale procurement compresses supplier timelines.
Among diversified technology conglomerates, Microchip Technology Inc. and Texas Instruments Incorporated occupy positions reflecting defense-aerospace semiconductor heritage, while Infineon Technologies AG exemplifies the European ESCC-qualified archetype with continental supply security positioning. STMicroelectronics represents the Grenoble-based R&D-intensive model serving dual-use technology requirements across civilian and defense satellite programs.
| Leading Market Players |
|---|
| Microchip Technology Inc. |
| Infineon Technologies AG |
| STMicroelectronics |
| BAE Systems |
| Honeywell International Inc. |
| Renesas Electronics Corporation |
| Texas Instruments Incorporated |
| Teledyne Technologies Inc. |
| Advanced Micro Devices, Inc. |
| Others |
Pricing and Supply Chain Analysis
SpaceX and OneWeb volume procurement mandates are compressing supplier margins while forcing foundries to absorb MIL-STD-883 qualification costs into long-term contract structures. This buyer concentration shifts pricing power toward constellation operators and away from discrete component distributors.
Pricing Analysis
Cost-down pressure on heritage silicon tiers accelerates because automotive SiC supply chains are pulling substrate pricing lower through volume scale. Contract-based long-term offtake dominates, with pricing stratifying across ESCC-qualified premium lots, MIL-STD-883 standard grades, and pre-screened commercial-off-the-shelf economy tiers. Certification level and volume scale drive price differentiation, with small satellite builders most price-sensitive and NASA prime contractors least sensitive due to federal cost-plus structures.
Supply Chain Analysis
Regional distribution centers in Dallas, Munich, and Grenoble anchor hub-and-spoke patterns for qualified component delivery to satellite prime contractors. Six-inch SiC substrate supply concentrates in Japan and the United States, while epitaxial wafer processing rests on defense-captive foundries in these same markets. Single-source vulnerability around radiation-hardened epitaxy creates chokepoint exposure. Distribution runs through OEM direct channels for constellation-scale procurement and specialized distributors for Tier-2 satellite builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around qualification-holding incumbents as constellation procurement timelines squeeze out foundries lacking MIL-STD-883 or ESCC process heritage.
For Market Incumbents: Deploy capacity addition in Grenoble and Munich to capture EU Strategic Autonomy funding flows. Deepen backward integration into SiC substrate sourcing to offset Japanese supply concentration. Lock in long-term qualification contracts with SpaceX and OneWeb before second-source mandates proliferate. For New Entrants and Emerging Players: Wide-bandgap technology qualification gaps in Indian and Middle Eastern constellation programs offer white-space entry. Target ISRO commercial arm procurement through BIS compliance pathways. Pursue funded irradiation campaigns as a go-to-market angle to bypass traditional 36-month qualification timelines. For Investors and Strategic Acquirers: The window for entry favors ESCC-qualified European foundries with dual-use civilian-defense revenue streams. Five-to-ten year viability hinges on SiC process transition completion. Watch for NASA Commercial Lunar Payload Services contract awards as an inflection signal for 300+ krad(Si) device demand.| Strategic Initiative | Industry Significance |
|---|---|
| ESCC Qualification Investment | Unlocks ESA Copernicus and EU Space Programme Agency procurement flows for European foundries. |
| SiC Epitaxy Capacity Buildout | Captures electric propulsion specification shifts at Thales Alenia Space and Airbus Defence and Space. |
| Indian Market Entry Partnership | Positions suppliers for ISRO commercial arm and private launch venture procurement acceleration. |
| On-Orbit Servicing Component Development | Addresses mission extension vehicle demand for enhanced single-event burnout immunity beyond baseline satellite requirements. |
| Dual-Source Contract Structuring | Aligns with NASA federal acquisition regulations mandating redundant supplier qualification for Artemis lunar lander programs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with satellite prime contractor procurement officers, radiation effects modeling specialists at national laboratories, foundry process engineers, and ESA qualification auditors combined with secondary validation from NASA-STD-8739 documentation, ESCC 5000 series specifications, and FAA launch licensing records. Bottom-up component demand modeling and top-down constellation deployment forecasts underwent cross-triangulation.
Granularity-level framing applied separate models for power MOSFET, RF MOSFET, and linear device categories across silicon, silicon carbide, and gallium nitride technology platforms. End-use segmentation distinguished geostationary communications, low-Earth orbit constellations, lunar surface missions, and deep-space probe applications. CAGRs derived from unit deployment projections tied to named constellation operator public filings and government procurement announcements. Radiation hardness requirement trajectories and wide-bandgap material adoption curves served as industry-specific forecast inputs across the projection horizon.
Several conditions sit outside the modeled scope, including ITAR regulatory reinterpretations, SiC substrate supply disruptions from geopolitical events, and NewSpace operator bankruptcy scenarios. Forecasts reflect documented assumptions around qualification timeline compression and federal budget continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Photosensitive Semiconductor Device Market
Semiconductor Devices
Spintronic Logic Devices Market
Semiconductor Devices
Global Substrate-Like PCB Market
Semiconductor Devices
Voltage Controlled Oscillators Market
Semiconductor Devices
Asia-Pacific Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Epi Wafer Market
Semiconductor Devices
Taiwan Discrete Semiconductor Market
Semiconductor Devices
5G Modems Market
Semiconductor Devices
China Semiconductor Diode Market
Semiconductor Devices
Metal-Semiconductor-Metal Photodetector Market
Semiconductor Devices
China Power Transistor Market
Semiconductor Devices
Europe Power Transistor Market
Semiconductor Devices
Polymer Core Solder Ball Market
Semiconductor Devices
Thin Film Transistors (TFT) Market
Semiconductor Devices
TC-SAW Filter Market
Semiconductor Devices
Europe Ultra-Low-Power Microcontroller Market