
 Americas Power Transistor Market | 2026-2036
Americas Power Transistor Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Power Transistor Market Insights
Power electronics engineering talent scarcity across Mexico and Central American assembly hubs is reorganizing how semiconductor firms allocate wafer fabrication and packaging operations. Infineon Technologies AG leverages its vertically integrated silicon carbide substrate capacity to anchor high-voltage industrial demand in the southern United States. Texas Instruments Inc. sustains broad analog and embedded processing portfolios that dominate price-competitive MOSFET segments across automotive tier-one suppliers.
Americas power transistors are three-terminal semiconductor devices engineered to switch or amplify electrical power above one watt, typically fabricated on silicon or silicon carbide wafers with epitaxial layering to withstand junction temperatures exceeding 175 degrees Celsius. These components regulate current flow in motor drives, inverters, and switched-mode power supplies across heavy industrial and transportation systems. MOSFET and IGBT product categories lead value generation owing to their lock-in within electric vehicle traction inverters and grid-tied solar converters. Field Effect Transistor architectures, particularly planar and trench-gate silicon carbide variants, represent the fastest-expanding margin pool as OEMs redesign thermal management around higher switching frequencies.
EPA emissions benchmarks for medium- and heavy-duty vehicles, NHTSA fuel economy standards, and OSHA electrical safety directives collectively force power transistor suppliers toward higher efficiency certifications and isolated packaging designs. The FCC's electromagnetic compatibility rules for telecommunications infrastructure further constrain allowable switching noise spectra in 5G base station power amplifiers. Stakeholders must monitor how forthcoming Department of Energy efficiency mandates for industrial motor systems redirect procurement specifications toward wide-bandgap devices.
Market Dynamics
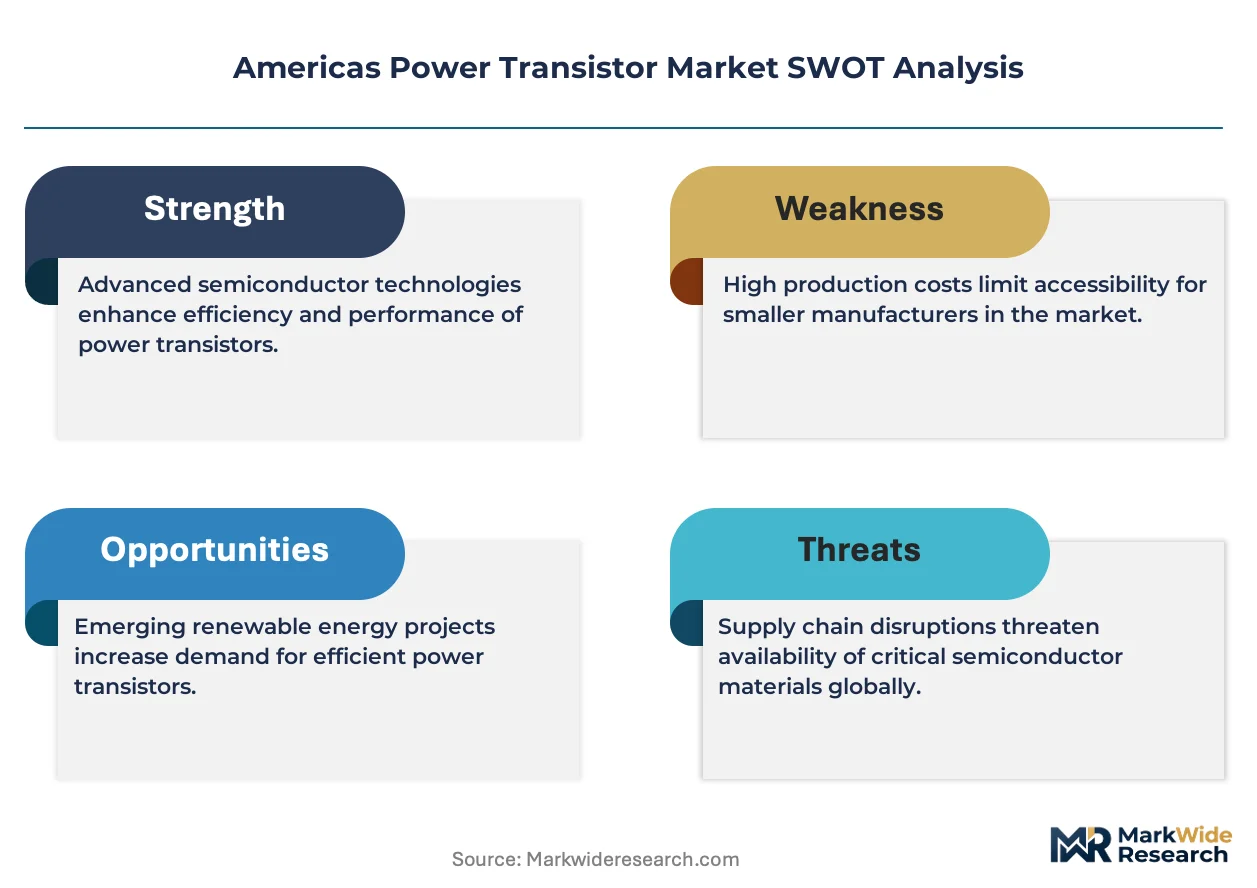
Silicon carbide substrate availability is concentrating competitive advantage among vertically integrated suppliers while EPA emissions benchmarks for medium- and heavy-duty vehicles force rapid powertrain redesign cycles across automotive tier-one suppliers.
Growth Catalysts
- Electric vehicle traction inverter demand:NHTSA fuel economy standards compel OEMs to adopt wide-bandgap semiconductors for higher switching frequencies and reduced thermal losses.
- Grid-tied solar converter deployment:Department of Energy efficiency mandates for industrial motor systems redirect procurement specifications toward silicon carbide MOSFET architectures.
- Texas and California manufacturing corridor expansion:Concentrated clean energy investment and semiconductor fabrication incentives attract power transistor packaging operations.
Market Restraints
- Silicon carbide substrate cost volatility:Limited high-purity substrate supply concentrates pricing power among captive producers, compressing margins for fabless designers.
- EPA certification timeline friction:Extended validation cycles for medium- and heavy-duty vehicle powertrains delay volume ramp schedules.
- Copper and aluminum metallization input inflation:Raw material cost swings in packaging interconnects destabilize contract pricing for industrial motor drive suppliers.
Strategic Opportunities
- Mexico assembly hub talent development:Power electronics engineering scarcity creates first-mover advantage for firms establishing captive training programs in Guadalajara and Monterrey.
- OSHA electrical safety directive compliance services:Isolated packaging design requirements open adjacent revenue streams for certification consulting and thermal simulation software.
- 5G base station power amplifier convergence:FCC electromagnetic compatibility rules for telecommunications infrastructure drive gallium nitride and silicon carbide co-development.
Industry Challenges
- Epitaxial layering process engineering scarcity:Specialized wafer fabrication expertise for 175-degree Celsius junction tolerance remains concentrated in legacy silicon foundries.
- Legacy IGBT inventory integration complexity:Automotive tier-one suppliers face redesign costs when retrofitting existing motor drive architectures with trench-gate silicon carbide variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Power Transistor Market |
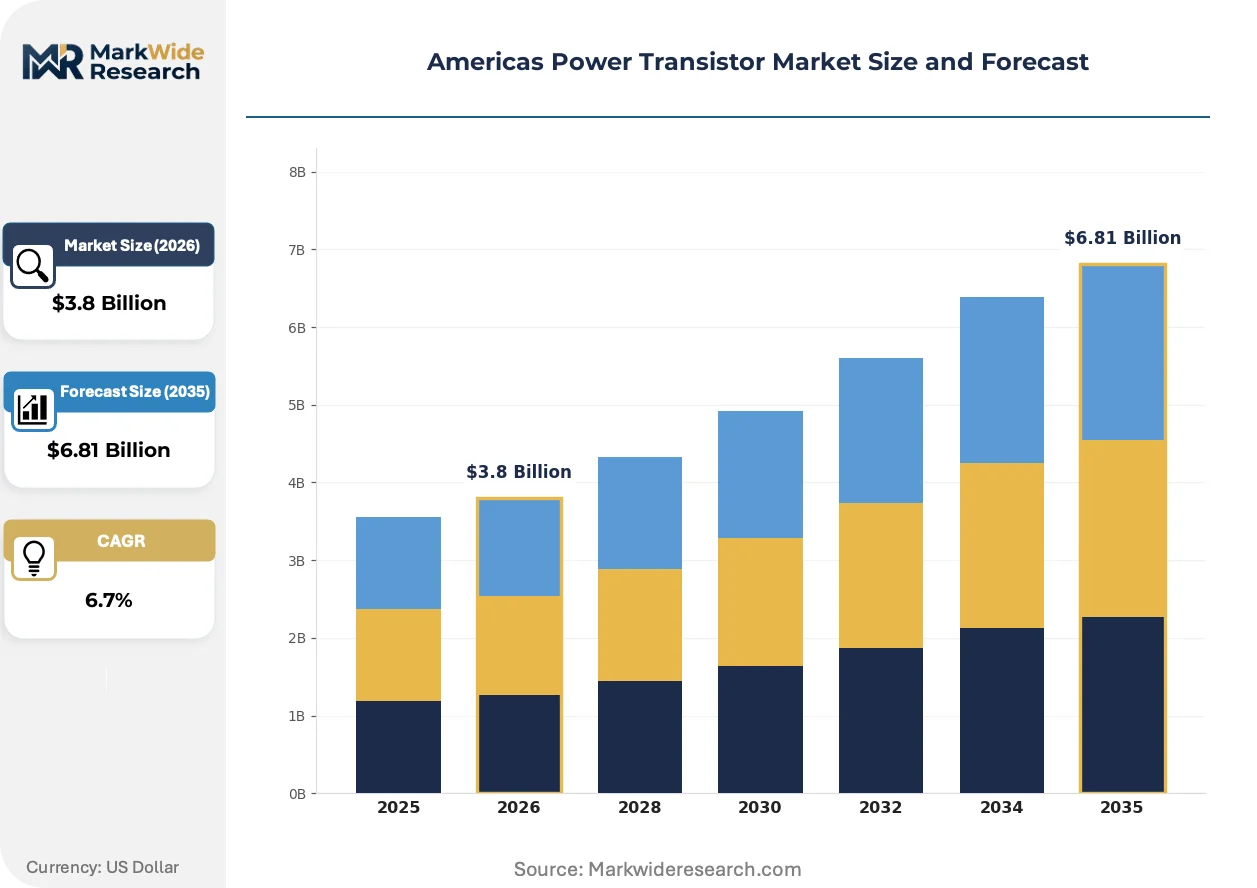
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bipolar Junction Transistor, Field Effect Transistor, IGBT, MOSFET Application: Industrial Automation, Renewable Energy, Consumer Electronics, Electric Vehicles End User: Telecommunications, Automotive, Power Generation, Aerospace Technology: Analog, Digital, Linear, Switching |
| Companies Covered | Infineon Technologies AG, Texas Instruments Inc., STMicroelectronics N.V., NXP Semiconductors N.V., Renesas Electronics Corporation, Mitsubishi Electric Corporation, ON Semiconductor Corporation, Toshiba Corporation, Diodes Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Power Transistor Market Trends and Innovations
Trench-gate silicon carbide MOSFET architectures are compressing thermal management system requirements while enabling higher-frequency switching. Regulatory pressure from emissions and efficiency mandates is accelerating material substitution timelines across transportation and industrial segments.
Silicon carbide substrates enable junction temperatures exceeding 175 degrees Celsius while reducing switching losses by half compared to silicon IGBTs. Automotive OEMs in California and Texas are adopting these devices for 800-volt traction inverters. Silicon carbide is supplanting planar silicon MOSFETs in price-competitive segments as foundry economics improve and substrate supply expands.
EPA emissions benchmarks for medium- and heavy-duty vehicles mandate powertrain efficiency improvements that silicon-based devices cannot achieve. Tier-one suppliers must redesign inverters and DC-DC converters to meet 2027 compliance deadlines. The southern United States manufacturing corridor faces the steepest certification burden as heavy-duty truck production concentrates in Texas.
Fleet procurement managers now specify total cost of ownership metrics including energy losses and cooling system mass rather than unit device pricing. Direct sourcing from wafer fabricators is displacing traditional distribution channels for high-volume automotive contracts. This pattern is most visible in California, where electric vehicle OEMs negotiate captive silicon carbide supply agreements.
Americas Power Transistor Market Segmentation
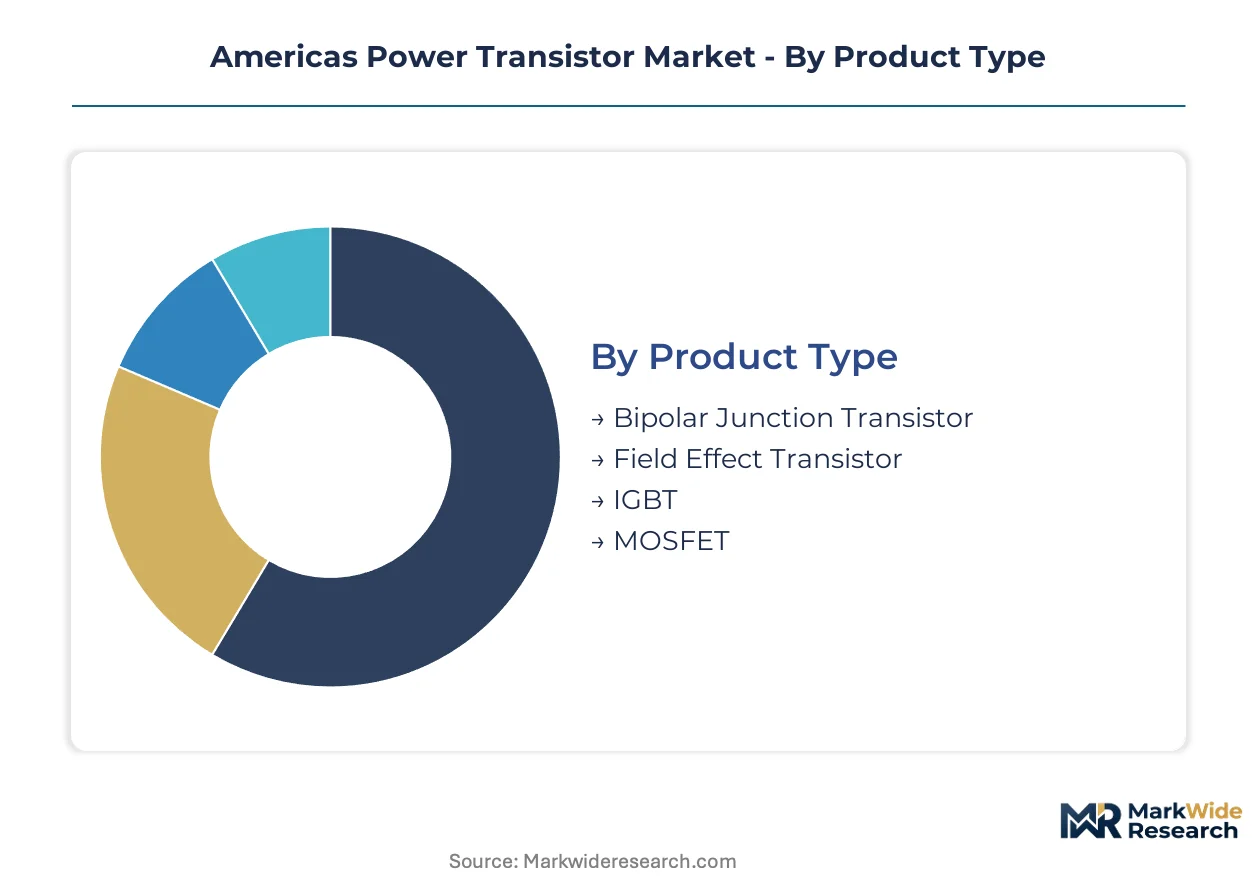
Americas power transistor procurement patterns diverge sharply across product architectures and end-use certifications. Regulatory pressure from EPA and NHTSA mandates reshapes how OEMs prioritize efficiency ratings against unit economics.
Product Type:
EPA emissions benchmarks for medium- and heavy-duty vehicles create divergent certification pathways across semiconductor architectures, concentrating procurement specifications toward wide-bandgap variants.
- MOSFET:Metal-oxide-semiconductor field-effect transistors dominate 800-volt electric vehicle traction inverters across Texas and California manufacturing corridors. Silicon carbide trench-gate variants satisfy NHTSA fuel economy standards while reducing cooling system mass in California-designed battery electric platforms.
- IGBT:Insulated-gate bipolar transistors retain lock-in within industrial motor drives and heavy-duty vehicle powertrains requiring 175-degree Celsius junction tolerance. Extended EPA certification timelines for medium- and heavy-duty applications delay volume migration to wide-bandgap alternatives in southern United States truck manufacturing.
- Field Effect Transistor:Planar and trench-gate architectures enable higher switching frequencies in grid-tied solar converters.
- Bipolar Junction Transistor:Legacy silicon devices persist in cost-sensitive analog amplification and low-frequency switching.
Established volume favors IGBT; emerging adoption favors MOSFET.
Application:
Cost tier stratification separates premium wide-bandgap deployments from price-competitive silicon legacy systems.
- Electric Vehicles:Traction inverters and DC-DC converters in 800-volt architectures demand silicon carbide MOSFETs with switching loss reductions unattainable through silicon IGBTs. California OEMs negotiate captive substrate supply agreements directly with wafer fabricators, bypassing traditional distribution.
- Renewable Energy:Grid-tied solar converters and wind turbine inverters specify wide-bandgap devices for efficiency gains under Department of Energy industrial motor mandates. Texas utility-scale installations drive concentrated demand for high-voltage packaging.
- Industrial Automation:Motor drives and switched-mode power supplies balance thermal performance against unit economics.
- Consumer Electronics:Low-voltage switching applications prioritize cost minimization over junction temperature tolerance.
Procurement scale concentrates in Electric Vehicles; margin expansion concentrates in Renewable Energy.
End User:
Customer type determines packaging complexity and certification burden across isolated versus non-isolated designs.
- Automotive:Tier-one suppliers redesign powertrain architectures to meet EPA 2027 compliance deadlines for medium- and heavy-duty vehicles. Direct sourcing from vertically integrated silicon carbide producers displaces distributor relationships for high-volume contracts.
- Power Generation:Utility-scale inverter deployments specify wide-bandgap semiconductors for grid stability applications. Texas and California clean energy investment attracts packaging operations to manufacturing corridors.
- Telecommunications:5G base station power amplifiers face FCC electromagnetic compatibility constraints on switching noise spectra.
- Aerospace:Radiation-hardened and high-reliability specifications demand specialized epitaxial layering processes.
Volume concentration sits with Automotive; specification complexity peaks in Aerospace.
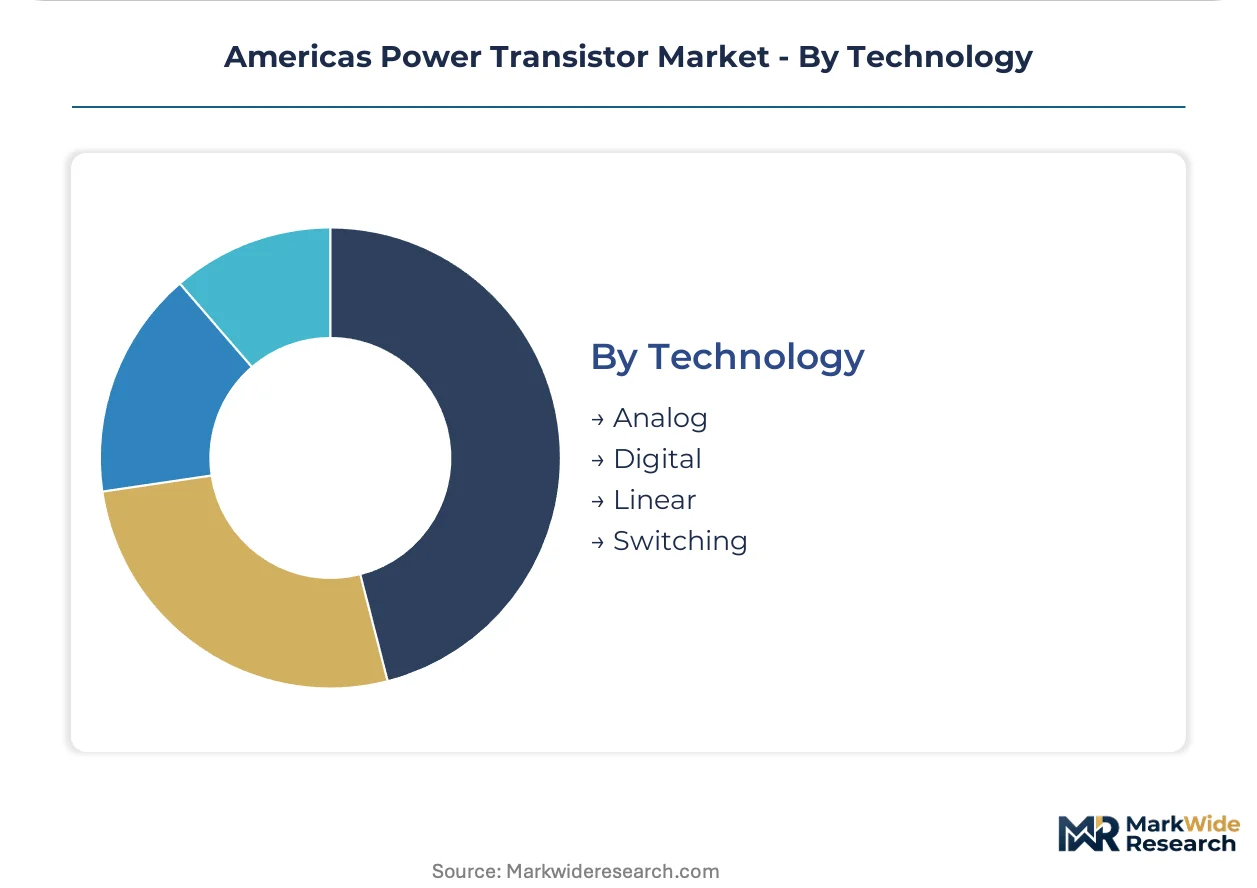
Technology:
Supply concentration in legacy silicon foundries shapes availability for specialized process nodes.
- Switching:Pulsed operation at elevated frequencies enables efficiency gains in electric vehicle traction inverters and solar converters. Silicon carbide substrates support switching losses half those of silicon equivalents, satisfying NHTSA fuel economy standards.
- Analog:Continuous signal amplification retains relevance in motor drive control loops and power supply regulation.
- Digital:Integrated gate drivers and protection logic reduce external component count.
- Linear:Class-A and Class-AB operation persists in audio and instrumentation amplification.
Efficiency mandates favor Switching; design simplicity favors Linear.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Americas power transistor consumption mix diverges sharply between the United States, where automotive and industrial electrification dominates procurement, and Latin American markets where cost-sensitive industrial motor drives retain silicon IGBT preference.
United States
EPA emissions benchmarks for medium- and heavy-duty vehicles and NHTSA fuel economy standards compel OEMs to adopt silicon carbide MOSFETs in 800-volt traction inverters. The Department of Energy efficiency mandates for industrial motor systems redirect procurement toward wide-bandgap devices. Texas and California manufacturing corridors concentrate clean energy investment and semiconductor fabrication incentives, anchoring power transistor packaging operations and captive substrate supply negotiations.
Canada
Utility-scale renewable energy deployments in Ontario and Alberta specify wide-bandgap semiconductors for grid-tied solar converters and wind turbine inverters. Health Canada electrical safety regulations align with OSHA directives on isolated packaging designs for industrial applications. The Pacific Northwest and Quebec manufacturing clusters attract power electronics assembly for mining equipment and hydroelectric infrastructure.
Mexico
Automotive tier-one suppliers in Nuevo León and Jalisco face talent scarcity in power electronics engineering for wafer fabrication and packaging operations. The country's national industrial regulator enforces electrical safety standards harmonized with US OSHA requirements. Guadalajara and Monterrey assembly hubs reorganize semiconductor firm allocation strategies as captive training programs create first-mover advantage.
Brazil
Industrial motor drive suppliers in São Paulo and Minas Gerais balance thermal performance against unit economics in cost-sensitive segments. ANVISA medical device regulations and national energy efficiency programs create divergent certification pathways for power transistor procurement. The Southeast manufacturing corridor concentrates demand from agricultural machinery and mining equipment OEMs.
Chile
Grid-tied solar converter deployment in the Atacama Desert drives concentrated demand for high-voltage silicon carbide packaging. The country's national energy commission mandates efficiency benchmarks for utility-scale renewable integration. Santiago and Antofagasta industrial clusters anchor power electronics procurement for mining electrification and copper smelting operations.
Americas Power Transistor Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the Americas power transistor market. Vertically integrated substrate producers command pricing power in silicon carbide supply-constrained segments, while fabless designers compete on architectural innovation in price-competitive MOSFET categories. Three archetypes dominate: captive substrate suppliers with backward integration into wafer growth, broad analog portfolio houses serving automotive tier-ones, and discrete specialists focused on industrial motor drive certification. Competitive moves concentrate on capacity expansion in Texas and California corridors and strategic partnerships for Mexico assembly hub talent development.
Among European-integrated semiconductor houses, Infineon Technologies AG and STMicroelectronics N.V. exemplify the captive substrate archetype, occupying positions where in-house silicon carbide wafer production anchors high-voltage industrial demand. Texas Instruments Inc. represents the broad portfolio tier, sitting within price-competitive MOSFET segments across automotive supplier channels. These three companies illustrate how geographic integration strategy and product architecture breadth determine competitive positioning in EPA- and NHTSA-regulated procurement environments.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| Texas Instruments Inc. |
| STMicroelectronics N.V. |
| NXP Semiconductors N.V. |
| Renesas Electronics Corporation |
| Mitsubishi Electric Corporation |
| ON Semiconductor Corporation |
| Toshiba Corporation |
| Diodes Incorporated |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide substrate substitution for silicon wafers simultaneously redraws supply geography toward Texas and California manufacturing corridors and compresses pricing economics for fabless designers locked out of captive wafer growth. This material transition concentrates pricing power among vertically integrated producers while forcing tier-one automotive suppliers into long-term offtake negotiations.
Pricing Analysis
Long-term offtake contracts dominate high-volume automotive procurement as California and Texas OEMs secure captive silicon carbide supply, while spot-market exposure persists for industrial motor drive suppliers facing copper and aluminum metallization cost swings. Price differentiation rests on junction temperature certification tiers and volume scale, with 175-degree Celsius tolerance commanding premiums over standard-grade alternatives. Cost compression in silicon IGBT segments is intensifying because legacy inventory integration delays wide-bandgap migration timelines. Fleet procurement managers exhibit lowest price sensitivity, prioritizing total cost of ownership metrics including energy losses and cooling system mass.
Supply Chain Analysis
Port congestion across Pacific trade lanes elevates inbound logistics costs for silicon carbide substrates sourced from Asian wafer growth facilities, compressing margins for packaging operations in Mexico assembly hubs. Supply concentrates in Taiwan, South Korea, and the United States for epitaxial layering and trench-gate fabrication. Raw material dependencies include high-purity silicon carbide boules, copper metallization interconnects, and ceramic packaging substrates. Single-source vulnerability in substrate supply creates structural risk for fabless designers lacking backward integration. Distribution runs through direct OEM contracts displacing traditional channel partners in high-volume electric vehicle segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized epitaxial layering expertise for 175-degree Celsius junction tolerance remains trapped in legacy silicon foundries, creating a bottleneck that favors incumbents with in-house process engineering and disadvantages new entrants lacking captive fabrication assets.
For Market Incumbents: Fortify substrate supply security through captive wafer growth expansion in Texas and California corridors, locking in automotive tier-one contracts before EPA 2027 certification deadlines force competitor redesign cycles. Deepen thermal simulation software capabilities to capture adjacent revenue from OSHA electrical safety directive compliance services, defending against fabless designers seeking architectural innovation offsets. For New Entrants and Emerging Players: Differentiate on Mexico assembly hub talent development, establishing captive training programs in Guadalajara and Monterrey ahead of power electronics engineering scarcity resolution. Target industrial motor drive certification as the most penetrable segment, where extended EPA timelines delay incumbent silicon carbide migration and price-competitive silicon IGBT alternatives retain relevance. For Investors and Strategic Acquirers: The market sits at a substrate-supply-constrained phase that favors vertically integrated producers with backward wafer growth control over fabless architectural innovators. Long-term viability across the next decade hinges on silicon carbide foundry economics improvement and automotive direct-sourcing pattern maturation. Monitor captive supply agreement announcements from California electric vehicle OEMs as the critical inflection signal for pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Silicon Carbide Wafer Growth Expansion | Backward integration into substrate production locks in automotive tier-one supply security under NHTSA fuel economy mandates. |
| Mexico Assembly Hub Talent Development Program | Guadalajara and Monterrey training centers address power electronics engineering scarcity reshaping regional allocation strategies. |
| Thermal Simulation Software Acquisition | OSHA electrical safety directive compliance services open adjacent revenue streams from isolated packaging design demand. |
| Direct OEM Contract Negotiation | Bypassing distribution channels captures high-volume electric vehicle procurement shifting toward captive supply agreements. |
| Industrial Motor Drive Certification Investment | Extended EPA timelines for medium- and heavy-duty vehicles preserve silicon IGBT relevance in cost-sensitive segments. |
Research Methodology
Initial hypotheses were tested against primary input from power electronics engineering directors, automotive tier-one procurement leads, wafer fabrication operations managers, and industrial motor drive OEMs and refined through secondary validation against SEC semiconductor filings, Department of Energy efficiency mandate documentation, EPA emissions benchmark releases, and customs trade data for silicon carbide substrate flows. Bottom-up segment sizing triangulated against top-down market aggregation ensures dimensional consistency across product architectures and end-use certifications.
Variance decomposition across switching technology, application vertical, and regional manufacturing cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by average selling price evolution. Forecast inputs included electric vehicle platform electrification roadmaps, utility-scale solar deployment pipelines, and industrial motor system replacement cycles under efficiency mandates.
Decision-makers should treat outputs as directional under assumptions of sustained EPA and NHTSA regulatory stringency and silicon carbide substrate supply expansion; material deviation in emissions timeline enforcement or wafer growth capacity addition would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
N-Topcon Solar Cells Market
Semiconductor Devices
Europe Touch Screen Controllers Market
Semiconductor Devices
Europe MLCC Market
Semiconductor Devices
Global Bipolar Power Transistor Market
Semiconductor Devices
Global Power MOSFET Market
Semiconductor Devices
Non-Volatile Dual in-Line Memory Module Market
Semiconductor Devices
Solar Cell Paste Market
Semiconductor Devices
3D TSV Device Market
Semiconductor Devices
Superconductor Wire Market
Semiconductor Devices
Global Embedded FPGA Market
Semiconductor Devices
CMP Pads Market
Semiconductor Devices
5G Modems Market
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
Field Programmable Gate Array (FPGA) Market
Semiconductor Devices
Large-Size PV Silicon Wafer Market
Semiconductor Devices
APAC Semiconductor Device in Aerospace and Defense Market