
 Semiconductor in Phones Market | 2026-2036
Semiconductor in Phones Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor in Phones Market Insights
Direct procurement between foundries and flagship smartphone OEMs is tilting away from traditional distributor intermediaries. Qualcomm Technologies leverages its integrated modem-AP platforms to sustain premium tier design wins. Samsung Electronics anchors supply security through captive foundry and memory production. MediaTek competes aggressively in mid-range 5G SoC slots across emerging market handset brands.
Semiconductor in Phones encompasses the integrated circuits, discrete devices, and system-level packages engineered specifically for mobile handset operation, typically fabricated on process nodes ranging from mature 28nm to leading-edge 3nm and packaged into thermally constrained enclosures under 8W sustained power budgets. These components execute baseband processing, application computation, image signal processing, and power conversion to enable voice, data, and multimedia services in portable form factors. Processor and SoC categories command the dominant share of handset semiconductor value, while memory chips exhibit the steepest content growth per device as RAM and storage configurations expand. Power Management ICs represent a mature margin pool where analog specialization and voltage rail count proliferation sustain incumbent positions.
FCC equipment authorization in the United States, CE marking under the EU Radio Equipment Directive, and China's MIIT network access licensing collectively gate market entry by mandating electromagnetic compatibility, SAR limits, and interoperability testing. REACH substance restrictions and evolving EU battery regulations further constrain material selection and end-of-life design obligations for components sold into European phones. Stakeholders must monitor how divergent national cybersecurity certification requirements for handset chipsets reshape sourcing flexibility and inventory segmentation across regional product variants.
Market Dynamics
Foundry capacity concentration in Taiwan and South Korea is forcing smartphone OEMs into multi-year prepayment contracts for advanced node allocation, fundamentally restructuring working capital requirements and supplier bargaining power across the handset semiconductor supply base.
Growth Catalysts
- EU AI Act compliance mandates:European-bound handsets require dedicated neural processing units and on-device inference capabilities, pulling higher ASP silicon into mid-tier devices.
- China's MIIT network access licensing:Domestic 5G baseband certification requirements favor local fabless designers and foundry partnerships, accelerating import substitution.
- On-device generative AI:Large language model compression techniques enable 7B-parameter models to run on smartphone NPUs, expanding premium silicon content per device.
Market Restraints
- Advanced node cost escalation:3nm wafer prices from TSMC exceed $20,000, compressing gross margins for all but the highest-volume flagship programs.
- EUV lithography equipment chokepoints:ASML's annual extreme ultraviolet scanner output limits leading-edge capacity expansion regardless of capital availability.
- REACH substance restrictions:ECHA's expanding candidate list of restricted chemicals forces material requalification for European-bound chip packaging and substrates.
Strategic Opportunities
- India PLI scheme incentives:Production-linked incentives for semiconductor assembly and testing attract handset component localization for export markets.
- Chiplets and 2.5D packaging:Die disaggregation enables cost-effective mixing of process nodes within a single smartphone SoC, opening architectural differentiation.
- Automotive-to-handset IP migration:Functional safety methodologies from ISO 26262-adjacent design practices transfer to mission-critical smartphone subsystems.
Industry Challenges
- Packaging thermomechanical simulation expertise:Advanced fan-out and hybrid bonding require specialized finite element modeling talent concentrated among a handful of OSAT engineering teams.
- Multi-regional certification parallelism:Simultaneous FCC, CE, and MIIT approval timelines create inventory segmentation complexity for global SKU strategies.
- Legacy baseband IP licensing:Essential patent thickets around 4G and 5G standards impose royalty stacking that erodes margin on cost-optimized modem platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor in Phones Market |
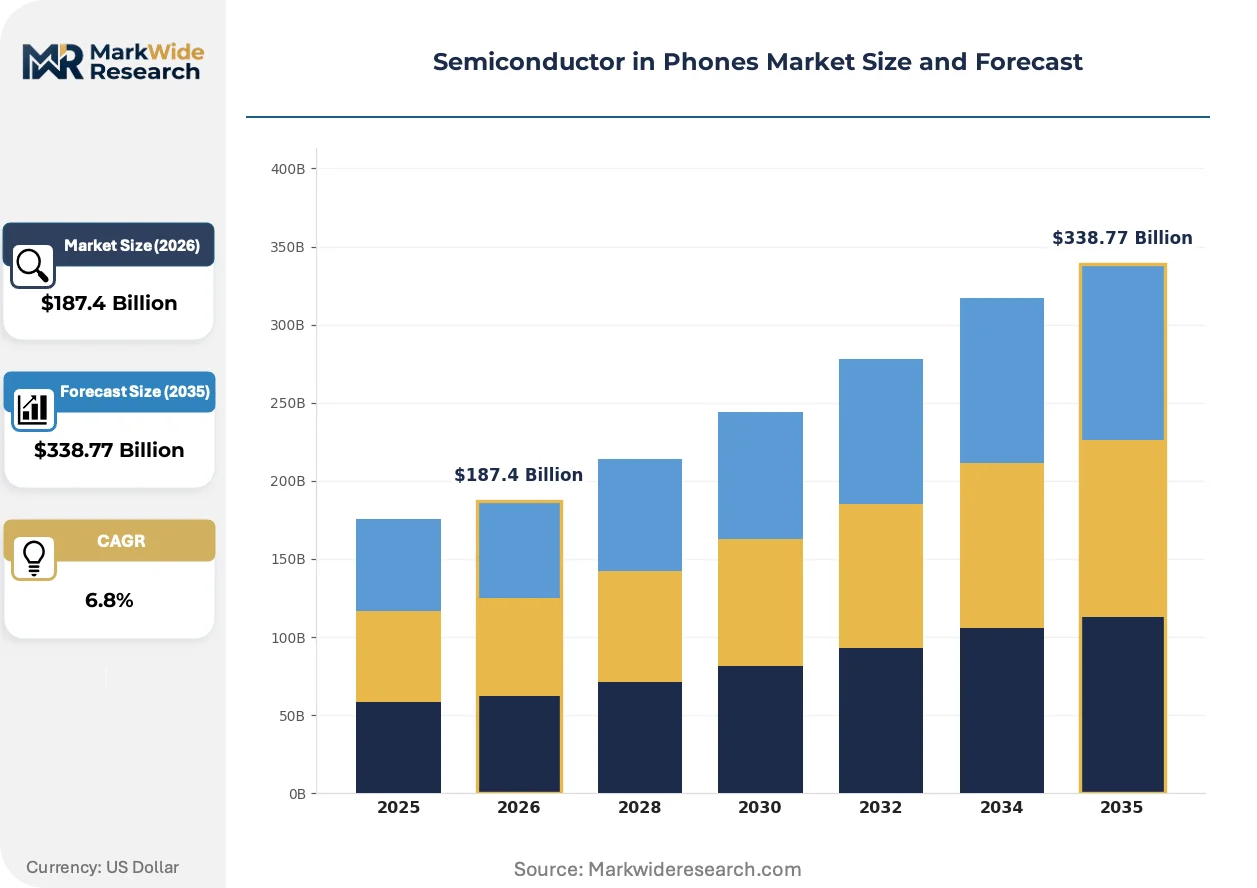
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Processors, Memory Chips, Power Management ICs End User: OEMs, Aftermarket Providers, Assemblers, Retailers Technology: FPGA, ASIC, SoC, DSP Application: Smartphones, Feature Phones, Tablets, Wearables |
| Companies Covered | Qualcomm Technologies, MediaTek, Samsung Electronics, Apple, HiSilicon Technologies, UNISOC Technologies, Skyworks Solutions, Qorvo, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor in Phones Market Trends and Innovations
Gate-all-around transistor architectures and heterogeneous integration are compressing power-performance-area tradeoffs, enabling new computational workloads inside thermally constrained handset enclosures without expanding physical device dimensions.
Gate-all-around nanosheet transistors replace finFET structures at the 3nm node and below, delivering superior electrostatic control and reduced leakage currents. Samsung Foundry and TSMC have both qualified GAA processes for smartphone SoC production. This architecture is rendering obsolete the voltage-frequency scaling assumptions that governed finFET-era power management IC design.
REACH substance restrictions under ECHA oversight now cover 235 hazardous chemicals with mandatory supply chain disclosure obligations. Smartphone semiconductor packaging must eliminate specific brominated flame retardants and phthalate plasticizers to maintain European market access. Mid-tier handset OEMs without dedicated compliance teams face the steepest requalification burdens and sourcing disruption risks.
Direct foundry contracting is displacing traditional distributor relationships for flagship smartphone programs, with OEMs now negotiating wafer allocation two to three years ahead of volume production. This concentration of purchasing power among the top five handset brands squeezes component margins and reduces design win visibility for second-tier semiconductor suppliers. The shift is most pronounced in China, where domestic brands leverage captive foundry relationships for supply security.
Semiconductor in Phones Market Segmentation
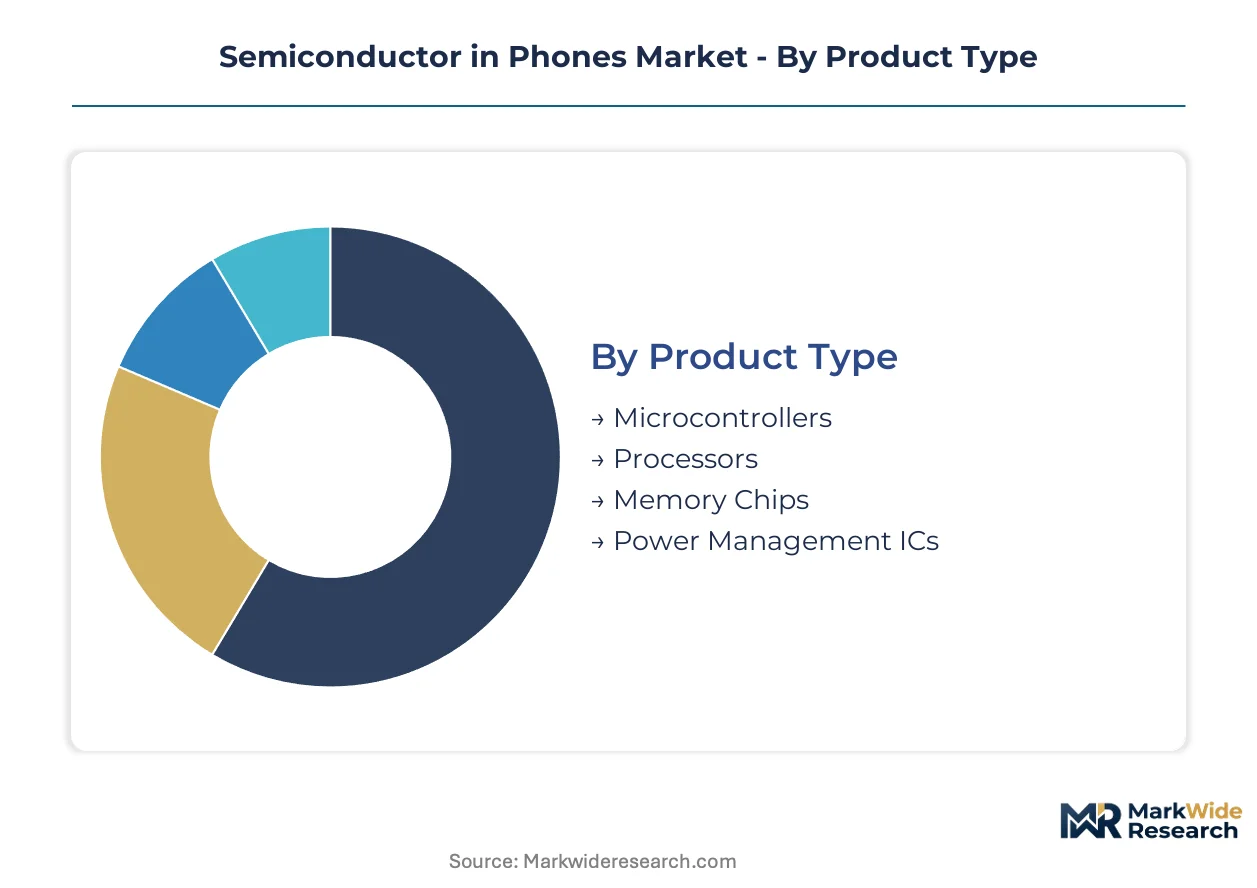
Smartphone semiconductor procurement patterns diverge sharply across product categories and supply chain tiers. OEMs negotiate directly for advanced processors while distributors handle legacy analog components. Regulatory fragmentation across FCC, CE, and MIIT jurisdictions forces inventory segmentation that reshapes demand concentration by application type.
Product Type:
Use cases span from deterministic real-time control to high-performance generative inference, creating distinct margin pools and supplier relationships across the handset silicon stack.
- Microcontrollers:Embedded 32-bit ARM Cortex-M cores manage sensor fusion, haptic feedback, and battery gauge monitoring in sub-1W power envelopes. Demand clusters in China for domestic brand TWS companion chips and wearable controllers, driven by MIIT localization requirements for connected accessories.
- Processors:Application processors and baseband modems integrate on leading-edge 3nm-4nm nodes, consuming 60-70% of handset semiconductor value per device. Qualcomm and MediaTek design wins concentrate in flagship and mid-tier 5G slots respectively, with EU AI Act compliance pulling NPU silicon into European-bound SKUs.
- Memory Chips:LPDDR5X DRAM and UFS 4.0 NAND stack in package-on-package configurations.
- Power Management ICs:Multi-rail regulators and battery charger ICs fabricated on mature BCD processes.
By volume, Power Management ICs lead. By growth pace, Memory Chips are expanding most quickly.
End User:
Cost tier stratification separates direct foundry contracting from distributor-mediated procurement, with working capital requirements scaling inversely with supply chain proximity to silicon.
- OEMs:Apple, Samsung, and Xiaomi negotiate multi-year wafer prepayments for advanced node allocation, bypassing traditional distribution. Their captive procurement teams manage qualification pipelines across TSMC, Samsung Foundry, and SMIC for supply security.
- Aftermarket Providers:Independent repair networks and refurbishment specialists source legacy chipsets through authorized distributors. REACH substance documentation requirements for European repair parts create compliance friction that favors larger aftermarket consolidators over independent operators.
- Assemblers:Foxconn, Pegatron, and BYD Electronics manage component consignment from OEM-specified suppliers.
- Retailers:Carrier stores and electronics chains stock replacement parts and accessory chipsets.
OEMs dominate value capture. Aftermarket Providers are gaining share fastest as right-to-repair regulations expand.
Technology:
Integration density determines architectural tradeoffs between flexibility, unit cost, and time-to-market across handset subsystem design.
- FPGA:Programmable logic enables rapid prototyping of camera ISP pipelines and AI acceleration for flagship validation platforms. Demand concentrates in Samsung and Apple pre-silicon development labs, constrained by power consumption penalties that disqualify FPGAs from production handset deployment.
- ASIC:Custom-designed accelerators for image signal processing and neural inference optimize die area and power efficiency. Google's Tensor G-series and Apple's dedicated camera ISPs exemplify this approach, with design costs amortizable only at 10M+ unit volumes.
- SoC:Integrated application processor, modem, and NPU complexes dominate premium handset silicon.
- DSP:Dedicated audio and sensor processing cores offload real-time tasks from the main CPU.
SoC integration leads by volume. ASIC deployment is climbing the fastest as OEMs seek camera and AI differentiation.
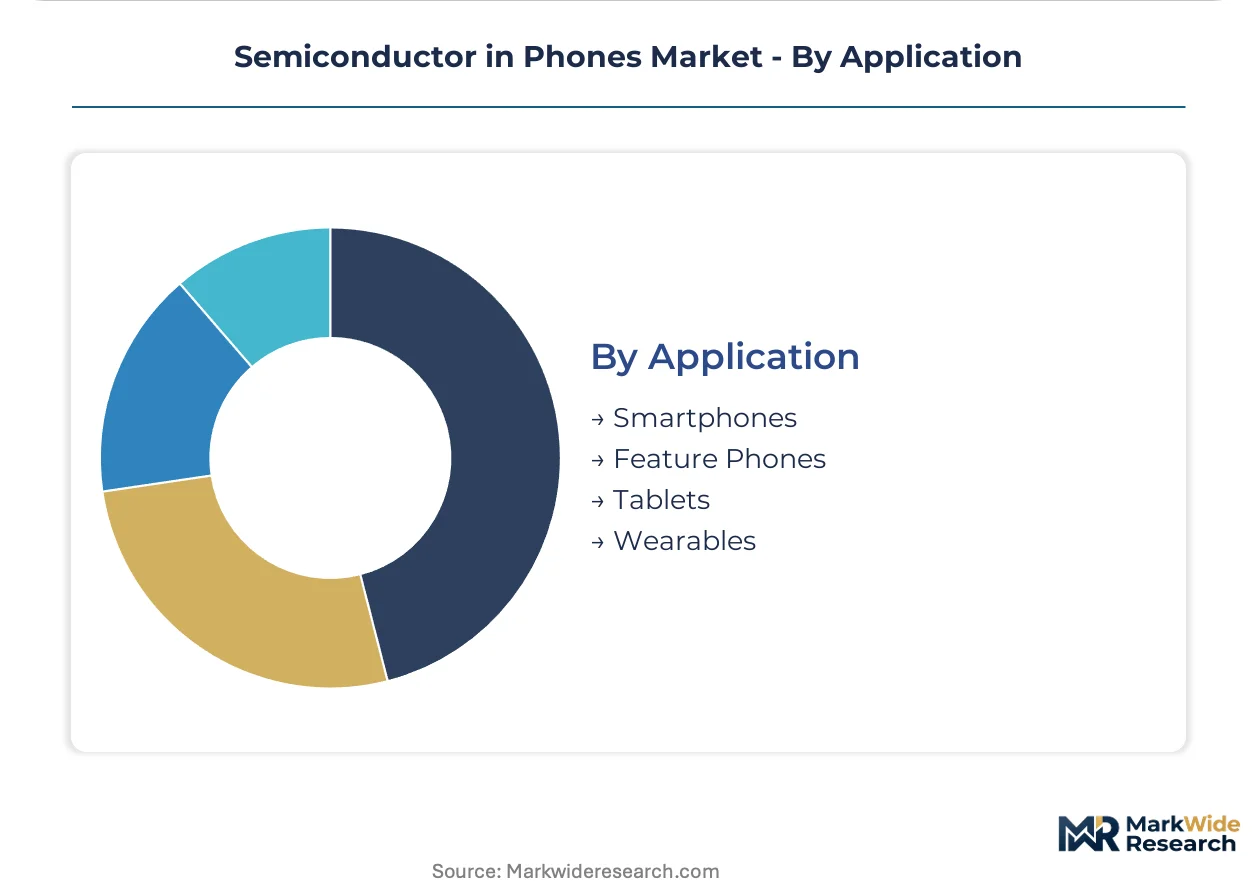
Application:
Form factor thermal envelopes and battery constraints dictate semiconductor content mix, with wearables imposing the most severe power-performance tradeoffs.
- Smartphones:Flagship devices integrate 3nm SoCs, 16GB+ LPDDR5X, and multi-camera ISP pipelines within 8W sustained thermal budgets. China's domestic brands drive fastest content growth as MIIT 5G certification requirements accelerate local baseband adoption.
- Feature Phones:4G VoLTE-enabled voice-centric devices run on mature 28nm-40nm integrated modem-AP chips. Demand persists in India and sub-Saharan Africa where TRAI and national regulators mandate local assembly for network access subsidies.
- Tablets:Larger thermal envelopes enable higher TDP processors shared with smartphone platforms.
- Wearables:Sub-1W power budgets drive ultra-low-power microcontroller and specialized sensor hub architectures.
Smartphones dominate unit volumes. Wearables are gaining share fastest as health monitoring expands TAM.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT certification requirements in China are restructuring procurement patterns across the handset semiconductor supply base. Foundry capacity concentration in Taiwan and South Korea forces multi-year prepayment contracts. Divergent regulatory frameworks in the United States, Europe, and China reshape inventory segmentation strategies.
United States
FCC equipment authorization mandates electromagnetic compatibility testing for all handset chipsets entering the market. The IRA's domestic manufacturing incentives attract advanced packaging investments to Arizona and Texas. Apple's silicon engineering operations in Cupertino drive captive SoC design that bypasses traditional merchant semiconductor channels.
China
Domestic brands accelerate import substitution through local foundry partnerships for baseband and power management chips. MIIT network access licensing favors fabless designers with captive certification pipelines. Yangtze River Delta clusters in Shanghai and Suzhou concentrate advanced packaging capacity for European-bound handset exports.
South Korea
Samsung Electronics anchors supply security through captive foundry and memory production serving both internal handset divisions and external OEMs. MFDS cybersecurity certification requirements for biometric processing chips add compliance layers to flagship programs. Seoul Capital Area engineering centers concentrate GAA transistor process development for 3nm smartphone SoCs.
Germany
REACH substance restrictions under ECHA oversight force material requalification for European-bound chip packaging. KBA-adjacent functional safety methodologies transfer to mission-critical smartphone subsystems through Munich and Stuttgart engineering hubs. Bavarian semiconductor distributors manage qualification pipelines for mid-tier handset OEMs lacking dedicated compliance teams.
India
PLI scheme incentives attract semiconductor assembly and testing investments for export-market handset components. TRAI mandates local assembly for network access subsidies on voice-centric devices. Gujarat and Tamil Nadu industrial corridors concentrate EMS operations that consign OEM-specified chips from TSMC and Samsung Foundry.
Semiconductor in Phones Market Competitive Landscape
Integrated platform vendors and specialized component suppliers split the market along architectural integration boundaries. The vendor base concentrates among five firms controlling advanced node allocation through direct foundry contracting. Fabless designers with captive modem-AP integration capabilities occupy one archetype; memory and analog specialists with process-specific expertise occupy another. Competitive moves center on multi-year wafer prepayment contracts and heterogeneous packaging partnerships that mix process nodes within single device enclosures.
Within the integrated platform tier, Qualcomm Technologies and MediaTek exemplify divergent positioning strategies. Qualcomm Technologies leverages modem-AP integration for premium-tier design wins. MediaTek competes aggressively in mid-range 5G SoC slots across emerging market handset brands. Samsung Electronics anchors a distinct archetype through captive foundry and memory production that supplies both internal handset divisions and external OEM programs.
| Leading Market Players |
|---|
| Qualcomm Technologies |
| MediaTek |
| Samsung Electronics |
| Apple |
| HiSilicon Technologies |
| UNISOC Technologies |
| Skyworks Solutions |
| Qorvo |
| NXP Semiconductors |
| Others |
Pricing and Supply Chain Analysis
Foundry undercapacity in Taiwan and South Korea is compressing supplier flexibility and amplifying pricing power for advanced node allocation, forcing smartphone OEMs into multi-year prepayment structures that reshape working capital dynamics across the handset semiconductor supply base.
Pricing Analysis
Wafer price spreads between 3nm leading-edge and 28nm mature nodes exceed tenfold, creating extreme cost stratification across smartphone tiers. Three-tier pricing structure across premium, standard, and economy levels separates flagship SoC programs from mid-range 5G slots and legacy 4G voice-centric devices. Cost compression in the mid-tier is intensifying because MediaTek and UNISOC are absorbing margin erosion to secure design wins against Qualcomm's modem-AP integration. Emerging market handset brands exhibit highest price sensitivity, while Apple and Samsung's captive silicon teams demonstrate lowest sensitivity due to volume scale and backward integration.
Supply Chain Analysis
High-purity silicon wafers, EUV-grade photoresists, and specialty gases for 3nm etching processes anchor upstream feedstock dependencies for handset semiconductor manufacturing. Supply concentrates in Taiwan for leading-edge foundry capacity, South Korea for memory fabrication, and Japan for specialty chemical and equipment components. Single-source vulnerability around ASML's extreme ultraviolet scanner output limits capacity expansion regardless of capital availability. Distribution runs through direct foundry contracting for flagship OEMs, while authorized distributors handle legacy analog and power management components for mid-tier programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among the top five smartphone OEMs, who now command multi-year wafer allocation negotiations that squeeze component margins and reduce design win visibility for second-tier suppliers.
For Market Incumbents: Pre-empt foundry capacity lock-in by securing 3nm allocation commitments before EUV equipment constraints harden. Anchor supply security through captive or exclusive foundry partnerships in Taiwan and South Korea. Counter MediaTek's mid-range aggression by accelerating NPU integration for EU AI Act compliance, creating differentiation that justifies premium pricing against cost-optimized alternatives. For New Entrants and Emerging Players: Pursue heterogeneous packaging specialization as architectural differentiation opens white-space between monolithic SoC and discrete component approaches. Target India's PLI scheme incentives for semiconductor assembly and testing localization, where export-market handset component demand outstrips qualified supplier capacity. Lead with chiplets and 2.5D integration expertise to bypass the capital barriers blocking leading-edge node entry. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among analog and power management specialists with process-specific expertise that sustains incumbent positions through multi-generation product cycles. Long-term viability in this market hinges on backward integration into foundry relationships or forward integration into OEM-specified supplier status. Watch for MIIT certification pipeline acceleration as the signal indicating which fabless designers are securing sustainable China market access.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Foundry Prepayment Contract | TSMC and Samsung Foundry allocation commitments secure 3nm capacity for flagship smartphone programs against EUV equipment constraints. |
| Heterogeneous Packaging Partnership | Die disaggregation enables cost-effective mixing of process nodes within single smartphone SoC architectures. |
| EU AI Act Compliance Certification | ECHA and EU regulatory alignment pulls dedicated NPU silicon into mid-tier European-bound handset SKUs. |
| India PLI Scheme Localization | Production-linked incentives attract semiconductor assembly and testing investments for export-market handset components. |
| REACH Substance Requalification | ECHA oversight mandates supply chain disclosure for 235 hazardous chemicals in European-bound chip packaging. |
Research Methodology
A spread of perspectives from foundry operations executives, smartphone OEM procurement directors, fabless semiconductor R&D leads, and OSAT engineering managers converged on the working assumptions underlying this analysis. Primary interviews combined with secondary validation against SEC filings, MIIT network access licensing records, ECHA REACH substance databases, and customs trade data. Bottom-up smartphone semiconductor content modeling and top-down foundry capacity allocation analysis were triangulated for consistency.
Demand-supply balance dynamics across the analysis window shaped the forecast framework, with segmentation by product type, end user tier, technology integration level, and application form factor. CAGRs were derived from unit shipment projections and silicon content per device trajectories, incorporating foundry wafer pricing trends and memory spot market volatility as industry-specific inputs.
Sensitivities concentrate around EUV lithography equipment delivery schedules, MIIT certification timeline shifts, and REACH substance list expansions. Cross-checking against TSMC and Samsung Foundry disclosed capacity roadmaps is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Die Spacer Market
Semiconductor Devices
Global Switched Capacitor Filter Market
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
Micro and Nano PLC Market
Semiconductor Devices
Silicon Carbide (SIC) Power Semiconductors Market
Semiconductor Devices
Japan CEP Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
United Arab Emirates (UAE) CEP Market
Semiconductor Devices
Europe MLCC Market
Semiconductor Devices
Smart Gate Driver Market
Semiconductor Devices
Hybrid Microcircuits Market
Semiconductor Devices
Single Electron Transistor Market
Semiconductor Devices
Japan International CEP Market
Semiconductor Devices
Gallium Nitride (Gan) Semiconductor Devices Market
Semiconductor Devices
LTCC and HTCC Market
Semiconductor Devices
China MLCC Market