
 Wttx Market | 2026-2036
Wttx Market Size, Share, and Industry Trends Forecast 2026-2036
Wttx Market Analytics
Leasing-based network infrastructure models is reconfiguring capital deployment patterns for wireless broadband operators. Huawei Technologies leverages integrated baseband and radio unit portfolios to sustain manufacturing scale across multiple continents. Nokia Corporation anchors its competitiveness through specialized massive MIMO antenna systems for dense urban WTTx rollouts. Ericsson differentiates via end-to-end network slicing capabilities that position it for enterprise-grade service level agreements.
WTTx (Wireless To The x) denotes fixed wireless access systems that deliver broadband connectivity through cellular or microwave radio links rather than fiber or copper cable, typically operating in sub-6 GHz or millimeter-wave spectrum bands with throughput exceeding 100 Mbps. These systems serve residential, commercial, and institutional endpoints where wired infrastructure proves economically unviable or deployment timelines extend beyond acceptable thresholds. The technology dimension spans Fixed Wireless Access, Satellite Communications, Microwave, and LTE, with Fixed Wireless Access currently dominating volume due to 5G NR standardization while Satellite Communications represents the fastest-expanding margin pool as low-earth orbit constellations mature. Deployment modalities split across On-Premises, Cloud-Based, Hybrid, and Virtualized configurations, and cloud-based architectures are capturing disproportionate investment as operators seek centralized radio access network management.
The Federal Communications Commission shapes WTTx market access through spectrum allocation rules and competitive bidding frameworks, while the International Telecommunication Union coordinates global standards that determine equipment interoperability and roaming protocols. National regulators in key demand centers enforce cybersecurity certification requirements that filter vendor eligibility and influence procurement decisions. Stakeholders must monitor spectrum reallocation proceedings and open RAN interoperability mandates as these will determine which technology portfolios retain strategic value.
Market Dynamics
The shift toward open RAN architectures is fragmenting vendor lock-in patterns and forcing incumbents to unbundle proprietary hardware-software stacks, while spectrum scarcity pressures operators toward millimeter-wave and sub-6 GHz aggregation strategies.
Growth Catalysts
- FCC Spectrum Auctions:Competitive bidding frameworks for C-band and mmWave frequencies have accelerated infrastructure buildouts across the United States, enabling gigabit-speed residential deployments without fiber trenching.
- Rural Broadband Mandates:Government agencies in multiple jurisdictions are channeling subsidies toward fixed wireless access as the primary connectivity modality for underserved residential zones where cable economics fail.
- 5G NR Standardization:The unified air interface specification is hybridizing equipment ecosystems, allowing operators to leverage common hardware for mobile and fixed wireless services simultaneously.
Market Restraints
- Semiconductor Supply Concentration:Baseband processor and RF front-end module fabrication concentrates in East Asian foundries, exposing deployment timelines to geopolitical trade friction and capacity allocation decisions.
- Spectrum Licensing Costs:Upfront auction payments and recurring usage fees compress operator cash flows, particularly for regional challengers lacking the balance sheet depth of national incumbents.
- Line-of-Sight Limitations:Millimeter-wave propagation characteristics restrict coverage to unobstructed paths, requiring dense small-cell grids that escalate site acquisition and backhaul expenditures.
Strategic Opportunities
- LEO Satellite Convergence:Low-earth orbit constellations from SpaceX and emerging competitors are creating hybrid terrestrial-satellite service bundles for exurban and remote enterprise campuses.
- Cloud-Native RAN Architectures:Virtualized baseband processing enables operators to centralize compute resources, reducing per-site hardware footprints and enabling dynamic capacity scaling.
- Enterprise Network Slicing:End-to-end isolation capabilities position fixed wireless operators to capture manufacturing, logistics, and healthcare verticals requiring guaranteed service level agreements.
Industry Challenges
- Open RAN Integration Complexity:Multi-vendor interoperability testing extends deployment timelines as operators validate performance across disaggregated radio units, distributed units, and centralized units from different suppliers.
- RF Engineering Talent Scarcity:Specialized expertise in massive MIMO beamforming and mmWave propagation modeling remains concentrated among legacy infrastructure vendors, constraining operator in-house deployment capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wttx Market |
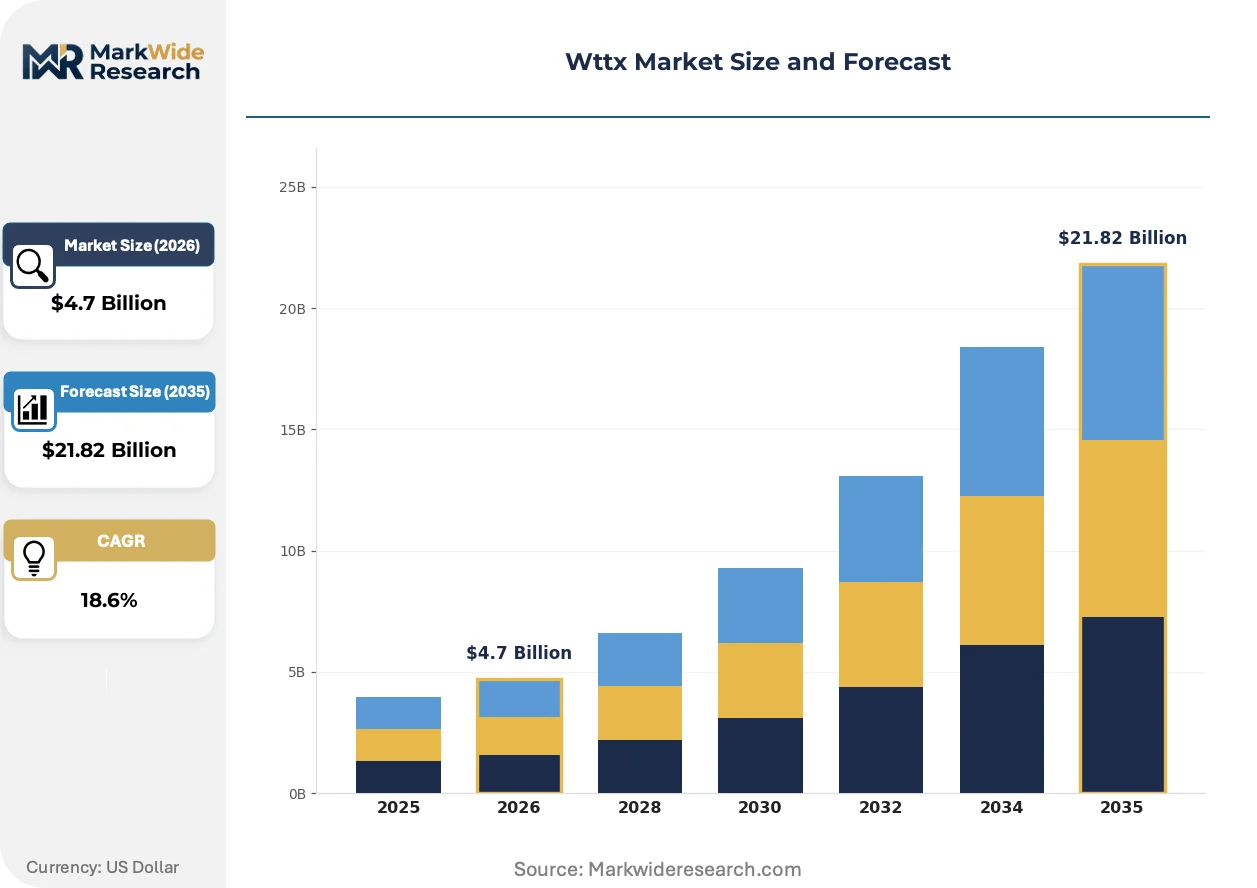
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $21.82 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fixed Wireless Access, Satellite Communications, Microwave, LTE End User: Residential, Small Business, Large Enterprise, Government Service Type: Managed Services, Technical Support, Consulting, Installation Deployment: On-Premises, Cloud-Based, Hybrid, Virtualized |
| Companies Covered | Huawei Technologies, Nokia Corporation, Ericsson, ZTE Corporation, Samsung Electronics, Qualcomm Technologies, CommScope, Cisco Systems, Airspan Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wttx Market Evolving Landscape
Open interface specifications and software-defined networking principles are dissolving traditional hardware-centric procurement patterns, while artificial intelligence is embedding into radio resource management for real-time spectral efficiency optimization.
Massive MIMO antenna arrays are hybridizing with intelligent reflecting surfaces to extend millimeter-wave coverage into non-line-of-sight environments. Rural electric cooperatives and municipal utilities are piloting these augmented deployments to bypass terrain constraints that previously blocked fixed wireless penetration. The structural consequence is compression of the addressable market gap between fiber-served urban cores and satellite-dependent remote areas.
The FCC's spectrum reallocation proceedings for the 3.45-3.55 GHz band are mandating coordination mechanisms between federal radar systems and commercial wireless operations. Equipment vendors must now certify base stations for dynamic spectrum sharing capabilities, adding firmware complexity but preserving auctioned spectrum value. Defense-dependent regions in the continental United States face elongated deployment timelines as interference mitigation protocols undergo field validation.
Enterprise procurement teams are consolidating vendor relationships around integrated fixed-wireless and private-network solution providers. Manufacturing facilities in the Midwest and Southeast are displacing discrete wireline and Wi-Fi contracts with unified 5G campus deployments managed through single service agreements. This concentration pattern is most visible among automotive suppliers and distribution centers seeking deterministic latency for automated material handling systems.
Wttx Market Segmentation
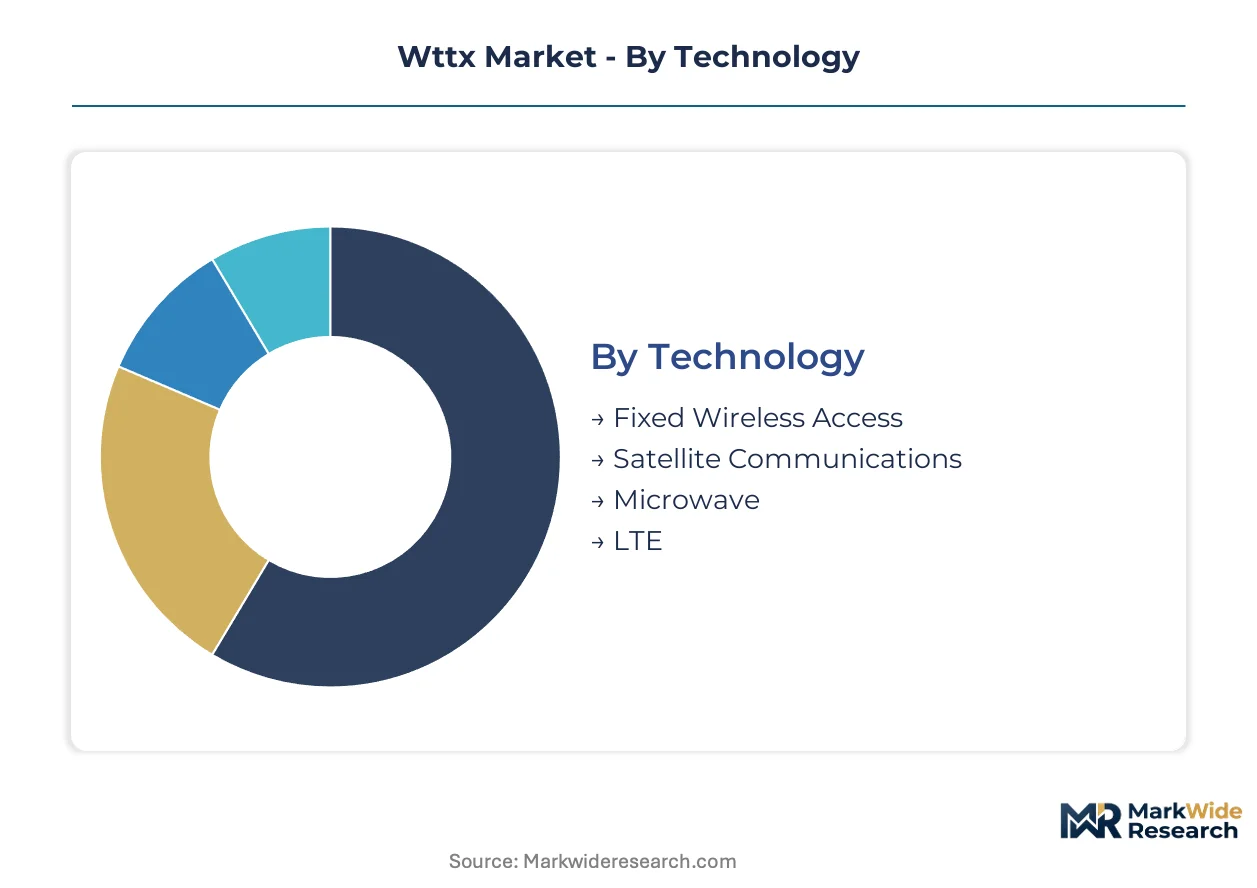
WTTx market segmentation reveals distinct service intensity profiles across deployment models. Each category carries specific margin structures and capital requirements that shape vendor positioning and operator procurement strategies.
Technology:
After-sales service intensity varies sharply across radio access technologies, with spectrum-dependent hardware requiring differentiated field engineering support and software update cadences.
- Fixed Wireless Access:5G NR-based systems operating in sub-6 GHz and millimeter-wave bands deliver throughput exceeding 100 Mbps to residential and commercial endpoints. United States operators concentrate procurement here following FCC C-band auctions that enabled gigabit-speed deployments without fiber trenching economics.
- Satellite Communications:Low-earth orbit constellations provide coverage extension into terrain-blocked regions where terrestrial radio links fail. Demand is climbing the fastest among remote enterprise campuses and exurban residential clusters seeking hybrid terrestrial-satellite bundles.
- Microwave:Point-to-point backhaul links serve as connectivity bridges for cell site aggregation and rural broadband extension.
- LTE:Legacy 4G infrastructure supports transitional deployments and cost-sensitive markets awaiting 5G NR hardware refresh cycles.
By volume, Fixed Wireless Access leads. By growth pace, Satellite Communications is ahead.
End User:
Customer type determines contract structure, with enterprise accounts demanding service level agreements that residential subscribers rarely negotiate.
- Residential:Household subscribers in underserved zones where cable economics fail drive volume procurement of standardized equipment packages. Rural broadband mandates from government agencies channel subsidies toward this segment across multiple jurisdictions.
- Large Enterprise:Manufacturing facilities and distribution centers require deterministic latency for automated material handling systems. Midwest and Southeast United States automotive suppliers consolidate procurement around unified 5G campus deployments.
- Small Business:Commercial establishments seek cost-competitive alternatives to fiber with minimal installation lead times.
- Government:Public sector entities prioritize cybersecurity certification requirements that filter vendor eligibility.
Residential deployments dominate unit shipments. Enterprise contracts generate premium pricing.
Service Type:
Recurring revenue attachment rates diverge based on whether operators internalize network operations or outsource to vendor-managed arrangements.
- Managed Services:Third-party network operation centers handle monitoring, optimization, and incident response for operators lacking in-house RF engineering depth. Cloud-based RAN architectures enable this model by centralizing compute resources.
- Technical Support:Tiered response commitments address hardware failure and software anomaly resolution.
- Consulting:Radio frequency planning and propagation modeling services support deployment design.
- Installation:Site acquisition, antenna mounting, and commissioning labor represent upfront project costs.
Managed Services commands the highest renewal rates. Installation revenue peaks during infrastructure buildout phases.
Deployment:
Infrastructure architecture choice directly impacts hardware footprint, spectral agility, and long-term upgrade pathways.
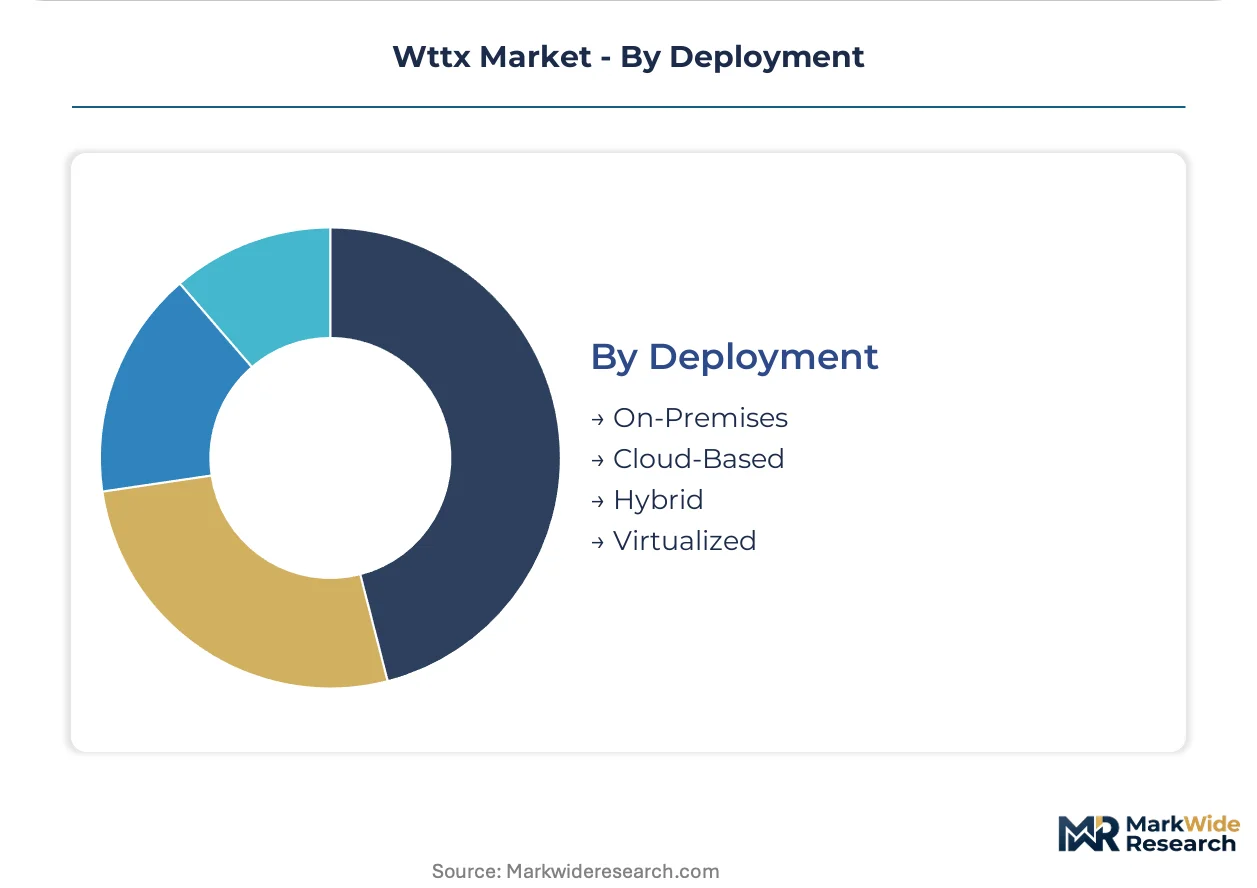
- Cloud-Based:Centralized baseband processing reduces per-site hardware requirements and enables dynamic capacity scaling. United States operators capture disproportionate investment here as they seek centralized radio access network management.
- Hybrid:Split processing between edge and core balances latency requirements against cost constraints. Municipal utilities and rural electric cooperatives pilot these configurations to bypass terrain limitations.
- On-Premises:Traditional distributed architectures maintain full hardware presence at each cell site.
- Virtualized:Software-defined implementations disaggregate hardware-software dependencies.
Cloud-Based architectures absorb the largest capital commitments. Hybrid models are expanding most quickly among mid-tier operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where FCC spectrum auctions created scarcity premiums, while Indian operators absorb equipment costs through government subsidy programs that compress vendor margins.
United States
C-band and mmWave infrastructure buildouts drive procurement intensity across suburban and rural zones. The FCC mandates dynamic spectrum sharing capabilities for 3.45-3.55 GHz band coordination with federal radar systems. Defense-dependent regions in the continental interior face elongated deployment timelines as interference mitigation protocols undergo field validation.
Germany
Industrial automation corridors in Baden-Württemberg and Bavaria generate enterprise-grade fixed wireless demand for deterministic latency applications. The Bundesnetzagentur enforces cybersecurity certification requirements under EU-wide network resilience directives. Stuttgart's automotive supplier cluster consolidates procurement around unified 5G campus deployments for automated material handling systems.
China
Sub-6 GHz massive MIMO rollouts serve residential broadband extension in tier-two and tier-three cities. The Ministry of Industry and Information Technology coordinates spectrum allocation across state-owned operators with centralized procurement frameworks. Shenzhen's equipment manufacturing ecosystem sustains baseband processor and radio unit production scale across multiple continents.
India
Rural broadband mandates channel subsidies toward fixed wireless access as the primary connectivity modality for underserved residential zones. The Telecom Regulatory Authority of India governs spectrum pricing frameworks that influence operator capital deployment patterns. Karnataka's technology corridor hosts pilot deployments of cloud-native RAN architectures for centralized radio access network management.
Japan
Enterprise network slicing trials target manufacturing and logistics verticals requiring guaranteed service level agreements. The Ministry of Economy, Trade and Industry coordinates 5G private network licensing for industrial facility automation. Nagoya's automotive production cluster evaluates hybrid terrestrial-satellite bundles for supply chain connectivity resilience.
Wttx Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying radio frequency modules and baseband processors. The vendor base organizes around three strategic archetypes: integrated infrastructure vendors with end-to-end portfolios, specialized radio access network component suppliers, and cloud-native software providers enabling virtualized deployments. Competitive positioning hinges on spectrum portfolio breadth, massive MIMO antenna system performance, and open RAN interoperability certification. Incumbents pursue strategic partnerships with semiconductor fabricators to secure supply allocation, while challengers license reference designs to accelerate time-to-market.
Within the integrated infrastructure tier, Huawei Technologies and Nokia Corporation exemplify divergent responses to open RAN fragmentation pressures. Huawei leverages manufacturing scale across integrated baseband and radio unit portfolios to sustain cost positioning. Nokia anchors competitiveness through specialized massive MIMO antenna systems engineered for dense urban deployment scenarios. Ericsson occupies a position emphasizing end-to-end network slicing capabilities for enterprise-grade service level agreements.
| Leading Market Players |
|---|
| Huawei Technologies |
| Nokia Corporation |
| Ericsson |
| ZTE Corporation |
| Samsung Electronics |
| Qualcomm Technologies |
| CommScope |
| Cisco Systems |
| Airspan Networks |
| Others |
Value Network & Pricing Analysis
Semiconductor fabrication concentration in East Asian foundries determines both equipment pricing spreads and supply chain vulnerability for WTTx infrastructure vendors. Tariff exposure and single-source dependencies for baseband processors compress margins on mid-tier equipment while amplifying premiums for certified, multi-sourced configurations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the WTTx equipment market. Premium tiers command spreads based on FCC certification status and massive MIMO beamforming performance, while economy tiers face compression from subsidized rural broadband procurement programs. Spectrum licensing cost pass-through intensifies pricing pressure on regional challengers lacking national incumbent balance sheet depth. Government and large enterprise segments exhibit lowest price sensitivity due to cybersecurity mandate compliance requirements, whereas residential operators remain most cost-constrained.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculus for WTTx baseband processors and RF front-end modules. Manufacturing concentrates in Taiwan, South Korea, and mainland China for advanced semiconductor nodes and antenna component fabrication. Raw material dependencies span gallium nitride substrates, high-frequency laminates, and precision filter ceramics. Distribution runs through authorized distributor networks serving tier-one operators alongside direct procurement channels for national carriers with sufficient volume scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open RAN interoperability mandates represent a platform-economics inflection that restructures vendor competitive dynamics around disaggregated hardware-software ecosystems rather than integrated stack dominance.
For Market Incumbents: Pre-empt margin erosion from cloud-native RAN challengers by deepening backward integration into semiconductor supply allocation and accelerating open interface certification timelines. Secure manufacturing scale advantages through captive foundry partnerships in Taiwan and South Korea. Prioritize massive MIMO antenna system performance differentiation to defend dense urban deployment positions against disaggregated radio unit competitors.
For New Entrants and Emerging Players: Build out cloud-native RAN software stacks targeting mid-tier operators lacking in-house RF engineering depth for managed services capture. Focus initial penetration on rural electric cooperatives and municipal utilities piloting hybrid deployment configurations. Leverage open RAN interoperability testing gaps to establish reference design licensing revenue before incumbents complete multi-vendor validation cycles.
For Investors and Strategic Acquirers: FCC spectrum reallocation proceedings for 3.45-3.55 GHz band coordination reshape the acquisition landscape toward vendors with proven dynamic spectrum sharing capabilities. Frame long-term viability around enterprise network slicing revenue attachment rates rather than residential subscriber volume. Monitor open RAN interoperability certification completion rates as the critical inflection signal for vendor portfolio strategic value retention.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Interoperability Certification | FCC mandates for 3.45-3.55 GHz band coordination filter vendor eligibility and preserve auctioned spectrum value. |
| Cloud-Native RAN Architecture Deployment | Centralized baseband processing enables dynamic capacity scaling for United States operators seeking operational efficiency. |
| Enterprise Network Slicing Capability Investment | End-to-end isolation positions vendors for manufacturing and logistics verticals requiring deterministic latency guarantees. |
| Semiconductor Supply Allocation Partnership | Taiwan and South Korea foundry relationships secure baseband processor fabrication capacity against geopolitical trade friction. |
| Hybrid Terrestrial-Satellite Service Bundle Development | LEO constellation convergence creates coverage extension revenue for exurban and remote enterprise campus connectivity. |
Research Methodology
Operator-level perspectives from network engineering directors, procurement officers at tier-one carriers, RF planning consultants, and regulatory affairs specialists anchored the qualitative base for this analysis. Primary interview findings triangulated against secondary sources including FCC spectrum auction records, SEC equipment vendor filings, ITU standardization documentation, and national regulator cybersecurity certification databases. Bottom-up deployment modeling across technology segments reconciled with top-down market sizing derived from operator capex disclosure patterns.
Scenario-bracketing framed the analytical approach across the projection horizon, with optimistic and conservative bounds reflecting spectrum allocation timing uncertainty and semiconductor supply disruption probabilities. Segmentation dimensions modeled encompass technology type, deployment architecture, end-user category, and service intensity tier alongside geographic regulatory cluster differentiation. CAGRs derived from equipment shipment trajectories and average selling price evolution patterns, incorporating 5G NR standardization adoption curves and rural broadband subsidy program scaling assumptions.
Stress conditions across spectrum licensing cost inflation, foundry capacity allocation disruptions, and open RAN interoperability validation delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding government subsidy persistence and equipment refresh cycle timing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Advanced HDI PCB Market
Semiconductor Devices
Global Small Signal Diode Market
Semiconductor Devices
Graphene Electronics Market
Semiconductor Devices
Global 8 - Bit Microcontroller Market
Semiconductor Devices
Topcon Solar Cell Market
Semiconductor Devices
Japan Power Transistor Market
Semiconductor Devices
Europe MLCC Market
Semiconductor Devices
APAC Semiconductor Device for Industrial Applications Market
Semiconductor Devices
Europe Semiconductor Device Market
Semiconductor Devices
Ram BOP Market
Semiconductor Devices
IT & Telecom Discrete Semiconductor Market
Semiconductor Devices
Global Gan on Diamond Semiconductor Substrates Market
Semiconductor Devices
Epi Wafer Market
Semiconductor Devices
Dynamic Electrograph Market
Semiconductor Devices
Europe Power Transistor Market
Semiconductor Devices
Field Programmable Gate Array (FPGA) Market