
 Advanced HDI PCB Market | 2026-2036
Advanced HDI PCB Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced HDI PCB Market Insights
The EU Green Deal is realigning material sourcing requirements for European electronics supply chains. Unimicron leverages its captive copper foil operations to manage resin-system costs across multi-layer HDI builds. AT&S sustains technology leadership in embedded-die substrates for automotive radar modules. Ibiden anchors Japan's supply of high-reliability substrates through vertical control of ABF laminate production.
Advanced HDI PCB refers to printed circuit boards fabricated with microvia interconnects below 150 micrometers, sequential lamination cycles, and line-space geometries under 75 micrometers, enabling dense component mounting in portable electronics and high-frequency modules. The boards serve primarily to miniaturize signal routing while preserving electrical integrity in space-constrained devices. Multi-layer HDI configurations command the dominant share of fabrication value as smartphone AP substrates and baseband modules require ten or more conductive layers. Microvia technology is expanding fastest among fabrication methods as stacked and staggered microvias replace through-hole vias in 5G handset boards. OEMs represent the most concentrated end-user channel, with Apple and Samsung procurement teams negotiating directly with substrate houses for flagship device allocations.
FCC equipment authorization rules govern electromagnetic emissions for wireless devices using HDI substrates in the United States. EPA hazardous waste regulations affect etching chemistry disposal at fabrication plants across North America. ISO 14001 environmental management standards shape supplier qualification criteria for European automotive OEMs. Stakeholders must track how REACH substance restrictions on halogenated flame retardants redirect laminate formulation roadmaps before next-generation product qualifications freeze.
Market Dynamics
Smartphone OEM procurement teams now negotiate directly with substrate houses for flagship device allocations, compressing traditional distribution layers and concentrating volume with vertically integrated fabricators.
Growth Catalysts
- EU F-Gas Regulation:The restriction on fluorinated gases in plasma etching is accelerating laser-based microvia adoption across European fabs, creating equipment upgrade cycles.
- 5G handset boards:Stacked and staggered microvia architectures are replacing through-hole vias in next-generation smartphone substrates, pulling demand for sequential lamination capacity.
- Taiwan's Taoyuan-Airport corridor:Substrate makers cluster near semiconductor packaging houses, generating co-location efficiencies that shorten qualification timelines for new designs.
Market Restraints
- ABF laminate supply concentration:Japanese suppliers control high-performance resin systems, exposing fabricators to input cost volatility during demand spikes.
- Copper foil purity requirements:Ultra-thin foil for microvia plating commands premium pricing, compressing margins on mid-tier HDI builds.
- REACH substance restrictions:Halogenated flame retardant bans are forcing laminate reformulations that delay next-generation product qualifications.
Strategic Opportunities
- Automotive radar modules:Embedded-die substrates for ADAS sensors represent underpenetrated volume as Tier-1s qualify new HDI suppliers.
- EU Green Deal alignment:Material sourcing requirements are creating first-mover advantages for European fabricators with certified green supply chains.
- Laser direct imaging:Convergence with additive manufacturing processes is enabling prototyping services that bypass traditional photomask bottlenecks.
Industry Challenges
- Microvia plating chemist talent:The specialized skill set for controlling aspect ratios below 0.8:1 is scarce across fabrication floors.
- ISO 14001 certification timelines:European automotive OEM supplier qualification cycles now extend 18-24 months for new substrate entrants.
- Sequential lamination capex:Each additional lamination cycle requires dedicated press capacity that strains balance sheets at mid-scale fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced HDI PCB Market |
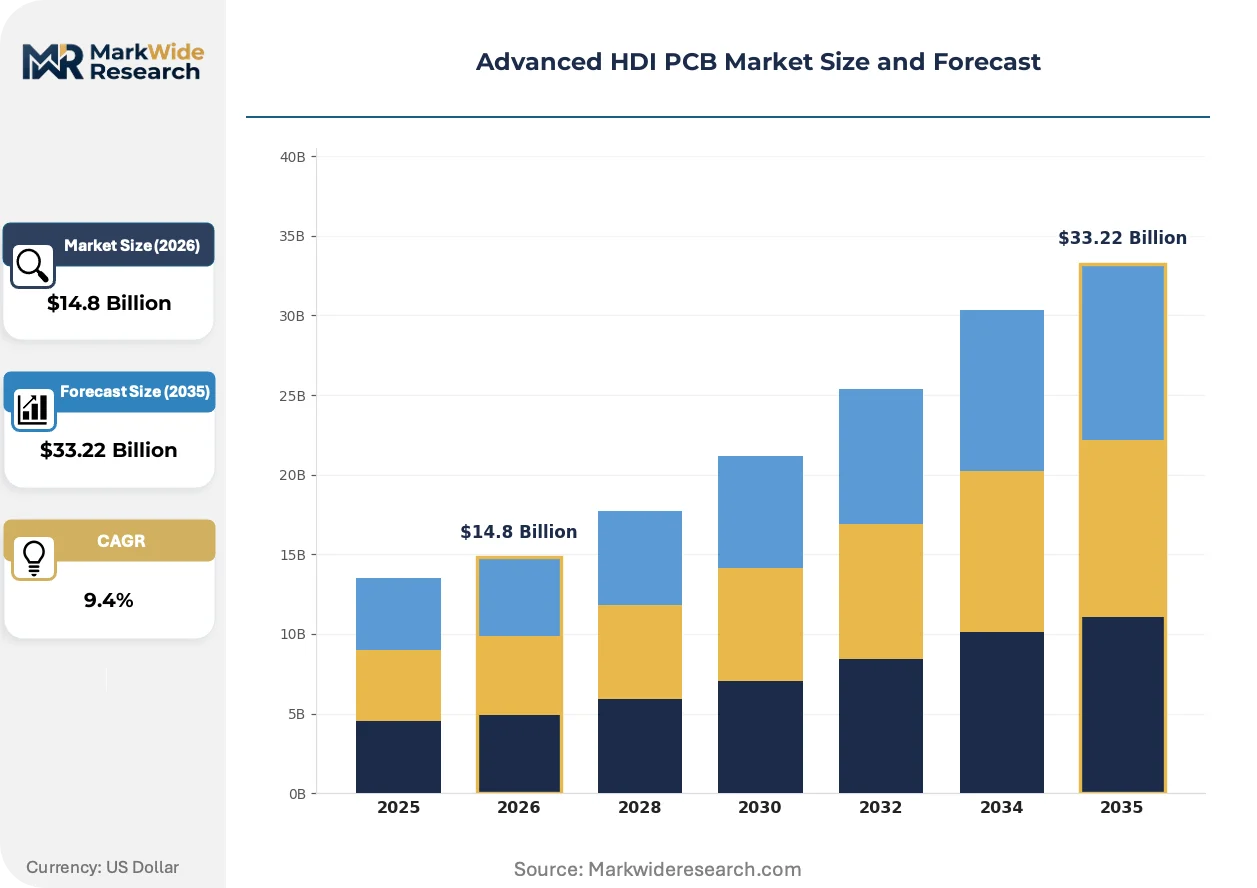
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $33.22 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid, Flexible, Rigid-Flex, Multi-layer Application: Consumer Electronics, Automotive, Telecommunications, Medical Devices End User: OEMs, Contract Manufacturers, ODMs, Aftermarket Providers Technology: Laser Direct Imaging, Via Plating, Microvia, HDI Lamination |
| Companies Covered | Unimicron, Compeq, AT&S, SEMCO, Ibiden, TTM Technologies, Zhen Ding Technology, Tripod Technology, Nan Ya PCB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced HDI PCB Market Trends and Innovations
Process innovation is compressing line-space geometries while regulatory pressure on etching chemistry redirects capital toward dry-patterning alternatives.
Laser-based microvia formation is expanding into high-volume smartphone substrate production as East Asian OEMs specify any-layer HDI for flagship models. Samsung and Apple procurement teams now mandate stacked microvia architectures that eliminate mechanical drilling entirely. This shift is expanding into automotive radar modules where signal integrity requirements favor laser-drilled blind vias.
The EU F-Gas Regulation is prohibiting fluorinated greenhouse gases in plasma etching chambers, forcing fabs to retrofit equipment or adopt laser ablation for dielectric removal. German and Austrian substrate houses face the steepest compliance deadlines under national implementations. High-frequency module producers are responding by qualifying laser-direct imaging for finer feature control.
Direct OEM contracting is displacing traditional distribution channels for premium smartphone substrate volumes. Procurement teams at flagship device makers now negotiate allocation agreements 12-18 months ahead of launch, locking capacity at named substrate houses. This pattern is most visible in Taiwan and South Korea where packaging houses sit adjacent to HDI fabrication facilities.
Advanced HDI PCB Market Segmentation
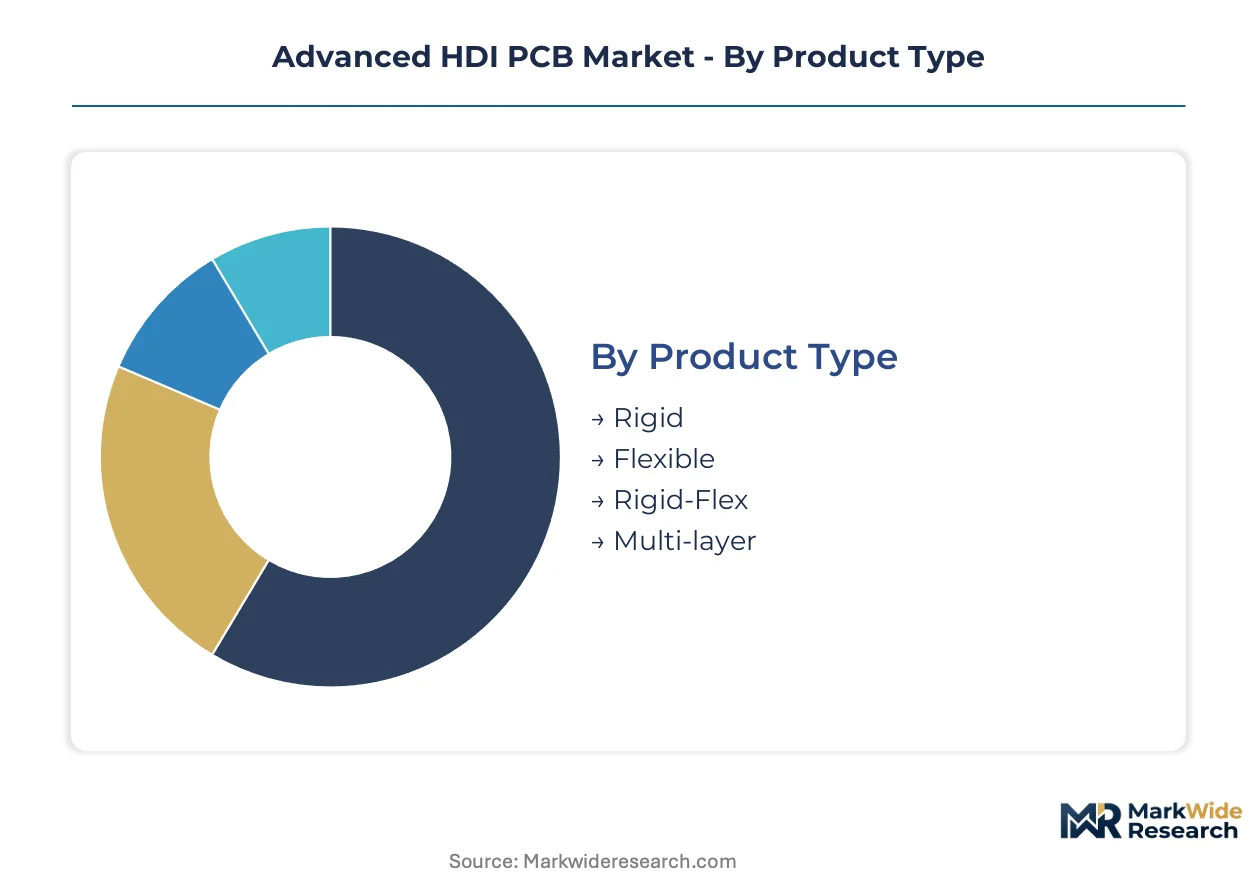
Advanced HDI PCB fabrication splits across four structural dimensions that determine pricing power, qualification timelines, and capital intensity. Each segmentation axis reveals distinct integration patterns between substrate houses and downstream electronics assembly.
Product Type:
Integration depth varies sharply across substrate form factors, with rigid boards serving standalone modules while flex and rigid-flex variants embed into larger mechanical assemblies.
- Multi-layer:Configurations stack ten or more conductive layers with sequential lamination cycles, enabling dense signal routing for smartphone AP substrates and baseband modules. Taiwan's Taoyuan-Airport corridor concentrates fabrication capacity as substrate makers cluster near semiconductor packaging houses to shorten qualification timelines for new designs.
- Rigid:Standard epoxy-glass constructions dominate high-volume consumer electronics where cost sensitivity limits layer counts to four to eight. East Asian smartphone OEMs in Taiwan and South Korea anchor procurement volumes through direct allocation agreements with named substrate houses.
- Flexible:Polyimide-based substrates conform to curved device geometries in wearables and foldable handsets.
- Rigid-Flex:Hybrid constructions bridge mechanical sections in automotive camera modules and medical imaging equipment.
Volume placements concentrate in Multi-layer; the faster expansion belongs to Rigid-Flex as automotive ADAS penetration deepens.
Application:
End-use sectors impose divergent reliability standards that filter the supplier base into automotive-qualified and consumer-grade tiers.
- Consumer Electronics:Smartphones, tablets, and wearables drive the dominant share of HDI substrate consumption, with flagship device launches pulling concentrated volume spikes. Apple and Samsung procurement teams negotiate directly with substrate houses, compressing traditional distribution layers and locking capacity twelve to eighteen months ahead of product launches.
- Automotive:Radar modules and camera systems for ADAS require embedded-die substrates with thermal cycling resilience that exceeds consumer-grade specifications. German and Austrian substrate houses face steep compliance deadlines under national implementations of the EU F-Gas Regulation, accelerating laser-based microvia adoption for dielectric removal.
- Telecommunications:5G baseband and mmWave antenna-in-package modules demand stacked microvia architectures.
- Medical Devices:Implantable and diagnostic equipment requires ISO 13485-qualified fabrication with extended traceability records.
Consumer Electronics commands the heaviest volume loading; Automotive is climbing the fastest as Tier-1s qualify new HDI suppliers for sensor substrates.
End User:
Customer type determines contract structure, with direct OEM engagement displacing traditional distribution for premium smartphone volumes.
- OEMs:Original equipment manufacturers in consumer electronics and automotive now mandate allocation agreements with named substrate houses rather than spot-market purchasing. This pattern is most visible in Taiwan and South Korea where packaging houses sit adjacent to HDI fabrication facilities, generating co-location efficiencies that compress qualification timelines.
- Contract Manufacturers:EMS providers aggregate demand across multiple OEM programs, retaining sourcing flexibility for mid-tier builds.
- ODMs:Original design manufacturers in East Asia integrate substrate specification into early-stage product development.
- Aftermarket Providers:Repair and refurbishment channels absorb excess inventory from primary production runs.
OEMs dominate value capture in flagship segments; ODMs are expanding their share fastest as design authority shifts toward integrated manufacturing partners.
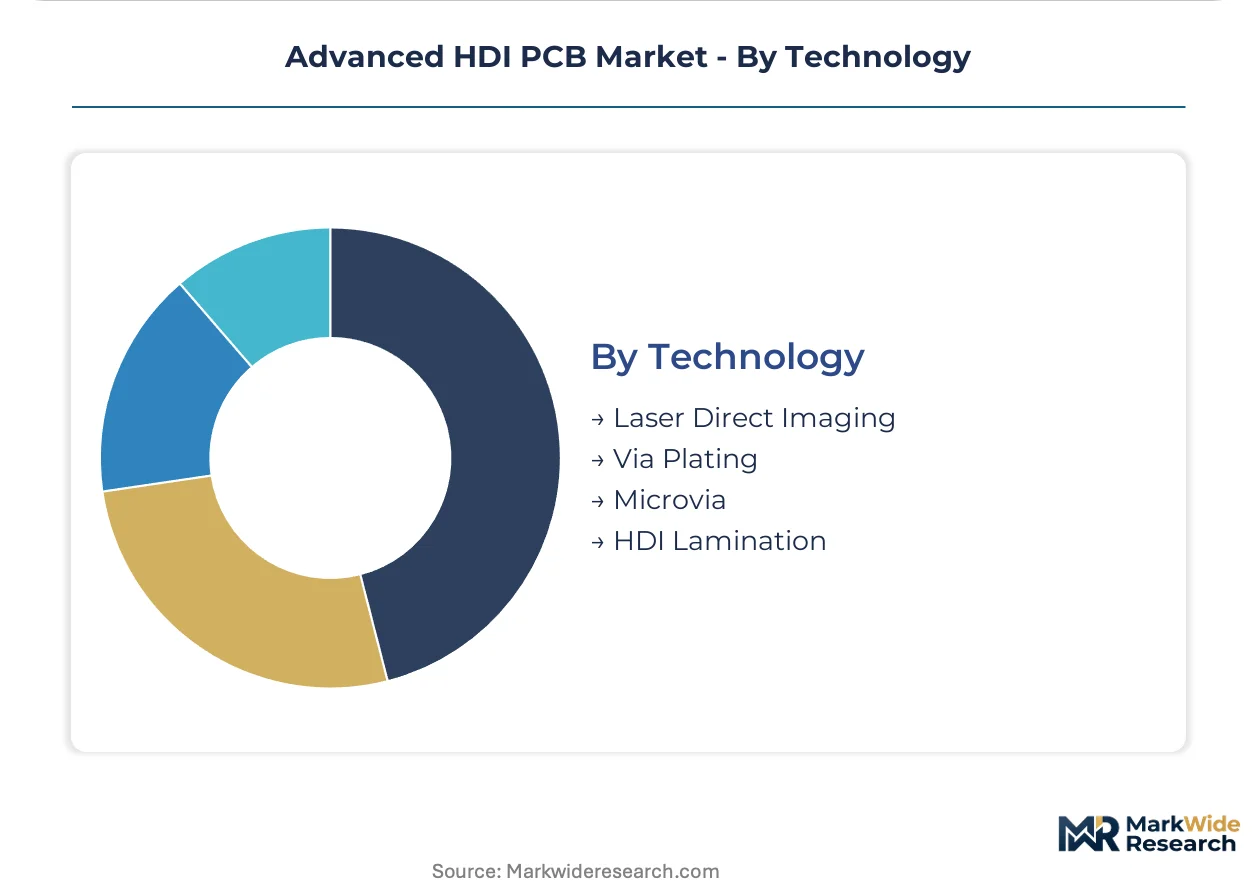
Technology:
Fabrication method selection tracks the regulatory trajectory on etching chemistry and the precision requirements of next-generation interconnects.
- Microvia:Stacked and staggered microvia architectures are replacing through-hole vias in 5G handset boards and automotive radar modules, pulling demand for sequential lamination capacity. Samsung and Apple procurement teams now mandate laser-drilled blind vias that eliminate mechanical drilling entirely, expanding laser-based microvia formation into high-volume smartphone substrate production.
- Laser Direct Imaging:Dry-patterning technology bypasses photomask bottlenecks for prototyping services and fine-feature production. High-frequency module producers are responding to EU F-Gas Regulation compliance deadlines by qualifying laser-direct imaging for finer feature control and reduced fluorinated gas dependence.
- Via Plating:Electroless copper deposition controls aspect ratios below 0.8:1 in high-density interconnects.
- HDI Lamination:Sequential press cycles build multi-layer structures with controlled impedance.
Microvia claims the deepest volume penetration; Laser Direct Imaging is gaining share fastest as European fabs retrofit equipment for F-Gas compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's Taoyuan-Airport corridor concentrates the densest cluster of advanced HDI fabrication, with substrate makers positioning facilities adjacent to semiconductor packaging houses to compress qualification timelines for new smartphone designs.
United States
5G infrastructure deployment and defense electronics sustain demand for high-frequency HDI substrates in the US. FCC equipment authorization rules govern electromagnetic emissions for wireless devices using these boards. The Pacific Northwest hosts prototyping facilities serving aerospace and satellite communication modules.
Germany
Automotive radar modules for ADAS sensors drive qualification of embedded-die substrates among German Tier-1 suppliers. National implementation of the EU F-Gas Regulation imposes steep compliance deadlines on plasma etching operations, accelerating laser-based microvia adoption. Bavarian substrate houses retrofit equipment to meet fluorinated gas restrictions.
China
Domestic smartphone OEMs expand orders for any-layer HDI boards as flagship device launches concentrate procurement volumes. MIIT standards shape supplier qualification criteria for consumer electronics supply chains. The Yangtze River Delta anchors multi-layer fabrication capacity serving regional packaging houses.
South Korea
Samsung procurement teams negotiate direct allocation agreements with named substrate houses twelve to eighteen months ahead of flagship launches. MFDS alignment with international medical device standards opens qualification pathways for diagnostic equipment substrates. The Seoul Capital Area clusters packaging facilities adjacent to HDI fabrication plants.
Japan
High-reliability substrates for automotive and industrial applications sustain premium-margin production in Japan. METI industrial policy supports domestic supply chain resilience for critical electronic materials. ABF laminate production concentrates under vertically integrated suppliers controlling resin system formulations.
Advanced HDI PCB Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and layer-count capability, with automotive-qualified fabricators commanding pricing power that consumer-grade specialists cannot match. The vendor base organizes into three strata: vertically integrated resin-to-substrate houses, sequential lamination specialists with captive copper foil operations, and regional fabricators dependent on merchant laminate supply. Two strategic moves dominate competitive positioning: backward integration into ABF laminate and copper foil production to manage input cost volatility, and co-location partnerships with semiconductor packaging houses to secure allocation agreements with flagship smartphone OEMs.
Among Taiwan-based fabricators, Unimicron and Zhen Ding Technology occupy positions within the vertically integrated tier, exemplifying the archetype of substrate houses controlling upstream laminate and foil supply. AT&S represents the European specialist model, anchoring high-reliability qualification pathways for automotive radar substrates. These three companies illustrate how geographic origin and corporate structure correlate with competitive positioning across premium and standard-margin segments.
| Leading Market Players |
|---|
| Unimicron |
| Compeq |
| AT&S |
| SEMCO |
| Ibiden |
| TTM Technologies |
| Zhen Ding Technology |
| Tripod Technology |
| Nan Ya PCB |
| Others |
Pricing and Supply Chain Analysis
Captive copper foil production anchors both supply security and margin control for advanced HDI fabricators, with in-house foil operations insulating sequential lamination specialists from resin-system cost spikes while concentrating pricing power among vertically integrated houses.
Pricing Analysis
Yield-based pricing anchors contract structures, with fabricators charging premiums tied to microvia plating success rates rather than raw material throughput. Pricing stratifies across automotive-qualified, smartphone-flagship, and consumer-economy tiers, with ISO 14001 certification and ABF laminate grade as primary differentiation drivers. Cost compression in mid-tier HDI builds is intensifying because ultra-thin copper foil purity requirements command premium input pricing. Smartphone OEM procurement teams show least price sensitivity for flagship allocations, while contract manufacturers aggregating mid-volume demand resist pass-through of resin cost volatility.
Supply Chain Analysis
Freight cost sensitivity is reshaping geographic sourcing patterns as substrate houses co-locate with semiconductor packaging facilities to minimize qualification timeline risk. Taiwan, Japan, and South Korea concentrate ABF laminate and high-purity copper foil supply, with fabricators drawing from Japanese resin system suppliers and Korean electrolytic copper refiners. Single-source vulnerability in halogenated flame retardant alternatives under REACH compliance timelines threatens laminate reformulation schedules. Distribution runs through direct OEM allocation agreements for premium smartphone volumes, compressing traditional EMS and distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The advanced HDI PCB sector is consolidating around a vertical-integration race, with control over ABF laminate formulations and captive copper foil operations emerging as the decisive lever for margin defense and capacity security.
For Market Incumbents: Anchor qualification timelines by securing co-location partnerships with semiconductor packaging houses in Taiwan's Taoyuan-Airport corridor, compressing design-to-production cycles for flagship smartphone allocations. Deepen backward integration into copper foil production to manage input cost volatility from Korean and Japanese metal suppliers. Defend against laser-based microvia equipment upgrade cycles by pre-qualifying dry-patterning capacity ahead of EU F-Gas Regulation compliance deadlines.
For New Entrants and Emerging Players: The premium-to-economy tier price gap in automotive radar modules offers accessible entry points for embedded-die substrate specialists lacking smartphone OEM relationships. Target German and Austrian Tier-1 supplier qualification pathways where ISO 14001 certification timelines extend 18-24 months, creating defensive moats against fast-follower competition. Pursue prototyping services using laser direct imaging to bypass photomask bottlenecks and capture design-win relationships before volume commitments crystallize.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated resin-to-substrate houses seeking geographic diversification or automotive qualification expansion. Five-to-ten year viability favors fabricators with captive laminate supply and established allocation agreements with Apple or Samsung procurement teams. Monitor EU F-Gas Regulation enforcement intensity as an inflection signal for equipment retrofit capex cycles and distressed asset availability among non-compliant European substrate houses.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Foil | Unimicron's captive foil operations insulate sequential lamination margins from Korean metal supplier pricing volatility. |
| Laser Equipment Retrofit for F-Gas Compliance | German and Austrian fabs accelerate laser-based microvia adoption to meet national fluorinated gas restriction deadlines. |
| Co-location with Semiconductor Packaging | Taiwan's Taoyuan-Airport corridor clustering shortens smartphone substrate qualification timelines by eliminating logistics buffers. |
| Automotive Radar Module Qualification | AT&S anchors European embedded-die substrate supply for ADAS sensor Tier-1s seeking thermal cycling resilience. |
| ABF Laminate Formulation Control | Ibiden's vertical control over resin systems secures Japanese supply of high-reliability substrates for automotive and industrial applications. |
Research Methodology
Independent corroboration across substrate house procurement executives, semiconductor packaging operations managers, and laser equipment suppliers underwrites the qualitative findings in this study. Primary interviews with OEM material sourcing directors, EMS category managers, and ABF laminate technical sales leads combined with secondary validation from MIIT standards filings, METI industrial policy documents, and EU F-Gas Regulation implementation schedules. Bottom-up triangulation across fabrication capacity announcements and top-down reconciliation with smartphone shipment forecasts anchored volume estimates.
Rate-of-change decomposition across the projection horizon separates volume growth from value-per-unit expansion in multi-layer versus rigid-flex configurations. Segmentation modeling incorporated product type, application sector, end-user channel, and fabrication technology dimensions. CAGRs derived from iterative convergence between supplier capacity expansion timelines and OEM allocation agreement patterns, with sequential lamination cycle counts and microvia aspect ratio requirements as industry-specific forecast inputs.
Underlying measurement precision varies by segment; automotive-qualified substrate forecasts carry tighter precision than consumer-economy tiers due to visible Tier-1 qualification pipelines. Forecasts reflect assumptions about EU F-Gas Regulation enforcement consistency and REACH halogenated flame retardant substitution timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
VCSEL Market
Semiconductor Devices
Middle East and Africa Silicon Carbide Wafers Market
Semiconductor Devices
Europe Printed Circuit Board (PCB) Market
Semiconductor Devices
DNA Chip Market
Semiconductor Devices
Silicon on Insulator Market
Semiconductor Devices
Semiconductor Memory IP Market
Semiconductor Devices
Non-Volatile Dual in-Line Memory Module Market
Semiconductor Devices
Field Programmable Gate Array (FPGA) Market
Semiconductor Devices
CMP Pads Market
Semiconductor Devices
Silicon-Based Anode Market
Semiconductor Devices
Global Diodes Market
Semiconductor Devices
Finfet Technology Market
Semiconductor Devices
Voltage Controlled Oscillators Market
Semiconductor Devices
Europe Silicon Carbide Wafers Market
Semiconductor Devices
Global Substrate-Like PCB Market
Semiconductor Devices
N-Topcon Solar Cells Market