
 Europe Room Cell Module Market | 2026-2036
Europe Room Cell Module Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Room Cell Module Market Intelligence
Healthcare procurement teams are unwinding traditional construction contracts in favor of rapid-deployment room cell modules for hospital expansions and temporary clinical capacity. Wernick Group leverages its British manufacturing footprint to serve NHS retrofit programs. Max Bögl Bauservice GmbH & Co.KG anchors German-speaking markets with precision-engineered concrete-core modules. Laing O'Rourke competes on design-build integration, controlling project timelines from factory to site.
Room cell modules are prefabricated volumetric units manufactured with steel or concrete frames, insulation cores, and pre-installed MEP services, designed for rapid on-site assembly and immediate occupancy. Wall assemblies typically achieve fire ratings and acoustic dampening specified under EN standards, with module weights ranging from lightweight timber-composite to heavy reinforced concrete depending on application height and seismic requirements. Smart Modules lead product type revenue due to embedded sensor infrastructure commanding premium pricing, while Thermal Modules capture fastest growth as envelope efficiency regulations tighten across EU member states. Healthcare Facilities dominate application demand through accelerated clinic construction timelines, whereas Educational Institutions represent a maturing segment with standardized repeat specifications.
The EU Green Deal and Energy Performance of Buildings Directive (EPBD) shape product standards by mandating operational carbon thresholds and embodied carbon disclosure, forcing manufacturers to certify module lifecycle data under harmonized EN 15804 rules. ECHA REACH compliance restricts certain insulation chemistries, redirecting R&D toward bio-based and mineral wool alternatives. Stakeholders must monitor how the EU AI Act and emerging smart building cybersecurity frameworks will redefine connectivity requirements for IoT-integrated modules before specification cycles harden.
Market Dynamics
Healthcare construction timelines across Europe are compressing from years to months, forcing hospital procurement teams to abandon stick-built methods for factory-delivered volumetric units with pre-certified MEP and fire ratings. This structural acceleration is reordering contractor relationships and capital allocation patterns continent-wide.
Growth Catalysts
- EPBD Energy Thresholds:The Energy Performance of Buildings Directive mandates near-zero operational carbon for new healthcare facilities, pushing specifiers toward thermal-optimized modules with certified envelope performance.
- Hospital Capacity Expansion:NHS England and regional German health authorities are procuring rapid-deployment clinical modules to address elective surgery backlogs and pandemic-resilient surge capacity.
- Timber-Composite Engineering:Cross-laminated timber and engineered wood products are achieving structural spans and fire ratings previously reserved for steel frames, reducing module weight and transport costs.
Market Restraints
- Steel Input Volatility:Structural steel and rebar pricing fluctuations compress margins for manufacturers locked into fixed-price public contracts with 12-18 month delivery windows.
- Eastern European Supply Concentration:Insulation and mineral wool production clusters in Poland and Czechia create vulnerability to regional energy price shocks and logistics bottlenecks.
- Seismic Zoning Limitations:Reinforced concrete-core modules remain mandatory in Italian and Romanian high-seismic zones, blocking lightweight timber alternatives from cost-sensitive projects.
Strategic Opportunities
- Nordic Healthcare Modernization:Sweden and Finland are retiring 1960s-1970s hospital stock, creating sustained demand for replacement clinical modules with integrated digital infrastructure.
- EU AI Act Compliance:Smart modules with embedded IoT sensor networks can capture premium positioning by certifying cybersecurity and data governance standards before competitor specification cycles harden.
- Direct-to-Developer Distribution:Bypassing traditional general contractors, manufacturers are establishing direct relationships with healthcare real estate developers and institutional investors for repeat-build portfolios.
Industry Challenges
- Digital Fabrication Talent Scarcity:BIM-to-factory workflow integration requires skilled technicians proficient in both architectural modeling and CNC production equipment, with European vocational pipelines insufficient to demand.
- Multi-Jurisdiction Certification Lag:Modules manufactured in Britain for continental EU sites face duplicated fire testing and structural approval processes despite harmonized EN standards, extending project timelines.
- Legacy MEP Integration Complexity:Connecting factory-built modules to existing hospital central plant infrastructure—steam, medical gas, emergency power—demands specialized commissioning expertise that generalist contractors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Room Cell Module Market |
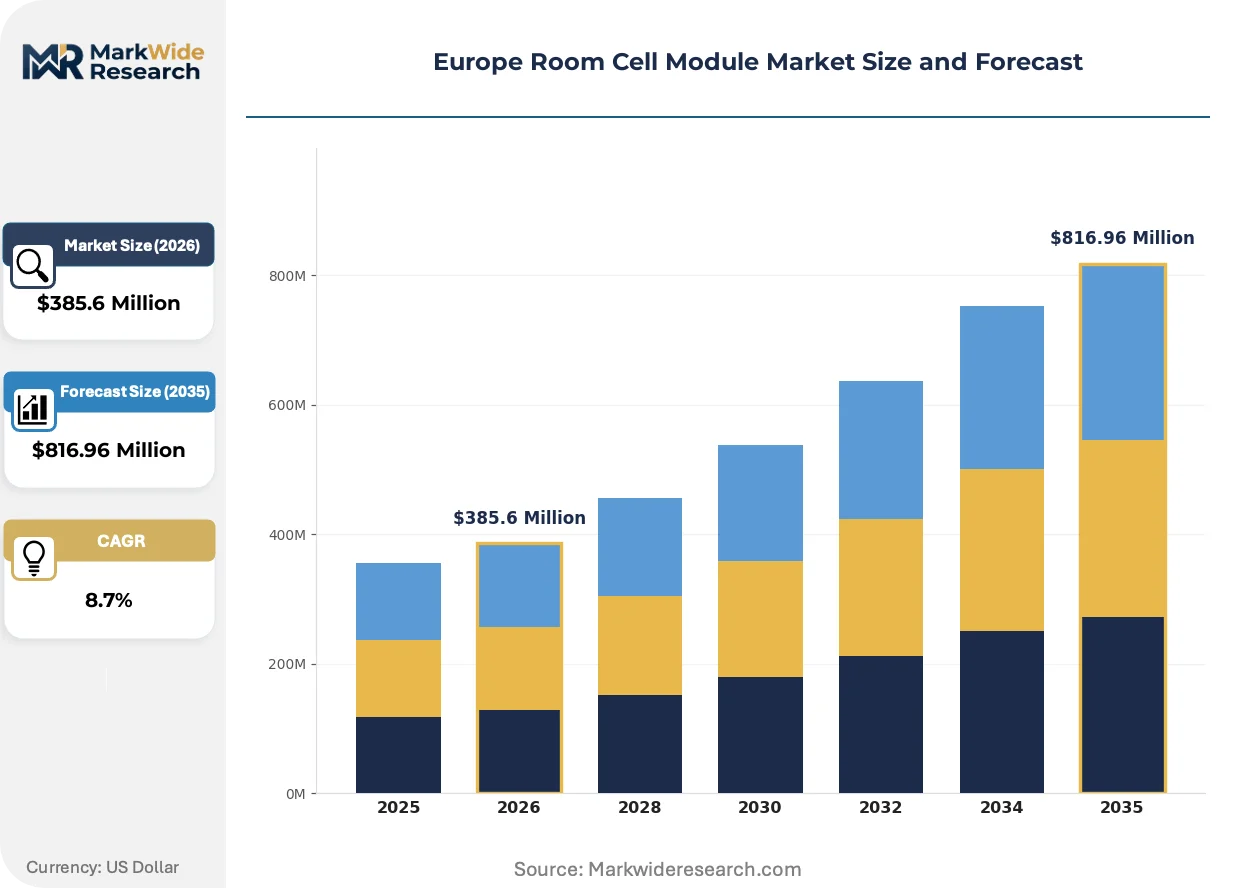
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Modules, Thermal Modules, Acoustic Modules, Energy Modules Application: Healthcare Facilities, Office Spaces, Educational Institutions, Hospitality Technology: IoT Integration, Wireless Connectivity, Energy Management, HVAC Systems End User: Commercial Buildings, Residential Homes, Industrial Facilities, Public Infrastructure |
| Companies Covered | Wernick Group, Lechner Group GmbH, Max Bögl Bauservice GmbH & Co.KG, Kaufmann Bausysteme GmbH, Ausco Modular, Kleusberg GmbH & Co. KG, Laing O'Rourke, Skanska AB, Modulaire Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Room Cell Module Market Strategic Shifts & Innovations
Prefabrication technology is converging with building digitization to compress project delivery timelines while embedding operational intelligence directly into structural components. This fusion is redefining how European healthcare and education clients evaluate total cost of ownership.
Mineral wool and bio-based insulation formulations are supplanting legacy polyurethane and XPS cores in module wall assemblies. German and Dutch hospital developers are specifying these alternatives to satisfy ECHA REACH restrictions on certain flame retardants and volatile organic compounds. The shift is compressing R&D cycles for insulation suppliers while opening specification pathways previously blocked by chemical compliance concerns.
The EU Green Deal's embodied carbon disclosure requirements under harmonized EN 15804 rules are forcing manufacturers to document cradle-to-gate environmental product declarations. French and Belgian healthcare procurement frameworks are weighting these disclosures in tender scoring, advantaging producers with verified supply chain data. Module producers without lifecycle transparency are losing access to public sector frameworks in these markets.
Hospital capital planning departments are consolidating vendor relationships around design-build-operate partnerships rather than discrete construction contracts. British NHS trusts and French regional health agencies are piloting long-term service agreements where module suppliers retain responsibility for MEP maintenance and technology refresh cycles. This restructuring concentrates procurement authority among fewer, more vertically capable manufacturers.
Europe Room Cell Module Market Segmentation
Module specification patterns across Europe diverge sharply by end-use performance requirements and regulatory exposure. Procurement teams weight thermal efficiency, digital infrastructure, and acoustic isolation differently depending on whether they serve NHS hospital retrofits or Nordic educational developments.
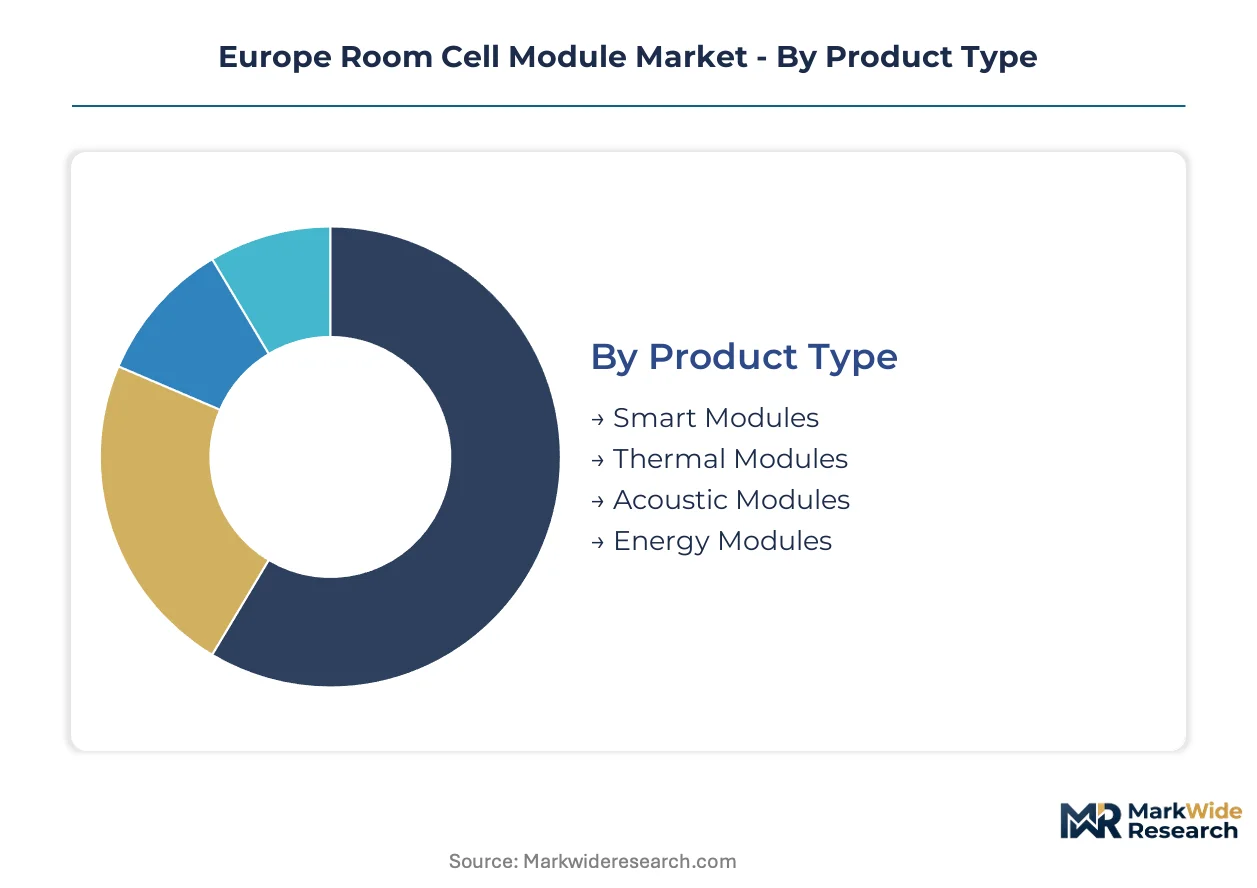
Product Type:
Margin pools concentrate in premium-positioned modules carrying embedded sensor infrastructure and certified lifecycle data under EN 15804 rules.
- Smart Modules:Steel or concrete-framed volumetric units with pre-installed IoT sensor networks, integrated building management interfaces, and cybersecurity-hardened connectivity. NHS England and French regional health agencies specify these for surgical suites and patient monitoring zones where real-time environmental control commands premium positioning. The dominant share belongs to Smart Modules, while Thermal Modules is closing the gap fastest.
- Thermal Modules:High-performance envelope assemblies with mineral wool or bio-based insulation cores engineered for near-zero operational carbon under EPBD thresholds. German and Dutch hospital developers procure these for energy retrofit programs where envelope efficiency determines tender scoring.
- Acoustic Modules:Multi-layer wall systems achieving EN-rated sound dampening for clinical confidentiality and open-plan office concentration.
- Energy Modules:Integrated photovoltaic and battery storage configurations for grid-independent deployment in remote healthcare outposts.
Smart Modules command the highest unit economics, though Thermal Modules is expanding most quickly as EU Green Deal compliance hardens.
Application:
Volume concentrates in sectors where construction timeline compression justifies factory delivery premiums over stick-built alternatives.
- Healthcare Facilities:Rapid-deployment clinical units for hospital expansions, elective surgery backlogs, and pandemic-resilient surge capacity. NHS trusts and German health authorities unwind traditional construction contracts for factory-delivered modules with pre-certified MEP and fire ratings.
- Educational Institutions:Standardized classroom and laboratory specifications with repeat-build portfolios across municipal procurement frameworks. Sweden and Finland deploy these for 1960s-1970s school stock replacement with shorter procurement cycles than healthcare.
- Office Spaces:Flexible workspace modules for corporate campus reconfigurations and hybrid work infrastructure.
- Hospitality:Guest room and back-of-house units for hotel development timelines compressed by seasonal revenue windows.
Healthcare Facilities absorb the dominant procurement volume, while Educational Institutions offers the most predictable repeat-build economics.
Technology:
Specification differentiation increasingly hinges on connectivity certification ahead of EU AI Act implementation.
- IoT Integration:Embedded sensor networks for occupancy detection, air quality monitoring, and predictive maintenance with factory-calibrated commissioning.
- Wireless Connectivity:Mesh network and 5G-ready infrastructure for module-to-module communication without hardwired data cabling.
- Energy Management:Sub-metering and load-balancing systems integrated at factory stage to streamline site commissioning with hospital central plants.
- HVAC Systems:Pre-piped and pre-wired climate control units sized for rapid connection to existing building infrastructure.
IoT Integration carries the steepest premium trajectory as cybersecurity frameworks reshape procurement scoring.
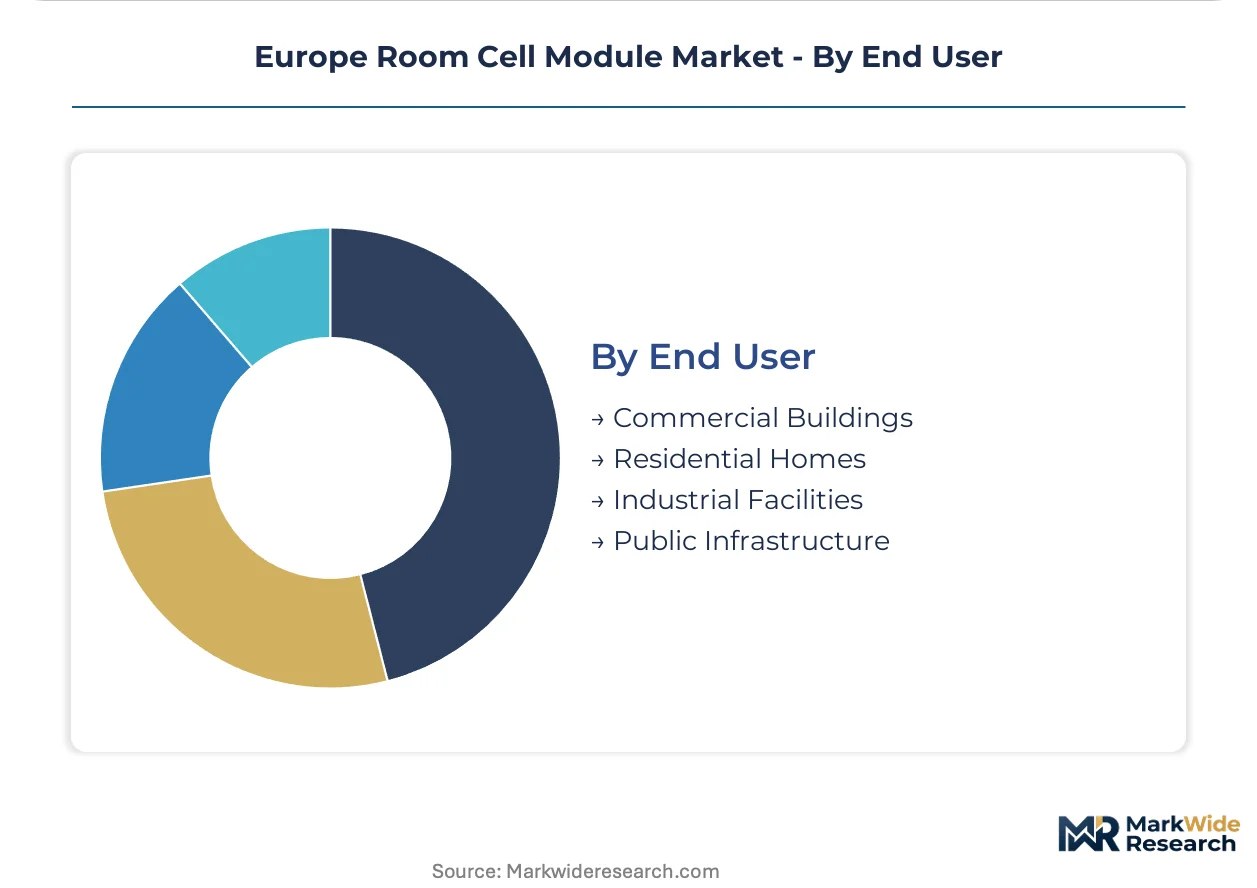
End User:
Customer sophistication varies by asset ownership structure and maintenance capability.
- Commercial Buildings:Corporate real estate developers and institutional investors specifying design-build-operate partnerships with long-term service agreements.
- Public Infrastructure:Municipal and regional government procurement with tender frameworks weighting EN 15804 lifecycle disclosures.
- Industrial Facilities:Manufacturing and logistics campuses requiring rapid cleanroom or control room deployment.
- Residential Homes:Single-family and multi-family volumetric construction with lighter MEP integration than institutional applications.
Commercial Buildings lead contract value per project, while Public Infrastructure offers the deepest pipeline visibility through framework agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision-engineered concrete-core modules across the Nordic corridor and into NHS procurement frameworks, establishing a dominant trade-flow corridor from Central Europe to Northern and Western European healthcare systems.
Germany
Hospital capacity expansion and energy retrofit programs drive procurement of thermal-optimized modules. The Energy Performance of Buildings Directive mandates near-zero operational carbon for new clinical facilities. Bavarian engineering clusters around Munich and Nuremberg concentrate production of steel-framed volumetric units with certified MEP integration.
United Kingdom
NHS trusts unwind traditional construction contracts for rapid-deployment clinical modules addressing elective surgery backlogs. NHS England procurement frameworks weight factory delivery speed and pre-certified fire ratings. British manufacturing footprints in the Midlands serve national retrofit programs with reduced cross-border certification friction.
France
Regional health agencies pilot design-build-operate partnerships with long-term service agreements replacing discrete construction contracts. The EU Green Deal's embodied carbon disclosure requirements under EN 15804 rules shape tender scoring. Healthcare procurement concentrates in Île-de-France and Auvergne-Rhône-Alpes, where 1960s-1970s hospital stock requires replacement.
Sweden
Nordic healthcare modernization creates sustained demand for replacement clinical modules with integrated digital infrastructure. EPBD energy thresholds accelerate specification of high-performance envelope assemblies. Stockholm and Gothenburg clusters lead timber-composite engineering for lightweight structural spans.
Netherlands
Dutch hospital developers procure thermal modules for energy retrofit programs where envelope efficiency determines tender outcomes. ECHA REACH restrictions redirect specification toward bio-based insulation alternatives. The Randstad corridor anchors mineral wool and engineered wood product supply chains serving Benelux healthcare construction.
Europe Room Cell Module Market Key Industry Players
Player mix skews toward vertically integrated engineering-to-delivery specialists with captive manufacturing footprints and design-build capabilities. The competitive structure tiers across precision-engineered concrete-core fabricators, rapid-deployment timber-composite specialists, and full-service design-build operators controlling project timelines from factory to site. Dominant moves include direct-to-developer distribution bypassing traditional general contractors, and strategic partnerships with healthcare real estate developers for repeat-build portfolios.
Among British fabricators, Wernick Group anchors the rapid-deployment segment for NHS frameworks, while Laing O'Rourke occupies a position exemplifying design-build integration. German engineering specialists Max Bögl Bauservice GmbH & Co.KG and Lechner Group GmbH represent the precision-manufacturing tier serving German-speaking markets with concrete-core modules. These three entities collectively illustrate the geographic and capability stratification defining competitive positioning across Northern and Western Europe.
| Leading Market Players |
|---|
| Wernick Group |
| Lechner Group GmbH |
| Max Bögl Bauservice GmbH & Co.KG |
| Kaufmann Bausysteme GmbH |
| Ausco Modular |
| Kleusberg GmbH & Co. KG |
| Laing O'Rourke |
| Skanska AB |
| Modulaire Group |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between NHS procurement frameworks and British manufacturers lock in 12-18 month delivery windows with fixed steel-input pricing, granting supply visibility while exposing producers to margin compression when rebar costs spike. This contract structure concentrates procurement authority among fabricators with captive Midlands production footprints who can absorb input volatility without tender disqualification.
Pricing Analysis
Next-generation smart modules with embedded IoT infrastructure command substantial premiums over standard steel-framed units, while legacy concrete-core products face price erosion from timber-composite alternatives. Project-based pricing dominates, with differentiation driven by EN 15804 certification tier and factory-integrated MEP complexity. Cost compression in standard thermal modules intensifies as Eastern European insulation suppliers compete on volume. Healthcare procurement teams show lowest price sensitivity for surge-capacity clinical units, while educational repeat-build portfolios squeeze margins through framework aggregation.
Supply Chain Analysis
Inventory buffers for structural steel and mineral wool have compressed to 6-8 weeks across German and British fabrication clusters, exposing producers to rebar price spikes and Polish energy-cost volatility. Supply concentrates in Germany, the United Kingdom, and the Czech Republic, with engineered timber feeds from Swedish and Finnish forestry operations. Production rests on cross-laminated timber, galvanized steel coil, and bio-based insulation formulations. Single-source vulnerability clusters around Czech mineral wool production threatened by regional gas-price shocks. Distribution runs through direct-to-developer channels bypassing traditional general contractors for NHS and German health authority frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare construction cyclicality is recovering from pandemic-delayed capital programs, with NHS England's elective surgery backlog clearance and Nordic hospital replacement cycles providing sustained demand visibility through the mid-2020s.
For Market Incumbents: Compound design-build-operate capabilities to capture recurring MEP maintenance revenue streams from NHS trusts piloting long-term service agreements. Backward integration into mineral wool and bio-based insulation production insulates margin positions from ECHA REACH compliance disruptions. Acquire timber-composite engineering talent in Stockholm and Gothenburg clusters before specification cycles harden against lightweight alternatives.
For New Entrants and Emerging Players: Differentiate on EU AI Act pre-certification for cybersecurity-hardened IoT modules before incumbent specification cycles close. Target French regional health agencies transitioning from discrete construction contracts to design-build partnerships, where procurement frameworks remain less consolidated than NHS England. Penetrate through direct relationships with healthcare real estate developers building repeat-build surgical clinic portfolios.
For Investors and Strategic Acquirers: Precision-engineered concrete-core fabricators with German health authority framework access represent the most defensible acquisition archetype given seismic-zoning limitations blocking timber alternatives in Southern Europe. Monitor EN 15804 lifecycle disclosure compliance rates as an inflection signal—producers without verified supply chain data are losing French and Belgian public tender access, creating distressed entry opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Design-Build-Operate Partnership | NHS trusts and French health agencies consolidate procurement authority around vendors retaining long-term MEP maintenance responsibility. |
| Timber-Composite Engineering Investment | Swedish and Finnish clusters achieve structural spans and fire ratings that displace steel frames in non-seismic Northern European zones. |
| EU AI Act Pre-Certification | Smart module producers capturing cybersecurity-hardened connectivity standards command premium positioning before competitor specification cycles harden. |
| Direct-to-Developer Distribution | Bypassing general contractors concentrates repeat-build revenue with healthcare real estate developers and institutional investors. |
| Backward Integration into Bio-Based Insulation | ECHA REACH restrictions on legacy flame retardants redirect R&D toward mineral wool alternatives with certified cradle-to-gate transparency. |
Research Approach
Desk research of EU procurement framework databases, EN standard certification registries, and hospital capital planning disclosures preceded structured interviews with NHS procurement directors, German health authority facility planners, timber-composite engineering specialists, and mineral wool supply chain managers. Secondary validation drew from ECHA REACH substance restriction updates, EPBD implementation guidance documents, and healthcare construction trade association reports. Bottom-up module shipment estimates triangulated against top-down healthcare construction spend allocations across the analysis window.
Variance decomposition across product type, application, technology, and national regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level shipment trajectories weighted by EN 15804 certification penetration and timber-composite engineering adoption curves. Modeled inputs included NHS capital program pipeline visibility, Nordic hospital replacement schedules, and EPBD energy threshold implementation timelines.
Material uncertainties—steel input volatility, ECHA substance restriction expansions, and EU AI Act cybersecurity framework finalization—sit outside the modeled envelope. Forecasts reflect assumptions about healthcare construction timeline compression and factory-delivery preference persistence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Switched Capacitor Filter Market
Semiconductor Devices
Gaming GPU Market
Semiconductor Devices
Epi Wafer Market
Semiconductor Devices
Dual Voltage Comparator Market
Semiconductor Devices
China MCU Market
Semiconductor Devices
Schottky Rectifiers Market
Semiconductor Devices
APAC Semiconductor Device for Processing Applications Market
Semiconductor Devices
Ferroelectric FET Market
Semiconductor Devices
Power Transistor Market
Semiconductor Devices
Asia Pacific Motherboard Market
Semiconductor Devices
APAC Semiconductor Device in Aerospace and Defense Market
Semiconductor Devices
Global 8 - Bit Microcontroller Market
Semiconductor Devices
Graphene Electronics Market
Semiconductor Devices
Americas Semiconductor Device Market
Semiconductor Devices
Plastic Transistors Market
Semiconductor Devices
Superconductor Wire Market