
 Nanowires Market | 2026-2036
Nanowires Market Size, Share, and Industry Trends Forecast 2026-2036
Nanowires Market Outlook
Consumer electronics is pivoting toward energy-dense nanowire architectures in portable power systems. Amprius Technologies leverages silicon nanowire anode designs to sustain technology leadership in aviation and defense battery contracts. BASF SE anchors European supply through its specialty chemicals R&D infrastructure for nanomaterial precursors. Sila Nanotechnologies competes with composite silicon-based formulations that occupy the premium tier of EV battery partnerships.
Nanowires are filamentary structures with diameters below 100 nanometers and aspect ratios exceeding 1000:1, typically synthesized through chemical vapor deposition or template-assisted electrodeposition to achieve controlled crystallinity and surface functionalization. Semiconducting nanowires dominate volume production for transistor and sensor applications where bandgap tunability determines device performance. Metallic variants in energy storage applications represent the fastest-expanding margin pool as automotive OEMs qualify silicon nanowire anodes for production platforms. Template synthesis retains cost advantages for research-scale output, while laser ablation serves specialized photonics applications with demanding purity thresholds.
The US EPA governs nanomaterial discharge under TSCA Section 5 premanufacture notification rules, compelling domestic producers to submit comprehensive toxicity data before commercial scale-up. REACH registration requirements in Europe mandate full substance characterization for metallic and semiconducting nanowire imports above one tonne annually. China's SAMR enforces GB standards for nanomaterial labeling and workplace exposure limits that filter smaller producers from export eligibility. Stakeholders must monitor evolving classification thresholds under OECD nanomaterial testing guidelines that harmonize safety protocols across jurisdictions.
Market Dynamics
Automotive OEMs are driving qualification timelines for silicon nanowire anodes from laboratory validation toward production-scale integration, compressing development cycles and forcing upstream material suppliers to synchronize capacity expansion with platform launch schedules.
Growth Catalysts
- China's dual carbon goals:National emissions targets mandate battery energy density improvements that silicon nanowire architectures deliver, accelerating domestic anode material procurement.
- Aviation electrification:Defense contractors and commercial drone operators specify nanowire-enhanced cells for mission-critical power systems requiring extreme gravimetric energy density.
- Template-assisted electrodeposition:This synthesis method achieves crystallinity control at research-scale throughput, lowering barriers for specialized photonics and sensor applications.
Market Restraints
- Precursor chemical volatility:Organosilane feedstock prices fluctuate with semiconductor foundry demand, squeezing anode material margins unpredictably.
- South Korean supply concentration:Samsung SDI and LG Energy Solution suppliers anchor electrode manufacturing in Gyeonggi-do and Ochang, creating single-geography vulnerability.
- GB standard compliance costs:China's SAMR labeling and workplace exposure requirements filter smaller producers from export eligibility, raising effective market entry thresholds.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for advanced cell chemistry manufacturing attract nanowire anode technology transfer from established East Asian suppliers.
- Composite silicon formulations:Hybrid architectures blending nanowire and particulate silicon occupy the premium tier of EV battery partnerships where pure nanowire costs remain prohibitive.
- OECD harmonization:Converging testing guidelines across jurisdictions reduce redundant safety data generation, streamlining multi-market registration for metallic and semiconducting variants.
Industry Challenges
- Electrolyte formulation expertise:Silicon nanowire anodes require proprietary electrolyte additives that stabilize solid-electrolyte interphase formation, and talent pools for this specialty remain shallow.
- TSCA Section 5 timelines:EPA premanufacture notification reviews extend commercialization schedules for novel nanomaterial compositions, compressing revenue realization windows.
- Legacy electrode coating infrastructure:Existing roll-to-roll systems designed for graphite slurries demand retooling for nanowire dispersion and binder adhesion protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanowires Market |
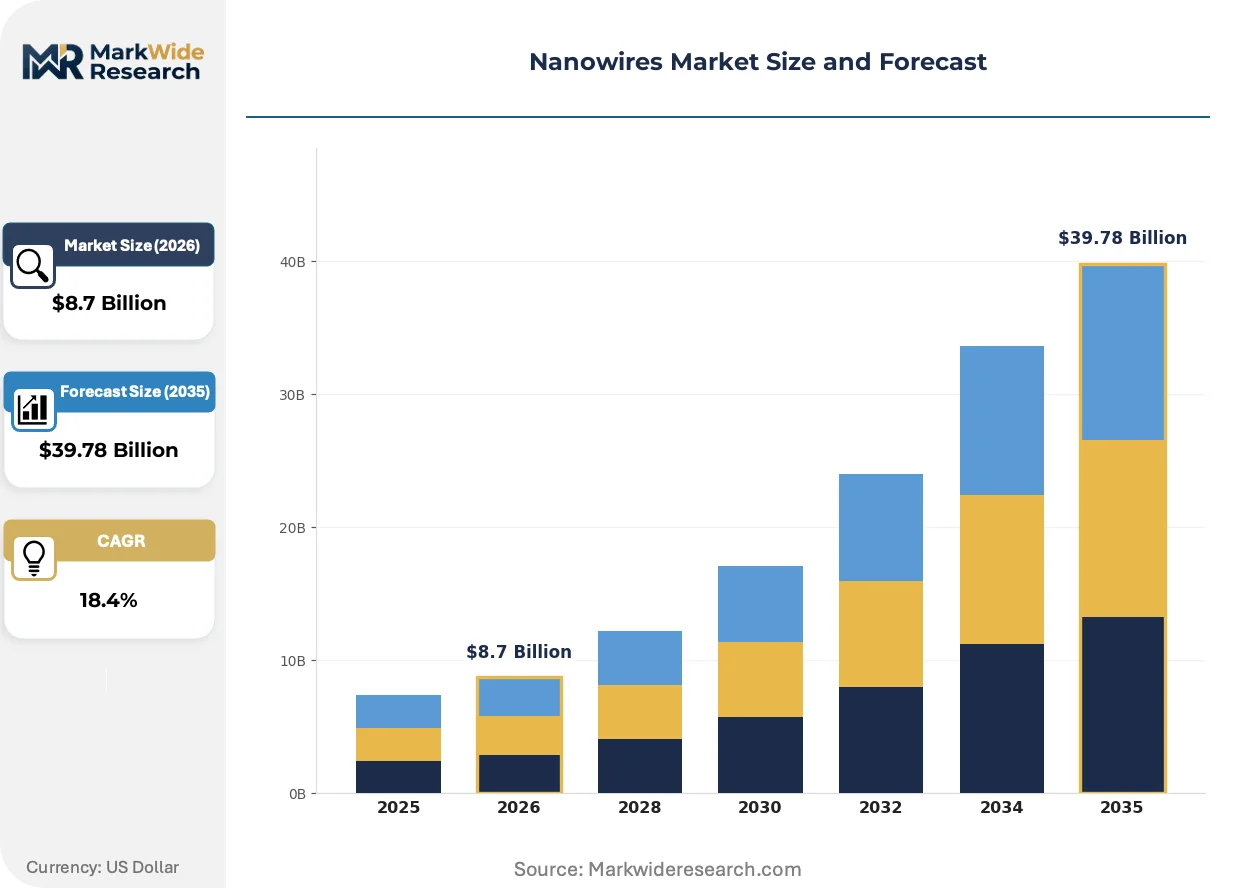
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic, Semiconducting, Insulating, Composite Application: Electronics, Energy Storage, Sensors, Photovoltaics End User: Consumer Electronics, Automotive Sector, Telecommunications, Healthcare Manufacturing Process: CVD, Electrodeposition, Template Synthesis, Laser Ablation |
| Companies Covered | ACS Materials, NanoComposix Inc., Amprius Technologies, C3 Nano, BASF SE, Sila Nanotechnologies, Novarials Corporation, Blue Nano Inc., Cambrios Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanowires Market Strategic Shifts
Synthesis methods and regulatory frameworks are converging to reshape how nanowire materials transition from laboratory output to qualified industrial supply. Three developments dominate this transition.
Silicon nanowire anodes are integrating into next-generation lithium-ion cell designs through chemical vapor deposition processes that achieve controlled surface functionalization. Automotive battery engineering teams at Korean and Chinese OEMs are accelerating validation protocols for these architectures. The structural consequence is compressing qualification timelines from five-year horizons toward eighteen-month platform integration cycles.
REACH registration requirements in Europe mandate full substance characterization for metallic and semiconducting nanowire imports above one tonne annually. ECHA's evolving guidance on nanomaterial-specific hazard assessment is forcing importers to generate chronic toxicity datasets earlier in commercial planning. Specialty chemical distributors serving German and French battery material markets are restructuring supplier qualification to front-load registration documentation.
Aviation and defense procurement officers are consolidating supplier relationships around vertically integrated nanowire anode producers capable of spanning precursor synthesis through cell assembly. This concentration displaces multi-tier sourcing models that separated material science from battery engineering. The shift is most visible in US Department of Energy advanced battery manufacturing grants and Israeli defense contractor supply agreements.
Nanowires Market Segmentation
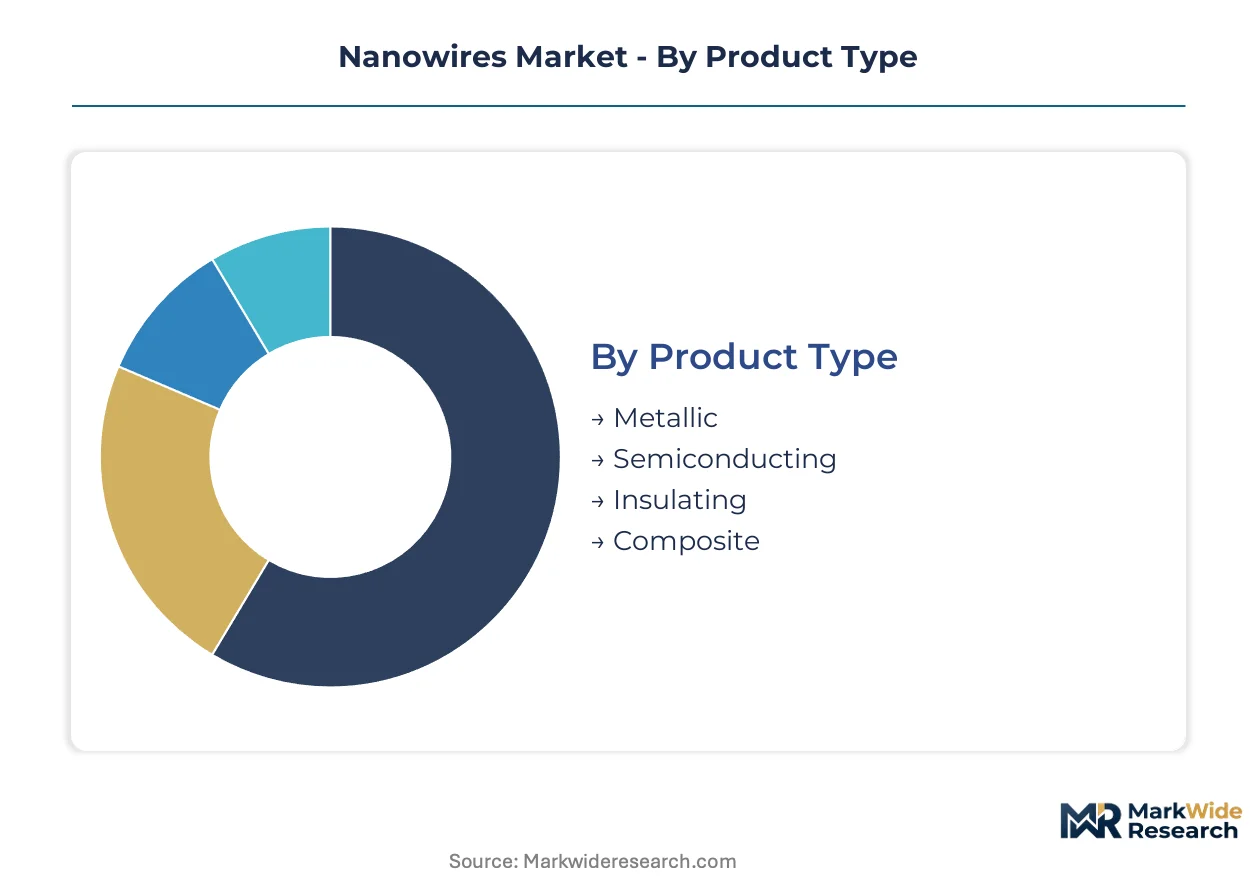
Nanowire architectures vary dramatically in conductivity, mechanical properties, and synthesis economics. Buyers select segments based on whether they prioritize electrical performance, energy density, or scalable manufacturing throughput.
Product Type:
Cost tiers separate commodity metallic feedstock from precision-engineered semiconducting variants demanding foundry-grade purity.
- Metallic:Gold, silver, and copper nanowires achieve high electrical conductivity for transparent electrode applications. Demand concentrates in South Korean display manufacturing clusters where Samsung SDI suppliers qualify silver nanowire formulations for foldable screen architectures.
- Semiconducting:Silicon and gallium arsenide nanowires enable bandgap engineering for transistor and photonic devices. Chinese foundries in Hsinchu and Shanghai are expanding procurement of silicon nanowire precursors to support 3nm node development timelines.
- Insulating:Ceramic oxide nanowires provide thermal barrier and dielectric functions in high-temperature sensors.
- Composite:Hybrid metal-semiconductor architectures merge conductive cores with functionalized shells for multi-property devices.
Volume sits with metallic nanowires for transparent conductors; growth tilts toward semiconducting variants for advanced node logic.
Application:
Application selection tracks directly to battery chemistry roadmaps and semiconductor device scaling requirements.
- Electronics:Nanowire field-effect transistors and interconnects address short-channel effects in sub-10nm nodes. TSMC and Intel process engineering teams are integrating germanium nanowire channels into gate-all-around transistor architectures.
- Energy Storage:Silicon nanowire anodes deliver gravimetric energy density improvements for lithium-ion cells. LG Energy Solution and CATL procurement specifications now include nanowire-enhanced anode materials for premium EV battery platforms.
- Sensors:High surface-to-volume ratios enable ppb-level chemical detection in industrial monitoring.
- Photovoltaics:Radial p-n junction architectures in nanowire arrays reduce material consumption for III-V solar cells.
Electronics commands current procurement volumes; energy storage applications are climbing the fastest as automotive qualification cycles compress.
End User:
Customer maturity determines whether buyers accept prototype-grade material variability or demand six-sigma process control.
- Consumer Electronics:Smartphone and laptop manufacturers prioritize cost-optimized silver nanowire transparent conductors for touch sensors. Apple's supply chain specifications for foldable devices are driving yield improvement requirements for flexible electrode formulations.
- Automotive Sector:OEM battery engineering teams enforce rigorous silicon nanowire anode qualification protocols spanning cell cycling, calendar life, and safety abuse testing. Tesla and BYD cell suppliers must demonstrate 1,000+ cycle retention before platform integration approval.
- Telecommunications:5G base station antenna arrays employ nanowire metamaterials for beam steering.
- Healthcare:Biosensor applications exploit surface functionalization for molecular recognition in diagnostic platforms.
Consumer electronics anchors present volume; automotive sector partnerships are gaining share fastest through long-term offtake agreements.
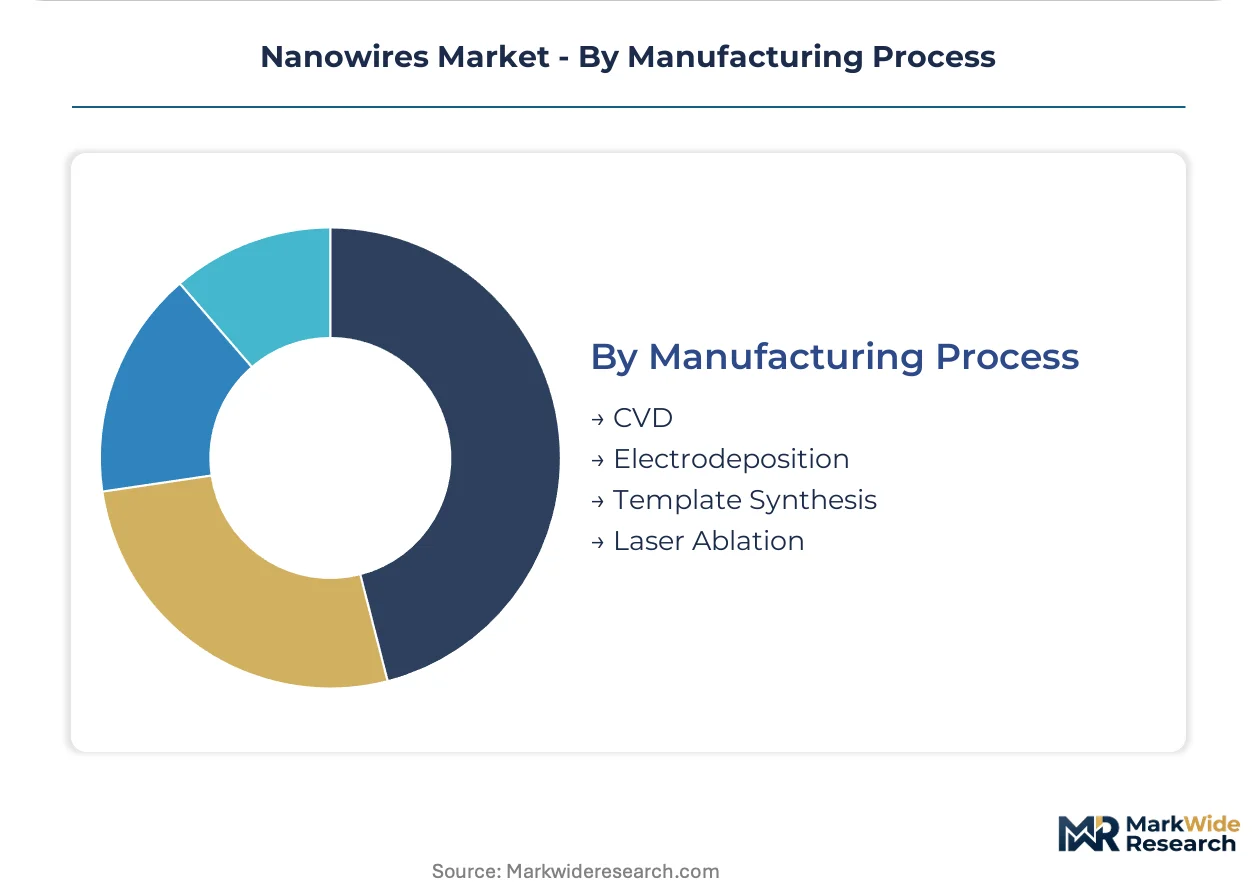
Manufacturing Process:
Process selection trades capital intensity against crystallinity control and throughput scalability.
- CVD:Chemical vapor deposition achieves epitaxial growth with precise diameter control for semiconducting nanowires. Applied Materials and Tokyo Electron equipment platforms support high-volume production for logic device manufacturing.
- Electrodeposition:Template-assisted electrochemical synthesis offers cost advantages for metallic nanowire production. Chinese suppliers in Jiangsu province leverage anodized aluminum oxide templates to scale silver nanowire output for display applications.
- Template Synthesis:Porous membrane templating enables research-scale production with broad material compatibility.
- Laser Ablation:Pulsed laser methods generate ultrahigh-purity nanowires for specialized photonics and defense applications.
Electrodeposition dominates metallic nanowire volume; CVD platforms are expanding most quickly for semiconductor device integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate nanowire precursor manufacturing through tax incentives tied to dual carbon compliance. Korean battery clusters in Gyeonggi-do leverage free trade zone status to anchor electrode material exports. German chemical parks in Ludwigshafen and Leverkusen integrate nanomaterial R&D with REACH registration support infrastructure.
China
SAMR enforces GB labeling standards that filter smaller producers from export eligibility, concentrating qualified supply among Yangtze Delta chemical parks. The dual carbon goals mandate battery energy density improvements that silicon nanowire architectures deliver, accelerating domestic anode procurement. Shanghai and Suzhou industrial zones host integrated precursor-to-anode production lines serving CATL and BYD cell suppliers.
South Korea
Samsung SDI and LG Energy Solution procurement specifications now include nanowire-enhanced anode materials for premium EV platforms. MFDS workplace exposure limits align with OECD nanomaterial testing guidelines, streamlining multi-market registration for metallic and semiconducting variants. Gyeonggi-do and Ochang electrode manufacturing corridors anchor regional supply concentration with dedicated nanomaterial qualification labs.
United States
EPA TSCA Section 5 premanufacture notification rules compel domestic producers to submit comprehensive toxicity data before commercial scale-up. Department of Energy advanced battery manufacturing grants favor vertically integrated nanowire anode producers spanning precursor synthesis through cell assembly. Silicon Valley and Boston-area startups cluster near national laboratories with nanofabrication user facilities.
Germany
ECHA REACH registration requirements mandate full substance characterization for metallic and semiconducting nanowire imports above one tonne annually. Specialty chemical distributors serving Stuttgart and Munich battery material markets restructure supplier qualification to front-load registration documentation. BASF SE anchors European supply through Ludwigshafen infrastructure for nanomaterial precursors.
Japan
METI funding programs support 3nm node development timelines driving silicon nanowire precursor procurement from Hsinchu and Shanghai foundries. JIS standards for nanomaterial characterization align with ISO protocols, reducing redundant safety data generation for exporters. Tokyo and Osaka industrial corridors concentrate template synthesis equipment for research-scale metallic nanowire production.
Nanowires Market Competitive Environment
Top-tier vendors anchor battery material supply chains through long-term offtake agreements, while research-scale specialists occupy photonics and sensor niches with lower volume thresholds. The vendor base stratifies across three archetypes: integrated chemical conglomerates with precursor-to-anode pipelines, venture-backed battery material pure-plays, and university-spinout synthesis technology licensors. Dominant competitive moves include capacity expansion synchronized with automotive platform launches and strategic partnerships securing electrolyte formulation expertise.
Among US-based battery material developers, Amprius Technologies and Sila Nanotechnologies exemplify the venture-backed archetype competing for aviation and defense contracts. BASF SE represents integrated chemical conglomerates leveraging European R&D infrastructure to anchor specialty precursor supply. These three occupy positions across the premium tier where silicon nanowire anode qualification timelines compress from five-year horizons toward eighteen-month cycles.
| Leading Market Players |
|---|
| ACS Materials |
| NanoComposix Inc. |
| Amprius Technologies |
| C3 Nano |
| BASF SE |
| Sila Nanotechnologies |
| Novarials Corporation |
| Blue Nano Inc. |
| Cambrios Technologies Corporation |
| Others |
Value Chain & Pricing Dynamics
Automotive OEM procurement teams in South Korea and China anchor pricing power through multi-year offtake agreements that compress spot market liquidity. Contract structures favor foundry-grade semiconducting nanowires with eighteen-month qualification timelines over metallic variants trading on shorter cycles.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as battery platform launches compress procurement windows. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified silicon nanowire anodes from display-grade silver nanowire feedstock and research-scale template synthesis outputs. Cost compression in metallic nanowires is intensifying because Chinese electrodeposition capacity expansion outpaces Korean display demand growth. Automotive cell suppliers exhibit the lowest price sensitivity due to performance-linked qualification requirements, while academic research buyers negotiate aggressively on volume discounts.
Supply Chain Analysis
China's GB standard domestic-content mandates are reshaping sourcing patterns for export-bound nanowire anode producers. Precursor chemical supply concentrates in Jiangsu province chemical parks, South Korean Gyeonggi-do battery corridors, and German Ludwigshafen specialty chemical hubs. Organosilane feedstock, anodized aluminum oxide templates, and high-purity metal salts constitute critical input dependencies. Single-source vulnerability runs through South Korean electrode manufacturing concentration where Samsung SDI and LG Energy Solution suppliers anchor regional output. Distribution runs through qualified material distributors front-loading REACH and TSCA registration documentation for European and North American battery material markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nanowires market sits in a technology-transition phase where silicon nanowire anode architectures displace legacy graphite slurry electrode formulations across automotive platforms.
For Market Incumbents: Cement technology leadership through backward integration into organosilane precursor synthesis and captive electrolyte additive formulation capabilities. Threats from composite silicon particulate formulations by Sila Nanotechnologies and other venture-backed competitors demand accelerated capacity expansion in Yangtze River Delta zones aligned with CATL and BYD platform schedules. Certification investment in dual carbon compliance documentation for Chinese SAMR export eligibility represents a critical defensive lever. For New Entrants and Emerging Players: The price-point gap between premium aerospace-qualified anodes and economy-grade research materials opens white-space targeting. India's PLI scheme for advanced cell chemistry manufacturing offers the most penetrable geography for technology transfer partnerships with established East Asian equipment licensors. Composite silicon-nanowire hybrid architectures occupy an underserved premium tier where pure nanowire costs remain prohibitive for mass-market EV platforms. A go-to-market angle emphasizing template-assisted electrodeposition scalability for specialized photonics applications bypasses incumbent lock-in across battery supply chains. For Investors and Strategic Acquirers: Distressed-cycle entries favor venture-backed battery material pure-plays with stalled commercialization timelines in Silicon Valley and Boston corridors. Long-term viability across the analysis window hinges on qualification success with at least one Tier 1 automotive cell supplier. Acquisition targets should display upstream control over precursor synthesis or proprietary electrolyte formulation IP. The signal to watch is EPA TSCA Section 5 premanufacture notification clearance timelines compressing toward twelve-month cycles as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | Secures organosilane supply against semiconductor foundry demand volatility for anode producers. |
| Long-term Supply Agreement with Automotive OEM | Locks in volume commitments from Tesla or BYD cell suppliers through platform launch cycles. |
| Technology Licensing to Indian PLI Beneficiaries | Monetizes electrodeposition expertise as domestic-content rules reshape Asian supply geography. |
| Green Manufacturing Transition | Aligns production with China's dual carbon goals and SAMR export eligibility thresholds. |
| Joint Venture with Electrolyte Formulation Specialist | Addresses talent scarcity in solid-electrolyte interphase stabilization for silicon nanowire cells. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with battery material procurement managers, nanofabrication R&D directors, electrodeposition equipment specialists, and regulatory affairs leads at specialty chemical distributors combined with EPA TSCA premanufacture notifications, ECHA REACH registration databases, Chinese SAMR GB standard publications, and Korean MFDS workplace exposure guidelines. Bottom-up capacity estimates triangulated against top-down automotive platform demand projections.
Granularity-level modeling spanned product type metallic-semiconducting-composite splits, application segments across electronics-energy storage-sensors, manufacturing process CVD-electrodeposition-template-laser distinctions, and end-user tiers from consumer electronics to automotive qualification protocols. CAGRs derived from segment-level volume build-ups and value-per-unit trajectories across the projection horizon. Forecast inputs incorporated silicon nanowire anode cycling retention benchmarks and OECD nanomaterial testing guideline harmonization timelines.
Inputs from automotive OEM procurement specifications and national laboratory nanofabrication user facilities were available through the study window; gaps in proprietary electrolyte additive formulations and solid-electrolyte interphase failure mode data introduce uncertainty bands around energy storage application penetration rates. Forecasts reflect assumptions on qualification timeline compression and regulatory clearance efficiency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Asia-Pacific Silicon Carbide Wafers Market
Semiconductor Devices
Semiconductor Memory IP Market
Semiconductor Devices
Global ASIC Bitcoin Mining Hardware Market
Semiconductor Devices
Global Diodes Market
Semiconductor Devices
IGCT Market
Semiconductor Devices
ADC & DAC In Quantum Computing Market
Semiconductor Devices
Nano-Magnetic Devices Market
Semiconductor Devices
Gan on Silicon Technology Market
Semiconductor Devices
Gallium Oxide Transistor Market
Semiconductor Devices
Europe Touch Screen Controllers Market
Semiconductor Devices
Modular Plating System Market
Semiconductor Devices
Thin Film Transistors (TFT) Market
Semiconductor Devices
Ferroelectric FET Market
Semiconductor Devices
India MLCC Market
Semiconductor Devices
Quartz Crystal Oscillators Market
Semiconductor Devices
Silicon on Insulator Market